
Blogs
PW Consulting: Semiconductor Etch Equipment Market Reaches $25.13 Billion in 2025, Projects 7.61% CAGR
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Semiconductor Etch Equipment Market: A 2026 Outlook
The semiconductor manufacturing landscape is entering a decisive phase where equipment capability defines technological leadership. As node sizes shrink and 3D architectures become the standard, the etch process stands as a critical bottleneck and enabler. For executives and investors navigating the 2026 fiscal year, understanding the trajectory of the Semiconductor Etch Equipment Market is not merely an operational concern but a strategic imperative. PW Consulting presents a comprehensive analysis designed to illuminate the path forward, offering clarity amidst volatile demand cycles and tightening regulatory frameworks.
The market has demonstrated remarkable resilience and growth over the past half-decade, evolving from a recovery phase into a sustained expansion period. According to our latest research, the overall market size is projected to reach new heights as we move through the decade. Starting from a base of approximately 25.13 billion USD in 2025, the trajectory indicates a steady climb toward nearly 42 billion USD by 2032. This growth is underpinned by a compound annual growth rate that reflects robust demand across high-performance computing and memory sectors. Such figures represent more than just revenue; they signal a fundamental shift in capital expenditure priorities as manufacturers race to secure supply chain sovereignty and technological edge.
Our report serves as a navigational tool for these complex waters. It dissects the market mechanics without fluff, providing actionable intelligence for strategic planning. Below, we offer a preview of the analytical depth contained within the full study, highlighting why this intelligence is essential for organizational decision-making in 2026.
Market Dynamics and Growth Trajectories
The current valuation of the sector reflects a compound effect of technological adoption and geographic shifts in manufacturing capacity. The progression from 2020 to 2025 shows a clear upward trend, with revenue expanding from 16.0 billion USD to over 25 billion USD. This historical context validates the investment thesis for etch technology but also raises questions about sustainability and concentration risks. The forecast period extending to 2032 suggests that this momentum is not accidental. It is driven by the intensifying requirements for atomic-scale precision in conductor and dielectric processes.
While the aggregate numbers are impressive, the true value for decision-makers lies in understanding the drivers behind the growth. The full report details the segmentation across equipment types, distinguishing between the dominance of dry etch solutions versus wet etch applications. It explores the process-specific demands, analyzing how conductor etch and dielectric etch segments are diverging in terms of growth velocity and technological complexity. Furthermore, the application landscape is scrutinized, revealing how logic chips and memory chips are contributing differently to the revenue pool. Each segment presents unique risk profiles and opportunity sets that require tailored strategic approaches.
Access to the granular data behind these segments is crucial. Organizations need to know not just that the market is growing, but where the growth is concentrated and which technologies are capturing the premium value. The complete analysis provides the necessary breakdown to inform capacity planning, R&D allocation, and partnership strategies without relying on generalized industry assumptions.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a high degree of concentration, where a select few players command the majority of revenue share. Our analysis indicates that the top three companies hold a significant portion of the market, while the top five consolidate even greater dominance. This oligopolistic structure creates a high barrier to entry for newcomers and forces established players to constantly innovate to maintain margins. For stakeholders, this concentration implies that competitor moves must be monitored with extreme precision.
Several key enterprises define the current competitive arena. Applied Materials and Lam Research Corporation remain pivotal forces, each leveraging distinct technological advantages. Tokyo Electron Limited continues to expand its manufacturing footprint to meet demand, while Hitachi High-Tech Corporation and Oxford Instruments plc offer specialized solutions for niche but critical applications. ASML Holding N.V., though often associated with lithography, plays an intertwined role in the broader equipment ecosystem. Other significant contributors include ULVAC, Inc., NAURA Technology Group Co., Ltd., SPTS Technologies Ltd, Plasma-Therm LLC, and SAMCO Inc., each carving out positions based on specific regional strengths or technological niches.
Semiconductor Etch Equipment Market
Recent developments among these key players offer a window into future strategies. Lam Research Corporation, for instance, has been aggressive in both product innovation and ecosystem building. In early 2025, they launched the Akara conductor etch tool, emphasizing atomic-scale precision via DirectDrive plasma control technology. This was followed by a donation of leading-edge multi-chamber etch systems to UC Berkeley for advanced R&D, signaling a commitment to securing the talent pipeline and validating technology in academic settings. Later in the year, collaborations focused on dry resist technology further underscore the industry's shift toward atomic layer etching and deposition.
Tokyo Electron Limited responded to capacity pressures with a facility expansion announcement in Miyagi, aimed at boosting plasma etch systems manufacturing. Meanwhile, Oxford Instruments plc made strides into adjacent emerging sectors, supplying atomic layer etch systems for quantum device fabrication. These moves are not isolated; they are strategic bets on where the next wave of demand will originate beyond traditional logic and memory nodes. Our report analyzes these movements to help clients anticipate competitor capacity expansions and technology pivots.
Regulatory Environment and Geopolitical Risks
No analysis of the semiconductor equipment market in 2026 is complete without a rigorous assessment of the regulatory landscape. The industry is operating under a cloud of evolving export controls and bipartisan legislative actions that directly impact equipment deployment and supply chain logistics. The dynamic nature of these regulations means that compliance is not a one-time checklist but a continuous strategic variable.
Recent actions by the U.S. Department of Commerce Bureau of Industry and Security have tightened constraints significantly. In December 2024, new rules were implemented affecting advanced packaging semiconductor manufacturing equipment, including specific etch tools. This was accompanied by expansions to the foreign direct product rule, extending jurisdiction over foreign-produced equipment destined for certain regions. Additionally, numerous entities were added to the Entity List, and specific types of equipment were added to the Commerce Control List. These measures fundamentally alter the accessible market for major players and require careful navigation for any international supply chain.
Furthermore, legislative moves such as the Bipartisan MATCH Act introduced in April 2026 propose prohibitions on the sale of cryogenic etch tools and deep ultraviolet immersion lithography systems to countries of concern. These regulations create a bifurcated market scenario where technology access is determined by geopolitical alignment rather than purely economic factors. Our report integrates these regulatory variables into the market forecast, helping clients understand the potential impact on revenue streams and market entry strategies in restricted regions. Understanding the nuance of these controls is vital for avoiding compliance pitfalls while optimizing global footprint allocation.
The Strategic Value of Comprehensive Intelligence
In a market defined by high concentration, rapid technological shifts, and stringent regulations, surface-level data is insufficient for robust decision-making. The full PW Consulting report on the Semiconductor Etch Equipment Market goes beyond high-level summaries to provide the depth required for executive strategy. It connects the dots between revenue trends, competitive maneuvers, and regulatory constraints to paint a holistic picture of the operating environment.
The report details the segmentation splits that drive revenue, offering clarity on where capital is flowing. It examines the regional distribution of market value, highlighting the disparities between mature markets and high-growth regions without oversimplifying the complexities of local demand drivers. It provides a thorough examination of the production and consumption dynamics that define the supply-demand equilibrium.
Access to this level of detail allows organizations to:
- Validate internal projections against independent market data.
- Identify potential gaps in product portfolios relative to market demand.
- Assess the risk exposure associated with regulatory changes in key regions.
- Benchmark competitor activities to refine go-to-market strategies.
- Pinpoint emerging opportunities in specialized etch applications beyond standard CMOS manufacturing.
The semiconductor industry rewards those who can anticipate change before it becomes obvious. By leveraging our detailed segmentation data—covering types, processes, applications, and regions—clients can move from reactive planning to proactive strategy. The report includes profiles and strategies for the key companies mentioned, analyzing how their recent developments align with broader market trends. This competitor intelligence is crucial for understanding who is gaining share, who is investing in which technologies, and where the next competitive threats may emerge.
Plasma Etch System Market
Moreover, the analysis considers the macroeconomic context, including the currency valuation and revenue units that frame the financial expectations. The forecast period through 2032 provides a long-term horizon for ROI calculations, allowing stakeholders to justify capital expenditures in equipment development or acquisition. The distinction between dry and wet etch equipment, for example, is not just a technical classification but a financial indicator of where the industry is placing its bets for the next decade. Similarly, the split between conductor and dielectric processes reveals the relative intensity of backend versus frontend manufacturing investments.
Conclusion: Navigating the Next Phase
The Semiconductor Etch Equipment Market is at a crossroads where technological capability and geopolitical reality intersect. The growth trajectory is clear, but the path to capturing value is fraught with complexity. Companies must balance the drive for innovation with the constraints of international regulation. They must watch the few dominant players while keeping an eye on specialists who may disrupt specific segments. They must allocate resources across logic and memory applications without knowing exactly which node will define the next cycle.
PW Consulting's full market research report is designed to equip leadership teams with the intelligence needed to make these judgments with confidence. We invite you to access the complete study to unlock the specific data points, regional breakdowns, and strategic recommendations that will inform your 2026 planning. Do not rely on assumptions when the stakes involve billions in capital and the future of technological sovereignty.
For detailed segmentation data, comprehensive competitor profiles, and in-depth regulatory impact analysis, please visit our dedicated market research portal. The complete intelligence package offers the granularity required to turn market insights into competitive advantage.
For detailed analysis of this topic, please visit the official page: Semiconductor Etch Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Mascara Market Hits $7.5B in 2025, Poised for 6.09% CAGR Growth Through 2032
By pmarketresearch, 2026-09-15
Global Mascara Market 2026: Strategic Intelligence for Competitive Advantage
Setting the Stage: Why This Research Matters Now
The global cosmetics industry is entering a decisive growth cycle, and mascara remains at the center of category innovation. As consumer expectations around wear performance, ingredient transparency, and sustainability continue to reshape purchasing behavior, brands and manufacturers must act on evidence rather than intuition. The latest PW Consulting Mascara Market study delivers exactly that foundation. Covering historical data from 2020 through 2025 with a forward-looking forecast extending to 2032, our analysis is built to help leadership teams evaluate where to invest, how to position portfolios, and which competitive pressures will define the next several years of category development.
The market has already demonstrated steady expansion across the past half-decade, reaching an estimated valuation of 7.5 billion US dollars in 2025. Growth momentum is projected to continue into the forecast window, with the category advancing toward a compound annual growth rate of 6.09 percent between 2026 and 2032. By the terminal year of our modeling horizon, total market value is expected to exceed 11 billion dollars. These are not abstract numbers; they reflect the combined impact of innovation cycles, formulation differentiation, retail infrastructure shifts, and evolving demand patterns in both mainstream and prestige channels. For decision-makers, the central question is no longer whether the category is growing, but which structural forces will determine who captures disproportionate share within it.
This article previews the strategic architecture of our full report. It outlines the business questions the research is designed to answer, describes the operational content included inside the study, and situates the most recent industry developments into a defensible competitive context. Core segment splits, detailed regional breakdowns, and company-specific revenue figures are intentionally held back. That architecture is deliberate: the complete intelligence is structured for use in board-level planning, portfolio reviews, and market-entry assessments, and it belongs in your hands where it can be applied with precision.
The Strategic Value of Data-Backed Forecasting for 2026 Decisions
A market study becomes strategically useful when it converts numerical trends into decision-ready intelligence. For 2026, executives face a particularly crowded field of competing priorities: formulation innovation must be balanced against cost discipline, distribution strategies must align with channel consolidation and digital-led purchase journeys, and sustainability commitments must be translated into credible product narratives that withstand scrutiny. In that environment, high-level growth statements offer little direction. What matters is how the growth breaks down across use cases, format categories, regional demand intensity, and competitive positioning.
The PW Consulting research is built around that requirement. Rather than presenting a single aggregate projection, the analysis is organized to help teams evaluate the category from multiple business angles at once. Readers can examine how different usage occasions contribute to total category pull, assess which product characteristics are most closely associated with repeat purchase behavior, and compare regional market size with structural demand signals. That multi-layered approach is essential because mascara is not a monolithic category. Daily wear routines, event-driven application, and professional makeup contexts each generate distinct purchasing logic, and the relative weight of those contexts shapes everything from SKU architecture to marketing investment.
Equally important, the forecast period is structured to support operational planning. A six-year outlook enables supply chain teams to test capacity assumptions, finance departments to build scenarios around revenue ramps, and product organizations to sequence innovation pipelines with realistic timing. Instead of relying on short-term snapshots, leadership gets a view of how the category is likely to scale and where acceleration or deceleration may occur as competitive intensity and consumer preference evolve.
What the Study Delivers: Operational Content for Real-World Planning
The report is designed for immediate application. It moves beyond high-level commentary to provide content that marketing leaders, product developers, procurement professionals, and strategic planners can use directly in day-to-day decision-making. Among the practical components included are:
Mascara Market
Lipstick Market
- A historical reconstruction of market movement from 2020 to 2025, allowing teams to test how past disruptions, channel shifts, and product launches influenced category performance.
- A forward forecast through 2032 that supports scenario planning for capacity, investment timing, and portfolio prioritization.
- Detailed segmentation across product types, usage occasions, and geographic demand patterns so that strategy teams can identify where specialized formulations and targeted messaging create the strongest commercial logic.
- Competitive analysis covering the major global players and specialized manufacturers shaping supply, innovation, and private-label capability.
- Recent industry developments, including trade show launches and materials innovation, placed in context to show how product and packaging advances are influencing the competitive field.
The segmentation framework is especially valuable for organizations deciding how to allocate limited resources. When companies can see how distinct product attributes relate to overall market structure, they are better positioned to prioritize claims development, packaging choices, and brand differentiation. In practice, that means fewer assumptions about where category growth is concentrated and more confidence in which product narratives deserve shelf space, promotional support, and R&D investment.
Competitive Dynamics in a Concentrated Market
Planning in the mascara category requires an honest assessment of competitive concentration. The market remains led by a small group of large multinational companies, with the top three firms together accounting for a substantial share of category revenue and the top five firms holding an even larger collective position. That structure shapes pricing power, innovation cadence, and channel influence. Large players benefit from broad brand portfolios, established distribution relationships, and the ability to scale successful formulas across multiple consumer tiers. At the same time, the presence of specialized manufacturers, private-label suppliers, and regional leaders creates meaningful opportunities for partners and challengers who can execute with focus.
Several global names define the competitive core. L'Oréal operates across mass and prestige with a wide portfolio that spans accessible and premium performance claims. The Estée Lauder Companies competes in the higher-end space through brands known for advanced wear, curl retention, and premium application experience. Procter & Gamble maintains a strong mass-market footprint with products built around affordable volume and lengthening performance. Coty Inc. continues to play a significant role in color cosmetics with long-wear and waterproof positioning. Shiseido extends the competitive field in Asia with high-precision formulas and conditioning-focused benefits, while Chanel anchors prestige demand with luxury brush design and long-lasting pigmentation. Amorepacific remains closely aligned with K-beauty preferences, particularly around curling and lengthening effects.
Beneath the brand owners, the supplier and contract manufacturing layer is equally important. Schwan Cosmetics specializes in high-volume private-label production with broad texture options and full-service manufacturing capability. Geka GmbH supplies sustainable brush and packaging solutions, including materials using post-consumer recycled content with low-emission decoration processes. HCP Packaging has introduced renewable applicator technologies aimed at reducing dependence on conventional synthetic materials. In the contract and export segment, Homax Cosmetics, Columbia Cosmetics, Xiran Cosmetics, and Aurora Global Brands each support different combinations of budget and premium positioning, private-label customization, and international distribution. Together, this ecosystem determines how quickly new formulas can reach market, how much differentiation can be achieved through applicator and packaging design, and where cost efficiencies are possible without sacrificing product quality.
Latest Developments Shaping Competitive Positioning
Recent activity in materials, packaging, and sustainability commitments is already influencing the category's next competitive cycle. At the trade-show level, Geka GmbH introduced a music-inspired mascara brush collection with updated brush designs and shadow printing on fully post-consumer recycled packaging. Alongside that launch, HCP Packaging presented a cellulose-derived renewable fiber applicator technology developed as an alternative to traditional synthetic materials. These developments are not isolated design exercises; they reflect broader pressure on manufacturers and brands to reduce environmental footprint while preserving application performance and shelf appeal. In that context, packaging and applicator innovation are becoming part of the product proposition itself, not just a logistics consideration.
Sustainability is also entering the formulation conversation more directly. One of the largest multinational players has expanded its long-term sustainability program with a commitment to make its mascara formulations biodegradable or naturally derived by 2030. That kind of public target changes expectations across the supply chain. It raises the bar for ingredient sourcing, encourages supplier partnerships around material innovation, and increases the importance of credible claims language. For competitors and partners alike, it signals that environmental performance is moving from a marketing overlay to a core development requirement.
For industry participants, these shifts create both risk and opportunity. Companies that can integrate performance, sustainability, and application experience into a coherent package will be better positioned to justify premium positioning and consumer loyalty. Those that rely solely on legacy formulas or conventional materials may find it harder to defend differentiation as buyer expectations and regulatory attention continue to increase.
How to Use This Research for Strategic Planning
The report is most valuable when treated as a working document for cross-functional planning. Product teams can use it to evaluate where formulation innovation is likely to generate the strongest return and how to sequence development relative to category demand. Commercial leaders can use it to refine channel and geographic priorities without relying on guesswork about where demand depth is greatest. Procurement and operations teams can use the forecast structure to align capacity and sourcing decisions with a realistic growth path. And corporate strategy groups can use the competitive overview to assess partnership opportunities, private-label dynamics, and the positioning of challenger brands against established leaders.
This preview is intended to demonstrate the scope and rigor of the full study, not to replace it. The market framework, segmentation architecture, company profiles, and competitive developments are built to support precise decisions in a category where small differences in product performance, packaging credibility, and usage positioning can translate into meaningful share movement over time. The full report provides the underlying figures, segmentation detail, and scenario context needed to move from directional insight to actionable planning.
For organizations preparing for 2026 and beyond, the strategic imperative is clear: understand the market structure early, anticipate where innovation and sustainability expectations are heading, and use validated data to prioritize investment. The PW Consulting Mascara Market research is designed to support that process from the first strategic review through ongoing portfolio management.
For detailed analysis of this topic, please visit the official page: Mascara Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: High Strength Steel Market Hits $130M in 2025, Forecast 7.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the High Strength Steel Market: A 2026 Executive Briefing
The global high strength steel market stands at a critical inflection point as industrial demand converges with stringent regulatory frameworks and accelerated technological innovation. For corporate strategists, procurement leaders, and capital allocators, navigating this landscape requires more than top-line projections. It demands granular, actionable intelligence that maps macroeconomic momentum to on-the-ground competitive shifts. PW Consulting’s latest High Strength Steel Market research delivers precisely that intelligence, offering a decision-ready architecture designed to de-risk strategic planning and unlock structural advantages across the 2026 to 2032 horizon.
A Market Defined by Resilient Growth and Structural Rebalancing
Tracing the market’s trajectory from 2020 through 2025 establishes a clear baseline of steady expansion, with revenue compounding at a pace that outpaces broader industrial metal benchmarks. The transition from historical performance into the forecast window reveals an acceleration pattern that demands immediate strategic attention. By 2026, the market has crossed a significant revenue threshold, and the forward projection indicates sustained upward momentum through the end of the decade. The implied compound annual growth rate across the full forecast period underscores a structurally healthy demand environment rather than a cyclical spike. This trajectory is not uniform across all vectors, which is exactly why executives must look beyond aggregate figures. The reallocation of investment, shifting end-user priorities, and evolving material specifications are reshaping where value accrues and which product architectures capture premium positioning.
Leadership teams operating in capital-intensive sectors cannot afford to treat high strength steel as a commoditized input. The market’s expansion is increasingly tied to performance-critical applications, weight-reduction mandates, and infrastructure modernization cycles. Understanding how these drivers fragment across product architectures and end-use ecosystems is the difference between capturing margin expansion and being squeezed by price volatility. Our research isolates these dynamics without diluting them into vague trend summaries, providing a clear line of sight from macro momentum to segment-level execution pathways.
Decoding the Competitive Architecture
The industry’s leadership cohort reflects a deliberate concentration of technological capability, geographic footprint, and application-specific expertise. A handful of entrenched players command the majority of realized market value, yet the competitive field remains highly active as incumbents recalibrate portfolios and challengers target niche performance tiers. The market structure exhibits moderate oligopolistic characteristics, meaning that while scale players set pricing anchors and technology benchmarks, there remains meaningful room for differentiated positioning through grade specialization, regional supply chain optimization, and application engineering.
High Strength Steel Market
Several globally recognized producers anchor the landscape, each pursuing distinct strategic vectors. A Swedish leader has cemented its reputation through premium structural and automotive grades engineered for extreme load conditions and lightweighting targets. A Luxembourg-headquartered multinational continues to scale its high-yield and advanced-grade offerings, particularly where construction durability and automotive crash performance intersect. A South Korean manufacturer has extended its global sales architecture around premium structural steels and automotive high-strength lines, leveraging integrated production advantages to compete in export-driven markets. A Japanese enterprise maintains a strong presence in ultra-high-tensile and offshore-grade plates, serving infrastructure and heavy industrial buyers who prioritize certification depth and metallurgical consistency. In North America, the largest domestic supplier of advanced high-strength steels is pushing third-generation grades that directly address vehicle lightweighting requirements, while a major U.S. integrated producer has introduced proprietary advanced grades designed for electric vehicle platforms and transformer applications. European and Indian counterparts round out the competitive matrix, with one German firm supplying high-strength flat-rolled products for automotive and industrial use, an Austrian manufacturer emphasizing premium grades for machinery and automotive segments, and an Indian producer focusing on corrosion-resistant high-tensile offerings for offshore and maritime environments.
This is not a static hierarchy. Recent corporate movements demonstrate how quickly product launches, capacity decisions, and industry consortium studies can reshape sourcing preferences. A major European producer recently introduced a new line of ultra-high-strength steels engineered specifically for electric vehicle chassis, positioning the release around lightweighting efficiency and updated safety compliance thresholds. A leading U.S. integrated manufacturer simultaneously expanded its portfolio to include proprietary advanced high-strength formulations and ultra-thin lightweight grades tailored for EV and transformer applications. Meanwhile, a North American capacity expansion initiative committed substantial capital toward increasing quenched-and-tempered steel output, extending the availability of flagship high-strength brands for demanding industrial and transportation users. Complementing these corporate moves, an industry-wide research body published a new parts consolidation study that quantifies how advanced high-strength steels can simplify vehicle architecture while maintaining structural integrity. These developments are not isolated headlines; they signal where R&D capital is flowing, where downstream buyers are being encouraged to re-evaluate material selections, and which performance benchmarks are becoming table stakes rather than differentiators.
Forces Reshaping Market Dynamics
Executive decision-making in this sector is being compressed by a convergence of policy shifts, input cost volatility, and standardization updates that directly alter procurement economics and specification strategies. Trade policy remains one of the most immediate variables. The reinstatement and subsequent escalation of import tariffs in the United States through mid-2025 fundamentally altered the cost baseline for imported high strength steel, forcing regional buyers to reconsider sourcing geography, inventory positioning, and contract structuring. Across the Atlantic, parallel moves by the European Union to reduce duty-free quotas and impose steep duties beyond those thresholds have recalibrated the cost landscape for European manufacturers and their supply chain partners. These policy adjustments do not merely affect landed cost; they influence capacity utilization patterns, redirect trade flows, and elevate the strategic importance of regional supply security.
Input cost dynamics add another layer of complexity. Recent price adjustments by major domestic producers in response to rising prime scrap costs illustrate how raw material inflation transmits rapidly into finished high-strength-grade economics. When base material costs move sharply, the margin sensitivity of advanced grades becomes a board-level concern, particularly for automotive and construction programs that operate on tightly negotiated multi-year agreements. Simultaneously, updated welding electrode classification standards have introduced new specification considerations for fabrication and construction workflows, requiring engineering teams to align procurement choices with revised compatibility and certification requirements. These are not peripheral compliance items; they are operational variables that influence total cost of ownership, lead-time reliability, and vendor qualification timelines.
What ties these forces together is their compounding effect. Tariff exposure changes sourcing logic, raw material inflation compresses margin tolerance, and specification updates alter fabrication readiness. Companies that treat these as independent risks often overcorrect in one area while under-hedging another. Our research integrates these variables into a unified operational framework, enabling leaders to model how policy, input costs, and technical standards interact across procurement cycles and capital planning horizons.
Inside the Research: Actionable Architecture for 2026 Decision-Making
This study is constructed for executives who need precision over generality. Rather than presenting a static market snapshot, the report maps the decision environment across product architecture, application demand, regional positioning, and competitive behavior, with explicit guidance on where and how to act. The analytical core is built around a multi-layered segmentation framework that dissects the market by type, application, and geography, while deliberately avoiding the trap of superficial share arithmetic. Each segmentation layer is evaluated for growth durability, price sensitivity, specification trajectory, and substitution risk so that sourcing and product-strategy teams can identify where to protect exposure and where to pursue premium positioning.
The competitive section goes beyond corporate profiling to assess strategic posture, capacity intent, and portfolio direction. Readers gain a structured view of how leading producers are aligning R&D investments with end-user requirements, which product families are being prioritized, and how recent launches and capacity decisions signal the next phase of market competition. This enables procurement and product-development teams to anticipate supplier positioning, evaluate alternative grade pathways, and construct negotiation strategies grounded in forward-looking supplier behavior rather than historical pricing alone.
Regulatory and cost-environment analysis is embedded throughout the report, not isolated in a compliance appendix. Trade-policy escalations, duty-quota adjustments, raw material price movements, and updated technical standards are mapped to their operational consequences, giving strategy and supply-chain leaders a practical reference for scenario planning. The forecast architecture extends across the full outlook window, providing a coherent growth narrative that supports capacity decisions, long-term contract structuring, and product-mix optimization. Crucially, the report maintains a tight focus on decision utility: it highlights where growth is structurally supported, where volatility is likely to intensify, and which strategic levers deliver the highest return on analytical investment.
To preserve the depth required for real-world application, certain granular breakdowns are reserved for the full intelligence package. The complete report provides the detailed regional and application-level decompositions, type-specific revenue architecture, concentration measurements, and company-by-company strategic assessments that turn high-level direction into executable planning inputs. This deliberate structure ensures that the executive summary establishes credibility and directional clarity while the full dataset delivers the specificity needed for budgeting, sourcing, and product-roadmap decisions.
Why This Intelligence Matters Now
Market leadership in high strength steel is increasingly defined by the speed and accuracy with which organizations integrate demand signals, policy reality, and supplier strategy into their capital and procurement plans. The growth trajectory through the end of the decade is robust, but the path to capturing it is uneven. Winners will be those who align material specifications with downstream performance mandates, manage exposure to trade and input-cost volatility, and position their product or sourcing strategies ahead of competitor portfolio shifts. Delaying that alignment until quarterly reviews or spot-market disruptions force action is a structural disadvantage.
PW Consulting’s High Strength Steel Market research provides the analytical foundation to move from reactive monitoring to proactive positioning. It equips leadership teams with a consolidated view of where value is concentrating, how competitive intentions are evolving, and which operational variables deserve immediate attention in 2026. The full report is designed to be read by strategists, commercial directors, procurement executives, and engineering leaders who need to translate market momentum into measurable advantage. Accessing the complete dataset will reveal the detailed segmentation architectures, competitive granularities, and scenario-ready breakdowns necessary to convert insight into execution.
High-strength Polyester Thread Market
For organizations preparing for the next phase of industrial demand, the question is no longer whether high strength steel will remain central to lightweighting, durability, and infrastructure performance, but how precisely to navigate the opportunities and risks embedded in its growth path. This research is built to answer that question with the clarity, rigor, and operational relevance that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aseptic Packaging Market Hits $78.29B in 2025, Projects 10.5% CAGR Through 2032
By pmarketresearch, 2026-09-15
Unlocking Growth in the Aseptic Packaging Market: Strategic Insights for 2026 and Beyond
The global packaging landscape is undergoing a profound transformation, driven by shifting consumer expectations, stringent regulatory frameworks, and an enduring demand for shelf-stable solutions that ensure product integrity. For senior executives and strategic planners, understanding the nuances of this evolution is no longer optional; it is a critical component of long-term viability. PW Consulting's latest comprehensive market research on the Aseptic Packaging Market offers a detailed roadmap for navigating this complex terrain, providing the intelligence necessary to make informed decisions throughout the forecast period.
This analysis serves as an introduction to our extensive study, highlighting the macro-economic trajectories, competitive shifts, and regulatory pressures that will define the industry from 2026 through 2032. By synthesizing historical performance with future projections, we aim to equip stakeholders with the foresight needed to capitalize on emerging opportunities while mitigating inherent risks.
Macro-Economic Trajectory and Market Valuation
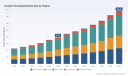
The financial magnitude of the aseptic packaging sector underscores its importance within the broader manufacturing ecosystem. Our historical analysis tracks a consistent upward trend, reflecting the sector's resilience and capacity for expansion. In 2020, the market generated approximately USD 45.67 Billion in revenue. This figure climbed steadily over the following years, reaching USD 50.26 Billion in 2021 and USD 55.08 Billion in 2022. The momentum continued through 2023 and 2024, with valuations rising to USD 61.45 Billion and USD 70.76 Billion respectively, before closing the base year of 2025 at USD 78.29 Billion.
Looking forward, the forecast period from 2026 to 2032 indicates sustained growth. The market is projected to reach USD 88.76 Billion in 2026. This growth trajectory is expected to accelerate slightly, culminating in a valuation of USD 156.25 Billion by 2032. This expansion represents a Compound Annual Growth Rate (CAGR) of 10.5% over the forecast period. Such robust performance suggests that aseptic packaging is not merely a passive container solution but a dynamic sector integrated deeply into supply chain efficiencies and product lifecycle management.
Bulk Aseptic Packaging Market
However, understanding the top-line numbers is only the first step. The strategic value lies in dissecting the drivers behind this growth and anticipating where value pools will shift. Our report delves into these specific drivers, analyzing how different variables interact to influence overall market health. While the aggregate figures provide a horizon, the detailed segmentation analysis within the full study reveals the specific lanes of opportunity that will drive this CAGR.
Structural Dynamics and Regional Shifts
The composition of market demand is shifting as regional economic conditions evolve and manufacturing capabilities expand. Historically, mature markets have held significant share, but the growth velocity in emerging regions is reshaping the competitive map. Our research indicates that regional dynamics are becoming increasingly complex, influenced by local regulatory environments, infrastructure development, and changing consumption patterns.
For instance, the demand landscape is not uniform. Different regions exhibit varying preferences for packaging types and applications based on local industrial strengths. While some areas maintain strong dominance in specific sectors due to established infrastructure, others are witnessing rapid adoption rates driven by urbanization and retail expansion. The full report provides a granular breakdown of these regional performances, allowing strategists to identify where to allocate capital for maximum return.
Furthermore, the type of packaging utilized varies significantly across industries. The market encompasses a diverse range of formats, from cartons and bags to bottles and vials. Each format serves distinct functional requirements regarding barrier properties, portability, and stacking efficiency. The interplay between these formats and the industries they serve creates a complex web of dependencies. Understanding which formats are gaining traction in specific application sectors is crucial for manufacturing planning and inventory management. Our detailed segmentation analysis isolates these trends, offering clarity on which product categories are poised for the steepest growth curves.
Regulatory Pressures and Sustainability Imperatives
One of the most significant forces reshaping the industry is the regulatory environment, particularly within major economic zones. The European Union's Packaging and Packaging Waste Regulation (PPWR), which entered into force on February 11, 2025, stands as a pivotal development. This regulation mandates that all packaging on the EU market must be recyclable, with detailed design for recycling criteria set via delegated acts by 2028. It becomes fully applicable from August 12, 2026, following an 18-month transition period.
For aseptic packaging, this presents a specific compliance challenge. The PPWR requires that aseptic packaging placed on the European market must be recyclable, necessitating aluminum layer minimization and the use of mono-material components to meet compliance standards. This regulatory shift is forcing manufacturers to innovate rapidly. The traditional reliance on multi-layer structures containing aluminum for barrier protection is being scrutinized under the new framework. Companies must now balance the functional requirement of sterility and shelf-life extension with the imperative of recyclability.
This regulatory context is not just a compliance hurdle; it is a catalyst for innovation. It drives the development of new materials and processing technologies that can maintain product safety while reducing environmental impact. Our report analyzes the implications of these regulations across different geographies, helping companies anticipate compliance costs and adjust their product development pipelines accordingly. The transition period offers a window of opportunity for early movers to establish compliant solutions before the enforcement date, potentially securing a competitive advantage in key markets.
Competitive Landscape and Strategic Maneuvers
The market structure is characterized by a moderate level of concentration, with key players exerting significant influence over pricing, technology standards, and supply chain dynamics. The concentration ratio indicates that a handful of major entities control a substantial portion of the market share. This oligopolistic tendency suggests that strategic partnerships, mergers, and acquisitions will continue to be relevant tools for companies seeking to scale or diversify their portfolios.
Several core enterprises define the current competitive arena. Tetra Laval S.A., headquartered in Lund, Sweden, remains a pioneer of aseptic packaging systems and carton/filling technology for dairy, beverages, and liquid foods. Their recent strategic moves highlight the industry's direction. In January 2026, Tetra Pak announced a EUR 60 Million investment in a new pilot plant at Lund, Sweden, focused on paper-based barrier technology to replace aluminum foil in aseptic cartons. This move directly addresses the sustainability challenges posed by regulations like the PPWR, signaling a commitment to mono-material solutions.
Similarly, SIG Combibloc Group AG, based in Zug, Switzerland, is a major provider of flexible aseptic bag-in-box systems, including the SteriSeal Spout for bulk liquids. Their activity level remains high, with a USD 35 Million investment announced in July 2025 to expand their aseptic carton plant in Querétaro, Mexico, targeting dairy and shelf-stable beverages. Furthermore, in January 2026, SIG entered the camel milk category with new aseptic carton solutions, demonstrating agility in capturing niche market segments. They also rolled out a new aluminum-free aseptic carton solution in select European markets in 2025, enhancing recycling yield for dairy and juice applications.
Other significant players contribute to the diverse ecosystem. Amcor plc, located in Zurich, Switzerland, supplies aseptic plastic bottles and extended shelf-life ESL packaging with UV protection and shelf lives ranging from 90 days to 1 year. Elopak AS, from As, Norway, manufactures aseptic cartons for dairy, juice, and shelf-stable beverages. In Asia, Greatview Aseptic Packaging Co., Ltd., based in Beijing, China, is a key producer of rolled-fed and blank-fed aseptic cartons for dairy and non-carbonated soft drinks. DS Smith plc, headquartered in London, United Kingdom, offers aseptic sterilised transit packaging solutions for pharma and food applications. Sealed Air Corporation, in Charlotte, United States, provides advanced flexible aseptic pouches and componentry for liquid food packaging. Sidel Group, based in Paris, France, operates as an aseptic filler and packaging equipment provider, including PET bottle lines.
Recent trade show activity also underscores the collaborative and innovation-driven nature of the sector. In June 2026, ASEPTO exhibited aseptic liquid packaging innovations at ProPak MENA 2026 in Cairo, Egypt. Similarly, Steriline showcased advanced aseptic packaging filling lines at Interphex 2025 in New York. These exhibitions highlight the continuous flow of technological advancements in filling and packaging equipment, which is essential for maintaining the sterility assurance levels required by end-users.
The competitive dynamics are further influenced by raw material suppliers and specialized manufacturers. For example, NewJF Packaging, formed in 2003 and listed on the Hong Kong Stock Exchange, is recognized as the world's third-largest manufacturer of aseptic cartons. Such entities play a critical role in the supply chain, affecting availability and cost structures for downstream converters.
Application Drivers and Sector Growth
The demand for aseptic packaging is fundamentally tied to the needs of the industries it serves. The Food and Beverage sector remains a dominant force, driven by the need to preserve nutritional value, flavor, and safety without the use of preservatives. This sector benefits immensely from the extended shelf-life capabilities that aseptic technology provides, allowing for broader distribution networks and reduced food waste.
The Pharmaceutical sector also represents a critical application area. Sterility and contamination control are non-negotiable in this field. Aseptic packaging ensures that sensitive biological products, vaccines, and liquid medications remain safe for consumption or administration. The stringent regulatory requirements in pharma drive demand for high-quality vials, ampoules, and specialized containers that can withstand rigorous sterilization processes. Our report analyzes how growth in these application sectors correlates with broader healthcare trends and food security initiatives.
While these two sectors are prominent, there are other applications gaining traction. Understanding the specific growth rates and volume contributions of each application segment is vital for companies aiming to specialize or diversify. The full study provides precise data on how each application area contributes to the overall market revenue, enabling clients to benchmark their performance against industry averages.
Aseptic Packaging Market
Strategic Implications for 2026 Decision-Making
As we move through 2026, the decisions made by industry leaders will set the course for the next decade. The convergence of regulatory pressure, material innovation, and regional demand shifts creates a complex operating environment. Companies must decide whether to invest heavily in R&D for sustainable materials, pursue geographic expansion into high-growth regions, or consolidate market share through strategic acquisitions.
The investment signals from key players suggest a clear trend toward sustainability and regional localization. The EUR 60 Mn investment by Tetra Pak and the USD 35 Mn expansion by SIG indicate confidence in long-term demand but also a necessity to adapt product structures to meet future compliance standards. For smaller players or new entrants, the barrier to entry may rise as compliance costs increase, potentially favoring well-capitalized incumbents who can absorb the transition costs.
Moreover, the supply chain resilience demonstrated during previous global disruptions continues to be a priority. Localization of production facilities, such as the expansion in Mexico, reduces logistics risks and aligns with "nearshoring" trends. Understanding the cost implications of these logistics shifts and their impact on final product pricing is another critical insight provided in our detailed analysis.
Conclusion and Access to Comprehensive Intelligence
The Aseptic Packaging Market is poised for significant expansion, driven by a 10.5% CAGR and a valuation trajectory moving from USD 88.76 Billion in 2026 to over USD 156 Billion by 2032. However, realizing value in this environment requires more than just acknowledging growth figures. It demands a deep understanding of the regulatory mechanisms shaping material choices, the competitive strategies employed by industry leaders, and the specific regional dynamics that influence market access.
PW Consulting's full market research report offers an unparalleled depth of analysis. It moves beyond the high-level overview to provide actionable intelligence on market entry strategies, supply chain optimization, and competitive benchmarking. The report details the specific segmentation splits, regional revenue contributions, and application-specific growth rates that are essential for granular strategic planning.
To fully leverage these insights and secure a competitive edge in the evolving landscape of 2026 and beyond, stakeholders are encouraged to access the complete study. The detailed data, combined with our expert analysis of industry trends and regulatory impacts, provides the foundation necessary for robust strategic decision-making. Visit the PW Consulting source page to download the comprehensive report and gain access to the full suite of intelligence designed to guide your organization through the next phase of market evolution.
For detailed analysis of this topic, please visit the official page: Aseptic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting DNA Sequencing Market Report: $16.89B 2025 Revenue, 14.9% CAGR to $44.63B by 2032
By pmarketresearch, 2026-09-15
Strategic Foresight in Genomics: Navigating the DNA Sequencing Market Through 2032
The global DNA sequencing industry has transitioned from a specialized research tool to a cornerstone of modern healthcare, public safety, and agricultural innovation. As we enter 2026, executives, investors, and policy stakeholders face a landscape defined by rapid technological iteration, evolving regulatory frameworks, and intensifying competitive dynamics. PW Consulting's latest market research offers a comprehensive blueprint for navigating this complex environment, translating historical momentum into actionable strategy for the decade ahead.
DNA Sequencing Market
A Market Defined by Sustained Expansion
Historical revenue data from 2020 through 2025 reveals a decade of uninterrupted growth, with the global market expanding from approximately 9.12 billion USD to 16.89 billion USD. This trajectory reflects not merely cyclical demand but a structural shift in how biological data is generated, analyzed, and deployed across commercial and clinical ecosystems. Looking forward, our forecast model projects the market to reach 19.48 billion USD in 2026, accelerating steadily toward 44.63 billion USD by 2032. This pathway corresponds to a compound annual growth rate of 14.9 percent, underscoring the durability of demand drivers ranging from precision oncology to population-scale genomic surveillance.
For corporate strategists, these figures are more than aggregate indicators. They signal where capital allocation, R&D prioritization, and partnership development will yield the highest marginal returns. The research dissects the underlying engines of this expansion, mapping how technological transitions, application diversification, and regional uptake patterns intersect to shape competitive positioning. Rather than presenting static snapshots, the analysis emphasizes dynamic interdependencies, enabling decision-makers to anticipate inflection points before they materialize in financial results.
What the Research Delivers: From Macro Trends to Operational Intelligence
A market study is only as valuable as its translational capacity. This report is engineered for practitioners who require more than directional guidance. It combines top-down market sizing with bottom-up operational analysis, providing a multi-layered view of the sequencing ecosystem. The following components form the analytical backbone of the study:
- Technology evolution pathways, including the maturation of established platforms and the commercialization readiness of emerging long-read and single-molecule approaches
- Application-driven demand mapping across clinical, research, agricultural, and public health use cases, with emphasis on adoption velocity and reimbursement maturation
- Competitive positioning frameworks that evaluate instrument throughput, workflow integration, consumable economics, and software-driven differentiation
- Regulatory and standards development tracking, capturing how evolving guidance shapes product development cycles, clinical validation requirements, and market entry strategies
- Scenario-based forecasting that stress-tests growth assumptions against potential technological disruptions, pricing compression, and policy shifts
By integrating these dimensions, the research equips leadership teams with a structured lens to evaluate market entry timing, portfolio optimization, and partnership strategies. The methodology deliberately isolates signal from noise, ensuring that strategic recommendations rest on verified adoption patterns rather than speculative hype.
The Competitive Arena: Incumbents, Disruptors, and the Battle for Workflow Dominance
The sequencing market is characterized by high concentration, with the top three players accounting for approximately 65 percent of industry revenue and the leading five firms capturing roughly 78 percent. This structure reflects the capital intensity of platform development, the importance of installed base economies, and the strategic value of integrated reagent and software ecosystems. Yet concentration does not equate to stagnation. The competitive landscape is being reshaped by targeted innovation, workflow specialization, and the entry of well-capitalized challengers seeking to redefine cost-performance thresholds.
Illumina, headquartered in San Diego, remains a central force through its leadership in next-generation sequencing platforms, sequencing instruments, reagents, and whole-genome sequencing-based minimal residual disease research solutions. Its product cadence continues to influence downstream adoption patterns across both academic and commercial laboratories. Thermo Fisher Scientific, based in Waltham, complements this landscape with a comprehensive portfolio spanning NGS, Sanger sequencing, and genomics instruments alongside a broad consumable lineup, enabling multi-technology deployments within single organizational environments.
On the long-read frontier, Oxford Nanopore Technologies, operating from Oxford, has advanced nanopore-based sequencing platforms and analytical tools that emphasize real-time data generation and portable deployment formats. Pacific Biosciences, located in Menlo Park, continues to push the boundaries of single-molecule real-time technology and HiFi long-read sequencing systems, targeting applications where structural variant resolution and haplotype phasing carry high clinical or research value. These platforms are not merely technical alternatives; they represent strategic choices about read length, error profiles, turnaround time, and total cost of ownership.
Additional dynamics are emerging from companies that specialize in workflow integration and data-centric precision medicine. 10x Genomics, based in Pleasanton, has carved a differentiated position through Chromium single-cell and spatial transcriptomics solutions, expanding the analytical scope beyond bulk sequencing into cellular and spatial context. Element Biosciences, in San Diego, has introduced the AVITI benchtop NGS platform, targeting high-throughput, cost-effective sequencing for laboratories seeking to optimize instrument capital efficiency. Ultima Genomics, operating from Fremont and Newark, has pushed the economics of large-scale genomics with high-throughput systems designed for population-scale applications.
Geographic and technology diversification is further reflected in the presence of BGI Group, through MGI Tech in Shenzhen, which offers DNBSEQ NGS platforms and sequencing solutions for whole-genome and targeted applications. QIAGEN, headquartered in Venlo, contributes through QIAseq NGS panels, library preparation, and hybrid capture technologies, embedding sequencing workflows into broader molecular diagnostic and research pipelines. Clear Labs, based in San Carlos, focuses on fully automated NGS platforms for rapid pathogen and oncology sequencing, addressing throughput and hands-on time constraints in high-volume environments. Tempus AI, located in Chicago, integrates whole-genome sequencing assays with an AI-driven precision medicine platform, illustrating how sequencing data is increasingly coupled with computational inference to guide clinical decision-making.
This competitive mosaic matters because platform selection is rarely a purely technical decision. It encompasses service availability, bioinformatics support, consumable supply reliability, regulatory positioning, and the strategic alignment of a vendor's roadmap with a buyer's application pipeline. Our analysis evaluates how these factors interact across procurement cycles and how incumbents and challengers are repositioning their offerings to capture specific workflow segments.
Regulatory and Standards Dynamics: Shaping the Pace of Adoption
Technology alone does not dictate market velocity. Regulatory frameworks and quality standards increasingly function as adoption accelerators or bottlenecks, particularly in clinical and food safety applications. In April 2026, the FDA distributed for comment a draft guidance on NGS-based methods for safety assessment of genome editing in human gene therapy products, supporting clinical trial initiation. This development signals a maturing regulatory posture toward sequence-based validation, with implications for both therapeutic developers and diagnostic platform providers.
Across the Atlantic, the European Commission adopted regulation 2025/179 requiring member states to perform whole-genome sequencing on isolates of specific foodborne pathogens, including Salmonella enterica, Listeria monocytogenes, Escherichia coli, Campylobacter jejuni, and Campylobacter coli, for outbreak investigations. Such mandates expand the public sector demand base and institutionalize sequencing as a routine epidemiological tool. In parallel, the ongoing development of ISO/DIS 22692 on genomics informatics and quality control metrics for DNA sequencing, with the standard under enquiry phase as of 2025, reflects a broader push toward standardized performance benchmarking and data interoperability.
Sanger Sequencing Service Market
For commercial strategists, these regulatory and standards signals carry direct operational implications. They influence validation timelines, shape procurement requirements, and affect cross-border market access. The report maps these developments against technology readiness and application adoption, helping organizations distinguish between transient compliance burdens and structural shifts in demand.
Strategic Priorities for 2026 and Beyond
The convergence of sustained market growth, platform competition, and regulatory evolution demands a disciplined approach to strategic planning. Our research highlights several priority areas for leadership teams evaluating their position in the sequencing ecosystem:
- Assessing whether existing or planned instrument portfolios align with the workflow economics of target applications, including throughput needs, consumable consumption patterns, and bioinformatics support requirements
- Monitoring how long-read, single-cell, and spatial approaches are moving from specialized use cases into broader clinical and translational pipelines, and identifying where integration costs may create entry barriers or partnership opportunities
- Evaluating the strategic significance of automation and AI-enabled interpretation, particularly as sequencing volume scales and data interpretation becomes a more binding constraint than data generation
- Preparing for regulatory-driven demand expansion in public health, food safety, and gene therapy assessment, while calibrating compliance investment against realistic adoption horizons
- Understanding concentration dynamics and the implications for supply continuity, pricing negotiation leverage, and the risk of technology lock-in as platform ecosystems mature
These priorities are interdependent. A procurement decision influences workflow agility; a partnership choice affects data integration capabilities; a regulatory preparation strategy shapes long-term market access. The report provides a structured framework to evaluate these trade-offs in a unified manner, enabling more coherent strategy formulation across R&D, commercial, and compliance functions.
Access the Full Intelligence Landscape
The DNA sequencing market is entering a phase where competitive advantage will increasingly derive from the ability to integrate technology selection, application focus, regulatory readiness, and data strategy into a coherent operating plan. Aggregate growth figures provide context, but durable strategy requires deeper segmentation, scenario analysis, and competitive benchmarking. This research is designed to bridge that gap, offering the granularity needed to support capital allocation, product planning, and market entry decisions throughout the forecast period.
For executives and analysts seeking to move beyond high-level trends and into actionable market intelligence, the full report delivers detailed segmentation analysis, competitive profiles, regulatory impact assessment, and forecast scenarios built for corporate decision-making. The complete dataset, methodology documentation, and strategic recommendations are available through our official research portal, where the full depth of the analysis can be reviewed and applied to your specific strategic context.
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Band Saw Blade Market Hits $1.75B in 2025, Projected 5.5% CAGR to $2.53B by 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Next Seven Years: Navigating the Band Saw Blades Market (2026–2032)
Powering Precision Manufacturing Through Measurable Growth
The global band saw blades market stands at a decisive inflection point. Over the historical review period from 2020 to 2025, the sector demonstrated remarkable resilience, advancing from a baseline of approximately $1,500 million to an estimated $1,750 million in the most recent base year. As manufacturing enterprises recalibrate their capital allocation strategies for the forecasted 2026–2032 horizon, our latest comprehensive market study delivers the analytical clarity required to transform macroeconomic tailwinds into competitive advantage. With a projected compound annual growth rate of 5.5 percent, the market is on a clear trajectory toward sustained expansion, driven by intensifying industrial automation, resurgence in heavy structural fabrication, and evolving material-handling requirements across both traditional and emerging end-use verticals.
This executive overview serves as a strategic preamble to our full research publication. It outlines the market mechanics, competitive architecture, and operational variables that will define procurement, product development, and market-entry decisions throughout the forecast period. While the headline trajectory points to unambiguous growth, the true strategic value lies beneath the surface—in the nuanced interplay between material cost volatility, regulatory compliance frameworks, regional supply chain realignments, and the rapid productization cycles of incumbents. Decision-makers who understand these underlying dynamics will be best positioned to optimize inventory strategies, negotiate supplier contracts, and capture margin expansion in an increasingly concentrated industry landscape.
Market Trajectory and the Strategic Imperative for 2026
The seven-year forward projection maps a clear acceleration phase. Following a modest contraction observed in 2023 that reflected broader industrial slowdowns and post-pandemic supply normalization, the market rebounded forcefully. The 2024–2025 recovery established a new operational baseline, and the forecast extends this momentum through 2032. By the close of the projection window, total market revenue is expected to approach the $2,500 million threshold. This trajectory is not merely a numerical exercise; it signals a structural shift in how manufacturers specify cutting tooling, evaluate total cost of ownership, and balance performance against operational safety requirements.
For procurement leaders and strategic planners, the 2026 decision window is particularly critical. Capital-intensive projects initiated this year will lock in tooling specifications and supplier relationships well into the late 2020s. Early movers who align their procurement roadmaps with the forecasted growth corridors can secure favorable pricing, mitigate raw material exposure, and establish long-term service-level agreements before capacity constraints tighten. Conversely, organizations that treat band saw blades as commoditized consumables risk margin erosion and operational downtime as premium-grade tooling becomes increasingly differentiated by material science, tooth geometry optimization, and application-specific engineering.
Our research translates these macro projections into actionable planning frameworks. The report maps growth vectors against production capacity expansions, raw material sourcing strategies, and regional demand shifts, enabling executives to stress-test their five-year operating plans against multiple scenario assumptions. By focusing on the structural drivers rather than transient pricing fluctuations, organizations can build procurement and supply chain strategies that remain robust across cyclical variations.
Competitive Architecture and Strategic Positioning
The band saw blades market is characterized by a concentrated competitive environment where scale, material expertise, and application-specific innovation act as primary differentiators. Our analysis identifies a clear tier of market leaders whose combined footprint shapes pricing dynamics, technology roadmaps, and channel access. Understanding how these players position themselves is essential for both incumbents defending share and new entrants evaluating market entry pathways.
Worldwide Welded Band Saw Blades Market
European manufacturers continue to anchor the high-precision segment, leveraging deep metallurgical heritage and established global distribution networks. WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG, headquartered in Spangenberg, Germany, remains Europe’s largest dedicated band saw blade manufacturer, delivering precision metal-cutting solutions backed by an expansive international sales infrastructure. Their recent activity underscores a deliberate focus on large-scale industrial applications and continuous product innovation. In mid-2025, WIKUS secured a landmark deployment when its SKALAR X3000 band saw blade was selected for the world’s largest band saw, a machine engineered for workpiece capacities reaching 5,100 millimeters. This followed a strong exhibition presence at Blechexpo 2025, where the company showcased advanced solutions for industrial sheet metal processing, and a subsequent demonstration of cutting-edge sawing technologies at NORTEC 2026 in Hamburg. These milestones illustrate how leading European players are aligning product engineering with the most demanding heavy-industrial specifications.
On the North American front, premium engineering and heavy-duty fabrication expertise define the competitive posture. The L.S. Starrett Company, based in Athol, Massachusetts, maintains a strong reputation for bi-metal construction and optimized tooth geometry across metal, wood, plastics, and composite applications. The M. K. Morse Company, headquartered in Canton, Ohio, competes aggressively in the heavy structural steel and superalloy segments, emphasizing American-made production and carbide-tipped tooling for high-production environments. DoALL Company Inc. rounds out the U.S. lineup with a full-line industrial metal fabrication portfolio spanning bi-metal and carbide-tipped offerings. These manufacturers leverage stringent quality standards, domestic supply chain advantages, and application-specific engineering to command premium positioning in demanding fabrication sectors.
Specialized German producers and diversified international players further shape the competitive matrix. ARNTZ GmbH + Co. KG, operating from Remscheid, focuses on carbide-tipped and bi-metal blades for industrial metal and construction materials, with recent catalog expansions reinforcing their commitment to advanced carbide-tipped solutions. JN Eberle & Cie. GmbH, based in Augsburg, emphasizes precision and durability in specialized metal-cutting blades. Across the Atlantic, Bahco International in Sweden drives heavy-duty metal cutting with trimetal and bi-metal series, including the Easy-Cut Xtreme line. Pilana Metal s.r.o. in the Czech Republic extends the bi-metal and wood-cutting portfolio, while Simonds Saw and Steel Company maintains a strong presence across industrial and woodworking applications in the United States. In Asia, Dalian Special Steel Products Co. Ltd. has emerged as a notable supplier of bi-metal blades engineered for high-strength steel and industrial-grade requirements, reflecting the broader regional shift toward specialized tooling production.
With the top three players collectively accounting for approximately 65 percent of global revenue and the top five extending that share to 75 percent, market concentration is a defining strategic variable. This structure compresses the window for un differentiated market entry and elevates the importance of application-specific value propositions, regional distribution partnerships, and compliance-driven quality certifications. Our report dissects these competitive dynamics in granular detail, mapping market share trajectories, product portfolio overlaps, and strategic response patterns to help organizations identify white-space opportunities and anticipate competitive countermoves.
Segmentation Architecture: Application and Material Differentiation
Beneath the aggregate growth figures lies a highly differentiated segmentation landscape where material science and end-use requirements dictate pricing, performance benchmarks, and procurement cycles. The report deconstructs these segments without oversimplifying the trade-offs that manufacturing engineers and procurement teams must navigate.
Material composition remains the foundational axis of differentiation. Bi-metal blades capture the dominant share of the market, reflecting their balanced performance profile across general metal cutting, extended service life, and adaptive tooth geometry. Carbide-tipped variants occupy a high-value niche, favored for abrasive materials, hardened alloys, and high-production environments where reduced downtime and consistent cut quality justify elevated unit costs. Carbon steel and other specialized formulations address specific cost-sensitive or application-tailored requirements. The interplay between raw material availability, alloy pricing, and manufacturing yield directly influences segment-level margin structures. High-carbon strip steel serves as the primary input for band saw blades, with pricing subject to volatility driven by global steel supply dynamics. Simultaneously, supply chain disruptions and price fluctuations in high-speed steel alloys continue to pressure production economics for advanced tooling, making strategic sourcing and inventory buffering critical competencies.
Application-driven segmentation reveals complementary demand engines. Metal working remains the largest consumption basin, reflecting the breadth of fabrication, structural steel processing, and precision machining operations that depend on reliable band saw performance. Wood working sustains a steady, mature demand profile, while food processing applications introduce specialized hygiene, corrosion resistance, and regulatory compliance requirements that differentiate tooling specifications from traditional industrial segments. Additional niche applications span composite cutting, maintenance repair and overhaul operations, and specialty material processing. The report examines how these application verticals interact with regional manufacturing footprints, automation adoption rates, and end-market capital expenditure cycles, enabling readers to align product development roadmaps with the highest-value demand pockets.
We intentionally reserve the full breakdown of segment-level revenue contributions, exact regional distribution figures, and precise application share percentages for the complete dataset. This deliberate approach ensures that strategic readers engage with the complete analytical framework, where segmentation data is contextualized against pricing tiers, regional cost structures, and competitive density maps.
Regulatory, Operational, and Supply Chain Dynamics
Technical performance alone no longer determines competitive outcomes in the band saw blades market. Regulatory compliance, operational safety mandates, and supply chain resilience now function as strategic gates that shape market access, production planning, and procurement risk. Organizations that integrate these variables into their strategic planning will navigate the forecast period with greater agility and lower exposure to operational disruption.
Safety and quality standards impose non-negotiable operational disciplines. European and United States safety regulations mandate periodic inspection and tension testing for band saw blades to ensure operational safety across industrial environments. In parallel, ISO 9001 certification has become a baseline requirement for manufacturers seeking to maintain quality control in precision metal cutting, influencing supplier evaluation criteria, audit schedules, and contract eligibility. In Europe, CE marking compliance ensures that band saw blades and associated equipment meet industrial safety requirements for metal processing machinery, adding a layer of regulatory due diligence for both producers and end-users. These standards are not merely compliance checkboxes; they shape production workflows, documentation systems, and warranty structures, and they increasingly serve as proxies for supplier reliability in procurement scoring models.
Raw material and supply chain dynamics introduce continuous cost and availability uncertainty. The dependence on high-carbon strip steel and specialized high-speed steel alloys ties band saw blade economics to broader metallurgical market cycles. Geopolitical trade flows, energy cost fluctuations, and regional capacity constraints can trigger rapid input price shifts, which in turn affect finished blade pricing and margin stability. Manufacturers with vertically integrated sourcing, diversified supplier bases, and forward hedging strategies are better equipped to absorb volatility and protect competitive pricing. Procurement teams must therefore evaluate not only unit price and delivery lead times, but also supplier resilience, certification compliance, and exposure to upstream material constraints.
These dynamics create a strategic environment where differentiation is built on reliability, compliance assurance, and total cost of ownership rather than headline specifications alone. The complete report maps these operational and regulatory factors against regional market structures, enabling organizations to quantify compliance burden, assess supplier risk profiles, and align sourcing strategies with evolving safety and quality expectations.
What the Full Study Delivers: Methodology, Data Architecture, and Decision Frameworks
The complete Band Saw Blades Market research publication is engineered as a decision-support instrument rather than a static data repository. It integrates historical performance tracking, forward-looking demand modeling, competitive benchmarking, and operational scenario analysis into a cohesive analytical architecture. The methodology combines bottom-up segment evaluation, top-down macroeconomic correlation, and primary industry intelligence to produce a multi-layered view of market behavior across the 2026–2032 forecast window.
Readers gain access to a structured suite of analytical outputs designed for immediate strategic application. The report provides granular market sizing across historical and forecasted periods, enabling revenue projection alignment with internal planning cycles. It examines competitive positioning through company profiles, product portfolio mapping, and recent strategic developments, including trade fair activations, catalog expansions, and flagship product deployments that signal shifting technology priorities. It evaluates segmentation dynamics across material types, application verticals, and regional demand centers, contextualizing each segment within pricing structures, growth drivers, and competitive intensity. It also assesses the regulatory and raw material landscape, translating compliance requirements and supply chain variables into operational risk indicators and procurement planning parameters.
Band Saw Blades Market
To support scenario-based planning, the study incorporates sensitivity considerations around raw material pricing trajectories, capacity expansion timing, and regional demand variation. Rather than presenting a single deterministic forecast, the research equips decision-makers with the contextual ranges and structural drivers needed to test internal assumptions against realistic market behavior. This approach is particularly valuable for capital equipment manufacturers, tooling distributors, procurement departments, and investors evaluating exposure to industrial fabrication and metalworking end-markets.
Detailed regional revenue distributions, exact application share percentages, and precise segment-level monetary breakdowns are embedded within the complete dataset and interactive analytical modules. These elements are intentionally excluded from this executive preview to preserve the integrity of the full research offering and to ensure that strategic users access the complete contextual framework required for accurate market modeling.
Strategic Outlook: Securing Advantage in a Concentrated, Compliance-Driven Market
The band saw blades market entering 2026 rewards disciplined strategic positioning. Growth is real and structurally supported, but it is distributed unevenly across segments, regions, and competitive tiers. Organizations that succeed will be those that treat blade procurement and product development as strategic capabilities rather than transactional functions. That means aligning specification standards with application requirements, embedding compliance and safety expectations into supplier selection, and building sourcing strategies that can withstand raw material volatility without sacrificing performance or delivery reliability.
For incumbents, the priority is to protect premium positioning through continuous product innovation, certified quality systems, and application-specific engineering that raises switching costs for end-users. For distributors and channel partners, the opportunity lies in expanding technical advisory capabilities, bundling tooling with service and maintenance agreements, and strengthening regional inventory positioning to reduce lead-time risk. For new market entrants and investors, the concentrated competitive structure demands a clear value proposition—whether through specialized carbide-tipped applications, regional cost advantages, or differentiated service models—rather than head-on confrontation with established multi-product portfolios.
The full market study provides the analytical depth required to translate these strategic imperatives into concrete action plans. By combining historical trajectory validation, forward growth modeling, competitive benchmarking, and operational risk mapping, the research equips leadership teams with the intelligence needed to allocate capital, negotiate supplier relationships, and prioritize product development where margin and market position can be defended or expanded.
Contact and Access
This executive preview has outlined the strategic architecture of the global band saw blades market and the decision-critical variables that will shape the 2026–2032 forecast period. The complete research publication extends this foundation with full market sizing, detailed segmentation analysis, comprehensive competitive profiling, and scenario-based planning frameworks tailored for executive, procurement, and investment audiences. To access the complete dataset, interactive analytical tools, and company-level strategic assessments, please visit the PW Consulting research portal and request the full Band Saw Blades Market study. Our advisory team is available to discuss customized briefing sessions, data licensing options, and sector-specific applications of the research findings.
For detailed analysis of this topic, please visit the official page: Band Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tire Changers Market Hits $1,470.8M in 2025, Earmarks 6.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Turn: Navigating the Tire Changers Market in 2026
The global automotive service equipment sector is entering a critical phase of expansion, driven by an increasingly complex landscape of vehicle technologies, regulatory frameworks, and shifting consumer demands. For enterprise decision-makers, fleet operators, and industry investors, understanding the trajectory of the Tire Changers Market is no longer a niche analytical exercise—it is a strategic imperative. Our latest comprehensive market research report on the Tire Changers Market delivers a forward-looking intelligence framework designed to guide capital allocation, product development, supply chain strategy, and competitive positioning through the forecast horizon of 2026 to 2032.
This introductory overview outlines the strategic architecture of the study, highlights the macro-level dynamics reshaping industry value chains, and demonstrates how granular, actionable insights can be leveraged to outmaneuver competitors in an environment defined by rapid technological iteration and evolving compliance mandates. The following analysis is structured to provide executives with a clear appreciation of the report's methodological rigor, its practical utility, and the specific decision-making advantages it offers.
Tire Changers Market
Market Trajectory and Structural Expansion Drivers
Historical performance data reveals a consistent and accelerating growth pattern across the global tire changer market. Over the observation window from 2020 through 2025, total market revenue has climbed steadily, reflecting sustained demand from both retail service networks and commercial fleet maintenance operations. The base year valuation for 2025 establishes a substantial baseline, which our forecasting models project will expand at a compound annual growth rate of 6.8 percent through 2032. This trajectory translates into significant revenue escalation, with the market anticipated to reach new financial milestones by the end of the forecast period.
Several structural forces underpin this expansion. The ongoing transition toward increasingly specialized tire architectures—including run-flat compounds, reinforced commercial truck tires, and high-performance winter formulations—has elevated the technical requirements for safe and efficient tire mounting and dismounting. Service centers and fleet maintenance facilities are consequently investing in equipment that can handle non-standard wheel dimensions, reinforced bead structures, and low-profile assemblies without risking damage to costly rims or compromising technician safety. Simultaneously, the proliferation of electric vehicle platforms, while altering powertrain maintenance profiles, has not diminished tire rotation and replacement demand; instead, it has shifted operational focus toward specialized service bays equipped with precision handling tools.
Supply chain normalization following recent global disruptions has further accelerated equipment procurement cycles, although new trade policy interventions are actively reshaping sourcing strategies. Manufacturers and procurement leaders must now navigate a landscape where import duty structures, regional manufacturing incentives, and localized content requirements are becoming decisive factors in total cost of ownership calculations. These dynamics are not peripheral; they are central to understanding where value will accrue across the market over the next seven years.
Segmentation Architecture and Operational Deployment Patterns
The market's value distribution is inherently multifaceted, reflecting divergent operational priorities across service environments, geographic territories, and equipment complexity tiers. Our analysis dissects these variation patterns to reveal where demand intensity is concentrated and how procurement preferences are evolving.
Across geographic territories, regional demand profiles are heavily influenced by fleet density, service center modernization rates, and local regulatory environments. Established automotive service markets with mature dealer networks and high vehicle parc densities continue to anchor significant portions of equipment procurement, while emerging service ecosystems are experiencing accelerated modernization as independent garages and fleet operators upgrade aging infrastructure. Each territory presents distinct purchasing rhythms, compliance expectations, and competitive intensity levels that require localized strategic responses rather than one-size-fits-all deployment models.
Equipment typology segmentation reveals a clear spectrum of technological adoption. Fully automated solutions are capturing growing share among high-throughput commercial facilities and premium service centers seeking to minimize labor intensity and standardize operational outcomes. Semi-automatic configurations maintain strong relevance for mid-tier operations balancing throughput requirements with budget constraints and workflow flexibility. Manual equipment continues to serve specialized repair contexts and cost-sensitive segments, though its proportional footprint is gradually compressed as automation capabilities become more accessible and demonstrable return-on-investment cases strengthen. The interplay between these categories is not merely a function of price; it is driven by labor availability, training infrastructure, throughput expectations, and the increasing technical demands of contemporary tire assemblies.
Application-based segmentation further illuminates deployment priorities. Passenger vehicle service networks represent the largest demand pool, reflecting high vehicle volumes and frequent tire rotation and replacement cycles. Commercial vehicle service applications follow as a substantial and strategically critical segment, where equipment reliability, uptime preservation, and compliance with heavy-duty maintenance standards carry heightened operational and financial consequences. Additional application verticals, including motorcycle service, specialty fleet maintenance, and regional mobility operations, contribute differentiated demand signatures that reward operators who can align equipment specifications with niche workflow requirements.
Competitive Landscape and Strategic Positioning
The competitive architecture of the tire changers market is characterized by a mix of established engineering-led manufacturers, specialized regional producers, and globally distributed equipment suppliers. Market concentration metrics indicate that a relatively compact group of leading firms commands a substantial share of total industry revenue, reflecting the capital intensity of product development, the importance of service and warranty infrastructure, and the value placed by commercial buyers on equipment reliability and dealer support networks.
Hunter Engineering Company, headquartered in Bridgeton, Missouri, continues to reinforce its market position through a sustained cadence of product innovation. Recent launches underscore a strategic emphasis on hybrid leverless mount head technology, enhanced inflation systems such as FastBlast™, and design configurations that address increasingly challenging tire profiles. The introduction of the Maverick® Pro and TCX53Pro models exemplifies a focus on torque delivery, speed optimization, and versatile mounting architectures that accommodate both center-clamp and swing-arm operational preferences. Concurrently, Coats Company, LLC, based in LaVergne, Tennessee, has advanced its commercial fleet serving capabilities by integrating high-pressure bead loosening systems, polymer and nylon duckhead configurations, and recently expanded steel jaw compatibility for 17.5-inch and 19.5-inch commercial wheels. Its refreshed brand platform and smart shop solution initiatives signal a broader commitment to integrated service bay ecosystems.
BendPak Inc., operating from Denton, Texas, has strengthened its accessible professional-grade positioning through the APEX line, pairing tire changers with complementary lift and balancing equipment to offer bundled value propositions for cost-conscious professional shops. Hofmann Equipment, leveraging its position within Snap-on Incorporated's global subsidiary structure and German engineering heritage, emphasizes integrated wheel service platforms that combine tire changing functionality with balancers and alignment systems, appealing to facilities pursuing workflow consolidation. European and Asian manufacturers—including Cormach S.r.l. in Italy, Ravaglioli S.p.A., NEXION S.p.A., ACE MACHINE TOOLS CO., LTD in Suzhou, Derek Weaver Inc., and Atlas Automotive Equipment in the United States—contribute diverse product philosophies ranging from superautomatic garage-oriented solutions to touchless automatic configurations and variable-speed direct-drive designs. This multiplicity of strategic approaches creates a dynamic competitive environment where differentiation hinges on engineering precision, total cost of ownership, regional service density, and the ability to anticipate evolving tire and wheel architecture requirements.
Regulatory, Compliance, and Supply Chain Dynamics
Market participants are operating within an increasingly prescriptive regulatory environment that directly influences equipment specification, procurement timing, and operational risk management. In the United States, sweeping tariff interventions introduced in 2025 have placed new cost and sourcing considerations on imported automotive service equipment. A baseline blanket rate structure, followed by substantially higher country-specific duties for select nations, has prompted procurement teams to reevaluate international supply chains, consider domestic manufacturing alternatives, and weigh freight and tariff exposure in total acquisition cost models. These trade policy shifts are particularly relevant for organizations balancing equipment price sensitivity against long-term service reliability and parts availability.
Occupational safety and machine guarding requirements continue to shape equipment design expectations and facility compliance protocols. OSHA standards governing machine guarding, including provisions applicable to turntable mechanisms and bead breaker assemblies, mandate safeguards that preserve operator accessibility while mitigating injury risk. In commercial trucking and heavy-duty maintenance contexts, adherence to these standards intersects with CVSA out-of-service criteria and broader fleet safety programs, making equipment selection a direct contributor to downtime reduction and regulatory compliance. Tire changers deployed in these environments must demonstrably satisfy guarding, trip hazard prevention, and operational safety expectations without compromising servicing efficiency.
Raw material sourcing strategies also carry growing strategic weight. Manufacturers emphasizing domestically sourced steel construction and vertically integrated component fabrication are positioning themselves as resilience-oriented alternatives in an environment where supply continuity, pricing stability, and compliance documentation are increasingly scrutinized by institutional buyers. These considerations are not isolated procurement details; they are becoming embedded in vendor qualification frameworks and long-term service contract negotiations.
Report Methodology and Actionable Intelligence Framework
Our Tire Changers Market research study is engineered to translate complex market signals into structured, decision-ready intelligence. The report integrates historical performance analysis, forward-looking forecasting, segmentation mapping, and competitive profiling into a unified analytical model. Methodological rigor is maintained through multi-source data triangulation, demand-side validation, supply-side capacity assessment, and scenario-based sensitivity testing to ensure that conclusions remain robust across varying macroeconomic and regulatory conditions.
The study provides detailed examination of equipment type evolution, application-specific deployment trends, and regional procurement behavior, while deliberately avoiding oversimplified aggregation that would obscure the operational nuances practitioners need. Competitive profiling extends beyond product catalogs to assess strategic positioning, innovation cadence, service infrastructure depth, and responsiveness to regulatory and trade policy shifts. Recent product launch activity, brand platform refreshes, and technical enhancement timelines are contextualized within broader market momentum to distinguish transient promotional activity from enduring strategic direction.
Operational utility is prioritized throughout. Readers will find structured guidance on evaluating equipment automation levels against throughput requirements, aligning procurement specifications with compliance mandates, assessing vendor reliability and regional support coverage, and anticipating demand shifts driven by tire technology evolution and fleet composition changes. The analytical architecture is designed to support capital investment justification, product portfolio planning, market entry evaluation, and competitive benchmarking with clarity and precision.
Strategic Implications for 2026 Decision-Making
As organizations prepare their operational and investment agendas for 2026 and beyond, the Tire Changers Market presents both opportunity and complexity. Growth trajectory is clear, but the distribution of value will increasingly favor participants who can align equipment capabilities with evolving service demands, navigate trade and compliance constraints intelligently, and differentiate through engineering reliability and integrated workflow support. Decision-makers who possess granular visibility into segmentation performance, competitive movement, and regional procurement behavior will be better positioned to time acquisitions, shape product development roadmaps, and engage vendors from a position of informed leverage.
This market research report is designed to deliver that visibility. It provides the analytical depth required to move beyond surface-level market narratives and the structured intelligence necessary to support high-stakes strategic choices. To access the complete dataset, detailed segmentation breakdowns, full competitive profiles, and scenario-based forecasts, we invite you to explore the full report through our official publication channel. The comprehensive intelligence contained within will equip your organization to navigate the tire changers market with confidence, precision, and strategic advantage.
Worldwide Tool Changers Market
For detailed analysis of this topic, please visit the official page: Tire Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MMA Market to Reach $272.5M by 2032, Driven by 7.9% CAGR & Automotive Demand
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Global Methyl Methacrylate Market: Insights for 2026 Decision-Makers
Executive Perspective
The global Methyl Methacrylate (MMA) market stands at a critical inflection point as industries navigate renewed supply chain realignments, evolving sustainability mandates, and shifting end-use demand patterns. For corporate strategists, procurement leaders, and investment committees operating in 2026, access to granular, forward-looking intelligence is no longer a discretionary advantage—it is a baseline requirement for capital allocation, capacity planning, and competitive positioning. PW Consulting’s latest comprehensive market research on the MMA sector delivers precisely this operational clarity, translating multi-year historical trajectories and decade-long projections into actionable frameworks tailored for executive decision-making.
This report is engineered to serve as a strategic compass rather than a static data repository. It maps the structural forces reshaping methacrylate economics, evaluates the competitive postures of incumbent producers and emerging challengers, and isolates the regulatory, technological, and macroeconomic variables that will dictate margin resilience through the end of the decade. Readers will find a meticulously calibrated analysis that balances quantitative rigor with qualitative industry context, enabling organizations to stress-test their 2026 portfolios against realistic supply-demand scenarios and pricing trajectories.
Market Architecture and Forward Trajectory
The MMA market has demonstrated consistent expansion across the historical review window, transitioning from a base of approximately $113.25 million in 2020 to an estimated $162.50 million by 2025. This upward trajectory reflects sustained downstream consumption, incremental capacity optimization, and the material’s entrenched role across high-growth industrial verticals. Looking ahead, the forecast horizon through 2032 projects continued expansion at a compound annual growth rate of 7.9 percent, positioning the market to reach $272.50 million by the terminal forecast year.
Such growth is neither uniform nor automatic. The forecast model accounts for regional production realignments, feedstock volatility, and the gradual integration of lower-carbon manufacturing pathways that are beginning to redefine cost structures. Strategic buyers and producers alike must recognize that aggregate growth figures mask divergent local dynamics, differential adoption rates across application segments, and the compounding effects of geopolitical trade flows. Our analysis disentangles these layers, providing decision-makers with a nuanced view of where volume expansion will materialize, which supply corridors will experience tightness, and how pricing momentum is likely to evolve as production costs and capacity utilization intersect.
Competitive Landscape and Strategic Positioning
The MMA industry remains highly concentrated, with a small cohort of globally integrated producers commanding the majority of installed capacity and downstream distribution networks. Consolidated market dynamics mean that pricing power, technology licensing, and strategic capacity announcements frequently ripple across the entire value chain. Understanding the operational footprint, technological orientation, and recent corporate maneuvers of these key players is essential for evaluating supply security, negotiating long-term contracts, and anticipating market-wide price signals.
The competitive field is anchored by several prominent organizations whose strategic initiatives directly shape market equilibrium. Röhm GmbH has been executing a deliberate production footprint transformation, transitioning from legacy Gulf Coast capacity toward its newly commissioned ethylene-based LiMA MMA facility in Bay City, Texas. This plant has now achieved full industrial-scale operation, with all four reactors running at planned throughput, reinforcing North American supply resilience while introducing a lower-carbon manufacturing route that integrates chemical recycling for closed-loop operations. Concurrently, the company has adjusted its regional pricing architecture, implementing immediate increases for its MERACYL® MMA product line across Asian markets outside mainland China, reflecting both cost pressures and localized supply-demand rebalancing.
Mitsubishi Chemical Corporation maintains its position as the world’s largest producer of methacrylates and MMA, operating extensive production infrastructure with cumulative capacity exceeding 1.2 million tons annually. Despite this scale advantage, the company’s recent portfolio decisions—including the discontinuation of a planned 350,000 ton/year MMA monomer facility in Louisiana—signal a more selective approach to greenfield expansion, emphasizing capital efficiency and regional demand alignment over undifferentiated capacity additions. BASF SE continues to function as an integrated supplier across coatings, adhesives, and polymethyl methacrylate (PMMA) applications, leveraging its broader chemical ecosystem to stabilize supply and cross-sell derivative solutions. Dow Inc. has similarly reinforced its North American manufacturing presence, directing investment toward capacity expansions that align with regional downstream demand and feedstock availability.
European and Asian producers further diversify the competitive matrix. Arkema S.A. has prioritized sustainable production methodologies for coatings and advanced materials, while Sumitomo Chemical Co., Ltd. has formalized a dedicated MMA division to better serve electronics and automotive end markets. Asahi Kasei Corporation continues to emphasize high-performance acrylic materials spanning automotive, construction, and optical applications. Chi Mei Corporation supplies PMMA sheets and compounds across signage, electronics, and construction verticals, and Evonik Industries AG maintains a specialized focus on methacrylate derivatives and sustainable PMMA formulations. Huntsman Corporation rounds out the field as a broad-spectrum supplier of MMA-based solutions for coatings, adhesives, and polyurethane systems, supported by a globally distributed distribution network.
Capacity Realignment and Operational Shifts Driving Market Dynamics
The competitive equilibrium is being actively reshaped by a series of high-impact operational decisions that have unfolded over the past 24 months. These moves are not isolated corporate restructuring events; they represent structural recalibrations of regional supply corridors, technological pathway selection, and portfolio prioritization that will influence pricing volatility, availability, and contract negotiation leverage throughout the forecast period.
Capacity consolidation and technology substitution have emerged as dominant themes. Röhm’s phased closure of its 250,000 ton Westwego, Louisiana facility, synchronized with the ramp-up of its Bay City ethylene-based plant, illustrates a broader industry migration toward integrated, lower-emission production routes. This transition carries direct implications for regional supply balances, logistics costs, and the cost base of North American MMA availability. Simultaneously, Kuraray Co., Ltd. has executed a strategic contraction in its methacrylic resin sheet manufacturing operations in China, transferring subsidiary control as part of its PASSION 2026 portfolio optimization plan. This follows an earlier halving of its domestic Japanese MMA production capacity from 67,000 tons per year and the cessation of external sales, effectively reducing marketplace volumes and signaling a retreat from commoditized exposure in favor of higher-margin specialty positioning.
Poly Methyl Methacrylate (PMMA) Market
These realignments intersect with broader market signals. Global MMA pricing exhibited upward momentum during the first quarter of 2026, accelerating toward the quarter’s end as supply tightened and production costs climbed. For procurement teams and downstream converters, this environment demands more sophisticated hedging strategies, multi-sourcing architectures, and closer coordination with suppliers whose technological transitions may temporarily constrain flexibility. For producers, the same dynamics raise critical questions about capacity utilization, maintenance scheduling, and the timing of price adjustments across different geographic markets.
End-Use Demand Ecosystems and Application Drivers
Sustained MMA consumption is anchored by a diversified application base that spans high-volume industrial sectors and specialized performance markets. Automotive demand remains a primary growth engine, driven by lightweighting initiatives, exterior and interior surface specifications, and the material’s compatibility with advanced coating and molding processes. Construction continues to represent a substantial consumption pillar, fueled by architectural glazing, translucent panels, and durable finishing systems that leverage PMMA’s optical clarity and weather resistance.
The electronics sector has emerged as an increasingly strategic demand center, with MMA-derived materials supporting display components, protective housings, and precision manufacturing requirements. Medical applications, while smaller in aggregate volume, contribute high-value demand streams tied to diagnostic equipment, fluid handling components, and biocompatibility-grade formulations. Each of these application verticals operates with distinct cost sensitivities, regulatory environments, and substitution risks. Our report maps how demand intensity is evolving within each segment, identifying the specific catalysts that will accelerate or moderate consumption growth, the interplay between end-market cyclicality and MMA procurement cycles, and the implications for producers seeking to align capacity specialization with downstream value creation.
Geographic Supply Corridors and Regional Rebalancing
Regional market dynamics are undergoing meaningful restructuring as production footprints shift, trade patterns adapt, and local demand profiles diverge. North American supply chains are being reconfigured around new ethylene-based production investments and the retirement of legacy capacity, altering the regional cost basis and availability calculus. European markets continue to navigate energy cost variability and sustainability-driven formulation requirements, prompting both supply optimization and demand-side innovation. The Asia Pacific region remains a central consumption hub, with localized pricing adjustments, supplier network recalibration, and evolving regulatory expectations shaping procurement strategies across multiple sub-markets. Latin American and Middle East/Africa corridors present distinct opportunity sets tied to infrastructure development, industrial modernization, and import dependency patterns.
Methyl Methacrylate (MMA) Market
Importantly, regional analysis cannot be reduced to simple volume comparisons. Pricing differentials, freight economics, tariff structures, and the proximity of integrated feedstock sources all influence the effective competitiveness of MMA supply in each geography. Our research evaluates these intersecting variables to help stakeholders identify which corridors present the most favorable risk-adjusted access, where supply interruptions are most likely to emerge, and how regional capacity additions will interact with existing demand centers over the forecast window.
Regulatory, Sustainability, and Technology Vectors
The MMA market is increasingly shaped by forces that extend beyond traditional supply-demand economics. Sustainability mandates, carbon intensity expectations, and chemical recycling integration are moving from peripheral considerations to core operational priorities. Producers that can demonstrate lower lifecycle emissions, closed-loop material flows, and transparent ESG reporting are gaining negotiating advantages with downstream customers who face their own Scope 3 reduction targets and brand-level sustainability commitments.
Technological differentiation is becoming a structural competitive lever. The transition toward C2-based production pathways, as exemplified by recent large-scale plant commissioning, illustrates how process innovation can simultaneously address cost efficiency, emissions reduction, and supply reliability. At the same time, regulatory developments and corporate portfolio optimization decisions—such as the discontinuation of certain greenfield projects and the strategic scaling back of external sales in specific regions—reflect a more disciplined approach to capital deployment. These shifts suggest that future market growth will be delivered not merely through volume expansion but through selective capacity modernization, application-specific specialization, and tighter alignment between production technology and end-market performance requirements.
What This Report Delivers for 2026 Strategy
PW Consulting’s MMA market research is designed to convert complex industry signals into executable strategic insight. The study provides a comprehensive mapping of historical performance, forward-looking volume and revenue projections, competitive positioning assessments, and application-side demand analysis. It integrates real-time operational developments—including plant ramp-ups, capacity closures, pricing actions, and portfolio restructuring events—into a cohesive analytical narrative that supports scenario planning and risk evaluation.
Key components of the report include:
- A quantified market trajectory spanning historical baseline years and a detailed forecast through 2032, with explicit attention to the growth drivers, constraints, and inflection points that will shape outcomes.
- Competitive profiling of leading global producers, examining capacity orientation, technological strategy, recent operational milestones, and the strategic implications of their market actions.
- Application-level demand analysis that isolates the consumption dynamics, growth catalysts, and substitution risks across automotive, construction, electronics, and medical end-use segments.
- Regional supply corridor assessment that evaluates production realignments, trade flow implications, and localized pricing momentum without relying on overly simplified aggregate comparisons.
- Integration of recent industry events—such as plant commissioning milestones, capacity rationalization moves, ESG reporting developments, and pricing adjustments—into a forward-looking strategic framework.
- Actionable recommendations for procurement strategy, supplier diversification, capacity planning, and investment prioritization in an environment characterized by concentrated supply, evolving cost structures, and sustainability-driven differentiation.
Why This Intelligence Matters Now
The 2026 operating environment demands more than retrospective market summaries. Organizations must anticipate how capacity transitions will affect regional availability, how pricing momentum will propagate through downstream supply chains, and where competitor strategy shifts will open or close competitive windows. The convergence of technology substitution, portfolio optimization, and sustainability expectations is compressing decision cycles and raising the cost of informational asymmetry. In this context, a rigorously constructed market study becomes a strategic asset, enabling leadership teams to move from reactive adjustment to proactive positioning.
This report is structured to support multiple functional audiences: corporate development teams evaluating market entry or expansion opportunities, procurement leaders designing resilient sourcing architectures, finance and investment committees stress-testing volume and margin assumptions, and operational executives aligning production or conversion strategies with anticipated supply conditions. By synthesizing quantitative forecasts, competitive intelligence, and event-driven market context, the analysis provides a unified reference point for cross-functional alignment.
Next Steps for Strategic Readers
The full scope of this research extends well beyond the market-level trajectory and competitive overview presented here. Detailed segmentation analysis, granular regional assessments, application-specific demand modeling, and comprehensive supplier benchmarking are integrated into the complete study to support precise strategic planning. Organizations that require defensible assumptions for capacity investments, contract negotiations, or portfolio reallocation will find the full dataset and accompanying analytical commentary essential to validating their decision frameworks.
To access the complete market intelligence, including all segmentation detail, regional breakdowns, competitive profiles, and forward-looking scenario analysis, please visit the official PW Consulting report page. The full study is structured to serve as a living strategic reference, enabling teams to translate macro-level trends into targeted operational actions throughout the 2026–2032 forecast horizon.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Stabilizer Bar Market Hits $3.63B in 2025, Projects 5.3% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Horizons in the Automotive Stabilizer Bar Market: A 2026 Decision-Maker's Guide
The automotive suspension landscape is undergoing a structural transformation, driven by the dual imperatives of vehicle electrification and stringent safety regulations. For executives and strategic planners operating within the automotive supply chain, understanding the trajectory of the stabilizer bar market is no longer optional—it is a critical component of risk management and opportunity capture. The Automotive Stabilizer Bar Market report by PW Consulting provides a comprehensive navigational chart for this complex terrain, offering data-driven insights designed to inform capital allocation and product development strategies through 2032.
As the industry pivots from internal combustion engines to electric powertrains, the demand characteristics for passive safety components are shifting. This report serves as an essential intelligence tool, bridging the gap between historical performance and future forecasting. By analyzing the market from a base year of 2025 through a forecast period extending to 2032, stakeholders can anticipate supply chain disruptions, regulatory impacts, and competitive maneuvers that will define the next decade of automotive manufacturing.
Worldwide Automotive Stabilizer Bar Link Market
Executive Summary of Market Trajectory
The global market for automotive stabilizer bars has demonstrated resilience and steady growth over the past five years. Historical analysis from 2020 to 2025 reveals a consistent upward trend in revenue, reflecting the sustained demand for vehicle stability and safety systems across major automotive producing nations. The market size, measured in USD Million, has expanded significantly as vehicle production volumes recovered from pandemic-era disruptions and safety mandates tightened globally.
Looking forward, the forecast period from 2026 to 2032 projects a Compound Annual Growth Rate (CAGR) of 5.3. This growth rate indicates a mature yet expanding market where innovation rather than volume alone will drive value. The projected revenue trajectory suggests that while the market is not experiencing explosive volatility, the cumulative value creation over the forecast horizon represents a substantial opportunity for well-positioned manufacturers. The transition from 2025 baseline figures to the 2032 endpoint underscores the importance of long-term capacity planning and investment in lightweight materials.
This growth is not uniform across all segments. The report delineates how different vehicle types and regional manufacturing hubs contribute to this aggregate figure. Understanding the macro-level movement allows executives to calibrate their expectations for revenue growth against the backdrop of broader economic conditions, including raw material price fluctuations and geopolitical supply chain constraints.
Segmentation Landscape and Material Dynamics
Type and Application Segmentation
The market is structurally divided by stabilizer bar type and vehicle application, each presenting unique value propositions and manufacturing challenges. The report provides a detailed breakdown of solid, hollow, splined, and tubular stabilizer bars, analyzing how engineering requirements differ between passenger comfort and heavy-duty durability. Hollow bars, for instance, are gaining traction in segments where weight reduction is prioritized, while solid bars remain critical for applications requiring maximum rigidity and load-bearing capacity.
In terms of application, the distinction between passenger cars and commercial vehicles is vital. Passenger cars continue to represent the largest volume share, driven by consumer safety expectations and regulatory compliance. However, the commercial vehicle segment offers distinct growth vectors, particularly as fleet operators seek to improve fuel efficiency and cargo stability. The report explores how these application segments interact with regional manufacturing capabilities, highlighting where demand is most concentrated and where supply gaps may emerge.
Material Shifts and Raw Material Volatility
Material composition remains a pivotal factor in stabilizer bar manufacturing. Steel stabilizer links, including high-strength steel grades and ductile iron variants, maintain a dominant market share, reflecting mature manufacturing processes and proven performance reliability. However, the industry is witnessing a gradual shift toward aluminum and composite materials, particularly in scenarios where weight reduction directly correlates with energy efficiency.
This shift is not without risk. Aluminum prices fluctuate significantly, often ranging 15-25% annually based on global supply-demand dynamics and geopolitical factors affecting mining and refining operations. For procurement managers and CFOs, this volatility introduces a layer of complexity to cost forecasting. The report examines how leading manufacturers are hedging against these material risks and whether the premium for lightweight materials is justified by the total cost of ownership benefits in electric vehicle platforms.
Regional Dynamics and Regulatory Drivers
Geographic segmentation reveals distinct growth patterns across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate data provides a high-level view of market distribution, the strategic value lies in understanding the local drivers propelling demand in each region. Asia Pacific, for instance, continues to be a critical hub due to high vehicle production volumes, while North America and Europe are driven more by replacement markets and stringent safety regulations.
Regulatory frameworks are acting as accelerators for market innovation. In Europe, Euro 7 regulations are driving continuous suspension system innovation, including lightweight and smart stabilizer link designs. Furthermore, EU emissions regulations targeting aggressive average fleet emissions levels by 2025 are accelerating the adoption of lightweight suspension components. These regulatory pressures are not merely compliance hurdles; they are strategic levers that force manufacturers to innovate faster than competitors who may be slower to adapt.
In the United States, government procurement activities also signal market vitality. Recent solicitation notices for fleet sustainment indicate ongoing demand for robust suspension components in defense and logistics applications. Such public sector engagements provide a stable demand floor for manufacturers capable of meeting specific government specifications and durability standards.
Competitive Landscape and Strategic Moves
The market concentration is characterized by a mix of global tier-1 suppliers and specialized manufacturers. The report analyzes the Competitive Rivalry among key players, noting that the top three companies hold a combined market share of approximately 32.5%, while the top five control around 45.2%. This fragmentation suggests that while large players dominate, there is sufficient room for niche specialists to thrive, particularly those offering differentiated technology or superior regional service networks.
Profile of Key Industry Players
The competitive arena includes established automotive giants and focused component manufacturers, each pursuing distinct strategies to secure market position:
- ZF Friedrichshafen AG: A major provider of integrated solid and hollow automotive stabilizer bars and links, including active damping variants for passenger and commercial vehicles. ZF continues to leverage its integrated systems approach to offer complete suspension solutions.
- thyssenkrupp AG: Producing hollow and solid stabilizer bars with a focus on lightweight aluminum and high-strength steel variants for OEMs. Their recent product launches demonstrate a commitment to material innovation for electric vehicles.
- Sogefi Group: Specializing in solid and hollow stabilizer bars and links for suspension systems in automotive and heavy-duty applications, maintaining a strong presence in Europe and emerging markets.
- Mubea Group: Manufactures precision stabilizer bars and links used in passenger cars, light trucks, and commercial vehicles, emphasizing lightweight engineering and structural integrity.
- Kongsberg Automotive: Manufactures solid and hollow stabilizer bars and links for OEM integration in passenger cars and light commercial vehicles, focusing on high-quality Nordic engineering standards.
- Tinsley Bridge Group: Produces solid and hollow stabilizer bars and links for OEM and aftermarket passenger and commercial vehicle suspension, bridging the gap between original manufacturing and service parts.
- ADDCO Manufacturing Company: Offers aftermarket solid stabilizer bars and links with polymer bushings for performance and standard automotive applications, catering to the enthusiast and repair market.
- SwayTec: Manufactures solid and hollow stabilizer bars and links for performance-oriented automotive and truck applications, targeting niche segments where handling characteristics are paramount.
Recent Strategic Developments
Recent activities among these key players highlight the dynamic nature of the market. In November 2025, ZF Friedrichshafen AG formed a joint venture with Wolong Electric Group Co., Ltd. to manufacture electric motors for driveline and stabilizer systems, signaling a move toward tighter integration of powertrain and suspension technologies.
Similarly, thyssenkrupp Automotive Technology launched a new high-strength aluminum stabilizer bar series for electric vehicles in March 2025, directly addressing the weight concerns associated with EV platforms. In April 2025, Federal-Mogul LLC introduced a new line of corrosion-resistant stabilizer bars with advanced surface treatment for harsh climates, expanding the addressable market for vehicles operating in extreme environments. These product launches and partnerships illustrate how competitors are actively reshaping the value chain to capture emerging opportunities.
Strategic Value for 2026 Decision-Making
For corporate strategists, procurement leaders, and investors, the primary value of this report lies in its ability to convert raw data into actionable intelligence. The period of 2026 represents a inflection point where historical trends meet new regulatory realities. Decision-makers need to understand not just where the market has been, but where the friction points and growth accelerators will be located over the next seven years.
Investment in capacity expansion, for example, must be timed correctly. Overinvesting in steel-based production lines while the market gradually shifts toward aluminum or hybrid solutions could lead to stranded assets. Conversely, waiting too long to adopt lightweight technologies could result in a loss of competitiveness in regions with strict emissions targets. The report provides the analytical framework to evaluate these trade-offs.
Automotive Stabilizer Bar Market
Supply chain resilience is another critical area. With raw material prices subject to significant volatility and geopolitical tensions affecting trade flows, understanding the regional concentration of supply and demand is essential. The report details how regions like Asia Pacific interact with North American and European demand centers, allowing supply chain managers to optimize logistics and inventory strategies.
Furthermore, the competitive intelligence provided allows companies to benchmark their performance against peers. By understanding the strategic moves of competitors like ZF, thyssenkrupp, and Sogefi, organizations can anticipate market shifts and adjust their own R&D pipelines accordingly. Whether a company is looking to enter the market, expand its footprint, or divest from underperforming segments, the segmentation data provides the necessary granularity to support these decisions without relying on guesswork.
Conclusion: Navigating the Future
The Automotive Stabilizer Bar Market is poised for steady evolution rather than disruptive revolution. The 5.3 CAGR projected through 2032 suggests a environment where operational excellence and technological adaptation will determine market leadership. The dominance of steel materials remains a baseline, but the pressure to reduce weight for electrification and emissions compliance is creating new niches for aluminum and advanced composites.
Regulatory pressures in Europe and procurement demands in North America will continue to shape production standards. Meanwhile, the competitive landscape remains contested, with joint ventures and product launches indicating that incumbents are actively defending their positions while seeking new growth vectors. For organizations aiming to thrive in this environment, access to detailed, segmented data is indispensable.
This report offers more than just numbers; it offers a strategic lens through which to view the future of automotive suspension components. By understanding the interplay between material costs, regulatory mandates, and regional demand shifts, stakeholders can make informed decisions that safeguard their interests and capitalize on emerging opportunities. The full depth of this analysis, including specific regional breakdowns and detailed segmentation splits, is available to provide the precise intelligence needed for your strategic planning.
For detailed analysis of this topic, please visit the official page: Automotive Stabilizer Bar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: NB Latex Market Hits $215M in 2025, Projected 7.45% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the NB Latex Market: Strategic Intelligence for 2026 Corporate Planning
The natural and synthetic rubber latex sector stands at a critical inflection point as enterprises move through the 2026 fiscal year. Supply chain realignments, evolving regulatory frameworks, and persistent demand growth across core end-use verticals are reshaping competitive dynamics and forcing leadership teams to reevaluate procurement strategies, capacity allocation, and geographic exposure. PW Consulting has just released a comprehensive market intelligence study designed to equip executives, procurement directors, and investment strategists with a rigorous, forward-looking view of how the NB Latex Market will evolve through the end of the decade. This article outlines the strategic architecture of that research, explains why the current analytical window is essential for 2026 decision-making, and demonstrates how the full report equips organizations to convert macroeconomic signals into actionable commercial advantage.
For corporate planners operating in commodity-dependent industries, ambiguity is rarely a neutral condition. It is a direct driver of margin variability, inventory risk, and competitive positioning. The NB Latex Market has historically exhibited cyclical sensitivity to agricultural output, energy-linked synthetic feedstock pricing, and downstream manufacturing cycles. Yet the current environment introduces structural shifts that separate short-term forecasting exercises from durable strategic frameworks. Our latest study bridges that gap by anchoring historical trajectory analysis to a disciplined forward-looking methodology, enabling stakeholders to stress-test assumptions rather than rely on linear extrapolation.
A Macro Baseline Built for Decision Confidence
Any credible strategic assessment begins with a transparent historical foundation and a clearly defined forecast horizon. The research underestimates neither historical volatility nor forecast uncertainty. Drawing on a six-year historical baseline spanning 2020 through 2025, the analysis captures how the market navigated post-pandemic recovery, logistics disruptions, and sectoral demand recalibration. That historical sequence establishes a realistic reference frame for evaluating the forward trajectory.
The forecast period extends from 2026 through 2032, providing sufficient runway to evaluate capital planning cycles, supplier diversification programs, and product portfolio shifts. Over this window, the study models a compound annual growth rate of 7.45 percent, reflecting a market that is expanding at a pace faster than mature commodity baselines yet balanced enough to warrant disciplined rather than speculative investment. Revenue is tracked in USD millions, allowing multinational stakeholders to align the findings with consolidated financial planning and cross-border procurement benchmarks.
This top-line trajectory is not presented as a single deterministic line. Instead, the report contextualizes growth as a function of intersecting supply-side constraints, demand-pull from core industrial and consumer verticals, and regulatory transitions that alter compliance cost structures. For 2026 executives, that framing matters because it shifts the strategic question from "How large will the market become?" to "Where will value concentrate, and under what operational conditions?"
Structural Composition: Where Growth and Risk Intersect
A market-level aggregate can inform board-level narrative, but it does not guide sourcing strategy. The report decomposes the NB Latex Market across three foundational dimensions that directly affect commercial planning: type, application, and region. By isolating how revenue distribution behaves across these axes, the study helps organizations identify where demand resilience is strongest, where substitution risk is most pronounced, and where geographic dependencies may require hedging or dual-sourcing strategies.
Type Segmentation and Material Strategy
The analysis partitions the market across natural rubber latex, synthetic rubber latex, and other material categories. Each pathway carries a distinct cost profile, performance footprint, and supply-risk signature. Natural latex routes remain tightly linked to agricultural yield dynamics, seasonal variability, and geopolitical conditions in producing regions. Synthetic routes are more closely tied to petrochemical feedstock behavior and industrial downstream demand. For procurement and R&D leaders, understanding the balance between these streams is essential for negotiating contract structures, evaluating substitute feasibility, and determining how much exposure to concentrate in any single material pathway.
Application Segmentation and Demand Durability
Demand quality varies sharply by end-use. The report assesses how core application areas shape consumption patterns and dictate the pace of uptake. Automotive-linked demand remains a central driver given continued tire and component requirements, but it is not isolated from broader vehicle production cycles. Construction and building materials represent another substantial demand pool, where latex-based products serve functional roles in coatings, adhesives, and specialized building systems. Consumer goods and personal care applications contribute a steadier usage base, often characterized by higher specification sensitivity and brand-driven quality standards. Industrial products and other use cases round out the landscape, frequently reflecting niche but high-margin requirements.
For 2026 planning, the actionable insight is not merely which application is largest, but which application provides the most stable demand floor, which is most exposed to discretionary spending cycles, and which is likely to see specification upgrades that alter material requirements. Leadership teams that align sourcing and capacity commitments with those distinctions can reduce inventory volatility and avoid overcommitting to transient demand peaks.
Regional Dynamics and Sourcing Architecture
Geographic distribution shapes both cost competitiveness and resilience. The report examines regional market participation to highlight where consumption is concentrated and where sourcing options are expanding. This is particularly relevant for enterprises that are evaluating supplier diversification away from single-region dependence or recalibrating logistics footprints in response to shipping cost variability, trade policy uncertainty, and local content expectations.
Because the full report contains detailed regional breakdowns, readers are encouraged to consult the complete study when designing market-entry evaluations or supplier audits. The executive-level takeaway is that regional strategy in the NB Latex Market cannot be reduced to price arbitrage alone. It must account for logistics reliability, regulatory alignment, and the operational maturity of downstream processing ecosystems.
Competitive Landscape: Intensity, Structure, and Strategic Posture
A market growing at a mid-to-high single-digit pace does not automatically translate into balanced profitability. Competitive structure determines how value is divided among producers, processors, and integrated traders. The study evaluates the market through the lens of concentration, examining how consolidated the supplier base is and what that implies for buyer leverage, contract stability, and innovation diffusion.
Concentration metrics indicate that the market remains relatively fragmented at the top tier, with the three largest firms accounting for a modest share of total revenue and the five largest firms holding a somewhat larger but still measured position. That structure has practical consequences. It suggests that no single entity dominates pricing across all grades and applications, while simultaneously implying that scale advantages, certification capability, and supply chain integration can create meaningful differentiation. For buyers, this environment rewards careful supplier qualification and multi-source design. For producers, it underscores the importance of quality consistency, traceability, and service reliability as competitive levers.
Key Enterprises and Differentiated Positioning
The report profiles a set of influential companies whose operational footprints help define the current competitive terrain. Several Thai-based processors feature prominently, reflecting the region's central role in natural rubber latex processing and export. Sri Trang Agro-Industry Public Company Limited stands out for its large-scale processing capacity and substantial share of global natural rubber consumption, giving it both volume leverage and broad market visibility. Von Bundit Co., Ltd. is highlighted for its emphasis on quality-certified grades and high throughput, attributes that matter in specification-sensitive downstream markets. Halcyon Agri Corporation Limited is examined for its integrated approach and vertical supply chain control across tire, glove, and industrial applications, an architecture that can reduce intermediary friction and improve traceability.
Thai Rubber Latex Group Public Company Limited and Thai Hua Rubber Public Company Limited are assessed as established exporters with strong orientation toward concentrated and creamed latex supply across Southeast Asian and broader international channels. Southland Rubber Co., Ltd. and Num Rubber & Latex Co., Ltd. are reviewed for their focus on specialty grades and medical or industrial applications, where compliance, consistency, and technical service often outweigh commodity price competition alone. Vietnam Rubber Group is incorporated as a state-linked producer with a meaningful presence in Southeast Asian supply, while Sinochem International Corporation represents the integrated trader-processor model serving global demand from a major commodity hub. Apcotex Industries Limited is profiled for its positioning in adhesive, coating, and industrial pathways, where formulation and application support can be as important as volume supply.
These profiles are not included merely as company summaries. They are used to map how different operating models compete on cost, quality, compliance, and integration. In 2026, the strategic implication is clear: procurement teams should evaluate suppliers not only by price and availability, but by the durability of their supply chain controls, their certification posture, and their ability to support specification changes without disruptive lead times.
Market Dynamics: Regulatory Shifts, Input Signals, and Pricing Context
Strategic planning in the NB Latex Market depends heavily on external forces that can alter both operating cost and market access. The report integrates current industry context to help decision-makers separate temporary noise from structural change.
Regulatory Developments and Compliance Timing
Regulatory evolution is one of the most consequential variables for exporters, importers, and processors. The European Union Deforestation Regulation has introduced plantation-level geolocation requirements for natural rubber latex and related products placed on the EU market. This compliance expectation changes the burden of documentation, traceability, and supplier qualification for any organization with EU-facing demand. At the same time, recent adjustments have postponed enforcement timelines for large and medium operators to December 30, 2026, with micro and small operators subject to a later deadline in mid-2027. For 2026 planners, that postponement does not eliminate the requirement; it compresses the preparation window. Companies that treat compliance as a near-term documentation exercise rather than a structural supply chain upgrade may face rushed implementation risk later in the year and into 2027.
In parallel, Indonesian policy adjustments on crude palm oil export duties have raised cost pressure within parts of the broader vegetable oil and plantation-linked ecosystem. While palm oil is not the same as latex, the move illustrates how export tax and duty policy can quickly change producer economics, trade flow incentives, and regional cost competitiveness. For latex market stakeholders, the broader lesson is that fiscal and trade policy shifts in producing countries can influence input availability, substitution decisions, and logistics planning.
Price Signals and Input Environment
Commodity pricing remains a central concern for both procurement and margin planning. Recent price projections from a major multilateral institution point to an approximate 7.3 percent increase in technically specified rubber prices during 2026, with estimates moving toward about 1.90 USD per kilogram. The forecast is underpinned by steady automotive-sector demand growth and ongoing supply tightness across key producing countries. For NB Latex Market participants, such a signal reinforces the importance of contract timing, inventory positioning, and price-risk mitigation. It also highlights the possibility that cost increases may be passed through at different speeds across applications, depending on downstream pricing power and specification sensitivity.
The report also situates latex planning within a wider commodity environment where cross-commodity signals matter. For example, palm oil price movements have been volatile in the recent trading window, with values moving lower on a day-to-day basis yet remaining materially higher year-on-year. This kind of input backdrop matters because energy, oleochemical, and plantation-linked commodities often influence broader operational cost sentiment, logistics budgeting, and substitution considerations, even when the immediate product focus is latex.
Worldwide Latex Binders Market
What the Full Report Delivers for 2026 Decision-Makers
This article has outlined the strategic logic behind the study and previewed the analytical dimensions it covers. The complete report extends that foundation into a fully operational intelligence package designed for immediate corporate use. It combines historical evaluation, forward-looking modeling, segmentation analysis, competitive profiling, and dynamic market context into a single integrated reference.
The report is structured to support concrete operational questions, including how to assess supplier resilience, where to focus negotiation leverage, how to anticipate specification and compliance pressure, and how to evaluate differing regional sourcing options without overrelying on surface-level price comparisons. It also provides the evidentiary backbone for scenario planning, allowing leadership teams to test how changes in feedstock cost, regulation, and end-use demand could affect both sourcing strategy and profitability.
NB Latex Market
Because the full study preserves the granularity required for precise planning, it intentionally goes beyond the high-level synthesis presented here. Detailed segmentation values, regional and application-level breakdowns, and company-specific strategic implications are embedded in the complete version to support procurement modeling, market-entry assessment, and competitive benchmarking. This approach ensures that the report functions not as a static market summary but as a working tool for cross-functional planning teams.
Why the 2026 Window Demands Earlier Strategic Clarity
The intersection of demand growth, regulatory preparation, supplier concentration, and input-cost uncertainty makes 2026 a pivotal year for NB Latex Market strategy. Companies that defer structural decisions until price signals become acute often discover that options have narrowed. Organizations that use the current period to strengthen supplier qualification, map compliance readiness, align sourcing with demand durability, and evaluate regional exposure are better positioned to protect margins and preserve flexibility.
PW Consulting's NB Latex Market research was developed for precisely that purpose: to convert complex, fast-moving market conditions into a clear strategic framework. The complete report provides the detailed segmentation, competitive analysis, and forward-looking intelligence needed to support confident 2026 decisions and to prepare for the 2027-2032 trajectory with greater certainty.
For executives who require the full segmentation detail, regional breakdowns, and company-level strategic implications, the complete study is available through the PW Consulting market research portal. Accessing the full report ensures that your planning teams can move beyond macro direction and into the specific intelligence required for sourcing strategy, compliance readiness, and competitive positioning throughout the forecast period.
For detailed analysis of this topic, please visit the official page: NB Latex Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com