

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: High Strength Steel Market Hits $130M in 2025, Forecast 7.8% CAGR to 2032

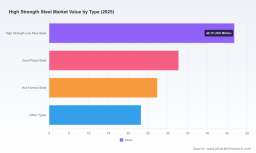
Strategic Imperatives in the High Strength Steel Market: A 2026 Executive Briefing
The global high strength steel market stands at a critical inflection point as industrial demand converges with stringent regulatory frameworks and accelerated technological innovation. For corporate strategists, procurement leaders, and capital allocators, navigating this landscape requires more than top-line projections. It demands granular, actionable intelligence that maps macroeconomic momentum to on-the-ground competitive shifts. PW Consulting’s latest High Strength Steel Market research delivers precisely that intelligence, offering a decision-ready architecture designed to de-risk strategic planning and unlock structural advantages across the 2026 to 2032 horizon.
A Market Defined by Resilient Growth and Structural Rebalancing
Tracing the market’s trajectory from 2020 through 2025 establishes a clear baseline of steady expansion, with revenue compounding at a pace that outpaces broader industrial metal benchmarks. The transition from historical performance into the forecast window reveals an acceleration pattern that demands immediate strategic attention. By 2026, the market has crossed a significant revenue threshold, and the forward projection indicates sustained upward momentum through the end of the decade. The implied compound annual growth rate across the full forecast period underscores a structurally healthy demand environment rather than a cyclical spike. This trajectory is not uniform across all vectors, which is exactly why executives must look beyond aggregate figures. The reallocation of investment, shifting end-user priorities, and evolving material specifications are reshaping where value accrues and which product architectures capture premium positioning.
Leadership teams operating in capital-intensive sectors cannot afford to treat high strength steel as a commoditized input. The market’s expansion is increasingly tied to performance-critical applications, weight-reduction mandates, and infrastructure modernization cycles. Understanding how these drivers fragment across product architectures and end-use ecosystems is the difference between capturing margin expansion and being squeezed by price volatility. Our research isolates these dynamics without diluting them into vague trend summaries, providing a clear line of sight from macro momentum to segment-level execution pathways.
Decoding the Competitive Architecture
The industry’s leadership cohort reflects a deliberate concentration of technological capability, geographic footprint, and application-specific expertise. A handful of entrenched players command the majority of realized market value, yet the competitive field remains highly active as incumbents recalibrate portfolios and challengers target niche performance tiers. The market structure exhibits moderate oligopolistic characteristics, meaning that while scale players set pricing anchors and technology benchmarks, there remains meaningful room for differentiated positioning through grade specialization, regional supply chain optimization, and application engineering.
High Strength Steel Market
Several globally recognized producers anchor the landscape, each pursuing distinct strategic vectors. A Swedish leader has cemented its reputation through premium structural and automotive grades engineered for extreme load conditions and lightweighting targets. A Luxembourg-headquartered multinational continues to scale its high-yield and advanced-grade offerings, particularly where construction durability and automotive crash performance intersect. A South Korean manufacturer has extended its global sales architecture around premium structural steels and automotive high-strength lines, leveraging integrated production advantages to compete in export-driven markets. A Japanese enterprise maintains a strong presence in ultra-high-tensile and offshore-grade plates, serving infrastructure and heavy industrial buyers who prioritize certification depth and metallurgical consistency. In North America, the largest domestic supplier of advanced high-strength steels is pushing third-generation grades that directly address vehicle lightweighting requirements, while a major U.S. integrated producer has introduced proprietary advanced grades designed for electric vehicle platforms and transformer applications. European and Indian counterparts round out the competitive matrix, with one German firm supplying high-strength flat-rolled products for automotive and industrial use, an Austrian manufacturer emphasizing premium grades for machinery and automotive segments, and an Indian producer focusing on corrosion-resistant high-tensile offerings for offshore and maritime environments.
This is not a static hierarchy. Recent corporate movements demonstrate how quickly product launches, capacity decisions, and industry consortium studies can reshape sourcing preferences. A major European producer recently introduced a new line of ultra-high-strength steels engineered specifically for electric vehicle chassis, positioning the release around lightweighting efficiency and updated safety compliance thresholds. A leading U.S. integrated manufacturer simultaneously expanded its portfolio to include proprietary advanced high-strength formulations and ultra-thin lightweight grades tailored for EV and transformer applications. Meanwhile, a North American capacity expansion initiative committed substantial capital toward increasing quenched-and-tempered steel output, extending the availability of flagship high-strength brands for demanding industrial and transportation users. Complementing these corporate moves, an industry-wide research body published a new parts consolidation study that quantifies how advanced high-strength steels can simplify vehicle architecture while maintaining structural integrity. These developments are not isolated headlines; they signal where R&D capital is flowing, where downstream buyers are being encouraged to re-evaluate material selections, and which performance benchmarks are becoming table stakes rather than differentiators.
Forces Reshaping Market Dynamics
Executive decision-making in this sector is being compressed by a convergence of policy shifts, input cost volatility, and standardization updates that directly alter procurement economics and specification strategies. Trade policy remains one of the most immediate variables. The reinstatement and subsequent escalation of import tariffs in the United States through mid-2025 fundamentally altered the cost baseline for imported high strength steel, forcing regional buyers to reconsider sourcing geography, inventory positioning, and contract structuring. Across the Atlantic, parallel moves by the European Union to reduce duty-free quotas and impose steep duties beyond those thresholds have recalibrated the cost landscape for European manufacturers and their supply chain partners. These policy adjustments do not merely affect landed cost; they influence capacity utilization patterns, redirect trade flows, and elevate the strategic importance of regional supply security.
Input cost dynamics add another layer of complexity. Recent price adjustments by major domestic producers in response to rising prime scrap costs illustrate how raw material inflation transmits rapidly into finished high-strength-grade economics. When base material costs move sharply, the margin sensitivity of advanced grades becomes a board-level concern, particularly for automotive and construction programs that operate on tightly negotiated multi-year agreements. Simultaneously, updated welding electrode classification standards have introduced new specification considerations for fabrication and construction workflows, requiring engineering teams to align procurement choices with revised compatibility and certification requirements. These are not peripheral compliance items; they are operational variables that influence total cost of ownership, lead-time reliability, and vendor qualification timelines.
What ties these forces together is their compounding effect. Tariff exposure changes sourcing logic, raw material inflation compresses margin tolerance, and specification updates alter fabrication readiness. Companies that treat these as independent risks often overcorrect in one area while under-hedging another. Our research integrates these variables into a unified operational framework, enabling leaders to model how policy, input costs, and technical standards interact across procurement cycles and capital planning horizons.
Inside the Research: Actionable Architecture for 2026 Decision-Making
This study is constructed for executives who need precision over generality. Rather than presenting a static market snapshot, the report maps the decision environment across product architecture, application demand, regional positioning, and competitive behavior, with explicit guidance on where and how to act. The analytical core is built around a multi-layered segmentation framework that dissects the market by type, application, and geography, while deliberately avoiding the trap of superficial share arithmetic. Each segmentation layer is evaluated for growth durability, price sensitivity, specification trajectory, and substitution risk so that sourcing and product-strategy teams can identify where to protect exposure and where to pursue premium positioning.
The competitive section goes beyond corporate profiling to assess strategic posture, capacity intent, and portfolio direction. Readers gain a structured view of how leading producers are aligning R&D investments with end-user requirements, which product families are being prioritized, and how recent launches and capacity decisions signal the next phase of market competition. This enables procurement and product-development teams to anticipate supplier positioning, evaluate alternative grade pathways, and construct negotiation strategies grounded in forward-looking supplier behavior rather than historical pricing alone.
Regulatory and cost-environment analysis is embedded throughout the report, not isolated in a compliance appendix. Trade-policy escalations, duty-quota adjustments, raw material price movements, and updated technical standards are mapped to their operational consequences, giving strategy and supply-chain leaders a practical reference for scenario planning. The forecast architecture extends across the full outlook window, providing a coherent growth narrative that supports capacity decisions, long-term contract structuring, and product-mix optimization. Crucially, the report maintains a tight focus on decision utility: it highlights where growth is structurally supported, where volatility is likely to intensify, and which strategic levers deliver the highest return on analytical investment.
To preserve the depth required for real-world application, certain granular breakdowns are reserved for the full intelligence package. The complete report provides the detailed regional and application-level decompositions, type-specific revenue architecture, concentration measurements, and company-by-company strategic assessments that turn high-level direction into executable planning inputs. This deliberate structure ensures that the executive summary establishes credibility and directional clarity while the full dataset delivers the specificity needed for budgeting, sourcing, and product-roadmap decisions.
Why This Intelligence Matters Now
Market leadership in high strength steel is increasingly defined by the speed and accuracy with which organizations integrate demand signals, policy reality, and supplier strategy into their capital and procurement plans. The growth trajectory through the end of the decade is robust, but the path to capturing it is uneven. Winners will be those who align material specifications with downstream performance mandates, manage exposure to trade and input-cost volatility, and position their product or sourcing strategies ahead of competitor portfolio shifts. Delaying that alignment until quarterly reviews or spot-market disruptions force action is a structural disadvantage.
PW Consulting’s High Strength Steel Market research provides the analytical foundation to move from reactive monitoring to proactive positioning. It equips leadership teams with a consolidated view of where value is concentrating, how competitive intentions are evolving, and which operational variables deserve immediate attention in 2026. The full report is designed to be read by strategists, commercial directors, procurement executives, and engineering leaders who need to translate market momentum into measurable advantage. Accessing the complete dataset will reveal the detailed segmentation architectures, competitive granularities, and scenario-ready breakdowns necessary to convert insight into execution.
High-strength Polyester Thread Market
For organizations preparing for the next phase of industrial demand, the question is no longer whether high strength steel will remain central to lightweighting, durability, and infrastructure performance, but how precisely to navigate the opportunities and risks embedded in its growth path. This research is built to answer that question with the clarity, rigor, and operational relevance that 2026 decision-making demands.
For detailed analysis of this topic, please visit the official page: High Strength Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com