

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tire Changers Market Hits $1,470.8M in 2025, Earmarks 6.8% CAGR to 2032

Strategic Intelligence for the Turn: Navigating the Tire Changers Market in 2026
The global automotive service equipment sector is entering a critical phase of expansion, driven by an increasingly complex landscape of vehicle technologies, regulatory frameworks, and shifting consumer demands. For enterprise decision-makers, fleet operators, and industry investors, understanding the trajectory of the Tire Changers Market is no longer a niche analytical exercise—it is a strategic imperative. Our latest comprehensive market research report on the Tire Changers Market delivers a forward-looking intelligence framework designed to guide capital allocation, product development, supply chain strategy, and competitive positioning through the forecast horizon of 2026 to 2032.
This introductory overview outlines the strategic architecture of the study, highlights the macro-level dynamics reshaping industry value chains, and demonstrates how granular, actionable insights can be leveraged to outmaneuver competitors in an environment defined by rapid technological iteration and evolving compliance mandates. The following analysis is structured to provide executives with a clear appreciation of the report's methodological rigor, its practical utility, and the specific decision-making advantages it offers.
Tire Changers Market
Market Trajectory and Structural Expansion Drivers
Historical performance data reveals a consistent and accelerating growth pattern across the global tire changer market. Over the observation window from 2020 through 2025, total market revenue has climbed steadily, reflecting sustained demand from both retail service networks and commercial fleet maintenance operations. The base year valuation for 2025 establishes a substantial baseline, which our forecasting models project will expand at a compound annual growth rate of 6.8 percent through 2032. This trajectory translates into significant revenue escalation, with the market anticipated to reach new financial milestones by the end of the forecast period.
Several structural forces underpin this expansion. The ongoing transition toward increasingly specialized tire architectures—including run-flat compounds, reinforced commercial truck tires, and high-performance winter formulations—has elevated the technical requirements for safe and efficient tire mounting and dismounting. Service centers and fleet maintenance facilities are consequently investing in equipment that can handle non-standard wheel dimensions, reinforced bead structures, and low-profile assemblies without risking damage to costly rims or compromising technician safety. Simultaneously, the proliferation of electric vehicle platforms, while altering powertrain maintenance profiles, has not diminished tire rotation and replacement demand; instead, it has shifted operational focus toward specialized service bays equipped with precision handling tools.
Supply chain normalization following recent global disruptions has further accelerated equipment procurement cycles, although new trade policy interventions are actively reshaping sourcing strategies. Manufacturers and procurement leaders must now navigate a landscape where import duty structures, regional manufacturing incentives, and localized content requirements are becoming decisive factors in total cost of ownership calculations. These dynamics are not peripheral; they are central to understanding where value will accrue across the market over the next seven years.
Segmentation Architecture and Operational Deployment Patterns
The market's value distribution is inherently multifaceted, reflecting divergent operational priorities across service environments, geographic territories, and equipment complexity tiers. Our analysis dissects these variation patterns to reveal where demand intensity is concentrated and how procurement preferences are evolving.
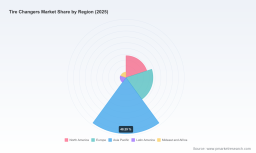
Across geographic territories, regional demand profiles are heavily influenced by fleet density, service center modernization rates, and local regulatory environments. Established automotive service markets with mature dealer networks and high vehicle parc densities continue to anchor significant portions of equipment procurement, while emerging service ecosystems are experiencing accelerated modernization as independent garages and fleet operators upgrade aging infrastructure. Each territory presents distinct purchasing rhythms, compliance expectations, and competitive intensity levels that require localized strategic responses rather than one-size-fits-all deployment models.
Equipment typology segmentation reveals a clear spectrum of technological adoption. Fully automated solutions are capturing growing share among high-throughput commercial facilities and premium service centers seeking to minimize labor intensity and standardize operational outcomes. Semi-automatic configurations maintain strong relevance for mid-tier operations balancing throughput requirements with budget constraints and workflow flexibility. Manual equipment continues to serve specialized repair contexts and cost-sensitive segments, though its proportional footprint is gradually compressed as automation capabilities become more accessible and demonstrable return-on-investment cases strengthen. The interplay between these categories is not merely a function of price; it is driven by labor availability, training infrastructure, throughput expectations, and the increasing technical demands of contemporary tire assemblies.
Application-based segmentation further illuminates deployment priorities. Passenger vehicle service networks represent the largest demand pool, reflecting high vehicle volumes and frequent tire rotation and replacement cycles. Commercial vehicle service applications follow as a substantial and strategically critical segment, where equipment reliability, uptime preservation, and compliance with heavy-duty maintenance standards carry heightened operational and financial consequences. Additional application verticals, including motorcycle service, specialty fleet maintenance, and regional mobility operations, contribute differentiated demand signatures that reward operators who can align equipment specifications with niche workflow requirements.
Competitive Landscape and Strategic Positioning
The competitive architecture of the tire changers market is characterized by a mix of established engineering-led manufacturers, specialized regional producers, and globally distributed equipment suppliers. Market concentration metrics indicate that a relatively compact group of leading firms commands a substantial share of total industry revenue, reflecting the capital intensity of product development, the importance of service and warranty infrastructure, and the value placed by commercial buyers on equipment reliability and dealer support networks.
Hunter Engineering Company, headquartered in Bridgeton, Missouri, continues to reinforce its market position through a sustained cadence of product innovation. Recent launches underscore a strategic emphasis on hybrid leverless mount head technology, enhanced inflation systems such as FastBlast™, and design configurations that address increasingly challenging tire profiles. The introduction of the Maverick® Pro and TCX53Pro models exemplifies a focus on torque delivery, speed optimization, and versatile mounting architectures that accommodate both center-clamp and swing-arm operational preferences. Concurrently, Coats Company, LLC, based in LaVergne, Tennessee, has advanced its commercial fleet serving capabilities by integrating high-pressure bead loosening systems, polymer and nylon duckhead configurations, and recently expanded steel jaw compatibility for 17.5-inch and 19.5-inch commercial wheels. Its refreshed brand platform and smart shop solution initiatives signal a broader commitment to integrated service bay ecosystems.
BendPak Inc., operating from Denton, Texas, has strengthened its accessible professional-grade positioning through the APEX line, pairing tire changers with complementary lift and balancing equipment to offer bundled value propositions for cost-conscious professional shops. Hofmann Equipment, leveraging its position within Snap-on Incorporated's global subsidiary structure and German engineering heritage, emphasizes integrated wheel service platforms that combine tire changing functionality with balancers and alignment systems, appealing to facilities pursuing workflow consolidation. European and Asian manufacturers—including Cormach S.r.l. in Italy, Ravaglioli S.p.A., NEXION S.p.A., ACE MACHINE TOOLS CO., LTD in Suzhou, Derek Weaver Inc., and Atlas Automotive Equipment in the United States—contribute diverse product philosophies ranging from superautomatic garage-oriented solutions to touchless automatic configurations and variable-speed direct-drive designs. This multiplicity of strategic approaches creates a dynamic competitive environment where differentiation hinges on engineering precision, total cost of ownership, regional service density, and the ability to anticipate evolving tire and wheel architecture requirements.
Regulatory, Compliance, and Supply Chain Dynamics
Market participants are operating within an increasingly prescriptive regulatory environment that directly influences equipment specification, procurement timing, and operational risk management. In the United States, sweeping tariff interventions introduced in 2025 have placed new cost and sourcing considerations on imported automotive service equipment. A baseline blanket rate structure, followed by substantially higher country-specific duties for select nations, has prompted procurement teams to reevaluate international supply chains, consider domestic manufacturing alternatives, and weigh freight and tariff exposure in total acquisition cost models. These trade policy shifts are particularly relevant for organizations balancing equipment price sensitivity against long-term service reliability and parts availability.
Occupational safety and machine guarding requirements continue to shape equipment design expectations and facility compliance protocols. OSHA standards governing machine guarding, including provisions applicable to turntable mechanisms and bead breaker assemblies, mandate safeguards that preserve operator accessibility while mitigating injury risk. In commercial trucking and heavy-duty maintenance contexts, adherence to these standards intersects with CVSA out-of-service criteria and broader fleet safety programs, making equipment selection a direct contributor to downtime reduction and regulatory compliance. Tire changers deployed in these environments must demonstrably satisfy guarding, trip hazard prevention, and operational safety expectations without compromising servicing efficiency.
Raw material sourcing strategies also carry growing strategic weight. Manufacturers emphasizing domestically sourced steel construction and vertically integrated component fabrication are positioning themselves as resilience-oriented alternatives in an environment where supply continuity, pricing stability, and compliance documentation are increasingly scrutinized by institutional buyers. These considerations are not isolated procurement details; they are becoming embedded in vendor qualification frameworks and long-term service contract negotiations.
Report Methodology and Actionable Intelligence Framework
Our Tire Changers Market research study is engineered to translate complex market signals into structured, decision-ready intelligence. The report integrates historical performance analysis, forward-looking forecasting, segmentation mapping, and competitive profiling into a unified analytical model. Methodological rigor is maintained through multi-source data triangulation, demand-side validation, supply-side capacity assessment, and scenario-based sensitivity testing to ensure that conclusions remain robust across varying macroeconomic and regulatory conditions.
The study provides detailed examination of equipment type evolution, application-specific deployment trends, and regional procurement behavior, while deliberately avoiding oversimplified aggregation that would obscure the operational nuances practitioners need. Competitive profiling extends beyond product catalogs to assess strategic positioning, innovation cadence, service infrastructure depth, and responsiveness to regulatory and trade policy shifts. Recent product launch activity, brand platform refreshes, and technical enhancement timelines are contextualized within broader market momentum to distinguish transient promotional activity from enduring strategic direction.
Operational utility is prioritized throughout. Readers will find structured guidance on evaluating equipment automation levels against throughput requirements, aligning procurement specifications with compliance mandates, assessing vendor reliability and regional support coverage, and anticipating demand shifts driven by tire technology evolution and fleet composition changes. The analytical architecture is designed to support capital investment justification, product portfolio planning, market entry evaluation, and competitive benchmarking with clarity and precision.
Strategic Implications for 2026 Decision-Making
As organizations prepare their operational and investment agendas for 2026 and beyond, the Tire Changers Market presents both opportunity and complexity. Growth trajectory is clear, but the distribution of value will increasingly favor participants who can align equipment capabilities with evolving service demands, navigate trade and compliance constraints intelligently, and differentiate through engineering reliability and integrated workflow support. Decision-makers who possess granular visibility into segmentation performance, competitive movement, and regional procurement behavior will be better positioned to time acquisitions, shape product development roadmaps, and engage vendors from a position of informed leverage.
This market research report is designed to deliver that visibility. It provides the analytical depth required to move beyond surface-level market narratives and the structured intelligence necessary to support high-stakes strategic choices. To access the complete dataset, detailed segmentation breakdowns, full competitive profiles, and scenario-based forecasts, we invite you to explore the full report through our official publication channel. The comprehensive intelligence contained within will equip your organization to navigate the tire changers market with confidence, precision, and strategic advantage.
Worldwide Tool Changers Market
For detailed analysis of this topic, please visit the official page: Tire Changers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com