

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MMA Market to Reach $272.5M by 2032, Driven by 7.9% CAGR & Automotive Demand

Strategic Imperatives in the Global Methyl Methacrylate Market: Insights for 2026 Decision-Makers
Executive Perspective
The global Methyl Methacrylate (MMA) market stands at a critical inflection point as industries navigate renewed supply chain realignments, evolving sustainability mandates, and shifting end-use demand patterns. For corporate strategists, procurement leaders, and investment committees operating in 2026, access to granular, forward-looking intelligence is no longer a discretionary advantage—it is a baseline requirement for capital allocation, capacity planning, and competitive positioning. PW Consulting’s latest comprehensive market research on the MMA sector delivers precisely this operational clarity, translating multi-year historical trajectories and decade-long projections into actionable frameworks tailored for executive decision-making.
This report is engineered to serve as a strategic compass rather than a static data repository. It maps the structural forces reshaping methacrylate economics, evaluates the competitive postures of incumbent producers and emerging challengers, and isolates the regulatory, technological, and macroeconomic variables that will dictate margin resilience through the end of the decade. Readers will find a meticulously calibrated analysis that balances quantitative rigor with qualitative industry context, enabling organizations to stress-test their 2026 portfolios against realistic supply-demand scenarios and pricing trajectories.
Market Architecture and Forward Trajectory
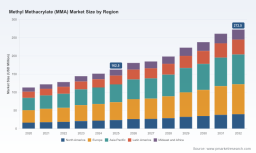
The MMA market has demonstrated consistent expansion across the historical review window, transitioning from a base of approximately $113.25 million in 2020 to an estimated $162.50 million by 2025. This upward trajectory reflects sustained downstream consumption, incremental capacity optimization, and the material’s entrenched role across high-growth industrial verticals. Looking ahead, the forecast horizon through 2032 projects continued expansion at a compound annual growth rate of 7.9 percent, positioning the market to reach $272.50 million by the terminal forecast year.
Such growth is neither uniform nor automatic. The forecast model accounts for regional production realignments, feedstock volatility, and the gradual integration of lower-carbon manufacturing pathways that are beginning to redefine cost structures. Strategic buyers and producers alike must recognize that aggregate growth figures mask divergent local dynamics, differential adoption rates across application segments, and the compounding effects of geopolitical trade flows. Our analysis disentangles these layers, providing decision-makers with a nuanced view of where volume expansion will materialize, which supply corridors will experience tightness, and how pricing momentum is likely to evolve as production costs and capacity utilization intersect.
Competitive Landscape and Strategic Positioning
The MMA industry remains highly concentrated, with a small cohort of globally integrated producers commanding the majority of installed capacity and downstream distribution networks. Consolidated market dynamics mean that pricing power, technology licensing, and strategic capacity announcements frequently ripple across the entire value chain. Understanding the operational footprint, technological orientation, and recent corporate maneuvers of these key players is essential for evaluating supply security, negotiating long-term contracts, and anticipating market-wide price signals.
The competitive field is anchored by several prominent organizations whose strategic initiatives directly shape market equilibrium. Röhm GmbH has been executing a deliberate production footprint transformation, transitioning from legacy Gulf Coast capacity toward its newly commissioned ethylene-based LiMA MMA facility in Bay City, Texas. This plant has now achieved full industrial-scale operation, with all four reactors running at planned throughput, reinforcing North American supply resilience while introducing a lower-carbon manufacturing route that integrates chemical recycling for closed-loop operations. Concurrently, the company has adjusted its regional pricing architecture, implementing immediate increases for its MERACYL® MMA product line across Asian markets outside mainland China, reflecting both cost pressures and localized supply-demand rebalancing.
Mitsubishi Chemical Corporation maintains its position as the world’s largest producer of methacrylates and MMA, operating extensive production infrastructure with cumulative capacity exceeding 1.2 million tons annually. Despite this scale advantage, the company’s recent portfolio decisions—including the discontinuation of a planned 350,000 ton/year MMA monomer facility in Louisiana—signal a more selective approach to greenfield expansion, emphasizing capital efficiency and regional demand alignment over undifferentiated capacity additions. BASF SE continues to function as an integrated supplier across coatings, adhesives, and polymethyl methacrylate (PMMA) applications, leveraging its broader chemical ecosystem to stabilize supply and cross-sell derivative solutions. Dow Inc. has similarly reinforced its North American manufacturing presence, directing investment toward capacity expansions that align with regional downstream demand and feedstock availability.
European and Asian producers further diversify the competitive matrix. Arkema S.A. has prioritized sustainable production methodologies for coatings and advanced materials, while Sumitomo Chemical Co., Ltd. has formalized a dedicated MMA division to better serve electronics and automotive end markets. Asahi Kasei Corporation continues to emphasize high-performance acrylic materials spanning automotive, construction, and optical applications. Chi Mei Corporation supplies PMMA sheets and compounds across signage, electronics, and construction verticals, and Evonik Industries AG maintains a specialized focus on methacrylate derivatives and sustainable PMMA formulations. Huntsman Corporation rounds out the field as a broad-spectrum supplier of MMA-based solutions for coatings, adhesives, and polyurethane systems, supported by a globally distributed distribution network.
Capacity Realignment and Operational Shifts Driving Market Dynamics
The competitive equilibrium is being actively reshaped by a series of high-impact operational decisions that have unfolded over the past 24 months. These moves are not isolated corporate restructuring events; they represent structural recalibrations of regional supply corridors, technological pathway selection, and portfolio prioritization that will influence pricing volatility, availability, and contract negotiation leverage throughout the forecast period.
Capacity consolidation and technology substitution have emerged as dominant themes. Röhm’s phased closure of its 250,000 ton Westwego, Louisiana facility, synchronized with the ramp-up of its Bay City ethylene-based plant, illustrates a broader industry migration toward integrated, lower-emission production routes. This transition carries direct implications for regional supply balances, logistics costs, and the cost base of North American MMA availability. Simultaneously, Kuraray Co., Ltd. has executed a strategic contraction in its methacrylic resin sheet manufacturing operations in China, transferring subsidiary control as part of its PASSION 2026 portfolio optimization plan. This follows an earlier halving of its domestic Japanese MMA production capacity from 67,000 tons per year and the cessation of external sales, effectively reducing marketplace volumes and signaling a retreat from commoditized exposure in favor of higher-margin specialty positioning.
Poly Methyl Methacrylate (PMMA) Market
These realignments intersect with broader market signals. Global MMA pricing exhibited upward momentum during the first quarter of 2026, accelerating toward the quarter’s end as supply tightened and production costs climbed. For procurement teams and downstream converters, this environment demands more sophisticated hedging strategies, multi-sourcing architectures, and closer coordination with suppliers whose technological transitions may temporarily constrain flexibility. For producers, the same dynamics raise critical questions about capacity utilization, maintenance scheduling, and the timing of price adjustments across different geographic markets.
End-Use Demand Ecosystems and Application Drivers
Sustained MMA consumption is anchored by a diversified application base that spans high-volume industrial sectors and specialized performance markets. Automotive demand remains a primary growth engine, driven by lightweighting initiatives, exterior and interior surface specifications, and the material’s compatibility with advanced coating and molding processes. Construction continues to represent a substantial consumption pillar, fueled by architectural glazing, translucent panels, and durable finishing systems that leverage PMMA’s optical clarity and weather resistance.
The electronics sector has emerged as an increasingly strategic demand center, with MMA-derived materials supporting display components, protective housings, and precision manufacturing requirements. Medical applications, while smaller in aggregate volume, contribute high-value demand streams tied to diagnostic equipment, fluid handling components, and biocompatibility-grade formulations. Each of these application verticals operates with distinct cost sensitivities, regulatory environments, and substitution risks. Our report maps how demand intensity is evolving within each segment, identifying the specific catalysts that will accelerate or moderate consumption growth, the interplay between end-market cyclicality and MMA procurement cycles, and the implications for producers seeking to align capacity specialization with downstream value creation.
Geographic Supply Corridors and Regional Rebalancing
Regional market dynamics are undergoing meaningful restructuring as production footprints shift, trade patterns adapt, and local demand profiles diverge. North American supply chains are being reconfigured around new ethylene-based production investments and the retirement of legacy capacity, altering the regional cost basis and availability calculus. European markets continue to navigate energy cost variability and sustainability-driven formulation requirements, prompting both supply optimization and demand-side innovation. The Asia Pacific region remains a central consumption hub, with localized pricing adjustments, supplier network recalibration, and evolving regulatory expectations shaping procurement strategies across multiple sub-markets. Latin American and Middle East/Africa corridors present distinct opportunity sets tied to infrastructure development, industrial modernization, and import dependency patterns.
Methyl Methacrylate (MMA) Market
Importantly, regional analysis cannot be reduced to simple volume comparisons. Pricing differentials, freight economics, tariff structures, and the proximity of integrated feedstock sources all influence the effective competitiveness of MMA supply in each geography. Our research evaluates these intersecting variables to help stakeholders identify which corridors present the most favorable risk-adjusted access, where supply interruptions are most likely to emerge, and how regional capacity additions will interact with existing demand centers over the forecast window.
Regulatory, Sustainability, and Technology Vectors
The MMA market is increasingly shaped by forces that extend beyond traditional supply-demand economics. Sustainability mandates, carbon intensity expectations, and chemical recycling integration are moving from peripheral considerations to core operational priorities. Producers that can demonstrate lower lifecycle emissions, closed-loop material flows, and transparent ESG reporting are gaining negotiating advantages with downstream customers who face their own Scope 3 reduction targets and brand-level sustainability commitments.
Technological differentiation is becoming a structural competitive lever. The transition toward C2-based production pathways, as exemplified by recent large-scale plant commissioning, illustrates how process innovation can simultaneously address cost efficiency, emissions reduction, and supply reliability. At the same time, regulatory developments and corporate portfolio optimization decisions—such as the discontinuation of certain greenfield projects and the strategic scaling back of external sales in specific regions—reflect a more disciplined approach to capital deployment. These shifts suggest that future market growth will be delivered not merely through volume expansion but through selective capacity modernization, application-specific specialization, and tighter alignment between production technology and end-market performance requirements.
What This Report Delivers for 2026 Strategy
PW Consulting’s MMA market research is designed to convert complex industry signals into executable strategic insight. The study provides a comprehensive mapping of historical performance, forward-looking volume and revenue projections, competitive positioning assessments, and application-side demand analysis. It integrates real-time operational developments—including plant ramp-ups, capacity closures, pricing actions, and portfolio restructuring events—into a cohesive analytical narrative that supports scenario planning and risk evaluation.
Key components of the report include:
- A quantified market trajectory spanning historical baseline years and a detailed forecast through 2032, with explicit attention to the growth drivers, constraints, and inflection points that will shape outcomes.
- Competitive profiling of leading global producers, examining capacity orientation, technological strategy, recent operational milestones, and the strategic implications of their market actions.
- Application-level demand analysis that isolates the consumption dynamics, growth catalysts, and substitution risks across automotive, construction, electronics, and medical end-use segments.
- Regional supply corridor assessment that evaluates production realignments, trade flow implications, and localized pricing momentum without relying on overly simplified aggregate comparisons.
- Integration of recent industry events—such as plant commissioning milestones, capacity rationalization moves, ESG reporting developments, and pricing adjustments—into a forward-looking strategic framework.
- Actionable recommendations for procurement strategy, supplier diversification, capacity planning, and investment prioritization in an environment characterized by concentrated supply, evolving cost structures, and sustainability-driven differentiation.
Why This Intelligence Matters Now
The 2026 operating environment demands more than retrospective market summaries. Organizations must anticipate how capacity transitions will affect regional availability, how pricing momentum will propagate through downstream supply chains, and where competitor strategy shifts will open or close competitive windows. The convergence of technology substitution, portfolio optimization, and sustainability expectations is compressing decision cycles and raising the cost of informational asymmetry. In this context, a rigorously constructed market study becomes a strategic asset, enabling leadership teams to move from reactive adjustment to proactive positioning.
This report is structured to support multiple functional audiences: corporate development teams evaluating market entry or expansion opportunities, procurement leaders designing resilient sourcing architectures, finance and investment committees stress-testing volume and margin assumptions, and operational executives aligning production or conversion strategies with anticipated supply conditions. By synthesizing quantitative forecasts, competitive intelligence, and event-driven market context, the analysis provides a unified reference point for cross-functional alignment.
Next Steps for Strategic Readers
The full scope of this research extends well beyond the market-level trajectory and competitive overview presented here. Detailed segmentation analysis, granular regional assessments, application-specific demand modeling, and comprehensive supplier benchmarking are integrated into the complete study to support precise strategic planning. Organizations that require defensible assumptions for capacity investments, contract negotiations, or portfolio reallocation will find the full dataset and accompanying analytical commentary essential to validating their decision frameworks.
To access the complete market intelligence, including all segmentation detail, regional breakdowns, competitive profiles, and forward-looking scenario analysis, please visit the official PW Consulting report page. The full study is structured to serve as a living strategic reference, enabling teams to translate macro-level trends into targeted operational actions throughout the 2026–2032 forecast horizon.
For detailed analysis of this topic, please visit the official page: Methyl Methacrylate (MMA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com