

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Stabilizer Bar Market Hits $3.63B in 2025, Projects 5.3% CAGR to 2032

Strategic Horizons in the Automotive Stabilizer Bar Market: A 2026 Decision-Maker's Guide
The automotive suspension landscape is undergoing a structural transformation, driven by the dual imperatives of vehicle electrification and stringent safety regulations. For executives and strategic planners operating within the automotive supply chain, understanding the trajectory of the stabilizer bar market is no longer optional—it is a critical component of risk management and opportunity capture. The Automotive Stabilizer Bar Market report by PW Consulting provides a comprehensive navigational chart for this complex terrain, offering data-driven insights designed to inform capital allocation and product development strategies through 2032.
As the industry pivots from internal combustion engines to electric powertrains, the demand characteristics for passive safety components are shifting. This report serves as an essential intelligence tool, bridging the gap between historical performance and future forecasting. By analyzing the market from a base year of 2025 through a forecast period extending to 2032, stakeholders can anticipate supply chain disruptions, regulatory impacts, and competitive maneuvers that will define the next decade of automotive manufacturing.
Worldwide Automotive Stabilizer Bar Link Market
Executive Summary of Market Trajectory
The global market for automotive stabilizer bars has demonstrated resilience and steady growth over the past five years. Historical analysis from 2020 to 2025 reveals a consistent upward trend in revenue, reflecting the sustained demand for vehicle stability and safety systems across major automotive producing nations. The market size, measured in USD Million, has expanded significantly as vehicle production volumes recovered from pandemic-era disruptions and safety mandates tightened globally.
Looking forward, the forecast period from 2026 to 2032 projects a Compound Annual Growth Rate (CAGR) of 5.3. This growth rate indicates a mature yet expanding market where innovation rather than volume alone will drive value. The projected revenue trajectory suggests that while the market is not experiencing explosive volatility, the cumulative value creation over the forecast horizon represents a substantial opportunity for well-positioned manufacturers. The transition from 2025 baseline figures to the 2032 endpoint underscores the importance of long-term capacity planning and investment in lightweight materials.
This growth is not uniform across all segments. The report delineates how different vehicle types and regional manufacturing hubs contribute to this aggregate figure. Understanding the macro-level movement allows executives to calibrate their expectations for revenue growth against the backdrop of broader economic conditions, including raw material price fluctuations and geopolitical supply chain constraints.
Segmentation Landscape and Material Dynamics
Type and Application Segmentation
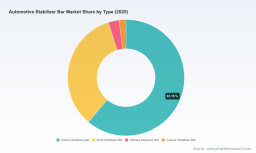
The market is structurally divided by stabilizer bar type and vehicle application, each presenting unique value propositions and manufacturing challenges. The report provides a detailed breakdown of solid, hollow, splined, and tubular stabilizer bars, analyzing how engineering requirements differ between passenger comfort and heavy-duty durability. Hollow bars, for instance, are gaining traction in segments where weight reduction is prioritized, while solid bars remain critical for applications requiring maximum rigidity and load-bearing capacity.
In terms of application, the distinction between passenger cars and commercial vehicles is vital. Passenger cars continue to represent the largest volume share, driven by consumer safety expectations and regulatory compliance. However, the commercial vehicle segment offers distinct growth vectors, particularly as fleet operators seek to improve fuel efficiency and cargo stability. The report explores how these application segments interact with regional manufacturing capabilities, highlighting where demand is most concentrated and where supply gaps may emerge.
Material Shifts and Raw Material Volatility
Material composition remains a pivotal factor in stabilizer bar manufacturing. Steel stabilizer links, including high-strength steel grades and ductile iron variants, maintain a dominant market share, reflecting mature manufacturing processes and proven performance reliability. However, the industry is witnessing a gradual shift toward aluminum and composite materials, particularly in scenarios where weight reduction directly correlates with energy efficiency.
This shift is not without risk. Aluminum prices fluctuate significantly, often ranging 15-25% annually based on global supply-demand dynamics and geopolitical factors affecting mining and refining operations. For procurement managers and CFOs, this volatility introduces a layer of complexity to cost forecasting. The report examines how leading manufacturers are hedging against these material risks and whether the premium for lightweight materials is justified by the total cost of ownership benefits in electric vehicle platforms.
Regional Dynamics and Regulatory Drivers
Geographic segmentation reveals distinct growth patterns across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. While aggregate data provides a high-level view of market distribution, the strategic value lies in understanding the local drivers propelling demand in each region. Asia Pacific, for instance, continues to be a critical hub due to high vehicle production volumes, while North America and Europe are driven more by replacement markets and stringent safety regulations.
Regulatory frameworks are acting as accelerators for market innovation. In Europe, Euro 7 regulations are driving continuous suspension system innovation, including lightweight and smart stabilizer link designs. Furthermore, EU emissions regulations targeting aggressive average fleet emissions levels by 2025 are accelerating the adoption of lightweight suspension components. These regulatory pressures are not merely compliance hurdles; they are strategic levers that force manufacturers to innovate faster than competitors who may be slower to adapt.
In the United States, government procurement activities also signal market vitality. Recent solicitation notices for fleet sustainment indicate ongoing demand for robust suspension components in defense and logistics applications. Such public sector engagements provide a stable demand floor for manufacturers capable of meeting specific government specifications and durability standards.
Competitive Landscape and Strategic Moves
The market concentration is characterized by a mix of global tier-1 suppliers and specialized manufacturers. The report analyzes the Competitive Rivalry among key players, noting that the top three companies hold a combined market share of approximately 32.5%, while the top five control around 45.2%. This fragmentation suggests that while large players dominate, there is sufficient room for niche specialists to thrive, particularly those offering differentiated technology or superior regional service networks.
Profile of Key Industry Players
The competitive arena includes established automotive giants and focused component manufacturers, each pursuing distinct strategies to secure market position:
- ZF Friedrichshafen AG: A major provider of integrated solid and hollow automotive stabilizer bars and links, including active damping variants for passenger and commercial vehicles. ZF continues to leverage its integrated systems approach to offer complete suspension solutions.
- thyssenkrupp AG: Producing hollow and solid stabilizer bars with a focus on lightweight aluminum and high-strength steel variants for OEMs. Their recent product launches demonstrate a commitment to material innovation for electric vehicles.
- Sogefi Group: Specializing in solid and hollow stabilizer bars and links for suspension systems in automotive and heavy-duty applications, maintaining a strong presence in Europe and emerging markets.
- Mubea Group: Manufactures precision stabilizer bars and links used in passenger cars, light trucks, and commercial vehicles, emphasizing lightweight engineering and structural integrity.
- Kongsberg Automotive: Manufactures solid and hollow stabilizer bars and links for OEM integration in passenger cars and light commercial vehicles, focusing on high-quality Nordic engineering standards.
- Tinsley Bridge Group: Produces solid and hollow stabilizer bars and links for OEM and aftermarket passenger and commercial vehicle suspension, bridging the gap between original manufacturing and service parts.
- ADDCO Manufacturing Company: Offers aftermarket solid stabilizer bars and links with polymer bushings for performance and standard automotive applications, catering to the enthusiast and repair market.
- SwayTec: Manufactures solid and hollow stabilizer bars and links for performance-oriented automotive and truck applications, targeting niche segments where handling characteristics are paramount.
Recent Strategic Developments
Recent activities among these key players highlight the dynamic nature of the market. In November 2025, ZF Friedrichshafen AG formed a joint venture with Wolong Electric Group Co., Ltd. to manufacture electric motors for driveline and stabilizer systems, signaling a move toward tighter integration of powertrain and suspension technologies.
Similarly, thyssenkrupp Automotive Technology launched a new high-strength aluminum stabilizer bar series for electric vehicles in March 2025, directly addressing the weight concerns associated with EV platforms. In April 2025, Federal-Mogul LLC introduced a new line of corrosion-resistant stabilizer bars with advanced surface treatment for harsh climates, expanding the addressable market for vehicles operating in extreme environments. These product launches and partnerships illustrate how competitors are actively reshaping the value chain to capture emerging opportunities.
Strategic Value for 2026 Decision-Making
For corporate strategists, procurement leaders, and investors, the primary value of this report lies in its ability to convert raw data into actionable intelligence. The period of 2026 represents a inflection point where historical trends meet new regulatory realities. Decision-makers need to understand not just where the market has been, but where the friction points and growth accelerators will be located over the next seven years.
Investment in capacity expansion, for example, must be timed correctly. Overinvesting in steel-based production lines while the market gradually shifts toward aluminum or hybrid solutions could lead to stranded assets. Conversely, waiting too long to adopt lightweight technologies could result in a loss of competitiveness in regions with strict emissions targets. The report provides the analytical framework to evaluate these trade-offs.
Automotive Stabilizer Bar Market
Supply chain resilience is another critical area. With raw material prices subject to significant volatility and geopolitical tensions affecting trade flows, understanding the regional concentration of supply and demand is essential. The report details how regions like Asia Pacific interact with North American and European demand centers, allowing supply chain managers to optimize logistics and inventory strategies.
Furthermore, the competitive intelligence provided allows companies to benchmark their performance against peers. By understanding the strategic moves of competitors like ZF, thyssenkrupp, and Sogefi, organizations can anticipate market shifts and adjust their own R&D pipelines accordingly. Whether a company is looking to enter the market, expand its footprint, or divest from underperforming segments, the segmentation data provides the necessary granularity to support these decisions without relying on guesswork.
Conclusion: Navigating the Future
The Automotive Stabilizer Bar Market is poised for steady evolution rather than disruptive revolution. The 5.3 CAGR projected through 2032 suggests a environment where operational excellence and technological adaptation will determine market leadership. The dominance of steel materials remains a baseline, but the pressure to reduce weight for electrification and emissions compliance is creating new niches for aluminum and advanced composites.
Regulatory pressures in Europe and procurement demands in North America will continue to shape production standards. Meanwhile, the competitive landscape remains contested, with joint ventures and product launches indicating that incumbents are actively defending their positions while seeking new growth vectors. For organizations aiming to thrive in this environment, access to detailed, segmented data is indispensable.
This report offers more than just numbers; it offers a strategic lens through which to view the future of automotive suspension components. By understanding the interplay between material costs, regulatory mandates, and regional demand shifts, stakeholders can make informed decisions that safeguard their interests and capitalize on emerging opportunities. The full depth of this analysis, including specific regional breakdowns and detailed segmentation splits, is available to provide the precise intelligence needed for your strategic planning.
For detailed analysis of this topic, please visit the official page: Automotive Stabilizer Bar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com