

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting DNA Sequencing Market Report: $16.89B 2025 Revenue, 14.9% CAGR to $44.63B by 2032

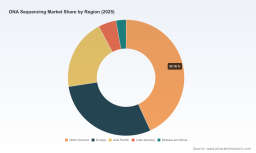
Strategic Foresight in Genomics: Navigating the DNA Sequencing Market Through 2032
The global DNA sequencing industry has transitioned from a specialized research tool to a cornerstone of modern healthcare, public safety, and agricultural innovation. As we enter 2026, executives, investors, and policy stakeholders face a landscape defined by rapid technological iteration, evolving regulatory frameworks, and intensifying competitive dynamics. PW Consulting's latest market research offers a comprehensive blueprint for navigating this complex environment, translating historical momentum into actionable strategy for the decade ahead.
DNA Sequencing Market
A Market Defined by Sustained Expansion
Historical revenue data from 2020 through 2025 reveals a decade of uninterrupted growth, with the global market expanding from approximately 9.12 billion USD to 16.89 billion USD. This trajectory reflects not merely cyclical demand but a structural shift in how biological data is generated, analyzed, and deployed across commercial and clinical ecosystems. Looking forward, our forecast model projects the market to reach 19.48 billion USD in 2026, accelerating steadily toward 44.63 billion USD by 2032. This pathway corresponds to a compound annual growth rate of 14.9 percent, underscoring the durability of demand drivers ranging from precision oncology to population-scale genomic surveillance.
For corporate strategists, these figures are more than aggregate indicators. They signal where capital allocation, R&D prioritization, and partnership development will yield the highest marginal returns. The research dissects the underlying engines of this expansion, mapping how technological transitions, application diversification, and regional uptake patterns intersect to shape competitive positioning. Rather than presenting static snapshots, the analysis emphasizes dynamic interdependencies, enabling decision-makers to anticipate inflection points before they materialize in financial results.
What the Research Delivers: From Macro Trends to Operational Intelligence
A market study is only as valuable as its translational capacity. This report is engineered for practitioners who require more than directional guidance. It combines top-down market sizing with bottom-up operational analysis, providing a multi-layered view of the sequencing ecosystem. The following components form the analytical backbone of the study:
- Technology evolution pathways, including the maturation of established platforms and the commercialization readiness of emerging long-read and single-molecule approaches
- Application-driven demand mapping across clinical, research, agricultural, and public health use cases, with emphasis on adoption velocity and reimbursement maturation
- Competitive positioning frameworks that evaluate instrument throughput, workflow integration, consumable economics, and software-driven differentiation
- Regulatory and standards development tracking, capturing how evolving guidance shapes product development cycles, clinical validation requirements, and market entry strategies
- Scenario-based forecasting that stress-tests growth assumptions against potential technological disruptions, pricing compression, and policy shifts
By integrating these dimensions, the research equips leadership teams with a structured lens to evaluate market entry timing, portfolio optimization, and partnership strategies. The methodology deliberately isolates signal from noise, ensuring that strategic recommendations rest on verified adoption patterns rather than speculative hype.
The Competitive Arena: Incumbents, Disruptors, and the Battle for Workflow Dominance
The sequencing market is characterized by high concentration, with the top three players accounting for approximately 65 percent of industry revenue and the leading five firms capturing roughly 78 percent. This structure reflects the capital intensity of platform development, the importance of installed base economies, and the strategic value of integrated reagent and software ecosystems. Yet concentration does not equate to stagnation. The competitive landscape is being reshaped by targeted innovation, workflow specialization, and the entry of well-capitalized challengers seeking to redefine cost-performance thresholds.
Illumina, headquartered in San Diego, remains a central force through its leadership in next-generation sequencing platforms, sequencing instruments, reagents, and whole-genome sequencing-based minimal residual disease research solutions. Its product cadence continues to influence downstream adoption patterns across both academic and commercial laboratories. Thermo Fisher Scientific, based in Waltham, complements this landscape with a comprehensive portfolio spanning NGS, Sanger sequencing, and genomics instruments alongside a broad consumable lineup, enabling multi-technology deployments within single organizational environments.
On the long-read frontier, Oxford Nanopore Technologies, operating from Oxford, has advanced nanopore-based sequencing platforms and analytical tools that emphasize real-time data generation and portable deployment formats. Pacific Biosciences, located in Menlo Park, continues to push the boundaries of single-molecule real-time technology and HiFi long-read sequencing systems, targeting applications where structural variant resolution and haplotype phasing carry high clinical or research value. These platforms are not merely technical alternatives; they represent strategic choices about read length, error profiles, turnaround time, and total cost of ownership.
Additional dynamics are emerging from companies that specialize in workflow integration and data-centric precision medicine. 10x Genomics, based in Pleasanton, has carved a differentiated position through Chromium single-cell and spatial transcriptomics solutions, expanding the analytical scope beyond bulk sequencing into cellular and spatial context. Element Biosciences, in San Diego, has introduced the AVITI benchtop NGS platform, targeting high-throughput, cost-effective sequencing for laboratories seeking to optimize instrument capital efficiency. Ultima Genomics, operating from Fremont and Newark, has pushed the economics of large-scale genomics with high-throughput systems designed for population-scale applications.
Geographic and technology diversification is further reflected in the presence of BGI Group, through MGI Tech in Shenzhen, which offers DNBSEQ NGS platforms and sequencing solutions for whole-genome and targeted applications. QIAGEN, headquartered in Venlo, contributes through QIAseq NGS panels, library preparation, and hybrid capture technologies, embedding sequencing workflows into broader molecular diagnostic and research pipelines. Clear Labs, based in San Carlos, focuses on fully automated NGS platforms for rapid pathogen and oncology sequencing, addressing throughput and hands-on time constraints in high-volume environments. Tempus AI, located in Chicago, integrates whole-genome sequencing assays with an AI-driven precision medicine platform, illustrating how sequencing data is increasingly coupled with computational inference to guide clinical decision-making.
This competitive mosaic matters because platform selection is rarely a purely technical decision. It encompasses service availability, bioinformatics support, consumable supply reliability, regulatory positioning, and the strategic alignment of a vendor's roadmap with a buyer's application pipeline. Our analysis evaluates how these factors interact across procurement cycles and how incumbents and challengers are repositioning their offerings to capture specific workflow segments.
Regulatory and Standards Dynamics: Shaping the Pace of Adoption
Technology alone does not dictate market velocity. Regulatory frameworks and quality standards increasingly function as adoption accelerators or bottlenecks, particularly in clinical and food safety applications. In April 2026, the FDA distributed for comment a draft guidance on NGS-based methods for safety assessment of genome editing in human gene therapy products, supporting clinical trial initiation. This development signals a maturing regulatory posture toward sequence-based validation, with implications for both therapeutic developers and diagnostic platform providers.
Across the Atlantic, the European Commission adopted regulation 2025/179 requiring member states to perform whole-genome sequencing on isolates of specific foodborne pathogens, including Salmonella enterica, Listeria monocytogenes, Escherichia coli, Campylobacter jejuni, and Campylobacter coli, for outbreak investigations. Such mandates expand the public sector demand base and institutionalize sequencing as a routine epidemiological tool. In parallel, the ongoing development of ISO/DIS 22692 on genomics informatics and quality control metrics for DNA sequencing, with the standard under enquiry phase as of 2025, reflects a broader push toward standardized performance benchmarking and data interoperability.
Sanger Sequencing Service Market
For commercial strategists, these regulatory and standards signals carry direct operational implications. They influence validation timelines, shape procurement requirements, and affect cross-border market access. The report maps these developments against technology readiness and application adoption, helping organizations distinguish between transient compliance burdens and structural shifts in demand.
Strategic Priorities for 2026 and Beyond
The convergence of sustained market growth, platform competition, and regulatory evolution demands a disciplined approach to strategic planning. Our research highlights several priority areas for leadership teams evaluating their position in the sequencing ecosystem:
- Assessing whether existing or planned instrument portfolios align with the workflow economics of target applications, including throughput needs, consumable consumption patterns, and bioinformatics support requirements
- Monitoring how long-read, single-cell, and spatial approaches are moving from specialized use cases into broader clinical and translational pipelines, and identifying where integration costs may create entry barriers or partnership opportunities
- Evaluating the strategic significance of automation and AI-enabled interpretation, particularly as sequencing volume scales and data interpretation becomes a more binding constraint than data generation
- Preparing for regulatory-driven demand expansion in public health, food safety, and gene therapy assessment, while calibrating compliance investment against realistic adoption horizons
- Understanding concentration dynamics and the implications for supply continuity, pricing negotiation leverage, and the risk of technology lock-in as platform ecosystems mature
These priorities are interdependent. A procurement decision influences workflow agility; a partnership choice affects data integration capabilities; a regulatory preparation strategy shapes long-term market access. The report provides a structured framework to evaluate these trade-offs in a unified manner, enabling more coherent strategy formulation across R&D, commercial, and compliance functions.
Access the Full Intelligence Landscape
The DNA sequencing market is entering a phase where competitive advantage will increasingly derive from the ability to integrate technology selection, application focus, regulatory readiness, and data strategy into a coherent operating plan. Aggregate growth figures provide context, but durable strategy requires deeper segmentation, scenario analysis, and competitive benchmarking. This research is designed to bridge that gap, offering the granularity needed to support capital allocation, product planning, and market entry decisions throughout the forecast period.
For executives and analysts seeking to move beyond high-level trends and into actionable market intelligence, the full report delivers detailed segmentation analysis, competitive profiles, regulatory impact assessment, and forecast scenarios built for corporate decision-making. The complete dataset, methodology documentation, and strategic recommendations are available through our official research portal, where the full depth of the analysis can be reviewed and applied to your specific strategic context.
For detailed analysis of this topic, please visit the official page: DNA Sequencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com