

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Band Saw Blade Market Hits $1.75B in 2025, Projected 5.5% CAGR to $2.53B by 2032

Strategic Intelligence for the Next Seven Years: Navigating the Band Saw Blades Market (2026–2032)
Powering Precision Manufacturing Through Measurable Growth
The global band saw blades market stands at a decisive inflection point. Over the historical review period from 2020 to 2025, the sector demonstrated remarkable resilience, advancing from a baseline of approximately $1,500 million to an estimated $1,750 million in the most recent base year. As manufacturing enterprises recalibrate their capital allocation strategies for the forecasted 2026–2032 horizon, our latest comprehensive market study delivers the analytical clarity required to transform macroeconomic tailwinds into competitive advantage. With a projected compound annual growth rate of 5.5 percent, the market is on a clear trajectory toward sustained expansion, driven by intensifying industrial automation, resurgence in heavy structural fabrication, and evolving material-handling requirements across both traditional and emerging end-use verticals.
This executive overview serves as a strategic preamble to our full research publication. It outlines the market mechanics, competitive architecture, and operational variables that will define procurement, product development, and market-entry decisions throughout the forecast period. While the headline trajectory points to unambiguous growth, the true strategic value lies beneath the surface—in the nuanced interplay between material cost volatility, regulatory compliance frameworks, regional supply chain realignments, and the rapid productization cycles of incumbents. Decision-makers who understand these underlying dynamics will be best positioned to optimize inventory strategies, negotiate supplier contracts, and capture margin expansion in an increasingly concentrated industry landscape.
Market Trajectory and the Strategic Imperative for 2026
The seven-year forward projection maps a clear acceleration phase. Following a modest contraction observed in 2023 that reflected broader industrial slowdowns and post-pandemic supply normalization, the market rebounded forcefully. The 2024–2025 recovery established a new operational baseline, and the forecast extends this momentum through 2032. By the close of the projection window, total market revenue is expected to approach the $2,500 million threshold. This trajectory is not merely a numerical exercise; it signals a structural shift in how manufacturers specify cutting tooling, evaluate total cost of ownership, and balance performance against operational safety requirements.
For procurement leaders and strategic planners, the 2026 decision window is particularly critical. Capital-intensive projects initiated this year will lock in tooling specifications and supplier relationships well into the late 2020s. Early movers who align their procurement roadmaps with the forecasted growth corridors can secure favorable pricing, mitigate raw material exposure, and establish long-term service-level agreements before capacity constraints tighten. Conversely, organizations that treat band saw blades as commoditized consumables risk margin erosion and operational downtime as premium-grade tooling becomes increasingly differentiated by material science, tooth geometry optimization, and application-specific engineering.
Our research translates these macro projections into actionable planning frameworks. The report maps growth vectors against production capacity expansions, raw material sourcing strategies, and regional demand shifts, enabling executives to stress-test their five-year operating plans against multiple scenario assumptions. By focusing on the structural drivers rather than transient pricing fluctuations, organizations can build procurement and supply chain strategies that remain robust across cyclical variations.
Competitive Architecture and Strategic Positioning
The band saw blades market is characterized by a concentrated competitive environment where scale, material expertise, and application-specific innovation act as primary differentiators. Our analysis identifies a clear tier of market leaders whose combined footprint shapes pricing dynamics, technology roadmaps, and channel access. Understanding how these players position themselves is essential for both incumbents defending share and new entrants evaluating market entry pathways.
Worldwide Welded Band Saw Blades Market
European manufacturers continue to anchor the high-precision segment, leveraging deep metallurgical heritage and established global distribution networks. WIKUS-Sägenfabrik Wilhelm H. Kullmann GmbH & Co. KG, headquartered in Spangenberg, Germany, remains Europe’s largest dedicated band saw blade manufacturer, delivering precision metal-cutting solutions backed by an expansive international sales infrastructure. Their recent activity underscores a deliberate focus on large-scale industrial applications and continuous product innovation. In mid-2025, WIKUS secured a landmark deployment when its SKALAR X3000 band saw blade was selected for the world’s largest band saw, a machine engineered for workpiece capacities reaching 5,100 millimeters. This followed a strong exhibition presence at Blechexpo 2025, where the company showcased advanced solutions for industrial sheet metal processing, and a subsequent demonstration of cutting-edge sawing technologies at NORTEC 2026 in Hamburg. These milestones illustrate how leading European players are aligning product engineering with the most demanding heavy-industrial specifications.
On the North American front, premium engineering and heavy-duty fabrication expertise define the competitive posture. The L.S. Starrett Company, based in Athol, Massachusetts, maintains a strong reputation for bi-metal construction and optimized tooth geometry across metal, wood, plastics, and composite applications. The M. K. Morse Company, headquartered in Canton, Ohio, competes aggressively in the heavy structural steel and superalloy segments, emphasizing American-made production and carbide-tipped tooling for high-production environments. DoALL Company Inc. rounds out the U.S. lineup with a full-line industrial metal fabrication portfolio spanning bi-metal and carbide-tipped offerings. These manufacturers leverage stringent quality standards, domestic supply chain advantages, and application-specific engineering to command premium positioning in demanding fabrication sectors.
Specialized German producers and diversified international players further shape the competitive matrix. ARNTZ GmbH + Co. KG, operating from Remscheid, focuses on carbide-tipped and bi-metal blades for industrial metal and construction materials, with recent catalog expansions reinforcing their commitment to advanced carbide-tipped solutions. JN Eberle & Cie. GmbH, based in Augsburg, emphasizes precision and durability in specialized metal-cutting blades. Across the Atlantic, Bahco International in Sweden drives heavy-duty metal cutting with trimetal and bi-metal series, including the Easy-Cut Xtreme line. Pilana Metal s.r.o. in the Czech Republic extends the bi-metal and wood-cutting portfolio, while Simonds Saw and Steel Company maintains a strong presence across industrial and woodworking applications in the United States. In Asia, Dalian Special Steel Products Co. Ltd. has emerged as a notable supplier of bi-metal blades engineered for high-strength steel and industrial-grade requirements, reflecting the broader regional shift toward specialized tooling production.
With the top three players collectively accounting for approximately 65 percent of global revenue and the top five extending that share to 75 percent, market concentration is a defining strategic variable. This structure compresses the window for un differentiated market entry and elevates the importance of application-specific value propositions, regional distribution partnerships, and compliance-driven quality certifications. Our report dissects these competitive dynamics in granular detail, mapping market share trajectories, product portfolio overlaps, and strategic response patterns to help organizations identify white-space opportunities and anticipate competitive countermoves.
Segmentation Architecture: Application and Material Differentiation
Beneath the aggregate growth figures lies a highly differentiated segmentation landscape where material science and end-use requirements dictate pricing, performance benchmarks, and procurement cycles. The report deconstructs these segments without oversimplifying the trade-offs that manufacturing engineers and procurement teams must navigate.
Material composition remains the foundational axis of differentiation. Bi-metal blades capture the dominant share of the market, reflecting their balanced performance profile across general metal cutting, extended service life, and adaptive tooth geometry. Carbide-tipped variants occupy a high-value niche, favored for abrasive materials, hardened alloys, and high-production environments where reduced downtime and consistent cut quality justify elevated unit costs. Carbon steel and other specialized formulations address specific cost-sensitive or application-tailored requirements. The interplay between raw material availability, alloy pricing, and manufacturing yield directly influences segment-level margin structures. High-carbon strip steel serves as the primary input for band saw blades, with pricing subject to volatility driven by global steel supply dynamics. Simultaneously, supply chain disruptions and price fluctuations in high-speed steel alloys continue to pressure production economics for advanced tooling, making strategic sourcing and inventory buffering critical competencies.
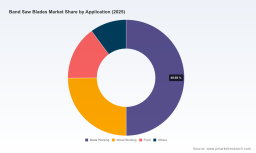
Application-driven segmentation reveals complementary demand engines. Metal working remains the largest consumption basin, reflecting the breadth of fabrication, structural steel processing, and precision machining operations that depend on reliable band saw performance. Wood working sustains a steady, mature demand profile, while food processing applications introduce specialized hygiene, corrosion resistance, and regulatory compliance requirements that differentiate tooling specifications from traditional industrial segments. Additional niche applications span composite cutting, maintenance repair and overhaul operations, and specialty material processing. The report examines how these application verticals interact with regional manufacturing footprints, automation adoption rates, and end-market capital expenditure cycles, enabling readers to align product development roadmaps with the highest-value demand pockets.
We intentionally reserve the full breakdown of segment-level revenue contributions, exact regional distribution figures, and precise application share percentages for the complete dataset. This deliberate approach ensures that strategic readers engage with the complete analytical framework, where segmentation data is contextualized against pricing tiers, regional cost structures, and competitive density maps.
Regulatory, Operational, and Supply Chain Dynamics
Technical performance alone no longer determines competitive outcomes in the band saw blades market. Regulatory compliance, operational safety mandates, and supply chain resilience now function as strategic gates that shape market access, production planning, and procurement risk. Organizations that integrate these variables into their strategic planning will navigate the forecast period with greater agility and lower exposure to operational disruption.
Safety and quality standards impose non-negotiable operational disciplines. European and United States safety regulations mandate periodic inspection and tension testing for band saw blades to ensure operational safety across industrial environments. In parallel, ISO 9001 certification has become a baseline requirement for manufacturers seeking to maintain quality control in precision metal cutting, influencing supplier evaluation criteria, audit schedules, and contract eligibility. In Europe, CE marking compliance ensures that band saw blades and associated equipment meet industrial safety requirements for metal processing machinery, adding a layer of regulatory due diligence for both producers and end-users. These standards are not merely compliance checkboxes; they shape production workflows, documentation systems, and warranty structures, and they increasingly serve as proxies for supplier reliability in procurement scoring models.
Raw material and supply chain dynamics introduce continuous cost and availability uncertainty. The dependence on high-carbon strip steel and specialized high-speed steel alloys ties band saw blade economics to broader metallurgical market cycles. Geopolitical trade flows, energy cost fluctuations, and regional capacity constraints can trigger rapid input price shifts, which in turn affect finished blade pricing and margin stability. Manufacturers with vertically integrated sourcing, diversified supplier bases, and forward hedging strategies are better equipped to absorb volatility and protect competitive pricing. Procurement teams must therefore evaluate not only unit price and delivery lead times, but also supplier resilience, certification compliance, and exposure to upstream material constraints.
These dynamics create a strategic environment where differentiation is built on reliability, compliance assurance, and total cost of ownership rather than headline specifications alone. The complete report maps these operational and regulatory factors against regional market structures, enabling organizations to quantify compliance burden, assess supplier risk profiles, and align sourcing strategies with evolving safety and quality expectations.
What the Full Study Delivers: Methodology, Data Architecture, and Decision Frameworks
The complete Band Saw Blades Market research publication is engineered as a decision-support instrument rather than a static data repository. It integrates historical performance tracking, forward-looking demand modeling, competitive benchmarking, and operational scenario analysis into a cohesive analytical architecture. The methodology combines bottom-up segment evaluation, top-down macroeconomic correlation, and primary industry intelligence to produce a multi-layered view of market behavior across the 2026–2032 forecast window.
Readers gain access to a structured suite of analytical outputs designed for immediate strategic application. The report provides granular market sizing across historical and forecasted periods, enabling revenue projection alignment with internal planning cycles. It examines competitive positioning through company profiles, product portfolio mapping, and recent strategic developments, including trade fair activations, catalog expansions, and flagship product deployments that signal shifting technology priorities. It evaluates segmentation dynamics across material types, application verticals, and regional demand centers, contextualizing each segment within pricing structures, growth drivers, and competitive intensity. It also assesses the regulatory and raw material landscape, translating compliance requirements and supply chain variables into operational risk indicators and procurement planning parameters.
Band Saw Blades Market
To support scenario-based planning, the study incorporates sensitivity considerations around raw material pricing trajectories, capacity expansion timing, and regional demand variation. Rather than presenting a single deterministic forecast, the research equips decision-makers with the contextual ranges and structural drivers needed to test internal assumptions against realistic market behavior. This approach is particularly valuable for capital equipment manufacturers, tooling distributors, procurement departments, and investors evaluating exposure to industrial fabrication and metalworking end-markets.
Detailed regional revenue distributions, exact application share percentages, and precise segment-level monetary breakdowns are embedded within the complete dataset and interactive analytical modules. These elements are intentionally excluded from this executive preview to preserve the integrity of the full research offering and to ensure that strategic users access the complete contextual framework required for accurate market modeling.
Strategic Outlook: Securing Advantage in a Concentrated, Compliance-Driven Market
The band saw blades market entering 2026 rewards disciplined strategic positioning. Growth is real and structurally supported, but it is distributed unevenly across segments, regions, and competitive tiers. Organizations that succeed will be those that treat blade procurement and product development as strategic capabilities rather than transactional functions. That means aligning specification standards with application requirements, embedding compliance and safety expectations into supplier selection, and building sourcing strategies that can withstand raw material volatility without sacrificing performance or delivery reliability.
For incumbents, the priority is to protect premium positioning through continuous product innovation, certified quality systems, and application-specific engineering that raises switching costs for end-users. For distributors and channel partners, the opportunity lies in expanding technical advisory capabilities, bundling tooling with service and maintenance agreements, and strengthening regional inventory positioning to reduce lead-time risk. For new market entrants and investors, the concentrated competitive structure demands a clear value proposition—whether through specialized carbide-tipped applications, regional cost advantages, or differentiated service models—rather than head-on confrontation with established multi-product portfolios.
The full market study provides the analytical depth required to translate these strategic imperatives into concrete action plans. By combining historical trajectory validation, forward growth modeling, competitive benchmarking, and operational risk mapping, the research equips leadership teams with the intelligence needed to allocate capital, negotiate supplier relationships, and prioritize product development where margin and market position can be defended or expanded.
Contact and Access
This executive preview has outlined the strategic architecture of the global band saw blades market and the decision-critical variables that will shape the 2026–2032 forecast period. The complete research publication extends this foundation with full market sizing, detailed segmentation analysis, comprehensive competitive profiling, and scenario-based planning frameworks tailored for executive, procurement, and investment audiences. To access the complete dataset, interactive analytical tools, and company-level strategic assessments, please visit the PW Consulting research portal and request the full Band Saw Blades Market study. Our advisory team is available to discuss customized briefing sessions, data licensing options, and sector-specific applications of the research findings.
For detailed analysis of this topic, please visit the official page: Band Saw Blades Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com