
Blogs
PW Consulting: Trehalose Market to Reach $275M by 2032, Growing at 5.45% CAGR
By pmarketresearch, 2026-09-15
### Strategic Trajectory of the Global Trehalose Market: Navigating Value Creation Opportunities Through 2032
Executive Perspective
In an era where ingredient functionality directly dictates product shelf-life, consumer acceptance, and formulation economics, few compounds offer the multifunctional promise of trehalose. As a non-reducing disaccharide celebrated for its moisture-retention capabilities, thermal stability, and ability to preserve structural integrity in proteins and cellular matrices, trehalose has transitioned from a specialized biochemical reagent to a cornerstone ingredient across food, nutraceutical, pharmaceutical, and cosmetic supply chains. Our latest comprehensive market intelligence report dissects this evolution with meticulous granularity, positioning procurement leaders, R&D directors, and corporate strategists to make informed capital allocations and portfolio adjustments for the 2026 horizon and beyond.
The global trehalose market has demonstrated resilient expansion over the past half-decade, climbing from a baseline valuation of 130.0 million USD in 2020 to an estimated 190.85 million USD in 2025. This trajectory reflects sustained demand pull from clean-label formulation shifts, heightened investment in biologic stabilization technologies, and the gradual commercialization of trehalose-enabled cosmetic actives. Our forecast window extends through 2032, projecting the market to reach 275.0 million USD. This expansion translates to a compound annual growth rate of 5.45 percent, a figure that underscores steady, non-speculative growth rather than erratic hype cycles. For decision-makers, this CAGR is not merely a top-line metric; it signals a mature yet still structurally expanding addressable market where early positioning, supply chain resilience, and application-specific differentiation can yield disproportionate returns.
Market Architecture and Growth Drivers
Historical Resilience and Forecast Trajectory
The historical record from 2020 through 2025 reveals a market that navigated pandemic-era logistics disruptions, raw material volatility, and shifting regulatory frameworks without losing momentum. The year-over-year progression from 146.74 million USD in 2021 to 159.09 million USD in 2022, then to 172.06 million USD in 2023, illustrates incremental but compounding demand. By 2024, the market reached 176.61 million USD, and the acceleration into 2025 at 190.85 million USD suggests that trehalose has embedded itself deeply into industrial workflows. Looking ahead, the forecast period paints a picture of sustained scaling: 204.22 million USD in 2026, 218.92 million USD in 2027, a slight recalibration to 216.8 million USD in 2028 reflecting expected short-term supply chain rebalances, and then renewed expansion toward 235.33 million USD in 2029, 243.67 million USD in 2030, 260.96 million USD in 2031, and finally 275.0 million USD in 2032. This trajectory signals that trehalose demand is not cyclical but structurally anchored in multiple end-use verticals.
Structural Segmentation Dynamics
Our report deconstructs the market into three primary segmentation dimensions: product formulation type, end-use application, and regional distribution. In the type dimension, the landscape is divided between powdered and liquid trehalose formats, each serving distinct handling, dosing, and formulation requirements. Powdered trehalose commands a larger absolute share, reflecting its versatility in bulk industrial processing, dry blend applications, and extended shelf-life storage. Liquid trehalose, meanwhile, addresses continuous-process manufacturing environments and specific beverage or liquid formulation workflows where dissolution speed and dosing precision are paramount. Both formats are expanding, but their relative attractiveness varies sharply by vertical and by regional manufacturing infrastructure.
Trehalose Market
D-Mannose Market
In the application dimension, food and beverage applications represent the largest consumption pool, driven by trehalose's function as a mild sweetener, texture modifier, and moisture stabilizer in baked goods, confectionery, and frozen desserts. Dietary supplements and nutraceuticals constitute a meaningful secondary stream, leveraging trehalose's reputation for cellular protection and metabolic neutrality. The pharmaceutical sector represents a high-value, high-specification niche where trehalose dihydrate serves as a critical cryoprotectant, lyoprotectant, and formulation stabilizer for biologics, vaccines, and cell therapies. Cosmetics and personal care applications, while smaller in absolute volume, are expanding rapidly as formulators seek naturally derived humectants and skin-barrier-supporting sugars with clean-label profiles. A residual others category captures specialized industrial and research uses that, while niche, often command premium pricing and technical service requirements.
Regionally, the market exhibits a multi-polar distribution. North America maintains a leading position, supported by advanced pharmaceutical development pipelines, well-established food ingredient distribution networks, and strong consumer demand for functional and clean-label products. Europe follows as a substantial market, shaped by stringent quality expectations, a robust cosmetics and personal care ecosystem, and growing pharmaceutical biomanufacturing activity. Asia Pacific represents a high-growth engine, where expanding food processing capacity, rising healthcare expenditure, and localized manufacturing investments are driving both volume growth and supplier diversification. Latin America and the Middle East and Africa collectively represent smaller but strategically emerging footprints, where import dependencies, regulatory evolution, and infrastructure development create both challenges and first-mover opportunities. The precise regional value distribution, application-level breakdowns, and type-specific volume allocations are mapped in exhaustive detail within the full report, enabling granular scenario modeling that goes far beyond aggregate market sizing.
Competitive Landscape and Strategic Positioning
The trehalose market is characterized by a moderately concentrated supplier base, with the top three players accounting for approximately 45 percent of total market revenue and the top five collectively commanding around 65 percent. This concentration reflects the technical barriers associated with high-purity production, enzymatic process optimization, and, in the pharmaceutical grade segment, compliance with pharmacopoeial standards and low-endotoxin specifications. Yet the remaining market share is distributed among a diverse set of regional and application-focused suppliers, creating a landscape where competitive advantage is increasingly defined by application engineering, regulatory readiness, and supply reliability rather than volume alone.
Nagase & Co., Ltd., headquartered in Tokyo, Japan, exemplifies the high-purity, application-engineered approach. Through its TREHA® brand, the company manufactures high-purity trehalose via a proprietary enzymatic process derived from starch, supplying food and beverage ingredient channels with a product designed for clean-label, texture-preserving, and flavor-modulating formulations. Nagase's positioning emphasizes technical service, regulatory documentation, and consistent quality, aligning with customers who prioritize formulation predictability and label credibility.
Shandong Fuyang Biotechnology Co., Ltd., based in Pingyuan, Shandong, China, operates within the corn deep-processing ecosystem and produces food-grade trehalose as part of a broader carbohydrate ingredient portfolio. Its export-oriented model reflects the growing integration of Asian starch-derived ingredient manufacturing into global supply chains. Meihua Holdings Group Co., Ltd., located in Langfang, Hebei, China, similarly leverages its scale and integrated processing capabilities to supply trehalose as a colloidal polysaccharide ingredient, emphasizing freshness preservation and product quality enhancement in food applications. Meihua's commitment to environmental management, evidenced by full ISO 14001 certification coverage, signals an ESG-aware supplier profile that increasingly matters to multinational procurement teams.
On the Western side, Cargill, Incorporated, headquartered in Minneapolis, USA, distributes and supplies food-grade trehalose dihydrate tailored for bakery, confectionery, and clean-label applications. Cargill's strength lies in its global distribution reach, formulation expertise, and ability to embed trehalose within broader sweetener and functional ingredient portfolios. Pfanstiehl, based in Waukegan, Illinois, USA, occupies a distinct high-value niche by manufacturing USP-NF, EP, JP, and ChP-grade high-purity, low-endotoxin trehalose dihydrate for biopharmaceutical stabilization and cryopreservation. Pfanstiehl's compliance with multiple pharmacopoeial standards and its focus on endotoxin control make it a critical partner for biotechnology and pharmaceutical customers where quality specifications are non-negotiable and batch consistency directly impacts product viability.
Additional suppliers such as Shandong Deshang Chemical Co., Ltd. and Changyi Longchang Bio-Chemical Co., Ltd., both operating from the Shandong region of China, contribute to a vibrant competitive ecology. Shandong Deshang remains an active supplier of trehalose for food applications, while Changyi Longchang manufactures trehalose as a core product for food and ingredient markets. The presence of multiple capable Chinese producers underscores the region's importance as both a manufacturing hub and a competitive pressure point on pricing and supply agility. The full report provides detailed corporate profiles, competitive positioning assessments, and strategic implication analyses for each key player, enabling clients to benchmark their own supplier relationships and identify potential partnership or substitution opportunities.
Regulatory and Industry Dynamics Shaping the Road Ahead
Trehalose's commercial expansion is being reinforced by a series of regulatory clarifications and industry-level developments that reduce uncertainty and broaden addressable use cases. Health Canada has formally notified Hayashibara International Inc. and Cargill, Inc. that it has no objection to the use of trehalose for human food applications, a determination that removes a potential barrier for Canadian market access and reinforces international regulatory alignment. Simultaneously, the pharmacopoeial landscape has consolidated around trehalose's role in high-specification pharmaceutical use. Pfanstiehl's trehalose is available in USP-NF, EP, and JP grades, reflecting the multi-jurisdictional compliance requirements of global biopharmaceutical supply chains. In parallel, Nagase Viita Co., Ltd., operating as Nagase Food Ingredients, continues to manufacture TREHA® via its proprietary enzymatic starch-conversion process, underscoring the importance of process innovation in maintaining quality consistency and cost efficiency.
Regulatory dynamics are not static, and procurement strategies must account for evolving food additive classifications, novel food notifications, and pharmacopoeial updates. Our report embeds these regulatory trajectories within the broader market dynamics section, illustrating how compliance pathways can create entry barriers, expand addressable markets, or shift competitive advantage among suppliers with differing certification portfolios.
Operational Content and Decision-Support Architecture
This market research report is designed as a decision-support instrument rather than a static data compilation. It integrates macroeconomic context, segmentation analysis, competitive profiling, and regulatory intelligence into a coherent narrative that supports actionable planning. The report content includes detailed volume and value analysis across the forecast horizon, decomposed by type, application, and region. It provides market concentration metrics and supplier share assessments that help clients evaluate bargaining power, supply risk, and partnership potential. It maps historical growth patterns against projected trajectories, enabling sensitivity analysis around demand shocks, raw material cost fluctuations, and regulatory changes.
The operational scope extends to application-specific usage patterns, formulation advantages, and technical requirements that distinguish one end-use vertical from another. For food and beverage teams, the report examines how trehalose functions as a moisture regulator, texture stabilizer, and flavor modulator, and where it can replace or complement existing ingredients without triggering label or cost penalties. For dietary supplement and nutraceutical strategists, the focus shifts to metabolic neutrality, stability in dry and liquid formats, and alignment with consumer-facing wellness narratives. For pharmaceutical and biotech decision-makers, the report addresses grade requirements, endotoxin control, cryopreservation performance, and the implications of pharmacopoeial compliance for supply chain qualification. For cosmetics and personal care developers, the analysis highlights humectant behavior, skin-barrier compatibility, and clean-label positioning in an increasingly crowded functional sugar landscape.
Beyond segmentation and application analysis, the report provides a structured view of market drivers, restraints, opportunities, and challenges. It evaluates the interplay between raw material availability, process technology maturity, regulatory clearance timelines, and end-market demand elasticity. It maps historical resilience against forward-looking risk factors, allowing procurement and strategy teams to stress-test their assumptions. All regional and application-level percentage splits, specific revenue figures by sub-segment, and granular supplier-level volume estimates are disclosed in full within the complete report. This deliberate depth ensures that clients can run their own scenario models, calibrate procurement timing, and identify the exact sub-markets where investment, reformulation, or supply diversification will generate the greatest incremental value.
Strategic Implications for 2026 and Beyond
For enterprise decision-makers, the trehalose market presents a rare combination of steady macro growth and segmented opportunity pockets. The overall 5.45 percent CAGR through 2032 signals that the market is expanding in a predictable, structurally supported manner, but predictability should not be mistaken for uniformity. The largest absolute opportunity resides in the food and beverage vertical, where trehalose's functional attributes align with clean-label reformulation, texture optimization, and shelf-life extension. The highest specification and margin potential resides in pharmaceutical and biopharmaceutical applications, where grade compliance, low-endotoxin performance, and batch reproducibility justify premium pricing and long-term supply agreements. The cosmetics and personal care segment offers a high-growth adjacency where trehalose's humectant and barrier-supporting properties can be leveraged in premium skincare, barrier repair formulations, and naturally derived ingredient narratives. Dietary supplements and nutraceuticals add a further layer of opportunity, particularly where trehalose can be positioned around cellular protection, stability, and metabolic benignity.
Regional strategy will be equally important. The leading regional markets each present distinct procurement profiles, regulatory frameworks, and supplier ecosystems. North American and European customers benefit from established distribution infrastructures and deep technical service capabilities among global suppliers, but they also face pricing and margin pressures from efficient Asian manufacturers. Asian Pacific markets offer volume growth and localized supply options, but they require careful navigation of quality assurance, export logistics, and application-specific technical support. Latin America and the Middle East and Africa, while smaller in current scale, are relevant for companies seeking geographic diversification, import substitution, or early entry into developing food and pharmaceutical manufacturing corridors. The complete report quantifies these regional dynamics and provides the sub-segment breakdowns necessary to prioritize investments by geography and application.
Competitive strategy should also account for the moderately concentrated supplier base. The top three and top five players hold significant revenue share, but the presence of multiple capable regional producers creates both collaboration and negotiation leverage. Procurement teams can use the market concentration data to assess supply security, benchmark pricing, and evaluate whether dual-sourcing or specification-tailored supplier portfolios are warranted. R&D and formulation teams can use the application and type segmentation to identify where powdered versus liquid formats are most cost-effective and where supplier technical documentation and regulatory support will accelerate time-to-market. Executive teams can use the forward-looking forecast to align capital expenditure, capacity planning, and partnership discussions with a market that is expanding but not inflating, allowing disciplined, evidence-based growth strategies.
Call to Strategic Engagement
The trehalose market is at an inflection point where functional necessity, regulatory clarity, and supplier maturity are converging to create durable growth across multiple verticals. Yet the precise magnitude of opportunity in each sub-segment, the exact regional value distribution, and the detailed supplier-level share allocations remain strategically sensitive information that can differentiate early movers from late followers. Our full market research report is built to provide that intelligence with analytical rigor, commercial relevance, and actionable structure.
This article has outlined the macro trajectory, segmentation logic, competitive architecture, and regulatory context that define the market's current shape and forward path. The complete report goes further, delivering the exact segmentation percentages, regional revenue breakdowns, application-level consumption splits, and detailed competitive profiles that enable precise procurement timing, portfolio prioritization, and risk calibration. For organizations that need to make 2026 sourcing decisions, evaluate reformulation options, assess supplier partnerships, or build long-range demand models through 2032, this research provides the evidentiary foundation required to move from assumption to confidence. We invite strategic leaders to access the complete report to unlock the full depth of market intelligence and translate structural growth into measurable commercial advantage.
For detailed analysis of this topic, please visit the official page: Trehalose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Viscose Filament Yarn Market Reaches $2.89B in 2025, Projected 5.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Next Decade: Unlocking the Viscose Filament Yarns Market Opportunity
The global textile and industrial materials landscape is undergoing a structural transformation. As sustainability mandates tighten, supply chains reconfigure, and performance expectations rise, Viscose Filament Yarns (VFY) have emerged as a critical intermediary between traditional cellulosic manufacturing and next-generation sustainable textiles. For executives, procurement leaders, and strategic planners, understanding where this market is headed is no longer optional; it is a prerequisite for capital allocation, product positioning, and regional expansion.
PW Consulting’s latest deep-dive research on the Viscose Filament Yarns Market is designed to convert macroeconomic complexity into actionable decision architecture. Drawing on a rigorous historical baseline spanning 2020 through 2025 and projecting forward through 2032, this report offers a multi-dimensional view of value creation, competitive pressure points, and regulatory inflection moments that will define the industry over the next seven years.
The market’s trajectory signals a steady expansion path. From a global revenue baseline of approximately 2.27 billion USD in 2020, the sector has advanced through consistent year-over-year growth, reaching an estimated 2.89 billion USD in 2025. The forward-looking forecast places the market on a measured 5.5 percent compound annual growth rate trajectory, with valuations expected to surpass 3.0 billion USD in 2026 and continue a sustained upward curve toward the early 2030s. These figures are not merely historical artifacts; they encode the underlying demand resilience of textile applications, the gradual diversification into medical and industrial end-uses, and the persistent influence of regional manufacturing gravity. More importantly, they establish the scale at which competitive advantage must now be engineered.
For business leaders operating in or adjacent to this market, the strategic question is no longer whether the category will grow, but how to position within a landscape where feedstock volatility, certification expectations, trade policy shifts, and product differentiation intersect simultaneously. This research was built to answer precisely that question.
Viscose Fiber Market
Why This Research Matters for 2026 Decision-Making
The year 2026 represents a pivotal planning horizon. Companies are finalizing capacity commitments, renegotiating supplier frameworks, and aligning product roadmaps with incoming regulatory and sustainability requirements. In this environment, decision-makers need more than aggregated market size numbers. They need a structured view of how demand is distributed across end-use verticals, how regional manufacturing footprints influence pricing and supply security, and how type-level product segmentation reflects commercial priorities such as luster, dyeability, and downstream processing compatibility.
This report is engineered to support that level of operational reasoning. Rather than presenting a single-line growth narrative, the analysis connects market size evolution with the underlying structural drivers that will determine which participants capture margin resilience and which face squeeze. Readers will find a carefully designed framework for interpreting where volume concentrates, where value differentiation is emerging, and where external shocks—whether raw material price swings or trade remedy actions—can reshape short-term profitability.
Equally important, the research is designed to support cross-functional alignment. Strategy teams can use the forecast architecture to test expansion assumptions. Commercial teams can use the segmentation logic to refine positioning against competing fiber categories. Sustainability and compliance teams can use the regulatory and certification discussion to identify where traceability and certification are moving from differentiator to requirement. By integrating these lenses into one coherent intelligence package, the report reduces the risk of siloed decision-making.
Inside the Report: What the Analysis Delivers
A market study earns its value through practical utility. This report is structured to give executives a working map of the Viscose Filament Yarns landscape, not just a static description of it. The analytical content is built to support scenario planning, competitive benchmarking, and entry-or-retreat decisions across multiple dimensions.
At the core of the report is a historically grounded forecast model that traces how the market has moved from its 2020 base through the most recent baseline year and into the projection window extending to 2032. This temporal structure allows readers to evaluate whether recent growth patterns reflect cyclical recovery, structural demand shifts, or region-specific manufacturing expansion. The forecast framework is presented in a way that supports sensitivity reasoning, enabling users to test how changes in feedstock cost, demand elasticity, or trade conditions could alter outcomes.
The segmentation architecture is deliberately designed to illuminate commercial reality. Readers will examine how the market divides by geography, revealing where production concentration, demand pull, and supply chain thickness shape regional competitiveness. The report also breaks down the category by product type, distinguishing between bright and dull viscose filament yarns and explaining how these variants map to different textile finishing requirements, end-market preferences, and price-performance trade-offs. In parallel, the application view provides a structured reading of where demand is anchored, with textiles representing the dominant anchor of market volume and medical, industrial, and other end-uses contributing more specialized, often higher-value demand streams.
Beyond segmentation, the report delivers operational content that leadership teams can use immediately. This includes a supplier and competitor landscape that maps out the strategic posture of key manufacturing players, an assessment of capacity and product range dynamics, and a review of recent launches, facility expansions, and production upgrades that signal where the industry is placing its bets. The study also addresses raw material exposure, particularly the role of dissolving wood pulp and other cellulosic inputs in shaping production economics. Where relevant, pricing movement and feedstock shifts are discussed as leading indicators rather than isolated events, helping readers anticipate cost pressure before it reaches the bottom line.
To support execution, the research also examines the regulatory and standards environment shaping procurement and product design. From sustainability claim verification to trade remedy investigations and regional policy direction, the report connects compliance pressure with commercial consequence. This is especially important for organizations that source across borders or plan to position certified, traceable, or recycled-content yarns as part of their differentiation strategy.
Competitive Landscape: Who Is Shaping the Market
The Viscose Filament Yarns market is defined by a concentrated yet strategically diverse competitive field. Market leadership is not uniform; it varies by region, product range, sustainability positioning, and integration depth across the cellulosic value chain. Understanding these differences is essential for evaluating supplier risk, partnership opportunities, and competitive threats.
Several large-scale producers anchor the industry. In India, Grasim Industries Limited stands out as a major viscose filament yarn manufacturer with broad denier coverage and a developing emphasis on traceable, sustainably sourced product lines. Its recent introduction of a sustainable traceable variant under its established brand family reflects a wider industry push toward verifiable sourcing and differentiated product storytelling. Across China, the competitive picture is equally significant, with multiple integrated players operating at substantial scale. Jilin Chemical Fiber Co., Ltd. represents a producer focused on expandingNext-generation grades with certified wood feedstocks and recycled cotton content, signaling that sustainability-related input strategies are increasingly becoming part of core production planning rather than peripheral branding.
Xinxiang Bailu Chemical Fiber Co., Ltd. contributes to the Chinese manufacturing base with a diversified viscose product set spanning filament, embroidery, and dyeing yarns. Yibin Grace Group Co., Ltd. has pushed further into recycled-content positioning, supported by dedicated capacity and the establishment of a recycled textile dissolving pulp facility, an infrastructure move that points to longer-term feedstock independence and circularity ambitions. Sinopec Yizheng Chemical Fibre Co., Ltd. reflects the advantage of integration within a larger state-linked industrial complex, where filament production is tied to broader dissolving pulp and chemical fiber operations. Sateri Holdings Limited operates at exceptional scale within the broader viscose fiber ecosystem and uses that scale to support filament offerings alongside staple and lyocell products, with a strong international footprint and certification-aligned supply chain.
At the premium and sustainability-led end of the spectrum, Lenzing AG remains a defining reference point for closed-loop, wood-based filament and related cellulosic yarns, particularly where high-luster, biodegradable, and performance-oriented characteristics matter. The presence of such players underscores a broader competitive dynamic: the market is not simply competing on volume, but on fiber quality, environmental credentials, processing efficiency, and downstream compatibility.
Viscose Filament Yarns Market
This competitive diversity creates both opportunity and risk. Buyers can leverage supplier variety to negotiate terms, secure supply, and access differentiated product attributes. Producers, in turn, must defend position through capacity reliability, feedstock strategy, product breadth, and increasingly, verifiable sustainability performance. The report maps these dynamics in detail so that readers can judge where consolidation pressure may intensify, where niche leadership can be defended, and where new entrants or expansions may alter regional balance.
Market Dynamics: Feedstock, Regulation, and Trade Pressures
No forecast exists in a vacuum. The Viscose Filament Yarns market is sensitive to a set of external forces that can amplify or dampen growth outcomes over the forecast period. One of the most immediate is raw material economics. Dissolving wood pulp prices have shown periodic volatility, with quarter-over-quarter movement in key sourcing regions directly affecting production cost structures. When feedstock costs rise, pricing power, margin endurance, and contract timing become critical variables. The report treats these cost dynamics as integral to market interpretation rather than as background noise, helping readers understand how input fluctuations can propagate into pricing, regional competitiveness, and demand timing.
Regulatory and policy developments are shaping the market with equal force. Sustainability claim verification is moving from aspirational positioning toward enforceable expectation. The EU Green Deal textile strategy and related Green Claims Directive implementation are accelerating demand for credibly certified viscose filament yarns, especially those supported by FSC or PEFC-aligned sourcing. For manufacturers and buyers alike, certification is increasingly tied to market access, premium positioning, and reputational risk management. The report contextualizes these shifts so that organizations can separate near-term compliance burdens from longer-term strategic requirements.
Trade policy adds another layer of complexity. Anti-dumping investigations and duty recommendations targeting viscose rayon filament yarn imports have emerged in key markets, including actions involving India and Chinese-origin supply. Where such measures progress toward formal duties, they can alter sourcing patterns, change relative price relationships, and affect the competitiveness of cross-border supply chains. These developments are particularly relevant for companies that rely on imported filament or operate in regions where trade remedy outcomes may shift the balance between domestic and overseas supply.
Finally, price movements in the Asian market illustrate how quickly regional conditions can shift. Recent pricing surges tied to cellulose feedstock volatility demonstrate that regional price signals can diverge from global averages and create short-term windows of advantage or disadvantage. By integrating these dynamics into the broader market narrative, the report gives readers a more realistic foundation for planning than a simple demand-growth storyline would provide.
How to Use This Research for Strategic Advantage
The strongest market research does not simply describe the past; it sharpens the next decision cycle. This report is intended to support a range of strategic actions. For organizations evaluating capacity expansion or product line extension, the segmentation and forecast structure provides a basis for testing where demand depth justifies investment. For procurement and sourcing teams, the regional and competitor analysis supports supplier diversification, contract strategy, and exposure management in environments where feedstock and trade conditions can change quickly.
For commercial leaders, the bright versus dull product distinction and the application mix offer a framework for aligning product attributes with customer priorities, whether those priorities center on aesthetics, dye behavior, processing efficiency, or end-use performance. For sustainability and compliance functions, the regulatory discussion helps prioritize certification pathways, traceability investments, and claims substantiation in markets where verifiable sustainability is becoming a condition of participation rather than a voluntary advantage.
Most importantly, the report supports integrated decision-making. Growth potential, competitive intensity, feedstock exposure, and regulatory direction are rarely independent. This research connects them so that executives can evaluate trade-offs more clearly, challenge internal assumptions more effectively, and align strategy across functions with a shared view of the market’s direction.
Conclusion
The Viscose Filament Yarns Market is entering a period in which scale, sustainability, and supply-chain resilience must be managed together. Historical growth has established a meaningful base, and the forward forecast points to continued expansion through the end of the decade and into the early 2030s. Yet the real strategic challenge lies beneath the headline trajectory: understanding where demand is concentrated, how competitors are positioning themselves, how feedstock and trade dynamics influence margin, and how sustainability requirements are reshaping procurement expectations.
PW Consulting’s full market research report provides the depth required to navigate that complexity. It combines historical context, forecast architecture, segmentation logic, competitive profiling, and market-dynamic analysis into a single decision-ready framework. For leaders who need to move beyond surface-level market sizing and toward targeted, evidence-based strategy, the complete study offers the intelligence necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Viscose Filament Yarns Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Nuclear Valve Market Hits $2,143.69M in 2025, Projected 6.1% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Imperatives in the Nuclear Valves Market: A 2026 Decision-Maker's Guide
The nuclear energy sector stands at a critical inflection point. As global decarbonization mandates intensify and energy security concerns reshape national strategies, the reliability of nuclear infrastructure has never been more pivotal. At the heart of this infrastructure lies a specialized, high-stakes component market: nuclear valves. These engineered systems are not merely ancillary equipment; they are the guardians of containment, pressure regulation, and safety protocols within some of the world's most hazardous environments. For executives navigating capital allocation, supply chain resilience, and technology roadmaps, understanding the trajectory of the nuclear valves market is essential.
This article serves as a strategic preview of PW Consulting's latest comprehensive market intelligence product. It outlines the macro-economic currents driving the sector, highlights the competitive architecture defining the landscape, and explains why access to granular, forward-looking data is indispensable for outperforming in 2026. By synthesizing historical performance with projected growth vectors, we provide a foundation for decisions that will define operational success over the next half-decade.
The Macro Landscape: Growth, Scale, and Trajectory
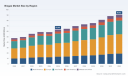
The nuclear valves market has demonstrated consistent resilience and expansion over the past five years. Drawing from our analysis of historical data spanning 2020 through 2025, the market has evolved from a base valuation of 1.60 billion USD in 2020 to an estimated 2.14 billion USD in 2025. This represents a compound annual growth trajectory that underscores the sector's steady maturation and the sustained investment in nuclear capacity worldwide.
Nuclear Valves Market
Looking ahead, our forecast model projects the market to reach 2.23 billion USD in 2026, continuing a growth arc that extends through 2032. By the end of the forecast period, the market is anticipated to approach 3.25 billion USD. This expansion is underpinned by a forecast-period CAGR of 6.1 percent, a figure that signals robust demand driven by reactor restarts, new-build programs, and the modernization of aging facilities. The growth is not merely nominal; it reflects deepening complexity in valve specifications, stricter regulatory compliance requirements, and the integration of advanced materials and digital monitoring systems.
While the headline figures paint a picture of steady expansion, the underlying dynamics are nuanced. Value creation is increasingly concentrated within specific engineering niches, where differentiation stems from certifications, heritage in safety-critical applications, and the ability to support both legacy reactors and emerging technologies like small modular reactors (SMRs). The market's structure, characterized by a consolidated landscape where the top three players command significant share and the top five entities control a substantial majority of revenue, suggests that competitive advantages are deeply entrenched. This concentration implies that new entrants face high barriers, while incumbents leverage long-term utility relationships and certified manufacturing capabilities to maintain pricing power and customer stickiness.
Unpacking the Forecast: Beyond Aggregate Numbers
A superficial glance at the market trajectory might suggest a uniform growth environment. However, the strategic reality is far more segmented. The distribution of value across valve types reveals distinct engineering priorities. Gate valves and globe valves continue to dominate the revenue mix, reflecting their foundational roles in isolation, throttling, and high-integrity containment within nuclear circuits. Ball valves and butterfly valves occupy significant positions, particularly in applications demanding rapid actuation and lower flow resistance profiles. Check valves, diaphragm valves, and other specialized types round out a diversified portfolio that responds to the heterogeneous needs of nuclear facilities.
The application domain further stratifies the market. Nuclear power plants remain the primary revenue engine, absorbing the lion's share of demand as operators focus on reliability, life extension, and compliance with evolving safety codes. Yet, adjacent segments are gaining traction. Research reactors and nuclear waste management applications represent specialized, high-value niches where valve performance criteria diverge sharply from commercial power settings. Waste management, in particular, introduces unique challenges around radiation resistance, long-term sealing integrity, and material degradation, driving demand for purpose-built solutions that command premium positioning.
Geographically, the market's footprint is broad but uneven. Asia Pacific has emerged as a region of considerable scale, reflecting the aggressive nuclear expansion programs in several key economies. North America and Europe continue to represent mature, high-compliance environments where valve procurement is heavily influenced by regulatory frameworks, long-term service agreements, and the need for certified domestic or allied supply chains. Latin America and the Middle East and Africa, while smaller in absolute terms, are regions where infrastructure development and energy diversification initiatives are creating incremental opportunities for qualified suppliers. Understanding how these regional dynamics interact with local content requirements, sanctions regimes, and technology transfer restrictions is essential for firms planning cross-border strategies.
Competitive Architecture: The Incumbents and the New Dynamics
The competitive landscape of the nuclear valves market is defined by a cadre of firms that have invested decades in building technical credibility, regulatory certifications, and deep relationships with utility operators. These companies do not compete solely on price; they compete on audit-ready documentation, code compliance, heritage in specific reactor types, and the ability to deliver integrated valve-actuator packages with full lifecycle support.
Crane Nuclear, headquartered in Kennesaw, Georgia, exemplifies long-standing heritage in the sector. Since 1956, the firm has specialized in manufacturing nuclear-grade gate, globe, check, and quarter-turn valves bearing ASME N and NPT stamps for Class 1, 2, and 3 applications. Its historical footprint includes supplying valves for the first commercial nuclear power plant at Shippingport, and its ongoing diagnostics and services offerings reinforce its position as a trusted partner for commercial nuclear power plants. This legacy translates into a competitive moat built on decades of operational data, regulatory familiarity, and customer trust.
Neway Valve, based in Suzhou, Jiangsu, China, represents the growing capability of Asian manufacturers to meet rigorous international standards. The company produces nuclear gate, ball, globe, check, and butterfly valves qualified to NNSA Grade 1, 2, and 3 design and manufacturing licenses, alongside full ASME N and NPT certificates. Its portfolio is tailored for EPR, AP1000, and Hualong-1 reactors, positioning it as a supplier capable of supporting both established and next-generation reactor designs with full-range nuclear compliance. This dual certification footprint allows Neway to serve markets that demand both domestic regulatory approval and internationally recognized code compliance.
Trillium Flow Technologies, located in Huddersfield, United Kingdom, brings a focused engineering approach to nuclear valves and actuators. The company designs and manufactures engineered nuclear valves and actuators with ASME Section III N and NPT stamps, including safety relief and specialty valves for new-build and operating reactors worldwide. Its active ASME Section III N and NPT stamps at two production sites underscore a commitment to redundancy and supply chain resilience, qualities that are increasingly valued by operators seeking to mitigate single-source vulnerabilities.
Velan Inc., headquartered in Montreal, Quebec, Canada, has carved out a distinctive role in the nuclear space. The company produces nuclear Class 1, 2, and 3 gate, globe, check, and ball valves under ASME N and NPT certificates, and has expanded its relevance into the SMR domain, including projects such as the BWRX-300. Notably, Velan secured the first ASME N stamp for nuclear valves in 1971, and it remains the only manufacturer supplying nuclear valves to the first U.S. small modular reactor project. In October 2025, Velan secured a main services agreement for valves on North America's first small modular reactor project, marking a milestone in the commercialization of SMR valve supply chains.
Flowserve Corporation, based in Irving, Texas, USA, operates at the intersection of pumps, valves, and seals for nuclear applications. Its supply of nuclear-qualified equipment across Class 1-3 applications for global nuclear projects is supported by long-term utility relationships and ongoing SMR qualification programs. Flowserve's breadth of portfolio and established service networks make it a versatile partner for operators seeking integrated fluid control solutions.
Framatome, headquartered in Paris, France, leverages its broader reactor systems expertise to deliver safety-related nuclear valves and actuators. Through subsidiaries including Valserve, Framatome designs and manufactures components for PWRs, BWRs, and advanced reactors under ASME III, RCC-M, and other codes. In April 2025, Framatome completed the acquisition of Trillium Flow Technologies France, rebranding it as Sebim to strengthen its nuclear valves product line. This move signals a strategic consolidation within the European supply base, aiming to bundle valve and actuator capabilities under a unified engineering umbrella. Concurrently, in April 2025, Bruce Power signed a 10-year alliance with Trillium Flow Technologies for nuclear valve supply and related services, illustrating how long-term partnerships are becoming a defining feature of the market's procurement architecture.
Regulatory and Technical Dynamics Shaping Procurement
The nuclear valves market operates within a tightly regulated environment where certification is not a formality but a prerequisite for market access. ASME N and NPT stamps, along with national regulatory approvals such as NNSA grades, function as gatekeepers that separate qualified suppliers from the broader industrial valve market. Companies like Crane Nuclear, which has maintained ASME N and NPT stamps since its inception, and Neway Valve, which holds NNSA Grade 1, 2, and 3 licenses plus full ASME certifications, demonstrate how regulatory standing is intertwined with commercial viability. Trillium Flow Technologies' dual-site ASME Section III N and NPT stamp coverage further highlights how manufacturers are building geographic and operational redundancy to satisfy utility procurement requirements and risk management protocols.
These regulatory dynamics have direct implications for supply chain planning. Utilities and EPC contractors increasingly prioritize vendors that can demonstrate traceability, material certification, and code compliance at every stage of the valve lifecycle. The presence of ASME stamps, the ability to support Class 1, 2, and 3 applications, and the capacity to provide diagnostics and services are becoming differentiators that influence bid evaluation criteria. In this context, market participants that invest in certification maintenance, quality system upgrades, and digital documentation are better positioned to capture high-value contracts and sustain margins.
Why Granular Intelligence Matters for 2026 Decision-Making
While the macro trends and competitive profiles outlined here provide a strategic compass, they are insufficient on their own for operational planning. The nuances that drive procurement decisions, pricing negotiations, and technology adoption are embedded in the granular detail of the market. For example, understanding how the revenue split across valve types correlates with specific reactor programs, or how regional demand patterns align with local content mandates, requires access to segmented data that reveals the interplay between engineering specifications, regulatory environments, and commercial execution.
Valves Market
Similarly, the competitive dynamics are not static. Acquisitions, alliance formations, and certification expansions can shift market share, alter supply chain dependencies, and redefine the value proposition of incumbents overnight. The recent acquisition of Trillium Flow Technologies France by Framatome and the 10-year alliance between Bruce Power and Trillium Flow Technologies are indicative of a market where strategic bundling and long-term service commitments are reshaping competitive boundaries. Decision-makers need to know not just who the players are, but how their capabilities, geographic footprints, and partnership networks are evolving in real time.
This is precisely why PW Consulting's Nuclear Valves Market report is structured to deliver actionable intelligence beyond top-line forecasts. The report provides a deep dive into the segmentation landscape, competitive positioning, regulatory frameworks, and demand drivers that collectively inform capital allocation, vendor selection, and risk mitigation strategies. By mapping the revenue distribution across valve types, application domains, and regions, the report equips stakeholders with the context needed to identify growth pockets, anticipate supply constraints, and align product development with the most promising market vectors.
For executives planning 2026 initiatives, the report offers a structured framework to evaluate where to invest, whom to partner with, and how to navigate the certification and compliance pathways that gate market entry. Whether the objective is to expand into new reactor programs, secure long-term service agreements, or assess the impact of SMR commercialization on valve demand, the granular data and analytical rigor contained in the full report provide a reliable foundation for evidence-based decision-making.
Navigating Forward: From Insight to Action
The nuclear valves market is on a sustained growth trajectory, but growth alone does not guarantee strategic success. The firms that thrive will be those that translate market awareness into disciplined execution: investing in certified manufacturing capabilities, forging durable utility partnerships, adapting to the technical demands of advanced reactors and SMRs, and maintaining a vigilant eye on regulatory evolution. As the market approaches the 2026 horizon, the difference between reactive participation and proactive leadership will be determined by the quality of intelligence and the speed with which insights are operationalized.
PW Consulting's comprehensive research is designed to be that intelligence engine. By delivering a detailed, data-rich, and strategically oriented view of the nuclear valves market, the report enables stakeholders to cut through noise, focus on high-impact variables, and make decisions that compound value over the forecast period. The full analysis, including segmentation breakdowns, competitive assessments, and forward-looking scenarios, is available in the complete report. For those ready to move from strategic overview to precision planning, the next step is to access the full intelligence package and begin aligning 2026 agendas with the realities of a market in transformation.
For detailed analysis of this topic, please visit the official page: Nuclear Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Biogas Market Hits $63.48B in 2025, Projected to Reach $90.82B by 2032 at 5.27% CAGR
By pmarketresearch, 2026-09-15
Navigating the Biogas Transition: Strategic Intelligence for 2026 and Beyond
The global energy landscape is undergoing a structural shift, driven by decarbonization mandates and the urgent need for sustainable waste management solutions. At the heart of this transformation is the biogas sector, a market that has evolved from a niche renewable energy source into a critical component of the circular economy. For corporate strategists, investors, and policymakers, understanding the trajectory of this market is no longer optional it is a prerequisite for resilient decision-making.
PW Consulting is pleased to introduce our latest comprehensive market research, designed specifically to equip stakeholders with the actionable intelligence needed to navigate the complexities of 2026 and the subsequent seven-year forecast period. This report moves beyond surface-level headlines to deliver a granular analysis of market dynamics, competitive positioning, and risk factors that define the current operational environment.
As we enter a new fiscal year, the decisions made today regarding asset allocation, supply chain partnerships, and technology adoption will dictate competitive advantage for the remainder of the decade. The following analysis outlines the macro-economic context and the strategic value embedded within this new research publication, offering a preview of the depth and rigor applied to our findings.
Macro-Economic Trajectory and Market Size
The biogas industry has demonstrated remarkable resilience and growth potential over the past five years. Our historical analysis covering the period from 2020 through 2025 reveals a consistent upward trend in revenue generation across the sector. The market valuation data indicates that the industry has successfully navigated supply chain disruptions and regulatory shifts that challenged other renewable sectors during the same timeframe.
Looking forward, the forecast period spanning 2026 to 2032 suggests a sustained growth trajectory. Our models project a Compound Annual Growth Rate (CAGR) of 5.27 percent over this horizon. This growth rate, while steady, masks significant volatility in specific sub-sectors and regions, which our report unpacks in detail. The market is expected to reach substantial valuation milestones by 2032, reflecting not only organic expansion but also increasing integration into broader energy grids and transport fuel mandates.
It is important to note that while the aggregate numbers show growth, the base year data from 2025 highlights a market that is maturing. The transition from high-growth experimental phases to commercial-scale deployment is evident in the revenue patterns. Stakeholders must understand where the growth is concentrated to avoid overexposure to saturating segments while capitalizing on emerging opportunities. Our full analysis provides the specific vessel for this understanding without relying on generalized industry averages.
Segmentation Dynamics and Feedstock Realities
The composition of the biogas market is defined by diverse input materials and application endpoints. Understanding the weight of different feedstock types is essential for evaluating supply chain security and operational costs. Our segmentation analysis covers agricultural waste, municipal waste, sewage sludge, and energy crops. However, raw numbers only tell part of the story.
Recent industry intelligence gathered from IEA Bioenergy Task 37 indicates that manure feedstock prices have risen due to volatility in fertilizer markets, directly increasing operational costs for manure-based anaerobic digestion plants. This cost pressure alters the profitability equations for specific plant types. Similarly, data from the Global Methane Initiative suggests that feedstock prices for cow dung in India have doubled due to disruptions affecting agricultural demand, leading to unprofitability and plant shutdowns in certain regions. These are not isolated incidents but indicators of structural risks within specific feedstock categories.
On the application side, the market serves ends ranging from electricity generation and heating to combined heat and power systems and biofuel production. The mix of these applications varies significantly by geography and regulatory environment. Our report dissects which applications are driving margin expansion versus those that rely heavily on subsidies. By analyzing the interplay between feedstock availability and end-use demand, we identify where logistical bottlenecks may emerge in 2026 and beyond.
Competitive Landscape and Key Players
The competitive environment in the biogas sector is characterized by a mix of specialized technology providers, large-scale operators, and influential industry associations. While market concentration metrics suggest a relatively fragmented landscape on paper, influence is often concentrated among key innovators and strategic developers who are setting the standards for technology and sustainability.
Our research profiles several core enterprises that are shaping the market. In the United Kingdom, Future Biogas stands out as a leading operator and developer, notably securing offtake agreements for unsubsidised biomethane projects, such as their facility for AstraZeneca. This signals a shift towards corporate power purchase agreements that reduce reliance on public subsidies.
Technology providers are equally critical. Clarke Energy, based in the UK, has expanded its footprint as a supplier of biogas upgrading systems. Their recent commissioning of the first membrane-based biogas upgrader in India demonstrates the globalization of technology deployment. In Germany, EnviTec Biogas AG remains a pivotal manufacturer of plant technology and components for anaerobic digestion systems worldwide, while VORN Bioenergy GmbH focuses on operating and developing facilities.
Corporate involvement is also increasing. Air Products and Chemicals from the USA provides membrane solutions for biogas separation, highlighting the convergence of industrial gas expertise with renewable energy infrastructure. Other significant players include Entsorga S.p.A. in Italy, known for waste-to-energy facilities, Green Data Science in Germany specializing in biomethane upgrading, and Genia Bioenergy in Spain, which focuses on livestock and agricultural waste facilities.
Industry associations play a surveillance and advocacy role that indirectly shapes market conditions. The American Biogas Council provides critical industry data, reporting that US biogas investment exceeded 2 billion dollars in 2025 with 70 new projects coming online. Meanwhile, the European Biogas Association released its 15th Statistical Report highlighting 165 new biomethane plants operational in the EU during 2024-2025. These data points inform our assessment of market momentum but the strategic implications vary widely by stakeholder type.
Biogas Power Plants Market
Regulatory and Operational Dynamics
No strategic analysis of the biogas market is complete without a rigorous examination of the regulatory framework. The period from 2025 to 2026 is seeing significant policy adjustments that alter the economic viability of projects. In Europe, the EU Methane Regulation 2024 requires detection and repair of methane leakage. However, recent analysis by the European Environmental Bureau points out there are no equivalent mandatory requirements for biogas and biomethane plants, creating a regulatory asymmetry that informed investors should monitor closely.
Furthermore, the EU energy crop limit for biomethane has been tightened. According to the HyFuelUp consortium, a floor deduction reduces the limit from 12 percent to 4 percent in 2025/2026. This shift pushes the market away from energy crops and towards waste-based feedstocks, fundamentally changing the supply chain requirements for producers.
Economic incentives are also undergoing revision. For instance, the Danish gas distribution company Evida proposed a new tariff model from January 2025 imposing a large feed-in tariff that reduces incentives for green biogas producers. Such changes at the regional level can ripple through investment models, affecting internal rates of return and payback periods.
Biogas Market
Our report synthesizes these regulatory fragments into a cohesive risk matrix. We analyze how these policies impact different project types and geographies, allowing readers to anticipate compliance costs and permitting delays. The goal is to provide a clear view of where policy support is strengthening and where it is thinning.
Why This Research Matters for 2026 Decision Making
In a market defined by policy volatility and feedstock fluctuations, generic market reports fail to provide the specificity needed for high-stakes decisions. Our research is built on the premise that competitive advantage comes from anticipating change before it becomes mainstream news. We do not just report what happened; we model what happens next.
For operations managers, this study offers insights into supply chain resilience, particularly regarding feedstock procurement in volatile markets. For financial analysts, the breakdown of revenue streams by application and region helps in valuation modeling and risk assessment. For policymakers and association leaders, the analysis of industry developments and regulatory gaps offers a benchmark against which to measure future policy efficacy.
The report includes detailed profiles of key companies, analysis of recent developments such as new plant launches and investment milestones, and a forward-looking assessment of market concentration. We also incorporate industry context noise, turning raw facts about material costs and regulatory changes into strategic signals.
This level of detail is crucial because the biogas market is not a monolith. A strategy that works for agricultural waste in Europe may not translate to municipal waste in Asia Pacific or energy crops in Latin America. Our segmentation analysis respects these differences, providing the nuance required to tailor strategies to specific contexts.
Conclusion
The biogas sector offers significant opportunities for growth and sustainability impact, but capturing that value requires precise intelligence. As the market moves toward 2032, the convergence of regulatory pressure, technological innovation, and feedstock economics will create winners and losers. PW Consulting's new Biogas Market research is designed to ensure that your organization is positioned among the winners.
To fully leverage the findings outlined in this preview, we invite you to access the complete report on our website. The full document contains the specific data tables, deep-dive regional analysis, and detailed financial modeling necessary to build a robust 2026 strategy. Trust in data-driven insight to navigate the complexities of the biogas revolution.
For detailed analysis of this topic, please visit the official page: Biogas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pelvic Organ Prolapse Repair Device Market to Hit $1,573.3M by 2032, 8.32% CAGR
By pmarketresearch, 2026-09-15
Strategic Intelligence for the Pelvic Organ Prolapse Repair Device Market: Navigating Growth and Complexity in 2026
The global landscape for pelvic organ prolapse repair devices is undergoing a profound transformation. For medical device executives, investors, and strategic planners, understanding the nuanced interplay between regulatory shifts, material science advancements, and evolving surgical preferences is no longer optional—it is critical for survival and growth. As we move into 2026, the market presents a complex matrix of opportunities tempered by significant compliance and reimbursement challenges. This article serves as a strategic primer, drawing from our latest comprehensive market research report, designed to equip leadership teams with the foresight needed to navigate the forecast period from 2026 through 2032.
Our analysis indicates that the global market for pelvic organ prolapse repair devices, valued at approximately 892.5 million USD in 2025, is on a steady upward trajectory. The sector is projected to expand significantly over the coming years, reaching a valuation of 1,573.3 million USD by 2032. This growth is underpinned by an estimated Compound Annual Growth Rate (CAGR) of 8.32 percent during the forecast period. However, raw top-line numbers only tell a fraction of the story. The real strategic value lies in understanding the drivers behind this expansion, the fragmentation within the competitive landscape, and the specific dynamics reshaping product portfolios and surgical protocols.
Market Trajectory and Value Driver Analysis
The historical data from 2020 to 2025 reveals a consistent pattern of growth, recovering from 712.5 million USD in 2020 to the current 2025 baseline. This historical resilience sets the stage for the forecast period. The projected increase from 957.66 million USD in 2026 to over 1.5 billion USD by 2032 suggests a market that is maturing but still expanding. For stakeholders, this implies that while the low-hanging fruit of early adoption may be diminishing, significant volume remains in emerging markets and in the adoption of advanced procedural kits.
Several macroeconomic and demographic factors are converging to drive this demand. The aging global population continues to be a primary catalyst, as the prevalence of pelvic floor disorders increases with age. Furthermore, there is a shifting preference toward minimally invasive procedures and outpatient settings, driven by cost containment pressures within healthcare systems. This shift influences not just the volume of procedures but the type of devices being procured. For instance, the move toward single-use procedural instrumentation configurations reduces the need for extensive institutional sterilization infrastructure in ambulatory settings, aligning with hospital efficiency goals. Understanding where this shift is most pronounced geographically and by procedure type is essential for market entry or expansion strategies.
The Competitive Landscape: Consolidation and Innovation
The competitive environment is characterized by a moderate level of concentration. Our analysis shows that the top three companies hold approximately 58.0 percent of the market share, while the top five control around 62.0 percent. This concentration indicates that while there are dominant players, there is still substantial room for challengers and niche innovators to carve out significant value positions. The presence of major multinational corporations alongside specialized innovators creates a dynamic ecosystem where acquisition targets and partnership opportunities are frequent.
Pelvic Organ Prolapse Repair Device Market
Key players are actively differentiating their portfolios through technological innovation and strategic positioning. Johnson & Johnson MedTech (Ethicon) continues to leverage its scale to offer bioresorbable materials and minimally invasive kits aimed at restoring pelvic ligament support. Similarly, Boston Scientific Corporation provides the Capio SLIM suture-capturing device and Upsylon Y-Mesh, focusing on pelvic floor reconstruction and prolapse repair. These large entities benefit from established distribution networks and comprehensive reimbursement support.
However, the market is also seeing activity from specialized players. Coloplast Group develops and supplies biologic mesh solutions and procedural kits, capitalizing on the shift toward biological materials. Cook Medical Incorporated supplies customized mesh solutions and instrumentation for patient-specific reconstruction, addressing the need for tailored surgical outcomes. Integra LifeSciences and CooperSurgical, Inc. also remain pivotal, providing biologic grafts, support systems, and procedural kits. Additionally, companies like Utah Medical Products, Inc. focus on manufacturing instruments and support systems that streamline the procedural workflow.
Innovation is also coming from newer entrants disrupting traditional paradigms. Escala Medical, based in Israel, offers the Mendit device, an FDA-cleared incision-free anchor system for pelvic organ prolapse surgical repair. This type of innovation represents a shift away from traditional mesh or graft reliance toward anchor-based systems. In June 2025, Escala Medical raised 4.5m EUR (approximately 5.3m USD) to accelerate commercialization and global expansion of the Mendit device, signaling strong investor confidence in alternative surgical approaches. Meanwhile, regulatory clearances continue to shape the non-surgical segment. In March 2024, Cosm Medical received FDA 510(k) clearance for the Gynethotics Pessary, a collapsible device for temporary nonsurgical management, highlighting the ongoing demand for conservative management options alongside surgical interventions.
Regulatory and Reimbursement Dynamics
No strategic analysis of this market is complete without a rigorous examination of the regulatory and reimbursement environment. These factors often dictate the viability of product lines and the speed of adoption. The regulatory landscape presents a dichotomy of challenges and opportunities. The FDA maintains that transvaginal surgical mesh devices for pelvic organ prolapse do not have a favorable benefit-risk profile due to potential additional risks compared to native tissue repair. This stance has fundamentally altered product development roadmaps for many manufacturers, pushing innovation toward bioresorbable materials and alternative support systems.
In response to these regulatory pressures, new bioresorbable mesh solutions from major manufacturers emphasize faster tissue integration to address post-operative complication concerns in pelvic organ prolapse repair. This technological pivot is not merely a compliance exercise but a competitive differentiator. Companies that can demonstrate superior tissue integration and reduced complication rates are likely to secure preferential positioning with surgeons and hospital procurement committees. Furthermore, biological grafts are noted as the fastest-growing segment in pelvic organ prolapse repair following reduced synthetic mesh use. This trend underscores the importance of material science in the current market cycle.
On the reimbursement front, clarity is essential for financial modeling. Pelvic organ prolapse repair procedures such as transabdominal allograft treatment use CPT code 57280, which is reimbursed under Medicare physician fee schedules. Understanding the nuances of coding and payment guides, such as the Boston Scientific 2026 Coding and Payment Guide, is vital for sales teams and market access strategists. Variations in reimbursement policies across different regions can significantly impact the total addressable market for specific device types. Our full report delves into these nuances, providing the granular data necessary to model revenue streams accurately under different regulatory scenarios.
Strategic Implications for 2026 Decision Makers
As we approach 2026, several strategic imperatives emerge for organizations operating in this space. First, portfolio diversification is key. Given the regulatory scrutiny on synthetic mesh, companies must balance their offerings with biologic grafts and non-mesh support systems. Relying too heavily on a single material class exposes a firm to significant risk if regulatory guidance tightens further. Second, geographic expansion strategies must be data-driven. Different regions exhibit different adoption rates for new technologies and varying levels of regulatory strictness. Understanding where the market volume is concentrated without relying on generic data is crucial for resource allocation.
Third, partnerships and M&A activity should be monitored closely. The presence of companies like Escala Medical securing funding for novel devices suggests that venture capital is willing to back innovation in this sector. For larger incumbents, acquiring these technologies could accelerate their pipeline and mitigate risks associated with internal R&D delays. Fourth, sales and marketing efforts should align with the shift toward ambulatory settings. Emphasizing single-use instrumentation and ease of use in marketing collateral can resonate with facilities looking to optimize throughput and reduce sterilization costs.
Unlocking the Full Intelligence Picture
While this overview highlights the macro trends, the competitive moves, and the regulatory constraints, it necessarily omits the granular data required for immediate operational planning. To make informed decisions for 2026 and beyond, leadership needs access to detailed segmentation analysis, precise regional breakdowns, and specific application-based growth rates. Our full market research report provides this depth. It dissects the market by specific device types, application categories, and regional dynamics, offering the precise metrics needed to validate strategic hypotheses.
Vaginal Pessary Market
The report includes comprehensive profiles of key companies, detailed analysis of recent developments, and a thorough examination of the industry context noise that impacts market viability. It moves beyond general observations to provide actionable intelligence on market share distributions, growth vectors within specific segments, and the financial implications of regulatory changes. For executives who need to justify capital allocation, R&D spending, or market entry strategies to their boards, this level of detail is indispensable.
The pelvic organ prolapse repair device market is poised for significant growth, but the path to capturing that value is fraught with complexity. The difference between success and stagnation lies in the quality of intelligence guiding your strategy. We invite you to access the full research study to obtain the complete dataset, including specific regional valuations, segment percentage splits, and detailed company competitive analysis. Equip your organization with the precise knowledge required to lead in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Pelvic Organ Prolapse Repair Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Acrylic Fibers Market to Hit $6.5B by 2032 as Asia Pacific Leads with 3.46% CAGR
By pmarketresearch, 2026-09-15
Navigating the Acrylic Fibers Market: Strategic Insights for 2026 and Beyond
The global acrylic fibers industry stands at a critical juncture as we move through 2026. For textile manufacturers, chemical producers, and investment strategists, understanding the nuanced shifts in this sector is no longer optional—it is a prerequisite for sustainable growth. The convergence of raw material volatility, evolving regulatory landscapes, and changing consumer preferences towards performance and sustainability is reshaping the competitive terrain. At PW Consulting, we have compiled an extensive analysis designed to cut through the noise and provide actionable intelligence for stakeholders aiming to secure their position in this evolving market.
This report serves as a foundational tool for executive decision-making. It moves beyond surface-level trends to offer a granular view of supply chain dynamics, regional performance, and competitive maneuvers. As the industry transitions from post-pandemic recovery patterns to a new normal defined by resource constraints, having access to precise data is the differentiator between reactive management and proactive strategy. Our analysis covers the historical trajectory from 2020 through 2025 and projects forward to 2032, providing a comprehensive timeline for planning capital allocation and product development.
Market Trajectory and Growth Catalysts
The market has demonstrated resilience over the past half-decade, navigating disruptions that affected global supply chains. Current valuation places the global market at a significant scale, with projections indicating a steady climb over the forecast period. The compound annual growth rate (CAGR) during the 2026-2032 window is estimated to reflect moderate but stable expansion, driven by consistent demand in core application sectors and emerging technical uses.
Historical Performance and Future Outlook
Understanding where the market has been is essential for predicting where it is going. The historical data from 2020 to 2025 reveals a market that has absorbed shocks while maintaining an upward trend. Starting from a baseline in 2020, the industry saw recovery and growth leading into 2025. The forecast suggests a continued path upward, with market size expected to reach new milestones by the early 2030s. However, this growth is not linear. Stakeholders must account for intermittent fluctuations caused by feedstock availability and regulatory adjustments.
- Base year analysis anchors current valuation metrics.
- Forecast period extends through 2032 to capture long-term investment cycles.
- Growth drivers include urbanization, synthetic fiber demand, and technical textile innovation.
Revenue Projections and Valuation Dynamics
Revenue projections indicate a healthy trajectory. The financial outlook suggests that while top-line growth is positive, the pace is influenced by external macroeconomic factors. Currency stability and production costs play pivotal roles in the final realized revenue for major players. Our analysis dissects these variables to help firms model their own financial scenarios against market averages.
Segmentation: Product Types and Application Verticals
Success in the acrylic fibers market depends heavily on understanding the specific performance characteristics of different product types and where they are applied. The market is broadly divided into staple and filament fibers, each serving distinct end-user needs. Our report provides a deep dive into how these segments are evolving independently and in relation to one another.
Product Type Dynamics
Staple fiber remains a dominant force, particularly in applications requiring texture, warmth, and blendability. Filament fiber, while representing a smaller portion of the volume, is critical for specific high-performance uses where strength and sheen are paramount. The balance between these types shifts based on pricing mechanisms and technological advancements in polymerization.
Application Sector Analysis
Demand is generated across three primary verticals. Apparel continues to be a major consumer of acrylic fibers, driven by fashion trends and the need for durable, cost-effective synthetic alternatives to natural fibers. Household furnishing represents a stable segment where acrylics offer durability and resistance to environmental factors. The industrial sector is increasingly becoming a focus area, leveraging acrylic fibers for technical applications that require specific chemical or physical properties.
- Apparel sector demand is sensitive to fashion cycles and raw material costs.
- Household furnishing applications benefit from the longevity and aesthetic versatility of acrylics.
- Industrial usage is expanding as new use-cases are validated for technical grades.
Regional Market Dynamics
Geographical performance varies significantly based on local manufacturing capacity, consumption patterns, and regulatory environments. Asia Pacific remains a central hub for both production and consumption, reflecting the broader shift in the global textile industry. However, mature markets in Europe and North America retain significant value due to higher pricing power and specific quality standards.
Production and Consumption Hubs
Certain regions have established themselves as key nodes in the supply chain. Production capabilities are concentrated in areas with access to requisite feedstocks and logistical infrastructure. Consumption patterns are tied to local textile manufacturing robustness and retail demand. Our report maps these flows to identify potential bottlenecks or opportunities for market entry.
Acrylic Fibers Market
- Asia Pacific continues to drive volume growth due to manufacturing density.
- Europe and North America focus on high-value segments and compliance-driven markets.
- Emerging markets in Latin America and MEA are showing incremental but notable interest.
Competitive Landscape
The industry is characterized by a mix of regional players and global conglomerates. Market concentration indicates that while there are dominant players, there is still room for specialized niche providers. The CR3 and CR5 metrics suggest a moderate level of consolidation, but competition remains fierce based on innovation and cost efficiency.
Key Market Participants
Several key companies define the current competitive landscape. Organizations such as Aksa Akrilik Kimya Sanayii A.Ş. in Turkey, Dralon GmbH in Germany, and various Japanese entities like Toray Industries, Inc. and Kaneka Corporation represent established operational bases. Asian players from India, including Vardhman Acrylics Ltd. and Indian Acrylics Limited, as well as Chinese manufacturers like Jilin Chemical Fiber Group Co., Ltd., are also critical to the supply equation.
- Global players leverage scale and technology to maintain market share.
- Regional manufacturers often compete on agility and localized supply chain advantages.
- Collaboration and partnerships are becoming more common to secure raw material access.
Recent Strategic Developments
Recent activities among key players highlight the direction of the industry. In March 2025, Toray Industries, Inc. announced the implementation of mass balance methodology in their TORAYLON acrylic staple fiber production, signaling a strong move towards transparent sustainability tracking. Around the same period, Aksa Akrilik Kimya Sanayii A.Ş. expanded its acrylic fibre product range specifically for apparel and technical textile applications, indicating a strategy to diversify beyond commodity grades.
Operational investments remain a priority. Dralon GmbH continued production optimization and operational investments at acrylic fibre facilities throughout 2025, aiming to enhance efficiency amidst cost pressures. On the sustainability front, Thai Acrylic Fibre Co. Ltd. made significant strides in 2024. They partnered with FibreTrace to introduce traceability technology for Regel recycled acrylic fiber and subsequently launched Regel recycled acrylic fiber with Global Recycled Standards certification. These moves underscore a growing market demand for verified sustainable content.
Industry Dynamics: Risks and Regulations
Navigating the market requires a clear understanding of the headwinds facing producers. Raw material costs and regulatory compliance are the two most significant variables affecting profitability and expansion plans in 2026.
Acrylic Rubber Market
Raw Material Volatility
Feedstock stability is a persistent concern. Propylene prices have shown regional increases in early 2026, rising between 3% to 7% due to feedstock volatility and supply constraints. This directly impacts acrylonitrile costs, which are fundamental to acrylic fibers production. Furthermore, specific regional pricing spikes have been observed, such as a significant surge in U.S. Acrylonitrile prices in late March 2026 driven by declining global inventories and tighter upstream availability. Managing these cost fluctuations is central to maintaining margin health.
Regulatory Landscape
Compliance is becoming more rigorous and costly. Environmental restrictions on acrylonitrile have led to compliance costs affecting synthetic fibre producers, with nearly 40% facing operational limits on expansion. North American and European jurisdictions are tightening product certification and safety standards, increasing compliance requirements for acrylic fibers. Similarly, East Asian markets, led by India, are tightening quality and safety thresholds. These regulatory shifts favor suppliers with established compliance frameworks and robust quality assurance systems, potentially raising barriers to entry for smaller or less equipped competitors.
Strategic Value of Comprehensive Market Intelligence
In a market defined by complexity, guesswork is a liability. The strategic value of our Acrylic Fibers Market research lies in its ability to convert data into decision-ready insights. For CEOs and Strategy Directors, this report offers the evidence needed to justify capital expenditure, enter new geographies, or divest from underperforming segments. For Supply Chain Managers, it provides the context needed to negotiate contracts and manage inventory risks related to feedstock volatility.
The 2026 outlook is not just about revenue numbers; it is about understanding the ecosystem. It involves recognizing which competitors are investing in sustainability technologies and how those investments will affect market share in the coming years. It requires knowing where regulatory tightening might pause expansion projects and how to pivot accordingly. Our analysis provides the structural understanding necessary to anticipate these shifts rather than merely reacting to them.
Decision-makers need clarity on where the growth pockets are hidden. While overall market growth is steady, specific applications and regions may outperform the average. Identifying these pockets early allows companies to allocate resources more effectively. Furthermore, understanding the competitive moves of key players like Toray or Aksa helps in benchmarking one's own strategic direction.
Ultimately, this report is designed to empower your organization with the confidence to move forward. Whether you are looking to optimize existing production lines, explore partnerships for recycled fiber initiatives, or assess the risks associated with raw material procurement, the detailed intelligence contained within this study provides the roadmap. In an industry where margins can be squeezed by commodity fluctuations and compliance costs, knowledge is the most valuable asset.
To access the full depth of data, including detailed segmentation revenue figures, regional breakdowns, and proprietary company profiles, we invite stakeholders to review the complete Strategic Market Intelligence Report. This document is structured to support boardrooms discussions and strategic planning sessions throughout 2026 and beyond.
Begin your strategic planning with confidence. Secure the complete market intelligence necessary to navigate the complexities of the Acrylic Fibers Market.
For detailed analysis of this topic, please visit the official page: Acrylic Fibers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ROV Revenue Hits $915M in 2025, Set for 6.89% CAGR Growth to $1.45B by 2032
By pmarketresearch, 2026-09-15
Navigating the Deep: Strategic Imperatives in the 2026 Offshore ROV Market
The offshore energy sector stands at a critical inflection point. As global demand for subsea infrastructure intensifies, driven by both traditional hydrocarbon extraction and the rapid expansion of renewable energy capabilities, the role of Remotely Operated Vehicles (ROVs) has evolved from auxiliary support to mission-critical necessity. For stakeholders navigating this complex environment, understanding the trajectory of the Offshore ROV Market is not merely an academic exercise; it is a fundamental component of risk management and capital allocation strategy.
PW Consulting's latest market research provides a comprehensive lens through which to view these dynamics. This analysis is designed to equip decision-makers with the intelligence required to optimize portfolios, identify partnership opportunities, and anticipate technological shifts that will define the industry through 2032.
Market Trajectory and Historical Context
To understand where the market is going, one must first appreciate the resilience and growth pattern established over the last half-decade. The industry has demonstrated a robust recovery and expansion phase following the volatility of the early 2020s. Historical data indicates a steady climb in market valuation, reflecting increased operational activity and capital investment in subsea technologies.
Starting from a baseline in 2020, the market has progressed through a period of consolidation and growth. By 2025, the industry reached a significant milestone in valuation, setting the stage for the forecast period. The momentum is expected to continue with a compound annual growth rate that underscores the sector's health and long-term viability. This growth is not linear but is influenced by varying regional demands, technological adoptions, and application-specific requirements.
Financial Outlook and Forecast Horizon
The forecast period extending to 2032 suggests a clear upward trajectory. Projections indicate that market revenue will expand from approximately 996 million in 2026 to over 1.45 billion by the end of the forecast window. This expansion represents more than just nominal growth; it signals increased deployment rates, higher specification requirements for ROV systems, and broader adoption across diverse offshore activities.
For strategic planners, these figures highlight a market that is maturing yet still offers room for differentiation. The consistent growth rate of nearly 7 percent implies that while competition is intensifying, the total addressable market is expanding sufficiently to accommodate new entrants and innovative solutions. However, capturing this value requires a nuanced understanding of where the demand originates and how it is distributed across different operational classes and regions.
Segmentation Dynamics and Operational Diversity
The Offshore ROV Market is not a monolith. It is segmented by operational capability, geographic presence, and application vertical. Each segment presents unique challenges and opportunities for vendors and end-users alike. Our research delves into the specific revenue contributions and volume drivers within these categories, providing a granular view that aggregate numbers often obscure.
Vehicle Classifications and Technical Specifications
The market is broadly categorized by the class of ROV, ranging from observation-class systems used for light inspection to heavy work-class systems capable of complex intervention tasks. The divergence in pricing and capability between a micro/mini system and a heavy work-class unit is substantial. Price points can vary from a few thousand dollars for basic units to several million for advanced systems equipped with sophisticated navigation packages utilizing DVL and USBL technology, which alone can command significant premiums depending on range and precision requirements.
Understanding the revenue split among these classes is vital for manufacturers aligning their production capabilities with market demand. Light work-class and observation-class vehicles continue to hold significant share, driven by their versatility in inspection and maintenance roles. However, the heavy work-class segment remains critical for deep-water construction and high-intensity intervention, particularly in the oil and gas sector. Our report details the specific valuation of each class, allowing stakeholders to assess where their technology fits within the value chain.
Geographic Distribution and Regional Hubs
Demand for ROV services and systems is geographically dispersed, with established hubs in North America, Europe, and the Asia Pacific region. Each region presents distinct regulatory environments, energy mix priorities, and operational challenges. For instance, regulatory frameworks such as the NORSOK U-102 standard in Norway dictate specific requirements for safety, operator competence, and equipment, influencing how ROV services are procured and deployed in that region.
Similarly, international guidelines from the International Maritime Organization provide protocols for operations involving both divers and ROVs, adding a layer of compliance complexity that varies by jurisdiction. Our analysis maps the market value across key regions, identifying where growth is most pronounced. This regional intelligence is crucial for supply chain planning, sales localization, and identifying potential barriers to entry in emerging markets.
Application Verticals: Beyond Traditional Oil and Gas
While the oil and gas sector has historically been the dominant driver of ROV demand, the landscape is diversifying. Offshore wind energy, scientific research, and military and defense applications are contributing an increasing share of the total market volume. This diversification is a key risk mitigation factor for the industry, reducing reliance on a single commodity price cycle.
Diversification into Renewables and Defense
The growth of offshore wind farms requires extensive cable laying, inspection, and maintenance, creating a steady demand for ROVs specialized in these tasks. Military and defense applications also present unique requirements for underwater surveillance and intervention, driving innovation in stealth and endurance. Our report quantifies the revenue contribution from these varying sectors, highlighting how the balance of demand is shifting. Stakeholders who rely solely on traditional energy cycles may find their growth potential limited compared to those who have diversified their service offerings to include renewables and research support.
Regulatory and Compliance Landscape
Operating in these diverse sectors requires adherence to strict regulatory standards. In addition to regional safety standards, industrial and offshore ROV operations often require certified operators and documented maintenance procedures. Compliance is not just a legal obligation but a competitive differentiator. Companies that can demonstrably meet these rigorous standards gain trust with major operators who prioritize safety and reliability above cost alone. Our analysis examines how regulatory trends are shaping procurement criteria and vendor selection processes.
Competitive Landscape and Strategic Positioning
The market structure is characterized by a mix of large multinational corporations and specialized niche players. While the top few companies hold a noticeable portion of the market share, the market remains relatively fragmented compared to other heavy industrial sectors. This fragmentation suggests opportunities for consolidation, strategic partnerships, or specialized niche dominance.
Key Players and Capability Profiles
Several key companies define the current competitive environment. Oceaneering International, based in Houston, stands as one of the world's largest manufacturers and operators of work-class ROV systems, providing integrated services ranging from deepwater work-class systems to remote piloting and advanced visualization. Their scale allows them to influence pricing and technology standards across the industry.
In Europe, companies like Soil Machine Dynamics in the UK and Saab Seaeye Limited are pushing the boundaries of electric and hybrid systems. SMD specializes in advanced work-class ROVs including electric Quantum EV and Quasar MkII systems, focusing on cable tracking and offshore wind cable laying. Saab Seaeye offers electric and hybrid ROV systems for inspection and maintenance in both oil and gas and renewables.
TechnipFMC plc, also headquartered in Houston, leverages its Schilling Robotics legacy to provide advanced work-class ROV systems and intervention tools. They emphasize electric ROV electrification and remote piloting proof-of-concepts, positioning themselves at the forefront of subsea robotics innovation. Forum Energy Technologies and IKM Group round out the significant players, offering subsea technologies and inspection tools tailored for oil and gas and renewables.
International representation is strong, with Saipem in Italy focusing on subsea services for construction and IRM projects, and ECA Group in France providing ROV systems for subsea intervention. L3Harris Technologies and Deep Ocean Engineering contribute communication and integration systems, while TMT and Argus Remote Systems offer specialized ROV and subsea technologies for offshore operations.
Recent Innovations and Technology Shifts
The competitive landscape is currently being reshaped by technological announcements and product launches. In early 2026, Deep Trekker Inc. launched the SPECTRA ROV at Oceanology International, a next-generation subsea robot designed for high-current offshore environments with heavy payloads and precise inspection tasks. This highlights the industry's move towards higher performance in challenging conditions.
Simultaneously, Oceaneering has discussed the ROV electrification inflection point, positioning electric systems as a key efficiency driver in offshore energy. This aligns with broader industry trends towards decarbonization and operational efficiency. Furthermore, MacArtney Offshore Solutions was awarded a contract for a fully electrical eLARS system in early 2026, supporting ROV operations on offshore vessels. These developments signal a clear shift towards electrification and automation, themes that our report explores in depth to help companies prepare their technology roadmaps.
Strategic Value for 2026 Decision-Making
In an environment defined by rapid technological change and shifting energy priorities, access to accurate, forward-looking data is paramount. This market research is not just a retrospective on performance but a tool for shaping future strategy. It enables executives to validate assumptions, benchmark against competitors, and identify whitespace opportunities.
Risk Mitigation and Opportunity Identification
By understanding the concentration of market power, companies can better anticipate pricing pressures and competitive moves. The data on market concentration reveals the degree of rivalry and potential for consolidation. For investors, this informs valuation models and exit strategies. For operators, it informs procurement strategies and vendor management. Furthermore, recognizing the growth rates across different applications allows companies to pivot resources towards high-growth sectors such as offshore wind or specialized defense contracts before the market becomes saturated.
Technology Roadmap Alignment
The shift towards electric systems and automation requires significant capital investment and retraining. Companies need to know the pace of this adoption to avoid stranded assets or obsolescence. Our research provides the context needed to align internal R&D with external market demand. Whether it is investing in navigation precision, payload capacity, or energy efficiency, knowing the specific requirements of the end-user is critical.
Conclusion and Access to Intelligence
The Offshore ROV Market presents a compelling case for strategic investment and careful planning. With a clear growth trajectory extending into the next decade and a evolving competitive landscape driven by electrification and diversification, the opportunities are significant for those equipped with the right intelligence.
Offshore ROV Market
Offshore AUV Market
However, the macro trends discussed here only scratch the surface of the available intelligence. To truly navigate this landscape, stakeholders require a granular understanding of segment-specific revenue flows, regional growth nuances, and detailed competitor benchmarking that goes beyond public profiles.
PW Consulting's full Offshore ROV Market report offers this depth. It provides the specific segmentation data, regional valuations, and comprehensive competitive analysis necessary to formulate robust strategies for 2026 and beyond. To access the complete dataset and detailed forecasts that will inform your critical business decisions, we invite you to visit the source webpage for the full research briefing.
For detailed analysis of this topic, please visit the official page: Offshore ROV Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Small Caliber Ammunition Market Hits $8,170M in 2025, Forecasts 3.55% CAGR to $10,375M by 2032
By pmarketresearch, 2026-09-15
Navigating the Small Caliber Ammunition Market: Strategic Intelligence for 2026 and Beyond
The global defense and commercial landscape is undergoing a period of rapid recalibration, driven by shifting security architectures, heightened procurement demands, and persistent supply chain complexities. For executives, investors, and procurement leaders operating in the munitions sector, understanding the trajectory of small caliber ammunition is no longer a peripheral exercise. It is a central component of risk management, capacity planning, and competitive positioning. As we enter 2026, the market stands at a critical inflection point where historical performance, near-term procurement cycles, and long-term capability transitions intersect. This industry insight introduces our latest comprehensive research report on the Small Caliber Ammunition Market, designed to equip stakeholders with actionable intelligence for strategic decision-making throughout the forecast period and beyond.
Market Trajectory and Structural Evolution
Over the past half-decade, the small caliber ammunition sector has demonstrated a clear pattern of resilience and steady expansion. Historical tracking from 2020 through 2025 reveals a market that has consistently navigated fluctuating demand signals, procurement cycles, and macroeconomic variables. The baseline valuation for 2025 anchors the industry at approximately 8,170.0 million USD, reflecting a mature yet continuously evolving ecosystem. Looking forward, the forecast horizon spanning 2026 to 2032 projects a compound annual growth rate of 3.55 percent, culminating in a projected market size of 10,375.0 million USD by the terminal forecast year.
This growth trajectory is not merely a function of incremental volume increases. It reflects deeper structural shifts in how governments, security agencies, and commercial enterprises approach ammunition procurement and inventory management. The forecast period captures the ramp-up of next-generation weapon platform transitions, sustained homeland security requirements, and the commercial sector's adaptation to evolving regulatory and market conditions. Importantly, the data underscores a market that is expanding at a measured but durable pace, demanding that stakeholders balance short-term operational agility with long-term strategic foresight.
Core Dimensions of the Industry Landscape
The contemporary small caliber ammunition market operates across multiple intersecting dimensions, each carrying distinct implications for pricing, production capacity, and competitive positioning. The product architecture is dominated by centerfire and rimfire configurations, with specialized variants serving highly specific tactical, training, and commercial requirements. These product segments interact continuously with downstream application demands, ranging from military combat and training programs to homeland security and law enforcement operations, as well as hunting, sports, and commercial self-defense markets.
Small Caliber Ammunition Market
Geographically, the market exhibits pronounced regional concentration patterns, with certain territories accounting for a disproportionate share of total revenue generation. This distribution is driven by defense spending priorities, domestic manufacturing capabilities, export policies, and the localization of procurement frameworks. Understanding these geographic dynamics is essential for companies evaluating market entry, capacity allocation, and partnership strategies. The interplay between regional demand centers and production hubs creates a complex web of opportunity and constraint, particularly as supply chain localization and strategic autonomy become increasingly prominent policy objectives.
Furthermore, the market's competitive structure reflects a moderately concentrated environment. The top three players command a significant share of total industry revenue, while the leading five firms collectively account for the majority of market output. This concentration highlights the importance of scale, established defense contracting relationships, and proprietary manufacturing capabilities. At the same time, it leaves room for specialized manufacturers and regional players to capture niche segments, particularly where localized demand, export opportunities, or differentiated product offerings create competitive openings.
Competitive Dynamics and Strategic Positioning
The competitive landscape is shaped by a blend of established defense contractors, national munitions manufacturers, and specialized commercial producers. Winchester Ammunition, operating from East Alton, Illinois, remains a defining force in the sector, leveraging its operational control of the Lake City Army Ammunition Plant to manufacture critical small caliber ammunition, including 5.56mm, 7.62mm, and .50 caliber variants for both U.S. military and commercial channels. Its deep institutional integration with defense procurement programs positions it as a central actor in shaping production capacity and technology flow.
In Europe, Nammo AS, headquartered in Lysaker, Norway, maintains a strong footprint through its comprehensive 5.56mm and 7.62mm ammunition series. The company's portfolio spans ball, armor piercing, tracer, and training variants, supporting both military readiness and commercial applications across allied markets. This diversified product approach enables Nammo to respond to varying operational requirements while maintaining a consistent presence in high-demand caliber categories.
Meanwhile, regional manufacturers are increasingly asserting their strategic relevance. CBC Global Ammunition, based in São Paulo, Brazil, produces small caliber ammunition for military and commercial markets, including 5.56mm, 7.62mm, and .50 caliber formats. Its presence underscores the growing importance of Latin American production capabilities and export-oriented manufacturing strategies. Similarly, PT Pindad, headquartered in Bandung, Indonesia, manufactures small caliber ammunition for the Indonesian military and export markets, reflecting the broader trend of regional defense industrialization and indigenous capability development.
These companies operate within an environment where scale, technological integration, and supply chain resilience determine competitive advantage. The ability to align production capacity with procurement cycles, manage raw material dependencies, and meet stringent quality and compliance standards remains a defining differentiator. For stakeholders evaluating partnership, investment, or market entry opportunities, understanding the strategic posture of these key players is essential.
Recent Industry Developments and Capacity Expansion
The period leading into 2026 has been marked by notable operational and strategic developments across the small caliber ammunition sector. Organizational restructuring and asset integration have emerged as recurring themes. In April 2025, Olin Corporation completed the acquisition of small caliber ammunition manufacturing assets from AMMO, Inc., integrating brass shellcase production and the Manitowoc, Wisconsin facility into Winchester operations. This move signals a strategic emphasis on vertical coordination and production consolidation, reinforcing manufacturing efficiency and supply chain control.
On the defense procurement front, the U.S. Army and the Joint Program Executive Office for Armaments and Ammunition broke ground in February 2025 on a new 6.8mm ammunition production facility at the Lake City Army Ammunition Plant. This initiative is designed to support the Next Generation Squad Weapon Program, illustrating how caliber transitions and platform modernization are directly reshaping production infrastructure. By January 2026, the facility reached a significant milestone with the topping out of the 508,345-square-foot production building, marking tangible progress in next-generation ammunition capacity development.
International capacity expansion efforts have also accelerated. Sellier & Bellot expanded its production capabilities with a new manufacturing facility in the Czech Republic in September 2025, enhancing its ability to serve European and export markets. In June 2025, Mesko announced a substantial capacity expansion, quintupling its small-caliber ammunition production capacity to 250 million rounds annually. These initiatives reflect a broader industry response to sustained demand pressure and the strategic imperative to build resilient, scalable manufacturing networks.
Supply Chain, Raw Material, and Regulatory Dynamics
The operational environment for small caliber ammunition manufacturers is increasingly defined by raw material dependencies and regulatory frameworks that shape procurement, production, and trade. Nitrocellulose, a critical propellant component, has emerged as a focal point of supply chain management and pricing strategy. Recent solicitations have referenced Economic Price Adjustment mechanisms for Nitrocellulose in small caliber ammunition contracts, highlighting the sensitivity of production costs to raw material market fluctuations and the need for contractual flexibility.
In response to these dependencies, major industry participants have pursued strategic supply chain security measures. Colt CZ Group acquired a majority stake in Synthesia Nitrocellulose to secure propellant supply for small caliber ammunition, while CSG acquired IFF nitrocellulose production in Germany to strengthen propellant supply capabilities. These moves underscore a broader industry trend: the recognition that raw material access is not merely a procurement variable but a strategic asset that directly affects production continuity, cost stability, and competitive resilience.
Regulatory developments are equally influential. In June 2025, the ATF authorized the importation of certain marking or training rounds under the Gun Control Act for research use only, creating new pathways for specialized procurement while reinforcing compliance boundaries. Export controls also remain a defining parameter, as evidenced by the certification of 5.56mm assault rifle exports under the Arms Export Control Act with congressional notifications. These regulatory frameworks shape market access, trade flows, and the strategic calculus of international procurement and distribution.
What Our Research Report Delivers
Our Small Caliber Ammunition Market research report is structured to provide decision-makers with a comprehensive, actionable intelligence framework. Rather than offering static snapshots, the analysis is built around forward-looking scenario planning, competitive benchmarking, and operational insight. The report maps market size evolution across historical and forecast periods, providing a clear baseline for evaluating growth trajectories and demand drivers.
Beyond macroeconomic indicators, the report delivers granular examinations of product architecture, application segmentation, and regional distribution patterns. These analyses are integrated with competitive profiling, enabling stakeholders to assess market share dynamics, production capacity trends, and strategic positioning among leading manufacturers and emerging entrants. The research also incorporates a detailed review of recent industry developments, including facility expansions, asset acquisitions, and capacity milestones, contextualizing them within broader market forces.
Supply chain and regulatory considerations are treated as core analytical pillars. The report examines raw material dependencies, pricing mechanisms, and strategic procurement adjustments, while mapping the regulatory landscape that governs importation, export control, and compliance requirements. This multidimensional approach ensures that executives, analysts, and investors can evaluate not only where the market is heading, but also the structural factors that will influence profitability, risk exposure, and strategic optionality.
Large Caliber Ammunition Propellant Market
Strategic Imperatives for 2026 Decision-Making
For organizations operating in or adjacent to the small caliber ammunition market, 2026 presents a decisive window for strategic alignment. The convergence of caliber modernization programs, capacity expansion initiatives, raw material security measures, and evolving regulatory frameworks creates both opportunity and complexity. Companies that succeed in this environment will be those that integrate market intelligence into procurement planning, capacity investment, and partnership strategy.
Decision-makers must evaluate how shifts in military procurement priorities, law enforcement demand, and commercial market dynamics will affect volume forecasts and pricing structures. They must also assess how competitive concentration and regional manufacturing strategies influence supply reliability and market access. The ability to anticipate capacity bottlenecks, manage raw material exposure, and navigate regulatory parameters will separate resilient organizations from those that are overly exposed to volatility.
This report is designed to support that evaluation. By synthesizing market sizing, segmentation insights, competitive analysis, and industry dynamics into a coherent intelligence framework, it provides the foundation for informed strategic choices. Stakeholders who engage with the full analysis will gain a clearer understanding of where value is being created, how competitive boundaries are shifting, and what operational adjustments are required to maintain positioning in a market that is expanding with purpose and precision.
The small caliber ammunition market is not defined by sudden disruption alone, but by the cumulative effect of procurement strategy, manufacturing investment, supply chain security, and regulatory evolution. For leaders navigating this landscape, the difference between reactive positioning and proactive strategy lies in the quality of intelligence available. Our research report offers that intelligence in depth, providing the analytical rigor necessary to support confident, forward-looking decisions throughout 2026 and the forecast period ahead.
For detailed analysis of this topic, please visit the official page: Small Caliber Ammunition Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Textile Dyes Market Hits $1.19 Billion in 2025, Projected 5.2% CAGR Through 2032
By pmarketresearch, 2026-09-15
Navigating the Chromatics of Growth: Strategic Intelligence for the Textile Dyes Market Through 2032
The global textile dyes industry is entering a defining era. As sustainability mandates tighten, raw material volatility accelerates, and regional manufacturing footprints shift, color chemistry has evolved from a commoditized input into a strategic differentiator. For executives, procurement leaders, and product developers operating in the fibers and fabrics value chain, the ability to anticipate demand curves, regulatory inflection points, and competitive realignments is no longer optional. It is the foundation of resilient margin planning and portfolio strategy.
PW Consulting's latest Textile Dyes Market research report delivers a structured, data-rich examination of the sector across the forecast horizon of 2026 through 2032. Drawing on a rigorous historical evaluation spanning 2020 to 2025 and anchored in a base year of 2025, this study translates complex market mechanics into actionable intelligence. The following overview outlines the strategic architecture of the report, highlights the macro-momentum shaping the industry, and demonstrates how decision-makers can leverage these findings to outperform in a rapidly evolving landscape.
Market Trajectory: A Measured Expansion with Strategic inflection Points
Over the past half-decade, the textile dyes sector has demonstrated consistent growth, reflecting steady fiber production, evolving consumer color preferences, and the ongoing technical upgrading of dyeing infrastructure across mature and emerging manufacturing hubs. Historical revenue expanded from approximately 920.5 million USD in 2020 to a base-year valuation of 1190.0 million USD in 2025, underscoring the industry's capacity to compound value even amid supply chain disruptions and raw material price fluctuations.
Looking ahead, the forecast trajectory signals sustained expansion. The market is projected to reach a valuation of 1246.44 million USD in 2026, climbing steadily through the decade to attain a terminal forecast value of 1689.4 million USD by 2032. This path reflects a compound annual growth rate of 5.2 percent across the full forecast period, a pace that rewards early strategic positioning while demanding disciplined capacity planning, pricing architecture, and compliance readiness. Critically, the growth curve is not linear; it is shaped by distinct catalysts—including regulatory phase-ins, regional capacity realignments, and technology-led differentiation in dye chemistry—that require granular analysis to translate into operational advantage.
This study dissects those catalysts without oversimplifying them. Rather than offering a single headline number, the report maps the interplay between historical demand elasticity, forward-looking procurement signals, and the structural factors that will determine which market participants capture disproportionate share. Readers will find that the macro-outlook serves as an anchoring framework, while the deeper segmentation layers reveal where margin pools are forming and where competitive intensity is likely to compress returns.
Report Architecture: From Strategic Framework to Operational Playbook
A market study earns its place on the executive dashboard only when it bridges high-level economic signals with on-the-ground decision variables. The PW Consulting Textile Dyes Market report is built around that principle. It delivers a comprehensive, multi-layered assessment that spans quantitative forecasting, qualitative industry mapping, and competitive benchmarking, all organized to support scenario planning and resource allocation.
At its core, the report integrates a detailed industry analysis covering the period from 2020 through 2032, with a sharp focus on the immediate two-year strategic window of 2026 and 2027. This design enables leadership teams to calibrate both near-term tactical responses and longer-term capital deployment. The study examines the market through a structured segmentation lens—by type, by application, and by region—allowing users to isolate the demand engines most relevant to their product portfolios, manufacturing footprint, and distribution channels. Each segmentation dimension is evaluated for growth momentum, pricing sensitivity, and substitution risk, ensuring that strategic plans rest on differentiated evidence rather than aggregated averages.
Beyond segmentation, the report incorporates a thorough competitive landscape assessment. Market concentration metrics are analyzed to clarify the balance between consolidated leadership and fragmented niche competition, while company-level profiles illuminate the strategic priorities shaping the actions of dominant players. These profiles are not static corporate summaries; they are structured around each firm's specific dye offerings, regional strengths, and innovation orientation, providing a practical map of where incumbents are reinforcing their positions and where gaps may be opening for fast-moving challengers.
Dyes Market
The research also embeds a robust view of industry dynamics. Raw material economics, regulatory evolution, and sustainability-driven procurement requirements are treated as interconnected forces, not isolated events. By tying these dynamics to forecast periods and competitive behavior, the report equips readers to anticipate cost pressures, compliance expenditures, and product reformulation timelines that will influence sourcing strategies and product roadmaps.
For practitioners seeking operational depth, the study delivers the kind of actionable detail that supports concrete decisions: pricing architecture considerations, demand-center prioritization, regulatory readiness checks, and technology adoption pathways. The objective is to give executives and analysts a reference point that can be directly integrated into commercial planning, supply chain strategy, and R&D prioritization.
Competitive Landscape: Positioning, Differentiation, and the Battle for Specialty Relevance
The textile dyes market is characterized by a mix of global specialty chemical leaders, regional manufacturing powerhouses, and focused dye specialists. Competitive intensity is shaped not only by volume scale, but by the ability to offer performance-advantaged products, compliance-forward formulations, and application-specific color solutions. Market concentration reflects a moderately consolidated structure, with leading players commanding a meaningful share of total revenue while leaving substantial space for differentiated mid-tier and regional competitors to compete on technical service, agility, and customer intimacy.
Several organizations stand out for the strategic direction of their dye portfolios. Archroma, headquartered in Pratteln, Switzerland, has been advancing sustainable specialty dyes and dyeing solutions with bio-based options, signaling a clear orientation toward lower-environmental-impact chemistry and resource-efficient processing. DyStar Group, based in Singapore, continues to position itself as a leading supplier of textile dyes, pigments, and colorants with broad fiber coverage, an approach that supports customers seeking continuity across diverse material inputs. Huntsman Corporation, operating from The Woodlands, Texas, United States, maintains a portfolio of textile effects dyes and performance chemicals, reinforcing a value proposition centered on functional outcomes as well as color.
In Europe, Clariant AG of Muttenz, Switzerland, contributes specialty chemicals including dyes tailored for textile applications, while Lanxess AG, based in Cologne, Germany, offers dyes under its Macrolex brand for textiles, aligning its product identity with established performance credentials. Across the Indian subcontinent, Atul Ltd., headquartered in Atul, Gujarat, and Kiri Industries Ltd., also based in Gujarat, represent strong regional capabilities—Atul with performance chemicals and dyes for textiles, and Kiri with a focused emphasis on reactive and acid dyes. BASF SE, headquartered in Ludwigshafen, Germany, sustains a broad offering of dyes and intermediates for textile applications, leveraging scale and integrated chemistry competencies. Meanwhile, Sumitomo Chemical Co., Ltd., operating from Tokyo, Japan, pursues specialty dyes for textiles, underscoring the continued relevance of application-specific innovation in the global supply base.
Together, these players illustrate the competitive logic of the market: scale provides procurement and distribution advantages, but differentiation increasingly depends on sustainability attributes, color fastness and reproducibility, regulatory compliance readiness, and the ability to support customers through process optimization. The report analyzes how these firms are navigating raw material cycles, expanding or rationalizing capacity, and positioning their portfolios against tightening compliance expectations. By synthesizing these competitive signals, the study helps readers identify which strategic moves are likely to strengthen market standing and which product categories may face intensifying margin pressure.
Industry Dynamics: Regulation, Raw Materials, and the New Compliance Premium
No strategic assessment of the textile dyes market can ignore the regulatory and input-cost environment reshaping procurement behavior. In 2026, these forces are not background conditions; they are direct determinants of product design, supplier selection, and regional sourcing decisions.
On the regulatory front, compliance expectations are becoming more demanding and more tightly enforced. From 1 January 2026, OEKO-TEX standards tightened PFAS limits to 25 µg/kg across all standards, accompanied by enhanced verification mechanisms. This change directly affects the colorant and auxiliary chemistry that textile manufacturers can confidently specify, accelerating the shift toward lower-concern formulations. In parallel, REACH Annex XVII Entry 72 continues to restrict 33 substances in clothing, textiles, and footwear that come into contact with human skin, with ongoing enforcement sustaining pressure on product stewardship across the value chain. Broader chemical policy signals add further complexity: a PFAS restriction in consumer textiles such as rain jackets bans the sale and use of PFHxA from 2025 onward, and a U.S. Environmental Protection Agency final rule prohibits the distribution of articles containing phenol, isopropylated phosphate in U.S. commerce starting 31 October 2026, affecting textile and fashion supply chains.
These developments carry a strategic implication: compliance is moving from a defensive obligation to a commercial asset. Manufacturers that can demonstrate clear substance profiles, robust verification documentation, and reformulated dye systems are better positioned to serve brands and converters facing their own disclosure and procurement requirements. The report examines how regulatory timing interacts with product launch cycles and sourcing transitions, helping readers gauge where compliance-driven demand may accelerate adoption of specific dye technologies.
Raw material dynamics are equally consequential. During the first quarter of 2026, H acid prices increased moderately in Germany to 5,266 USD per metric ton, up 3.09 percent, driven by steady demand from specialty chemical and textile converter procurement. While the move is measured rather than disruptive, it reflects a broader environment in which input costs are influenced by regional demand patterns, production constraints, and the specialized nature of key intermediates. For dye producers and downstream textile processors, even moderate input-price movements can affect margin structures, quotations, and inventory timing.
Recent market events further illustrate the operational reality of this environment. In February 2026, Zhejiang Runtu Co., Ltd. announced a significant price surge for disperse dyes effective that month, with increases reaching up to 600 USD per metric ton for high-concentration blacks and blues. Around the same time, Zhejiang Longsheng Group Co., Ltd. announced an additional CNY 2,000 increase for disperse black and blue dyes, bringing the cumulative hike in the year to CNY 5,000, a move attributed to raw material costs. These announcements underscore how regional pricing actions can quickly affect cost planning and highlight the importance of monitoring supplier signaling as part of broader procurement strategy.
On the innovation and validation side, January 2026 saw Archroma announce the commercial launch of a new line of cellulosic direct dyes with up to 35 percent effluent COD reduction compared to conventional grades, a development that aligns product performance with wastewater management objectives. In April 2026, SGS attended China Interdye 2026 in Shanghai, connecting with experts on sustainable chemical management and awarding the first No PFAS Detected green-mark certificate for a water-repellent agent to a textile firm. Such milestones matter because they signal where validation frameworks, customer expectations, and product differentiation are converging.
Strategic Priorities for 2026 Decision-Making
For executives entering 2026, the central challenge is to convert market complexity into structured choices. The forecast growth rate of 5.2 percent confirms that demand expansion will continue, but value capture will depend on how well organizations align portfolio, sourcing, and compliance strategies with the specific forces shaping their segments. Several strategic priorities emerge from the broader market picture.
Textile Dyes Market
First, portfolio composition should be evaluated against both demand durability and regulatory exposure. Dye families and application areas that face higher compliance scrutiny may require accelerated reformulation, while segments with strong growth momentum and lower substitution risk may justify prioritized capacity or inventory support. Second, pricing and procurement planning should account for regional raw material behavior and supplier-level pricing actions, especially in disperse dye categories where recent increases have demonstrated the speed at which cost structures can shift. Third, sustainability and verification capabilities are becoming competitive levers. Formulations that reduce effluent load, lower concern-substance risk, and support customer documentation needs can strengthen supplier positioning in brand-driven procurement environments. Fourth, regional demand patterns should inform distribution and service strategies, since growth is not evenly distributed and customer expectations differ across manufacturing centers.
The study is designed to support each of these priorities with specific evidence, enabling readers to test assumptions, compare scenarios, and identify where decisive action will generate the greatest strategic return. By connecting the macro trajectory to segmentation-level dynamics, competitive behavior, and regulatory timing, the report provides a decision framework rather than a static market snapshot.
Accessing the Full Intelligence
The overview presented here reflects the analytical direction and strategic scope of the full Textile Dyes Market research report. To obtain the complete dataset, detailed segmentation analysis, comprehensive company profiles, and the full set of market forecasts and competitive assessments that support rigorous planning, readers are encouraged to access the complete report and accompanying materials directly. The depth required for precise sourcing, product roadmap decisions, and competitive positioning can be found in the full study, where each macro signal is reinforced by structured evidence and actionable interpretation.
For detailed analysis of this topic, please visit the official page: Textile Dyes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cover Glass Market Hits $1.56B with 1.3% CAGR from 2026-2032
By pmarketresearch, 2026-09-15
Strategic Intelligence for the 2026 Decision-Maker: Smartphone Cover Glass Market Outlook
The smartphone cover glass market stands at a critical inflection point as industrial leaders navigate the 2026 operating environment. Following five years of moderate historical expansion from 2020 through 2025, the sector now enters a forecast horizon extending to 2032 that demands precise strategic calibration. Our latest market research study translates complex supply-demand signals, regulatory shifts, and competitive maneuvers into actionable intelligence for procurement executives, R&D planners, and C-suite strategists who must allocate capital with confidence in a market defined by high concentration, evolving material science, and geopolitical recalibration.
This introduction outlines the strategic architecture of the full report, demonstrating why leadership teams should treat this assessment as a core input to 2026 portfolio decisions, capacity planning, and supplier negotiations. Rather than presenting a static snapshot, the research functions as a forward-looking decision framework that connects macro trajectory signals to on-the-ground execution priorities.
Market Trajectory and the Strategic Imperative for 2026
Historical revenue data from 2020 through 2025 reveals a market that has demonstrated resilience through cycles of component volatility, shifting OEM demand patterns, and intermittent supply disruptions. The sector crossed the 1,560 million USD threshold in the most recent base year measurement before entering the current forecast window, where trajectory modeling projects growth toward the 1,700 million USD range by the close of the decade. The forecasted compound annual growth rate of 1.3 percent across the 2026 to 2032 period underscores a market characterized by measured, structural expansion rather than explosive volatility.
For decision-makers, this trajectory carries nuanced implications. A modest CAGR in a high-value component category often masks significant underlying shifts in product mix, regional sourcing preferences, and premiumization trends within flagship device portfolios. The market is not simply growing; it is recomposing. Foldable device architectures, chemically strengthened glass specifications, and OEM supply chain localization strategies are altering where margin accrues and which suppliers capture disproportionate value. Strategic leaders who rely on backward-looking averages risk misallocating resources in a landscape where product-level differentiation and capacity positioning matter far more than aggregate market size.
The full report decomposes this trajectory into decision-grade scenarios, enabling teams to map procurement commitments, capital expenditure timing, and partnership strategies against realistic demand pathways rather than single-point projections. Readers are invited to access the complete forecast modeling and scenario analysis on our source page, where detailed growth drivers, sensitivity parameters, and regional momentum indicators are presented in full operational depth.
Competitive Architecture and Supplier Positioning
Market concentration remains a defining structural feature of the smartphone cover glass landscape. With the top three participants commanding approximately 80 percent of revenue and the top five collectively representing roughly 85 percent, the sector operates as an oligopolistic environment where incumbent scale, proprietary material formulations, and long-standing OEM relationships create formidable barriers to displacement. Yet within this concentrated framework, competitive dynamics are intensifying as suppliers race to align capacity with next-generation device requirements and navigate cost pressures from regulatory and raw-material headwinds.
Incumbent Technology Leaders
Corning Incorporated continues to anchor the premium cover glass segment through its Gorilla Glass series, anchoring a substantial share of flagship smartphone adoption. The launch of Corning® Gorilla® Glass Ceramic 3 in March 2026 marks a deliberate push into enhanced drop durability for foldable device architectures, signaling how material innovation is being reoriented around new form factors rather than traditional flat-panel optimization. This product introduction follows a broader capacity expansion effort in early 2026 designed to support high-volume flagship OEM demand across North American and Asian supply networks.
The strategic weight of these moves was reinforced by the August 2025 commencement of production at a Kentucky facility developed in partnership with Apple, representing a 2.5 billion USD investment that consolidated a significant share of iPhone and Apple Watch cover glass manufacturing within a single U.S.-based operation. For the broader market, this capacity concentration illustrates how anchor OEM commitments can reshape regional supply footprints while reinforcing the competitive moat of leading material science firms.
Diversified Global Contenders
AGC Inc. maintains a strong premium positioning through its Dragontrail® product family, delivering chemically strengthened glass solutions targeted at flagship and high-tier device segments. Schott AG continues to compete in the chemically strengthened category with its Xensation® series, including the Xensation® α specification engineered for improved drop performance in flagship smartphones. Nippon Electric Glass Co., Ltd. supplies chemically strengthened cover glass across smartphone and foldable device applications, while AvanStrate Inc. operates production facilities across Japan, Taiwan, and Korea to support display and cover glass requirements for major OEM customers.
In the broader production ecosystem, Biel Crystal Manufactory Ltd. has scaled as a major global producer of cell phone cover glass and sapphire components, with annual production capacity exceeding 1.85 billion units. Lens Technology Co., Ltd. functions as a key supplier of cover glass, structural parts, and functional modules for smartphones, serving major OEMs worldwide. TPK Holding Co., Ltd. rounds out the competitive field as a manufacturer of cover glass and touch solutions for smartphones. Together, these players illustrate a competitive matrix in which differentiation hinges on material specifications, geographic production flexibility, and the ability to secure multi-year OEM program wins.
The report's competitive analysis module provides granular supplier benchmarking, program win trajectory assessment, and capability-to-capacity alignment mapping. Complete supplier profiles, performance scorecards, and strategic risk indicators are available through the full research portal, enabling procurement and R&D teams to pressure-test their current sourcing strategies against an evolving competitive baseline.
Market Dynamics Shaping Strategic Decisions
The operating environment for smartphone cover glass in 2026 is shaped by intersecting forces that extend well beyond simple demand forecasting. Regulatory compliance costs, export control expansions, import surge patterns, raw-material lead-time elongation, and critical material export restrictions all contribute to a more complex sourcing and planning landscape. Decision-makers must integrate these factors into scenario planning rather than treating them as peripheral risks.
Regulatory and Chemical Compliance Pressure
The European Chemicals Agency reported that compliance costs for hydrofluoric acid used in glass tempering processes rose by 15 percent in 2024. This increase directly touches the cost structure of chemically strengthened glass production, a category that constitutes a meaningful share of premium cover glass supply. For procurement teams, the implication is twofold: cost models that rely on historical chemical input assumptions may underestimate current and forward pricing pressure, and supplier negotiations must account for regional regulatory divergence that affects landed cost and availability.
A separate indicator of demand strength and import dependency comes from the U.S. International Trade Commission, which recorded a 17 percent increase in imports of chemically strengthened glass for smartphones in 2024. This import trajectory signals both robust downstream demand and the extent to which supply chains remain internationally interconnected, even as OEMs pursue localized capacity strategies. The tension between import reliance and regional supply expansion is a key theme explored in the full report's dynamics section.
Geopolitical and Supply Chain Disruption Vectors
U.S. export controls on advanced computing items expanded in 2024, creating ripple effects across global supply chains for specialty glass components. While cover glass may not always fall directly within the narrowest controlled categories, the broader export control environment influences manufacturing equipment access, technology transfer constraints, and supplier qualification pathways across multiple jurisdictions. Strategic sourcing plans that do not explicitly model geopolitical fragmentation risk understimating qualification timelines and dual-sourcing complexity.
Compounding these dynamics, supply chain constraints and precursor cost surges drove average lead times for cover glass components to approximately 45 days in 2024. For program managers and inventory planners, extended lead times translate directly into buffer stock requirements, working capital exposure, and scheduling rigidity. The report's operations section translates these lead-time signals into inventory strategy recommendations and supplier diversification frameworks tailored to high-concentration supply markets.
Smartphone Cover Glass Market
In addition, China's Export Control Law and related MOFCOM regulations, updated with detailed rules in October 2024, impose restrictions on exports of critical materials used in display cover glass production. For organizations with material dependencies crossing this regulatory boundary, the compliance pathway now demands explicit mapping of raw-material origin, processing steps, and end-use classification. The research study provides a regulatory impact matrix that helps teams identify where material flow vulnerabilities could affect cost, availability, or program continuity.
Report Contents and Practical Applications
The full market research study is designed as a decision-support toolkit rather than a static market description. It integrates historical baseline analysis, multi-year forecasting, segmentation perspectives, competitive profiling, and dynamic risk factor assessment into a cohesive reference for 2026 strategy development. The following components represent the operational core of the study.
- Market Sizing and Trajectory Framework: A comprehensive revenue trajectory spanning historical baseline years and a forecast window extending through 2032, structured to support demand planning, capacity justification, and investment prioritization. The analysis presents total market perspective alongside segmentation views that illuminate type-based and application-based composition without isolating strategic detail from its broader market context.
- Segment-Level Composition Analysis: Detailed coverage of material type categories and end-use application patterns, enabling teams to understand where revenue concentration lies and how product mix evolution may influence sourcing requirements, specification priorities, and supplier selection criteria over the forecast horizon.
- Competitive Intelligence and Supplier Profiling: In-depth profiles of the key companies shaping the market, including headquarters location, product positioning, recent strategic developments, and capability signals. The study connects company-level moves to market-level implications, allowing readers to assess competitive threats, partnership opportunities, and supply base resilience.
- Dynamics and Risk Factor Integration: A structured treatment of regulatory cost pressures, export control and trade policy developments, import trend indicators, raw-material lead-time dynamics, and critical material export restrictions. This section translates external signals into actionable planning considerations for procurement, compliance, and supply chain leadership.
- Strategic Implications and Decision Scenarios: Synthesis sections that connect market data, competitive signals, and dynamic risks into decision scenarios for capacity planning, supplier diversification, program timing, and technology roadmapping. These scenarios are designed to support internal alignment across R&D, operations, procurement, and executive strategy functions.
Throughout the study, segmentation insights are presented with the discipline required for confidential strategic use: enough structural clarity to inform sourcing and planning logic, while preserving the detailed quantitative granularity that belongs in the paid research deliverable. The complete segmentation splits, scenario parameters, and sensitivity ranges are available in the full report, where they can be applied directly to internal models and negotiation frameworks.
Why This Research Matters for 2026 Decisions
In a market where a small number of suppliers command the majority of revenue, where material specifications are rapidly evolving around foldable and flagship device requirements, and where regulatory and geopolitical factors are reshaping cost and availability assumptions, strategic advantage depends on early visibility and precise interpretation. Aggregate market size alone does not reveal where margin is shifting, which supplier capabilities will be stressed by new device architectures, or how regional compliance costs will alter sourcing economics over the forecast period.
This research is built to answer those questions with the rigor required for enterprise decision-making. It equips leaders with a structured view of market trajectory, competitive positioning, and dynamic risk factors so that 2026 planning can move beyond reactive adjustments and toward proactive portfolio design. Whether the objective is to validate a long-term supplier partnership, prioritize R&D investment in cover glass specifications, or construct a resilient sourcing strategy amid extended lead times and raw-material constraints, the study provides the analytical foundation to make those choices with greater confidence.
The complete market research study, including full forecast modeling, detailed segmentation breakdowns, supplier capability assessments, and dynamic risk matrices, is available through our source page. We encourage strategy, procurement, and product leadership teams to access the full report to integrate these insights directly into 2026 planning cycles and supplier engagement strategies.
Glass Screen Protector Market
For detailed analysis of this topic, please visit the official page: Smartphone Cover Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com