
Blogs
Strategic Shifts and Commercial Opportunities in the Gas Engines Market
The global gas engines market has entered a phase of disciplined expansion, driven by evolving energy security priorities, decarbonization mandates, and the growing need for flexible, dispatchable power. Recent market trajectories indicate a transition from predominantly traditional applications toward integrated systems that combine generation, cogeneration, and progressively lower-emission fuel capabilities. Understanding the structural shifts behind this growth is critical for manufacturers, investors, and procurement teams seeking to align capital deployment and product roadmaps with where demand is truly heading.
Market Landscape and Core Challenges
The market has demonstrated steady growth over the past five years, with revenue scaling from the mid-four-billion-dollar range in the early 2020s to nearly six billion dollars by the mid-2020s. Forward projections point to a sustained compound annual growth rate in the mid-five-percent range, extending through the end of the decade and into the early 2030s. This trajectory reflects both replacement demand in mature installations and incremental growth tied to electrification, data center expansion, and industrial resilience needs. While the top-line growth appears consistent, the path is uneven across applications and fuel types, creating a landscape where scale alone is no longer a sufficient competitive advantage.
Several structural challenges are shaping how companies navigate this environment.
- Fuel quality variability and operational reliability. As gas engines are deployed across diverse supply networks, variability in gas composition increasingly affects performance, maintenance cycles, and warranty outcomes. Operators face rising scrutiny over combustion stability, emissions compliance, and lifecycle costs when gas specifications deviate from design assumptions.
- Regulatory fragmentation. Compliance requirements are diverging by jurisdiction and by engine class, forcing manufacturers and operators to manage multiple reporting timelines, certification pathways, and emission thresholds. This complexity raises the cost of market entry and slows standardization across global product lines.
- Transition pressure on incumbent applications. Traditional mechanical drive and standby generation use cases are being reassessed against alternatives such as battery integration, hybrid systems, and efficiency upgrades. Engine suppliers must demonstrate not only power output but also total system value, including fuel flexibility, grid services capability, and lower operating risk.
These challenges do not weaken the market; rather, they redefine where value is created. Companies that can standardize performance across variable operating conditions, simplify compliance exposure, and package engines within broader energy solutions are positioned to capture disproportionate share.
Key Drivers Shaping Market Evolution
Technological Innovation and Fuel Flexibility
Advancements in combustion control, materials, and engine management systems are expanding the envelope of fuels that gas engines can handle reliably. This matters because the commercial value of a gas engine increasingly depends on its ability to operate across a range of gas qualities without sacrificing availability or emissions performance. Manufacturers are responding with designs that maintain efficiency as methane content, calorific value, and contaminant levels fluctuate. Parallel progress in hydrogen blending readiness and low-emission combustion strategies is broadening the addressable base, particularly in regions where future fuel pathways remain uncertain. The strategic implication is clear: engines that can adapt to changing fuel profiles over their service life will command stronger positioning in both power generation and cogeneration segments.
Policy and Regulatory Architecture
Regulatory frameworks are becoming a primary determinant of deployment economics. New reporting obligations, emissions thresholds, and performance standards are reshaping the cost structure for operators and influencing procurement specifications. In some jurisdictions, medium and large engine operators face defined reporting deadlines tied to specific calendar years, creating predictable but rigorous compliance cycles. In parallel, technical guidelines addressing the impact of gas quality on engine performance are being formalized, reinforcing the link between fuel characteristics and operational accountability. These dynamics push buyers toward suppliers that can offer documentation, configuration support, and service models aligned with local obligations. For manufacturers, regulatory alignment is increasingly a product feature, not just a legal requirement.
Demand-Side Behavior and Industrial Electrification
End users are shifting from viewing engines as isolated assets to treating them as components within broader energy systems. Power generation remains a central application, but the value proposition is changing. Data centers, industrial campuses, and distributed energy projects increasingly prioritize reliability, rapid deployment, and the ability to support grid stabilization or combined heat and power economics. Cogeneration applications continue to attract interest where thermal demand can be monetized, while mechanical drive applications are being selectively replaced or supplemented by lower-emission alternatives. This demand-side evolution rewards suppliers that can deliver integrated offerings, predictable lead times, and operating flexibility across multiple use cases.
Cost Structures and Supply Chain Realities
The economic equation for gas engines is being reshaped by component availability, manufacturing scale, and service network density. Engine programs that depend on specialized subsystems face exposure to lead-time variability and regional supply constraints. At the same time, the rise of lower-emission configurations and advanced control systems adds complexity to the bill of materials, which can pressure margins unless offset by design standardization or higher-value service arrangements. Commercial success is therefore tied not only to unit sales but also to the ability to manage total cost of ownership, localize content where feasible, and maintain responsive aftermarket support. Companies that reduce friction in the procurement-to-installation cycle and provide clear service economics are better positioned to defend pricing and secure repeat business.
Worldwide Power Generation Engines Market
Competitive Landscape and Leading Strategies
The competitive field is defined by established engine manufacturers with strong installed bases, differentiated fuel strategies, and distinct geographic strengths. The market remains moderately concentrated at the top, but differentiation is increasingly driven by application focus, fuel readiness, and the breadth of support services rather than by volume alone.
Leaders are pursuing several distinct strategic postures.
- Dedicated gas engine specialists. Some manufacturers have built identity around gas-specific platforms and large installed bases in power generation, cogeneration, and hydrogen-ready configurations. Their advantage lies in application depth, field experience across varied gas conditions, and the credibility that comes from a broad operational footprint.
- Multisegment power and mobility players. Larger diversified manufacturers leverage scale, global distribution, and cross-platform integration. Their gas engine offerings often serve multiple end markets, including power generation, compression, and commercial fleets, with emphasis on near-zero emission configurations and heavy-duty performance.
- Industrial and harsh-environment specialists. Other participants focus on robustness, serviceability, and suitability for demanding operating conditions. Their value proposition centers on durability, simplified maintenance, and strong support in regions where environmental extremes or infrastructure constraints matter.
- Marine and industrial engine providers. Certain firms maintain strong positions through product families tailored to industrial and marine use, with attention to emissions performance, fuel adaptability, and system compatibility.
The market is not consolidating into a single winner-takes-all structure. Instead, it is bifurcating around capability clusters: fuel-flexible power generation and cogeneration platforms on one side, and rugged industrial or specialized mechanical applications on the other. New entrants and adjacent players are exploring niches where hydrogen readiness, hybridization, or regional compliance advantages create room for differentiated offerings. However, incumbents with established service networks, installation bases, and application knowledge retain meaningful barriers, especially where operators prioritize availability and total lifecycle cost over initial acquisition price.
Strategic differentiation is increasingly visible in three areas. First, engine platforms that can accommodate varying gas qualities and future fuel blends reduce risk for operators and expand the addressable market for suppliers. Second, alignment with local reporting and emissions expectations shortens procurement cycles and lowers operational uncertainty. Third, bundling engines with generator sets, control systems, and service agreements creates stickier customer relationships and shifts competition toward total delivered value. Companies that treat compliance, fuel adaptability, and service economics as core design inputs are gaining an edge in bidding and long-term account retention.
PW Consulting Automotive & Machinery Research Center
Future Trends and Commercial Implications
Fuel adaptability becomes a baseline requirement
Over the next three to five years, gas engines will face increasing pressure to perform reliably across fluctuating fuel compositions and, in many markets, to accommodate progressive shifts toward blended or lower-carbon gases. This trend will reward platforms designed for broader fuel envelopes and modular combustion adjustments, especially where gas infrastructure is still maturing or where renewable gas integration is accelerating. The commercial opportunity lies in offering engines that maintain availability and efficiency while simplifying operator risk. The uncertainty is the pace and direction of fuel transition, which may differ sharply by region and by supply infrastructure readiness.
Compliance-driven procurement accelerates
Regulatory and technical standards are expected to remain a central force in purchasing decisions. As reporting cycles mature and performance guidelines become more explicit, operators will favor suppliers who can deliver documentation, configuration certainty, and service paths that align with local obligations. This creates a commercial opening for manufacturers that streamline compliance integration and can demonstrate consistent adherence across engine classes. The risk is that fragmented requirements increase engineering and administrative burden, particularly for companies operating across multiple jurisdictions with differing reporting thresholds and emissions expectations.
Diesel Engines Market
System integration displaces standalone product competition
Demand is shifting toward complete solutions that pair engines with generation equipment, heat recovery, controls, and service contracts. In power generation and cogeneration, buyers increasingly evaluate projects based on grid interaction, thermal utilization, lead-time reliability, and operating resilience rather than engine specifications alone. The opportunity for suppliers is to expand value capture through integrated offerings, performance guarantees, and lifecycle support. The risk is that integration raises complexity and can blur product boundaries, making it harder to compete on engine performance in isolation. Companies that can clearly articulate system-level benefits while maintaining technical credibility will be better positioned to participate in this shift.
Strategic Recommendations for Decision-Makers
For Manufacturers
Invest in fuel-flexible platform design and modular combustion capabilities that can accommodate variable gas quality and future blend scenarios without sacrificing availability. Standardize as much of the core architecture as possible to control cost and simplify service, while differentiating through emissions performance, compliance support, and application-specific configurations. Strengthen service networks and documentation processes so that compliance, maintenance, and warranty management become selling points rather than overhead.
For Investors
Focus on companies that combine installed-base credibility with clear pathways to lower-emission and fuel-adaptive offerings. Evaluate exposure to applications where reliability, cogeneration economics, and grid-support value are rising, and assess whether the target can manage regulatory complexity across multiple markets. The most resilient opportunities are likely to come from suppliers that can convert technical adaptability into commercial differentiation and that have service models aligned with operator total-cost concerns.
For Procurement and Operations Leaders
Prioritize suppliers that can demonstrate real-world performance across gas quality variability, provide transparent compliance support, and offer service terms that reduce operational risk. Evaluate projects on total system value, including thermal use, dispatch flexibility, and lifecycle economics, rather than on headline power output alone. Where possible, structure procurement to include clear documentation, configuration certainty, and service response expectations, as these factors increasingly determine long-term operating cost and availability.
Closing Perspective
The gas engines market is expanding along a path that favors adaptability, compliance readiness, and system-level value over traditional volume competition alone. Fuel flexibility, regulatory alignment, and integrated service models are becoming decisive factors in where share is won and retained. For organizations making capital, product, or procurement decisions, the ability to access detailed segment-level data and targeted scenario analysis can materially improve timing, positioning, and risk management. A comprehensive market study can provide the granular view needed to translate these strategic dynamics into specific action plans across regions, applications, and technology pathways.
For detailed analysis of this topic, please visit the official page: Gas Engines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
When searching for a reliable Bandar Togel , security and transparency top the list. Players want assurance that the platform is licensed, that jackpots (JP) are paid promptly, and that personal and financial data remain protected. This guide helps you evaluate online toto operators, explains why ALEXISTOGEL stands out with a PAGCOR license through 2026, and outlines practical tips to play smarter and safer.

What Makes a Bandar Togel Trustworthy?
Not all online toto platforms are equal. A trustworthy Bandar Togel displays clear licensing information, strong customer support, fair play practices, and secure financial processes. Here are the core attributes to look for:
1. Valid License and Regulatory Oversight
Legitimate operators prominently display regulatory credentials. A recognized regulator, such as PAGCOR, provides oversight that reduces fraud risk and offers a recourse channel for disputes. A platform that lists a current license number and expiry date demonstrates transparency and accountability.
2. Secure Transactions and Data Protection
Bank-level encryption, audited payment gateways, and clear privacy policies are non-negotiable. Reliable Bandar Togel sites support multiple secure deposit and withdrawal methods and confirm transaction timestamps and confirmations to users.
3. Clear Rules and Fair Play
Fair odds, published game rules, and verified randomization processes are essential. Check whether the operator publishes RTP (return to player) rates, audit results, or independent testing certifications.
4. Prompt Payouts and Customer Support
Speedy jackpot payments and responsive customer service are practical indicators of a healthy operator. Look for live chat, email support, and visible transaction histories that prove payouts are processed reliably.
ALEXISTOGEL at a Glance: Why It’s a Top Choice
ALEXISTOGEL markets itself as a consultation and Bandar Togel operator with a PAGCOR license valid through 2026. Below are the reasons users prefer it and how it meets the trust criteria above.
Licensed and Transparent
ALEXISTOGEL lists its PAGCOR license, showing it operates under regulatory oversight. This gives players confidence that the platform follows mandated standards and is subject to routine checks. Licensing reduces risks associated with rogue operators and adds a layer of formal accountability.
Security and Responsible Operations
The platform emphasizes secure transactions and data protection, integrating trusted payment channels and encryption protocols. Users benefit from clear privacy statements and secure account verification steps, which help prevent fraud and unauthorized access.
Reliable Payments and User Support
A key selling point for ALEXISTOGEL is its commitment to paying jackpots. The site highlights prompt payout procedures, and customer feedback often references quick settlement times. Additionally, accessible support channels make it easier to resolve account or payment questions.
How to Verify Any Bandar Togel Before You Play
Even with positive reviews, always run your own checks. Follow these steps before depositing funds with any online toto operator:
1. Confirm the License
Check the license number and expiry date on the operator’s site, then verify it with the issuing regulator. For PAGCOR-licensed platforms, confirm the validity through official PAGCOR resources.
2. Read Terms and Withdrawal Policies
Transparency about wagering requirements, minimum withdrawals, and verification documents matters. Avoid platforms that hide or complicate payout rules.
3. Test Customer Service Response
Contact support with a few questions before deposit. Response time and the quality of answers reflect how disputes will be handled.
4. Check Community Feedback
User reviews and independent forums can highlight consistent payout issues or positive service patterns. Look for patterns rather than isolated incidents.
Responsible Play and Smart Bankroll Management
Gambling should be entertainment, not a financial burden. Set limits before you start: decide on deposit caps, loss thresholds, and time limits. Use the platform’s responsible gaming tools if available, and never chase losses. By treating play as a controlled expense, you keep it fun and reduce risk.
Conclusion: Play Safely, Choose Wisely
Choosing a reliable Bandar Togel requires diligence: verify licensing, inspect security and payout practices, and test support responsiveness. ALEXISTOGEL’s PAGCOR license through 2026, commitment to secure transactions, and focus on reliable jackpot payments make it a strong option for players seeking a safer toto experience. Remember to play responsibly and apply the verification steps above before making any deposits. Safe play and well-informed choices are the best ways to enjoy Bandar Togel with confidence.
Plastic Food Containers Market Report: Why 6.98% CAGR Signals Strategic Shifts
By pmarketresearch, 2026-09-21
Strategic Trends and Commercial Opportunities in the Plastic Food Containers Market
The plastic food containers market has entered a defining phase, shaped by steady demand expansion, shifting regulatory expectations, and an intensifying race toward sustainable materials. Valued at approximately USD 215.0 million in 2025 and projected to reach USD 344.8 million by 2032, the sector is advancing at a compound annual growth rate of 6.98 percent over the forecast period. This trajectory reflects more than incremental volume growth; it signals a structural transition in how food is packaged, distributed, and consumed across household and commercial channels. Market participants are navigating a landscape where performance, compliance, and circularity increasingly determine competitive positioning.
Market Landscape and Core Challenges
The market has demonstrated consistent expansion since 2020, with revenue compounding from roughly USD 163.15 million to a 2025 baseline near USD 215.0 million. The upward momentum is expected to continue through 2032, though the pace will be uneven as regional maturity, product mix, and regulatory adoption diverge. A moderately fragmented landscape persists, with the top three firms capturing 24.6 percent of revenue and the top five firms representing 26.2 percent. This concentration suggests that scale advantages coexist with room for differentiated players to compete on innovation, regional reach, and specialized applications rather than price alone.
Despite the favorable growth path, the industry faces three structural challenges that will shape margin dynamics and go-to-market strategies over the next several years. First, sustainability mandates are compressing traditional design cycles and forcing material substitution decisions that carry cost and performance trade-offs. Companies must reconcile recyclability targets, recycled content requirements, and consumer expectations while preserving functional properties such as heat resistance, shelf life, and leak protection. Second, raw material price volatility continues to pressure unit economics. Resin costs, energy inputs, and logistics expenses have introduced greater variability into production planning, making procurement strategy and hedging decisions more consequential. Third, regulatory fragmentation across jurisdictions is increasing compliance complexity. Divergent rules on single-use items, expanded polystyrene, PFAS restrictions, and recycled content create a patchwork that favors firms with robust regulatory intelligence and flexible manufacturing footprints.
These challenges are not purely defensive. They are reshaping value pools by rewarding capabilities in material science, supply chain agility, and compliance readiness. Firms that treat sustainability and regulation as design constraints rather than afterthought considerations are better positioned to capture premium segments and secure long-term customer relationships.
Key Demand Drivers
Material Innovation and Performance Breakthroughs
Material innovation is emerging as a primary engine of differentiation. The industry is moving beyond conventional resin formulations toward BPA-free architectures, compostable fibers, and natural polymer systems that retain or improve performance while addressing end-of-life concerns. Joint development efforts are accelerating the translation of laboratory concepts into commercial packaging, particularly where moisture barriers, thermal stability, and structural integrity must be maintained without relying on traditional additives. Recent collaborations signal a broader shift: the market is seeing coordinated work between packaging producers and specialty material suppliers to create fully plastic-free and biodegradable solutions built on natural polymers, alongside recyclable paper alternatives for confectionery and other sensitive categories. These advances expand the commercial envelope for foodservice operators who need to meet sustainability commitments without compromising food quality or handling convenience.
Worldwide Plastic Sterilization Containers Market
The commercial implication is clear. Packaging is increasingly a strategic asset rather than a commodity input. Buyers are evaluating suppliers on material safety, recyclability pathways, and compatibility with circular systems. Suppliers that can demonstrate verified performance, transparent lifecycle attributes, and scalable production will command stronger positioning in both household and commercial segments.
Regulation and Compliance as Market Architecture
Regulatory developments are no longer peripheral; they are becoming the scaffolding around which product portfolios, sourcing strategies, and regional expansion plans are built. The Packaging and Packaging Waste Regulation entered into force in early 2025 and is set to generally apply later in the year, with expectations that recyclable packaging will be mandatory by 2030 and that recycled plastic use in EU packaging will increase. In the United States, California finalized permanent regulations for its packaging extended producer responsibility program, establishing producer fees for single-use plastic food service ware and a mandatory 25 percent recycling rate for expanded polystyrene. Meanwhile, Virginia implemented a ban on single-use plastic food containers for large food businesses, with full expansion to all vendors scheduled for mid-2026.
These measures create two simultaneous effects. They raise the compliance bar for legacy materials, particularly expanded polystyrene and non-recyclable formats, while also opening space for alternative designs that align with extended producer responsibility economics and recycling infrastructure. For manufacturers, this means product roadmaps must account for jurisdictional timelines, fee structures, and end-market recycling availability. For investors, regulatory tailwinds can validate capital allocation into recyclable, compostable, and fiber-based lines, but only where end-user adoption and collection infrastructure can support scale.
Demand-Side Shifts in Household and Foodservice Channels
Demand patterns are evolving on both sides of the market. In household use, consumers continue to prioritize convenience, food safety, and storage efficiency, but purchasing decisions are increasingly influenced by perceived health safety and environmental impact. BPA-free containers have gained traction as a baseline expectation rather than a premium feature, reflecting broader awareness of material safety in food contact applications. In commercial and foodservice channels, operators are balancing cost discipline with brand positioning around sustainability. Quick-service and delivery models depend on containers that withstand microwave heating, maintain temperature integrity, and resist leakage during transit, while also meeting corporate sustainability targets and local ordinance requirements.
These demand dynamics create a split incentive structure. Household buyers reward safety, clarity, and convenience, while commercial buyers reward volume reliability, compliance, and brand alignment. Suppliers that can tailor product attributes to each channel, without over-indexing on a single use case, are better equipped to capture cross-channel growth. The market is therefore rewarding flexible product architectures and application-specific engineering over uniform commodity offerings.
PW Consulting Health Care Research Center
Supply Chain and Cost Structure Dynamics
Cost structure volatility is a persistent theme. Resin pricing, energy costs, and transportation expenses have introduced variability into production planning and margin forecasting. The U.S. Producer Price Index for plastics material and resin manufacturing has reflected elevated levels, underscoring the sensitivity of input costs to macroeconomic and feedstock conditions. In this environment, procurement strategy, contract design, and production scheduling are becoming competitive levers. Companies are increasingly seeking to stabilize input exposure through long-term agreements, diversified sourcing, and operational efficiency programs that reduce scrap and rework.
The broader implication is that cost leadership will depend less on sheer volume and more on resilience and precision. Manufacturers that can manage resin exposure, optimize changeover times, and maintain quality consistency under input cost pressure will protect margins more effectively than those relying solely on price negotiation. This dynamic also favors regional production strategies that shorten lead times and reduce transport exposure for bulky food containers.
Competitive Landscape and Leading Strategies
The competitive field features global container specialists, foodservice packaging producers, and paper-based packaging suppliers that are extending into plastic and hybrid formats. Several firms have established distinct strategic positions. Amcor operates as a global leader in rigid plastic containers, including polypropylene and PET food containers and trays for foodservice, leveraging scale and application engineering across multiple regions. Huhtamaki produces polypropylene and paper-based disposable food containers and takeaway packaging, with a visible push toward recyclable and biodegradable formats. Dart Container Corporation has expanded its ProPlanet compostable fiber and plastic food containers for foodservice and retail, including PFAS-free solutions, reflecting a focus on compliance-friendly sustainable lines. Berry Global Inc. produces rigid plastic containers and packaging solutions for disposable food containers and foodservice, combining broad portfolio coverage with manufacturing flexibility. Pactiv Evergreen remains a leading manufacturer of foam and plastic foodservice containers and disposable packaging, while Genpak and Sabert serve quick-service and catering segments with durable plastic and paper disposable containers and hot/cold/catering solutions.
Additional players contribute to regional depth and specialty positioning. Novolex focuses on recycled and compostable plastic take-out containers and foodservice packaging. Anchor Packaging specializes in premium take-out and delivery plastic containers resistant to microwave and heat, targeting delivery-heavy operators. International Paper supplies paper-based and plastic food containers with sustainable packaging solutions and has moved to strengthen U.S. production capacity through a recent sustainable packaging facility expansion. Reynolds Consumer Products and Silgan Holdings continue to participate in plastic foodservice and takeaway containers and packaging, while Sealed Air provides protective and disposable plastic food packaging and containers. International exposure is also evident from exporters such as Jinhua Lanxin Commodity Co., Ltd., which supplies disposable plastic food containers, plates, and tableware for catering.
Plastic Caps Market
Several strategic patterns stand out. First, differentiation is increasingly product- and compliance-led. Expandable polystyrene portfolios face mounting regulatory and consumer pressure, while recyclable, compostable, fiber-based, and BPA-free lines are gaining attention from buyers seeking to align with sustainability targets and local rules. Second, partnerships and collaborations are accelerating material transitions. Recent joint development work on natural polymer-based, plastic-free, and biodegradable packaging, alongside conversions of plastic packaging to recyclable paper options in confectionery, indicate that incumbents are using ecosystem partnerships to reduce time-to-market for next-generation formats. Third, capacity and geographic alignment are being revisited. Investments in U.S. production and sustainable packaging facilities point to a desire to serve regional demand more efficiently while reducing transport exposure and improving responsiveness.
The market is likely to continue a dual trajectory. Consolidated leaders will compete on scale, breadth, and integrated feedstock-to-finished-product capabilities, while smaller and regional players will compete on application specialization, speed, and localized compliance readiness. M&A and partnership activity may intensify where companies seek to fill gaps in recyclable or compostable lines, expand geographic coverage, or acquire material science competencies. New entrants will find opportunity in niches where conventional players are slower to adapt, particularly in compostable fibers, PFAS-free constructions, and microwave-resistant premium delivery containers.
Forward Outlook: Three Trends for the Next 3 to 5 Years
Trend 1: Compliance-Driven Portfolio Rebalancing
Over the next several years, product portfolios will increasingly reflect jurisdiction-specific compliance requirements rather than one-size-fits-all designs. Recyclable packaging expectations, expanded polystyrene restrictions, and recycled content mandates will push manufacturers to maintain parallel product lines tailored to different regions and customer segments. This rebalancing will favor firms with strong regulatory monitoring, flexible tooling, and clear communication of end-of-life pathways. The commercial opportunity lies in helping buyers navigate transition timelines with products that meet near-term rules while remaining compatible with longer-term recycling and circular economy goals.
Trend 2: Sustainable Materials Moving from Differentiator to Baseline
BPA-free containers, recyclable paper alternatives, compostable fibers, and PFAS-free formulations are expected to shift from premium or niche offerings toward baseline expectations in selected channels. As major foodservice operators and household brands set public sustainability targets, procurement specifications will increasingly include material safety, recyclability, and reduced additive use as standard criteria. The opportunity is not simply to launch sustainable products, but to build verifiable performance data, scalable production, and transparent claims that withstand scrutiny from regulators, retailers, and consumers. Companies that can prove functionality alongside sustainability will be better positioned to protect price points and customer loyalty.
Trend 3: Regionalized Production and Input Cost Management
Given resin price volatility and the logistical footprint of bulky food containers, regional production strategies are likely to gain importance. Facilities positioned closer to demand centers can reduce transport costs, shorten lead times, and improve responsiveness to local regulatory shifts. At the same time, procurement teams will continue to refine resin sourcing, hedging, and scrap reduction to protect margins against input cost swings. The strategic value will accrue to operators that can combine regional capacity with disciplined cost control and consistent quality, especially in high-volume commercial and foodservice applications where reliability is paramount.
These trends carry inherent uncertainties. Regulatory timelines may shift or be implemented unevenly, recycling infrastructure may lag packaging design ambitions, and raw material costs may remain volatile. Consumer willingness to accept tradeoffs in price or convenience will also shape adoption speed. Market participants should therefore treat sustainability and compliance investments as adaptive capabilities, with clear triggers for scaling successful formats and withdrawing underperformers.
Action Considerations for Decision Makers
For manufacturers, the priority is to align product roadmaps with compliance trajectories and channel-specific performance needs. This means investing in recyclable, compostable, and BPA-free lines where demand is most credible, while maintaining the engineering rigor required for heat resistance, leakage control, and structural durability. Procurement and production teams should also strengthen input cost resilience through diversified resin sourcing, longer-term contract structures where feasible, and continuous improvement in scrap and energy efficiency. Regional capacity decisions should be evaluated against local demand density, regulatory timing, and transport economics, particularly for bulky foodservice packaging.
For investors, the key is to distinguish between sustainability claims and scalable, commercially viable solutions. Preference should be given to companies with verified material performance, clear recycling or composting pathways, and manufacturing footprints that can respond to regional regulation. Growth exposure may be strongest where portfolios are expanding into PFAS-free compostable fibers, microwave-resistant delivery containers, and recyclable paper alternatives, especially if supported by partnerships that reduce development risk. Capital allocation should also account for the pace of infrastructure development, since end-market recycling and collection capacity will influence the practical impact of regulatory mandates.
For procurement and purchasing leaders, the focus should be on building supplier partnerships that can navigate a fragmented compliance environment without disrupting supply continuity. Evaluation criteria should include material safety, recyclability evidence, compatibility with delivery and heating workflows, and the supplier’s ability to adapt portfolios as regulations evolve. Multi-region sourcing and flexible specification management can help balance cost, compliance, and performance, particularly when local ordinances diverge on expanded polystyrene or single-use items. Maintaining visibility into resin cost trends and regional regulatory changes will also support more informed negotiation and inventory planning.
In a market advancing at a steady 6.98 percent CAGR through 2032, the winners will be those who convert sustainability, compliance, and cost volatility into structured competitive advantages. Detailed segmentation data, company-level tracking, and scenario modeling can sharpen these decisions further by illuminating where growth is concentrating, how portfolios are shifting, and which capabilities will matter most in each channel. For decision makers seeking a deeper view of regional dynamics, application splits, and company strategies, the full research report provides the granularity needed to translate these trends into targeted action.
For detailed analysis of this topic, please visit the official page: Plastic Food Containers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Power Quality Analyzer Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global power quality analyzer market has matured into a critical infrastructure intelligence segment, reflecting a broader shift from reactive fault management to continuous, data-driven electrical system oversight. By 2025, the market generated approximately 279.43 million USD in revenue, building on a consistent expansion trajectory from 216.87 million USD in 2020. Projections indicate that this growth will compound at a 5.2 percent CAGR through 2032, with revenue surpassing 398.84 million USD by the end of the forecast window. This expansion is not merely a function of incremental instrument sales; it signals a structural recalibration in how utilities, industrial operators, and commercial facility managers validate grid compliance, protect sensitive equipment, and underwrite operational resilience. The sector’s evolution is being shaped by tighter measurement standards, the proliferation of distributed energy resources, and a competitive environment where consolidation, specialization, and software-enabled services are redefining value creation.
Market Overview and Core Challenges
The market’s current scale and growth pattern point to a segment that has moved beyond early-adopter experimentation into broad operational necessity. Revenue growth between 2023 and 2025 accelerated modestly, reflecting both post-pandemic capital deployment and an increasing reliance on continuous monitoring rather than episodic testing. As the trajectory extends through 2032, the 5.2 percent CAGR suggests sustained demand, though the rate also implies a market that is gradually maturing and becoming more selective about technology upgrades and replacement cycles.
Several structural challenges are defining the next phase of growth. First, the sector is navigating a transition from periodic, campaign-based measurements to permanent or semi-permanent monitoring architectures. This shift requires new procurement logic, integration planning, and lifecycle management, because stakeholders must weigh the upfront cost of always-on instrumentation against the hidden costs of undetected disturbances, downtime, and compliance risk. Second, measurement complexity is rising faster than many organizations’ analytical capabilities. As power systems incorporate variable renewable generation, EV charging loads, and power-electronics-intensive equipment, the number of relevant disturbance parameters—harmonics, interharmonics, voltage dips, swells, and transient waveform characteristics—continues to expand. Instruments that can capture these parameters accurately are increasingly essential, yet the ability to interpret results, correlate them with asset performance, and act on them remains uneven across end markets. Third, the competitive environment is tightening around compliance and certification expectations. With stronger alignment to measurement standards such as the updated IEC 61000-4-30 framework, buyers are placing greater weight on traceable accuracy, documented test methodologies, and validation support. This raises the bar for manufacturers and creates a differentiation opportunity for those that can pair hardware performance with credible compliance narratives and after-sales calibration services.
Taken together, these challenges are transforming the market from a relatively transactional instrument segment into a more service-conscious, standards-driven domain. For decision-makers, the practical implication is that procurement and investment choices are increasingly evaluated over multi-year horizons, where accuracy, integration readiness, and ongoing support matter as much as the initial unit cost.
Key Drivers of Market Change
Several forces are converging to shape the next wave of demand and product development. Understanding them is essential for manufacturers positioning their portfolios, investors assessing sector resilience, and procurement teams separating tactical purchases from strategic monitoring investments.
Technology Innovation and Measurement Precision
Measurement precision and feature density are becoming central competitive axes. Recent product introductions demonstrate a clear move toward Class A accuracy, enhanced waveform capture, and broader parameter coverage in more compact form factors. One example is the launch of the PQ-Box ONE, a single-phase Class A mobile analyzer designed for fast socket-level measurements and rapid commissioning tasks. Its emphasis on reduced installation time and IEC 61000-4-30 compliance reflects a broader industry push to make high-accuracy measurement more accessible in low-voltage environments and field-deployed scenarios. Alongside such portable products, stationary and permanently installed systems are increasingly incorporating waveform capture, statistical analysis, and ITIC curve visualization, enabling operators to evaluate both instantaneous disturbances and cumulative stress on equipment.
The significance of these developments extends beyond instrument specifications. Higher-resolution measurement creates richer datasets, which in turn support root-cause diagnostics, maintenance scheduling, and grid-edge visibility. In industrial use cases, this is already visible in field deployments where waveform-level data is used to isolate voltage dip sources and link electrical disturbances to motor or pump performance issues. The commercial opportunity lies in converting raw measurement capability into actionable insight, either through onboard analytics, companion software, or integrated service offerings.
Policy, Standards, and Regulatory Alignment
Standards are acting as both a compliance requirement and a catalyst for product refresh cycles. The publication of the fourth edition of IEC 61000-4-30 has updated the methods for measuring and interpreting power quality parameters in 50 Hz and 60 Hz AC systems, including guidance on transducers and measurement consistency. For manufacturers, alignment with these definitions is increasingly non-negotiable for customers operating in regulated environments or seeking to compare results across sites and time periods. For buyers, standardized measurement frameworks simplify benchmarking, reduce ambiguity in vendor evaluations, and strengthen the case for repeatable monitoring programs.
This regulatory rhythm also influences purchasing timing. As standards evolve, organizations often re-evaluate existing instrumentation, calibration processes, and data interpretation practices. That dynamic can stimulate replacement demand, particularly where older devices cannot meet updated accuracy classes or cannot support the parameter sets now regarded as baseline. The strategic implication is that standards activity should be treated as an indicator of near-term procurement momentum, not merely as a technical reference.
Demand-Side Shifts in Utilities, Industry, and Commercial Operations
End-user behavior is changing as electrical systems become more distributed and more sensitive to disturbance. In electric power enterprises, continuous monitoring is increasingly viewed as a grid reliability tool rather than an optional testing activity, especially where renewable integration and bidirectional power flows make network behavior harder to predict. In industrial enterprises, power quality management is being tied more directly to production continuity, asset longevity, and maintenance optimization. Operations teams are seeking instrumentation that can identify the electrical conditions associated with premature equipment wear, process interruptions, and energy waste. A broader set of applications—including commercial facilities, data-centric environments, and specialized deployments—further broadens the addressable demand, though these segments often have different priorities around portability, permanent installation, and integration with existing building or site management systems.
What unites these demand-side shifts is a growing willingness to treat power quality as an operational variable rather than a peripheral concern. That mindset shift expands the role of analyzers from measurement devices to decision-support tools, reinforcing demand for products that can interface with broader monitoring ecosystems and deliver usable outputs for engineers, maintenance teams, and facility managers.
Supply Chain and Cost Structure Considerations
Cost and supply dynamics continue to influence both product design and purchasing behavior. Manufacturers are balancing the need for advanced sensing, connectivity, and software support against the reality of component availability, production complexity, and competitive pricing pressure. At the same time, buyers are increasingly attentive to total cost of ownership, especially where monitoring programs span multiple sites or require calibration, training, and periodic replacement. This environment favors companies that can streamline deployment, reduce installation friction, and offer predictable support models. It also rewards designs that can cover multiple use cases without excessive customization, because scalability and repeatability are becoming as important as peak technical performance.
The broader commercial effect is a market in which efficiency of deployment and reliability of support can differentiate even when hardware specifications appear broadly similar. For strategic planners, this means that product roadmaps should account not only for measurement performance but also for the operational friction that determines whether a device is widely adopted across sites and repeated use cases.
Competitive Landscape and Leading Strategies
The competitive field includes established measurement specialists, diversified electrical equipment providers, and regional players with strong positioning in specific application segments. Entries range from companies with broad portable and stationary portfolios to those emphasizing modular architectures, high-frequency harmonic and supra-harmonic measurement, and dedicated commissioning or field-diagnostic tools. The presence of calibration and test-set providers further underscores the importance of validation and compliance as part of the broader market ecosystem.
Several strategic patterns are emerging among leading participants. One is portfolio breadth combined with compliance credibility. Companies with strong three-phase and stationary offerings often pair Class A measurement with energy measurement and long-standing references in power and energy applications. This approach appeals to buyers seeking a single vendor relationship for multiple measurement contexts and wanting instruments that can support both spot checks and longer-duration logging. Another pattern is modular flexibility and extended frequency coverage. Some manufacturers differentiate through multi-system, multi-voltage, and modular designs that can adapt to varied installation environments and measurement needs, including measurement beyond traditional harmonic ranges. This flexibility is particularly relevant in settings where load characteristics are changing rapidly or where a single device must serve multiple analytical purposes. A third pattern is focused specialization for field deployment and fast commissioning. Compact single-phase Class A devices designed for rapid socket-level measurement and low-voltage network tasks address a distinct workflow: quick verification, troubleshooting, and commissioning without extensive setup overhead. This niche is strategically important because it lowers the barrier to high-accuracy measurement in routine operational contexts.
A fourth pattern is the integration of monitoring with broader asset and distribution management goals. Permanent installed meters with waveform capture, ITIC curve display, and statistical analysis are increasingly aligned with low-voltage distribution oversight and continuous asset monitoring. In parallel, advanced grid-edge diagnostic capabilities—such as environmental sensor integration, multi-load monitoring, and high-precision waveform capture—are expanding the role of analyzers into more networked, data-rich applications. Finally, calibration and verification specialists contribute to the ecosystem by supporting measurement confidence and repeatability, reinforcing the idea that accuracy is not only a device attribute but also a process attribute.
PW Consulting Automotive & Machinery Research Center
The market structure suggests both consolidation dynamics and continued differentiation. Larger, multi-product players are well positioned to capture demand across portable, stationary, and integrated monitoring use cases, especially where global support, broad documentation, and compliance narratives matter. At the same time, specialized entrants remain relevant where users need targeted performance, faster deployment, or distinctive measurement features. The likely evolution is not a simple winnowing of competitors but a sorting of offerings by use case, with customers choosing devices based on whether their priority is rapid field verification, permanent monitoring, modular industrial coverage, or compliance-led benchmarking. This sorting creates room for multiple successful strategies, provided each is clearly matched to a defensible end-user need.
Water Quality Analyzer Market
For competitive strategy, the key question is no longer whether a product measures power quality accurately, but how comprehensively it supports the full workflow: deployment speed, measurement consistency, data usability, calibration confidence, and integration into operational decision-making. Participants that can articulate and deliver on that full workflow are likely to capture stronger positions than those competing on specifications alone.
Forward Outlook: Strategic Trends Through 2032
The next several years are likely to be defined by three interlocking trends, each with distinct commercial implications.
Toward Always-On Measurement and Data-Driven Operations
Permanent and semi-permanent monitoring is expected to gain further traction as organizations seek to understand electrical behavior continuously rather than episodically. This trend will favor instruments and systems that can operate reliably in installed environments, deliver consistent data streams, and support long-term trend analysis. The commercial opportunity lies in bundling measurement hardware with dashboards, alarm logic, and service models that convert continuous data into maintenance planning, compliance reporting, and asset risk management. The uncertainty here is organizational readiness: many sites still lack the processes and staffing to absorb continuous data, so adoption may be uneven and heavily dependent on vendor support and system integration.
Standards-Driven Refreshes and Accuracy as a Market Filter
As measurement standards continue to evolve, accuracy and repeatability will increasingly function as market filters rather than optional enhancements. Devices aligned with updated measurement definitions and supported by clear calibration and verification pathways will have an advantage in regulated and multi-site deployments. The commercial opportunity is a replacement and upgrade cycle tied to standards adoption, alongside growing demand for documentation and testing support that helps customers demonstrate compliance. The risk is that standards-driven upgrades can concentrate spending among buyers with the strongest compliance mandates, leaving price-sensitive segments slower to refresh.
Application Expansion in Grid-Edge and Industrial Contexts
Power quality instrumentation is likely to broaden beyond traditional utility and large industrial contexts into more diverse grid-edge and industrial micro-environment applications. The ability to capture waveform-level data, correlate electrical disturbances with equipment performance, and integrate environmental or load sensors will make analyzers more useful in commissioning, troubleshooting, and performance optimization. This opens opportunities for deployment in mining operations, manufacturing lines, commercial sites, and distributed energy settings where the cost of undetected disturbances is high. The uncertainty lies in the variability of use cases: each application may require different form factors, parameter sets, and integration needs, making it harder for any single solution to dominate across all contexts.
Strategic Implications for Decision-Makers
Different roles within the market face different priorities, but all benefit from treating power quality instrumentation as a strategic enabler rather than a commodity purchase.
For manufacturers, the priority is to align product roadmaps with the practical workflows of field engineers, maintenance teams, and compliance managers. That means investing not only in measurement performance but also in deployment simplicity, calibration support, software usability, and clear alignment with recognized measurement definitions. Companies that can demonstrate repeatable accuracy and reduce the operational friction of measurement will be better positioned to win multi-site and recurring procurement decisions. It is also worth recognizing that differentiation may come from how well a product supports a specific use case, such as rapid commissioning, permanent low-voltage monitoring, or industrial waveform diagnostics, rather than from attempting to be uniformly superior across all scenarios.
Worldwide 5G Analyzer Market
For investors, the market offers a profile of steady growth with multiple value-creation pathways. The 5.2 percent CAGR through 2032 suggests durable demand, but the real differentiation is likely to come from companies that can capture recurring value through calibration services, software, monitoring ecosystems, or use-case-specific product lines. Evaluation should pay attention to standards alignment, support infrastructure, and the ability to convert hardware sales into longer-term customer relationships. The risk to monitor is market fragmentation, where too many narrowly targeted products compete without clear operational advantages, and where pricing pressure limits margin expansion.
For procurement and operations leaders, the strategic task is to define monitoring objectives before selecting instrumentation. Permanent monitoring, portable verification, and compliance benchmarking have different requirements, and the best device choice depends on the intended decision workflow. Procurement teams should prioritize traceable accuracy, compatibility with existing data and maintenance processes, and the availability of calibration and support over time. Where multiple sites are involved, standardization on measurement methods and reporting formats can reduce internal complexity and improve comparability. In industrial settings, it is especially valuable to connect measurement choices to specific outcomes, such as reducing downtime, identifying disturbance sources, or supporting predictive maintenance.
Across all of these roles, the value of detailed segmentation data, competitive benchmarking, and scenario-based planning is substantial. Market-level figures provide direction, but the operational decisions that determine success are usually made at a more granular level: by region, by deployment type, by compliance requirement, and by end-user workflow. Decision-makers who have access to more detailed breakdowns and customized analysis can better anticipate replacement cycles, prioritize product features, and align procurement with the standards and use cases that matter most to their organizations.
The strategic signal from the market is clear: power quality analysis is becoming a foundational input to reliable operations, compliance confidence, and asset performance management. Organizations that treat it as such—by choosing instrumentation with the right accuracy, workflow fit, and support model—will be better placed to manage the electrical complexity that defines the next phase of industrial and grid operations. For those seeking a deeper, data-backed view of segmentation, competitive positioning, and regional or application-level dynamics, a comprehensive research report can provide the level of detail needed to translate these trends into concrete investment, product, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Power Quality Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Blood Collection Tubes Market: Why the 7.2% CAGR Trajectory Changes Everything
By pmarketresearch, 2026-09-21
Beyond the Vacuum: Strategic Trajectories and Commercial Opportunities in the Blood Collection Tubes Market
The blood collection tube market has reached an inflection point where steady growth intersects with intensified regulatory scrutiny and evolving clinical demands. Revenue across the sector climbed from approximately 163.15 million in 2020 to an estimated 215.0 million in 2025, with the trajectory projected to reach 344.8 million by 2032. The forward compound annual growth rate stands at 7.2 percent, signaling sustained expansion rather than a temporary surge. This growth is not merely a function of volume; it reflects a structural shift in how samples are collected, stabilized, and managed within diagnostic and therapeutic workflows.
Despite the upward curve, the market faces a set of challenges that will define competitive positioning in the coming years. First, the margin between clinical performance and compliance risk is narrowing. Devices that appear functionally identical on paper can diverge sharply in quality control maturity, and recent enforcement actions have made that divergence costly. Second, the preanalytical phase remains the largest source of variability in laboratory results, yet standardization across collection environments, operator training, and tube chemistry continues to lag. Third, regional demand is accelerating in emerging markets while mature markets are squeezing efficiency, creating a dual mandate: scale without sacrificing quality, and differentiation without over-engineering.
These dynamics reshape how leaders should think about opportunity. The market is no longer a commodity contest around evacuation mechanics and additive chemistry alone; it is a reliability contest around consistency, traceability, and regulatory readiness. Growth will favor organizations that can convert operational discipline into commercial advantage, particularly as procurement teams, regulators, and clinical stakeholders align around sample integrity as a non-negotiable baseline.
The Core Growth Engines Redefining Value Creation
Three forces are driving the market’s trajectory and redefining where value is created. The first is technological innovation in tube chemistry, materials, and workflow integration. Advances in separator gel formulations, anticoagulant precision, and material biocompatibility are enabling tighter control over sample stability, shorter turnaround windows, and broader utility across diagnostic and therapeutic applications. At the same time, manufacturers are pushing toward designs that simplify handling and reduce user variability. The impact extends beyond product features: better chemistry and materials reduce preanalytical error, which in turn improves laboratory throughput and trust in downstream results.
The second force is a tightening regulatory and quality environment. Blood collection tubes are classified under FDA product code JKA and require 510(k) clearance for marketing, while evacuated, sterile, single-use devices must comply with biocompatibility and purity standards for metal additives. The regulatory perimeter has become more visible in day-to-day operations. Quality system expectations, corrective action rigor, and supplier management requirements now directly influence market access and brand credibility. This matters commercially because compliance is increasingly a differentiator rather than a baseline checkbox.
PW Consulting
The third force is demand-side evolution across the care continuum. Diagnostic testing continues to be the dominant pull, but the broader application base is diversifying as point-of-care needs, monitoring workflows, and specialized therapeutic programs increase the volume and variety of sample collection. Clinicians and laboratorians are prioritizing tubes that support consistent results across multiple settings, while procurement groups are weighing total cost of ownership rather than unit price alone. That shift favors suppliers that can demonstrate reliability, reduce error-related rework, and integrate smoothly into existing collection protocols.
A fourth force, often underappreciated, is the changing cost and supply chain structure. Materials, manufacturing consistency, and supplier oversight all affect margin and resilience. Because tubes are single-use devices with stringent purity and performance expectations, disruptions in raw material sourcing or component quality can cascade quickly into clinical risk and commercial exposure. Firms that invest in transparent supplier governance, robust design controls, and predictable production quality are better positioned to protect both margins and reputation.
Recent market events illustrate how these forces interact in practice. Regulatory enforcement actions in 2025 highlighted how quickly quality and documentation gaps can alter market access. A warning letter related to capillary blood collection tubes underscored the consequences of quality system and reporting deficiencies, resulting in an import alert that restricted U.S. entry. At the same time, Class 2 recalls involving labeling and gel separator omissions, as well as a recall tied to supplier management weaknesses, demonstrated that even established product lines can face disruption when change control, supplier oversight, or corrective action processes fall short. These episodes reinforce a central insight: product capability must be matched by quality system maturity if growth is to remain durable.
Vacuum Blood Collection Tube Market
The practical implication is clear. Innovation that improves sample handling or broadens application fit will gain traction only when paired with disciplined execution. For commercial leaders, that means measuring success not just by launch velocity or feature checklists, but by the reliability of the entire collection-to-result chain and the strength of the quality infrastructure supporting it.
Competitive Positioning and the Evolving Landscape
The market remains moderately concentrated, with the top three players accounting for roughly 24.6 percent of revenue and the top five reaching about 26.2 percent. That level of concentration indicates room for both consolidation and targeted disruption, depending on how companies leverage scale, portfolio breadth, and compliance capability. Several established players illustrate the strategic paths now shaping the field.
One large global player has built its position around a widely recognized evacuated tube system and a broad portfolio covering hematology, coagulation, chemistry, and therapeutic drug monitoring. Its emphasis on sample quality and analytical accuracy reflects a long-standing bet that consistency and clinical trust can sustain share even in a competitive category. The strategic message is straightforward: broad application coverage and a consistent quality narrative can create stickiness across laboratory and hospital channels.
A second major manufacturer has focused heavily on preanalytical safety and blood collection systems, including serum separator, gel separator, and safety-oriented models. This company’s trajectory suggests that differentiation through workflow safety, ease of use, and preanalytical reliability can be as valuable as chemistry alone. In practice, that positioning aligns well with institutions seeking to reduce handling risk and standardize collection across varied clinical environments.
A third contender has expanded through high-quality materials and chemistries, with a strong presence across Asia and global distribution for venous and capillary collection. Its strategy shows how geographic reach and material performance can combine to serve both mature and growth markets, especially where distribution logistics and product reliability are critical to winning procurement confidence.
A fourth established producer has emphasized flexibility and variety in its tube systems, aiming to suit different clinical environments and preanalytical applications. That flexibility-oriented approach reflects a pragmatic reality: no single tube design is optimal for every setting, and institutions often value suppliers that can adapt to local workflows without sacrificing standardization.
Taken together, these profiles point to a landscape that is neither fully consolidated nor fragmented beyond remedy. The more relevant trend is strategic differentiation around reliability, safety, workflow fit, and regulatory readiness. Leadership is increasingly defined by the ability to integrate product performance with quality systems, supplier governance, and clear documentation. This matters because recent recall and warning letter events have raised the cost of quality lapses, making execution a competitive weapon rather than a back-office function.
The market is also likely to see continued evolution in how value is captured. Some organizations will pursue integration through portfolio expansion and channel strength, using breadth to reduce customer switching and strengthen institutional relationships. Others will pursue niche positioning around specific applications, safety features, or regional distribution advantages. New entrants will face a steeper path if they cannot match the combination of product performance, regulatory compliance, and operational consistency, but they may still find openings where incumbents underinvest in particular applications, emerging-market distribution, or preanalytical innovation.
For decision-makers, the most useful conclusion is that competitive advantage in this market is becoming multidimensional. Price still matters, but it is no longer sufficient. Buyers and regulators are increasingly attentive to sample integrity, labeling control, supplier oversight, and documented quality processes. Companies that align their product roadmap with these expectations will be better positioned to defend share and expand into higher-value segments.
Where the Market Is Heading: Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape the market’s direction and the opportunities within it.
The first trend is the elevation of preanalytical quality from a technical concern to a commercial priority. As laboratories and health systems face continuing pressure to reduce errors, improve turnaround, and standardize results, tubes that support consistent fill, stable separation, and predictable anticoagulant performance will gain preference. This trend opens opportunities for suppliers that can document performance consistency, provide clear handling guidance, and design for reduced operator variability. It also raises the risk for products with ambiguous change control, weak supplier controls, or inconsistent labeling, since those weaknesses are increasingly exposed through regulatory and customer scrutiny.
The second trend is regulatory and quality maturity becoming a market access gate. With established classification and clearance expectations, as well as heightened attention to quality systems, medical device reporting, and supplier management, compliance will increasingly determine which products can enter or remain in key channels. The commercial opportunity lies in building trust through transparent documentation, repeatable production quality, and rapid corrective action capability. The risk is that companies treating compliance as a discretionary layer will face disruption not only from enforcement but also from procurement teams that now screen for quality readiness before volume commitments.
The third trend is demand diversification across diagnostic, therapeutic, and broader application needs, with regional growth uneven but meaningful. Mature markets will likely reward efficiency, integration, and reliability, while faster-growing regions will reward distribution strength, adaptability, and cost-conscious quality. This split creates an opportunity for companies to tailor portfolios by region and application rather than relying on a single global template. It also introduces uncertainty: demand patterns can shift with testing protocols, care delivery models, and procurement reforms, meaning that long-term plans should remain modular rather than overly rigid.
These trends converge on a shared commercial theme: the winners will be those who can pair product performance with operational credibility. For suppliers, that means investing in the full system around the tube, including design controls, supplier management, labeling discipline, and post-market responsiveness. For buyers, it means weighting total reliability more heavily than sticker price. For investors, it means looking beyond top-line growth to assess the quality infrastructure and regulatory posture that sustain it.
Blood Tubing Set Market
Actionable Priorities for Different Decision-Makers
Manufacturers and product leaders should treat quality system strength as a core product attribute. Prioritize design controls, change control discipline, supplier management, and labeling accuracy with the same rigor applied to chemistry and materials. Where possible, align innovation with preanalytical reliability and usability improvements that reduce variability in the field. Build post-market surveillance and corrective action processes that can detect and resolve issues quickly, because responsiveness now directly affects market access and customer confidence. In parallel, develop portfolio strategies that recognize regional and application differences instead of assuming one configuration will fit all channels.
Investors and strategic financiers should focus on execution risk as much as growth potential. Top-line projections and category tailwinds are important, but the durability of those projections depends on regulatory readiness, quality culture, and supply chain discipline. Diligence should examine not only product features and distribution reach, but also documentation practices, supplier oversight, recall history, and the organization’s ability to manage change control without compromising consistency. Companies that can demonstrate both growth ambition and operational maturity are better positioned to convert market expansion into sustainable returns.
Procurement and supply chain leaders should move beyond unit cost comparisons and evaluate the total reliability of collection systems. That includes consistency of fill and separator performance, clarity of labeling, supplier governance, and the supplier’s track record in managing quality issues. Where possible, establish criteria that reward transparency, documented process control, and corrective action responsiveness. The goal is to reduce downstream laboratory variability and operational risk, not simply to minimize purchase price. Contracts and supplier reviews should reflect this broader value lens, especially as regulatory and clinical stakeholders place greater weight on sample integrity.
Across all three audiences, the common thread is the need for current, granular intelligence. Broad category trends provide direction, but the decisions that matter most—portfolio prioritization, channel strategy, supplier selection, diligence framing, and risk mitigation—require detailed segmentation, regional nuance, and updated regulatory and competitive context. Leaders who incorporate that depth into planning can act faster and with more confidence than those relying on aggregate narratives alone.
For teams seeking a sharper view of where value is accumulating and where risk is building, the full research report offers a closer look at segmentation dynamics, regional demand patterns, and company-level positioning. It is designed to support practical decisions in portfolio strategy, procurement, and investment diligence by pairing market context with detailed, actionable breakdowns. The deeper the intelligence, the more precisely a business can align its next move with the market’s actual shape rather than its anticipated shape.
For detailed analysis of this topic, please visit the official page: Blood Collection Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Nail Gun Market 2026: How Asia Pacific Dynamics Drive 6.4% Growth Through 2032
By pmarketresearch, 2026-09-21
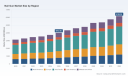
The Nail Gun Market at a Crossroads: Strategic Trends and Commercial Opportunities
The nail gun market has entered a phase of steady expansion, driven by sustained construction activity, evolving building codes, and a gradual shift toward more efficient fastening technologies. Between 2020 and 2025, the market grew from approximately 3.1 billion USD to over 4.0 billion USD, reflecting a compound annual growth rate of 6.4 percent through 2032. Forecasts project the market to cross 6.1 billion USD by the end of the decade, with the strongest acceleration expected in the latter half of the forecast period. This trajectory signals more than incremental growth; it points to a market where technology adoption, regulatory shifts, and regional demand patterns are reshaping competitive dynamics and creating distinct commercial opportunities for manufacturers, distributors, and investors.
Despite the positive outlook, the industry faces structural pressures that will determine which players capture value in the coming years. Labor markets in developed economies remain tight, pushing contractors and builders toward tools that reduce fatigue, improve precision, and lower training overhead. At the same time, safety expectations are rising, forcing manufacturers to reconsider trigger designs, ergonomics, and operator feedback systems. Supply chain volatility and raw material cost fluctuations continue to compress margins, particularly for price-sensitive segments. These factors converge into a market that rewards innovation with clear operational and safety benefits, while penalizing undifferentiated product lines that rely primarily on volume.
PW Consulting Automotive & Machinery Research Center
Market Context: Growth Trajectory and Structural Pressures
The market's expansion from 2020 through 2025 was supported by resilient residential activity, steady commercial retrofitting, and incremental industrial maintenance spending. The forecast horizon extends this momentum, with growth rates expected to remain robust as new building projects, renovation cycles, and infrastructure maintenance sustain demand for fastening tools. The size of the addressable market, combined with a moderate but consistent CAGR, suggests a mature yet still evolving landscape where share gains are increasingly tied to product differentiation and market segmentation rather than broad category growth alone.
Several structural challenges define the current inflection point. First, safety and ergonomics are moving from compliance considerations to competitive differentiators. Operators and site managers are increasingly aware of injury risks associated with certain trigger mechanisms, and this awareness is influencing purchasing decisions, rental channel requirements, and insurer expectations. Second, regional demand patterns are diverging. Some markets are driven by large-scale residential construction and do-it-yourself activity, while others depend more on commercial renovation and industrial maintenance. This divergence complicates product positioning and requires localized go-to-market strategies rather than one-size-fits-all portfolios. Third, cost control remains a persistent concern. Fluctuations in metals, plastics, and energy inputs, alongside freight and logistics variability, mean that margin management depends on disciplined sourcing, product rationalization, and selective premiumization.
Heat Guns Market
Safety Expectations as a Market Force
Safety is no longer a secondary feature; it is a purchasing criterion. Industry guidance has long emphasized that certain multi-shot contact triggers carry higher injury risk than single-shot sequential triggers, and this distinction continues to shape operator training, site protocols, and equipment selection. Employers are also expected to provide appropriate personal protective equipment, including hardhats, impact-rated eye protection, and hearing protection, reinforcing the broader culture of site safety. For nail gun manufacturers, this environment creates an opportunity to design products that reduce inadvertent firing, improve control, and simplify training. For distributors and rental houses, it creates a reason to prioritize inventory that aligns with safer operating practices and reduces liability exposure.
Regional Divergence and Segment Realities
The market is not moving uniformly. In some regions, residential and household applications dominate volume, supported by repair, remodeling, and light construction activity. In others, commercial and industrial use cases carry more weight, where higher-duty cycles, repeated fastening tasks, and site-scale procurement decisions matter more. This split means that product strategies must account for different usage intensities, user profiles, and purchasing centers. A tool designed primarily for intermittent residential use may not satisfy the durability expectations of commercial contractors, while a heavy-duty industrial-focused lineup may overshoot the needs of household users. Aligning product architecture with real-world usage patterns is becoming a critical success factor.
Key Drivers Reshaping the Market
Several forces are accelerating change in the nail gun market. Technology, regulation, demand behavior, and supply chain economics each contribute to a landscape where incremental improvements can unlock meaningful share shifts.
Technology Innovation and Performance Gains
Innovation is concentrated in three areas: trigger and control systems, power source efficiency, and ergonomics. Manufacturers are refining sequential and selective trigger mechanisms to reduce accidental actuation while preserving workflow speed. Battery-platform consolidation is improving runtime consistency and simplifying cross-product compatibility for electric tools. Pneumatic systems continue to benefit from improved airflow efficiency, lighter housings, and more reliable coupler designs. These advancements matter because they translate directly into operator comfort, reduced rework, and lower total cost of ownership. Products that combine safety, speed, and maintainability are increasingly favored in competitive bids and rental fleets.
Policy, Standards, and Site Compliance
Regulatory and standards-driven expectations are raising the bar for tool selection. Training requirements for powder-actuated tools remain an important compliance consideration, and site safety programs increasingly emphasize protective equipment and trigger-awareness protocols. While regulation does not uniformly dictate product design, it influences procurement criteria, rental channel requirements, and insurer preferences. Companies that proactively align product documentation, training support, and safety features with prevailing site expectations gain an advantage in markets where compliance and risk management are closely monitored.
Demand-Side Shifts in User Behavior
User behavior is changing on two fronts. Professional contractors are seeking tools that reduce fatigue during extended use, support faster setup, and integrate cleanly with existing battery or pneumatic ecosystems. In parallel, household and residential users are looking for easier-to-handle tools with straightforward operation and acceptable durability for periodic projects. This dual demand profile encourages manufacturers to segment portfolios more deliberately and to communicate use-case suitability clearly. It also encourages channel strategies that distinguish between professional distribution, retail, and rental pathways, each of which values different combinations of performance, support, and price.
Supply Chain and Cost Structure Dynamics
Cost structure remains a pivotal factor. Material input variability, component availability, and logistics costs can erode margins if not managed through design efficiency and sourcing strategy. Companies that standardize components across product families, optimize material usage, and balance manufacturing locations are better positioned to protect pricing flexibility. At the same time, selective premiumization allows firms to capture higher value in segments where performance, safety, and brand trust justify a stronger price position. The broader theme is not simply cost reduction, but cost intelligence: understanding which features drive willingness to pay and which inputs can be optimized without eroding perceived value.
Competitive Landscape and Leading Strategies
The market features a broad set of established players spanning Europe, North America, Asia, and Japan, with companies competing across pneumatic, combustion-powered, and electric categories. The presence of large industrial tool brands alongside specialized manufacturers creates a competitive environment where portfolio breadth, channel strength, and innovation cadence all matter. Market concentration indicates that a relatively compact group of leading firms holds a substantial share of revenue, but plenty of room remains for differentiated players to win in specific segments or geographies.
Leading manufacturers tend to pursue one or more of the following strategic positions. Some emphasize platform ecosystems, particularly in electric tools, where battery compatibility and cross-tool interoperability reduce customer friction and increase lifetime value. Others focus on specialized fastening solutions, emphasizing trigger safety, durability, and application-specific performance. A third group competes through distribution strength and rental channel relationships, using service reliability and product availability to build preference among contractors and site managers. Regional manufacturers often leverage cost-efficient production, responsive catalog updates, and strong presence in local trade channels to sustain momentum.
Recent product activity illustrates how competition is playing out in practice. In mid-2025, Makita U.S.A., Inc. released new 18V LXT 21° and 30° framing nailers, reinforcing the strategic importance of battery-platform familiarity and application-specific framing tools within the electric segment. In the pneumatic space, Everwin Pneumatic Corp. showcased latest pneumatic nail guns and staplers at the International Hardware Expo Taiwan in late 2025, and later announced participation in EISENWARENMESSE 2026 in Cologne, signaling continued emphasis on trade visibility, product refreshes, and regional outreach. These moves reflect a broader pattern: competitive advantage is increasingly built through clear product positioning, channel presence, and the ability to demonstrate performance in the applications that matter most to buyers.
Worldwide Combustion Powered Nail Gun Market
Market Structure Evolution
The competitive landscape is evolving along several directions. Consolidation remains possible where scale advantages in procurement, distribution, and brand investment are significant. At the same time, segmentation is deepening, with electric, pneumatic, and combustion-powered tools serving different usage profiles and price points. New entrants and regional specialists can gain traction by targeting overlooked applications, offering compelling value in rental or distribution channels, or introducing design improvements that address specific safety and ergonomic pain points. The likely outcome is a layered market in which a few broad-platform leaders compete alongside focused specialists, each winning through distinct combinations of performance, reach, and cost discipline.
Forward Outlook: Trends and Commercial Opportunities
Looking ahead three to five years, three trends appear particularly consequential.
- Safety-led product design will become a stronger share driver. As site protocols, training expectations, and insurer awareness continue to evolve, tools that reduce inadvertent firing, improve operator control, and simplify setup will gain preference. This creates an opportunity for manufacturers to differentiate through trigger technology, ergonomics, and supportive training materials, and for distributors to curate safer product assortments.
- Electric platform adoption will keep expanding where workflow integration matters. Battery-powered nailers benefit from compatibility with broader tool ecosystems, reduced onsite constraints, and easier handling for certain applications. Growth will not be uniform, but in segments where convenience, noise considerations, and site logistics favor electric tools, adoption should keep rising. The commercial opportunity lies in platform coherence, reliable runtime, and application-specific nailer designs.
- Regional specialization will reward localized strategies. Because demand drivers differ by region and by application intensity, companies that tailor product mixes, channel partnerships, and service support to local realities are better positioned to grow share. This includes aligning product strength with the dominant use cases in a market, whether residential, commercial, or industrial.
These trends create tangible opportunities. Manufacturers can pursue targeted innovation that combines safety and usability without overcomplicating the product line. Distributors and rental operators can differentiate through curated inventory, training support, and equipment that aligns with safer site practices. Investors can look for companies with clear platform strategies, disciplined cost structures, and evidence of momentum in application segments with durable demand. At the same time, uncertainty remains. Construction cycles can shift with interest rates and macroeconomic conditions. Raw material and logistics costs may continue to fluctuate. Safety and training expectations may evolve in ways that change procurement preferences more quickly than product development cycles. Managing these uncertainties requires scenario awareness and the ability to adjust product, pricing, and channel decisions as conditions change.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to connect product development to the applications and safety expectations that most influence buying decisions. That means evaluating where trigger design, ergonomics, and platform compatibility create real differentiation, and where component standardization can protect margins without weakening value perception. It also means deciding where to compete on premium performance versus value-oriented volume, and ensuring that channel support, training, and documentation reinforce the chosen positioning.
For investors, the focus should be on identifying companies with credible innovation roadmaps, resilient cost structures, and clear exposure to the demand segments most likely to sustain growth. Portfolio coherence in electric tools, strength in professional distribution or rental channels, and evidence of effective regional execution are useful indicators of competitive durability. Equally important is monitoring how firms respond to safety-driven purchasing shifts, since these can alter share dynamics even when overall market growth remains steady.
For procurement and construction organizations, the practical imperative is to align tool selection with site safety goals, operator training capacity, and total cost of ownership rather than sticker price alone. Evaluating trigger types, handling characteristics, maintenance requirements, and compatibility with existing ecosystems can reduce operational friction and improve consistency across crews. In rental and fleet contexts, prioritizing equipment that supports safer use and easier training can lower risk while maintaining productivity.
The nail gun market is large enough to reward focused strategy and dynamic enough to shift share quickly when safety, technology, and regional demand align. Understanding where these forces are heading, and what they mean for product portfolios, channel choices, and procurement standards, is essential for capturing value in the next phase of growth. For decision-makers seeking deeper segmentation data, company-level benchmarking, and tailored scenario planning, the full PW Consulting research report provides the level of detail needed to translate these trends into specific commercial choices.
For detailed analysis of this topic, please visit the official page: Nail Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Niacin (Vitamin B3) Market: Why Asia Pacific’s 6.65% CAGR Reshapes Global Growth
By pmarketresearch, 2026-09-21
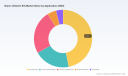
Strategic Shifts in the Niacin (Vitamin B3) Market: Navigating Growth, Consolidation, and Sustainable Innovation
The global niacin market has solidified its position as a high-growth specialty ingredient segment, driven by expanding applications across nutrition, pharmaceuticals, and personal care. With revenues reaching approximately 676 million USD in 2025 and a projected compound annual growth rate of 6.65 percent through 2032, the market is on a clear upward trajectory. This expansion is not merely a function of population growth or traditional feed demand; it reflects deeper structural changes in how formulators approach metabolic health, skin barrier function, and clean-label supply chains. For executives and investors, the niacin space presents a compelling balance of established demand drivers and emerging differentiation fronts. Understanding where value is created—and where margin pressure or regulatory friction will intensify—requires moving beyond headline figures and examining the interplay of feedstock dynamics, certification barriers, and strategic repositioning by leading suppliers.
Market Snapshot and the Anatomy of Growth
Growth in the niacin market has been steady rather than explosive, with annual revenue climbing from roughly 490 million USD in 2020 to the mid-670 million USD range by 2025. The forward curve points toward a market approaching 1.06 billion USD by 2032, indicating that incremental demand will be supported by both volume expansion and value migration toward higher-specification grades. The trajectory suggests that the next phase of growth will be less about raw volume and more about grade premiumization, application diversification, and regional production realignment.
Several structural characteristics define the current market environment. Demand is distributed across multiple end-use channels, with animal nutrition and human nutraceuticals representing the largest demand pools, while personal care and pharmaceutical applications serve as higher-margin, specification-driven niches. On the supply side, synthetic production dominates, reflecting the maturity of chemical synthesis routes and the scalability of established manufacturing hubs. Form factor preferences continue to favor dry formats for bulk handling and feed integration, while liquid variants maintain a differentiated role in formulation flexibility and specific cosmetic or pharmaceutical workflows.
PW Consulting
The market also exhibits a high degree of supplier concentration, with a small group of large-scale producers accounting for the majority of global capacity. This concentration has historically provided pricing stability and supply reliability for bulk grades, but it also concentrates risk around feedstock access, regulatory compliance pathways, and geopolitical exposure. As downstream customers increasingly demand traceability, sustainability credentials, and grade-specific documentation, the competitive frontier is shifting from pure cost leadership to capability-based differentiation.
Key Challenges and Inflection Points
Despite a favorable demand outlook, the niacin market faces several concurrent challenges that will shape investment decisions and sourcing strategies over the next few years.
- Feedstock volatility and petrochemical linkage. The primary precursor for niacinamide synthesis is tightly coupled to petrochemical market cycles. Price oscillations in this feedstock create margin variability for manufacturers and complicate long-term contract planning for buyers. Because a significant share of precursor supply and intermediate processing is concentrated in specific geographic regions, geopolitical disruptions or trade policy shifts can transmit quickly through the value chain.
- Regulatory and certification complexity. Pharmaceutical and nutraceutical grades require rigorous documentation, including pharmacopeial compliance and bioequivalence records at multiple production nodes. Regulatory frameworks across major markets mandate certifications that extend lead times and increase the cost of qualification. For animal feed and food applications, certifications related to quality management, food safety, and religious or dietary compliance have become baseline expectations rather than differentiators.
- Inventory cycles and qualification friction. In high-specification segments, extended lead times are increasingly tied to documentation and approval workflows rather than pure physical production constraints. Buyers in pharmaceutical and personal care channels must manage longer qualification cycles, which affects inventory planning and responsiveness to demand spikes. This dynamic rewards suppliers with integrated quality systems and penalizes those reliant on fragmented compliance processes.
These challenges do not undermine the market outlook; instead, they redefine where competitive advantage is earned. Suppliers that reduce qualification friction, stabilize feedstock exposure, and embed sustainability credentials into their operating models are better positioned to capture premium demand and defend margins.
Worldwide Cosmetic Grade Niacinamide Market
Core Growth Drivers: Innovation, Regulation, Demand, and Supply Chain Realignment
The niacin market is being reshaped by four interlocking drivers that will determine the pace and composition of growth through the late 2020s and into the early 2030s.
Technological Innovation and Specification Premiumization
Innovation in niacin and niacinamide is increasingly oriented around purity, sustainability, and application-specific performance rather than generic volume expansion. Bio-based feedstock approaches are gaining traction as formulators seek to align ingredient sourcing with broader environmental goals and consumer-facing sustainability narratives. In personal care, advanced niacinamide formats are being positioned around skin barrier support, redness reduction, and tolerability, which creates room for premium positioning when supported by robust documentation and stability data.
On the manufacturing side, process optimization and high-purity production capabilities are becoming important differentiators. Suppliers that can deliver consistent pharmaceutical-grade material with minimal batch variability and streamlined certification documentation are capturing share in higher-margin segments. This shift is especially pronounced where downstream brands are under pressure to reduce time-to-market while meeting stringent quality standards.
Policy, Regulation, and Certification as Commercial Gateways
Regulatory expectations are no longer a back-office compliance issue; they are a commercial gateway that shapes market access and supplier selection. Pharmaceutical and nutraceutical channels require pharmacopeial-grade compliance and documentation that supports bioequivalence and traceability. Food and feed channels increasingly treat certifications related to quality systems, food safety, and dietary compliance as standard procurement prerequisites. In practice, certification readiness determines which suppliers can enter tenders, which can scale with key accounts, and which can respond quickly to reformulation requests.
This environment favors scaled producers with established regulatory infrastructure, but it also creates opportunities for specialized manufacturers that can offer targeted grade solutions with faster qualification cycles. For buyers, the implication is clear: supplier selection should weigh not only unit cost but also the speed and reliability of documentation, the breadth of certification coverage, and the supplier’s ability to support regional regulatory variations.
Demand-Side Evolution: Nutrition, Personal Care, and Formulation Trends
Demand is being reshaped by two broad consumer and industry trends. In human nutrition, interest in metabolic health, B-vitamin supplementation, and functional ingredients continues to support steady demand for niacin in dietary supplement formats. In personal care, niacinamide remains a cornerstone ingredient for skin health formulations, and the rise of sensitive-skin positioning, barrier-focused skincare, and clean-label ingredient narratives creates additional demand pull. These channels are not growing at the same rate, but together they diversify the demand base and reduce dependence on any single end-use cycle.
Animal nutrition remains a large demand anchor, particularly where feed fortification and livestock productivity considerations support consistent volume. However, growth in this channel is more cyclical and cost-sensitive than in nutraceuticals or personal care. The differing demand characteristics across channels mean that successful suppliers often need segment-specific commercial models rather than a single one-size-fits-all approach.
Supply Chain Structure and Cost Dynamics
The supply chain for niacin is characterized by concentrated precursor access, regional production hubs, and grade-specific logistics requirements. Feedstock price movements translate directly into cost variability, and because precursor sourcing is exposed to petrochemical cycles and regional supply risks, manufacturers must manage both price and availability simultaneously. The result is that contract structures, inventory positioning, and multi-source strategies matter as much as production capacity.
At the same time, grade differentiation is reshaping logistics and lead times. Pharmaceutical-grade workflows require more rigorous documentation at each production node, which extends qualifying lead times and influences inventory strategy. For buyers, this creates a trade-off between responsiveness and compliance assurance. Suppliers that can compress qualification timelines without compromising documentation integrity will gain commercial leverage, particularly in fast-moving personal care and supplement channels.
Nicotinamide (NAA) (aka Niacinamide) Market
Competitive Landscape: Concentration, Differentiation, and Strategic Realignment
The niacin market is defined by a concentrated group of large-scale producers alongside specialized manufacturers that compete on grade, purity, and application focus. The leading players span chemical synthesis expertise, life sciences orientation, and contract manufacturing capabilities, creating a diversified competitive field in which companies differentiate through distinct value propositions rather than through undifferentiated capacity alone.
Several patterns stand out in the current landscape.
- Large-scale producers anchor bulk and feed demand. Established chemical synthesis capabilities support high-volume supply for animal nutrition, food, and industrial applications. These players compete on scale, reliability, and cost management, while increasingly adding grade-specific offerings to capture higher-margin demand.
- Life sciences and pharmaceutical-focused suppliers emphasize documentation and purity. Companies with strong pharmaceutical-grade infrastructure position around compliance, quality systems, and consistency. Their differentiation lies in the ability to meet rigorous pharmacopeial expectations and support bioequivalence and traceability requirements.
- Specialized and mid-sized manufacturers target niche grades and faster qualification. Some suppliers focus on personal care, supplement, or cosmetic-grade solutions, emphasizing flexibility, application support, and certification breadth. This positioning can be attractive to brands that value responsiveness and tailored technical support.
- Regional production dynamics create both opportunity and risk. With significant manufacturing capacity concentrated in specific regions, supply chain resilience depends on multi-source strategies, regional qualification readiness, and the ability to manage feedstock and logistics exposure.
The competitive field is also evolving through strategic realignment. Recent portfolio moves in the broader nutrition and health ingredients space illustrate how companies are reshaping their exposure to vitamin portfolios and adjacent businesses. Divestitures of animal nutrition and health-related assets by major players reflect a broader trend toward portfolio simplification and focus on higher-value or strategically aligned segments. At the same time, product-level innovation continues to expand the differentiation frontier. The introduction of bio-based niacinamide lines for personal care, combined with visible presence at regional industry events, signals that sustainability and application-specific messaging are becoming central to commercial positioning in cosmetics and skin health.
Taken together, these dynamics suggest a market that will continue to consolidate around capable, well-documented suppliers while also opening space for differentiated players in higher-specification niches. New entrants will face meaningful barriers in pharmaceutical and nutraceutical grades due to certification requirements, but may find more accessible pathways in cosmetic or supplement segments if they can demonstrate quality, consistency, and clear application value.
Looking Ahead: Three Trends Shaping the Next 3–5 Years
Based on current demand patterns, regulatory direction, and supplier behavior, three trends are likely to define the niacin market over the next several years.
Trend 1: Premium-grade migration and application diversification
As downstream brands seek differentiation, demand will increasingly shift toward grades that offer stronger documentation, consistent purity, and specific performance profiles. Pharmaceutical and nutraceutical channels will continue to reward suppliers with robust quality systems, while personal care and supplement segments will place greater emphasis on tolerability, stability, and sustainability narratives. This premium-grade migration creates margin opportunities for suppliers that can support higher specification requirements without sacrificing reliability.
Trend 2: Sustainable sourcing and bio-based differentiation
Sustainability credentials will move from baseline expectations to active commercial differentiators, especially in personal care and consumer-facing nutrition. Bio-based feedstock approaches, traceability improvements, and certifications aligned with dietary and religious requirements will matter more as brands use ingredient sourcing as part of their broader market positioning. Suppliers that can substantiate sustainability claims with verifiable processes and certifications will be better placed to capture preference-driven demand.
Trend 3: Supply chain resilience and qualification speed as core capabilities
Feedstock volatility, regional concentration, and documentation-heavy qualification workflows will make supply chain resilience a central competitive factor. Buyers will increasingly value suppliers that can offer predictable lead times, transparent compliance documentation, and flexible sourcing strategies. The ability to shorten qualification cycles while maintaining regulatory integrity will become a meaningful advantage, particularly for accounts that need to scale quickly or support reformulation programs.
These trends also carry risks. Feedstock price swings can compress margins if not managed through contract design or hedging approaches. Regulatory divergence across regions may increase complexity for globally distributed portfolios. And sustainability claims will face greater scrutiny, meaning that unsubstantiated positioning can create reputational and commercial exposure. The winners will be those who treat resilience, documentation, and credible sustainability as integrated capabilities rather than isolated initiatives.
Strategic Implications for Decision Makers
For executives, planners, and investors, the niacin market offers a mix of stable demand foundations and evolving differentiation opportunities. The strategic question is less whether the market will grow and more how to position for the kind of growth that will arrive.
For manufacturers and suppliers
Focus on grade-specific capability building. Invest in documentation infrastructure, pharmacopeial compliance readiness, and certification breadth that aligns with the channels you intend to serve. If sustainability is part of your positioning, ensure it is backed by verifiable processes and certification coverage that buyers can audit. Consider how feedstock exposure is managed in contracts and inventory planning, because cost variability will remain a persistent margin factor. Where possible, build segment-specific commercial models that match the purchasing logic of feed, supplements, personal care, and pharmaceutical customers rather than applying a single pricing and service model across all channels.
For investors
Evaluate exposure through the lens of grade mix and channel concentration. Businesses with stronger positioning in pharmaceutical, nutraceutical, or premium personal care segments may offer better margin resilience than those dependent primarily on cost-sensitive bulk channels. Pay attention to supply chain structure, regulatory readiness, and the credibility of sustainability claims, since these factors increasingly determine scalability and procurement preference. Also watch portfolio realignment activity across the larger nutrition and health ingredients space, as divestitures and refocusing can reshape competitive dynamics and create both acquisition and partnership opportunities.
For procurement and sourcing leaders
Treat supplier selection as a multi-dimensional decision. Unit price should be weighed against qualification speed, certification coverage, documentation reliability, and supply continuity. For pharmaceutical and supplement-grade procurement, the cost of delayed qualification or compliance gaps can exceed the apparent savings from lower-priced sources. Diversify sourcing where feasible to reduce exposure to feedstock and regional concentration risks, and align inventory strategies with the lead-time realities of higher-specification grades. Request clear evidence of certification status, traceability, and process consistency, especially when sustainability or grade claims are part of the sourcing decision.
Where deeper intelligence adds value
The niacin market is large enough to support multiple successful strategies, but the right strategy depends on segment-specific data that goes beyond aggregate growth figures. Detailed segmentation, regional demand intensity, grade-level margin structures, feedstock cost sensitivities, and competitor-specific capability maps can materially change sourcing, investment, and product roadmap decisions. For teams that need to move from broad market confidence to precise execution planning, deeper segmentation data and tailored competitive assessments provide the granularity required to prioritize capacity, negotiate contracts, and shape formulation strategies with greater confidence.
For detailed analysis of this topic, please visit the official page: Niacin (Vitamin B3) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Brown Sugar Market 2026: Beyond the 7.4% CAGR Growth Trajectory and Strategic Shifts
By pmarketresearch, 2026-09-21
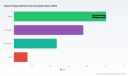
Strategic Trends and Commercial Opportunities in the Brown Sugar Market
The global brown sugar market demonstrates a trajectory of steady, quality-driven expansion as the industry transitions from a commoditized sweetener segment into a differentiated value category. In 2025, the market reached an estimated 2.39 billion USD in revenue, reflecting compounded growth from 1.88 billion USD in 2020. Looking ahead through 2032, the sector is projected to expand at a seven-point-four percent compound annual growth rate, crossing the 3.9 billion USD threshold by the end of the forecast window. This growth is not uniform across all categories; it is increasingly shaped by application-specific demand, regional consumption patterns, and a measurable shift toward premium and specialty formats. The market remains structurally fragmented, with the top three participants accounting for roughly twenty-five percent of total revenue and the top five capturing just under twenty-nine percent. Such concentration levels indicate that while scale advantages exist, competitive advantage is increasingly determined by formulation precision, sourcing reliability, and the ability to align product attributes with downstream manufacturing requirements.
Current Landscape and Critical Inflection Points
The brown sugar market sits at a notable intersection where volume growth, functional utility, and premiumization intersect. Historical volatility during the early part of the decade stabilized into a more predictable expansion curve, but that pattern is now being tested by a combination of supply-side constraints and demand-side recalibration. Industry participants are navigating an environment where raw material availability, trade policy adjustments, and formulation requirements intersect more frequently than in prior cycles.
Several structural challenges are actively shaping strategic decision-making. First, the sector faces ongoing sensitivity to input cost dynamics and sourcing stability. Sugar production is heavily influenced by seasonal conditions, regional cropping outcomes, and trade mechanism adjustments, all of which introduce variability into cost planning for industrial buyers. This is especially relevant for manufacturers that rely on consistent moisture content, molasses balance, and particle size to maintain product consistency across bakery lines, beverage formulations, and confectionery production.
Second, the market is confronting a divergence between traditional bulk demand and rising expectations for specification-grade, specialty-format products. While staple applications continue to drive baseline consumption, growth is increasingly tied to categories that require precise flavor profiles, clean-label alignment, and traceability. Suppliers that operate primarily in undifferentiated bulk segments are finding it harder to protect margins, whereas those capable of delivering consistent functional attributes and certification-backed positioning are capturing stronger downstream preference.
Third, regulatory and trade frameworks continue to shape regional accessibility and pricing stability. In major consuming markets, import mechanisms and domestic support arrangements influence the flow of raw and refined inputs, affecting both cost structures and supply planning. Companies that depend on cross-border sourcing must account for quota allocations, suspension agreements, and the periodic recalibration of trade thresholds, all of which can alter short-term availability and long-term procurement strategy.
Key Drivers Shaping Market Evolution
The expansion trajectory of the brown sugar market is not simply a function of population growth or broad sweetener consumption. It is being reshaped by a set of interacting drivers that reward operational precision and market-specific positioning.
One significant driver is the evolution of product formulation and process control. Producers are increasingly differentiating through controlled molasses integration, crystallization techniques, and variant consistency across light and dark formats. This matters because downstream users in bakery, beverage, and confectionery applications depend on predictable color, moisture, and flavor intensity to maintain line efficiency and product quality. Suppliers that invest in tighter specification control and flexible packaging formats are better positioned to serve industrial customers who require repeatability across batches and reduced rework.
A second driver is the alignment of product positioning with consumer-facing expectations around ingredient transparency. Clean-label considerations, non-genetically modified verification, vegan compatibility, and Kosher certification are no longer peripheral claims; they are becoming operational procurement criteria for food manufacturers that must meet retail and foodservice requirements. Offerings that combine domestically grown cane or beet inputs with verified certification structures are gaining traction, particularly in applications where label simplicity and ingredient sourcing are closely scrutinized.
A third driver is the structural shift in application demand. Brown sugar continues to hold relevance in bakery environments, where its moisture contribution and flavor depth support product differentiation in breads, pastries, and specialty doughs. At the same time, beverage and confectionery uses are expanding as formulators seek cost-effective yet distinctively flavored sweetening options. Dairy and adjacent applications remain smaller in relative scale but are becoming more relevant in flavored products and functional blends, where brown sugar’s organoleptic properties can be leveraged without requiring major formulation redesign.
A fourth driver is the interaction between supply-side planning and policy environment. Recent market intelligence from agricultural outlook agencies emphasizes continuing supply and utilization monitoring for U.S. sugar markets based on broader agricultural supply and demand estimates. At the same time, tariff-rate quota allocations for raw sugar are set annually to align with multilateral trade commitments, and domestic support mechanisms operate alongside suspension agreements with Mexico to stabilize input flows. These mechanisms do not merely influence pricing; they shape procurement timing, contract design, and the relative attractiveness of domestic versus imported sourcing strategies.
Taken together, these drivers create a market where competitive advantage is increasingly less about volume alone and more about the ability to deliver specification reliability, certification alignment, and procurement predictability. Companies that treat brown sugar as a functional ingredient rather than a passive sweetener are capturing stronger value capture across industrial and retail channels.
Competitive Landscape and Leading Strategies
The competitive environment in the brown sugar market is characterized by a mix of large diversified sugar producers, regional specialty manufacturers, and brand-focused refiners. No single entity dominates the category, and the moderately fragmented structure creates room for differentiation through crop origin, processing technology, and downstream application focus.
Among the most strategically visible participants, several patterns stand out. One major global food and agriculture company emphasizes a pure cane sugar base combined with molasses, supported by non-GMO verification, vegan-friendly positioning, and Kosher compliance. Its offering is structured to serve bakery, confectionery, sauce, and canned product production, with both bulk and retail packaging options. This model illustrates a broader competitive logic: pairing supply consistency with certification attributes that downstream food manufacturers can use as procurement assurance.
Another leading European producer focuses on crystalline and soft brown sugar produced by crystallizing beet or cane syrups with caramel syrup. Its dual-format approach enables participation across bakery, biscuit, cereal, sauce, and beverage segments, emphasizing formulation versatility. This flexibility is strategically important for industrial buyers that seek one supplier capable of meeting varied processing requirements without sacrificing specification consistency.
Regional processors also play a meaningful role. A U.S.-based beet sugar producer delivers liquid and brown sugars under a well-known regional brand, targeting industrial, commercial, and retail customers. Its relevance lies in localized sourcing and processing capabilities, which can reduce exposure to certain import-related variables and support steady supply for domestic food manufacturers. A major U.S. cane sugar refiner maintains strong brand recognition through established consumer and foodservice labels, while an Oregon-based cooperative and a Hong Kong-based cane sugar producer extend the competitive map across beet-and-cane portfolios and regional export markets.
In Southern Africa, a mill focused on high-quality VHP brown sugar illustrates how regional production can serve both local consumption and export-adjacent demand, particularly where quality consistency and processing standards are key to maintaining market access. Meanwhile, brand-oriented U.S. offerings in light and dark brown sugar continue to reinforce the importance of format clarity and application-specific naming for foodservice and retail buyers.
Across these participants, several strategic themes emerge. First, differentiation is increasingly achieved through a combination of sourcing origin, certification readiness, and format flexibility rather than price competition alone. Second, leading players are investing in the ability to serve industrial customers with reliable batch consistency and packaging options that match processing environments. Third, brand and label equity remains valuable in retail and foodservice channels, where recognition and compliance attributes streamline purchasing decisions.
The market structure also points to ongoing evolution rather than abrupt consolidation. While scale players benefit from procurement leverage and distribution breadth, smaller or regionally anchored producers can compete by specializing in specific formats, crop-based narratives, or application-focused solutions. New entry remains feasible in niche segments where certification, organic positioning, or regenerative agriculture credentials align with buyer requirements, but scaling such offerings typically depends on supply reliability and cost discipline.
Forward Outlook: Key Trends for the Next Three to Five Years
Looking toward the next several years, the brown sugar market is likely to be defined by three interrelated trends.
The first trend is continued premiumization within a still-substantial bulk baseline. Light and dark variants will remain core, but demand growth will increasingly concentrate in specification-managed products that offer predictable flavor intensity, controlled moisture, and certification support. Manufacturers that can standardize these attributes across batches will gain preference in bakery, confectionery, and beverage environments where formulation integrity is critical. This trend favors suppliers that can combine processing precision with transparent documentation and flexible pack sizes.
The second trend is deeper integration between sourcing strategy and regulatory awareness. Because trade mechanisms, quota allocations, and domestic support arrangements influence input availability and cost planning, procurement teams are likely to place greater emphasis on scenario-based sourcing, multi-origin flexibility, and contract structures that reduce exposure to short-term supply shocks. In practical terms, this means brown sugar procurement will become more strategic and less transactional, with buyers evaluating suppliers not only on price but also on reliability under changing trade conditions.
The third trend is the growing relevance of sustainability-linked sourcing narratives where they can be credibly documented and linked to buyer requirements. Organic certification, regenerative agriculture claims, and non-GMO verification are already present in portions of the market, and their commercial importance is likely to increase as food manufacturers seek to align ingredient sourcing with broader label and corporate expectations. The opportunity here is not simply in claims, but in the ability to provide traceable, repeatable sourcing that can withstand procurement scrutiny.
PW Consulting
These trends create tangible commercial opportunities. Suppliers that invest in specification control, certification readiness, and procurement transparency can capture stronger positioning with industrial buyers. Food manufacturers that align product development with brown sugar’s functional profile can use it as a differentiation lever in bakery and beverage portfolios. Investors and strategic planners can focus on the segments where application growth, certification alignment, and supply reliability intersect, rather than assuming uniform growth across all formats and regions.
At the same time, uncertainty remains. Input availability can shift with seasonal outcomes and trade policy adjustments. Certification and labeling requirements may evolve, affecting the cost and feasibility of certain positioning strategies. In addition, any broadening of tariff-rate quota constraints or changes to suspension agreements could alter the relative cost balance between domestic and imported supply in key markets. Companies that build flexibility into sourcing and product planning will be better positioned to navigate these variables.
Strategic Actions for Decision Makers
For manufacturers and brand owners, the priority is to treat brown sugar as a functional, specification-sensitive ingredient. This means aligning procurement with clear technical requirements for moisture, molasses balance, particle characteristics, and certification needs. Where possible, establish supplier relationships that provide batch consistency documentation and flexible packaging options suited to production environments. For product development teams, brown sugar can be used not only as a sweetener but also as a flavor and texture lever in bakery, beverage, and confectionery applications, provided formulation consistency is safeguarded.
For procurement and supply chain leaders, the emphasis should be on resilience and predictability. Evaluate sourcing options against not only unit cost but also supply reliability under changing trade and quota conditions. Consider multi-origin or mixed-format strategies where applicable, and structure contracts to reduce exposure to short-term input volatility. Maintain visibility into regulatory updates that affect import mechanisms and domestic support arrangements, since these can influence both availability and planning horizons.
Sugar Sphere Market
For investors and strategic planners, the opportunity lies in identifying participants and segments that combine scale, specification control, and credible certification or sourcing narratives. The market is large enough to support diverse models, but long-term outperformance is likely to favor those that can deliver consistent quality, serve industrial requirements efficiently, and adapt to evolving buyer expectations around transparency and sourcing. Monitoring application-side uptake, regional supply dynamics, and trade framework adjustments will be essential for anticipating shifts in competitive positioning.
For all of the above, the value of timely, granular intelligence is clear. Market-level projections provide useful direction, but operational decisions depend on detail: segment-by-segment demand patterns, specification preferences, sourcing constraints, certification adoption, and the cadence of regulatory and trade updates. Detailed reporting that breaks down these layers can support more precise planning, from product roadmap design to supplier selection and investment prioritization.
As the brown sugar market continues its transition toward more differentiated, specification-driven growth, the strategic question is no longer whether the category will expand, but how companies will position themselves to capture value within it. Those that combine process discipline, procurement awareness, and clear alignment with downstream application needs are best placed to convert market growth into durable commercial advantage.
Worldwide Brown Rice Market
For detailed analysis of this topic, please visit the official page: Brown Sugar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Pressure Vessels Market Explores the 4.93% CAGR Growth Path Beyond 2026
By pmarketresearch, 2026-09-21
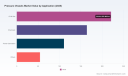
Pressure Vessels Market: Strategic Trends and Commercial Opportunities Through 2032
The global pressure vessels market has entered a phase of disciplined expansion, shaped by infrastructure reinvestment, evolving safety standards, and a gradual shift toward higher-specification equipment. Valued at approximately $422.4 million in 2020, the market reached $550.2 million in 2025 and is projected to grow to $769.0 million by 2032, reflecting a compound annual growth rate of 4.93 percent. This trajectory signals steady demand rather than explosive growth, with value increasingly concentrated in applications that demand tighter tolerances, advanced materials, and rigorous compliance. For executives and investors, the picture is one of a maturing industrial segment where margin differentiation, certification agility, and supply chain resilience matter more than volume alone.
PW Consulting
Market Snapshot and Structural Headwinds
The market’s growth path over the past five years reveals a sector that recovered from pandemic-era disruptions and then settled into a more predictable expansion rhythm. Revenue climbed from $431.72 million in 2021 to $473.83 million in 2022, pushed higher to $508.09 million in 2023, and reached $550.2 million in 2025 as capital spending in key end-use sectors stabilized. Forecasts extending to 2032 indicate a gradual acceleration in later years, with values moving from $578.92 million in 2026 toward $716.08 million in 2030 and $769.0 million by 2032. This pattern suggests that growth will be uneven across cycles, tied closely to project sanctioning timelines, regulatory adoption, and the pace of industrial modernization.
Despite the favorable top-line trajectory, the industry faces a set of structural challenges that will define competitive outcomes over the forecast horizon.
Cost Volatility and Material Sensitivity
Steel and alloy pricing remains the single largest cost variable for pressure vessel manufacturers, with carbon steel accounting for 35 percent to 45 percent of total production cost. This exposure means that margin compression can occur quickly when input prices spike or when contractual pass-through mechanisms lag behind market movements. Companies that rely on fixed-price bidding without hedging or index-linked clauses are particularly vulnerable. The practical implication is that procurement discipline, long-term supplier agreements, and design choices that optimize material usage are becoming strategic levers rather than operational details.
Regulatory Tightening and Compliance Burden
The 2025 ASME Boiler and Pressure Vessel Code (BPVC) Section VIII was published with new additions and enhancements for the design and construction of fired and unfired pressure vessels, becoming mandatory for compliance. Alongside this, the 2025 edition introduces updated rules for flanges and design by analysis, with educational webinars scheduled for March 2026 to explain impacts on pressure vessel design and documentation. On the inspection side, API 510 certification publications took effect for September 2025 through May 2026 exams and September 2026 through May 2027 exams, governing pressure vessel inspector qualifications. Together, these developments raise the bar for documentation, testing, and personnel certification. For manufacturers, the upside is a higher barrier to entry that benefits established, code-certified players; the downside is increased time-to-market and administrative overhead, especially for smaller fabricators.
Project Economics and Demand Cyclicality
Demand for pressure vessels is closely linked to large-project sanctioning in energy, chemicals, and power generation. When capital budgets tighten or project timelines slip, equipment orders can be delayed rather than cancelled, creating lumpy order books and unpredictable cash flow patterns. Companies that diversify across multiple verticals and offer modular or repowering solutions tend to smooth these cycles more effectively. The broader lesson is that dependency on a single sector or project type amplifies exposure to macroeconomic and policy shifts.
Key Drivers Reshaping the Market
Several interlocking forces are pushing the market beyond baseline growth and redefining where value is created.
Technology Innovation and Advanced Fabrication
Additive manufacturing and precision fabrication are gradually expanding the design envelope for high-pressure, high-temperature components. A notable example is SAMSON AG’s November 2025 achievement of CE certification from TÜV SÜD Industrie Service GmbH for its additively manufactured high-pressure valve, Type 3251-AM, enabling full market availability up to DN 100/PN 400. This milestone illustrates how certified additive processes can move from prototyping to commercial deployment, particularly where complex geometries, weight reduction, or rapid iteration offer tangible benefits. For pressure vessel ecosystems, the implication is broader than a single product: qualification pathways are opening for advanced manufacturing methods, and firms that invest early in certification, material validation, and digital design tools can capture premium segments that value performance and lead-time advantages.
Policy and Regulatory Environment
Regulatory frameworks are both a constraint and a catalyst. Mandatory updates to the ASME BPVC and the ongoing API 510 certification cycles increase the compliance burden, but they also reinforce the value of established quality systems and multi-code capabilities. In practice, this tends to favor manufacturers that can navigate multiple codes simultaneously and provide end-to-end documentation support. Regions with active plant safety initiatives, aging infrastructure replacement programs, and stringent inspection regimes are likely to see steadier demand for replacement and upgrade vessels, while newer project markets may prioritize first-time certification and faster delivery. The strategic takeaway is that regulatory competence is becoming a differentiator, not just a compliance checkbox.
Demand-Side Shifts in End-Use Industries
End-use industries are pushing pressure vessel specifications in two directions: higher durability for harsh operating environments and greater flexibility for modular or distributed installations. In oil and gas, chemicals, and power generation, operators are increasingly attentive to lifecycle costs, inspection intervals, and material degradation under elevated pressures and temperatures. This favors vessels designed for easier maintenance, better corrosion resistance, and compatibility with advanced monitoring. At the same time, some applications are shifting toward standardized, repeatable designs that reduce engineering overhead while preserving code compliance. The net effect is a bifurcated demand profile: high-spec custom work remains important, but there is growing value in repeatable platforms that can be deployed quickly across multiple sites.
Supply Chain and Cost Structure Evolution
Because material costs dominate production economics, supply chain strategy is now a core margin lever. Manufacturers are increasingly looking at long-term steel and alloy agreements, localized sourcing to reduce logistics risk, and design-for-manufacturability practices that reduce scrap and machining time. Digital procurement visibility and inventory buffering for critical materials are also gaining traction as ways to protect delivery commitments during volatile periods. Companies that integrate sourcing, design, and production planning more tightly are better positioned to hold margins without sacrificing competitiveness on price.
Competitive Landscape and Leading Strategies
The market is moderately concentrated, with the top three firms holding approximately 32.5 percent of revenue and the top five reaching about 38.2 percent. This level of concentration indicates a landscape where a handful of capable players command meaningful share, but ample room remains for specialized manufacturers, regional fabricators, and system integrators that can differentiate on service, certification breadth, or application expertise.
Strategic Positioning Among Established Players
A review of leading participants shows a clear split between large, multi-code equipment suppliers and focused fabricators that compete on customization, speed, or niche expertise.
- Samuel Pressure Vessel Group operates as an ASME-certified fabricator with emphasis on custom and standard vessels for industrial applications, positioning around flexibility and proven code compliance.
- Modern Welding Company, Inc. specializes in custom fabrication for process, storage, and high-pressure applications, appealing to customers that need tightly specified components and responsive engineering support.
- Larsen & Toubro Limited provides large-scale process plant pressure vessels and equipment for oil & gas, power, and chemical sectors with multi-code certifications, which supports complex, cross-border projects where regulatory diversity matters.
- Doosan Heavy Industries & Construction Co., Ltd. manufactures heavy process equipment including pressure vessels for power generation and petrochemical applications, leveraging scale and integration with broader plant systems.
- Mitsubishi Heavy Industries, Ltd. supplies pressure vessels for energy, nuclear, and industrial high-temperature/high-pressure applications, aligning with sectors that demand rigorous performance and long service life.
- Bharat Heavy Electricals Limited offers pressure vessels and process equipment for power generation, oil & gas, and chemical processing industries, benefiting from strong positioning in large infrastructure programs.
- IHI Corporation fabricates pressure vessels for high-pressure and high-temperature industrial and energy applications, competing on technical capability in demanding operating conditions.
On the specialized and regional side, a second tier of manufacturers competes through precision, filtration integration, and application-specific solutions.
Electric Pressure Cooker Market
- Precision Custom Components, LLC is recognized among top suppliers with a focus on precision fabrication, appealing to customers that prioritize dimensional accuracy and repeatability.
- APEX Engineered Products specializes in engineered pressure vessels and components for industrial and process applications, positioning around tailored engineering rather than commodity supply.
- Industrial Filter Manufacturers, Inc. provides pressure vessel solutions integrated with filtration systems for industrial use, creating value through combined functional packages.
- Buckeye Fabricating Company and Manchester Tank & Equipment are PVMA members with ASME certification, emphasizing industrial and process industry supply as well as equipment provision.
- Quality Steel Corporation produces steel-based pressure vessels for industrial applications, reflecting the importance of material-grade specialization.
- TRIARC Tank, LLC and Worthington Enterprises contribute additional fabrication and manufacturing services within the PVMA member ecosystem, reinforcing the role of accredited fabricators in meeting regional demand.
- Petrosmith Equipment, LP focuses on pressure vessel solutions for oil and gas applications, highlighting the continued relevance of sector-specific expertise.
These profiles reveal a market where competitive advantage is built on a combination of code certification, application knowledge, fabrication precision, and the ability to deliver integrated solutions rather than isolated hardware.
How Leaders Differentiate
Top performers tend to differentiate along four dimensions. First, multi-code certification and documentation capability reduce friction for customers operating across jurisdictions. Second, engineering-led customization enables firms to capture higher-margin work in complex or extreme-service applications. Third, integration with adjacent systems, such as filtration or monitoring, creates more complete offerings that can command stronger customer stickiness. Fourth, supply chain and material management discipline protects margins in an environment where steel and alloy costs remain the dominant variable. Companies that combine several of these strengths are better positioned to weather cycles and defend share.
Structural Evolution of the Landscape
The competitive map is evolving through selective consolidation, specialization, and new entry where certification and engineering capabilities allow. Larger suppliers are well placed to benefit from project scale, multi-code complexity, and global delivery requirements. At the same time, smaller and regional fabricators can thrive by serving localized demand, niche applications, or customers that value shorter lead times and closer collaboration. Additive manufacturing certification, such as the SAMSON AG CE approval, hints at a longer-term opening for new approaches to component production, especially where design complexity or throughput advantages can be validated under recognized codes. The likely outcome is a continued mix of scale players, specialized engineers, and certified fabricators, with differentiation increasingly tied to compliance agility and solution breadth.
Forward-Looking Trends and Commercial Opportunities
Looking ahead three to five years, several trends are likely to shape where growth and margin opportunities emerge.
Stabilization Around Code-Driven Quality and Documentation
With the 2025 ASME BPVC updates and ongoing API 510 certification cycles, the market will place greater weight on design-by-analysis competence, flange rule compliance, and inspector qualifications. This creates opportunities for firms that can offer robust documentation packages, training-aligned inspection support, and design services that reduce rework. Customers will increasingly value partners that can accelerate approvals and minimize compliance risk, which can translate into preference for suppliers with established quality systems and clear traceability.
Premium Segments in High-Temperature, High-Pressure Applications
Demand for vessels that can operate reliably under more severe conditions is expected to remain a focal point, particularly in power generation, energy, and chemical processing. This favors manufacturers with strong high-temperature and high-pressure expertise, advanced material selection, and proven performance records. Commercial opportunities include replacement and upgrade programs for aging assets, as well as new installations where operating envelopes are expanding. Firms that can demonstrate lifecycle value through reduced inspection frequency, better corrosion resistance, or improved durability will have a stronger value proposition than those competing solely on initial price.
Modular, Repeatable Platforms and Integrated Solutions
A countertrend to bespoke engineering is the growing appeal of standardized, modular designs that can be deployed across multiple sites with predictable lead times and lower engineering overhead. This is especially relevant where operators seek to scale capacity without repeating full custom cycles for each unit. Integrated offerings that combine pressure vessels with filtration, instrumentation, or monitoring can also increase project value and simplify procurement for end users. The commercial opportunity lies in building platform-based portfolios that preserve code compliance while improving scalability and delivery consistency.
Pressure Vessel Composite Materials Market
Material Strategy as a Margin Lever
Given that carbon steel represents 35 percent to 45 percent of production cost, material strategy will remain central to profitability. Companies that secure stable sourcing, optimize wall thickness and form factors through better design, and use index-linked contracting where appropriate will be better able to protect margins through input price swings. There is also opportunity in specifying alternative grades or coatings where they extend service life and reduce total cost of ownership, particularly in corrosive or cyclic service environments.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Project sanctioning delays in major end-use sectors can shift demand timing and create uneven order books. Regulatory interpretation and adoption rates may vary by region, affecting how quickly new code provisions translate into procurement requirements. Input cost volatility can compress margins if not managed through sourcing and contract structures. Finally, the pace at which advanced manufacturing methods achieve broad code acceptance and customer confidence will determine whether additive and related approaches expand beyond niche applications in the near term.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to convert compliance and engineering capability into visible commercial advantage. That means investing in multi-code documentation, design-by-analysis proficiency, and qualification pathways for advanced fabrication methods, while protecting margins through disciplined material sourcing and design-for-manufacturability practices. Building platform-based product families can improve delivery predictability and expand addressable volume without diluting the ability to take on custom work where margins are stronger.
For investors, the opportunity set favors companies that combine certification breadth, application expertise, and margin resilience rather than those chasing volume alone. Attention should be paid to firms with diversified end-market exposure, stable sourcing strategies, and the ability to serve high-temperature or high-pressure segments where barriers are higher and value is more defensible. Monitoring how quickly advanced manufacturing certifications translate into commercial adoption will also provide early signals about emerging competitive dynamics.
For procurement and engineering leaders, the focus should be on total lifecycle value and compliance risk reduction. Evaluating suppliers on documentation quality, inspection support, material strategy, and integration capability can reduce project risk and improve long-term performance. Where possible, favoring repeatable platforms with proven code compliance can shorten lead times and simplify multi-site deployment, while reserving custom engineering for applications where operating conditions truly demand it.
For those seeking a deeper dive into segment-level sizing, regional demand patterns, and company-specific positioning, the full research report provides detailed breakdowns and customized recommendations tailored to specific strategic questions.
For detailed analysis of this topic, please visit the official page: Pressure Vessels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
MIM Furnace Market 2026: How 6.7% CAGR and 302.1M Scale Reshape Competition
By pmarketresearch, 2026-09-21
Navigating the Metal Injection Molding Furnace Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global metal injection molding furnace market has entered a sustained expansion phase, driven by the broader adoption of Metal Injection Molding (MIM) for complex, high-volume components. Over the 2020 to 2025 period, the market demonstrated consistent upward momentum, with revenue reaching approximately USD 192.4 million in 2025. This trajectory is expected to continue through the 2026 to 2032 forecast horizon, supported by a projected five-year compound annual growth rate of 6.7 percent. The following years will see incremental but compounding gains, with revenue expected to cross the USD 230 million threshold in the latter half of the decade and approach USD 300 million by 2032.
While the headline growth trajectory is encouraging, the industry is navigating several structural inflection points that will shape competitive outcomes over the next half-decade.
The first challenge stems from the tightening of material standards and end-use certification requirements. The release of the 2025 Edition of the MPIF Standard 35 for Metal Injection Molded Parts has introduced updated specifications for high-performance materials including MIM-CpTi, MIM-Ti-6Al-4V, and MIM-420 HIP'd & HT stainless steel, alongside revised corrosion resistance criteria for MIM-17-4 PH. These updates render prior editions obsolete and raise the bar for furnace process control, thermal uniformity, and debinding precision. Manufacturers operating legacy equipment risk failing inspection benchmarks or incurring costly rework cycles, making furnace modernization a compliance-driven necessity rather than a discretionary upgrade.
A second pressure point lies in the regulatory and trade environment. Section 301 tariff considerations and Department of Defense contract clauses are anticipated to affect sourcing strategies within the sector during the 2024 to 2025 window and beyond. For furnace OEMs and integrated MIM suppliers alike, these dynamics create uncertainty around component sourcing, export markets, and defense-related qualification pathways. Companies with geographically concentrated supply chains or limited dual-sourcing options face elevated exposure, while those with diversified manufacturing footprints and clear compliance roadmaps are positioned to maintain delivery reliability.
The third challenge is tied to the operational tempo of downstream production. As MIM adoption expands among automotive tier suppliers, medical device manufacturers, and electronics producers, furnace operators are being asked to handle longer continuous runs, faster changeovers, and more sensitive alloy grades. This places new demands on thermal stability, atmosphere control, and integration with upstream debinding and downstream sintering workflows. Equipment that cannot match the throughput and repeatability requirements of advanced production cells risks becoming a bottleneck, particularly in high-mix environments where flexibility and consistency must coexist.
Key Drivers of Market Change
Several interrelated forces are shaping the direction of the furnace market, and understanding them is essential for executives evaluating capacity investments, technology roadmaps, and sourcing strategies.
PW Consulting Automotive & Machinery Research Center
Technology Innovation and Process Integration
Thermal processing technology continues to evolve in ways that directly address the productivity and quality demands of modern MIM operations. Advances in catalytic debinding, matched-size transfer between debinding and sintering units, and high-temperature vacuum architectures are reducing cycle times while improving dimensional control and surface integrity. One-step debinding and sintering cycles are gaining traction where process simplification can lower labor intensity and floor-space requirements without sacrificing metallurgical outcomes. Meanwhile, furnaces capable of handling hydrogen atmospheres or offering graphite and all-metal chamber options are broadening the envelope of alloys that can be processed reliably at elevated temperatures. These technical improvements are not incremental refinements; they alter the economics of MIM production by reducing scrap, lowering energy intensity per part, and enabling more aggressive material specifications.
Policy and Regulatory Environment
Standardization and contractual requirements are becoming powerful market forces. The 2025 MPIF Standard 35 update exemplifies how material specifications can ripple through equipment selection, furnace configuration, and quality assurance protocols. In parallel, trade measures and defense-related contract provisions are reshaping procurement behavior, particularly for components destined for aerospace and government applications. This environment favors furnace providers that can validate process capability against updated material benchmarks, document thermal profiles in a traceable manner, and support customers through qualification cycles. It also incentivizes end-users to plan furnace investments with compliance horizons in mind, rather than relying on equipment that may be obsolete relative to tomorrow's inspection criteria.
Demand-Side Behavior and End-Use Applications
Demand for MIM is being reinforced by structural preferences in several end-use sectors. Automotive manufacturers continue to pursue weight reduction, miniaturization, and cost-efficient production of complex components, making MIM attractive for brackets, gears, and structural parts that benefit from high-volume precision forming. In medical devices, the need for biocompatible, small-footprint components with tight tolerances supports steady adoption of MIM for surgical instruments, implants, and device assemblies. Electronics producers also contribute to demand growth by requiring reliable processing of specialty alloys and fine features in components where material performance and consistency are critical. Collectively, these demand signals raise the utilization expectations placed on furnace equipment and increase the premium on systems that can operate continuously with repeatable thermal profiles.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping how furnace OEMs and customers think about sourcing and lifetime value. Fluctuations in raw material availability, energy costs, and logistics complexity are encouraging suppliers to offer configurations that balance performance with operational efficiency. Equipment matched to transfer sizes that smooth the handoff between furnace stages, options for hydrogen atmosphere handling, and modular architectures that enable staged upgrades all contribute to lower total cost of ownership. At the same time, buyers are increasingly evaluating furnace purchases against downstream risk: a more capable furnace that reduces rework, accelerates qualification, and stabilizes output can justify a higher upfront cost when viewed against the broader value chain. This shift is driving a more scrutinizing and value-oriented procurement culture.
Competitive Landscape and Leading Strategies
The furnace market is characterized by a broad set of specialized suppliers, with leading players differentiated by application focus, process capability, and integration philosophy. Market concentration remains moderate, indicating that credible niche players and regional specialists retain meaningful presence alongside global contenders. This structure rewards differentiation, responsiveness, and the ability to translate technical requirements into practical production solutions.
Strategic Positioning and Differentiation
Leading companies are building their reputations by aligning furnace design with specific MIM process stages and end-use requirements. Several themes recur across top-tier offerings:
- Specialization in debinding and sintering workflows that reduce cycle complexity, including one-step debinding/sintering cycles and matched-size transfer options designed for seamless movement between process steps.
- Dedicated MIM furnace lines with configurable thermal and catalytic options, enabling customers to balance throughput, atmosphere control, and alloy compatibility across a range of production scenarios.
- Application-specific architectures that span catalytic debinding, debinding/pre-sintering, and rest debinding/full sintering, giving operators staged control over the most sensitive phases of the process.
- Continuous and batch series optimized for MIM production, with attention to hydrogen atmosphere handling and thermal consistency for high-volume or high-mix operations.
- Vacuum furnace platforms supporting high-temperature sintering with graphite or all-metal chambers, extending the range of alloys and surface outcomes available to MIM producers, particularly for demanding applications.
- Custom solutions tailored to aerospace and other precision-intensive sectors, where qualification depth, chamber integrity, and thermal reliability are paramount.
These strategies reflect a broader competitive logic. Differentiation is less about competing on generic heating capacity and more about demonstrating that a furnace can fit into a tightly controlled MIM workflow, support updated material standards, and provide the repeatability needed to reduce downstream risk. Vendors that articulate clear process links, offer validation support, and adapt equipment to customer-specific transfer and atmosphere requirements are best positioned to capture premiums in progressively demanding segments.
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. First, differentiation is intensifying around process integration and material compatibility. As standards tighten and end-use specifications become more exacting, furnace providers that can map equipment capabilities to updated alloys and certification pathways are gaining a clearer value proposition. Second, regional footprints matter more in an environment where tariffs, defense clauses, and supply continuity concerns can disrupt procurement plans; suppliers with flexible manufacturing and service networks are able to reduce friction for buyers operating across multiple jurisdictions. Third, new entrants and specialist innovators are bringing focused solutions to specific process stages or niche alloy classes, pressuring incumbents to sharpen application engineering and customer support. The result is a market where breadth of portfolio remains valuable, but context-specific expertise, documentation, and responsiveness increasingly determine share in priority segments.
Forward Outlook: Trends for the Next Three to Five Years
Connecting current data with the trajectory of innovation and regulation, several clear trends are likely to shape the furnace market through the early 2030s.
Trend One: Process Consolidation Around Multi-Stage, High-Repeatability Systems
The practical needs of automotive, medical, and electronics manufacturers will continue to favor furnaces that combine operational efficiency with metallurgical fidelity. Expect greater emphasis on systems that support staged debinding and sintering with tight thermal profiles, reduced handoff variability, and validated atmosphere control. For commercial decision-makers, this means equipment evaluations should increasingly center on cycle stability, transfer compatibility, and documented process capability rather than nominal capacity alone. Manufacturers offering such systems will capture a larger share of buyers seeking to scale MIM production without introducing variability.
Metal Injection Molding Materials Market
Trend Two: Compliance-Linked Equipment Upgrades as a Growth Catalyst
Updated material standards and inspection expectations are making furnace modernization a compliance lever. Over the next three to five years, organizations operating equipment that cannot reliably meet revised specifications for newer alloys or enhanced corrosion resistance will face mounting operational and qualification pressure. This dynamic will create a structured demand stream for furnace upgrades, retrofits, and replacements aligned with the latest benchmarks. For investors and capacity planners, the implication is that compliance-driven renewal cycles can provide visibility into demand, especially in sectors where documentation and traceability are non-negotiable.
Sinter HIP Furnace Market
Trend Three: Regionalization and Resilient Supply Architectures
Trade considerations, defense contract clauses, and the general premium on supply continuity are encouraging more regionally aware sourcing and manufacturing strategies. Furnace suppliers and integrated MIM operators alike are likely to favor configurations that reduce exposure to single-region dependencies, including modular designs that support staged investment and service networks that shorten response times. This trend favors organizations that can demonstrate adaptability across regions and maintain qualification readiness without adding complexity. For procurement leaders, the opportunity lies in aligning furnace choices with broader resilience objectives, so that equipment selection reinforces supply chain continuity rather than complicating it.
These trends are not without uncertainty. Shifts in trade policy, changes in end-use demand intensity, and the pace of standard adoption could all alter the timing and magnitude of investment cycles. Equipment that is over-configured for future requirements may leave capital underutilized, while under-invested operations may encounter rework and qualification bottlenecks. Companies that monitor standard updates, track demand signals by end-use, and maintain flexible investment options will be best equipped to navigate this uncertainty.
Strategic Recommendations for Decision-Makers
For executives and teams operating in or adjacent to the MIM furnace market, the following recommendations provide a practical path to aligning strategy with the emerging landscape.
For Furnace Manufacturers and MIM Suppliers
- Align product messaging and engineering support with updated material standards and the process steps that matter most to customers, including debinding precision, thermal uniformity, and atmosphere control for sensitive alloys.
- Strengthen qualification and documentation capabilities so customers can more efficiently meet inspection and contract requirements, particularly in aerospace and defense-adjacent applications.
- Offer configurations that balance throughput with flexibility, enabling customers to handle both high-volume continuity and high-mix changeovers without sacrificing repeatability.
For Investors and Strategic Planners
- Assess the market in terms of compliance-linked renewal cycles and end-use demand intensity, since these factors provide structural visibility into furnace demand over the forecast horizon.
- Prioritize players that can articulate clear process integration value, maintain regional service strength, and demonstrate responsiveness to evolving alloy specifications and certification demands.
- Consider how modular or staged investment models might reduce capital risk while preserving the ability to scale capacity as standards and demand evolve.
For Procurement and Operations Leaders
- Evaluate furnace purchases against downstream risk and lifetime value, weighing the impact of thermal stability, atmosphere handling, and transfer compatibility on rework, qualification speed, and output consistency.
- Incorporate standard updates and contractual requirements into equipment planning early, so that procurement decisions support compliance readiness rather than reacting to it after the fact.
- Map furnace choices to broader supply resilience goals, ensuring that equipment configurations and supplier footprints reinforce continuity across anticipated trade and demand scenarios.
The market is entering a phase where technical precision, compliance alignment, and supply resilience converge to define competitive advantage. Understanding how these forces interact at the equipment level can materially influence cost structures, qualification timelines, and production reliability. For decision-makers seeking deeper segmentation data, regional dynamics, and tailored recommendations aligned to specific end-use requirements or investment horizons, a comprehensive research report is available for further review.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com