

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Nail Gun Market 2026: How Asia Pacific Dynamics Drive 6.4% Growth Through 2032

The Nail Gun Market at a Crossroads: Strategic Trends and Commercial Opportunities
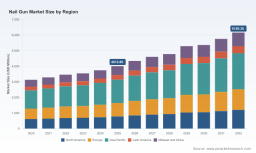
The nail gun market has entered a phase of steady expansion, driven by sustained construction activity, evolving building codes, and a gradual shift toward more efficient fastening technologies. Between 2020 and 2025, the market grew from approximately 3.1 billion USD to over 4.0 billion USD, reflecting a compound annual growth rate of 6.4 percent through 2032. Forecasts project the market to cross 6.1 billion USD by the end of the decade, with the strongest acceleration expected in the latter half of the forecast period. This trajectory signals more than incremental growth; it points to a market where technology adoption, regulatory shifts, and regional demand patterns are reshaping competitive dynamics and creating distinct commercial opportunities for manufacturers, distributors, and investors.
Despite the positive outlook, the industry faces structural pressures that will determine which players capture value in the coming years. Labor markets in developed economies remain tight, pushing contractors and builders toward tools that reduce fatigue, improve precision, and lower training overhead. At the same time, safety expectations are rising, forcing manufacturers to reconsider trigger designs, ergonomics, and operator feedback systems. Supply chain volatility and raw material cost fluctuations continue to compress margins, particularly for price-sensitive segments. These factors converge into a market that rewards innovation with clear operational and safety benefits, while penalizing undifferentiated product lines that rely primarily on volume.
PW Consulting Automotive & Machinery Research Center
Market Context: Growth Trajectory and Structural Pressures
The market's expansion from 2020 through 2025 was supported by resilient residential activity, steady commercial retrofitting, and incremental industrial maintenance spending. The forecast horizon extends this momentum, with growth rates expected to remain robust as new building projects, renovation cycles, and infrastructure maintenance sustain demand for fastening tools. The size of the addressable market, combined with a moderate but consistent CAGR, suggests a mature yet still evolving landscape where share gains are increasingly tied to product differentiation and market segmentation rather than broad category growth alone.
Several structural challenges define the current inflection point. First, safety and ergonomics are moving from compliance considerations to competitive differentiators. Operators and site managers are increasingly aware of injury risks associated with certain trigger mechanisms, and this awareness is influencing purchasing decisions, rental channel requirements, and insurer expectations. Second, regional demand patterns are diverging. Some markets are driven by large-scale residential construction and do-it-yourself activity, while others depend more on commercial renovation and industrial maintenance. This divergence complicates product positioning and requires localized go-to-market strategies rather than one-size-fits-all portfolios. Third, cost control remains a persistent concern. Fluctuations in metals, plastics, and energy inputs, alongside freight and logistics variability, mean that margin management depends on disciplined sourcing, product rationalization, and selective premiumization.
Heat Guns Market
Safety Expectations as a Market Force
Safety is no longer a secondary feature; it is a purchasing criterion. Industry guidance has long emphasized that certain multi-shot contact triggers carry higher injury risk than single-shot sequential triggers, and this distinction continues to shape operator training, site protocols, and equipment selection. Employers are also expected to provide appropriate personal protective equipment, including hardhats, impact-rated eye protection, and hearing protection, reinforcing the broader culture of site safety. For nail gun manufacturers, this environment creates an opportunity to design products that reduce inadvertent firing, improve control, and simplify training. For distributors and rental houses, it creates a reason to prioritize inventory that aligns with safer operating practices and reduces liability exposure.
Regional Divergence and Segment Realities
The market is not moving uniformly. In some regions, residential and household applications dominate volume, supported by repair, remodeling, and light construction activity. In others, commercial and industrial use cases carry more weight, where higher-duty cycles, repeated fastening tasks, and site-scale procurement decisions matter more. This split means that product strategies must account for different usage intensities, user profiles, and purchasing centers. A tool designed primarily for intermittent residential use may not satisfy the durability expectations of commercial contractors, while a heavy-duty industrial-focused lineup may overshoot the needs of household users. Aligning product architecture with real-world usage patterns is becoming a critical success factor.
Key Drivers Reshaping the Market
Several forces are accelerating change in the nail gun market. Technology, regulation, demand behavior, and supply chain economics each contribute to a landscape where incremental improvements can unlock meaningful share shifts.
Technology Innovation and Performance Gains
Innovation is concentrated in three areas: trigger and control systems, power source efficiency, and ergonomics. Manufacturers are refining sequential and selective trigger mechanisms to reduce accidental actuation while preserving workflow speed. Battery-platform consolidation is improving runtime consistency and simplifying cross-product compatibility for electric tools. Pneumatic systems continue to benefit from improved airflow efficiency, lighter housings, and more reliable coupler designs. These advancements matter because they translate directly into operator comfort, reduced rework, and lower total cost of ownership. Products that combine safety, speed, and maintainability are increasingly favored in competitive bids and rental fleets.
Policy, Standards, and Site Compliance
Regulatory and standards-driven expectations are raising the bar for tool selection. Training requirements for powder-actuated tools remain an important compliance consideration, and site safety programs increasingly emphasize protective equipment and trigger-awareness protocols. While regulation does not uniformly dictate product design, it influences procurement criteria, rental channel requirements, and insurer preferences. Companies that proactively align product documentation, training support, and safety features with prevailing site expectations gain an advantage in markets where compliance and risk management are closely monitored.
Demand-Side Shifts in User Behavior
User behavior is changing on two fronts. Professional contractors are seeking tools that reduce fatigue during extended use, support faster setup, and integrate cleanly with existing battery or pneumatic ecosystems. In parallel, household and residential users are looking for easier-to-handle tools with straightforward operation and acceptable durability for periodic projects. This dual demand profile encourages manufacturers to segment portfolios more deliberately and to communicate use-case suitability clearly. It also encourages channel strategies that distinguish between professional distribution, retail, and rental pathways, each of which values different combinations of performance, support, and price.
Supply Chain and Cost Structure Dynamics
Cost structure remains a pivotal factor. Material input variability, component availability, and logistics costs can erode margins if not managed through design efficiency and sourcing strategy. Companies that standardize components across product families, optimize material usage, and balance manufacturing locations are better positioned to protect pricing flexibility. At the same time, selective premiumization allows firms to capture higher value in segments where performance, safety, and brand trust justify a stronger price position. The broader theme is not simply cost reduction, but cost intelligence: understanding which features drive willingness to pay and which inputs can be optimized without eroding perceived value.
Competitive Landscape and Leading Strategies
The market features a broad set of established players spanning Europe, North America, Asia, and Japan, with companies competing across pneumatic, combustion-powered, and electric categories. The presence of large industrial tool brands alongside specialized manufacturers creates a competitive environment where portfolio breadth, channel strength, and innovation cadence all matter. Market concentration indicates that a relatively compact group of leading firms holds a substantial share of revenue, but plenty of room remains for differentiated players to win in specific segments or geographies.
Leading manufacturers tend to pursue one or more of the following strategic positions. Some emphasize platform ecosystems, particularly in electric tools, where battery compatibility and cross-tool interoperability reduce customer friction and increase lifetime value. Others focus on specialized fastening solutions, emphasizing trigger safety, durability, and application-specific performance. A third group competes through distribution strength and rental channel relationships, using service reliability and product availability to build preference among contractors and site managers. Regional manufacturers often leverage cost-efficient production, responsive catalog updates, and strong presence in local trade channels to sustain momentum.
Recent product activity illustrates how competition is playing out in practice. In mid-2025, Makita U.S.A., Inc. released new 18V LXT 21° and 30° framing nailers, reinforcing the strategic importance of battery-platform familiarity and application-specific framing tools within the electric segment. In the pneumatic space, Everwin Pneumatic Corp. showcased latest pneumatic nail guns and staplers at the International Hardware Expo Taiwan in late 2025, and later announced participation in EISENWARENMESSE 2026 in Cologne, signaling continued emphasis on trade visibility, product refreshes, and regional outreach. These moves reflect a broader pattern: competitive advantage is increasingly built through clear product positioning, channel presence, and the ability to demonstrate performance in the applications that matter most to buyers.
Worldwide Combustion Powered Nail Gun Market
Market Structure Evolution
The competitive landscape is evolving along several directions. Consolidation remains possible where scale advantages in procurement, distribution, and brand investment are significant. At the same time, segmentation is deepening, with electric, pneumatic, and combustion-powered tools serving different usage profiles and price points. New entrants and regional specialists can gain traction by targeting overlooked applications, offering compelling value in rental or distribution channels, or introducing design improvements that address specific safety and ergonomic pain points. The likely outcome is a layered market in which a few broad-platform leaders compete alongside focused specialists, each winning through distinct combinations of performance, reach, and cost discipline.
Forward Outlook: Trends and Commercial Opportunities
Looking ahead three to five years, three trends appear particularly consequential.
- Safety-led product design will become a stronger share driver. As site protocols, training expectations, and insurer awareness continue to evolve, tools that reduce inadvertent firing, improve operator control, and simplify setup will gain preference. This creates an opportunity for manufacturers to differentiate through trigger technology, ergonomics, and supportive training materials, and for distributors to curate safer product assortments.
- Electric platform adoption will keep expanding where workflow integration matters. Battery-powered nailers benefit from compatibility with broader tool ecosystems, reduced onsite constraints, and easier handling for certain applications. Growth will not be uniform, but in segments where convenience, noise considerations, and site logistics favor electric tools, adoption should keep rising. The commercial opportunity lies in platform coherence, reliable runtime, and application-specific nailer designs.
- Regional specialization will reward localized strategies. Because demand drivers differ by region and by application intensity, companies that tailor product mixes, channel partnerships, and service support to local realities are better positioned to grow share. This includes aligning product strength with the dominant use cases in a market, whether residential, commercial, or industrial.
These trends create tangible opportunities. Manufacturers can pursue targeted innovation that combines safety and usability without overcomplicating the product line. Distributors and rental operators can differentiate through curated inventory, training support, and equipment that aligns with safer site practices. Investors can look for companies with clear platform strategies, disciplined cost structures, and evidence of momentum in application segments with durable demand. At the same time, uncertainty remains. Construction cycles can shift with interest rates and macroeconomic conditions. Raw material and logistics costs may continue to fluctuate. Safety and training expectations may evolve in ways that change procurement preferences more quickly than product development cycles. Managing these uncertainties requires scenario awareness and the ability to adjust product, pricing, and channel decisions as conditions change.
Strategic Actions for Decision-Makers
For manufacturers, the priority is to connect product development to the applications and safety expectations that most influence buying decisions. That means evaluating where trigger design, ergonomics, and platform compatibility create real differentiation, and where component standardization can protect margins without weakening value perception. It also means deciding where to compete on premium performance versus value-oriented volume, and ensuring that channel support, training, and documentation reinforce the chosen positioning.
For investors, the focus should be on identifying companies with credible innovation roadmaps, resilient cost structures, and clear exposure to the demand segments most likely to sustain growth. Portfolio coherence in electric tools, strength in professional distribution or rental channels, and evidence of effective regional execution are useful indicators of competitive durability. Equally important is monitoring how firms respond to safety-driven purchasing shifts, since these can alter share dynamics even when overall market growth remains steady.
For procurement and construction organizations, the practical imperative is to align tool selection with site safety goals, operator training capacity, and total cost of ownership rather than sticker price alone. Evaluating trigger types, handling characteristics, maintenance requirements, and compatibility with existing ecosystems can reduce operational friction and improve consistency across crews. In rental and fleet contexts, prioritizing equipment that supports safer use and easier training can lower risk while maintaining productivity.
The nail gun market is large enough to reward focused strategy and dynamic enough to shift share quickly when safety, technology, and regional demand align. Understanding where these forces are heading, and what they mean for product portfolios, channel choices, and procurement standards, is essential for capturing value in the next phase of growth. For decision-makers seeking deeper segmentation data, company-level benchmarking, and tailored scenario planning, the full PW Consulting research report provides the level of detail needed to translate these trends into specific commercial choices.
For detailed analysis of this topic, please visit the official page: Nail Gun Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com