

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
MIM Furnace Market 2026: How 6.7% CAGR and 302.1M Scale Reshape Competition

Navigating the Metal Injection Molding Furnace Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The global metal injection molding furnace market has entered a sustained expansion phase, driven by the broader adoption of Metal Injection Molding (MIM) for complex, high-volume components. Over the 2020 to 2025 period, the market demonstrated consistent upward momentum, with revenue reaching approximately USD 192.4 million in 2025. This trajectory is expected to continue through the 2026 to 2032 forecast horizon, supported by a projected five-year compound annual growth rate of 6.7 percent. The following years will see incremental but compounding gains, with revenue expected to cross the USD 230 million threshold in the latter half of the decade and approach USD 300 million by 2032.
While the headline growth trajectory is encouraging, the industry is navigating several structural inflection points that will shape competitive outcomes over the next half-decade.
The first challenge stems from the tightening of material standards and end-use certification requirements. The release of the 2025 Edition of the MPIF Standard 35 for Metal Injection Molded Parts has introduced updated specifications for high-performance materials including MIM-CpTi, MIM-Ti-6Al-4V, and MIM-420 HIP'd & HT stainless steel, alongside revised corrosion resistance criteria for MIM-17-4 PH. These updates render prior editions obsolete and raise the bar for furnace process control, thermal uniformity, and debinding precision. Manufacturers operating legacy equipment risk failing inspection benchmarks or incurring costly rework cycles, making furnace modernization a compliance-driven necessity rather than a discretionary upgrade.
A second pressure point lies in the regulatory and trade environment. Section 301 tariff considerations and Department of Defense contract clauses are anticipated to affect sourcing strategies within the sector during the 2024 to 2025 window and beyond. For furnace OEMs and integrated MIM suppliers alike, these dynamics create uncertainty around component sourcing, export markets, and defense-related qualification pathways. Companies with geographically concentrated supply chains or limited dual-sourcing options face elevated exposure, while those with diversified manufacturing footprints and clear compliance roadmaps are positioned to maintain delivery reliability.
The third challenge is tied to the operational tempo of downstream production. As MIM adoption expands among automotive tier suppliers, medical device manufacturers, and electronics producers, furnace operators are being asked to handle longer continuous runs, faster changeovers, and more sensitive alloy grades. This places new demands on thermal stability, atmosphere control, and integration with upstream debinding and downstream sintering workflows. Equipment that cannot match the throughput and repeatability requirements of advanced production cells risks becoming a bottleneck, particularly in high-mix environments where flexibility and consistency must coexist.
Key Drivers of Market Change
Several interrelated forces are shaping the direction of the furnace market, and understanding them is essential for executives evaluating capacity investments, technology roadmaps, and sourcing strategies.
PW Consulting Automotive & Machinery Research Center
Technology Innovation and Process Integration
Thermal processing technology continues to evolve in ways that directly address the productivity and quality demands of modern MIM operations. Advances in catalytic debinding, matched-size transfer between debinding and sintering units, and high-temperature vacuum architectures are reducing cycle times while improving dimensional control and surface integrity. One-step debinding and sintering cycles are gaining traction where process simplification can lower labor intensity and floor-space requirements without sacrificing metallurgical outcomes. Meanwhile, furnaces capable of handling hydrogen atmospheres or offering graphite and all-metal chamber options are broadening the envelope of alloys that can be processed reliably at elevated temperatures. These technical improvements are not incremental refinements; they alter the economics of MIM production by reducing scrap, lowering energy intensity per part, and enabling more aggressive material specifications.
Policy and Regulatory Environment
Standardization and contractual requirements are becoming powerful market forces. The 2025 MPIF Standard 35 update exemplifies how material specifications can ripple through equipment selection, furnace configuration, and quality assurance protocols. In parallel, trade measures and defense-related contract provisions are reshaping procurement behavior, particularly for components destined for aerospace and government applications. This environment favors furnace providers that can validate process capability against updated material benchmarks, document thermal profiles in a traceable manner, and support customers through qualification cycles. It also incentivizes end-users to plan furnace investments with compliance horizons in mind, rather than relying on equipment that may be obsolete relative to tomorrow's inspection criteria.
Demand-Side Behavior and End-Use Applications
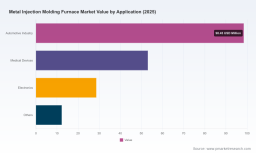
Demand for MIM is being reinforced by structural preferences in several end-use sectors. Automotive manufacturers continue to pursue weight reduction, miniaturization, and cost-efficient production of complex components, making MIM attractive for brackets, gears, and structural parts that benefit from high-volume precision forming. In medical devices, the need for biocompatible, small-footprint components with tight tolerances supports steady adoption of MIM for surgical instruments, implants, and device assemblies. Electronics producers also contribute to demand growth by requiring reliable processing of specialty alloys and fine features in components where material performance and consistency are critical. Collectively, these demand signals raise the utilization expectations placed on furnace equipment and increase the premium on systems that can operate continuously with repeatable thermal profiles.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping how furnace OEMs and customers think about sourcing and lifetime value. Fluctuations in raw material availability, energy costs, and logistics complexity are encouraging suppliers to offer configurations that balance performance with operational efficiency. Equipment matched to transfer sizes that smooth the handoff between furnace stages, options for hydrogen atmosphere handling, and modular architectures that enable staged upgrades all contribute to lower total cost of ownership. At the same time, buyers are increasingly evaluating furnace purchases against downstream risk: a more capable furnace that reduces rework, accelerates qualification, and stabilizes output can justify a higher upfront cost when viewed against the broader value chain. This shift is driving a more scrutinizing and value-oriented procurement culture.
Competitive Landscape and Leading Strategies
The furnace market is characterized by a broad set of specialized suppliers, with leading players differentiated by application focus, process capability, and integration philosophy. Market concentration remains moderate, indicating that credible niche players and regional specialists retain meaningful presence alongside global contenders. This structure rewards differentiation, responsiveness, and the ability to translate technical requirements into practical production solutions.
Strategic Positioning and Differentiation
Leading companies are building their reputations by aligning furnace design with specific MIM process stages and end-use requirements. Several themes recur across top-tier offerings:
- Specialization in debinding and sintering workflows that reduce cycle complexity, including one-step debinding/sintering cycles and matched-size transfer options designed for seamless movement between process steps.
- Dedicated MIM furnace lines with configurable thermal and catalytic options, enabling customers to balance throughput, atmosphere control, and alloy compatibility across a range of production scenarios.
- Application-specific architectures that span catalytic debinding, debinding/pre-sintering, and rest debinding/full sintering, giving operators staged control over the most sensitive phases of the process.
- Continuous and batch series optimized for MIM production, with attention to hydrogen atmosphere handling and thermal consistency for high-volume or high-mix operations.
- Vacuum furnace platforms supporting high-temperature sintering with graphite or all-metal chambers, extending the range of alloys and surface outcomes available to MIM producers, particularly for demanding applications.
- Custom solutions tailored to aerospace and other precision-intensive sectors, where qualification depth, chamber integrity, and thermal reliability are paramount.
These strategies reflect a broader competitive logic. Differentiation is less about competing on generic heating capacity and more about demonstrating that a furnace can fit into a tightly controlled MIM workflow, support updated material standards, and provide the repeatability needed to reduce downstream risk. Vendors that articulate clear process links, offer validation support, and adapt equipment to customer-specific transfer and atmosphere requirements are best positioned to capture premiums in progressively demanding segments.
Market Evolution and Competitive Dynamics
The competitive landscape is evolving along several axes. First, differentiation is intensifying around process integration and material compatibility. As standards tighten and end-use specifications become more exacting, furnace providers that can map equipment capabilities to updated alloys and certification pathways are gaining a clearer value proposition. Second, regional footprints matter more in an environment where tariffs, defense clauses, and supply continuity concerns can disrupt procurement plans; suppliers with flexible manufacturing and service networks are able to reduce friction for buyers operating across multiple jurisdictions. Third, new entrants and specialist innovators are bringing focused solutions to specific process stages or niche alloy classes, pressuring incumbents to sharpen application engineering and customer support. The result is a market where breadth of portfolio remains valuable, but context-specific expertise, documentation, and responsiveness increasingly determine share in priority segments.
Forward Outlook: Trends for the Next Three to Five Years
Connecting current data with the trajectory of innovation and regulation, several clear trends are likely to shape the furnace market through the early 2030s.
Trend One: Process Consolidation Around Multi-Stage, High-Repeatability Systems
The practical needs of automotive, medical, and electronics manufacturers will continue to favor furnaces that combine operational efficiency with metallurgical fidelity. Expect greater emphasis on systems that support staged debinding and sintering with tight thermal profiles, reduced handoff variability, and validated atmosphere control. For commercial decision-makers, this means equipment evaluations should increasingly center on cycle stability, transfer compatibility, and documented process capability rather than nominal capacity alone. Manufacturers offering such systems will capture a larger share of buyers seeking to scale MIM production without introducing variability.
Metal Injection Molding Materials Market
Trend Two: Compliance-Linked Equipment Upgrades as a Growth Catalyst
Updated material standards and inspection expectations are making furnace modernization a compliance lever. Over the next three to five years, organizations operating equipment that cannot reliably meet revised specifications for newer alloys or enhanced corrosion resistance will face mounting operational and qualification pressure. This dynamic will create a structured demand stream for furnace upgrades, retrofits, and replacements aligned with the latest benchmarks. For investors and capacity planners, the implication is that compliance-driven renewal cycles can provide visibility into demand, especially in sectors where documentation and traceability are non-negotiable.
Sinter HIP Furnace Market
Trend Three: Regionalization and Resilient Supply Architectures
Trade considerations, defense contract clauses, and the general premium on supply continuity are encouraging more regionally aware sourcing and manufacturing strategies. Furnace suppliers and integrated MIM operators alike are likely to favor configurations that reduce exposure to single-region dependencies, including modular designs that support staged investment and service networks that shorten response times. This trend favors organizations that can demonstrate adaptability across regions and maintain qualification readiness without adding complexity. For procurement leaders, the opportunity lies in aligning furnace choices with broader resilience objectives, so that equipment selection reinforces supply chain continuity rather than complicating it.
These trends are not without uncertainty. Shifts in trade policy, changes in end-use demand intensity, and the pace of standard adoption could all alter the timing and magnitude of investment cycles. Equipment that is over-configured for future requirements may leave capital underutilized, while under-invested operations may encounter rework and qualification bottlenecks. Companies that monitor standard updates, track demand signals by end-use, and maintain flexible investment options will be best equipped to navigate this uncertainty.
Strategic Recommendations for Decision-Makers
For executives and teams operating in or adjacent to the MIM furnace market, the following recommendations provide a practical path to aligning strategy with the emerging landscape.
For Furnace Manufacturers and MIM Suppliers
- Align product messaging and engineering support with updated material standards and the process steps that matter most to customers, including debinding precision, thermal uniformity, and atmosphere control for sensitive alloys.
- Strengthen qualification and documentation capabilities so customers can more efficiently meet inspection and contract requirements, particularly in aerospace and defense-adjacent applications.
- Offer configurations that balance throughput with flexibility, enabling customers to handle both high-volume continuity and high-mix changeovers without sacrificing repeatability.
For Investors and Strategic Planners
- Assess the market in terms of compliance-linked renewal cycles and end-use demand intensity, since these factors provide structural visibility into furnace demand over the forecast horizon.
- Prioritize players that can articulate clear process integration value, maintain regional service strength, and demonstrate responsiveness to evolving alloy specifications and certification demands.
- Consider how modular or staged investment models might reduce capital risk while preserving the ability to scale capacity as standards and demand evolve.
For Procurement and Operations Leaders
- Evaluate furnace purchases against downstream risk and lifetime value, weighing the impact of thermal stability, atmosphere handling, and transfer compatibility on rework, qualification speed, and output consistency.
- Incorporate standard updates and contractual requirements into equipment planning early, so that procurement decisions support compliance readiness rather than reacting to it after the fact.
- Map furnace choices to broader supply resilience goals, ensuring that equipment configurations and supplier footprints reinforce continuity across anticipated trade and demand scenarios.
The market is entering a phase where technical precision, compliance alignment, and supply resilience converge to define competitive advantage. Understanding how these forces interact at the equipment level can materially influence cost structures, qualification timelines, and production reliability. For decision-makers seeking deeper segmentation data, regional dynamics, and tailored recommendations aligned to specific end-use requirements or investment horizons, a comprehensive research report is available for further review.
For detailed analysis of this topic, please visit the official page: Metal Injection Molding Furnace Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com