

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Power Quality Analyzer Market 2026: Why 5.2% CAGR Redefines Growth

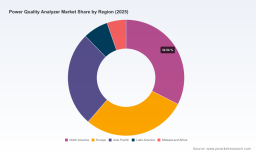
Power Quality Analyzer Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global power quality analyzer market has matured into a critical infrastructure intelligence segment, reflecting a broader shift from reactive fault management to continuous, data-driven electrical system oversight. By 2025, the market generated approximately 279.43 million USD in revenue, building on a consistent expansion trajectory from 216.87 million USD in 2020. Projections indicate that this growth will compound at a 5.2 percent CAGR through 2032, with revenue surpassing 398.84 million USD by the end of the forecast window. This expansion is not merely a function of incremental instrument sales; it signals a structural recalibration in how utilities, industrial operators, and commercial facility managers validate grid compliance, protect sensitive equipment, and underwrite operational resilience. The sector’s evolution is being shaped by tighter measurement standards, the proliferation of distributed energy resources, and a competitive environment where consolidation, specialization, and software-enabled services are redefining value creation.
Market Overview and Core Challenges
The market’s current scale and growth pattern point to a segment that has moved beyond early-adopter experimentation into broad operational necessity. Revenue growth between 2023 and 2025 accelerated modestly, reflecting both post-pandemic capital deployment and an increasing reliance on continuous monitoring rather than episodic testing. As the trajectory extends through 2032, the 5.2 percent CAGR suggests sustained demand, though the rate also implies a market that is gradually maturing and becoming more selective about technology upgrades and replacement cycles.
Several structural challenges are defining the next phase of growth. First, the sector is navigating a transition from periodic, campaign-based measurements to permanent or semi-permanent monitoring architectures. This shift requires new procurement logic, integration planning, and lifecycle management, because stakeholders must weigh the upfront cost of always-on instrumentation against the hidden costs of undetected disturbances, downtime, and compliance risk. Second, measurement complexity is rising faster than many organizations’ analytical capabilities. As power systems incorporate variable renewable generation, EV charging loads, and power-electronics-intensive equipment, the number of relevant disturbance parameters—harmonics, interharmonics, voltage dips, swells, and transient waveform characteristics—continues to expand. Instruments that can capture these parameters accurately are increasingly essential, yet the ability to interpret results, correlate them with asset performance, and act on them remains uneven across end markets. Third, the competitive environment is tightening around compliance and certification expectations. With stronger alignment to measurement standards such as the updated IEC 61000-4-30 framework, buyers are placing greater weight on traceable accuracy, documented test methodologies, and validation support. This raises the bar for manufacturers and creates a differentiation opportunity for those that can pair hardware performance with credible compliance narratives and after-sales calibration services.
Taken together, these challenges are transforming the market from a relatively transactional instrument segment into a more service-conscious, standards-driven domain. For decision-makers, the practical implication is that procurement and investment choices are increasingly evaluated over multi-year horizons, where accuracy, integration readiness, and ongoing support matter as much as the initial unit cost.
Key Drivers of Market Change
Several forces are converging to shape the next wave of demand and product development. Understanding them is essential for manufacturers positioning their portfolios, investors assessing sector resilience, and procurement teams separating tactical purchases from strategic monitoring investments.
Technology Innovation and Measurement Precision
Measurement precision and feature density are becoming central competitive axes. Recent product introductions demonstrate a clear move toward Class A accuracy, enhanced waveform capture, and broader parameter coverage in more compact form factors. One example is the launch of the PQ-Box ONE, a single-phase Class A mobile analyzer designed for fast socket-level measurements and rapid commissioning tasks. Its emphasis on reduced installation time and IEC 61000-4-30 compliance reflects a broader industry push to make high-accuracy measurement more accessible in low-voltage environments and field-deployed scenarios. Alongside such portable products, stationary and permanently installed systems are increasingly incorporating waveform capture, statistical analysis, and ITIC curve visualization, enabling operators to evaluate both instantaneous disturbances and cumulative stress on equipment.
The significance of these developments extends beyond instrument specifications. Higher-resolution measurement creates richer datasets, which in turn support root-cause diagnostics, maintenance scheduling, and grid-edge visibility. In industrial use cases, this is already visible in field deployments where waveform-level data is used to isolate voltage dip sources and link electrical disturbances to motor or pump performance issues. The commercial opportunity lies in converting raw measurement capability into actionable insight, either through onboard analytics, companion software, or integrated service offerings.
Policy, Standards, and Regulatory Alignment
Standards are acting as both a compliance requirement and a catalyst for product refresh cycles. The publication of the fourth edition of IEC 61000-4-30 has updated the methods for measuring and interpreting power quality parameters in 50 Hz and 60 Hz AC systems, including guidance on transducers and measurement consistency. For manufacturers, alignment with these definitions is increasingly non-negotiable for customers operating in regulated environments or seeking to compare results across sites and time periods. For buyers, standardized measurement frameworks simplify benchmarking, reduce ambiguity in vendor evaluations, and strengthen the case for repeatable monitoring programs.
This regulatory rhythm also influences purchasing timing. As standards evolve, organizations often re-evaluate existing instrumentation, calibration processes, and data interpretation practices. That dynamic can stimulate replacement demand, particularly where older devices cannot meet updated accuracy classes or cannot support the parameter sets now regarded as baseline. The strategic implication is that standards activity should be treated as an indicator of near-term procurement momentum, not merely as a technical reference.
Demand-Side Shifts in Utilities, Industry, and Commercial Operations
End-user behavior is changing as electrical systems become more distributed and more sensitive to disturbance. In electric power enterprises, continuous monitoring is increasingly viewed as a grid reliability tool rather than an optional testing activity, especially where renewable integration and bidirectional power flows make network behavior harder to predict. In industrial enterprises, power quality management is being tied more directly to production continuity, asset longevity, and maintenance optimization. Operations teams are seeking instrumentation that can identify the electrical conditions associated with premature equipment wear, process interruptions, and energy waste. A broader set of applications—including commercial facilities, data-centric environments, and specialized deployments—further broadens the addressable demand, though these segments often have different priorities around portability, permanent installation, and integration with existing building or site management systems.
What unites these demand-side shifts is a growing willingness to treat power quality as an operational variable rather than a peripheral concern. That mindset shift expands the role of analyzers from measurement devices to decision-support tools, reinforcing demand for products that can interface with broader monitoring ecosystems and deliver usable outputs for engineers, maintenance teams, and facility managers.
Supply Chain and Cost Structure Considerations
Cost and supply dynamics continue to influence both product design and purchasing behavior. Manufacturers are balancing the need for advanced sensing, connectivity, and software support against the reality of component availability, production complexity, and competitive pricing pressure. At the same time, buyers are increasingly attentive to total cost of ownership, especially where monitoring programs span multiple sites or require calibration, training, and periodic replacement. This environment favors companies that can streamline deployment, reduce installation friction, and offer predictable support models. It also rewards designs that can cover multiple use cases without excessive customization, because scalability and repeatability are becoming as important as peak technical performance.
The broader commercial effect is a market in which efficiency of deployment and reliability of support can differentiate even when hardware specifications appear broadly similar. For strategic planners, this means that product roadmaps should account not only for measurement performance but also for the operational friction that determines whether a device is widely adopted across sites and repeated use cases.
Competitive Landscape and Leading Strategies
The competitive field includes established measurement specialists, diversified electrical equipment providers, and regional players with strong positioning in specific application segments. Entries range from companies with broad portable and stationary portfolios to those emphasizing modular architectures, high-frequency harmonic and supra-harmonic measurement, and dedicated commissioning or field-diagnostic tools. The presence of calibration and test-set providers further underscores the importance of validation and compliance as part of the broader market ecosystem.
Several strategic patterns are emerging among leading participants. One is portfolio breadth combined with compliance credibility. Companies with strong three-phase and stationary offerings often pair Class A measurement with energy measurement and long-standing references in power and energy applications. This approach appeals to buyers seeking a single vendor relationship for multiple measurement contexts and wanting instruments that can support both spot checks and longer-duration logging. Another pattern is modular flexibility and extended frequency coverage. Some manufacturers differentiate through multi-system, multi-voltage, and modular designs that can adapt to varied installation environments and measurement needs, including measurement beyond traditional harmonic ranges. This flexibility is particularly relevant in settings where load characteristics are changing rapidly or where a single device must serve multiple analytical purposes. A third pattern is focused specialization for field deployment and fast commissioning. Compact single-phase Class A devices designed for rapid socket-level measurement and low-voltage network tasks address a distinct workflow: quick verification, troubleshooting, and commissioning without extensive setup overhead. This niche is strategically important because it lowers the barrier to high-accuracy measurement in routine operational contexts.
A fourth pattern is the integration of monitoring with broader asset and distribution management goals. Permanent installed meters with waveform capture, ITIC curve display, and statistical analysis are increasingly aligned with low-voltage distribution oversight and continuous asset monitoring. In parallel, advanced grid-edge diagnostic capabilities—such as environmental sensor integration, multi-load monitoring, and high-precision waveform capture—are expanding the role of analyzers into more networked, data-rich applications. Finally, calibration and verification specialists contribute to the ecosystem by supporting measurement confidence and repeatability, reinforcing the idea that accuracy is not only a device attribute but also a process attribute.
PW Consulting Automotive & Machinery Research Center
The market structure suggests both consolidation dynamics and continued differentiation. Larger, multi-product players are well positioned to capture demand across portable, stationary, and integrated monitoring use cases, especially where global support, broad documentation, and compliance narratives matter. At the same time, specialized entrants remain relevant where users need targeted performance, faster deployment, or distinctive measurement features. The likely evolution is not a simple winnowing of competitors but a sorting of offerings by use case, with customers choosing devices based on whether their priority is rapid field verification, permanent monitoring, modular industrial coverage, or compliance-led benchmarking. This sorting creates room for multiple successful strategies, provided each is clearly matched to a defensible end-user need.
Water Quality Analyzer Market
For competitive strategy, the key question is no longer whether a product measures power quality accurately, but how comprehensively it supports the full workflow: deployment speed, measurement consistency, data usability, calibration confidence, and integration into operational decision-making. Participants that can articulate and deliver on that full workflow are likely to capture stronger positions than those competing on specifications alone.
Forward Outlook: Strategic Trends Through 2032
The next several years are likely to be defined by three interlocking trends, each with distinct commercial implications.
Toward Always-On Measurement and Data-Driven Operations
Permanent and semi-permanent monitoring is expected to gain further traction as organizations seek to understand electrical behavior continuously rather than episodically. This trend will favor instruments and systems that can operate reliably in installed environments, deliver consistent data streams, and support long-term trend analysis. The commercial opportunity lies in bundling measurement hardware with dashboards, alarm logic, and service models that convert continuous data into maintenance planning, compliance reporting, and asset risk management. The uncertainty here is organizational readiness: many sites still lack the processes and staffing to absorb continuous data, so adoption may be uneven and heavily dependent on vendor support and system integration.
Standards-Driven Refreshes and Accuracy as a Market Filter
As measurement standards continue to evolve, accuracy and repeatability will increasingly function as market filters rather than optional enhancements. Devices aligned with updated measurement definitions and supported by clear calibration and verification pathways will have an advantage in regulated and multi-site deployments. The commercial opportunity is a replacement and upgrade cycle tied to standards adoption, alongside growing demand for documentation and testing support that helps customers demonstrate compliance. The risk is that standards-driven upgrades can concentrate spending among buyers with the strongest compliance mandates, leaving price-sensitive segments slower to refresh.
Application Expansion in Grid-Edge and Industrial Contexts
Power quality instrumentation is likely to broaden beyond traditional utility and large industrial contexts into more diverse grid-edge and industrial micro-environment applications. The ability to capture waveform-level data, correlate electrical disturbances with equipment performance, and integrate environmental or load sensors will make analyzers more useful in commissioning, troubleshooting, and performance optimization. This opens opportunities for deployment in mining operations, manufacturing lines, commercial sites, and distributed energy settings where the cost of undetected disturbances is high. The uncertainty lies in the variability of use cases: each application may require different form factors, parameter sets, and integration needs, making it harder for any single solution to dominate across all contexts.
Strategic Implications for Decision-Makers
Different roles within the market face different priorities, but all benefit from treating power quality instrumentation as a strategic enabler rather than a commodity purchase.
For manufacturers, the priority is to align product roadmaps with the practical workflows of field engineers, maintenance teams, and compliance managers. That means investing not only in measurement performance but also in deployment simplicity, calibration support, software usability, and clear alignment with recognized measurement definitions. Companies that can demonstrate repeatable accuracy and reduce the operational friction of measurement will be better positioned to win multi-site and recurring procurement decisions. It is also worth recognizing that differentiation may come from how well a product supports a specific use case, such as rapid commissioning, permanent low-voltage monitoring, or industrial waveform diagnostics, rather than from attempting to be uniformly superior across all scenarios.
Worldwide 5G Analyzer Market
For investors, the market offers a profile of steady growth with multiple value-creation pathways. The 5.2 percent CAGR through 2032 suggests durable demand, but the real differentiation is likely to come from companies that can capture recurring value through calibration services, software, monitoring ecosystems, or use-case-specific product lines. Evaluation should pay attention to standards alignment, support infrastructure, and the ability to convert hardware sales into longer-term customer relationships. The risk to monitor is market fragmentation, where too many narrowly targeted products compete without clear operational advantages, and where pricing pressure limits margin expansion.
For procurement and operations leaders, the strategic task is to define monitoring objectives before selecting instrumentation. Permanent monitoring, portable verification, and compliance benchmarking have different requirements, and the best device choice depends on the intended decision workflow. Procurement teams should prioritize traceable accuracy, compatibility with existing data and maintenance processes, and the availability of calibration and support over time. Where multiple sites are involved, standardization on measurement methods and reporting formats can reduce internal complexity and improve comparability. In industrial settings, it is especially valuable to connect measurement choices to specific outcomes, such as reducing downtime, identifying disturbance sources, or supporting predictive maintenance.
Across all of these roles, the value of detailed segmentation data, competitive benchmarking, and scenario-based planning is substantial. Market-level figures provide direction, but the operational decisions that determine success are usually made at a more granular level: by region, by deployment type, by compliance requirement, and by end-user workflow. Decision-makers who have access to more detailed breakdowns and customized analysis can better anticipate replacement cycles, prioritize product features, and align procurement with the standards and use cases that matter most to their organizations.
The strategic signal from the market is clear: power quality analysis is becoming a foundational input to reliable operations, compliance confidence, and asset performance management. Organizations that treat it as such—by choosing instrumentation with the right accuracy, workflow fit, and support model—will be better placed to manage the electrical complexity that defines the next phase of industrial and grid operations. For those seeking a deeper, data-backed view of segmentation, competitive positioning, and regional or application-level dynamics, a comprehensive research report can provide the level of detail needed to translate these trends into concrete investment, product, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Power Quality Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com