
Blogs
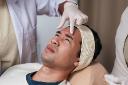
Wrinkles and fine lines are a natural part of aging, but factors such as sun exposure, facial expressions, lifestyle habits, and changes in skin elasticity can make them more noticeable over time. Today, people of different ages are exploring non-surgical aesthetic options to achieve smoother, fresher-looking skin while maintaining their natural facial expressions. Wrinkle smoothing injections in Riyadh can provide a convenient approach for individuals seeking to soften the appearance of dynamic wrinkles and create a more refreshed appearance.
Understanding Wrinkle Smoothing Treatments
Wrinkle-smoothing injections ( حقن تنعيم التجاعيد ) are non-surgical aesthetic treatments designed to temporarily relax specific facial muscles responsible for repetitive movements that contribute to dynamic lines. Common treatment areas can include forehead lines, frown lines between the eyebrows, and wrinkles around the eyes. The treatment is generally tailored according to facial anatomy, skin condition, and the individual's desired outcome.
How Wrinkle Smoothing Injections Work
These injections work by temporarily reducing muscle activity in targeted areas. When certain facial muscles relax, the overlying skin may appear smoother, making existing expression lines less noticeable. The approach is focused on achieving a balanced appearance rather than eliminating every facial movement, helping preserve natural-looking expressions when appropriately administered.
Wrinkle Smoothing for Different Age Groups
Wrinkle management is not limited to one particular age group. Younger adults may consider treatments when early expression lines become noticeable, while older individuals may seek to soften established dynamic wrinkles. The appropriate approach depends on individual facial characteristics, skin condition, treatment goals, and professional assessment rather than age alone.
Options for Younger Adults
People in their twenties and thirties may notice fine lines caused primarily by repeated facial expressions and environmental exposure. A personalized consultation can help determine whether wrinkle-smoothing treatment is appropriate and which areas may benefit from treatment. Maintaining realistic expectations is important, as these treatments are intended to address specific concerns rather than completely change facial appearance.
Options for Mature Skin
As skin ages, collagen and elastin production naturally decreases, which can contribute to visible lines and changes in skin texture. Wrinkle-smoothing injections may help address dynamic wrinkles, although they do not replace treatments designed specifically for significant skin laxity or surface texture concerns. A customized aesthetic plan can combine suitable approaches according to the individual's needs.
Areas Commonly Treated
Facial areas with frequent muscle movement are often the primary focus of wrinkle-smoothing treatments. Forehead lines may become more visible during expressions, while frown lines can develop between the eyebrows. Crow's feet around the outer corners of the eyes may also become prominent with repeated smiling or squinting. Treatment selection should be based on facial assessment and the individual's aesthetic objectives.
Maintaining a Natural Appearance
A natural result depends on careful treatment planning and appropriate product placement. Excessive treatment can affect facial movement, while a personalized approach can focus on softening lines without creating an overly altered appearance. Discussing desired results clearly during a consultation allows the treatment plan to be adjusted to individual preferences and facial characteristics.
What to Expect During Treatment
Wrinkle-smoothing injections are generally performed during an outpatient aesthetic appointment. The treatment area is assessed before the injections are administered, and the process typically involves several small injections into selected muscles. Temporary redness, swelling, tenderness, or minor bruising may occur around injection sites. Patients should follow the aftercare guidance provided by their aesthetic professional.
Choosing a Suitable Treatment Plan
Every face ages differently, so a personalized approach is important. Factors such as the location and depth of wrinkles, facial movement, skin condition, previous aesthetic treatments, and desired outcome can influence treatment planning. A professional consultation provides an opportunity to discuss expectations and determine whether wrinkle-smoothing injections are suitable.
Why Consider Wrinkle Smoothing in Riyadh?
Riyadh offers access to modern aesthetic services for individuals interested in non-surgical facial rejuvenation. People considering treatment can research clinics carefully, review available services, and arrange a consultation to understand the treatment process. Selecting an established clinic with appropriate clinical standards and personalized assessment can support a more informed treatment experience.
Frequently Asked Questions
Are wrinkle-smoothing injections suitable for all ages?
They may be considered by adults of different ages depending on their facial concerns, health considerations, and treatment goals. A professional assessment is recommended before treatment.
How long does a wrinkle-smoothing treatment take?
The appointment can be relatively brief, although the exact duration depends on the number of areas being treated and the individual's treatment plan.
Will wrinkle-smoothing injections remove every wrinkle?
These treatments primarily target dynamic wrinkles associated with muscle movement. They are not designed to remove every type of wrinkle or address all signs of skin aging.
Can the results look natural?
A carefully planned treatment can aim to soften targeted lines while preserving appropriate facial movement. Results depend on individual anatomy, treatment technique, and the amount administered.
When should I consider wrinkle-smoothing treatment?
There is no universal age at which treatment should begin. The decision generally depends on visible concerns, personal preferences, facial characteristics, and professional assessment.
Consultation at Enfield Royal Clinic
If you are considering a personalized approach to smoother-looking skin, a consultation can help you understand your options and determine whether wrinkle-smoothing treatment suits your facial concerns. Enfield Royal Clinic ( عيادة إنفيلد الملكية ) provides an opportunity to discuss your aesthetic goals and explore an appropriate treatment plan based on your individual needs.
PW Consulting: Global Electronic Helium Market Hits $2.19B in 2025, Projected 8.15% CAGR to 2032
By pmarketresearch, 2026-09-16
Navigating the Electronic Grade Helium Market: Strategic Intelligence for 2026 and Beyond
The global supply chain for high-technology manufacturing stands at a critical inflection point. As semiconductor fabrication pushes toward smaller nodes and new display technologies mature, the demand for ultra-high-purity gases has become a defining constraint for industrial capacity. Among these essential materials, electronic grade helium occupies a unique position. It is not merely a commodity but a foundational enabler for cooling, atmosphere control, and precision leak detection in advanced nodes. Our latest Worldwide Electronic Grade Helium Market research offers a comprehensive lens into this complex ecosystem, providing the data-driven foresight necessary for corporate strategy in 2026.
This report is designed for executive leadership, supply chain directors, and investment analysts who require more than surface-level statistics. It transforms historical performance and forward-looking projections into actionable intelligence. By examining the trajectory from 2020 through the forecast period ending in 2032, stakeholders can calibrate their portfolios against the expected compound annual growth rate of 8.15 percent. Such growth signals robust expansion, yet it also masks underlying volatility that only rigorous analysis can uncover.
Market Trajectory and Macro Dynamics
Understanding the scale of the opportunity requires a clear view of the market's evolution. In 2025, the global revenue for electronic grade helium reached approximately 2185.5 million USD. This figure represents a significant climb from the 1455.2 million USD recorded in 2020, illustrating a sustained upward trend driven by technological adoption and capacity expansion. The forecast suggests this momentum will continue, with revenue projected to approach 3782.13 million USD by 2032.
These numbers reflect more than simple volume increases. They encapsulate the intensifying arms race in semiconductor manufacturing, where purity standards are becoming non-negotiable. The market is segmented by purity grades, ranging from 6N and above to lower specifications. High-purity segments continue to command premium valuations as fabrication facilities prioritize yield integrity over cost minimization. Similarly, applications such as semiconductor wafer manufacturing, flat panel displays, optical fiber manufacturing, and photovoltaic cells drive distinct demand patterns. Each segment faces unique supply pressures and technological requirements that generic market summaries often overlook.
Geographical distribution also plays a pivotal role in shaping market dynamics. While the Asia Pacific region currently leads in consumption volume, North America and Europe maintain significant strategic importance due to their entrenched infrastructure and regulatory environments. The Rest of World segment, though smaller in current valuation, presents emerging opportunities as localized manufacturing capabilities develop. A granular understanding of these regional nuances is essential for companies planning multinational expansion or supply chain reconfiguration.
Competitive Landscape and Strategic Positioning
The electronic grade helium market is characterized by a high degree of concentration, with a small number of key players controlling a substantial share of global supply. Our analysis indicates that the top three companies account for over 62 percent of the market, while the top five firms command nearly 79 percent. This concentration creates both barriers to entry and potential vulnerabilities for downstream manufacturers who rely on a limited supplier base.
Leading incumbents such as Air Liquide S.A., Air Products and Chemicals, Inc., and Linde plc have established dominance through extensive purification, liquefaction, and distribution networks. These organizations leverage diverse global sourcing mixes and massive processing capabilities to ensure continuity of supply. For instance, Linde operates one of the largest processing plants globally, while Air Products pioneers extraction technologies tailored for semiconductor applications. Taiyo Nippon Sanso Corporation and Messer SE & Co. KGaA further reinforce the competitive field with specialized high-purity offerings.
Worldwide Electronic Grade Helium Market
Beyond the traditional gas giants, energy and resource corporations like Exxon Mobil Corporation and QatarEnergy LNG contribute significant volumes from natural gas and LNG processing facilities. Gazprom also remains a notable producer, extracting helium as a byproduct of natural gas operations. The interplay between these diverse entities defines the market's resilience and pricing power. Understanding the specific capabilities, sourcing rights, and strategic priorities of each competitor is vital for identifying partnership opportunities or assessing supply risk.
Disruption and Resilience in 2026
The year 2026 has already introduced profound disruptions that underscore the value of real-time intelligence. Recent developments highlight the fragility of the supply chain and the rapidity with which conditions can change. In March 2026, QatarEnergy declared force majeure on helium supply following a disruption at the Ras Laffan LNG facility. This event impacted approximately 30 percent of global semiconductor-grade helium output, triggering spot price surges ranging from 40 to 100 percent in early 2026.
Simultaneously, geopolitical tensions affecting the Strait of Hormuz have exacerbated logistics challenges, tightening supply for Asian semiconductor hubs in Taiwan and South Korea. These external shocks contrast sharply with strategic investments aimed at bolstering regional security. Air Liquide opened a new helium facility near Taichung port in Taiwan during the same period, specifically to support local chipmakers amid global constraints. Meanwhile, Guangdong Huate Gas achieved mass production of 6N ultra-high-purity helium and secured ASML certification, marking a significant milestone in domestic capability enhancement.
Helium Gas Market
China's domestic ultra-high-purity helium production capacity has also reached approximately 1.2 million cubic meters annually, with firms developing recovery systems achieving reprocessing rates up to 98 percent. These developments illustrate a bifurcated market where supply shocks coexist with aggressive capacity building and technological innovation. Companies must navigate this duality to secure reliable access without overpaying for scarcity premiums.
Strategic Value of the Research Report
Our Worldwide Electronic Grade Helium Market report goes beyond aggregating public information. It provides a structured framework for decision-making that integrates market sizing, competitive profiling, and dynamic scenario analysis. The research delves into the operational specifics of how leading firms manage purification technologies, distribution logistics, and customer certification requirements. It examines the implications of force majeure declarations and geopolitical shifts on long-term contracting strategies.
Readers will gain access to detailed segmentation analysis that breaks down demand drivers across purity grades and application verticals without exposing sensitive proprietary data shared by industry participants. The report also explores the regulatory and raw material contexts that influence production costs and availability. Since helium is primarily extracted as a byproduct of natural gas and LNG processing, understanding the upstream economics is crucial for predicting price floors and supply ceilings. Major sources, including Qatar LNG facilities and U.S. operations like ExxonMobil's Shute Creek, are evaluated for their capacity constraints and expansion potential.
Furthermore, the study assesses the competitive intensity and market concentration metrics that define bargaining power. By quantifying the share held by dominant players, the report helps buyers evaluate negotiation leverage and supplier diversification needs. It also identifies gaps in supply coverage that new entrants or regional producers might exploit. For investors, the forecast period from 2026 to 2032 offers a roadmap for evaluating growth potential across different segments and regions, highlighting where capital allocation may yield the highest returns.
Conclusion: Building Resilience Through Intelligence
In an environment where supply disruptions can halt production lines and geopolitical events can reshape logistics overnight, intuition is insufficient. Strategic success depends on access to verified data, expert analysis, and a clear understanding of market structures. The Worldwide Electronic Grade Helium Market research equips organizations with the insights needed to anticipate shifts, mitigate risks, and capitalize on growth opportunities.
From the macro trajectory of revenue growth to the micro details of facility openings and certification achievements, this report provides a holistic view of the industry. It enables stakeholders to benchmark their strategies against the best-in-class practices of leading competitors and to prepare for a future where electronic grade helium remains a critical bottleneck and a strategic asset. Accessing the full report unlocks the detailed tables, regional breakdowns, and company profiles required to execute informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Electronic Grade Helium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Projects Worldwide Cartridge Filters Market To Hit $10.4 Billion By 2032 At 6.15% CAGR
By pmarketresearch, 2026-09-16
Strategic Foresight in Filtration: Unlocking Value in the Global Cartridge Filters Market Through 2032
In an era defined by tightening regulatory frameworks, escalating sustainability mandates, and the relentless pursuit of operational efficiency, the cartridge filters market has evolved from a commoditized component segment into a strategically critical enabler of industrial resilience. As organizations navigate increasingly complex supply chains and performance-driven procurement cycles, access to granular, forward-looking intelligence is no longer a luxury—it is a operational imperative. PW Consulting’s latest Worldwide Cartridge Filters Market research delivers precisely that: a rigorously validated, structurally segmented, and competitively mapped assessment designed to inform capital allocation, product positioning, and go-to-market strategy through 2032.
The Macro Trajectory: Sizing the Opportunity Beyond Historical Baselines
The global cartridge filters market has demonstrated consistent expansion over the past half-decade, recovering from early pandemic-era supply disruptions and capitalizing on accelerated industrial modernization. Trailing performance from 2020 through 2025 established a robust foundation, with evaluated market revenue reaching approximately USD 6,850 million by the 2025 base year. This trajectory reflects more than cyclical recovery; it signals a structural shift in how enterprises approach fluid and air management across critical processes.
Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.15%, positioning the market on a clear upward arc. By 2026, evaluated industry revenue is anticipated to approach USD 7,271 million, with sustained momentum carrying the segment toward the USD 10,402 million threshold by 2032. These figures are not abstract aggregates; they represent the compounded effect of capacity expansions, material innovation cycles, regulatory-driven replacement schedules, and cross-sector procurement modernization. Organizations that understand the underlying growth vectors—rather than surface-level headline numbers—will be better equipped to time investments, optimize inventory strategies, and align product roadmaps with emerging demand pockets.
Crucially, the assessment behind these projections draws from a multi-year historical baseline, ensuring that forward estimates are stress-tested against real-world procurement patterns, regional capacity shifts, and material cost volatility. Decision-makers relying on truncated or backward-looking datasets risk misallocating resources in a market where lead times, specification upgrades, and compliance cycles increasingly dictate competitive outcomes.
Structural Dynamics: Material, Application, and Regional Interplay
The cartridge filters ecosystem is inherently multidimensional. Material selection dictates performance envelopes, cost structures, and compatibility with aggressive process environments. Application mandates drive specification granularity, replacement frequency, and certification requirements. Regional industrial footprints shape procurement behaviors, localization trends, and distribution architectures. PW Consulting’s analysis dissects these intersecting dimensions without reducing them to static snapshots, instead mapping how they evolve under varying macroeconomic and regulatory conditions.
Material architectures continue to bifurcate between cost-optimized conventional media and high-performance engineered substrates. Polypropylene remains a foundational standard, prized for chemical resistance and economic viability, while polyester, cellulose, and advanced membrane configurations capture specialized demand where purity, flux rates, or thermal stability are non-negotiable. The market’s material mix is further complicated by raw resin price fluctuations tied to petrochemical capacity and crude oil dynamics, creating margin pressures that reward suppliers with vertically integrated sourcing or differentiated formulation capabilities.
Worldwide Cartridge Filters Market
Application-side demand is equally diversified. Water treatment continues to anchor substantial volume, driven by municipal infrastructure upgrades, industrial effluent management, and tightening discharge standards. Food and beverage operations prioritize sanitary compatibility and regulatory conformance, while chemicals and petrochemicals sectors demand robust handling of corrosive or high-viscosity fluids. Pharmaceutical and biopharmaceutical manufacturing imposes the strictest purity and validation requirements, favoring membrane and precision-engineered cartridge solutions. Across these verticals, a common theme emerges: buyers are increasingly specifying filters not merely as replacement components, but as integrated process enablers that reduce downtime, extend service intervals, and minimize total cost of ownership.
Regional procurement landscapes reflect differing industrialization paces, environmental policy intensities, and supply chain localization strategies. mature markets emphasize compliance-driven replacements and high-efficiency upgrades, while emerging industrial corridors exhibit rapid capacity buildup, price-sensitive sourcing, and growing preferences for locally assembled or regionally distributed product lines. Understanding how these regional rhythms interact with material availability and application growth is essential for firms planning geographic expansion, manufacturing footprint adjustments, or partnership ecosystems.
Competitive Architecture and Strategic Positioning
The cartridge filters market operates within a moderately concentrated competitive structure, where scale, technical differentiation, and application-specific expertise determine market share trajectories. Evaluated industry concentration metrics indicate that the top three players command approximately 28.5% of aggregate revenue, while the top five account for roughly 38.75%. This distribution suggests a landscape where large multinational incumbents hold meaningful share but face persistent pressure from specialized challengers, regional manufacturers, and application-focused innovators.
Global leaders such as Pall Corporation and Parker Hannifin leverage broad filtration portfolios, extensive distribution networks, and legacy engineering capabilities to serve industrial, process, and fluid power applications at scale. Their strategies often center on integrated solution offerings, cross-selling across hydraulic, process, and water treatment verticals, and sustained investment in high-flow and membrane-based architectures. 3M Company applies materials science depth to liquid and air filtration, competing on formulation versatility and commercial-industrial crossover demand. Eaton Corporation and Donaldson Company maintain strong positions in fluid power, process filtration, and industrial dust collection, respectively, emphasizing system-level compatibility and durability.
In the water and municipal domain, Pentair delivers high-flow cartridge configurations tailored to residential, commercial, and industrial treatment workflows. Graver Technologies and Camfil address industrial water treatment, power generation, and cleanroom/HVAC air filtration, respectively, capitalizing on niche performance credentials and service-oriented engagement models. The biopharmaceutical and laboratory segment is heavily shaped by Merck Millipore (Merck KGaA), Sartorius Stedim Biotech, and Meissner Filtration Products, where sterile processing, traceability, and regulatory validation outweigh pure cost competition. GKN Powder Metallurgy differentiates through metallic membrane and sintered cartridge technologies, recently advancing new fine-filtration solutions aimed at enhanced efficiency for downstream industrial applications.
Regional and specialty manufacturers—including LOONG Filtration, Brother Filtration, and Gopani Filters—illustrate the growing importance of localized production, melt-blown and pleated media optimization, and flexible specification adaptation for water treatment and process industries. These players often compete on responsiveness, custom configuration capabilities, and proximity to regional procurement cycles, challenging incumbents to accelerate localization strategies or reinforce value-added engineering services.
Competitive intelligence in this market extends beyond corporate profiles. It requires mapping recent product introductions, certification expansions, capacity investments, and strategic partnerships to anticipate share shifts. The 2025 introduction of enhanced metallic membrane cartridge filters for fine filtration and efficiency, for example, signals incremental but meaningful movement toward higher-performance substrate competition. Firms that track such developments against their own specification roadmaps and procurement calendars gain a tangible advantage in pricing negotiations, vendor qualification processes, and product lifecycle planning.
Regulatory, Compliance, and Macro Trend Catalysts
Cartridge filter adoption is increasingly governed by a matrix of performance standards and environmental directives that shape both specification requirements and replacement economics. Compliance with testing frameworks such as ISO 16889:2012 for hydraulic filter element evaluation, alongside NSF/ANSI 61 for drinking water contact materials, remains essential for suppliers targeting regulated industrial and municipal applications. These standards do not merely certify products; they influence procurement qualification cycles, warranty expectations, and engineering acceptance criteria.
Environmental regulation continues to act as a structural demand driver. The U.S. EPA Clean Water Act and Clean Air Act, alongside comparable frameworks in other jurisdictions, reinforce the necessity of effective particulate and contaminant capture in industrial water and air treatment workflows. As discharge limits tighten and monitoring protocols become more rigorous, facilities face intensified pressure to maintain filtration integrity, reduce frequent change-outs, and document compliance performance. This regulatory environment favors suppliers capable of delivering consistent quality, traceable manufacturing processes, and technical support that bridges product specification with operational compliance.
Macro trends further reshape buyer priorities. Across pharmaceuticals, food and beverage, and water treatment sectors, there is growing demand for higher filtration precision, extended service life, and materials engineered to withstand aggressive process conditions. Procurement teams increasingly evaluate filters through a total-cost lens, weighing initial price against downtime reduction, waste minimization, chemical compatibility, and replacement frequency. Simultaneously, raw material dynamics—particularly volatility in polypropylene resin pricing linked to crude oil markets and petrochemical capacity—introduce margin variability that rewards suppliers with robust sourcing strategies, formulation flexibility, and transparent cost communication.
These dynamics converge to create a market where technical credibility, regulatory fluency, and supply chain reliability are as decisive as product performance alone. Organizations that integrate compliance foresight, material cost monitoring, and application-specific engineering support into their commercial strategies will navigate this environment with greater resilience.
What the Research Delivers: An Actionable Intelligence Framework
PW Consulting’s Worldwide Cartridge Filters Market study is structured to translate macro trends and competitive signals into decision-ready intelligence. Rather than offering static tables, the report builds a layered analytical architecture designed for strategic planning, investment justification, and market entry assessment. Core components include:
Cartridge Valve Market
- Evaluated historical performance and forward projections calibrated across multiple demand drivers, enabling scenario-based planning rather than single-point forecasting.
- Material-type and application-segment breakdowns that clarify where volume concentrates, where specification premiums emerge, and how replacement cycles differ across industrial contexts.
- Regional demand distributions that map procurement intensity, industrialization momentum, and localization preferences without oversimplifying cross-market variation.
- Competitive positioning analysis that tracks incumbent scale advantages, specialty manufacturer agility, and recent product or capability introductions shaping vendor qualification outcomes.
- Regulatory and standards context integrated into demand dynamics, helping readers anticipate qualification thresholds, compliance-driven replacement schedules, and engineering acceptance criteria.
- Raw material and cost structure considerations that connect resin price volatility, substrate innovation, and supply chain behavior to pricing strategies and margin management.
The assessment is built for teams that need to align product development with market reality, time capacity or partnership decisions with demand inflection points, and evaluate competitive threats with evidence rather than assumption. Whether the objective is to expand into high-growth application verticals, optimize regional distribution, benchmark against incumbents, or identify white-space opportunities in material or configuration specialization, the research provides the structural clarity required to move from observation to action.
Preparing for 2026 and Beyond
The cartridge filters market through 2032 will not be defined by a single driver, but by the interplay of regulatory pressure, material innovation, application-specific engineering demands, and competitive repositioning. Enterprises that treat filtration as a strategic process component—rather than a routine maintenance purchase—will capture disproportionate value in reliability, compliance performance, and total cost optimization. Those that delay informed planning risk exposure to specification misalignment, margin compression, and reactive procurement cycles.
PW Consulting’s comprehensive assessment offers the evidentiary foundation needed to navigate this landscape with precision. The full report details segment-level trajectories, competitive benchmarking, regional nuances, and forward-looking demand catalysts that cannot be fully captured in a preview. To access the complete intelligence architecture, evaluate scenario-based projections, and translate market structure into your organization’s strategic roadmap, explore the full Worldwide Cartridge Filters Market research at the source page.
For detailed analysis of this topic, please visit the official page: Worldwide Cartridge Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Patient Hygiene Aids Market Hits $15B in 2025, Expands at 6.89% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Worldwide Patient Hygiene Aids Market: A 2026 Outlook
The global healthcare landscape is undergoing a structural shift where infection prevention, patient comfort, and operational efficiency are no longer competing priorities but interconnected imperatives. Within this context, patient hygiene aids have emerged as a critical category of clinical consumables, bridging the gap between bedside care standards and hospital-acquired infection reduction protocols. As we enter 2026, procurement leaders, product strategists, and investors require a precise understanding of how this market will evolve through the end of the decade. The Worldwide Patient Hygiene Aids Market research report published by PW Consulting provides that blueprint.
Drawing on a rigorous historical analysis from 2020 through 2025 and a forward-looking forecast spanning 2026 to 2032, this study maps the revenue trajectories, competitive pressures, and demand-side dynamics shaping the sector. The market has demonstrated consistent expansion, with total revenue growing from approximately 10.8 billion USD in 2020 to an estimated 14.97 billion USD in 2025. The forecast period anticipates continued momentum, with revenues projected to reach roughly 15.29 billion USD in 2026 and climb steadily toward 23.87 billion USD by 2032. This growth path reflects a compound annual growth rate of 6.89 percent across the forecast horizon, signaling a mature yet expanding category that rewards strategic positioning rather than passive participation.
For enterprise decision-makers, these figures are more than summary statistics. They reveal the scale of opportunity in a market where procurement cycles, formulary integration, and value-based purchasing increasingly dictate commercial success. This article outlines the strategic architecture of the full report, demonstrates why its insights are essential for 2026 planning, and highlights the competitive and regulatory forces that will shape product roadmaps, distribution strategies, and partnership decisions in the year ahead.
Mapping the Market Architecture: Structure, Scale, and Growth Trajectory
Effective strategy begins with a clear taxonomy of the market. The report decomposes the worldwide patient hygiene aids landscape into three foundational dimensions: product type, end-user setting, and geographic region. Each dimension carries distinct demand drivers, formulary considerations, and growth characteristics. The analysis quantifies the current revenue base across these segments, illustrating how the category is distributed among rinse-free cleansing formats, bathing and skin-care accessories, oral hygiene products, shampoo caps and hair-care aids, and incontinence hygiene accessories. By mapping these product families against their respective clinical use cases and procurement pathways, the study provides a structural reference for companies evaluating portfolio gaps, line extensions, or consolidation targets.
Equally important is the segmentation by end-user environment. Hospitals continue to exert significant demand pull, supported by standardized infection control programs, high patient throughput, and institutional purchasing contracts. Long-term care facilities represent a substantial and steady demand base, driven by extended resident stays, staffing efficiency needs, and the practical advantages of no-rinse hygiene routines for mobility-limited populations. Home care settings add a distinct growth vector, reflecting the broader shift toward decentralized care, patient preference for portable hygiene solutions, and the operational realities of family-administered or visiting-nurse care protocols. The report analyzes how these end-user segments differ in purchasing behavior, volume sensitivity, and product specification requirements, enabling clients to tailor go-to-market plans rather than applying a uniform commercial approach.
Geographically, the analysis situates demand across major regions, revealing where market maturity, regulatory environments, and healthcare infrastructure intersect. Rather than presenting static regional snapshots, the study traces how regional revenue bases have evolved from 2020 to 2025 and projects how each geography will contribute to the overall trajectory through 2032. This regional framing is crucial for multinational suppliers evaluating expansion timing, localized product adaptation, and distribution partnerships, as well as for regional players seeking to benchmark their share against global comparators.
A central theme of the report is the differentiation between headline growth and the underlying mechanics that sustain it. While the category benefits from broad healthcare consumption trends, the forecast reflects the compounding effect of product innovation, clinical protocol adoption, and procurement rationalization. The hygiene aids market is not simply expanding because healthcare is expanding; it is expanding because the way care is delivered is changing. Bed-bound patient populations, staffing constraints in institutional settings, and heightened emphasis on cross-contamination reduction have all reinforced demand for rinse-free body washes, no-rinse shampoo systems, and dermatologist-tested wipes formulated for frequent use on delicate skin. At the same time, reimbursement realities in many hospital systems mean that hygiene consumables are typically absorbed within diagnosis-related group payments or facility operating budgets rather than reimbursed through standalone procedure codes. This cost-integration dynamic places a premium on product efficiency, bundle compatibility, and demonstrable contributions to infection prevention, all of which the report evaluates in detail.
Worldwide Patient Hygiene Aids Market
Beyond Headlines: Translating Forecast Data into 2026 Decision-Making
The strategic value of any market study lies not in the numbers it publishes, but in the decisions those numbers enable. For 2026 planning, the report is designed to support concrete choices across R&D prioritization, commercial segmentation, pricing architecture, and partnership strategy. Because the forecast extends through 2032, leadership teams can test multiple scenarios: How should product development resources be allocated if institutional procurement continues to favor standardized no-rinse systems? Where does the strongest volume upside reside if home-based care continues to grow as a share of total demand? How should pricing and packaging adapt if long-term care facilities increasingly consolidate purchases around fewer suppliers?
To answer these questions, the report goes beyond aggregate market sizing. It includes a structured competitive landscape assessment that profiles the companies shaping category standards today. The analysis covers global manufacturers and specialized suppliers whose product portfolios span no-rinse bathing cloths, bedside care consumables, antiseptic skin preparation products, incontinence management aids, and environmental hygiene systems. For each profiled player, the study examines product positioning, clinical application focus, and areas of differentiation, helping clients understand where competitive intensity is highest and where whitespace opportunities may exist. This competitive mapping is particularly valuable for organizations assessing potential acquisitions, evaluating entry into adjacent subcategories, or determining how to defend share in mature hospital segments.
The report also integrates the operational realities that influence buyer decisions. In clinical environments, rinse-free patient bath cloths and no-rinse body washes are formulated to be dermatologist-tested, hypoallergenic, pH-balanced, and non-irritating for frequent use. These formulation standards are not cosmetic niceties; they are procurement criteria tied to skin integrity, patient comfort, and workflow efficiency. Similarly, the practical advantage of no-rinse hygiene aids as alternatives to traditional basin-based bed baths is directly relevant to infection prevention programs that seek to reduce cross-contamination risks. The study ties these product attributes to purchasing logic, showing how clinical benefits translate into formulary inclusion, contract renewals, and volume resilience.
Another layer of decision-support comes from the regulatory and reimbursement environment. In 2025, regulatory guidance clarified that whole-room UVC microbial reduction devices used in healthcare hygiene protocols require FDA 510(k) clearance to ensure safety and efficacy. While this development primarily concerns environmental disinfection, it reflects a broader regulatory posture in which hygiene-related claims, device clearance, and infection-prevention efficacy are scrutinized more closely. For patient hygiene aid suppliers, this environment reinforces the importance of evidence-based product positioning and regulatory-aware messaging. On the reimbursement side, the fact that hospital hygiene consumables are generally embedded within DRG payments or facility operating costs means that buyers evaluate products through the lens of total cost of care, staff time savings, and supply chain simplicity. The report analyzes how these financial and regulatory dynamics shape pricing tolerance, contract structures, and value propositions across end-user segments.
Orthodontic Aids Market
Competitive Intensity and Recent Market Developments
The competitive structure of the patient hygiene aids market is defined by a mix of large diversified healthcare suppliers and focused specialists. Concentration metrics indicate that the top three participants account for approximately 28.45 percent of market revenue, while the top five represent roughly 41.12 percent. This level of concentration suggests a market in which scale, distribution reach, and institutional relationships confer meaningful advantages, yet it also leaves substantial room for specialized players to compete on product differentiation, clinical specialization, and niche application performance.
Recent developments in early 2026 reinforce the dynamic nature of this landscape. In January 2026, Fannin UK completed integration with ISKUS Health UK, expanding its offerings to include patient hygiene products alongside other medical consumables. This type of portfolio integration signals a strategic trend in which suppliers seek broader care-area coverage to capture cross-category purchasing and simplify procurement for institutional customers. In the second half of 2025, Surfacide received FDA 510(k) clearance for its Helios+ UV-C system, a whole-room microbial reduction device designed to support enhanced hygiene protocols in patient care environments. As the first such system to receive this clearance, the development highlights how infection prevention technology is advancing alongside consumable hygiene products, creating a broader ecosystem in which hygiene aids are part of a layered clinical strategy.
These events illustrate the kinds of strategic signals that procurement and product leaders must monitor. Portfolio expansion can alter competitive dynamics by bundling hygiene aids with adjacent consumables, while regulatory milestones for related hygiene technologies can shift buyer expectations around evidence, efficacy, and integrated infection control. The report analyzes these developments within a structured framework, helping clients distinguish between transient news and durable shifts in competitive behavior.
What the Full Study Delivers: Contents, Frameworks, and Actionable Intelligence
The complete report is built to support both strategic planning and practical execution. It combines quantitative forecasting with qualitative market intelligence, offering a multi-layered view of the category that companies can use across functions. Executive leadership can rely on the top-line trajectory and concentration data to inform investment posture; commercial teams can use segmentation detail to refine target accounts and channel strategy; and R&D or product management teams can use formulation, end-user, and competitive insights to prioritize development pipelines.
Key components of the study include a full historical and forecast revenue model spanning 2020 through 2032, a segmented breakdown by product type, end-user setting, and region, and a competitive landscape section that profiles major participants and recent market moves. The report also contextualizes demand drivers such as institutional infection prevention programs, long-term care workflow requirements, and the practical role of no-rinse hygiene routines in mobility-limited patient populations. In addition, it addresses the procurement and reimbursement realities that influence how hygiene consumables are purchased, budgeted, and justified within healthcare facilities.
Rather than leaving the analysis at a macro level, the study connects market structure to commercial implications. It shows where demand is most concentrated, how segment growth differs in character and pace, and what competitive positioning means for suppliers competing on price, performance, or clinical specialization. By preserving forward visibility through 2032, the report allows organizations to test medium-term strategy against a range of trajectory assumptions instead of planning solely around near-term demand.
Conclusion: Why This Research Matters Now
As 2026 unfolds, the worldwide patient hygiene aids market presents a rare combination of stability and transformation. Demand is anchored by enduring clinical needs and expanding care settings, yet it is also being reshaped by product innovation, procurement consolidation, regulatory clarity around hygiene-related technologies, and the continued shift toward rinse-free, cross-contamination-reducing hygiene routines. In this environment, strategy cannot rely on intuition alone. Organizations need a validated view of where revenue is coming from, how competitive forces are arranged, and which market mechanics will matter most over the next several years.
The Worldwide Patient Hygiene Aids Market report from PW Consulting is designed to meet that need. It translates historical performance and forward-looking forecasts into a strategic framework that supports segmentation, competitive assessment, product prioritization, and commercial execution. For decision-makers who require depth without noise, the study offers a structured pathway from market intelligence to action. To explore the full segmentation data, detailed company profiles, and complete forecast model, we invite you to access the full report and review the complete intelligence package.
For detailed analysis of this topic, please visit the official page: Worldwide Patient Hygiene Aids Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Ethane Market Hits $36.8B in 2025, Poised to Reach $51.86B by 2032 at 5.02% CAGR
By pmarketresearch, 2026-09-16
Worldwide Ethane Market Outlook 2026: Strategic Imperatives for Industry Leaders
The global ethane market stands at a critical inflection point as we move into 2026. Valued at approximately 36.8 billion USD in 2025, the market is projected to reach 51.86 billion USD by 2032, reflecting a steady compound annual growth rate of 5.02 percent. This trajectory is not merely a function of incremental demand growth but rather the result of structural shifts in feedstock logistics, regional capacity reallocation, and the accelerating integration of midstream export infrastructure with downstream petrochemical complexes. For executives, investors, and strategy teams operating across the hydrocarbon value chain, the Worldwide Ethane Market research report offers a comprehensive, data-driven lens into the forces that will define competitive positioning, capital allocation, and supply chain resilience over the next six years.
This introduction outlines the strategic value of the report, previews its analytical architecture, and demonstrates how the findings can be operationalized for 2026 decision-making. While macro indicators and industry milestones are highlighted here, the complete segmentation matrices, region-specific growth drivers, and granular competitor benchmarks are reserved for subscribers and readers accessing the full analysis ecosystem. The objective is simple: equip leadership teams with the framework to interpret market signals accurately, while providing a clear pathway to the deeper intelligence required for execution.
Market Trajectory and Structural Demand Drivers
The historical window from 2020 to 2025 establishes a clear baseline of expansion, with market size climbing from 27.5 billion USD to 36.8 billion USD. The forward forecast period from 2026 through 2032 anticipates continued upward momentum, with the market projected to cross 39.68 billion USD in 2026, reach 40.95 billion USD in 2027, 42.88 billion USD in 2028, and 43.95 billion USD in 2029 before accelerating toward 47.44 billion USD in 2030, 48.17 billion USD in 2031, and ultimately 51.86 billion USD by 2032. These figures are anchored in a 5.02 percent CAGR, a rate that underscores sustained demand for ethane as a feedstock and intermediate while reflecting the gradual pace of capacity additions, regulatory adjustments, and macroeconomic volatility.
Worldwide Ethane Market
Ethanolamine Market
The growth narrative is heavily influenced by the interplay between production recovery and export-oriented infrastructure expansion. U.S. ethane recovery is forecasted to average 3.06 million barrels per day in 2025 and rise to 3.15 million barrels per day in 2026, signaling a robust upstream supply environment that supports both domestic consumption and international shipment. Concurrently, U.S. ethane net exports are projected to grow 14 percent in 2025 followed by a 16 percent rise in 2026, driven by global petrochemical feedstock demand and expanded export terminals. This dual dynamic—rising domestic availability paired with structured export growth—creates a market characterized by shifting arbitrage opportunities, regional pricing sensitivity, and evolving supply chain dependencies.
The report systematically unpacks these dynamics by mapping demand sources across natural gas separation and refinery by-product pathways, measuring application intensity across ethylene synthesis, power generation, and chemical intermediate use, and isolating the segments that will experience the most pronounced volume and value shifts. Rather than presenting a single aggregate narrative, the analysis decomposes the market into its functional components, enabling stakeholders to identify where margin stability, volume expansion, and infrastructure bottlenecks converge.
Infrastructure Expansion and the Reshaping of Global Flows
The most consequential market behavior in 2025 and 2026 is the rapid scaling of export and fractionation infrastructure, particularly within the United States. U.S. ethane export capacity increased by 16 percent with the addition of the Nederland facility and the first phase of the Neches River terminal, and a further 21 percent expansion is expected from Neches River Phase 2 in early 2026. These commissioning milestones are not isolated engineering achievements; they represent the physical backbone of a market that is increasingly defined by cross-border feedstock mobility and the integration of Appalachian, Permian, and Gulf Coast supply networks into international demand centers.
Enterprise Products Partners commissioned the Neches River ethane export terminal in Texas with initial capacity of 120,000 barrels per day in July 2025, reinforcing the Gulf Coast as a primary export corridor. Energy Transfer followed with the commissioning of the Nederland facility in Texas in the second quarter of 2025, delivering capacity to export up to 250,000 barrels per day of NGLs including ethane. Energy Transfer is also expanding its Marcus Hook, Pennsylvania terminal by 20,000 barrels per day by the end of 2025 to support Appalachian ethane exports. These investments collectively broaden the geographic reach of U.S. ethane supply and reduce the friction associated with moving NGL streams from inland processing centers to marine export points.
The U.S. Energy Information Administration forecasted in October 2025 that U.S. ethane net exports would grow 14 percent in 2025 and 16 percent in 2026, supported by new export infrastructure. This export trajectory is reinforced by production volume trends and by strategic shifts in international feedstock procurement. Chinese petrochemical producers, including Wanhua Chemical and others, are investing in ethane crackers and infrastructure to increase use of imported U.S. ethane over naphtha or propane for cost advantages. In January 2025, Wanhua Chemical completed its second cracker in Yantai, China, taking ethane feedstock, and began conversion of its first cracker to ethane from propane. The convergence of U.S. supply-side capacity with Asian demand-side conversion represents one of the most structural realignments in recent petrochemical feedstock markets.
For strategy teams, the critical insight is that infrastructure expansion is not merely a capacity story; it is a competitive moat. Firms that control fractionation, pipeline connectivity, terminal access, and offtake agreements can influence regional pricing spreads, improve delivery reliability, and lock in long-term demand commitments from derivative producers. The report evaluates how these infrastructure assets interact with regional supply balances, how export growth alters domestic versus international valuation gaps, and where new terminal capacity creates both opportunity and competitive pressure for midstream and downstream participants.
Competitive Landscape and Strategic Differentiation
The market is characterized by moderate-to-high concentration, with a CR3 of 38.4 percent and a CR5 of 56.15 percent. This concentration profile indicates that while a small group of integrated producers and midstream leaders exercise substantial influence over feedstock supply, export capacity, and cracker operations, a broader ecosystem of specialized operators continues to shape regional flows and niche value propositions. The report’s competitive analysis goes beyond headquarter mapping and revenue classification; it examines operational footprints, feedstock procurement strategies, infrastructure portfolios, and recent strategic moves that indicate where each player is positioning itself for 2026 and beyond.
ExxonMobil Corporation, headquartered in Irving, Texas, remains a major integrated producer and consumer of ethane as feedstock for ethylene production via steam crackers, with significant U.S. Gulf Coast operations and joint ventures. Dow Chemical Company, based in Midland, Michigan, is a leading consumer of ethane for ethylene and derivative production, operating multiple ethane-based crackers in North America. LyondellBasell Industries, headquartered in Rotterdam, Netherlands, operates ethane-fed steam crackers for ethylene production, with substantial capacity in the U.S. Gulf Coast. Chevron Phillips Chemical Company, located in The Woodlands, Texas, serves as a joint venture partner in ethane crackers, including Golden Triangle Polymers, and is a major user of ethane feedstock. Saudi Aramco and SABIC collectively represent a powerful integrated petrochemical complex in the Middle East, with ethane-based production embedded in downstream integration and large-scale complex economics. Reliance Industries Limited, headquartered in Mumbai, India, imports large volumes of U.S. ethane for its crackers and is expanding ethane import infrastructure and fleet. INEOS, based in London, UK, operates ethane import and cracking facilities in Europe, with the Project One cracker in Antwerp scheduled to start operations in 2026.
Beyond the integrated cracker owners, midstream and production-oriented participants shape the market’s logistics and supply foundation. Enterprise Products Partners L.P., headquartered in Houston, Texas, is a major midstream provider of ethane extraction, fractionation, transportation, and export via terminals including Neches River and Morgan’s Point. Energy Transfer LP, based in Dallas, Texas, is a key midstream company involved in ethane pipeline transportation, fractionation, and exports via Nederland and Marcus Hook terminals. ONEOK, Inc., American Ethane Company, Williams Companies, and Occidental Petroleum Corporation each contribute to the ethane supply chain through natural gas processing, NGL fractionation, production output, and export-oriented supply arrangements. American Ethane Company, for example, is focused on ethane production and export, with contracts for supply to international markets including China.
Recent developments illustrate how these companies are actively reshaping the market environment. In addition to Enterprise’s Neches River terminal commissioning and Energy Transfer’s Nederland facility, INEOS’s Project One ethane cracker in Antwerp, Belgium, is expected to come online in the third quarter of 2026 with capacity of about 80,000 barrels per day of ethane. These milestones reflect a broader trend: new cracker capacity, new terminal capacity, and new import flows are converging simultaneously, creating a market where capacity additions in one node can cascade into pricing, utilization, and regional trade patterns across multiple continents.
The report’s competitive framework assesses each enterprise’s strategic posture in terms of feedstock security, midstream connectivity, export access, derivative integration, and regional expansion. It identifies where scale translates into bargaining power, where logistics constraints can become margin inhibitors, and where new entrants or expanded capacity may alter incumbent positioning. This analysis is designed to help readers evaluate not just who is operating in the market, but how operational decisions in 2026 will affect relative competitive advantage over the forecast horizon.
What the Report Delivers for 2026 Decision-Making
Translating market intelligence into executive action requires more than top-level size estimates and trend narratives. The Worldwide Ethane Market report is structured to support operational planning, capital evaluation, and risk assessment across a range of use cases. It integrates historical performance data, forward forecasts, segmentation detail, competitive profiles, and infrastructure milestones into a single analytical environment, enabling readers to cross-reference demand drivers with supply constraints and to evaluate strategic options against a consistent set of assumptions.
The report provides:
- A full historical reconstruction from 2020 through 2025, with year-by-year market sizing that establishes baseline trends and highlights inflection points in volume and value.
- A detailed forecast from 2026 to 2032, with annual projections that support budgeting, capacity planning, and long-cycle investment evaluation.
- Segment-level analysis across source and application categories, allowing readers to isolate the demand streams most relevant to their business and to quantify the relative importance of each pathway.
- Regional market insights that describe where growth is concentrated, where infrastructure expansion is most active, and how trade flows are reshaping supply access across geographies.
- A structured competitive assessment of the leading producers, midstream operators, and integrated petrochemical players, including profiles of operational focus, geographic presence, and recent strategic developments.
- A review of current industry dynamics, including export infrastructure expansion, production volume trends, export growth forecasts, feedstock substitution behaviors, and terminal commissioning milestones that are actively redefining market mechanics.
- Scenario-aware commentary that helps readers interpret how changes in terminal capacity, cracker utilization, import demand, and regional feedstock preferences may interact over time.
Crucially, the report is designed for practical application. Readers can use the segmentation architecture to benchmark internal assumptions against market-wide averages, identify which application or source segments warrant closer monitoring, and prioritize markets where export growth, cracker additions, or import infrastructure create the greatest strategic impact. The combined historical and forecast datasets support stress testing of volume projections, evaluation of regional exposure, and assessment of how midstream constraints may influence downstream procurement strategies.
Why 2026 Demands a Disciplined Market View
The 2026 operating environment is defined by simultaneous expansion on multiple fronts: production recovery, terminal commissioning, cracker start-ups, and international feedstock substitution. U.S. ethane recovery is projected to rise from 3.06 million barrels per day in 2025 to 3.15 million barrels per day in 2026, while net exports are expected to increase by 16 percent following a 14 percent rise in 2025. At the same time, the U.S. Energy Information Administration reported that export capacity grew 16 percent with the addition of the Nederland facility and Neches River Phase 1, with Neches River Phase 2 expected to add another 21 percent expansion in early 2026. These concurrent developments create a market that is both high-opportunity and high-complexity, where the benefits of capacity growth can be offset by regional pricing volatility, logistics bottlenecks, and shifting trade relationships.
Companies that approach 2026 with a fragmented view of these dynamics risk overcommitting to regions or segments without fully accounting for midstream constraints, pricing dislocations, or the timing of competitor capacity additions. Conversely, organizations that anchor their planning in a comprehensive market map can better align sourcing strategies with terminal access, evaluate export-oriented growth against domestic utilization patterns, and position derivative production to capitalize on emerging demand centers. The report is built to support exactly this kind of disciplined decision-making by connecting macro trends to operational implications and by identifying the variables that matter most for each stakeholder group.
Conclusion: Turning Intelligence into Strategy
The Worldwide Ethane Market research report provides a rigorous, forward-looking foundation for navigating the 2026 to 2032 period. It quantifies market size progression, clarifies the role of source and application segmentation, situates regional growth within infrastructure and trade developments, and profiles the competitive players whose decisions will shape the market’s trajectory. Equally important, it does so in a format that supports real-world use: budgeting, capacity planning, supply chain optimization, export strategy, and competitive benchmarking.
To move from strategic awareness to execution-ready intelligence, readers are encouraged to consult the full report and access the detailed segmentation breakdowns, regional growth narratives, competitor assessments, and scenario commentary that underpin the conclusions summarized here. The complete analysis preserves the quantitative depth, regional specificity, and application-level detail required to support confident decisions in a market where timing, infrastructure access, and feedstock strategy increasingly determine long-term competitive outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Ethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automated Poly Bagging Machines Market to Hit $724.18M by 2032, 6.12% CAGR
By pmarketresearch, 2026-09-16
Navigating the Automation Imperative: Strategic Insights into the Global Automated Poly Bagging Machines Market (2026–2032)
The global packaging landscape is undergoing a structural transformation. Automated poly bagging machines are no longer peripheral fulfillment tools; they are central to throughput optimization, labor cost mitigation, and operational resilience across e-commerce, healthcare, food, and industrial supply chains. As organizations align capital allocation with multi-year growth trajectories, the Worldwide Automated Poly Bagging Machines Market has emerged as a critical decision vector for manufacturing leaders, packaging engineers, and supply chain executives.
Box Making Machines Market
This market research report is designed as a decision-grade intelligence asset for 2026 and beyond. It synthesizes historical demand patterns from 2020 through 2025 with a forward-looking forecast spanning 2026 to 2032, enabling stakeholders to stress-test capacity plans, evaluate competitive positioning, and prioritize technology investments with precision. The analysis is anchored in revenue metrics expressed in USD millions, providing a consistent financial baseline for cross-functional planning.
Market Trajectory and Strategic Baseline
Historical market sizing demonstrates a clear acceleration in automated poly bagging adoption. Between 2020 and 2025, the sector expanded from approximately 345.12 million USD to 478.45 million USD, reflecting a sustained shift away from manual and semi-automated workflows. This progression was not purely cyclical; it was reinforced by persistent labor constraints in warehousing and packaging operations, alongside the compounding effect of rising order volumes driven by e-commerce expansion and fulfillment speed expectations.
Looking ahead, the forecast period through 2032 indicates continued growth momentum, with the market projected to reach approximately 724.18 million USD. The implied compound annual growth rate of 6.12 percent underscores a durable, investment-grade trajectory rather than a transient demand spike. For 2026 specifically, the baseline revenue estimate sits near 510.08 million USD, offering a practical reference point for organizations budgeting equipment procurements, integration services, and automation roadmaps this year.
The strategic value of these figures lies not in isolated numbers, but in what they reveal about demand durability. The upward slope across the forecast horizon suggests that automation in poly bagging is becoming embedded into standard operating models rather than remaining a discretionary upgrade. Decision-makers who anchor their 2026 CAPEX and OPEX assumptions to this trajectory can better synchronize production capacity, service readiness, and supplier negotiations.
Segment Architecture and Decision Relevance
Automated poly bagging demand does not distribute uniformly across machine types, end users, or geographies. The report maps these structural splits to expose where scale, customization, and service intensity diverge. By machine orientation, the market reflects a pronounced tilt toward horizontal configurations, which capture the larger revenue share, while vertical systems maintain a meaningful presence for applications requiring compact footprints and specialized handling. Understanding this balance is essential for vendors tailoring product roadmaps and for buyers matching machine geometry to product profiles, line speeds, and facility constraints.
End-user segmentation further clarifies where automation value is being captured. E-commerce and fulfillment operations represent the largest demand pool, consistent with high-order volatility, rapid turnaround requirements, and the need for repeatable bagging consistency at scale. Apparel and accessories follow as a significant application layer, where variable product dimensions and presentation quality drive machine flexibility. Pharmaceuticals and medical applications contribute a distinct demand stream shaped by compliance, traceability, and controlled packaging environments. Food and beverage, along with industrial and hardware applications, round out the demand landscape with requirements tied to throughput reliability, material compatibility, and operational robustness.
Regional demand patterns reveal a broadly distributed global footprint rather than a single dominant corridor. North America, Europe, and Asia Pacific each represent substantial share pools, while Latin America and the Middle East and Africa contribute incremental but strategically relevant growth nodes. For multinational operators, this dispersion matters because service coverage, spare-parts logistics, and localized integration capabilities increasingly determine total cost of ownership. The report uses these structural insights to help readers identify where regional deployment strategies, channel partnerships, and localization decisions will create the strongest competitive advantage.
Worldwide Automated Poly Bagging Machines Market
Competitive Landscape and Strategic Positioning
The automated poly bagging market is characterized by a concentrated yet increasingly contested supplier base. The report’s competitive analysis centers on the concentration dynamics that shape pricing power, innovation velocity, and customer switching behavior. With a top-three concentration near 38.5 percent and a top-five concentration near 52.2 percent, the market reflects a core of established players flanked by specialized entrants and regional specialists. This structure rewards vendors that can combine throughput reliability, modular scalability, and strong after-sales ecosystems, while challenging incumbents to defend margin and differentiate on integration depth rather than specification alone.
Sealed Air, through its AUTOBAG brand, anchors a high-speed, scalable approach focused on mailers, bags, and pouches, with clear emphasis on labor reduction and throughput for poly bagging applications. Pregis complements this landscape with Sharp automated bagging machines designed for e-commerce, retail, and healthcare environments, positioning compatibility with poly mailing solutions as a fulfillment efficiency lever. PAC Machinery’s Rollbag line extends automatic bagging into paper and poly mailer applications, including tabletop models integrated with printing capabilities that directly address e-commerce branding and tracking needs.
Advanced Poly-Packaging, Inc. brings long-standing specialization to the segment, offering tabletop and high-speed automatic baggers such as the T-1000 and T-300 series, reinforcing the importance of application depth and operator familiarity in niche but consistent demand pockets. Rennco focuses on vertical automatic bagging solutions for poly-bagged products, including electric models like the EZ20, which highlight compact, versatile operation for facilities with space or flexibility constraints. Audion contributes a high-speed bagging and labelling perspective through its Speedpack automatic baggers, supporting both paper and poly bag workflows where line integration and labeling efficiency are priorities.
PackSmart distributes Sharp-based automated bagging systems across industrial, e-commerce, pharma, and medical applications, illustrating how channel and integration partners can extend reach across multiple end-user segments. Tension Packaging & Automation addresses product variability through HPS variable length polybagging machines, particularly relevant for clothing and soft goods where item dimensions fluctuate and setup agility matters. Impackt Packaging, via its SwiftPack line, emphasizes rapid automatic poly bagging machines with conveyors built in the USA for high-volume operations, reinforcing the demand for domestically manufactured throughput solutions. WeighPack broadens the application envelope with poly bag packing machines such as Bingo Bagger, VS Bagger, and Zippy Bagger, serving food, hardware, and other product categories where machine versatility and operational simplicity are valued. Bagmatic rounds out the competitive field by offering semi- and fully automated bagging machines, including systems sourced from Advanced Poly Packaging, demonstrating how reseller and integrator models can bridge equipment capability with regional service requirements.
Recent product and exhibition activity confirms that innovation is proceeding on multiple fronts. PAC Machinery showcased the Rollbag R785 tabletop automatic poly bagger with thermal transfer printing and broader flexible packaging solutions at Pack Expo Southeast, signaling increased attention to compact, value-added unit operations. Rennco presented the new electric EZ20 bagging solution for poly-bagged products at PACK EXPO International, reinforcing momentum around electric actuation, compactness, and versatile deployment. These developments matter for 2026 decision-makers because they illustrate how machine vendors are expanding functionality, reducing footprint, and aligning product launches with live buyer priorities rather than abstract technology roadmaps.
Operational Dynamics Shaping 2026 Investment Decisions
Beyond equipment specifications and supplier profiles, the report integrates the operational forces that determine whether automation projects deliver anticipated returns. Labor availability remains a defining constraint in packaging and warehousing. Persistent staffing friction increases the strategic appeal of automated poly bagging systems that reduce manual dependency while improving line consistency and throughput predictability. Organizations evaluating 2026 deployments are increasingly treating automation not as a cost center, but as a buffer against operational volatility and a lever for scalable fulfillment.
Material cost conditions also influence procurement timing and total cost modeling. Stainless steel, a core input for frames and machine components, has exhibited pricing dynamics that warrant attention in budgeting cycles; for example, China FOB prices were reported around 2,082 USD per metric ton in March 2026. While equipment selection is never driven by a single commodity input, awareness of material price trends helps procurement teams anticipate supplier pricing behavior, negotiate service agreements, and sequence capital purchases to align with cost environments.
E-commerce growth continues to amplify demand for high-speed automated poly bagging by increasing order volumes and expanding the range of variable packaging needs. Faster fulfillment expectations place pressure on lines to handle diverse product profiles without sacrificing speed or repeatability. This dynamic favors machines that can adapt to variable lengths, integrate with downstream labeling or printing functions, and support rapid changeover. For 2026 planning, the operational implication is clear: automation decisions should be evaluated against fulfillment elasticity, changeover efficiency, and integration readiness, not merely headline speed ratings.
What the Report Delivers for Decision-Makers
This research is structured to support practical, high-stakes decisions rather than abstract market commentary. The report provides a comprehensive market size and forecast framework that links historical performance to forward projections, allowing organizations to benchmark internal growth assumptions and identify divergence points. It includes segmentation analysis across machine orientation, end-user application, and regional demand to help leaders match investment theses to the most relevant demand pools.
The competitive landscape section moves beyond company listings to examine concentration, positioning, and the strategic implications of supplier diversity. It interprets recent product launches, trade-show activity, and application focus areas as indicators of where the market is heading and which capabilities are becoming table stakes. In parallel, the operational dynamics analysis ties labor constraints, material cost awareness, and e-commerce-driven fulfillment pressure into a cohesive decision context, enabling readers to weigh automation benefits against implementation risk and total cost of ownership.
For vendors, the report offers a structured view of demand distribution, competitive intensity, and application prioritization. For buyers and integrators, it provides a basis for evaluating machine families, aligning procurement timelines with cost and labor dynamics, and identifying where service coverage and integration support will matter most. For investors and strategic planners, it delivers a market-level narrative grounded in measurable sizing, forecast assumptions, and concentration indicators that can inform portfolio and partnership decisions.
Recommended Strategic Actions for 2026
- Align 2026 automation budgets with the forecast trajectory, using the market baseline as a reference for capacity planning and phased investment rather than single-cycle procurement.
- Match machine orientation and end-user application analysis to internal product portfolios, prioritizing configurations that address throughput, footprint, and changeover requirements specific to your SKUs.
- Evaluate supplier options against concentration dynamics and service ecosystems, since installation, maintenance, and parts availability increasingly shape long-term operational value.
- Incorporate material cost awareness and labor availability into total cost models, ensuring that automation ROI reflects current input conditions and workforce constraints.
- Use regional demand distribution to inform rollout sequencing, channel partnerships, and localized support strategies where expansion or replacement programs are planned.
Conclusion
The Worldwide Automated Poly Bagging Machines Market is entering a phase where strategic planning and equipment selection must be tightly coupled to durable demand drivers, competitive concentration, and operational realities. The 2026 to 2032 forecast window offers a structured opportunity to move beyond reactive purchasing and toward disciplined automation investment. This report translates macro growth signals, segmentation structure, competitive maneuvering, and dynamic market forces into a coherent intelligence base for 2026 decision-making. For organizations seeking the detailed segmentation figures, company-level profiles, forecast assumptions, and application-specific breakdowns that underpin these strategic conclusions, the full market research provides the complete analytical foundation required to act with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Automated Poly Bagging Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Pet Food Delivery Revenue Hits $6.48B in 2025, Projected 10.51% CAGR to $13B by 2032
By pmarketresearch, 2026-09-16
Global Pet Food Delivery Market 2026: Strategic Imperatives in a High-Growth Subscription Economy
The worldwide pet food delivery market has transitioned from a discretionary convenience to a core distribution channel for the broader pet care industry. Over the past half-decade, structural shifts in consumer purchasing behavior, advancements in cold-chain logistics, and the maturation of recurring revenue models have fundamentally reshaped how pet nutrition reaches households. For executives, investors, and category managers navigating 2026, understanding the mechanics of this shift is no longer optional. It is a prerequisite for capital allocation, supply chain redesign, and competitive positioning.
This deep-dive analysis draws from our newly released Worldwide Pet Food Delivery Market research to outline the strategic landscape shaping the 2026–2032 forecast period. Rather than offering a superficial overview, the study dissects the operational, regulatory, and competitive forces driving sustained expansion. Below, we preview the critical insights that matter most for enterprise decision-making, while preserving the granular segmentation, pricing architectures, and regional breakdowns exclusively available in the full report.
Market Trajectory: A Decade of Accelerating Adoption and Forecasts Through 2032
The market's historical trajectory reflects a compounding adoption curve that accelerated sharply between 2020 and 2025. Revenue expanded from approximately 3,520.45 million USD in 2020 to 6,480.0 million USD by 2025, signaling a structural migration away from episodic, in-store purchasing toward recurring, digitally mediated fulfillment. This momentum carries directly into the forecast window: the market is projected to reach 7,184.13 million USD in 2026 and continue scaling toward 13,043.27 million USD by 2032.
The compound annual growth rate of 10.51% across the 2026–2032 horizon underscores a market that is compounding rather than merely recovering. Several underlying drivers sustain this trajectory. First, the normalization of subscription-based consumption has reduced purchase friction and elevated customer lifetime value across demographic segments. Second, premiumization trends in pet humanization have shifted spend toward specialized, fresh, and veterinarian-endorsed formulations that align naturally with recurring delivery models. Third, logistics networks have matured enough to support cold-chain and temperature-controlled fulfillment at scale, unlocking product categories that were previously constrained by retail shelf limitations.
For strategic planners, the forecast period presents both expansion opportunity and execution risk. Companies that treat delivery as a pure distribution add-on will likely cede share to operators who have embedded fulfillment architecture into their brand identity, pricing strategy, and unit economics. The full report quantifies the inflection points across product formats, subscription maturity curves, and geographic adoption differentials, enabling leadership teams to calibrate investment timing rather than react to market shifts after they materialize.
Structural Shifts Reshaping Delivery Economics and Consumer Behavior
The pet food delivery ecosystem is being reengineered by intersecting forces that alter cost structures, compliance requirements, and competitive moats. Understanding these dynamics is essential for scenario planning in 2026.
Regulatory Compliance as a Competitive Filter
Regulatory frameworks have moved from background compliance to front-line strategic considerations. In the European Union, Regulation (EU) 2023/2345 mandates clear nutritional labeling on all pet food packaging, including products sold through delivery channels, with compliance effective from January 2024. This requirement compels operators to align packaging, digital product pages, and fulfillment documentation with standardized transparency expectations. Meanwhile, in the United States, the FDA continues to require AAFCO nutrient profile compliance across delivery channels, with 2025 updates refining taurine level requirements to support cardiac health. These updates directly affect formulation strategies, supplier qualification, and quality assurance workflows for brands distributing through subscription or direct-to-consumer pipelines.
Operators that treat regulatory adherence as a periodic checklist often face costly rework, delayed listings, or formulation adjustments late in the product lifecycle. By contrast, organizations that integrate compliance architecture into product development and logistics planning can reduce time-to-market friction and strengthen consumer trust through transparent nutritional communication.
Input Cost Volatility and Supply Chain Configuration
Ingredient pricing and trade policy remain central to margin management. Global corn prices, a foundational input across multiple pet food categories, averaged 198 USD per metric ton in the fourth quarter of 2025 amid relatively stable supply conditions. While short-term stability provides planning visibility, the broader procurement environment remains sensitive to agricultural output variability, energy costs, and regional trade dynamics.
Compounding this sensitivity, US-China tariffs on pet food imports remain at 25% under Section 301, directly affecting delivery supply chains that rely on Asian-sourced ingredients or intermediate components. For operators with cross-border sourcing footprints, the tariff structure influences supplier diversification strategy, domestic manufacturing investment, and inventory positioning. Companies that proactively map ingredient origin, lead-time variability, and tariff exposure can build more resilient procurement architectures, while those with concentrated sourcing may encounter margin compression or fulfillment delays during trade policy shifts.
Segmentation Architecture: Food Type and Subscription Models
The market's composition reflects a divergence between traditional shelf-stable formats and the rapidly expanding premium fresh segment. Dry pet food continues to represent a substantial share of delivered volume, supported by established brand portfolios and efficient logistics economics. Wet pet food maintains a strong presence among consumers prioritizing moisture content, palatability, and specific dietary needs. Fresh and customized food has emerged as the most strategically dynamic category, driven by humanization trends, veterinary-backed formulation narratives, and the operational fit between subscription frequency and refrigerated fulfillment.
On the commercial model side, the market demonstrates a clear tilt toward recurring revenue. Subscription-based delivery accounts for a majority share of market value, reflecting the durability of autoship programs, personalized replenishment schedules, and loyalty-linked fulfillment incentives. One-time purchase transactions remain relevant, particularly for trial purchases, supplementary items, and same-day urgency fulfillment, but they generally contribute less to long-term retention economics. The strategic implication is consistent across categories: companies that can synchronize product design, packaging, and logistics with subscription cadence are better positioned to stabilize demand forecasting, reduce customer acquisition amortization, and build defensible retention loops.
The full report provides a detailed breakdown of these splits and their interaction with pricing tiers, channel mix, and regional purchasing patterns. This level of segmentation detail is critical for operators evaluating whether to expand into fresh formats, adjust autoship incentives, or restructure fulfillment partnerships.
Competitive Landscape: Leadership, Positioning, and Recent Strategic Moves
The competitive environment is defined by a mix of large-scale omnichannel retailers, e-commerce platforms, and specialized direct-to-consumer brands. Market concentration reflects meaningful share held by a limited group of scaled players, with the top three firms capturing approximately 32.4% of market revenue and the top five reaching roughly 45.6%. This concentration indicates that scale advantages in logistics, brand portfolio breadth, and customer data infrastructure matter significantly, while still leaving room for specialized operators that compete on formulation quality, personalization, and category expertise.
Scaled Retail and E-Commerce Platforms
Chewy, headquartered in Plantation, FL, remains a leading online retailer for direct-to-consumer pet food delivery. Its autoship subscription covers dry kibble, wet food, treats, and raw diets across major brands such as Purina and Blue Buffalo. In October 2025, Chewy expanded its fresh pet food line with refrigerated delivery options in partnership with PetSmart Ventures, signaling an intent to deepen its presence in higher-complexity fulfillment categories while leveraging external venture alignment for capability acceleration.
Petco, based in San Diego, CA, provides nationwide pet food delivery through its Vital Care subscription and same-day options, carrying premium brands including Hill's Science Diet and Wellness. In September 2025, Petco introduced unlimited free pet food delivery for Vital Care members, covering more than 5,000 SKUs. This move illustrates how subscription health and fulfillment incentives are being used to reinforce membership economics and reduce churn through perceived value expansion.
PetSmart, headquartered in Phoenix, AZ, offers delivery via its Autoship program with free shipping on orders over 49 USD, incorporating fresh and frozen meals from partners such as JustFoodForDogs. Its strategy highlights the continued relevance of brick-and-mortar-anchored brands extending into recurring digital fulfillment, using partner networks to broaden premium offerings without vertically building every capability in-house.
Amazon, headquartered in Seattle, WA, delivers pet food through Subscribe & Save and Prime fast shipping, featuring private-label brands like Wag! alongside third-party kibble options. Its advantages stem from nationwide fulfillment density, customer reach, and the ability to bundle pet food delivery into broader household subscription ecosystems. For competing brands, Amazon's presence raises the baseline for delivery speed, pricing transparency, and convenience expectations.
Instacart, based in San Francisco, CA, delivers pet food from grocery chains such as Kroger and Costco within hours, supporting same-day pet supply fulfillment. Its role in the market is distinct: rather than operating as a dedicated pet brand, it functions as an on-demand bridge between traditional grocery inventory and immediate household need, capturing urgency-driven purchases and expanding the definition of delivery beyond subscription replenishment.
Specialized Fresh and Direct-to-Consumer Operators
HelloFresh's pet division, operating from Berlin, Germany, manages The Farmer's Dog brand for fresh, human-grade pet food delivered weekly via subscription boxes in the US. In June 2025, The Farmer's Dog opened a new production facility in Columbus, OH to increase fresh pet food delivery capacity by 50%, reinforcing the strategic importance of production scale in sustaining growth for fresh-format subscription brands.
Ollie, headquartered in New York, NY, operates a direct-to-consumer fresh pet food delivery service that customizes recipes based on pet profiles and ships nationwide. Its positioning demonstrates how personalization and veterinary-aligned nutrition narratives can differentiate subscription offerings in a category where consumers are increasingly attentive to ingredient transparency and individual pet needs.
Pet Food Market
Nom Nom, based in San Francisco, CA, delivers veterinarian-formulated fresh pet meals monthly, focusing on nutritionally complete wet food portions. Its approach underscores the continued relevance of formulation expertise and portion design as differentiators, particularly for consumers seeking structured nutritional completeness rather than generalized premium branding.
Collectively, these competitive profiles reveal a marketplace where advantage is increasingly determined by the integration of formulation capability, recurring delivery economics, cold-chain execution, and customer retention design. The full report extends this analysis with a structured competitive benchmarking framework, examining positioning across fulfillment speed, brand portfolio breadth, subscription architecture, and regional service coverage.
What the Full Report Delivers for 2026 Decision-Making
This preview establishes the strategic terrain, but the operational and quantitative depth required for planning resides in the complete research package. The Worldwide Pet Food Delivery Market study is designed to support concrete decisions across strategy, operations, finance, and marketing functions. The report moves beyond high-level sizing to provide an actionable framework for evaluating where to invest, what to optimize, and how to respond to competitive and regulatory pressure.
Inside the full report, readers will find:
- A comprehensive market model spanning historical performance from 2020 to 2025 and a detailed forecast through 2032, anchored in consistent methodology and expressed in USD million.
- Segment-level analysis across food type categories and commercial delivery models, revealing how product format and subscription structure interact with growth dynamics and unit economics.
- Regional evaluation covering North America, Europe, Asia Pacific, and the Rest of the World, with context on adoption maturity, service density, and category preferences that shape localized go-to-market strategy.
- Competitive profiling of key market participants, including operating models, brand portfolios, fulfillment approaches, and recent strategic developments that indicate near-term trajectory.
- Structural market dynamics, including regulatory requirements, ingredient cost context, and trade policy exposure, integrated into the broader interpretation of market opportunity and risk.
- Strategic implications for subscription design, fresh-format expansion, supply chain configuration, and competitive positioning, enabling leadership teams to translate market data into operational priorities.
The purpose of this document is to demonstrate the rigor and applicability of the research while preserving the specific segmentation figures, regional revenue breakdowns, and detailed company-level indicators for the full report. Those data points matter because they convert broad market momentum into actionable investment logic. A company evaluating entry into fresh pet food delivery, for example, needs more than overall growth trends; it needs to understand how category economics vary by format, how subscription retention differs across customer profiles, and how regulatory and sourcing constraints shape feasible operating models in specific markets.
Conclusion: Positioning for the Next Phase of Market Expansion
The worldwide pet food delivery market is entering a phase where growth is increasingly determined by execution quality rather than category tailwinds alone. The forecast trajectory to 2032 points to continued expansion, but the companies that capture disproportionate value will be those that align subscription design, fulfillment capability, formulation strategy, and compliance discipline into a coherent operating model.
For 2026 planning, the strategic questions are already taking shape. How should a brand balance dry, wet, and fresh offerings within its delivery portfolio? What subscription incentives genuinely improve retention without eroding margin? Where do sourcing and tariff exposures create vulnerability, and how should procurement architecture adapt? Which competitive positions are defendable in a market where scale and specialization both matter?
These questions require more than directional insight. They require segment-level quantification, regional nuance, and competitive context that can be directly mapped to operational decisions. The complete Worldwide Pet Food Delivery Market research is built to provide that intelligence, giving executives a structured foundation for investment prioritization, channel strategy, and long-range planning.
Worldwide Pet Food Delivery Market
The market's next chapter will reward organizations that treat delivery not as a tactical channel, but as a strategic system. For decision-makers preparing for 2026, the full report offers the depth required to move from awareness to action with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Pet Food Delivery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Yeast Derivatives Market to Reach $4,775.66M by 2032, Growing at 7.0% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Yeast Derivatives Market: Navigating Growth from 2026 to 2032
The global yeast derivatives market stands at a pivotal inflection point. As manufacturers, formulators, and ingredient suppliers recalibrate their portfolios for the next decade, the need for precise, forward-looking intelligence has never been more acute. Our latest Worldwide Yeast Derivatives Market research report delivers a comprehensive, data-grounded view of an industry that is expanding steadily while undergoing rapid structural transformation. This briefing synthesizes the report’s core findings to equip executive teams, commercial strategists, and R&D leaders with the strategic context required to make informed decisions in 2026 and beyond.
Drawing on a multi-year historical baseline and an extended forecast horizon through 2032, the analysis captures both the steady momentum of established value chains and the disruptive forces reshaping supply networks, product formulations, and competitive positioning. Rather than offering static snapshots, the study maps the mechanics of growth: how raw material economics influence production viability, how regulatory frameworks shape application boundaries, and how consolidation and product innovation are redrawing the competitive map.
Macro Trajectory and Forward Outlook
The market has demonstrated consistent expansion across the historical review period, moving from approximately 2,120 million USD in 2020 to an estimated 2,974 million USD by 2025. This trajectory reflects sustained demand across food and beverage formulation, animal nutrition, and an expanding suite of pharmaceutical and biotechnological applications. Building on this base, the forecast period projects a compound annual growth rate of roughly 7.0 percent, with global revenue expected to progress from the 3,163 million USD range in 2026 toward higher plateaus as the decade advances.
Such headline figures, however, only tell part of the story. The true strategic signal lies in the underlying dispersion of growth drivers. Demand is not expanding uniformly; it is being pulled by specific functional requirements, reformulation trends, and regional supply chain recalibrations. The report deconstructs these dynamics across multiple lenses, allowing decision-makers to distinguish between cyclical surges and structural shifts. In an environment where capital allocation and capacity planning require precision, understanding which segments will absorb incremental volume and which will face margin compression is essential.
For organizations evaluating 2026 priorities, the forecast framing is particularly valuable. It situates near-term investment horizons within a longer arc of market maturation, helping leaders differentiate between opportunistic short-term moves and durable competitive advantages. The analysis also highlights the influence of upstream feedstock dynamics on production economics. Molasses remains the primary substrate for yeast cultivation and derivative manufacturing. Pricing volatility, compositional variability, and seasonal availability all feed directly into cost structures and yield efficiency. Recent market observations place molasses pricing in the US market around 295 USD per metric ton during late 2025, reflecting relatively stable supply from sugar processing channels. Yet the sensitivity of yeast growth productivity to substrate fluctuations means that forward-looking procurement and hedging strategies are becoming integral to maintaining cost competitiveness.
Yeast Market
Report Architecture and Actionable Deliverables
The research is structured to support practical decision-making across commercial, operational, and strategic functions. Rather than presenting isolated statistics, the report integrates quantitative sizing with qualitative scenario analysis to help teams stress-test assumptions and align cross-functional roadmaps.
Key components of the study include:
- Detailed segmentation views that break down market value by product type, application, and geographic region, enabling targeted portfolio assessment and go-to-market positioning.
- Comparative analysis of growth vectors, including the relative contribution of mainstream applications versus higher-value niche uses, with attention to formulation trends and ingredient substitution patterns.
- Supply-side evaluation covering production capacity trends, facility expansion activity, and the operational implications of substrate cost movements on derivative manufacturing.
- Regulatory and compliance mapping, including the role of food safety classification frameworks in shaping market access, formulation limits, and product positioning across major jurisdictions.
- Competitive landscape profiling that examines concentration dynamics, strategic moves, and the positioning of leading multinational and regional players.
- Forecast sensitivity and scenario discussion to support sensitivity testing around demand elasticity, input cost variance, and capacity utilization.
Throughout the report, analysts avoid oversimplified aggregations. Instead, the methodology prioritizes transparency around assumptions, data sources, and segmentation logic. This approach allows readers to trace how conclusions are derived and to adapt the insights to their own operational contexts. For instance, a formulation company seeking clean-label alternatives can use the application-level analysis to gauge adoption velocity and pricing tolerance, while a producer evaluating capacity additions can draw on the type-level and regional breakdowns to identify demand pockets with the strongest pull.
Competitive Landscape and Strategic Concentration
The yeast derivatives sector is characterized by a blend of established global incumbents, specialized ingredient specialists, and regionally anchored producers that have expanded their footprints through investment and acquisition. Market concentration metrics indicate a moderately consolidated environment, with the top three players accounting for a significant share of total industry revenue and the top five firms representing a substantial majority. This concentration has implications for pricing power, supply reliability, and the pace at which innovation diffuses through the value chain.
Among the organizations profiled in the study, several stand out for their strategic breadth and active portfolio management. Lesaffre Group, headquartered in France, operates as a global leader across yeast and derivative categories, including extracts, autolysates, beta-glucans, and nucleotides for food, feed, and nutrition applications. Its recent expansion through a major acquisition of a controlling stake in Biorigin’s relevant business unit underscores a deliberate push to strengthen capacity in yeast-derived savory ingredients and specialty solutions. Angel Yeast Co., Ltd., based in China, has been scaling its international footprint while deepening R&D in fermentation technology. The company’s recent product launches introduce yeast-based flavor variants with floral and buttery profiles aimed at natural flavor enhancement, complementing a concurrent capacity expansion initiative for specialty products in China.
Lallemand Inc. of Canada continues to emphasize yeast derivatives spanning extracts, cell wall components, and bioactive compounds for baking, brewing, animal nutrition, and human health, maintaining a recognized presence in probiotic and specialty yeast solutions. On the savory flavor side, Associated British Foods plc through its subsidiary operations focuses on yeast extracts and autolysates that serve taste enhancement and nutritional functions in food processing. Koninklijke DSM N.V., now operating under the DSM-Firmenich framework in the Netherlands, supplies high-purity extracts and functional components across nutrition, food, and biotechnology applications. Kerry Group plc in Ireland contributes yeast extracts as natural flavor enhancers and umami ingredients, aligning with reformulation trends that favor clean-label and plant-compatible taste solutions. Leiber GmbH in Germany specializes in brewers’ yeast derivatives, cell walls, and extracts for food, feed, and pharmaceutical-grade contexts, while Alltech Inc. in the United States supplies extracts and cell wall products with a strong orientation toward animal nutrition and feed additives.
Additional notable participants include Chr. Hansen A/S, now integrated within Novonesis, which develops microbial solutions and yeast derivatives for food cultures and natural ingredients; AB Mauri, which concentrates on baking and specialty yeast derivatives with global production capabilities; and Pak Group in Turkey, which produces yeast and derivatives for baking and industrial applications with a regional and export-oriented strategy. Together, these organizations illustrate the diversity of positioning within the market: some compete primarily on scale and supply reliability, others on functional specificity or application-focused innovation.
Recent Industry Moves Shaping the 2026 Landscape
Strategic activity over the past year signals a market in motion. Consolidation and capability-building transactions are accelerating as companies seek to secure access to differentiated ingredients, expand production capacity, and deepen application expertise. In mid-2025, a major European yeast and derivatives leader completed a transaction to acquire a controlling interest in a business unit focused on yeast-derived savory ingredients, reinforcing its ability to serve flavor and specialty solution demand. Around the same time, a leading Chinese producer introduced a new line of yeast-based flavor variants designed to broaden natural taste options, reflecting continued investment in formulation innovation. By the end of 2025, that same organization had initiated trial production at a new specialty plant designed to support higher-volume output of targeted product lines.
Separately, a prominent brewers’ yeast specialist was acquired by a global food group to expand its international presence and broaden access to derivative-based applications across food and feed channels. These moves collectively highlight three themes that the report examines in greater depth: the premiumization of functional ingredients, the geographic rebalancing of supply capacity, and the growing importance of differentiated taste and nutrition attributes in end-product formulation.
Regulatory and Standards Frameworks as Market Enablers and Constraints
Regulatory classification and safety recognition play a defining role in how yeast derivatives are positioned and adopted. In the United States, yeast extracts are generally recognized as safe for use as flavoring agents and nutrient enhancers in food products, providing a relatively stable pathway for inclusion in a wide range of applications. In Europe, producers operate under stringent food additive oversight and benefit from Qualified Presumption of Safety status for Saccharomyces-based products, which supports market access while also requiring rigorous documentation and quality assurance practices. These frameworks are not merely compliance hurdles; they shape formulation strategies, labeling approaches, and the speed at which new ingredients can be introduced to specific categories.
The report’s regulatory review connects these standards to commercial implications, including the relative ease of market entry for certain derivative types, the potential for reformulation-driven demand shifts, and the operational requirements that differentiate commodity-grade offerings from higher-specification functional ingredients. For suppliers and buyers alike, understanding how regulatory environments vary by region and application is a prerequisite for reliable forecasting and product planning.
Segmentation Insights Without Compromising Analytical Depth
To support precise decision-making, the study provides segmentation views across product types, applications, and regions. In terms of product categories, yeast extracts represent the largest share of market value, followed by autolyzed yeast, yeast cell wall ingredients, and other derivative types. Each category carries distinct functional attributes and application relevance: extracts are widely utilized for flavor and nutrition enhancement, autolyzed forms serve both taste and functional roles, cell wall components are valued in animal nutrition and specialized health applications, and other derivative types address niche formulation needs.
Application-wise, food and beverages dominate total market value, reflecting the breadth of formulation use cases and the ongoing push toward natural taste and texture improvement. Animal feed forms the second major application channel, driven by nutritional additives and functional feed ingredients. Pharmaceuticals and biotechnology account for a smaller but strategically important share, with growth tied to specialized functional components and high-purity requirements. A remaining set of applications encompasses additional industrial and specialty uses.
Regionally, Europe, North America, and Asia Pacific each represent substantial portions of total market value, with Latin America and the Middle East and Africa contributing complementary demand. The report examines these regional profiles not as static shares but as evolving ecosystems shaped by local formulation habits, procurement structures, regulatory environments, and capacity distribution. For 2026 planning, these regional nuances matter: growth opportunities are rarely uniform, and the most effective strategies typically align product positioning and supply planning with regional demand characteristics rather than relying on global averages alone.
Strategic Implications for 2026 Decision-Making
The convergence of sustained top-line growth, active consolidation, raw material sensitivity, and regulatory clarity creates a market environment where informed differentiation can yield durable advantages. The report is designed to help organizations translate market intelligence into concrete actions across several strategic dimensions.
First, portfolio and product strategy can be sharpened by understanding how demand is distributed across categories and applications. Companies can prioritize incremental investment in segments where functional benefits align with end-market reformulation trends, while selectively managing exposure to segments facing cost pressure or substitution risk. Second, supply chain and procurement planning can be strengthened by incorporating substrate cost dynamics and capacity expansion timelines into scenario models, reducing the likelihood of margin surprises. Third, competitive positioning can be refined by mapping how leading players are aligning production footprint, innovation pipelines, and application expertise, enabling more targeted differentiation rather than broad-based competition.
Finally, the forecast period through 2032 provides a long-enough horizon to evaluate capacity decisions, partnership opportunities, and innovation roadmaps against realistic demand trajectories. In a market where multiple routes to growth exist, the ability to distinguish between high-conviction opportunities and marginal gains is a decisive advantage.
This Worldwide Yeast Derivatives Market research report offers the analytical foundation required to make those distinctions with confidence. By combining rigorous sizing, segmentation logic, competitive profiling, and forward-looking scenario discussion, it equips commercial and strategic teams to act decisively in 2026 and to prepare for the structural shifts that will define the remainder of the decade. For the complete dataset, detailed segmentation tables, company profiles, and region-specific forecasts, please access the full report through our official publication page.
Worldwide Yeast Derivatives Market
For detailed analysis of this topic, please visit the official page: Worldwide Yeast Derivatives Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Calming Food Market Hits $415M in 2025, 7.95% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Pet Calming Food Market: Navigating Growth and Competition in 2026
The global pet care industry is undergoing a profound transformation driven by the humanization of animals and a heightened focus on welfare beyond basic nutrition. Among the most dynamic segments emerging from this shift is the market for pet calming food and supplements. As anxiety management becomes a priority for pet owners, companies must navigate a complex landscape of ingredient innovation, regulatory compliance, and intensifying competition. Our latest market research report provides a comprehensive analysis of this sector, offering the strategic depth required for informed decision-making throughout the forecast period.
For executives planning capital allocation and product development strategies in 2026, understanding the trajectory of this market is essential. Below, we examine the key structural trends, competitive dynamics, and regulatory frameworks that will define the industry. This preview highlights the analytical rigor of our full study while demonstrating why our proprietary data is critical for maintaining a competitive edge.
Market Trajectory and Structural Growth Drivers
The pet calming food and supplements market has demonstrated consistent resilience and expansion over the past five years. Historical data reveals a steady upward trajectory, reflecting the sustained demand for functional pet nutrition aimed at behavioral health. As we move from the base year into the forecast horizon, the market is positioned to reach new valuation milestones driven by increased consumer awareness and premiumization trends.
Our analysis projects that the global market revenue will continue to expand through the end of the forecast period. This growth is not merely a continuation of past trends but is underpinned by specific structural drivers including the rise of veterinary prescription diets integrating calming ingredients and the mainstreaming of over-the-counter wellness chews. The compound annual growth rate indicates a healthy expansion pace that invites both established players and new entrants to capture value.
- Historical market valuation has shown robust progression, moving from early 2020 levels to significant valuation by the base year.
- The forecast period anticipates a notable acceleration in revenue generation, reflecting broader adoption of calming solutions.
- Key growth catalysts include the increasing prevalence of separation anxiety in pets and the growing willingness of owners to invest in preventive mental health solutions for their companions.
Ingredient Innovation and Product Form Diversification
The formulation landscape of pet calming foods is evolving rapidly. Manufacturers are moving beyond single-ingredient solutions to develop complex blends that target multiple pathways of stress response. Our report details the shifting preferences in product forms, highlighting how texture, palatability, and ease of administration influence consumer purchasing decisions.
Soft chews have emerged as a dominant format due to their high palatability and ability to mask functional ingredients effectively. This segment is gaining substantial share as owners prefer treats that pets enjoy while delivering therapeutic benefits. Concurrently, traditional formats such as treats and biscuits remain relevant, particularly for owners seeking shelf-stable options. Liquids and powders are also gaining traction, especially in veterinary contexts or for pets with specific dietary restrictions.
Pet Food Market
- Soft chews represent a leading share of the product form segmentation, driven by convenience and pet acceptance.
- Treats and biscuits continue to serve as a staple category, often leveraging familiar flavor profiles to enhance consumer trust.
- Liquids and powders offer specialized applications, particularly in formulations requiring precise dosing or integration into wet food diets.
On the ingredient front, the market is seeing a convergence of natural botanicals and scientifically backed compounds. L-theanine derived from green tea is widely utilized for its calming properties without sedation. L-tryptophan serves as a precursor to serotonin, supporting mood regulation. The inclusion of adaptogens such as KSM-66 ashwagandha is gaining momentum, supported by species-specific clinical backing. Herbal ingredients like chamomile and valerian root remain popular for their natural appeal, aligning with the clean label movement that dominates premium pet nutrition.
Competitive Landscape and Strategic Positioning
The competitive environment in the pet calming food market is characterized by a mix of multinational corporations and agile specialty brands. Market concentration analysis reveals that while the top players hold significant share, a substantial portion of the market remains fragmented, allowing for niche innovation and regional expansion. Our report provides a granular assessment of how these companies are leveraging product portfolios, distribution networks, and scientific credibility to differentiate themselves.
Nestlé Purina PetCare, headquartered in St. Louis, Missouri, exemplifies the strategy of integrating calming solutions within a broader veterinary and nutritional ecosystem. Their Pro Plan Veterinary Supplements Calming Care probiotic supplement highlights the trend toward science-backed formulations that address gut-brain axis interactions, positioning the brand as a trusted authority in behavioral health.
Zesty Paws, based in Orlando, Florida, has established a strong presence in the consumer direct space with products like Calming Bites and Advanced Calming Bites. Their approach emphasizes ingredient transparency and consumer education, appealing to owners seeking natural support for stress and anxiety relief in dogs.
Pet Honesty, operating in the USA, has carved a niche by specializing in hemp-based calming chews and supplements that utilize natural ingredients such as valerian root and chamomile. Their product line caters to the growing demand for plant-derived solutions, aligning with wellness trends that span both human and pet nutrition.
Boops Pets has recently demonstrated aggressive innovation with the launch of KSM-66 Ashwagandha Calming Soft Chews for dogs. This product leverages adaptogens and is formulated with species-specific clinical backing for stress relief. The launch underscores the importance of third-party auditing and quality assurance, as evidenced by NASC compliance, which is becoming a critical differentiator in a market sensitive to safety and efficacy claims.
Virbac, with global operations and US headquarters in Texas, markets Anxitane with L-theanine, showcasing the veterinary channel's role in distributing clinically recognized ingredients. Their strategy reflects a focus on professional endorsement and efficacy validation.
NaturVet, associated with GARMON CORP., offers a broad portfolio of calming treats and supplements for pet anxiety management, targeting a wide range of価格 points and pet needs. Ceva Animal Health, based in France with global operations, provides pheromone-based calming solutions and relaxing snacks, illustrating the diversification of modalities beyond ingestion-based products to include environmental and sensory interventions.
Recent developments highlight the pace of activity in this sector. In March 2026, Boops Pets launched its KSM-66 Ashwagandha Calming Soft Chews, emphasizing NASC-audited quality and clinical backing. In April 2026, Kradle announced a nationwide retail launch of Daily Calming Chews, Calming Bliss Bars, and Nighttime Calming Chews at Petco stores, signaling the expansion of calming products into major retail channels and the introduction of format variations such as bars to capture additional consumption occasions.
Regulatory Environment and Industry Dynamics
Regulatory compliance is a cornerstone of market stability and consumer trust in the pet calming food sector. Products are regulated as food under AAFCO and FDA guidelines, which imposes strict requirements on labeling accuracy and safety standards while prohibiting disease treatment claims. This framework necessitates careful communication strategies to ensure that marketing messages align with regulatory boundaries, focusing on support and wellness rather than therapeutic outcomes.
Quality assurance mechanisms are increasingly visible to consumers and retailers. The NASC Quality Seal is utilized by manufacturers as a marker of third-party auditing and quality assurance, providing reassurance regarding ingredient purity and manufacturing practices. As recalls can impact brand reputation and market confidence, adherence to rigorous standards is not only a compliance obligation but a strategic imperative. For instance, industry reports noted a voluntary recall of certain soft chew products in April 2025 due to potential contamination risks, underscoring the importance of supply chain control and batch testing in maintaining market integrity.
Strategic Imperatives for 2026 and Beyond
For companies operating in or entering the pet calming food market, the path to value creation requires a multifaceted strategy. First, product development must be grounded in scientific validation and ingredient efficacy. Investments in clinical backing, such as species-specific studies for adaptogens or amino acids, can command premium pricing and foster deeper consumer trust. Second, distribution channel optimization is critical. The expansion of calming products into mass retail and veterinary channels presents opportunities for scale, but requires distinct branding and educational approaches tailored to each channel's decision-makers and end users.
Third, regulatory agility and quality transparency should be embedded in corporate culture. Proactive compliance with AAFCO and FDA guidelines, coupled with visible quality certifications like the NASC Quality Seal, can mitigate risk and enhance brand equity. Fourth, monitoring the competitive landscape is essential. With brands like Nestlé Purina, Zesty Paws, Pet Honesty, Boops Pets, Virbac, NaturVet, and Ceva Animal Health all competing on different axes of innovation, price, and channel access, companies must identify their unique value proposition and defend it through consistent execution.
Finally, understanding the segmentation of the market by region and pet type is vital for resource allocation. While global trends provide a macro view, regional preferences, regulatory nuances, and pet ownership demographics can vary significantly. Our full report provides the detailed breakdowns necessary to tailor strategies to specific markets, including insights into the relative performance of dogs versus cats and the varying demands across geographic zones.
Pet Calming Food Market
Why This Report Is Essential for Decision-Makers
The pet calming food market is at a pivotal moment where growth potential intersects with increasing complexity. Companies that rely on fragmented data or generic industry summaries risk misallocating resources or missing emerging opportunities. Our market research report delivers the precision and depth required to navigate this environment with confidence. It covers historical performance, forecast trajectories, segmentation analysis, competitive profiling, and regulatory context, all synthesized to support strategic planning for 2026 and the years ahead.
Readers seeking to unlock the full value of this analysis are encouraged to access the complete report. The detailed breakdowns of market size by region, product form, and application, along with comprehensive company profiles, recent developments, and dynamic industry intelligence, are available in the full publication. This preview illustrates the quality and scope of our research, but the actionable intelligence needed for precise budgeting, product roadmap planning, and competitive response resides in the complete dataset and expert commentary provided in the final deliverable.
For detailed analysis of this topic, please visit the official page: Pet Calming Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Data Center Optical Module Market to Hit $47.9B by 2032 at 16.48% CAGR
By pmarketresearch, 2026-09-16
Strategic Intelligence for the AI Infrastructure Era: Inside the Worldwide Data Center Optical Module Market to 2032
The modern data center is no longer a static repository of information. It has evolved into a high-performance computational engine, driving artificial intelligence training, real-time inference, and hyperscale cloud workloads that demand unprecedented bandwidth and energy efficiency. At the heart of this transformation lies the optical module, the critical interface that enables high-speed, low-latency connectivity across server racks, inter-facility links, and global networks. As enterprises navigate the complex intersection of AI adoption, power constraints, and geopolitical supply chain shifts, strategic decisions regarding optical connectivity infrastructure have become a defining competitive differentiator.
PW Consulting presents a comprehensive market research study, the Worldwide Data Center Optical Module Market, designed to equip executive leadership, procurement strategists, and industry investors with the actionable intelligence required to navigate this dynamic landscape from 2026 through 2032. This analysis offers a rigorous, data-driven examination of market trajectories, segmentation dynamics, competitive positioning, and the macro forces reshaping the optical interconnect ecosystem.
A Market Accelerating Beyond Traditional Growth Trajectories
The global market for data center optical modules has entered a period of sustained, high-velocity expansion, fundamentally outpacing historical growth patterns observed in earlier telecom and enterprise networking cycles. Historical data from 2020 through 2025 establishes a clear compound growth narrative, with revenue expanding from approximately 7,520 million USD to over 16,479 million USD by the base year of 2025. This trajectory reflects the rapid deployment of higher-speed interconnects driven by hyperscale cloud expansion, enterprise digital transformation, and the initial wave of AI cluster deployments.
Looking forward, the forecast period spanning 2026 to 2032 projects a steep acceleration, with the market anticipated to reach nearly 47,939 million USD by the terminal forecast year. This expansion is underpinned by a compound annual growth rate of 16.48 percent over the forecast horizon, a figure that underscores the structural, rather than cyclical, nature of current demand. The growth is not merely an extension of existing trends but a reflection of a fundamental architectural shift: the migration from 100G and 400G interconnects toward 800G, 1.6T, and beyond, coupled with the scaling of AI-driven computational infrastructure that requires dense, high-bandwidth fabric connectivity.
The Strategic Imperative for Decision-Makers in 2026
For enterprise architects, supply chain leaders, and capital allocators, the optical module market represents a critical nexus where technology roadmaps, cost structures, and risk management converge. In 2026, several overlapping forces elevate the strategic importance of this market intelligence:
- AI Infrastructure Scaling: The rollout of next-generation AI training and inference clusters demands interconnect solutions that can sustain multi-terabit throughput while minimizing latency and power consumption. Optical module selection directly influences overall system performance, thermal profiles, and total cost of ownership.
- Energy and Operational Cost Pressures: Electricity expenses typically consume around 40 percent of a large data center’s operating budget, amounting to approximately 7.4 million USD annually for large-scale operations. As data center electricity consumption in the United States reached 176 TWh in 2023, representing 4.4 percent of total U.S. electricity, and is projected to surge to between 325 and 580 TWh by 2028, the energy efficiency of optical transceivers and their associated signal processing architectures has become a board-level concern.
- Power Grid and Infrastructure Constraints: U.S. utility companies plan to invest 1.4 trillion USD over the next five years to update the power grid, driven in part by surging data center electricity demand. This infrastructure evolution will influence site selection, capacity planning, and the feasibility of large-scale optical interconnect deployments in key regional hubs.
- Geopolitical and Regulatory Complexity: U.S. export controls apply to advanced semiconductors, high-bandwidth memory, and related items used in data centers supporting AI model training or inference, particularly targeting certain countries. Simultaneously, governments are implementing data sovereignty laws and strategies to ensure control over data and AI infrastructure, influencing data center deployment patterns and optical connectivity requirements across regions.
These dynamics create a decision environment where intuition and legacy procurement models are insufficient. Leaders require granular visibility into how different data rate tiers, transmission distances, protocol ecosystems, and regional demand profiles will evolve, alongside a clear understanding of which suppliers are positioned to deliver scalable, compliant, and technically advanced solutions.
Coherent Optical Module Market
What This Research Delivers: A Practical Blueprint for Action
The Worldwide Data Center Optical Module Market report is structured to translate complex market data into operational guidance. Beyond macroeconomic sizing and growth forecasts, the study provides a detailed segmentation framework that enables stakeholders to evaluate demand across multiple dimensions critical to procurement, product planning, and investment strategy.
The analysis examines the market by region, capturing the distinct demand characteristics, infrastructure maturity, and deployment priorities that shape optical module consumption across North America, Asia Pacific, Europe, Latin America, and the Middle East and Africa. It further dissects the market by data rate, mapping the transition from legacy below-100G deployments through 100G/200G, 400G, and the rapidly expanding 800G and above segments that are redefining high-performance data center fabrics. Transmission distance segmentation distinguishes between short-reach intra-rack and direct-attach applications and intermediate/long-reach solutions that support data center interconnect, metro, and long-haul architectures. Protocol-level analysis clarifies the relative contributions of Ethernet, InfiniBand, and Fibre Channel and other standards, providing insight into the technology paths preferred by different workload profiles and customer segments.
In addition to segmentation, the report delivers a comprehensive competitive landscape assessment. It profiles the strategic positioning, product portfolios, and recent developments of leading market participants, including InnoLight Technology, Coherent Corp., Lumentum Holdings, Eoptolink Technology, Accelink Technologies, Broadcom, Cisco Systems, Applied Optoelectronics, Sumitomo Electric Industries, Hisense Broadband, Marvell Technology, and Fujitsu Optical Components. The analysis evaluates how these firms are responding to the AI-driven demand surge, the pace of their product commercialization, and the implications of their manufacturing and supply chain footprints for buyers and partners.
Recent industry developments illustrate the pace of innovation and commercial activity shaping the market. In April 2026, Applied Optoelectronics received a new upsized 71 million USD order for 800G single-mode data center transceivers from a major hyperscale customer for AI workloads, signaling the scale of demand and the strategic importance of high-volume, high-speed transceiver supply. In March 2026, Marvell Technology expanded its 1.6T optical DSP platform portfolio with new 3nm solutions, including Ara X, Ara T, Petra, and Aquila M, for AI data center connectivity, now sampling to customers. Also in March, Kyocera Corporation developed a pluggable optoelectronic module supporting PCIe 6.0 for high-speed, power-efficient AI data centers, to be exhibited at OFC 2026, while Semtech showcased 1.6T optical interconnect demonstrations and launched new 224 Gbps per lane TIAs and drivers for LPO and LRO architectures. Earlier, in July 2025, Universal Scientific Industrial announced the upcoming release of a next-generation 1.6T optical module for AI and high-performance computing data centers. These milestones reflect an industry in active transition, with multiple technology pathways and supplier capabilities competing for dominance in the next-generation interconnect landscape.
Navigating Competition, Concentration, and Supply Chain Realities
The competitive structure of the global data center optical module market reflects a blend of established multinational component suppliers, specialized transceiver manufacturers, and semiconductor firms extending into photonic integration. Market concentration metrics indicate that the top three players account for approximately 48.25 percent of total revenue, while the top five capture around 64.12 percent. This level of concentration suggests a market where scale, manufacturing capability, and long-term supplier relationships confer meaningful advantages, yet it also leaves substantial room for specialized players and regional participants to compete on technology differentiation, cost, and customer intimacy.
For buyers, this competitive environment carries several practical implications. First, the breadth of available solutions across data rates, transmission distances, and protocols means that procurement strategies must align technical requirements with supplier capabilities and roadmaps. Second, the concentration of revenue among leading suppliers underscores the importance of diversification, supply chain resilience, and contingency planning, particularly in a context where export controls and data sovereignty regulations may affect the availability of advanced components in certain geographies. Third, the rapid iteration of product generations, from 800G to 1.6T and beyond, demands that organizations maintain visibility into supplier development pipelines, sampling timelines, and manufacturing capacity to avoid bottlenecks as AI and high-performance computing deployments scale.
Worldwide Data Center Optical Module Market
Energy, Infrastructure, and the Broader Ecosystem Constraints
The optical module market does not operate in isolation. It is embedded within a broader data center ecosystem where power availability, thermal management, and total cost of ownership exert direct influence on technology selection and deployment economics. The fact that electricity expenses typically consume around 40 percent of a large data center’s operating budget, coupled with projected consumption growth to 325 to 580 TWh by 2028, makes energy efficiency a central criterion in evaluating optical interconnect options. Solutions that reduce power per bit, simplify thermal management, or enable higher density without proportional energy increases will increasingly command preference in procurement decisions.
At the same time, the need for grid modernization, with U.S. utility companies planning to invest 1.4 trillion USD over the next five years, highlights the infrastructural constraints that may shape where and how large-scale optical connectivity deployments can be sustained. Enterprises and cloud providers must factor these constraints into capacity planning, site selection, and the timing of interconnect upgrades. In parallel, regulatory frameworks, including U.S. export controls on advanced semiconductors and related items used in AI data centers, and the proliferation of data sovereignty mandates, add layers of complexity to cross-border supply chains and regional deployment strategies. Organizations that proactively map these constraints against their optical interconnect requirements will be better positioned to mitigate risk and maintain operational continuity.
Why the 2026 Outlook Demands a Forward-Looking Intelligence Framework
As the market advances toward the 2032 forecast horizon, the interplay of technology, cost, regulation, and demand will continue to evolve at a pace that challenges static planning assumptions. The projected expansion to nearly 47,939 million USD by 2032, supported by a 16.48 percent CAGR, signals that optical connectivity will remain a central enabler of data center growth, AI infrastructure scaling, and enterprise digital transformation. However, the distribution of that growth across regions, data rates, transmission distances, and protocols will not be uniform, and the competitive dynamics among suppliers will shift as new product generations, manufacturing investments, and regulatory developments take effect.
Organizations that treat optical module strategy as an afterthought risk facing escalating costs, performance limitations, and supply disruptions. Conversely, those that invest in rigorous market intelligence, align procurement roadmaps with technology trajectories, and incorporate energy, regulatory, and geographic factors into their decision frameworks will gain a measurable advantage in cost efficiency, deployment speed, and strategic flexibility.
Accessing the Full Strategic Picture
This overview provides a structured glimpse into the scope, methodology, and strategic relevance of the Worldwide Data Center Optical Module Market research. It highlights the macroeconomic arc of the market, the segmentation dimensions that matter most to decision-makers, the competitive players shaping the landscape, and the broader ecosystem forces that will influence deployment economics and supply chain resilience. Yet the full value of the study lies in its detailed segmentation data, granular regional and application insights, and comprehensive supplier analysis, which together enable precise scenario planning, benchmarking, and investment prioritization.
For executives, procurement leaders, and investors seeking to secure a decisive advantage in the AI and data center infrastructure race, the complete report offers the depth and specificity required to move from broad awareness to actionable strategy. We invite you to access the full Worldwide Data Center Optical Module Market study to obtain the comprehensive intelligence, detailed data tables, and strategic recommendations that will inform your 2026 decisions and long-term planning through 2032.
For detailed analysis of this topic, please visit the official page: Worldwide Data Center Optical Module Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com