

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Ethane Market Hits $36.8B in 2025, Poised to Reach $51.86B by 2032 at 5.02% CAGR

Worldwide Ethane Market Outlook 2026: Strategic Imperatives for Industry Leaders
The global ethane market stands at a critical inflection point as we move into 2026. Valued at approximately 36.8 billion USD in 2025, the market is projected to reach 51.86 billion USD by 2032, reflecting a steady compound annual growth rate of 5.02 percent. This trajectory is not merely a function of incremental demand growth but rather the result of structural shifts in feedstock logistics, regional capacity reallocation, and the accelerating integration of midstream export infrastructure with downstream petrochemical complexes. For executives, investors, and strategy teams operating across the hydrocarbon value chain, the Worldwide Ethane Market research report offers a comprehensive, data-driven lens into the forces that will define competitive positioning, capital allocation, and supply chain resilience over the next six years.
This introduction outlines the strategic value of the report, previews its analytical architecture, and demonstrates how the findings can be operationalized for 2026 decision-making. While macro indicators and industry milestones are highlighted here, the complete segmentation matrices, region-specific growth drivers, and granular competitor benchmarks are reserved for subscribers and readers accessing the full analysis ecosystem. The objective is simple: equip leadership teams with the framework to interpret market signals accurately, while providing a clear pathway to the deeper intelligence required for execution.
Market Trajectory and Structural Demand Drivers
The historical window from 2020 to 2025 establishes a clear baseline of expansion, with market size climbing from 27.5 billion USD to 36.8 billion USD. The forward forecast period from 2026 through 2032 anticipates continued upward momentum, with the market projected to cross 39.68 billion USD in 2026, reach 40.95 billion USD in 2027, 42.88 billion USD in 2028, and 43.95 billion USD in 2029 before accelerating toward 47.44 billion USD in 2030, 48.17 billion USD in 2031, and ultimately 51.86 billion USD by 2032. These figures are anchored in a 5.02 percent CAGR, a rate that underscores sustained demand for ethane as a feedstock and intermediate while reflecting the gradual pace of capacity additions, regulatory adjustments, and macroeconomic volatility.
Worldwide Ethane Market
Ethanolamine Market
The growth narrative is heavily influenced by the interplay between production recovery and export-oriented infrastructure expansion. U.S. ethane recovery is forecasted to average 3.06 million barrels per day in 2025 and rise to 3.15 million barrels per day in 2026, signaling a robust upstream supply environment that supports both domestic consumption and international shipment. Concurrently, U.S. ethane net exports are projected to grow 14 percent in 2025 followed by a 16 percent rise in 2026, driven by global petrochemical feedstock demand and expanded export terminals. This dual dynamic—rising domestic availability paired with structured export growth—creates a market characterized by shifting arbitrage opportunities, regional pricing sensitivity, and evolving supply chain dependencies.
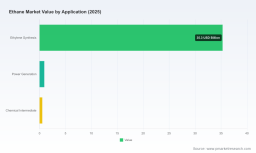
The report systematically unpacks these dynamics by mapping demand sources across natural gas separation and refinery by-product pathways, measuring application intensity across ethylene synthesis, power generation, and chemical intermediate use, and isolating the segments that will experience the most pronounced volume and value shifts. Rather than presenting a single aggregate narrative, the analysis decomposes the market into its functional components, enabling stakeholders to identify where margin stability, volume expansion, and infrastructure bottlenecks converge.
Infrastructure Expansion and the Reshaping of Global Flows
The most consequential market behavior in 2025 and 2026 is the rapid scaling of export and fractionation infrastructure, particularly within the United States. U.S. ethane export capacity increased by 16 percent with the addition of the Nederland facility and the first phase of the Neches River terminal, and a further 21 percent expansion is expected from Neches River Phase 2 in early 2026. These commissioning milestones are not isolated engineering achievements; they represent the physical backbone of a market that is increasingly defined by cross-border feedstock mobility and the integration of Appalachian, Permian, and Gulf Coast supply networks into international demand centers.
Enterprise Products Partners commissioned the Neches River ethane export terminal in Texas with initial capacity of 120,000 barrels per day in July 2025, reinforcing the Gulf Coast as a primary export corridor. Energy Transfer followed with the commissioning of the Nederland facility in Texas in the second quarter of 2025, delivering capacity to export up to 250,000 barrels per day of NGLs including ethane. Energy Transfer is also expanding its Marcus Hook, Pennsylvania terminal by 20,000 barrels per day by the end of 2025 to support Appalachian ethane exports. These investments collectively broaden the geographic reach of U.S. ethane supply and reduce the friction associated with moving NGL streams from inland processing centers to marine export points.
The U.S. Energy Information Administration forecasted in October 2025 that U.S. ethane net exports would grow 14 percent in 2025 and 16 percent in 2026, supported by new export infrastructure. This export trajectory is reinforced by production volume trends and by strategic shifts in international feedstock procurement. Chinese petrochemical producers, including Wanhua Chemical and others, are investing in ethane crackers and infrastructure to increase use of imported U.S. ethane over naphtha or propane for cost advantages. In January 2025, Wanhua Chemical completed its second cracker in Yantai, China, taking ethane feedstock, and began conversion of its first cracker to ethane from propane. The convergence of U.S. supply-side capacity with Asian demand-side conversion represents one of the most structural realignments in recent petrochemical feedstock markets.
For strategy teams, the critical insight is that infrastructure expansion is not merely a capacity story; it is a competitive moat. Firms that control fractionation, pipeline connectivity, terminal access, and offtake agreements can influence regional pricing spreads, improve delivery reliability, and lock in long-term demand commitments from derivative producers. The report evaluates how these infrastructure assets interact with regional supply balances, how export growth alters domestic versus international valuation gaps, and where new terminal capacity creates both opportunity and competitive pressure for midstream and downstream participants.
Competitive Landscape and Strategic Differentiation
The market is characterized by moderate-to-high concentration, with a CR3 of 38.4 percent and a CR5 of 56.15 percent. This concentration profile indicates that while a small group of integrated producers and midstream leaders exercise substantial influence over feedstock supply, export capacity, and cracker operations, a broader ecosystem of specialized operators continues to shape regional flows and niche value propositions. The report’s competitive analysis goes beyond headquarter mapping and revenue classification; it examines operational footprints, feedstock procurement strategies, infrastructure portfolios, and recent strategic moves that indicate where each player is positioning itself for 2026 and beyond.
ExxonMobil Corporation, headquartered in Irving, Texas, remains a major integrated producer and consumer of ethane as feedstock for ethylene production via steam crackers, with significant U.S. Gulf Coast operations and joint ventures. Dow Chemical Company, based in Midland, Michigan, is a leading consumer of ethane for ethylene and derivative production, operating multiple ethane-based crackers in North America. LyondellBasell Industries, headquartered in Rotterdam, Netherlands, operates ethane-fed steam crackers for ethylene production, with substantial capacity in the U.S. Gulf Coast. Chevron Phillips Chemical Company, located in The Woodlands, Texas, serves as a joint venture partner in ethane crackers, including Golden Triangle Polymers, and is a major user of ethane feedstock. Saudi Aramco and SABIC collectively represent a powerful integrated petrochemical complex in the Middle East, with ethane-based production embedded in downstream integration and large-scale complex economics. Reliance Industries Limited, headquartered in Mumbai, India, imports large volumes of U.S. ethane for its crackers and is expanding ethane import infrastructure and fleet. INEOS, based in London, UK, operates ethane import and cracking facilities in Europe, with the Project One cracker in Antwerp scheduled to start operations in 2026.
Beyond the integrated cracker owners, midstream and production-oriented participants shape the market’s logistics and supply foundation. Enterprise Products Partners L.P., headquartered in Houston, Texas, is a major midstream provider of ethane extraction, fractionation, transportation, and export via terminals including Neches River and Morgan’s Point. Energy Transfer LP, based in Dallas, Texas, is a key midstream company involved in ethane pipeline transportation, fractionation, and exports via Nederland and Marcus Hook terminals. ONEOK, Inc., American Ethane Company, Williams Companies, and Occidental Petroleum Corporation each contribute to the ethane supply chain through natural gas processing, NGL fractionation, production output, and export-oriented supply arrangements. American Ethane Company, for example, is focused on ethane production and export, with contracts for supply to international markets including China.
Recent developments illustrate how these companies are actively reshaping the market environment. In addition to Enterprise’s Neches River terminal commissioning and Energy Transfer’s Nederland facility, INEOS’s Project One ethane cracker in Antwerp, Belgium, is expected to come online in the third quarter of 2026 with capacity of about 80,000 barrels per day of ethane. These milestones reflect a broader trend: new cracker capacity, new terminal capacity, and new import flows are converging simultaneously, creating a market where capacity additions in one node can cascade into pricing, utilization, and regional trade patterns across multiple continents.
The report’s competitive framework assesses each enterprise’s strategic posture in terms of feedstock security, midstream connectivity, export access, derivative integration, and regional expansion. It identifies where scale translates into bargaining power, where logistics constraints can become margin inhibitors, and where new entrants or expanded capacity may alter incumbent positioning. This analysis is designed to help readers evaluate not just who is operating in the market, but how operational decisions in 2026 will affect relative competitive advantage over the forecast horizon.
What the Report Delivers for 2026 Decision-Making
Translating market intelligence into executive action requires more than top-level size estimates and trend narratives. The Worldwide Ethane Market report is structured to support operational planning, capital evaluation, and risk assessment across a range of use cases. It integrates historical performance data, forward forecasts, segmentation detail, competitive profiles, and infrastructure milestones into a single analytical environment, enabling readers to cross-reference demand drivers with supply constraints and to evaluate strategic options against a consistent set of assumptions.
The report provides:
- A full historical reconstruction from 2020 through 2025, with year-by-year market sizing that establishes baseline trends and highlights inflection points in volume and value.
- A detailed forecast from 2026 to 2032, with annual projections that support budgeting, capacity planning, and long-cycle investment evaluation.
- Segment-level analysis across source and application categories, allowing readers to isolate the demand streams most relevant to their business and to quantify the relative importance of each pathway.
- Regional market insights that describe where growth is concentrated, where infrastructure expansion is most active, and how trade flows are reshaping supply access across geographies.
- A structured competitive assessment of the leading producers, midstream operators, and integrated petrochemical players, including profiles of operational focus, geographic presence, and recent strategic developments.
- A review of current industry dynamics, including export infrastructure expansion, production volume trends, export growth forecasts, feedstock substitution behaviors, and terminal commissioning milestones that are actively redefining market mechanics.
- Scenario-aware commentary that helps readers interpret how changes in terminal capacity, cracker utilization, import demand, and regional feedstock preferences may interact over time.
Crucially, the report is designed for practical application. Readers can use the segmentation architecture to benchmark internal assumptions against market-wide averages, identify which application or source segments warrant closer monitoring, and prioritize markets where export growth, cracker additions, or import infrastructure create the greatest strategic impact. The combined historical and forecast datasets support stress testing of volume projections, evaluation of regional exposure, and assessment of how midstream constraints may influence downstream procurement strategies.
Why 2026 Demands a Disciplined Market View
The 2026 operating environment is defined by simultaneous expansion on multiple fronts: production recovery, terminal commissioning, cracker start-ups, and international feedstock substitution. U.S. ethane recovery is projected to rise from 3.06 million barrels per day in 2025 to 3.15 million barrels per day in 2026, while net exports are expected to increase by 16 percent following a 14 percent rise in 2025. At the same time, the U.S. Energy Information Administration reported that export capacity grew 16 percent with the addition of the Nederland facility and Neches River Phase 1, with Neches River Phase 2 expected to add another 21 percent expansion in early 2026. These concurrent developments create a market that is both high-opportunity and high-complexity, where the benefits of capacity growth can be offset by regional pricing volatility, logistics bottlenecks, and shifting trade relationships.
Companies that approach 2026 with a fragmented view of these dynamics risk overcommitting to regions or segments without fully accounting for midstream constraints, pricing dislocations, or the timing of competitor capacity additions. Conversely, organizations that anchor their planning in a comprehensive market map can better align sourcing strategies with terminal access, evaluate export-oriented growth against domestic utilization patterns, and position derivative production to capitalize on emerging demand centers. The report is built to support exactly this kind of disciplined decision-making by connecting macro trends to operational implications and by identifying the variables that matter most for each stakeholder group.
Conclusion: Turning Intelligence into Strategy
The Worldwide Ethane Market research report provides a rigorous, forward-looking foundation for navigating the 2026 to 2032 period. It quantifies market size progression, clarifies the role of source and application segmentation, situates regional growth within infrastructure and trade developments, and profiles the competitive players whose decisions will shape the market’s trajectory. Equally important, it does so in a format that supports real-world use: budgeting, capacity planning, supply chain optimization, export strategy, and competitive benchmarking.
To move from strategic awareness to execution-ready intelligence, readers are encouraged to consult the full report and access the detailed segmentation breakdowns, regional growth narratives, competitor assessments, and scenario commentary that underpin the conclusions summarized here. The complete analysis preserves the quantitative depth, regional specificity, and application-level detail required to support confident decisions in a market where timing, infrastructure access, and feedstock strategy increasingly determine long-term competitive outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Ethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com