

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Projects Worldwide Cartridge Filters Market To Hit $10.4 Billion By 2032 At 6.15% CAGR

Strategic Foresight in Filtration: Unlocking Value in the Global Cartridge Filters Market Through 2032
In an era defined by tightening regulatory frameworks, escalating sustainability mandates, and the relentless pursuit of operational efficiency, the cartridge filters market has evolved from a commoditized component segment into a strategically critical enabler of industrial resilience. As organizations navigate increasingly complex supply chains and performance-driven procurement cycles, access to granular, forward-looking intelligence is no longer a luxury—it is a operational imperative. PW Consulting’s latest Worldwide Cartridge Filters Market research delivers precisely that: a rigorously validated, structurally segmented, and competitively mapped assessment designed to inform capital allocation, product positioning, and go-to-market strategy through 2032.
The Macro Trajectory: Sizing the Opportunity Beyond Historical Baselines
The global cartridge filters market has demonstrated consistent expansion over the past half-decade, recovering from early pandemic-era supply disruptions and capitalizing on accelerated industrial modernization. Trailing performance from 2020 through 2025 established a robust foundation, with evaluated market revenue reaching approximately USD 6,850 million by the 2025 base year. This trajectory reflects more than cyclical recovery; it signals a structural shift in how enterprises approach fluid and air management across critical processes.
Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 6.15%, positioning the market on a clear upward arc. By 2026, evaluated industry revenue is anticipated to approach USD 7,271 million, with sustained momentum carrying the segment toward the USD 10,402 million threshold by 2032. These figures are not abstract aggregates; they represent the compounded effect of capacity expansions, material innovation cycles, regulatory-driven replacement schedules, and cross-sector procurement modernization. Organizations that understand the underlying growth vectors—rather than surface-level headline numbers—will be better equipped to time investments, optimize inventory strategies, and align product roadmaps with emerging demand pockets.
Crucially, the assessment behind these projections draws from a multi-year historical baseline, ensuring that forward estimates are stress-tested against real-world procurement patterns, regional capacity shifts, and material cost volatility. Decision-makers relying on truncated or backward-looking datasets risk misallocating resources in a market where lead times, specification upgrades, and compliance cycles increasingly dictate competitive outcomes.
Structural Dynamics: Material, Application, and Regional Interplay
The cartridge filters ecosystem is inherently multidimensional. Material selection dictates performance envelopes, cost structures, and compatibility with aggressive process environments. Application mandates drive specification granularity, replacement frequency, and certification requirements. Regional industrial footprints shape procurement behaviors, localization trends, and distribution architectures. PW Consulting’s analysis dissects these intersecting dimensions without reducing them to static snapshots, instead mapping how they evolve under varying macroeconomic and regulatory conditions.
Material architectures continue to bifurcate between cost-optimized conventional media and high-performance engineered substrates. Polypropylene remains a foundational standard, prized for chemical resistance and economic viability, while polyester, cellulose, and advanced membrane configurations capture specialized demand where purity, flux rates, or thermal stability are non-negotiable. The market’s material mix is further complicated by raw resin price fluctuations tied to petrochemical capacity and crude oil dynamics, creating margin pressures that reward suppliers with vertically integrated sourcing or differentiated formulation capabilities.
Worldwide Cartridge Filters Market
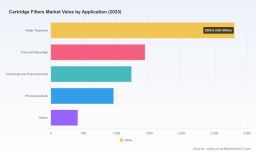
Application-side demand is equally diversified. Water treatment continues to anchor substantial volume, driven by municipal infrastructure upgrades, industrial effluent management, and tightening discharge standards. Food and beverage operations prioritize sanitary compatibility and regulatory conformance, while chemicals and petrochemicals sectors demand robust handling of corrosive or high-viscosity fluids. Pharmaceutical and biopharmaceutical manufacturing imposes the strictest purity and validation requirements, favoring membrane and precision-engineered cartridge solutions. Across these verticals, a common theme emerges: buyers are increasingly specifying filters not merely as replacement components, but as integrated process enablers that reduce downtime, extend service intervals, and minimize total cost of ownership.
Regional procurement landscapes reflect differing industrialization paces, environmental policy intensities, and supply chain localization strategies. mature markets emphasize compliance-driven replacements and high-efficiency upgrades, while emerging industrial corridors exhibit rapid capacity buildup, price-sensitive sourcing, and growing preferences for locally assembled or regionally distributed product lines. Understanding how these regional rhythms interact with material availability and application growth is essential for firms planning geographic expansion, manufacturing footprint adjustments, or partnership ecosystems.
Competitive Architecture and Strategic Positioning
The cartridge filters market operates within a moderately concentrated competitive structure, where scale, technical differentiation, and application-specific expertise determine market share trajectories. Evaluated industry concentration metrics indicate that the top three players command approximately 28.5% of aggregate revenue, while the top five account for roughly 38.75%. This distribution suggests a landscape where large multinational incumbents hold meaningful share but face persistent pressure from specialized challengers, regional manufacturers, and application-focused innovators.
Global leaders such as Pall Corporation and Parker Hannifin leverage broad filtration portfolios, extensive distribution networks, and legacy engineering capabilities to serve industrial, process, and fluid power applications at scale. Their strategies often center on integrated solution offerings, cross-selling across hydraulic, process, and water treatment verticals, and sustained investment in high-flow and membrane-based architectures. 3M Company applies materials science depth to liquid and air filtration, competing on formulation versatility and commercial-industrial crossover demand. Eaton Corporation and Donaldson Company maintain strong positions in fluid power, process filtration, and industrial dust collection, respectively, emphasizing system-level compatibility and durability.
In the water and municipal domain, Pentair delivers high-flow cartridge configurations tailored to residential, commercial, and industrial treatment workflows. Graver Technologies and Camfil address industrial water treatment, power generation, and cleanroom/HVAC air filtration, respectively, capitalizing on niche performance credentials and service-oriented engagement models. The biopharmaceutical and laboratory segment is heavily shaped by Merck Millipore (Merck KGaA), Sartorius Stedim Biotech, and Meissner Filtration Products, where sterile processing, traceability, and regulatory validation outweigh pure cost competition. GKN Powder Metallurgy differentiates through metallic membrane and sintered cartridge technologies, recently advancing new fine-filtration solutions aimed at enhanced efficiency for downstream industrial applications.
Regional and specialty manufacturers—including LOONG Filtration, Brother Filtration, and Gopani Filters—illustrate the growing importance of localized production, melt-blown and pleated media optimization, and flexible specification adaptation for water treatment and process industries. These players often compete on responsiveness, custom configuration capabilities, and proximity to regional procurement cycles, challenging incumbents to accelerate localization strategies or reinforce value-added engineering services.
Competitive intelligence in this market extends beyond corporate profiles. It requires mapping recent product introductions, certification expansions, capacity investments, and strategic partnerships to anticipate share shifts. The 2025 introduction of enhanced metallic membrane cartridge filters for fine filtration and efficiency, for example, signals incremental but meaningful movement toward higher-performance substrate competition. Firms that track such developments against their own specification roadmaps and procurement calendars gain a tangible advantage in pricing negotiations, vendor qualification processes, and product lifecycle planning.
Regulatory, Compliance, and Macro Trend Catalysts
Cartridge filter adoption is increasingly governed by a matrix of performance standards and environmental directives that shape both specification requirements and replacement economics. Compliance with testing frameworks such as ISO 16889:2012 for hydraulic filter element evaluation, alongside NSF/ANSI 61 for drinking water contact materials, remains essential for suppliers targeting regulated industrial and municipal applications. These standards do not merely certify products; they influence procurement qualification cycles, warranty expectations, and engineering acceptance criteria.
Environmental regulation continues to act as a structural demand driver. The U.S. EPA Clean Water Act and Clean Air Act, alongside comparable frameworks in other jurisdictions, reinforce the necessity of effective particulate and contaminant capture in industrial water and air treatment workflows. As discharge limits tighten and monitoring protocols become more rigorous, facilities face intensified pressure to maintain filtration integrity, reduce frequent change-outs, and document compliance performance. This regulatory environment favors suppliers capable of delivering consistent quality, traceable manufacturing processes, and technical support that bridges product specification with operational compliance.
Macro trends further reshape buyer priorities. Across pharmaceuticals, food and beverage, and water treatment sectors, there is growing demand for higher filtration precision, extended service life, and materials engineered to withstand aggressive process conditions. Procurement teams increasingly evaluate filters through a total-cost lens, weighing initial price against downtime reduction, waste minimization, chemical compatibility, and replacement frequency. Simultaneously, raw material dynamics—particularly volatility in polypropylene resin pricing linked to crude oil markets and petrochemical capacity—introduce margin variability that rewards suppliers with robust sourcing strategies, formulation flexibility, and transparent cost communication.
These dynamics converge to create a market where technical credibility, regulatory fluency, and supply chain reliability are as decisive as product performance alone. Organizations that integrate compliance foresight, material cost monitoring, and application-specific engineering support into their commercial strategies will navigate this environment with greater resilience.
What the Research Delivers: An Actionable Intelligence Framework
PW Consulting’s Worldwide Cartridge Filters Market study is structured to translate macro trends and competitive signals into decision-ready intelligence. Rather than offering static tables, the report builds a layered analytical architecture designed for strategic planning, investment justification, and market entry assessment. Core components include:
Cartridge Valve Market
- Evaluated historical performance and forward projections calibrated across multiple demand drivers, enabling scenario-based planning rather than single-point forecasting.
- Material-type and application-segment breakdowns that clarify where volume concentrates, where specification premiums emerge, and how replacement cycles differ across industrial contexts.
- Regional demand distributions that map procurement intensity, industrialization momentum, and localization preferences without oversimplifying cross-market variation.
- Competitive positioning analysis that tracks incumbent scale advantages, specialty manufacturer agility, and recent product or capability introductions shaping vendor qualification outcomes.
- Regulatory and standards context integrated into demand dynamics, helping readers anticipate qualification thresholds, compliance-driven replacement schedules, and engineering acceptance criteria.
- Raw material and cost structure considerations that connect resin price volatility, substrate innovation, and supply chain behavior to pricing strategies and margin management.
The assessment is built for teams that need to align product development with market reality, time capacity or partnership decisions with demand inflection points, and evaluate competitive threats with evidence rather than assumption. Whether the objective is to expand into high-growth application verticals, optimize regional distribution, benchmark against incumbents, or identify white-space opportunities in material or configuration specialization, the research provides the structural clarity required to move from observation to action.
Preparing for 2026 and Beyond
The cartridge filters market through 2032 will not be defined by a single driver, but by the interplay of regulatory pressure, material innovation, application-specific engineering demands, and competitive repositioning. Enterprises that treat filtration as a strategic process component—rather than a routine maintenance purchase—will capture disproportionate value in reliability, compliance performance, and total cost optimization. Those that delay informed planning risk exposure to specification misalignment, margin compression, and reactive procurement cycles.
PW Consulting’s comprehensive assessment offers the evidentiary foundation needed to navigate this landscape with precision. The full report details segment-level trajectories, competitive benchmarking, regional nuances, and forward-looking demand catalysts that cannot be fully captured in a preview. To access the complete intelligence architecture, evaluate scenario-based projections, and translate market structure into your organization’s strategic roadmap, explore the full Worldwide Cartridge Filters Market research at the source page.
For detailed analysis of this topic, please visit the official page: Worldwide Cartridge Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com