

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Electronic Helium Market Hits $2.19B in 2025, Projected 8.15% CAGR to 2032

Navigating the Electronic Grade Helium Market: Strategic Intelligence for 2026 and Beyond
The global supply chain for high-technology manufacturing stands at a critical inflection point. As semiconductor fabrication pushes toward smaller nodes and new display technologies mature, the demand for ultra-high-purity gases has become a defining constraint for industrial capacity. Among these essential materials, electronic grade helium occupies a unique position. It is not merely a commodity but a foundational enabler for cooling, atmosphere control, and precision leak detection in advanced nodes. Our latest Worldwide Electronic Grade Helium Market research offers a comprehensive lens into this complex ecosystem, providing the data-driven foresight necessary for corporate strategy in 2026.
This report is designed for executive leadership, supply chain directors, and investment analysts who require more than surface-level statistics. It transforms historical performance and forward-looking projections into actionable intelligence. By examining the trajectory from 2020 through the forecast period ending in 2032, stakeholders can calibrate their portfolios against the expected compound annual growth rate of 8.15 percent. Such growth signals robust expansion, yet it also masks underlying volatility that only rigorous analysis can uncover.
Market Trajectory and Macro Dynamics
Understanding the scale of the opportunity requires a clear view of the market's evolution. In 2025, the global revenue for electronic grade helium reached approximately 2185.5 million USD. This figure represents a significant climb from the 1455.2 million USD recorded in 2020, illustrating a sustained upward trend driven by technological adoption and capacity expansion. The forecast suggests this momentum will continue, with revenue projected to approach 3782.13 million USD by 2032.
These numbers reflect more than simple volume increases. They encapsulate the intensifying arms race in semiconductor manufacturing, where purity standards are becoming non-negotiable. The market is segmented by purity grades, ranging from 6N and above to lower specifications. High-purity segments continue to command premium valuations as fabrication facilities prioritize yield integrity over cost minimization. Similarly, applications such as semiconductor wafer manufacturing, flat panel displays, optical fiber manufacturing, and photovoltaic cells drive distinct demand patterns. Each segment faces unique supply pressures and technological requirements that generic market summaries often overlook.
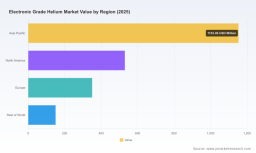
Geographical distribution also plays a pivotal role in shaping market dynamics. While the Asia Pacific region currently leads in consumption volume, North America and Europe maintain significant strategic importance due to their entrenched infrastructure and regulatory environments. The Rest of World segment, though smaller in current valuation, presents emerging opportunities as localized manufacturing capabilities develop. A granular understanding of these regional nuances is essential for companies planning multinational expansion or supply chain reconfiguration.
Competitive Landscape and Strategic Positioning
The electronic grade helium market is characterized by a high degree of concentration, with a small number of key players controlling a substantial share of global supply. Our analysis indicates that the top three companies account for over 62 percent of the market, while the top five firms command nearly 79 percent. This concentration creates both barriers to entry and potential vulnerabilities for downstream manufacturers who rely on a limited supplier base.
Leading incumbents such as Air Liquide S.A., Air Products and Chemicals, Inc., and Linde plc have established dominance through extensive purification, liquefaction, and distribution networks. These organizations leverage diverse global sourcing mixes and massive processing capabilities to ensure continuity of supply. For instance, Linde operates one of the largest processing plants globally, while Air Products pioneers extraction technologies tailored for semiconductor applications. Taiyo Nippon Sanso Corporation and Messer SE & Co. KGaA further reinforce the competitive field with specialized high-purity offerings.
Worldwide Electronic Grade Helium Market
Beyond the traditional gas giants, energy and resource corporations like Exxon Mobil Corporation and QatarEnergy LNG contribute significant volumes from natural gas and LNG processing facilities. Gazprom also remains a notable producer, extracting helium as a byproduct of natural gas operations. The interplay between these diverse entities defines the market's resilience and pricing power. Understanding the specific capabilities, sourcing rights, and strategic priorities of each competitor is vital for identifying partnership opportunities or assessing supply risk.
Disruption and Resilience in 2026
The year 2026 has already introduced profound disruptions that underscore the value of real-time intelligence. Recent developments highlight the fragility of the supply chain and the rapidity with which conditions can change. In March 2026, QatarEnergy declared force majeure on helium supply following a disruption at the Ras Laffan LNG facility. This event impacted approximately 30 percent of global semiconductor-grade helium output, triggering spot price surges ranging from 40 to 100 percent in early 2026.
Simultaneously, geopolitical tensions affecting the Strait of Hormuz have exacerbated logistics challenges, tightening supply for Asian semiconductor hubs in Taiwan and South Korea. These external shocks contrast sharply with strategic investments aimed at bolstering regional security. Air Liquide opened a new helium facility near Taichung port in Taiwan during the same period, specifically to support local chipmakers amid global constraints. Meanwhile, Guangdong Huate Gas achieved mass production of 6N ultra-high-purity helium and secured ASML certification, marking a significant milestone in domestic capability enhancement.
Helium Gas Market
China's domestic ultra-high-purity helium production capacity has also reached approximately 1.2 million cubic meters annually, with firms developing recovery systems achieving reprocessing rates up to 98 percent. These developments illustrate a bifurcated market where supply shocks coexist with aggressive capacity building and technological innovation. Companies must navigate this duality to secure reliable access without overpaying for scarcity premiums.
Strategic Value of the Research Report
Our Worldwide Electronic Grade Helium Market report goes beyond aggregating public information. It provides a structured framework for decision-making that integrates market sizing, competitive profiling, and dynamic scenario analysis. The research delves into the operational specifics of how leading firms manage purification technologies, distribution logistics, and customer certification requirements. It examines the implications of force majeure declarations and geopolitical shifts on long-term contracting strategies.
Readers will gain access to detailed segmentation analysis that breaks down demand drivers across purity grades and application verticals without exposing sensitive proprietary data shared by industry participants. The report also explores the regulatory and raw material contexts that influence production costs and availability. Since helium is primarily extracted as a byproduct of natural gas and LNG processing, understanding the upstream economics is crucial for predicting price floors and supply ceilings. Major sources, including Qatar LNG facilities and U.S. operations like ExxonMobil's Shute Creek, are evaluated for their capacity constraints and expansion potential.
Furthermore, the study assesses the competitive intensity and market concentration metrics that define bargaining power. By quantifying the share held by dominant players, the report helps buyers evaluate negotiation leverage and supplier diversification needs. It also identifies gaps in supply coverage that new entrants or regional producers might exploit. For investors, the forecast period from 2026 to 2032 offers a roadmap for evaluating growth potential across different segments and regions, highlighting where capital allocation may yield the highest returns.
Conclusion: Building Resilience Through Intelligence
In an environment where supply disruptions can halt production lines and geopolitical events can reshape logistics overnight, intuition is insufficient. Strategic success depends on access to verified data, expert analysis, and a clear understanding of market structures. The Worldwide Electronic Grade Helium Market research equips organizations with the insights needed to anticipate shifts, mitigate risks, and capitalize on growth opportunities.
From the macro trajectory of revenue growth to the micro details of facility openings and certification achievements, this report provides a holistic view of the industry. It enables stakeholders to benchmark their strategies against the best-in-class practices of leading competitors and to prepare for a future where electronic grade helium remains a critical bottleneck and a strategic asset. Accessing the full report unlocks the detailed tables, regional breakdowns, and company profiles required to execute informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Electronic Grade Helium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com