
Blogs
Indoor Wall Decoration Paint Market: Why 5.45% CAGR Through 2032 Changes Everything
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Indoor Wall Decoration Paint Market
Market Landscape and Core Challenges
The indoor wall decoration paint market is undergoing a period of measured but consistent expansion, driven by sustained construction activity, evolving consumer expectations, and tightening environmental standards. From 2020 to 2025, the industry demonstrated resilience through cycles of economic fluctuation, with total revenue climbing steadily to surpass sixty-two billion dollars by the 2025 base year. Looking ahead, the market is projected to grow at a compound annual rate of approximately 5.45 percent through 2032, reaching an estimated valuation of over ninety billion dollars by the close of the forecast horizon. This trajectory reflects a mature yet evolving sector where growth is increasingly tied to product innovation, regulatory compliance, and regional demand shifts rather than volume expansion alone.
Several structural challenges are reshaping how manufacturers, distributors, and end-users navigate this space. First, the regulatory landscape has become increasingly complex and fragmented across major markets. New mandatory standards governing volatile organic compound limits, hazardous substance restrictions, and compulsory certification requirements are forcing manufacturers to reformulate products, adjust production processes, and invest in compliance infrastructure. While these measures align with broader sustainability goals, they introduce short-term cost pressures and create barriers for smaller players lacking the technical and financial resources to adapt quickly. Second, the industry continues to grapple with raw material volatility. Key inputs such as titanium dioxide, a critical pigment for coverage and finish quality, have experienced notable price fluctuations in recent periods, directly impacting margin stability and pricing strategies for formulators. Third, shifting demand patterns are compelling companies to balance volume-driven residential construction cycles with higher-margin specialty and commercial applications, requiring more agile portfolio management and channel strategies.
PW Consulting Chemical & Energy Research Center
Competitive Concentration and Market Dynamics
The market remains moderately concentrated, with the top three players capturing a significant share of total revenue and the top five collectively accounting for just over half of industry sales. This concentration level suggests that scale advantages, brand recognition, and distribution networks continue to provide meaningful competitive insulation. However, the structure also indicates room for targeted disruption, particularly in segments where performance differentiation, localized formulation capabilities, or direct-to-consumer engagement models can unlock value outside the dominant incumbents. Companies that can align product innovation with regulatory readiness and cost discipline are best positioned to convert market growth into sustained profitability.
Core Drivers Shaping Market Evolution
Technological Innovation and Formulation Advances
Product innovation remains one of the most powerful levers for differentiation in this market. Leading manufacturers have progressively shifted their R&D focus toward water-based systems that deliver superior coverage, improved scrub resistance, and enhanced color retention without compromising environmental performance. One-coat application capabilities, stain-blocking formulations, and low-odor emulsions have moved from premium niche offerings to mainstream expectations, particularly in residential and light commercial settings. Advanced additive technologies are also enabling functional benefits such as anti-fungal properties, air-purifying characteristics, and moisture resistance, which resonate strongly with end-users concerned about indoor air quality and long-term maintenance costs. Companies that integrate these performance attributes with consistent finish quality and ease of application are capturing incremental share, especially in markets where renovation and upgrade cycles are accelerating.
The emphasis on low-VOC and eco-friendly formulations has evolved from a compliance exercise into a competitive necessity. Formulators are leveraging advanced resin technologies and pigment dispersion methods to achieve high opacity and washability while meeting stringent emissions thresholds. This technical progress is particularly relevant as regulatory bodies across multiple regions tighten allowable limits on volatile organic compounds, semi-volatile compounds, formaldehyde, benzene, and heavy metals. Manufacturers that have invested early in reformulation pipelines and testing infrastructure are converting compliance requirements into market-facing advantages, positioning their products as safer, cleaner, and more future-proof options for both professional applicators and DIY consumers.
Policy and Regulatory Environment
Regulatory developments are exerting a decisive influence on product architecture, market access, and competitive positioning. In China, new mandatory national standards governing hazardous substance limits in architectural coatings are set to take effect, replacing earlier frameworks with stricter thresholds across multiple chemical categories. This shift is complemented by compulsory certification requirements for water-based interior wall paints, adding an additional layer of scrutiny to product approvals and supply chain documentation. These measures are accelerating the phase-out of older solvent-heavy formulations and pushing both domestic and international players to localize their compliance strategies.
Across Europe, decorative paint and varnish regulations cap VOC content within defined ranges to reduce ozone-forming emissions, reinforcing demand for low-emission interior wall coatings and encouraging cross-border alignment on sustainability benchmarks. In the United States, stringent VOC limits for architectural coatings, particularly in leading states such as California, continue to shape formulation trends nationwide. Flat interior paints face tighter ceilings than non-flat products, compelling manufacturers to balance performance expectations with regulatory constraints. Collectively, these regulatory trajectories are narrowing the window for legacy formulations and rewarding companies that can demonstrate consistent compliance, transparent ingredient disclosure, and verifiable environmental benefits.
Demand-Side Shifts and Consumer Behavior
Demand patterns are increasingly shaped by a combination of housing market dynamics, renovation activity, and heightened awareness of indoor environmental quality. Residential construction continues to represent the largest application segment, with homeowners and renters prioritizing finishes that combine aesthetic appeal, durability, and ease of maintenance. At the same time, commercial building operators are seeking wall decoration solutions that support tenant retention, reduce lifecycle maintenance costs, and align with green building certifications. Educational and healthcare facilities represent a growing niche where hygiene, low odor, and washability are non-negotiable requirements, creating steady demand for specialized interior coatings.
Consumer expectations are also shifting toward premiumization in key demographics. Buyers are increasingly willing to pay a premium for paints that deliver richer color depth, superior stain resistance, and one-coat coverage, particularly in high-visibility areas such as living rooms, entryways, and commercial interiors. This trend is encouraging manufacturers to expand their premium and super-premium portfolios, while simultaneously pushing value-tier offerings to emphasize functional clarity, reliable performance, and accessible pricing. The result is a more segmented demand landscape where product positioning, channel strategy, and technical communication all play critical roles in capturing the right audience.
Supply Chain and Cost Structure Dynamics
Cost structures in the indoor wall decoration paint market are being reshaped by upstream input volatility and evolving logistics realities. Titanium dioxide, the primary pigment responsible for opacity and coverage, experienced a notable price decline in China during 2025, ending the year at a level that provided some relief to formulators after earlier periods of pressure. While such movements can improve short-term margin flexibility, they also introduce planning complexity, as pricing can reverse quickly in response to supply disruptions, energy costs, and regional demand shifts. Companies that maintain diversified supplier networks, implement strategic inventory buffers, and incorporate flexible pricing mechanisms are better equipped to manage these fluctuations without eroding customer confidence.
Beyond raw materials, supply chain resilience has become a strategic priority. Regulatory changes, certification requirements, and regional compliance standards are forcing manufacturers to strengthen documentation, quality control, and production traceability. At the same time, the growing importance of both professional and retail channels is driving investments in packaging, color matching systems, and application support tools that reduce waste and improve end-user outcomes. Firms that integrate cost discipline with channel-specific value propositions are gaining an edge in a market where price competition alone is rarely sufficient to sustain long-term advantage.
Competitive Landscape and Leading Strategies
Strategic Positioning of Key Players
The competitive field is defined by a mix of global incumbents and regionally dominant specialists, each pursuing distinct pathways to differentiation. Large multinational players are leveraging broad product portfolios, extensive distribution networks, and brand equity to maintain presence across residential, commercial, and specialty segments. Several of these companies have built reputations around premium acrylic latex systems that emphasize superior coverage, scrubbability, and low-VOC formulations, often supported by one-coat application claims and professional-grade color matching services. Their scale enables continued investment in formulation technology, compliance infrastructure, and marketing reach, reinforcing their position in both developed and high-growth markets.
Regional leaders are competing with a different playbook, focusing on localized market knowledge, tailored product lines, and deep relationships with contractors, retailers, and end-users. In Asia, for example, dominant players have built strong associations with luxury finishes, stain repellency, and water-beading technologies, while also expanding low-VOC and washable emulsion offerings to meet evolving sustainability expectations. Other regional specialists have differentiated through functional coatings that address specific pain points such as anti-fungal performance, odor reduction, and easy-clean surfaces, making their products particularly attractive in humid climates and high-traffic environments. Specialist and value-oriented brands, meanwhile, are carving out share through retail-focused formulations that balance one-coat coverage, stain-blocking, and accessible pricing, appealing to DIY consumers and budget-conscious professional buyers alike.
Differentiation Advantages and Capability Gaps
Across the competitive set, companies that consistently outperform tend to share several capability advantages. Strong formulation expertise enables them to deliver high opacity, color depth, and durability while meeting regulatory thresholds. Robust quality assurance and certification readiness allow faster market access in jurisdictions with strict compliance requirements. Effective channel management ensures that products reach both professional applicators and retail consumers with appropriate technical support, color selection tools, and application guidance. Brand trust and consistent finish quality further reinforce repeat purchases and professional recommendations, which remain influential in a category where visual results and long-term performance matter deeply to end-users.
Conversely, gaps in these areas create vulnerability. Manufacturers that lag in low-VOC reformulation, lack transparent certification pathways, or rely too heavily on legacy solvent-based systems face increasing risk as regulations tighten and buyer preferences shift. Companies that fail to invest in application support, color consistency, or retail experience may struggle to justify premium pricing or defend against competitors offering comparable performance at lower cost. In a market with moderate concentration, such gaps can be exploited by rivals with more agile product development cycles or stronger regional execution.
Evolving Market Structure and Entry Dynamics
The market structure is gradually evolving along two parallel tracks: consolidation among scale players seeking broader geographic and segment coverage, and fragmentation in niche or high-growth regions where localized expertise and functional specialization create openings for focused competitors. M&A activity, brand portfolio optimization, and distribution partnerships are likely to shape the next phase of industry evolution, particularly as companies look to strengthen their presence in high-growth regions and expand into premium or specialty decorative coatings. At the same time, new entrants and smaller regional brands can still gain traction by targeting underserved application needs, leveraging digital color visualization tools, or building direct engagement models that resonate with modern consumers. The result is a dynamic landscape where scale provides advantages, but execution quality, regulatory readiness, and customer-centric innovation determine who captures disproportionate value.
Future Trends and Forward Outlook
Accelerated Adoption of Low-Emission and Functional Coatings
Over the next three to five years, low-emission interior wall coatings are expected to move from a compliance-driven requirement to a baseline market expectation. As regulatory thresholds tighten across major regions and buyer awareness of indoor air quality continues to rise, formulators will increasingly prioritize water-based systems that combine high performance with reduced environmental impact. Functional benefits such as stain resistance, anti-fungal protection, odor control, and air-purifying properties will become more common across premium and mid-tier portfolios, not just specialty lines. This trend creates opportunities for companies that can communicate verifiable performance benefits, maintain consistent finish quality, and align product claims with recognized certification or testing standards.
Premiumization and Segment-Specific Portfolio Strategies
Demand segmentation is likely to deepen, with residential, commercial, and institutional applications drawing increasingly distinct product requirements and purchasing criteria. In residential settings, homeowners and renovators will continue to seek finishes that deliver visual richness, easy maintenance, and application convenience, supporting continued premiumization in color depth, coverage, and durability. Commercial and institutional buyers will place greater weight on lifecycle costs, hygiene performance, and alignment with green building standards, favoring coatings that reduce repainting frequency and support indoor environmental quality goals. Manufacturers that develop segment-specific portfolios rather than relying on one-size-fits-all offerings will be better positioned to capture margin and defend share in a maturing market.
Cost Volatility, Compliance Investment, and Strategic Risk
Despite the favorable growth outlook, several uncertainty factors warrant attention. Raw material pricing can shift quickly, particularly for key pigments and resins, creating margin volatility that requires disciplined procurement and pricing strategies. Regulatory complexity is likely to increase rather than stabilize, with more jurisdictions introducing stricter VOC limits, hazardous substance restrictions, and mandatory certification processes. Companies that delay compliance investments or depend on outdated formulations risk lost market access, reputational exposure, and higher reformulation costs later. Additionally, macroeconomic fluctuations in construction and renovation activity can create uneven demand cycles, making portfolio flexibility and channel diversification important risk mitigation tools. The central strategic question for leaders will be how to balance cost efficiency, compliance readiness, and product differentiation in a market where all three dimensions interact continuously.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
Invest early in low-VOC and water-based formulation capabilities, and treat compliance as a competitive advantage rather than a cost center. Prioritize product lines that combine high coverage, durability, and functional benefits with clear, verifiable environmental claims. Strengthen quality assurance and certification readiness to accelerate market access in regions with tightening standards, and consider portfolio segmentation that aligns premium, mid-tier, and value offerings with distinct use cases and channels. Finally, review supplier diversification and inventory planning for critical inputs to reduce exposure to raw material price swings.
Interior Stain Market
For Investors and Strategic Buyers
Evaluate companies based on their formulation pipeline, regulatory readiness, regional execution strength, and ability to capture premiumization trends without overrelying on price competition. Look for players with strong brand positioning in water-borne and specialty decorative coatings, as well as those demonstrating disciplined cost management and channel flexibility. In consolidation scenarios, assess whether target companies bring complementary geographic reach, technical capabilities, or segment expertise that can accelerate growth in high-value applications. Pay close attention to compliance infrastructure and certification status, since these factors increasingly influence market access and brand trust.
For Procurement and Channel Decision-Makers
Prioritize suppliers that can demonstrate consistent color performance, low-emission compliance, and application reliability across residential, commercial, and institutional projects. Request clear documentation on VOC limits, certification status, and product performance claims, especially when specifying finishes for healthcare, education, or green building projects. Balance premium options for high-visibility areas with value-tier solutions for routine refresh cycles, and work with partners who offer robust color matching, technical support, and waste-reducing application guidance. Building a diversified supplier base can also help mitigate pricing volatility and ensure continuity as regulatory requirements evolve.
The indoor wall decoration paint market is entering a phase where growth is increasingly tied to product performance, regulatory alignment, and segment-specific execution. Companies and investors that maintain disciplined focus on formulation quality, compliance readiness, and customer-centric innovation will be best positioned to navigate the next wave of market change. For decision-makers seeking deeper segmentation data, regional dynamics, and tailored scenario planning, the full research report provides expanded detail and actionable frameworks to support strategic planning.
Paint Market
For detailed analysis of this topic, please visit the official page: Indoor Wall Decoration Paint Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Worldwide Synchronous Buck Converter Market: What 6.55% CAGR Means for 2032
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Worldwide Synchronous Buck Converter Market
Market Overview and Core Challenges
The global synchronous buck converter market has entered a phase of sustained expansion, with the total market size reaching approximately $4.6 billion in 2025. Measured from 2020 through the forecast horizon extending to 2032, the sector demonstrates a compound annual growth rate of 6.55 percent, reflecting steady demand across power management applications. Revenue units are tracked in millions of USD, underscoring the commercial scale of this component category. The trajectory from 2020 to 2025 shows consistent year-over-year growth, with the market crossing the $3.3 billion mark in the early part of the decade and accelerating through the mid-2020s as electrification, data center buildouts, and consumer electronics refresh cycles converge. Projections through 2032 point toward a market exceeding $7.2 billion, driven by structural shifts rather than cyclical demand alone.
Three critical challenges define the current industry inflection point. First, the balance between performance and manufacturability is tightening as designs push toward higher switching frequencies and wider input voltage ranges. Engineers are increasingly tasked with maintaining thermal stability and electromagnetic compatibility while shrinking form factors, a constraint that places pressure on component suppliers to deliver integrated solutions without sacrificing reliability. Second, supply chain resilience has moved from a background concern to a board-level priority. Geopolitical tensions and export controls on semiconductors have accelerated onshoring initiatives, particularly in the United States, reshaping how power management ICs are sourced, qualified, and deployed across regions. Lead times for semiconductors have eased from the peaks observed in 2022, yet procurement strategies now require dual-sourcing flexibility and buffer planning that were less critical in earlier cycles. Third, the transition toward wide-bandgap materials is not uniformly adopted across all application segments. While gallium nitride and silicon carbide enable meaningful efficiency gains and support higher switching frequencies that reduce passive component size, the cost premium and qualification complexity create a phased adoption curve that varies by end-use and region.
These dynamics create a market that rewards companies capable of navigating technical complexity, supply chain volatility, and application-specific qualification requirements simultaneously. The overall concentration of the market, with the top three players holding a combined share near 38 percent and the top five near 52 percent, indicates that scale, portfolio breadth, and ecosystem integration matter, but there remains meaningful room for differentiated positioning by application or technology focus.
Key Drivers Shaping Market Trajectory
Several interconnected forces are propelling the synchronous buck converter market forward, and each carries distinct implications for product roadmaps, sourcing strategies, and investment allocation.
Technology Innovation and Wide-Bandgap Adoption
Advancements in wide-bandgap semiconductors are fundamentally improving efficiency and power density in synchronous buck converters, particularly for electric vehicle, data center, and renewable energy applications. The shift toward gallium nitride and silicon carbide enables efficiency gains on the order of two to five percent while supporting higher switching frequencies, which in turn reduces the size of passive components in synchronous buck designs. This is not simply a marginal improvement; it changes the design calculus for systems where thermal headroom, footprint, and conversion losses directly affect total cost of ownership. Recent product activity illustrates the pace of this transition. In October 2025, Texas Instruments released the LMG708B0, an 80V input, 20A output high power density GaN synchronous buck converter with reference designs incorporating frequency spread spectrum, targeting industrial, automotive, and computing applications where efficiency and integration are priorities. Around the same timeframe, Efficient Power Conversion launched the EPC91109, an ultra-compact 180W GaN-based two-phase synchronous buck converter evaluation board for USB-PD 3.1 applications, built around EPC2057 GaN FETs and an Analog Devices LTC7890 controller. These releases signal that GaN integration is moving from niche high-performance use cases into broader power delivery and compact power applications.
Policy, Regulation, and Supply Chain Realignment
Regulatory and geopolitical dynamics are reshaping where and how power management components are produced and qualified. Export controls and semiconductor-related tensions have accelerated onshoring initiatives in the United States, influencing supply chains for power management ICs including synchronous buck converters. At the same time, global supply chain dynamics for gallium nitride and silicon carbide discrete devices are being influenced by automotive electrification and AI data center demand, with a clear focus on stable sourcing. Average semiconductor lead times have decreased from a peak of 26.5 weeks in 2022 to around 15 weeks in 2024, easing pressure on production of power management components, but the structural preference for regional redundancy and qualified alternate sources remains. For manufacturers and procurement teams, this means that compliance, traceability, and multi-region qualification are becoming part of the baseline rather than exceptional requirements.
Demand-Side Shifts Across End-Use Segments
Demand is being reshaped by simultaneous growth in automotive electrification, data center and high-performance computing buildouts, and continued refresh cycles in consumer electronics. Automotive power architectures are increasingly requiring efficient step-down conversion for traction, gate drive, and auxiliary systems, while industrial and telecommunications infrastructure demands reliable conversion across wider input ranges. Consumer electronics continue to push for low quiescent current and compact footprints, especially in portable and battery-powered devices. Recent product introductions reflect these demand signals. In December 2025, Diodes Incorporated introduced a 5.5V, 4A low IQ synchronous buck converter with a versatile I²C interface designed for portable and compact power applications, addressing consumer electronics, computing, communications, and industrial markets. Such developments indicate that efficiency, intelligence, and integration are becoming table stakes across segments, even as the relative weight of each requirement differs by application.
PW Consulting
Cost Structure and Integration Trends
Cost structures are shifting as integration deepens and passive component reduction offsets some of the material cost premiums associated with wide-bandgap devices. Suppliers are emphasizing power efficiency, integration, and wide input ranges to help system designers manage bill-of-materials complexity while meeting performance targets. The result is a market where competitive advantage increasingly depends on reference design quality, qualification breadth, and the ability to support customers through application-specific integration challenges rather than on component pricing alone.
Competitive Landscape and Leading Strategies
The competitive field in synchronous buck converters is defined by a mix of broad-portfolio semiconductor leaders and specialized players that compete on technology depth, application focus, or integration advantage. The top three companies collectively hold roughly 38 percent of the market, and the top five reach just over 52 percent, indicating a landscape where scale and portfolio coverage provide meaningful leverage, but differentiation remains viable through technology positioning and application-specific solutions.
Strategic Positioning of Leaders
Texas Instruments maintains a broad portfolio spanning high-voltage and high-current synchronous buck converter ICs, including GaN-integrated solutions such as the LMG708B0 for industrial, automotive, and computing applications. Its emphasis on efficiency, integration, and wide input ranges aligns with the trend toward higher power density and application versatility. STMicroelectronics offers monolithic synchronous buck regulator ICs with input voltage capability up to 61V and output currents up to 4A, along with AEC-Q100 qualified isolated buck solutions targeted at automotive, industrial, and EV traction and gate drive systems, reflecting a strong orientation toward automotive-qualified and safety-relevant applications. Infineon Technologies supplies high-performance synchronous buck converters and dedicated synchronous buck driver ICs optimized for efficiency in computing, industrial, and automotive power management, with a focus on integration and thermal performance that addresses the thermal constraints of higher-density designs.
Synchronous Condenser Market
Analog Devices delivers synchronous buck regulators and controllers, including GaN-compatible offerings such as the LTC7890 and LTC7891, supporting high power density, multi-phase operation, and wide voltage ranges for data center, industrial, and high-performance computing needs. Its controller-centric approach complements the GaN ecosystem and positions the company well for applications where multi-phase and high-power density architectures are required. ON Semiconductor manufactures synchronous buck converter solutions for consumer, industrial, and automotive sectors, emphasizing power efficiency and integration in voltage regulation applications. Diodes Incorporated offers low-IQ synchronous buck converters, including a 5.5V, 4A device with an I²C interface announced in December 2025, targeting consumer electronics, computing, communications, and industrial markets with compact, high-efficiency designs. ROHM Semiconductor produces integrated FET synchronous buck DC/DC converters such as the BD9P series for high-efficiency voltage conversion in automotive, industrial, and consumer applications, while Microchip Technology supplies DC-DC switching synchronous buck converters and regulators with features tailored to power-sensitive industrial and embedded designs. Renesas Electronics provides high-performance buck regulators with integrated FETs for efficient step-down conversion in computing, industrial, and automotive power systems, and Efficient Power Conversion specializes in GaN-based high power density synchronous buck converter evaluation boards and reference designs, such as the EPC9195 and EPC91109 for USB-PD up to 180W, enabling compact, high-efficiency solutions that lower the barrier to adoption for GaN-based architectures.
Differentiation and Emerging Dynamics
Several patterns distinguish the current competitive dynamics. First, integration and reference design quality are becoming decisive. Companies that provide not only the IC but also controller pairings, evaluation boards, and application-specific reference designs reduce time-to-market for customers and reinforce lock-in through ecosystem familiarity. Second, qualification breadth is a strategic asset, particularly in automotive and industrial markets where AEC-Q100 and other reliability standards gate adoption. Third, the GaN ecosystem is fostering collaboration across suppliers, as seen in evaluation boards that pair GaN FETs with controller ICs from different vendors, suggesting that interoperability and reference design availability will matter as much as individual component specifications. Fourth, the market shows signs of both consolidation among scale players and fragmentation by application specialty, with new entrants and incumbents alike pursuing niche leadership in low-IQ portable designs, high-voltage industrial conversion, or GaN-based high power density solutions.
For decision-makers, the practical implication is that supplier selection is increasingly multidimensional. Portfolio breadth matters for platforms that span multiple applications, but application-specific qualification, thermal performance, integration support, and supply continuity can outweigh raw portfolio size in segment-critical deployments.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape the synchronous buck converter market and create distinct commercial opportunities.
One trend is the continued diffusion of wide-bandgap technologies beyond high-end niches into broader mainstream designs. As gallium nitride and silicon carbide adoption matures, efficiency gains of two to five percent and higher switching frequencies that reduce passive component size will become more accessible across industrial, automotive, and computing applications. This creates opportunities for suppliers that can offer qualified, integrated GaN-enabled solutions with strong reference design support, and for system designers that can leverage smaller footprints and improved thermal margins to reduce total cost of ownership.
A second trend is the deepening alignment between power management and application-specific intelligence. Low quiescent current, configurable interfaces, and multi-phase control are increasingly expected, particularly in portable consumer electronics, data center power delivery, and industrial automation. Products that combine efficiency with programmability and diagnostic capabilities will find stronger adoption in designs where power management is integrated into broader system optimization.
A third trend is the continued recalibration of supply chain strategy toward regional resilience and stable sourcing, especially for wide-bandgap discrete devices and power management ICs. Demand from automotive electrification and AI data center buildouts will keep pressure on stable sourcing, while lead time normalization reduces but does not eliminate the need for dual-sourcing and buffer planning. Companies that invest early in qualified alternate sources, onshored or nearshored production options, and transparent traceability will be better positioned to manage volatility.
Potential risks include uneven adoption of wide-bandgap materials due to cost and qualification complexity, regulatory shifts that affect cross-border sourcing, and competitive pressure that compresses margins in commoditizing segments. The balance between integration benefits and component cost premiums will remain a key uncertainty, particularly in price-sensitive consumer and industrial applications.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with application-specific efficiency, integration, and qualification requirements while building reference design capability that accelerates customer adoption. Investing in GaN-compatible architectures, thermal performance, and multi-phase control where relevant can differentiate offerings in computing, automotive, and industrial segments. For investors, the opportunity lies in identifying companies with strong application qualification, ecosystem support, and supply chain resilience rather than relying solely on portfolio size. Segment leadership in low-IQ portable designs, high-voltage industrial conversion, or GaN-based high power density solutions may offer more durable positioning than broad but undifferentiated portfolios.
Worldwide Synchronous Conveyor Market
For procurement and sourcing teams, the practical focus should be on qualifying alternate suppliers, securing stable sourcing for wide-bandgap discrete devices, and building buffer strategies that reflect both normalized lead times and regional redundancy expectations. Evaluating suppliers on reference design quality, qualification breadth, and supply continuity will reduce deployment risk in application-critical designs. Detailed segment-level data and customized sourcing guidance can help translate these priorities into specific supplier shortlists, qualification roadmaps, and inventory strategies tailored to each organization's application mix and risk tolerance.
For detailed analysis of this topic, please visit the official page: Worldwide Synchronous Buck Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Ovulation Microscope Market: Why Portable Devices Drive 5.68% CAGR Growth
By pmarketresearch, 2026-09-18
Navigating the Global Ovulation Microscope Market: Strategic Shifts and Commercial Imperatives Through 2032
The global ovulation microscope market has matured into a distinct niche within the broader at-home fertility and women’s health monitoring ecosystem. Valued at approximately $52.14 million in 2020, the market reached $67.31 million in 2025, and is projected to climb to $99.11 million by 2032. This trajectory reflects a compound annual growth rate of 5.68 percent, signaling steady but disciplined expansion rather than explosive volatility. Growth is being fueled by a structural shift toward decentralized reproductive health management, where consumers increasingly seek non-invasive, repeatable tools that fit into daily routines without recurring consumable costs.
Despite the positive momentum, the sector is confronting several inflection points that will separate sustainable operators from those struggling to justify margins or relevance. First, the market operates with a concentrated competitive base, where the top three players collectively command roughly 38.5 percent of revenue and the top five hold 52.2 percent. This concentration creates both a barrier to rapid diffusion and an opportunity for well-capitalized entrants or acquirers to reshape channel dynamics. Second, the value proposition hinges on behavioral adoption more than clinical urgency. Unlike single-use hormone strips that trigger frequent repurchases, reusable microscopes generate lower ongoing revenue per household, pressuring manufacturers to monetize through ecosystem extensions, digital tracking, and premium positioning. Third, the regulatory perimeter remains defined by over-the-counter fertility device frameworks. While urine-based luteinizing hormone tests benefit from established class exemptions, saliva-based microscopes navigate general controls and historical clearance pathways that underscore the importance of demonstrable equivalence and consumer safety. Companies must therefore balance innovation with compliance rigor, particularly as digital integration and health data collection introduce new scrutiny around privacy and claims substantiation.
These dynamics create a market where scale, clarity of use, and channel trust matter as much as the optical performance of the device itself. Executives evaluating this space must recognize that growth will be uneven across geographies, product architectures, and retail touchpoints, and that long-term positioning depends on how effectively players translate a simple physical tool into a trusted daily health habit.
Key Drivers Reshaping the Ovulation Microscope Landscape
Technological Innovation and Usability Convergence
The most immediate driver of market evolution is the convergence of optical simplicity with digital convenience. Saliva-based ovulation microscopes rely on observing estrogen-induced crystallization patterns, commonly referred to as ferning, in dried saliva samples. Historically, this concept required careful slide preparation and subjective interpretation. Modern iterations have reduced friction by standardizing reusable slides, improving illumination, and embedding companion applications that support cycle logging and result interpretation. The practical effect is a shift from a standalone optical instrument to a behavior-enabling tool. Devices that are compact, rinseable, and designed for daily use lower the barrier to consistent testing, while app-connected workflows help users visualize fertility windows over time. For manufacturers, the strategic implication is clear: hardware differentiation increasingly depends on ergonomics, repeatability, and the quality of the digital companion experience rather than on raw magnification claims alone.
Regulatory Context and the OTC Fertility Device Framework
Regulatory classification continues to shape product architecture, marketing claims, and time-to-market. Saliva ovulation microscopes have historically moved through over-the-counter fertility device pathways, with earlier examples securing clearance based on substantial equivalence for detecting fertile periods through saliva estrogen indicators. More recently, the broader fertility testing landscape has seen continued distinction between urine-based luteinizing hormone tests, which remain class I devices exempt from premarket clearance, and saliva-based microscopes that follow general controls for home-use fertility aids. This regulatory environment does not block innovation, but it reinforces the importance of disciplined claim language, clear user instructions, and evidence-backed accuracy narratives. Companies that align product design with these expectations reduce the risk of post-market friction and build consumer confidence through transparency. For investors and strategists, the takeaway is that compliance readiness is not a back-office concern; it is a differentiator that affects retail placement, channel trust, and brand durability.
Consumer Behavior and the Demand for Non-Invasive, Reusable Tracking
Demand-side shifts are reshaping how consumers evaluate fertility tools. Many users increasingly prefer non-invasive methods that avoid consumables and repeated hormone exposure, particularly for routine cycle awareness rather than acute conception timing. Saliva-based microscopes meet this preference by supporting daily, unlimited testing through a reusable device and dried-sample observation. This model appeals to consumers who want continuous insight without the recurring cost and waste associated with strip-based tests. At the same time, consumer expectations are rising around convenience, clarity, and integrated tracking. A device that is easy to carry, quick to interpret, and compatible with broader wellness routines gains traction more readily than a technically capable but cumbersome alternative. For businesses, this trend underscores the need to design for habit formation: packaging, instructions, storage, and companion features should all reduce cognitive load and encourage consistent use.
Supply Chain, Cost Structures, and Channel Economics
Cost structure and distribution economics remain pivotal in determining which business models can scale. Reusable microscope hardware typically carries a different margin profile than consumable tests, which means revenue growth depends on balancing unit economics with accessory sales, digital services, and bundle offerings. Channel selection also matters. Online retail has become a major discovery and purchase pathway, while pharmacies, drugstores, and clinical channels provide credibility and immediate availability for consumers who prefer in-person purchase experiences. Manufacturers that can optimize packaging, inventory predictability, and brand storytelling for each channel tend to outperform those relying on a single route. In practice, this requires a dual mindset: e-commerce demands clear digital product pages, review management, and direct engagement, while physical retail requires shelf-ready positioning, trusted brand recognition, and retailer confidence in repeat demand.
Competitive Positioning and the Evolution of Market Structure
The competitive field is led by companies that have built recognizable identities around reusable saliva-based fertility tracking, each with a distinct emphasis on accuracy claims, form factor, and cycle-tracking integration. Fairhaven Health has positioned its personal saliva ovulation microscope around at-home fertility tracking through ferning observation, promoting reusability and the ability to conduct unlimited testing. Carson Optical’s OvuScope emphasizes portability and lab-quality optics in a pocket-sized format, developed with clinical input and designed for rinseable slides that support repeated use without consumables. Maybe Mom has historically pursued regulatory clearance for its lipstick-sized reusable device, reinforcing a compact, discreet profile for daily tracking. Hilin Life Products’ KNOWHEN offering combines a built-in microscope with test kits and app integration, aiming to help users identify the most fertile days while supporting cycle tracking through digital tools.
PW Consulting
These players illustrate a broader strategic divergence. One cluster competes on usability and convenience, targeting consumers who value a simple, portable device that fits into daily routines. Another cluster leans into clinical credibility and testing support, pairing hardware with kits, instructions, or app workflows that increase perceived reliability. A third layer of differentiation comes from digital extension: companion apps and cycle-tracking features do not replace the microscope, but they increase engagement, data continuity, and the likelihood of sustained use. In a market where hardware alone can become commoditized, the winners are increasingly those who control the surrounding experience, not just the optical mechanism.
Market structure appears poised for selective consolidation and disciplined new entry rather than unfettered fragmentation. The current concentration suggests that established brands hold meaningful mindshare and channel relationships, making blind replication difficult. At the same time, the rise of online discovery and direct-to-consumer engagement lowers certain barriers for niche entrants with strong branding, clean design, or specialized digital features. Over time, the most likely evolution is a bifurcation: mature incumbents will deepen ecosystem value through apps, accessories, and trusted retail presence, while smaller players will attempt to compete on affordability, design, or targeted consumer segments. Consolidation may occur where channel access, brand trust, or digital infrastructure can be acquired more efficiently than built from scratch. For decision-makers, the strategic question is whether to invest in a durable multi-channel brand, pursue a focused niche with a strong digital hook, or evaluate M&A opportunities that add credibility, distribution, or technology assets.
Forward-Looking Trends and the Commercial Opportunities They Create
Over the next three to five years, three trajectories are likely to shape commercial outcomes. First, the integration of saliva-based microscopy with digital cycle tracking will become a baseline expectation rather than a premium add-on. Consumers increasingly expect their health tools to connect with broader wellness routines, and devices that offer cleaner data entry, visual trend summaries, and reminder functions will have an advantage in retention. The commercial opportunity lies in subscription-adjacent services, premium app features, or bundled kits that increase lifetime value without undermining the reusable hardware model. The risk is that digital features raise expectations around privacy, data security, and clinical claims, requiring disciplined product governance.
Second, channel hybridization will intensify. Online retail will continue to drive discovery and repeat purchases, but pharmacies, drugstores, and fertility clinics will remain important for credibility, impulse purchase, and consumer education. Brands that can maintain consistent messaging across digital and physical touchpoints, while tailoring packaging and in-store support to each environment, will capture a larger share of attentive buyers. The opportunity here is for retailers and manufacturers to co-develop display education, consultative merchandising, and bundle strategies that reduce purchase hesitation. The uncertainty is that channel costs and retailer terms can compress margins if brand differentiation is weak.
Third, consumer expectations around discretion, portability, and ease of interpretation will keep pushing form-factor refinement. Compact, carry-friendly designs and straightforward reading protocols will be critical for habitual use, especially among consumers who are not fertility specialists. Companies that simplify the user journey—sample preparation, viewing, interpretation, and record-keeping—can convert curiosity into a repeatable behavior. The upside is stronger repeat engagement and referral potential; the downside is that any complexity or ambiguous result interpretation can quickly erode trust in a category where confidence is paramount.
Worldwide Augmented Reality Microscope Market
Strategic Actions for Decision-Makers
For manufacturers, the priority is to treat the microscope as the anchor of a broader habit ecosystem rather than as an isolated optical product. That means investing in clear result interpretation, reliable companion workflows, and channel-appropriate packaging that supports both online discovery and retail confidence. Where possible, differentiate through usability, consistency, and transparent claims, because in a reusable-device category, trust and repeat use determine long-term economics.
For investors, the most relevant diligence question is whether a target has a credible path to durable brand equity and channel access, not just a functional device. Look for evidence of consumer retention mechanics, disciplined claims management, and a distribution strategy that can withstand margin pressure from hybrid channels. Targets that combine a defensible brand position with a digital extension and realistic channel economics offer a stronger risk-adjusted profile than those relying on hardware novelty alone.
For procurement and channel partners, the strategic task is to curate a portfolio that balances accessibility with credibility. Saliva-based microscopes can serve consumers who prefer non-invasive, reusable tracking, but their value is maximized when paired with clear instructions, supporting education, and trusted placement. Evaluating suppliers on consistency, claims support, and the ability to provide channel-appropriate merchandising can reduce returns, strengthen shopper confidence, and improve category performance.
Surgical Microscopes Market
For stakeholders seeking a deeper read on segment-level dynamics, regional performance patterns, and tailored competitive scenarios, the full PW Consulting market research report provides expanded data and decision-ready analysis designed for internal planning and investment evaluation.
For detailed analysis of this topic, please visit the official page: Worldwide Ovulation Microscope Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Crowd Management Solution Market: Why 8.5% CAGR and Software Analytics Reshape 2032 Trajectories
By pmarketresearch, 2026-09-18
Crowd Management Solution Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global crowd management solution market has established itself as a critical infrastructure sector, valued at approximately USD 2.5 billion in 2025 and projected to expand at a compound annual growth rate of 8.5 percent through 2032. This trajectory reflects more than incremental growth; it signals a structural shift in how organizations approach public safety, operational efficiency, and visitor experience. Over the past five years, the market has evolved from a fragmented collection of manual security practices into a technology-enabled discipline that integrates real-time analytics, automated monitoring, and coordinated personnel deployment. Trade show venues, sports stadiums, transportation hubs, and urban public spaces now treat crowd flow as a measurable operational variable rather than an unpredictable risk factor.
Despite this momentum, the industry faces a set of interconnected challenges that will shape competitive positioning over the coming years. The first challenge revolves around regulatory tension between advanced monitoring capabilities and privacy expectations. As operators deploy video analytics, sensor networks, and behavioral detection tools, they must navigate evolving data protection frameworks that restrict personal data collection and automated profiling in public environments. Compliance has shifted from a legal checkbox to a strategic design constraint, forcing vendors and end users to architect solutions that deliver visibility without compromising individual privacy.
The second challenge lies in the persistent reliance on large-scale human staffing alongside technology. High-profile events and dense public venues still require thousands of trained personnel to manage access, queueing, emergency response, and guest services. Labor availability, training consistency, and wage inflation create operational volatility that pure software deployments cannot fully absorb. Organizations are now pressured to determine where technology can reduce headcount dependency versus where human judgment remains indispensable, particularly during unplanned surges or incidents.
A third challenge concerns integration complexity. Crowd management no longer exists in isolation; it intersects with access control, video surveillance, communication systems, and venue operations platforms. Buyers frequently encounter fragmented vendor ecosystems, incompatible data streams, and uneven maturity across solution components. The organizations that succeed will be those that can standardize data flow across hardware, analytics, and staffing coordination while maintaining scalability across multiple sites or event types. These challenges do not diminish the market's growth outlook; rather, they define the criteria by which differentiated solutions will win demand.
Key Drivers Shaping Market Evolution
Technology Innovation and Behavioral Analytics
The most transformative driver is the maturation of AI-powered crowd behavior analysis and non-intrusive sensing technologies. Advanced video analytics now enable congestion detection, dwell-time measurement, anomaly recognition, and directional flow mapping in real time. These capabilities move crowd management beyond reactive security toward predictive operational control. At the same time, privacy-first sensing modalities such as LiDAR-based people flow analytics are gaining traction in airports, transport hubs, and event venues. By focusing on aggregate density, queue progression, and movement patterns rather than identifiable personal data, these solutions align operational insight with increasingly stringent privacy norms.
This technological shift has practical commercial implications. Venue operators can optimize staffing allocation, reduce bottleneck-related revenue loss, and improve safety outcomes without relying solely on manual observation. For solution providers, the value proposition is expanding from hazard prevention to operational efficiency and visitor experience enhancement. Companies that combine behavioral analytics with intuitive dashboards and actionable alerting are positioning themselves as operational partners rather than purely security vendors.
Regulatory Environment and Compliance as a Design Discipline
Regulatory developments are actively reshaping solution architecture. Data protection regimes and emerging AI governance frameworks are pushing vendors toward anonymized data processing, transparent data handling, and controls on automated decision-making in public spaces. This environment elevates privacy-by-design from a technical feature to a competitive requirement. Solutions that can demonstrate anonymized flow analytics, limited data retention, and clear usage boundaries are better positioned for public-sector procurement and multinational deployments.
For buyers, regulatory compliance introduces both risk and guidance. It restricts indiscriminate monitoring but also provides a clearer framework for evaluating vendor claims. Procurement teams are increasingly scrutinizing data pipelines, storage practices, and algorithmic transparency before committing to long-term deployments. This dynamic rewards suppliers that can document compliance rigorously and build flexibility into their platforms to accommodate jurisdiction-specific requirements.
PW Consulting Information & Electronics Research Center
Demand-Side Shifts in Visitor Experience and Safety Expectations
Crowd management is increasingly viewed through a dual lens of safety and experience. Event organizers, transport authorities, and commercial venue operators face rising expectations from visitors who expect seamless entry, predictable wait times, and responsive service during peak periods. Simultaneously, risk awareness has increased across public infrastructure, driven by higher attendance volumes, complex event programming, and heightened media scrutiny following operational disruptions.
This demand evolution is changing purchasing behavior. Organizations are investing in integrated crowd management that links flow analytics with access control, guest communication, and staffing dispatch. The goal is not only to prevent incidents but to smooth throughput, reduce friction points, and maintain brand reputation during high-traffic periods. As a result, solution value is being measured by operational continuity and visitor satisfaction alongside traditional security metrics.
Cost Structure and Labor Dynamics
The economics of crowd management continue to be influenced by labor intensity and staffing scalability. Major providers deploy large teams for high-profile events, and the availability of trained personnel remains a constraint in many markets. Wage pressures and turnover intensify the need for tools that improve staff efficiency, enhance situational awareness, and reduce manual coordination overhead.
These cost dynamics encourage a hybrid operating model. Technology handles repetitive monitoring, density threshold alerts, and flow optimization, while human teams focus on exception handling, guest assistance, and incident response. The commercial opportunity lies in solutions that demonstrably improve labor productivity without eroding service quality. Vendors that can connect analytics to staffing dispatch, route guidance, and real-time communication are better aligned with operator economics.
Competitive Landscape and Leading Strategies
Strategic Positioning Across the Value Chain
The competitive field spans traditional security and staffing providers, technology developers, and analytics specialists, each pursuing distinct strategic positioning. Large integrated security firms leverage scale, venue relationships, and multi-service offerings that combine personnel deployment with access control and command-center coordination. Their advantage lies in trusted relationships with event organizers and the ability to deliver end-to-end operational support during complex events. Technology-focused players differentiate through AI-driven behavior analysis, real-time monitoring, and sensor-based flow measurement. Their strength is in converting raw observation into predictive insight, enabling operators to intervene earlier and manage congestion more efficiently.
A distinct segment of entrants emphasizes privacy-preserving analytics and smartphone-sensor-based visitor flow analysis. These approaches attract buyers who need visibility across dense environments while minimizing personal data exposure. The strategic appeal is twofold: they satisfy compliance-sensitive procurement requirements and offer a lighter integration footprint for venues that want flow intelligence without full infrastructure replacement.
Differentiation Through Partnerships and Venue Networks
Recent commercial activity highlights how partnerships are becoming a decisive growth lever. Strategic alliances with large venue networks can dramatically expand deployment reach and standardize solution adoption across multiple sites. Partnerships with specific sports franchises or stadium operators also create high-visibility reference points that validate performance under demanding matchday or event conditions. These collaborations signal a shift from standalone product sales toward embedded operational relationships, where crowd management becomes part of the venue's ongoing service model rather than a one-off implementation.
The commercial implication is clear: distribution advantage increasingly depends on access to venue networks, event calendars, and operational procurement cycles. Providers that can align with venue operating rhythms and demonstrate measurable improvements in flow, safety, and guest service are more likely to secure multi-year relationships.
Market Structure and Evolution Trends
The market remains moderately concentrated, with leading players collectively holding meaningful share but far from dominating the entire ecosystem. This structure leaves room for specialization, particularly in analytics, privacy-first sensing, and vertical-specific deployments. Over the next several years, three patterns are likely to intensify. First, consolidation may accelerate as larger security and technology firms acquire niche analytics capabilities to broaden their offerings. Second, fragmentation may persist in verticals where specialized flow analytics, venue-type expertise, or regional compliance knowledge create durable differentiation. Third, new entrants will continue to emerge around non-intrusive sensing and real-time operational intelligence, especially where privacy expectations and integration simplicity are prioritized.
Content Moderation Solution Market
Competitive success will depend on more than feature breadth. Vendors will be judged on deployment speed, data governance clarity, interoperability with existing access and surveillance assets, and the ability to translate analytics into staffing and operational decisions. The firms that can connect technology outputs to day-to-day venue execution will capture the strongest positioning.
Future Outlook: Trends and Commercial Implications
Convergence of Analytics, Access Control, and Staffing Coordination
Over the next three to five years, crowd management solutions are expected to move toward tighter integration across analytics, access systems, and personnel dispatch. Standalone monitoring will increasingly give way to coordinated workflows where density thresholds trigger staffing adjustments, entry pacing, and guest communication automatically or with minimal manual intervention. This convergence creates commercial opportunity for platforms that can orchestrate multiple functions without requiring full rip-and-replace of existing infrastructure. Vendors that offer modular integration and clear operational playbooks will be better positioned to scale across diverse venues.
Privacy-First Sensing as a Default Expectation
Privacy-preserving technologies are likely to transition from niche alternatives to baseline expectations in many public-facing deployments. As enforcement and public sensitivity increase, solutions that rely on anonymized flow measurement, aggregated density metrics, and minimal personal data capture will gain preference in both public-sector and commercial procurement. This trend opens opportunities for sensor-based analytics and software layers that can retrofit or complement existing environments while maintaining compliance comfort. The risk lies in solutions that depend on data practices requiring continuous legal interpretation or that struggle to demonstrate transparent data handling.
Operational Experience as a Growth Battleground
Crowd management will increasingly be evaluated through its impact on visitor throughput, queue management, and event-day reliability. The commercial narrative is expanding from safety alone to overall venue performance, where smoother crowd flow contributes to revenue protection, reduced congestion complaints, and stronger repeat attendance. Organizations that can quantify these benefits will have stronger justification for investment and expansion. At the same time, uncertainty remains around labor market stability, regulatory evolution, and the pace at which venues standardize integrated platforms. Buyers and suppliers alike will need to manage implementation risk while building evidence of operational ROI.
Implications for Decision-Makers
For technology manufacturers and analytics providers, the priority is to build solutions that combine predictive crowd insight with privacy-conscious data handling and practical integration paths. Differentiation will come from reducing deployment friction, supporting interoperability with access control and existing video assets, and proving that analytics translate into staffing efficiency and throughput improvements. Companies that can package these capabilities into repeatable deployment models will be better positioned to expand across venues and event types.
People Counting System Market
For investors, the market's growth trajectory is supported by durable demand drivers, but value creation will likely concentrate among providers with clear compliance posture, scalable venue partnerships, and credible operational outcomes. Due diligence should assess not only technology sophistication but also data governance, integration complexity, and the ability to move beyond pilot deployments into multi-site contracts. Vertical specialization and privacy-first positioning may offer defensible niches, while broader platforms may win through partnership networks and service integration.
For procurement leaders and venue operators, the most effective approach is to evaluate crowd management as an operational system rather than a discrete security purchase. Criteria should include anonymized data practices, real-time actionability, staffing coordination support, and compatibility with current access and communication infrastructure. Multi-site standardization, vendor responsiveness during live events, and measurable improvements in flow and guest experience should carry significant weight in selection decisions.
Given the speed of regulatory change, technology maturation, and venue-level adoption patterns, detailed segmentation data and customized scenario planning can materially improve investment and procurement decisions. The full research report provides deeper breakdown across solution types, application contexts, regional dynamics, and competitive moves, along with tailored guidance for specific business objectives. For decision-makers seeking to act on these trends with greater precision, the complete analysis offers the level of detail needed to translate market direction into execution.
For detailed analysis of this topic, please visit the official page: Crowd Management Solution Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Chemical Injection Metering Pumps & Valves Market: Why Diaphragm Pumps Drive 3.85% CAGR Growth Beyond 2032
By pmarketresearch, 2026-09-18
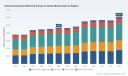
Navigating the Chemical Injection Metering Pumps & Valves Market: Strategic Shifts and Growth Vectors
The Current Market Landscape and Core Challenges
The global chemical injection metering pumps and valves market is experiencing a period of stabilization following a period of robust expansion. Valued at approximately $4.7 billion in 2025, the market has recovered from the pandemic-induced volatility of 2020-2021 and sustained growth through 2024. Current projections indicate a compound annual growth rate of 3.85 percent through 2032, implying a market valuation approaching $6.1 billion by the end of the forecast period. This trajectory signals a maturing market where growth is increasingly driven by replacement cycles, technological upgrades, and targeted capacity additions rather than broad-based industrial expansion.
Several structural challenges are reshaping how participants navigate this environment. First, the industry faces mounting pressure to meet increasingly stringent efficiency and environmental standards while managing rising raw material costs. Volatility in stainless steel and specialty alloy pricing directly affects the cost structure for corrosion-resistant metering pumps and valves, creating margin compression for manufacturers and procurement uncertainty for end-users. Second, the demand profile is fragmenting across applications. Oil and gas remains the dominant segment, but water and wastewater treatment, chemical processing, and emerging industrial applications represent distinct value pools with varying operational requirements, regulatory constraints, and pricing dynamics. Companies attempting to serve all segments with a standardized offering are encountering diminishing returns on engineering resources and commercial positioning.
A third challenge lies in the tension between legacy infrastructure and next-generation requirements. Many operational sites rely on graduated metering systems that prioritize reliability over precision, yet modern processes increasingly demand tighter control, reduced maintenance windows, and integration with digital monitoring platforms. Balancing upgrade economics with the need for enhanced performance is forcing both manufacturers and buyers to make deliberate trade-offs in technology adoption, service models, and total cost of ownership calculations.
Key Drivers Reshaping the Market
Technology innovation is fundamentally altering the competitive calculus in this market. The introduction of next-generation diaphragm metering pumps with expanded flow ranges, improved sealing architectures, and embedded digital connectivity reflects a broader shift toward precision, simplicity, and sustainability in chemical dosing. Recent product launches targeting ranges from milliliters per hour to tens of liters per hour illustrate how manufacturers are closing gaps between low-flow laboratory-grade applications and higher-capacity industrial dosing. Simultaneously, hydraulic diaphragm and solenoid-driven platforms are being refined to meet API 675 specifications, which remain the benchmark for reciprocating positive displacement metering pumps in petroleum, petrochemical, and gas chemical injection services. Compliance with these standards is no longer merely a technical checkbox; it is a commercial differentiator that signals reliability in harsh operating environments.
Regulatory and policy dynamics are acting as both a constraint and an accelerant. In oil and gas, increasing offshore and deepwater exploration activities are driving demand for high-pressure, reliable chemical injection systems that ensure flow assurance and corrosion control. Environmental regulations governing chemical handling, emissions, and wastewater discharge are pushing water treatment and chemical processing operators to upgrade metering accuracy and reduce spill risk. These regulatory pressures are not uniform across geographies, but the directional trend favors solutions that offer verifiable dosing accuracy, longer service intervals, and compatibility with leak-free design principles. Companies that can align product development with these regulatory expectations are gaining procurement preference, particularly in bid environments where lifecycle costs and compliance documentation weigh heavily in selection criteria.
Demand-side behavior is evolving as end-users recalibrate their procurement priorities. Industrial buyers are increasingly evaluating chemical injection equipment not as a standalone commodity but as part of a broader process reliability strategy. This shift is evident in the growing interest in pressure-independent chemical injection metering valves, which enable stable flow distribution across multiple injection points using a single pump source. Such configurations reduce capital intensity, simplify maintenance logistics, and improve dosing consistency in surface and subsea applications. At the same time, electrification and solar-powered pumping options are gaining traction in remote and decentralized installations, reflecting a broader operational push toward energy resilience and reduced dependence on grid-connected infrastructure.
Supply chain and cost structure dynamics continue to exert influence. The interplay between raw material pricing, manufacturing lead times, and regional sourcing strategies is shaping both product pricing and delivery reliability. Manufacturers with integrated casting, machining, and assembly capabilities are better positioned to absorb input cost fluctuations and maintain consistent delivery schedules. Conversely, players reliant on fragmented supplier networks face greater exposure to margin variability and inventory risk. This structural divergence is reinforcing a trend toward capacity consolidation and supplier qualification rigor among large end-users, who are prioritizing supply continuity alongside technical performance.
Competitive Landscape and Leading Strategies
The market features a mix of global platform providers, specialized niche manufacturers, and regional players with strong vertical application expertise. Leadership is not defined solely by scale; it is increasingly determined by the ability to combine technical differentiation with dependable delivery and lifecycle support. Several companies exemplify the strategic positioning shaping the current landscape.
One cohort of leaders focuses on high-pressure, critical-service applications, particularly in oil and gas and chemical processing. These manufacturers emphasize hermetically sealed diaphragm designs, complete chemical injection packages, and adherence to recognized industry standards. Their differentiation rests on engineering depth, proven performance in demanding environments, and the ability to deliver integrated solutions rather than isolated pump units. By aligning product architecture with the operational realities of refinery, upstream, and chemical processing settings, these players secure a premium position in projects where failure risk and downtime costs are decisive factors.
A second group competes through broad portfolio breadth and application coverage. These companies offer hydraulic diaphragm, solenoid-driven, and mechanical diaphragm metering pumps across industrial, water treatment, and chemical dosing segments. Their strategy leverages cross-selling opportunities, shared engineering platforms, and established distribution networks. Recent product introductions in hydraulic diaphragm metering and solenoid-driven chemical metering with advanced drive technologies illustrate how incumbents are renewing their portfolios to maintain relevance across both legacy and emerging applications. The advantage here lies in flexibility: the ability to serve multiple verticals with common components while still addressing segment-specific requirements through configuration and service options.
Balancing Valves Market
A third segment of the market consists of specialists focused on pressure-independent metering valves and niche high-pressure chemical injection solutions. These companies address a specific operational pain point: the need for stable, repeatable flow distribution across multiple injection points without proportional increases in pumping capacity. By enabling one pump to serve multiple points with controlled pressure independence, these specialists create value in surface and subsea oil and gas configurations where flow assurance and chemical distribution efficiency are critical. Their positioning demonstrates how targeted engineering focus can carve out defensible market space even in a broadly competitive environment. Manufacturers producing pneumatic, electric, and solar-driven chemical injection pumps with high-pressure capabilities further diversify the field, particularly for oilfield chemical programs requiring methanol, corrosion inhibitors, and similar applications under extreme operating conditions.
PW Consulting Automotive & Machinery Research Center
The competitive landscape is evolving along several axes. Consolidation remains a plausible pathway for larger players seeking to deepen application coverage, expand geographic reach, or acquire specialized engineering capabilities. At the same time, fragmentation persists in regional markets where local service responsiveness, price competitiveness, and familiarity with regional specification preferences drive procurement decisions. New entrants and smaller specialists continue to gain traction by focusing on precision dosing, digital connectivity, or underserved application niches such as micro-flow industrial dosing and remote-site solar-powered configurations. The net effect is a market where scale provides advantages in platform efficiency and supply chain leverage, but where differentiation increasingly depends on application-specific reliability, compliance alignment, and the ability to support aftermarket service and retrofits.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape the trajectory of this market. The first is the accelerating integration of metering pumps and valves with digital monitoring and control capabilities. Precision dosing, simplified maintenance, and sustainability objectives are pushing manufacturers and end-users toward platforms that offer clearer visibility into operating conditions, wear indicators, and dosing performance. This trend is not about replacing mechanical reliability; it is about augmenting it with data that supports predictive maintenance, reduces unplanned downtime, and improves process consistency. Commercial opportunities will accrue to providers that can package connectivity as a practical operational tool rather than a feature add-on, including those able to support integration with existing control architectures and aftermarket service workflows.
The second trend is the continued divergence between high-pressure, critical-service demand and broader industrial dosing requirements. Offshore and deepwater activity, flow assurance needs, and corrosion control requirements will sustain demand for high-pressure, high-reliability chemical injection systems. At the same time, water and wastewater treatment, chemical processing, and industrial dosing will drive demand for modular, configurable solutions that balance accuracy, cost, and ease of maintenance. Companies that can clearly separate these value pools in their product architecture, sales messaging, and service models will be better positioned to capture margin where it matters most, rather than diluting their offerings across incompatible requirements.
A third trend is the gradual influence of regulatory and cost pressures on procurement behavior. As environmental and operational compliance expectations tighten, buyers are placing greater weight on leak-free design, service intervals, and documented performance. Raw material volatility will continue to challenge cost structures, but it also favors organizations with robust sourcing strategies and engineering efficiency. Risk factors include uneven regional demand cycles, potential overcapacity in certain pump categories, and the possibility that digital connectivity investments outpace the readiness of end-users to absorb and act on the resulting data. Market participants that manage these uncertainties through disciplined product roadmaps and clear application focus are more likely to capture sustainable growth than those pursuing broad, undifferentiated expansion.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to sharpen technology roadmaps around precision, reliability, and practical digital integration while protecting cost competitiveness in materials and production. Rather than stretching across every application, leaders should emphasize differentiated platforms for high-pressure critical service and for modular industrial dosing, each supported by clear service and retrofit strategies. This segmentation allows engineering investment to translate into defensible pricing and stronger customer retention.
Powder Transfer Pumps Market
For investors, the opportunity lies in identifying providers with durable application positioning, disciplined cost structures, and credible aftermarket or service capabilities. The market’s moderate growth rate means outperformance will come from companies that can defend share in oil and gas critical service, expand selectively in water and chemical processing, and capture value from configuration flexibility and replacement cycles rather than relying solely on new equipment demand.
For procurement and operations leaders, the emphasis should shift from lowest initial price toward total cost of ownership, dosing accuracy, compliance alignment, and supply continuity. Evaluating pressure-independent configurations, leak-free designs, and service interval implications can materially affect long-term operating costs, particularly in distributed or remote installations where maintenance complexity is high. Detailed segmentation data, regional demand patterns, and vendor-specific capability comparisons can materially improve procurement decisions and investment timing. Accessing a comprehensive market assessment provides the granularity needed to validate assumptions, model scenarios, and align sourcing strategies with operational priorities.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Houttuynia Extract Market: Why 7.02% CAGR and Asia Pacific’s Dominance Redefine Growth
By pmarketresearch, 2026-09-18
Global Houttuynia Extract Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Critical Challenges
The worldwide market for Houttuynia extract has demonstrated consistent expansion over the past half-decade, with firm revenue trajectories indicating a compounding annual growth rate of approximately 7.02 percent from 2026 through 2032. Starting from a baseline of roughly 176.8 million US dollars in 2025, the sector is projected to surpass 284 million by the close of the forecast horizon. This growth trajectory reflects a broader shift toward botanical and naturally derived ingredients across consumer-facing and industrial applications, yet the underlying dynamics reveal a market that is both maturing and undergoing structural recalibration.
Despite the favorable top-line expansion, several structural challenges are reshaping how participants navigate the space. The first revolves around ingredient standardization and bioactivity consistency. Naturally derived botanical materials exhibit significant variation depending on cultivation geography, harvest timing, plant part utilization, and post-harvest processing methods. These variables directly influence flavonoid profiles, polysaccharide characteristics, and overall therapeutic or cosmetic performance. As downstream formulators demand tighter batch-to-batch consistency, producers face mounting pressure to implement rigorous quality control frameworks while maintaining cost competitiveness. The second challenge stems from regulatory and safety considerations in specific application channels. Historical adverse event monitoring in certain medicinal usage categories highlighted how excipient choices and formulation designs can trigger heightened scrutiny, prompting stricter allergen labeling requirements, quality reexamination protocols, and more conservative risk management approaches. These episodes underscore that regulatory acceptance is not static and that companies must anticipate how safety narratives evolve across different jurisdictions and application segments.
A third inflection point lies in geographic sourcing dynamics and the resulting supply complexity. Cultivation practices vary widely across producing regions, leading to divergent metabolite concentrations that can either constrain or enable targeted applications. Sourcing strategies that once prioritized volume and cost are increasingly being re-evaluated through the lens of functional performance, traceability, and regional quality reputation. Together, these challenges signal a market transitioning from broad commodity-style trading toward a more application-specific, quality-differentiated, and compliance-aware operating environment.
Key Growth Drivers
Technological Innovation in Extraction and Characterization
Advances in extraction methodologies and analytical characterization are fundamentally altering how Houttuynia materials are produced and positioned. Recent scientific investigations have focused on how different extraction approaches influence the structural properties and bioactivities of key constituents, particularly polysaccharides and essential oil fractions. These studies are not merely academic exercises; they provide actionable insight for manufacturers seeking to optimize yield, preserve delicate phytochemical profiles, and tailor ingredient specifications toward specific cosmetic, pharmaceutical, or dietary use cases.
At the commercial level, this research is translating into more refined processing capabilities. Ultrasonic and other precision extraction techniques are gaining visibility among suppliers aiming to deliver cleaner profiles, reduced solvent residues, and enhanced consistency for sensitive personal care formulations. Simultaneously, improved analytical workflows enable producers to verify active marker content more reliably, which is increasingly critical for customers seeking documented functional claims and robust quality assurance packages. The net effect is a gradual elevation of technical barriers to entry and a shift in competitive emphasis from purely price-driven transactions toward specification-driven partnerships.
Evolving Regulatory and Quality Expectations
Regulatory dynamics continue to shape market behavior, particularly where Houttuynia-derived materials intersect with health-related applications. Policy frameworks and pharmacopoeial standards are increasingly attentive to excipient safety, contaminant control, allergen disclosure, and adverse event documentation. While these expectations can raise operational complexity, they also create a defensible moat for manufacturers who have invested early in compliant production systems, transparent documentation, and rigorous batch testing.
In practice, companies that align internal quality architectures with evolving international expectations are better positioned to serve regulated downstream markets, including pharmaceutical-adjacent and premium cosmetic segments. Conversely, suppliers that treat compliance as an afterthought face growing friction when attempting to enter markets where traceability, standardized potency, and documented safety records are non-negotiable. This divergence is gradually concentrating higher-value, specification-sensitive demand toward better-documented production sources, reinforcing the value of quality infrastructure as a strategic asset rather than a cost center.
Demand-Side Shifts Across End-Use Industries
Consumer and corporate purchasing behavior is a powerful driver of market expansion. In personal care, the emphasis on soothing, skin-calming, and irritation-reducing ingredients has increased interest in botanical extracts that align with cleaner-label and dermatologically mindful positioning. Updated product listings and datasheets for Houttuynia-based ingredients marketed for redness reduction and comfort-focused formulations illustrate how suppliers are actively aligning their offerings with these end-user needs.
At the same time, dietary supplement and functional food channels continue to explore botanical ingredients that support natural wellness narratives, while pharmaceutical and medical-adjacent applications retain interest in standardized botanical actives where clinical or traditional usage rationales can be clearly communicated. The overarching pattern is one of channel-specific demand maturation: buyers are no longer purchasing generic botanical powders as undifferentiated inputs; they are seeking ingredients with clearly defined functional attributes, application-relevant documentation, and reliable supply continuity.
Supply Chain Realignment and Cost Structure Pressures
The cost and availability profile of Houttuynia extract is increasingly influenced by sourcing geography, agricultural variability, and processing efficiency. Regional differences in cultivation conditions affect metabolite expression, which in turn shapes the suitability of raw materials for specific end applications. This means sourcing decisions are becoming more nuanced, with procurement teams evaluating not only unit pricing but also functional fit, harvest timing, drying and handling practices, and the consistency of supply across seasons.
Worldwide Hamamelis Virginiana Extract Market
Logistics, testing, and certification costs further compound the total cost of ownership picture. Producers able to streamline harvesting, standardize drying and extraction workflows, and minimize rework through upstream quality control gain structural cost advantages. Such efficiencies matter most when combined with application-focused product design, because they allow suppliers to offer credible performance at competitive price points without compromising the consistency that downstream buyers increasingly expect.
Competitive Landscape and Leading Strategies
The current competitive environment is characterized by a wide field of production-oriented suppliers, with a meaningful concentration of activity among Chinese manufacturing hubs and a smaller but strategically distinct presence from other regions. The market remains moderately fragmented in terms of share distribution, yet competitive differentiation is intensifying along lines of specialization, certification posture, application focus, and technical service capability.
Participants such as Shaanxi Fairir Biotech and Shaanxi LonierHerb Bio-Technology Co., Ltd. operate with a clear emphasis on customized wholesale bulk supply and international merchant engagement, positioning themselves as scale-oriented sources for powder and extract formats. Xi'an Demeter Biotech Co., Ltd. leans into premium positioning, highlighting natural medicinal properties, strict quality control, and wholesale reliability. Hunan Sunfull Bio-Tech Co., Ltd., Changsha Comext Biotech Co., Ltd., Xi'an JT Plant Development Co., Ltd., and Ganzhou Baizhentang Perfumery Co., Ltd. each contribute production capacity across plant and herbal extract categories, reinforcing the breadth of the Chinese manufacturing base. Sinochem Nanjing adds an accredited factory dimension with rigorous quality testing, while Plum Flower illustrates cross-border distribution of single-herb extract formats for traditional medicinal herb channels.
A notable point of differentiation emerges among suppliers that pursue application-specific productization rather than generic bulk sales alone. The Garden of Naturalsolution Co., Ltd., for example, provides Houttuynia Cordata Extract ingredients such as PureCalm oriented toward cosmetic and personal care use, employing ultrasonic extraction methods to align with sensitive formulation requirements. This application-linked branding and processing focus reflects a broader trend in which suppliers seek closer alignment with end-use performance narratives. Similarly, recent product listing and datasheet updates from other market participants highlight active efforts to communicate functional benefits, such as redness and irritation reduction, directly to formulators and procurement teams.
Certification and quality assurance postures further shape competitive positioning. Suppliers with GMP, HACCP, and ISO credentials, alongside consistent internal testing and batch documentation, are better equipped to serve buyers who operate under stricter procurement standards or who require auditable quality records across multiple shipments. In this environment, differentiation is less about visibility alone and more about the ability to demonstrate repeatable performance, responsive technical support, and supply dependability.
Looking forward, the competitive landscape appears likely to follow a dual path. On one side, consolidation may gradually occur among mid-tier producers as scale economics, regulatory readiness, and technical service capabilities become more decisive in securing long-term supply agreements. On the other side, specialization will continue to create space for firms that build recognizable expertise in targeted application segments, whether that means cosmetic-grade extracts, standardized powder formats for dietary use, or regionally sourced materials suited to specific functional profiles. New entrants that can combine efficient processing with credible application documentation and transparent quality systems are likely to find receptive niches, especially where established suppliers remain too generalized to meet emerging formulation demands.
Future Trends and Strategic Outlook
The next three to five years are likely to be defined by a tighter coupling between functional specification and commercial value. As buyers continue to move away from undifferentiated botanical inputs, market pricing and partnership structures will increasingly reward suppliers who can deliver documented active profiles, consistent performance, and clear application fit. This does not mean price becomes irrelevant, but rather that price will be evaluated within a broader framework of quality assurance, technical support, and formulation compatibility.
PW Consulting
A second trend points toward greater regional and application-based sourcing intelligence. Because cultivation conditions and processing choices influence metabolite expression, procurement teams are likely to place higher value on suppliers who can explain why specific origins or production methods are better suited to a particular use case. The ability to match source material characteristics with intended end performance will become a meaningful differentiator, especially in premium personal care and health-adjacent segments.
A third trend concerns the continued elevation of regulatory literacy and safety documentation as commercial enablers. Suppliers that proactively address quality transparency, allergen and excipient considerations, and adverse event awareness will be better positioned to access constrained channels and to maintain credibility if scrutiny intensifies in any given application area. At the same time, uncertainty will persist around standardization expectations, seasonal supply variability, and the pace at which new scientific evidence is translated into commercial claims. Companies that treat these uncertainties as design parameters rather than external shocks will be more resilient in managing inventory, formulation risk, and customer communication.
Strategic Recommendations for Decision-Makers
For manufacturers, the most actionable priority is to align extraction and quality systems with the specification demands of the highest-value channels they intend to serve. This includes investing in application-relevant processing, strengthening batch documentation, and developing clear differentiation around functional performance rather than competing solely on volume pricing.
For investors and corporate development teams, attention should focus on participants with defensible quality infrastructure, credible application positioning, and the operational flexibility to adapt to shifting regulatory expectations. Ass scalability and market access are important, the durability of competitive advantage will increasingly depend on specification reliability, technical service, and the ability to support downstream formulation requirements.
For procurement leaders and formulators, the practical move is to treat sourcing as a performance partnership. Requesting detailed documentation on extraction methods, active marker consistency, 계절적 variation, and application testing can reduce downstream reformulation risk while improving the likelihood of stable supply. Building multi-source strategies that balance cost with functional fit and quality transparency will help protect formulations against the volatility inherent in botanical supply chains.
Baical Skullcap Extract Market
For organizations seeking a more detailed view of segment-level sizing, regional demand patterns, competitive benchmarking, and customized sourcing or expansion scenarios, PW Consulting's full market research report provides deeper data and structured analytical support for planning decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Houttuynia Extract Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Electronic Logbook Software Market: Why a 9.15% CAGR and Cloud Shift Reshape the Industry
By pmarketresearch, 2026-09-18
Electronic Logbook Software Market: Strategic Trends and Commercial Opportunities
Market Landscape and Core Challenges
The electronic logbook software market has entered a phase of sustained expansion, driven by the convergence of digital transformation mandates and stringent operational compliance requirements. Starting from a valuation of USD 1,065.2 million in 2020, the market grew to USD 1,650.0 million by 2025, reflecting a compound annual growth rate of 9.15 percent. Projections indicate the market will surpass USD 3,000 million by 2032, underscoring the structural shift away from paper-based documentation toward integrated digital platforms. This trajectory is not merely a reflection of incremental technology adoption; it represents a fundamental re-architecture of how regulated industries capture, store, and audit operational records.
Despite the favorable growth outlook, the market faces several critical inflection points that will shape competitive outcomes over the next five years. First, legacy system integration remains a persistent barrier. Many industrial facilities and regulated manufacturers operate alongside decades-old operational technology and enterprise resource planning systems that were never designed to interoperate with modern cloud-native logbook solutions. The friction involved in migrating historical records, aligning data formats, and ensuring continuous uptime during transition periods creates hesitation among procurement teams, particularly in environments where downtime carries significant financial or safety consequences.
Second, the compliance burden continues to intensify rather than stabilize. Regulatory frameworks across pharmaceutical manufacturing, energy production, and transportation now demand real-time auditability, tamper-resistant record-keeping, and adherence to principles such as ALCOA+ and 21 CFR Part 11. Organizations that delay digitization expose themselves to inspection findings, including FDA Form 483 observations tied to documentation errors, while those that rush implementation without robust validation protocols risk introducing new compliance vulnerabilities. The tension between speed of adoption and rigor of validation is a defining challenge for the market.
Third, the market is undergoing a concentration dynamic that warrants attention. While the competitive field remains relatively fragmented, the top three players collectively account for approximately 22.45 percent of revenue, and the top five reach 34.12 percent. This distribution suggests that scale advantages are beginning to materialize for established vendors with broad deployment footprints, yet significant room remains for specialized entrants targeting niche compliance scenarios or vertical-specific workflows. Companies that fail to articulate a clear differentiation strategy risk being squeezed between enterprise-scale platforms and highly focused point solutions.
Key Drivers of Market Transformation
Technological Innovation and Data Integrity Architecture
The most immediate catalyst for adoption is the maturation of cloud-based architectures that natively embed compliance and traceability capabilities. Early electronic logbook solutions often functioned as digital replacements for clipboard entries, requiring manual validation and offering limited interoperability. Modern platforms, by contrast, are engineered as data integrity layers that automatically enforce electronic signature workflows, generate immutable audit trails, and align with regulatory expectations out of the box. This shift transforms the logbook from an administrative burden into a strategic asset for operational visibility.
Worldwide Meeting Minutes Software Market
Browser-based deployment models have accelerated this transition by reducing the technological barriers for field operators and shift supervisors. Solutions such as InfoLog 4.0 demonstrate how manufacturing and GMP environments can capture operator activity, task completion, and shift-handoff data without requiring specialized client installations. The removal of infrastructure overhead allows regulated facilities to scale adoption across multiple sites more rapidly, while also simplifying IT governance. Furthermore, the integration of drag-and-drop template customization enables organizations to align log structures with internal standard operating procedures without sacrificing compliance safeguards.
Regulatory Pressure and the Cost of Non-Compliance
Regulatory expectations have moved from periodic documentation reviews to continuous, inspection-ready readiness. In pharmaceutical and life sciences manufacturing, adherence to 21 CFR Part 11 for electronic records and signatures is now a baseline requirement, not a differentiator. The same is true for EU GMP Annex 11, which emphasizes traceability, system validation, and data integrity principles that effectively disqualify many paper-based processes from modern compliance standards. Organizations that continue to rely on manual logs face escalating risk, not only in the form of regulatory observations but also in operational inefficiencies tied to error correction, version control, and retrospective audit preparation.
The healthcare segment illustrates how regulation can spawn entirely new product categories within the broader logbook ecosystem. The recent launch of electronic narcotic log software targeting DEA compliance highlights how specialized regulatory demands create opportunities for vendors to build audit-ready, tamper-resistant tracking systems with inspection-ready reporting capabilities. This pattern is likely to repeat across other regulated domains where documentation precision carries legal and operational weight. On a broader geographic scale, national transport authorities such as Kenya's NTSA are phasing out paper logbooks in favor of centralized electronic systems, reinforcing the global direction toward digitized record-keeping as a regulatory default rather than an optional upgrade.
Demand-Side Shifts and Operational Resilience
Beyond compliance, end-user demand is being reshaped by the need for operational resilience and real-time situational awareness. Power and utilities operators, for example, increasingly depend on electronic rounding and maintenance logs to detect anomalies before they escalate into service disruptions. In industrial manufacturing, shift-to-shift communication gaps have historically led to duplicated efforts, missed handoff notes, and delayed incident response. Cloud-based logbook platforms that provide live dashboards, searchable history, and structured handoff protocols directly address these pain points, making them attractive not only to compliance officers but also to operations leaders focused on throughput and safety.
The end-user mix reflects this broadening value proposition. Industries with high regulatory density and complex operational workflows, including oil and gas, maritime operations, and chemical and pharmaceutical manufacturing, continue to anchor demand. At the same time, the addressable base is expanding as organizations in adjacent sectors recognize that digital log management can reduce error rates, shorten audit cycles, and improve cross-functional visibility. The result is a market where the value narrative has evolved from "replace paper" to "enable continuous operational intelligence."
Supply-Side Dynamics and Integration Economics
Supply-side factors are also influencing the pace of adoption. Cloud-based deployment now represents the dominant revenue stream, reflecting both buyer preference for lower upfront capital expenditure and vendor incentives to build recurring, subscription-oriented revenue models. This structural shift pressures vendors to continuously deliver feature updates, security enhancements, and integration connectors that justify ongoing subscription costs. At the same time, consolidation activity is beginning to reshape the supply landscape. Strategic acquisitions, such as the acquisition of Informetric Systems by Datacor, signal a move toward bundling electronic logbook capabilities with broader manufacturing intelligence and data aggregation platforms. For customers, this trend creates both opportunities and trade-offs: integrated platforms can reduce vendor fragmentation, but they may also limit flexibility for organizations that prefer best-of-breed components.
Cost structures are further affected by the growing expectation that logbook software should interoperate with existing enterprise systems rather than operate as a silo. Vendors that invest in open APIs, configurable data export pathways, and validation-ready documentation packages are better positioned to reduce the total cost of ownership for customers navigating complex IT environments. Conversely, solutions that require heavy customization or manual data reconciliation risk longer implementation timelines and higher hidden costs, which can slow procurement decisions in cost-conscious sectors.
Competitive Landscape and Strategic Positioning
The competitive field in the electronic logbook software market is defined by a blend of specialized compliance vendors, vertically focused platforms, and emerging entrants targeting niche regulatory scenarios. Incumbents have built defensible positions by aligning product architecture with the documentation standards most critical to their target segments. For example, vendors serving life sciences manufacturing emphasize data integrity, electronic signature compliance, and template flexibility to meet the expectations of quality assurance and regulatory affairs teams. Platforms built around drag-and-drop configuration and customizable templates reduce the friction of adapting log structures to site-specific procedures, which is often the difference between rapid adoption and prolonged pilot stagnation.
Other players have carved out advantages through secure, audit-ready log management designed for regulated environments that demand traceability and electronic signatures. These solutions typically focus on reducing the time and cost associated with audit preparation while ensuring that records withstand regulatory scrutiny. In industrial settings, cloud-based logbook tools aimed at shift work and operational awareness prioritize real-time communication, operator activity capture, and shift-to-shift continuity. This differentiation matters because the buying committee in industrial contexts often includes operations managers and plant supervisors who evaluate usability and workflow fit as heavily as compliance features.
A distinct competitive vector has emerged around highly specialized regulatory use cases. In healthcare, electronic narcotic log software built for DEA compliance illustrates how targeted functionality, real-time tracking, tamper-resistant audit trails, and inspection-ready reporting can create a strong value proposition in a narrow but high-stakes segment. Similarly, browser-based logbooks engineered for manufacturing and GMP environments have gained traction by addressing the practical needs of operator rounds, task tracking, and shift data capture without imposing heavy IT requirements. These focused approaches allow vendors to compete on depth rather than breadth, appealing to organizations that prioritize rapid compliance alignment over expansive feature sets.
Strategic positioning also increasingly depends on demonstration of real-world adoption and integration credibility. Customer transitions to electronic logging for operational data in utility environments, for instance, serve as reference points that validate the feasibility of deployment in live operational settings. When a regulated or public-utility organization moves from paper to digital logs, it signals to prospective buyers that the solution can handle the practical demands of day-to-day data capture while maintaining compliance integrity. Such adoption stories are becoming essential currency in a market where perceived implementation risk still slows many procurement decisions.
The market is evolving through a combination of consolidation, specialization, and selective new entry. Acquisition activity suggests that larger industrial intelligence and data management providers view electronic logbook capabilities as a natural extension of their platforms, particularly when log data can feed into broader analytics, validation, or manufacturing execution workflows. At the same time, the relatively fragmented share structure indicates that smaller, agile vendors can still win by solving a specific compliance or workflow problem exceptionally well. New entrants are likely to continue appearing where regulatory requirements are tightening faster than incumbent platforms can adapt, especially in segments where documentation precision carries direct legal or operational consequences. The most successful players will be those that balance compliance rigor with operational usability, while also building credible integration pathways that reduce long-term total cost of ownership.
Forward-Looking Trends and Strategic Implications
Over the next three to five years, the electronic logbook market is likely to be shaped by three interconnected trends. The first is the shift from standalone logbook tools toward integrated compliance and operational data platforms. As organizations accumulate structured log data across shifts, sites, and processes, the value of that data will increasingly be measured by its usefulness in downstream analytics, audit automation, and operational decision-making. Vendors that enable log data to flow securely into broader enterprise workflows will capture more sustained relevance than those that treat the logbook as an isolated repository.
Electronic Flight Bag Market
The second trend is the deepening of compliance-by-design as a market expectation rather than a premium feature. Regulatory scrutiny around electronic records, signatures, audit trails, and data integrity is not receding; it is becoming more prescriptive and more enforced across jurisdictions. Solutions that can demonstrate validation readiness, configurable control frameworks, and inspection-ready reporting will be preferred, especially in pharmaceutical, healthcare, and energy contexts where documentation failures carry disproportionate consequences. This trend will also accelerate geographic expansion where national authorities are mandating electronic systems, creating new demand waves that early movers can capture if they adapt to local regulatory nuances.
The third trend is the growing premium on usability and field-level adoption. A logbook platform can be fully compliant on paper yet fail in practice if operators find it cumbersome, slow, or disconnected from their daily routines. Interfaces that reduce data entry burden, support mobile and browser-based access, and provide clear handoff and search capabilities will differentiate in competitive evaluations. The commercial opportunity here lies in reducing the human friction that often undermines digitization initiatives, thereby improving data quality and adoption rates simultaneously.
Potential risks should not be underestimated. Implementation complexity in heterogeneous IT environments can delay value realization, particularly where legacy systems and heavy validation requirements coexist. Vendor consolidation may also create uncertainty for customers who value flexibility or who fear migration friction if platforms are deprecated or rebranded. Finally, regulatory divergence across regions and sectors can complicate global rollouts, requiring vendors and buyers alike to navigate differing expectations without sacrificing core data integrity principles. Organizations that approach these risks with disciplined vendor evaluation, phased deployment, and clear compliance mapping will be better positioned to convert market momentum into durable operational gains.
PW Consulting Information & Electronics Research Center
Actionable Recommendations for Decision-Makers
For manufacturers and regulated operators, the priority should be to evaluate electronic logbook solutions through a dual lens of compliance assurance and operational fit. Selection criteria must go beyond feature checklists to include validation support, integration pathways with existing enterprise systems, and evidence of field usability in environments similar to your own. A phased rollout that starts with high-impact use cases, such as operator rounds, shift handoffs, or audit-sensitive documentation, can reduce risk while building internal confidence in digital workflows.
For investors and strategic buyers, the market offers opportunities in vendors that combine credible compliance architecture with clear deployment economics and expanding integration capabilities. Particular attention should be paid to companies that have demonstrated real-world adoption in regulated settings, developed defensible positions in specialized compliance niches, or strengthened their platforms through acquisitions that add manufacturing intelligence or data aggregation functionality. Monitoring where consolidation is likely to occur can also reveal valuation signals and partnership possibilities before the broader market fully prices in those shifts.
For procurement and IT leaders, the focus should be on total cost of ownership rather than initial license or subscription pricing. Solutions that require extensive customization, manual reconciliation, or prolonged validation cycles can erode projected savings and extend time-to-value. Prioritizing platforms with configurable templates, robust audit-ready documentation, and transparent integration options will help ensure that logbook investments support both compliance objectives and broader operational efficiency goals. Businesses seeking detailed segmentation data, vendor scorecards, and tailored implementation pathways can gain further clarity by reviewing the full PW Consulting market research report, which provides a deeper breakdown of regional dynamics, deployment trends, and end-user adoption patterns.
For detailed analysis of this topic, please visit the official page: Electronic Logbook Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Commercial Decorative Lighting Market: Beyond 5.45% CAGR, the Real Growth Drivers
By pmarketresearch, 2026-09-18
Strategic Trends and Commercial Opportunities in the Decorative Lighting Market
1. Market Landscape and Core Challenges
The commercial decorative lighting market has transitioned from a supplementary design element to a central component of built-environment strategy. Revenue reached an estimated $17.9 billion in 2025, expanding from $12.5 billion in 2020. The trajectory indicates a compound annual growth rate of 5.45 percent through 2032, with projected valuation approaching $25.9 billion. Growth is no longer linear; it is increasingly shaped by overlapping forces of aesthetic demand, technological maturation, and macroeconomic volatility. Industry participants navigating this environment must recognize that scale alone will not guarantee resilience. The market’s structure favors operators who can align design innovation with supply-chain agility and regulatory compliance.
Three structural challenges define the current inflection point. First, raw material cost pressure is reshaping margin economics. Aluminum and copper prices climbed notably in 2025, with Chinese aluminum spot rates surpassing 21,000 RMB per ton. Because raw inputs typically represent 70 to 80 percent of operating expenses in LED lighting manufacturing, cost volatility flows directly into fixture pricing and contract negotiations. Second, trade policy adjustments have amplified input costs. Higher U.S. tariffs on steel and aluminum imports throughout 2025 have forced manufacturers to either absorb expenses, renegotiate supplier terms, or pass costs downstream. Third, the convergence of decorative aesthetics with connected lighting systems is accelerating, but integration complexity is rising. Buyers expect visually compelling fixtures that also deliver dimming precision, daylight responsiveness, and network compatibility, raising the bar for engineering and certification resources.
These pressures are reshaping competitive expectations. Firms that rely on static product lines or fragmented sourcing face compression in profitability, while those that treat decorative lighting as a performance-driven design category are better positioned to capture premium placements. The market’s next phase will reward operators who can decouple value creation from raw material exposure and translate design intent into reliable, specification-friendly outcomes.
2. Key Demand Drivers Shaping Market Direction
Technology innovation continues to redefine the commercial decorative segment. LED performance has moved beyond baseline efficiency to embrace refined color rendering, thermal management, and form-factor flexibility. Contemporary product releases emphasize advanced LED performance paired with updated aesthetics, allowing decorative fixtures to meet hospitality and retail expectations without sacrificing energy targets. Additive manufacturing is also gaining traction in niche architectural applications, enabling faster prototyping and customized geometries that traditional tooling struggles to achieve. These advances shorten development cycles and expand the visual vocabulary available to specifiers.
Christmas Lights and Christmas Decorations Market
Policy and regulatory dynamics are simultaneously redirecting procurement priorities. Energy codes and sustainability mandates are pushing commercial projects toward fixtures that combine visual impact with measurable performance. The regulatory environment favors connected systems that support scheduling, occupancy response, and centralized monitoring. At the same time, trade measures on steel and aluminum imports have altered cost calculations for manufacturers, making material strategy a competitive variable rather than a back-office concern. Companies are responding by diversifying supplier bases, re-evaluating bill-of-materials architecture, and emphasizing designs that reduce dependency on tariff-sensitive inputs.
Demand-side behavior has shifted decisively. Retail and hospitality operators continue to treat lighting as a brand-expression tool, using decorative luminaires to influence dwell time, atmosphere, and perceived quality. Office environments are integrating decorative elements to support hybrid work identity and occupant well-being, while public and institutional projects increasingly specify fixtures that balance visual character with lifecycle efficiency. The result is broader specification activity across application types, with buyers evaluating decorative lighting not as an accessory but as part of a holistic spatial strategy.
Supply-chain and cost-structure adjustments are reinforcing these trends. Because raw materials account for the majority of manufacturing operating expenses, firms are prioritizing design-for-manufacturability, component commonality, and inventory planning that can absorb commodity swings. Recent trade show showcases and product launches illustrate how manufacturers are aligning outdoor decorative formats, interior pendants, and architectural wall units with both aesthetic refinement and production efficiency. The overall effect is a market where design differentiation and cost discipline must advance together.
3. Competitive Landscape and Leadership Strategies
The competitive environment remains moderately consolidated, with leading players holding meaningful share while specialized manufacturers compete on design authority and application expertise. Broad-portfolio providers compete through scale, specification support, and integrated product ecosystems. Their advantage lies in offering commercial indoor and outdoor decorative and architectural luminaires under established brand frameworks, enabling project teams to consolidate sourcing and simplify specification. Global lighting leaders extend this model with connected systems, energy-efficient fixtures, and wide geographic reach, positioning decorative lighting as part of broader professional solutions.
Design-focused manufacturers pursue a different path. Firms specializing in decorative and architectural LED fixtures concentrate on pendants, chandeliers, track, recessed, and commercial-grade formats tailored for hospitality, retail, and office settings. Their differentiation typically comes from refined proportions, material credibility, and close collaboration with architects and interior designers. Another segment of the market emphasizes high-end architectural and decorative lighting for interiors and exteriors, particularly retail and hospitality environments, where visual precision and finish quality drive specification decisions. Additional players bring decorative high-bay, cylinder, and architectural luminaires to commercial projects, with some exploring 3D-printed lighting approaches that open new pathways for custom forms and faster iteration.
Strategic positioning among leaders reflects a clear divide between breadth and depth. Large portfolios win when projects require multi-product consistency, broad availability, and integrated support. Niche specialists win when design intent is specific, finishes must be exact, and the project team values curated aesthetics over catalog convenience. Recent market activity reinforces both paths. New contemporary releases have expanded portfolios with refined aesthetics and advanced LED performance for commercial and hospitality spaces. Outdoor decorative introductions, including lantern-style LED post-top fixtures, highlight growing interest in streetscape, plaza, and entry-zone aesthetics. Major expos have also showcased architectural and decorative products aimed at commercial applications, signaling sustained demand for visually led yet performance-aligned solutions.
PW Consulting Automotive & Machinery Research Center
Market evolution is likely to continue along two tracks. Consolidation will remain attractive for buyers seeking procurement simplicity, warranty alignment, and specification continuity. At the same time, fragmentation will persist where design differentiation, regional taste, and custom architectural requirements create room for specialized entrants. New participants can gain traction by targeting underserved application niches, leveraging agile manufacturing, or combining decorative credibility with connected-function capabilities. The competitive edge will increasingly belong to firms that can articulate a clear design language while managing material exposure and specification complexity.
4. Future Trends and Commercial Implications
Over the next three to five years, decorative lighting in commercial environments is likely to move toward stronger integration between visual design and intelligent performance. Fixtures will be expected to do more than define a style; they will need to support adaptive dimming, tunable output where appropriate, and compatibility with broader building systems. This shift creates opportunities for manufacturers that can embed control readiness without compromising aesthetic integrity, and for specifiers who can standardize decorative families across multiple zones while preserving flexibility.
A second trend will be continued pressure on input costs and the resulting emphasis on material strategy. Because raw materials dominate manufacturing expense structures, firms that secure diversified sourcing, optimize component selection, and design for manufacturability will hold a cost advantage. Opportunities will emerge for product lines that maintain visual premium perception while reducing exposure to volatile metals and tariff-sensitive inputs. This also favors modular architectures that allow finish variation without redesigning core luminaire platforms.
A third trend involves application-driven customization across retail, hospitality, office, and public environments. Specification activity is broadening as buyers treat decorative lighting as part of spatial identity rather than a decorative afterthought. This opens room for tailored solutions in entry sequences, feature ceilings, retail display areas, and exterior pedestrian zones. The uncertainty lies in policy continuity, commodity pricing, and the pace at which connected-system standards mature. Firms that prepare for variation rather than assume stability will navigate these shifts more effectively. The commercial opportunity is clear: operators that align design credibility with performance reliability and supply resilience can capture higher-value placements and repeat specification cycles.
5. Strategic Actions for Decision Makers
Manufacturers should prioritize design platforms that can adapt to material volatility without abandoning aesthetic quality. That means investing in modular fixtures, control-ready internals, and sourcing strategies that reduce dependency on any single metal or import pathway. Leaders should also treat decorative lighting as a specification relationship business, strengthening collaboration with architects, designers, and facility teams so that product credibility translates into repeat project inclusion.
LED Lighting Market
Investors should evaluate exposure to both design differentiation and cost discipline. Companies with strong portfolio breadth may benefit from consolidation and specification simplification, while specialized players may offer attractive positioning if they serve high-value hospitality, retail, or architectural segments with clear finish and form advantages. Due diligence should examine raw-material sensitivity, tariff exposure, and the ability to integrate connected features without eroding margin.
Procurement leaders and specifier organizations should look beyond catalog variety and assess how decorative fixtures perform across lifecycle expectations, maintenance access, and control integration. Standardizing families where possible can reduce project risk, while reserving bespoke selections for feature zones can preserve design impact. Given the speed of product releases, trade-show activity, and shifting trade policy, timely access to detailed segment data and tailored scenario planning can improve sourcing decisions and reduce specification friction. For teams seeking deeper segmentation, competitive benchmarking, and customized strategic options, the full commercial decorative lighting market report provides expanded data and decision-ready breakdowns.
For detailed analysis of this topic, please visit the official page: Commercial Decorative Lighting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Germacrene D Market 5.02% CAGR: Why Fragrance Demand Drives $29.3M Growth by 2032
By pmarketresearch, 2026-09-18
Germacrene D Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The global market for Germacrene D has demonstrated consistent expansion over the past five years, moving from approximately $16.5 million in 2020 to an estimated $20.8 million in 2025. This trajectory reflects a compound annual growth rate of 5.02 percent, with projections indicating the market will reach $29.3 million by 2032. The steady upward curve underscores growing industrial reliance on specialized sesquiterpenes across multiple application verticals. However, beneath these aggregate figures lies a complex landscape shaped by supply chain vulnerabilities, regulatory evolution, and shifting consumer expectations.
One of the most pressing challenges facing market participants is the convergence of raw material volatility and sustainability mandates. Germacrene D is primarily sourced as a sesquiterpene from essential oils of plants such as Solidago canadensis or produced via microbial fermentation from renewable sugar-based feedstocks. Both pathways carry distinct risk profiles. Botanical extraction is subject to agricultural yield fluctuations, climate variability, and land-use constraints, while fermentation-based routes demand capital-intensive bioreactor infrastructure and face scaling bottlenecks. Companies must navigate these dual supply realities while maintaining cost competitiveness and meeting increasingly stringent environmental standards.
A second critical inflection point involves the tightening regulatory framework governing fragrance and flavor ingredients. Recent safety assessments have clarified the risk profile of Germacrene D, with a 2024 evaluation concluding no genotoxicity or skin sensitization concerns at current declared fragrance use levels. While this provides regulatory certainty, it also raises the bar for documentation, traceability, and compliance verification. Suppliers must invest in robust quality management systems and maintain alignment with evolving standards such as EU Regulation (EC) No 1334/2008 and US CFR 101.22 for natural flavor use. The burden of compliance disproportionately affects smaller manufacturers, potentially accelerating market consolidation.
A third structural challenge lies in balancing purity requirements across divergent application segments. The market spans natural extract grades with specified purity levels alongside high-purity reagent grades used in research and specialized formulations. Each grade demands distinct production protocols, validation procedures, and customer engagement models. Manufacturers that attempt to serve both segments without clear operational segmentation risk margin erosion, quality inconsistencies, or brand positioning conflicts. The ability to cleanly separate production streams and communicate value propositions to different buyer personas has become a decisive competitive factor.
Key Drivers of Market Evolution
Technological Innovation and Fermentation Breakthroughs
Advancements in microbial fermentation have fundamentally altered the supply dynamics of Germacrene D. Fermentation-based production enables consistent output independent of seasonal agricultural cycles, reduces reliance on land-intensive crop cultivation, and aligns with circular economy principles when paired with renewable sugar feedstocks. Several industry participants have demonstrated that carefully optimized bioprocesses can achieve purity levels suitable for flavor and fragrance applications while maintaining certifications such as kosher, halal, and pesticide-free status. These capabilities expand the addressable market by offering formulators a reliable, scalable alternative to botanical extraction, particularly in regions where agricultural supply chains face disruption or where traceability requirements are intensifying.
Beyond production methods, downstream formulation technologies are also shaping demand. The integration of Germacrene D into complex fragrance architectures requires precise understanding of its olfactory profile, stability characteristics, and interaction with other aroma chemicals. Suppliers that invest in application labs, sensory evaluation capabilities, and technical support services create stickier customer relationships and command premium positioning. This shift from commoditized molecule supply to integrated solution provision represents a meaningful margin opportunity for organizations willing to build technical depth.
Regulatory Clarity and Certification Momentum
Regulatory developments have moved from ambiguous risk discussions to more definitive safety conclusions, providing a foundation for confident commercialization. The affirmation of a FEMA GRAS number and compliance with major food and fragrance regulations reduce barriers to adoption in end-use products. Concurrently, certification renewals and expansions, such as the renewal of kosher certification for fermentation-derived Germacrene D through early 2026, signal ongoing commitment to dietary and religious compliance standards that matter to global brand owners.
These regulatory and certification dynamics are not merely compliance exercises; they function as market access enablers. Multinational consumer goods companies require ingredient suppliers to demonstrate harmonized compliance across multiple jurisdictions. Suppliers that proactively maintain and document certifications across EU, US, and international frameworks reduce friction in the procurement process and become preferred partners for large-scale formulation projects. The regulatory environment thus rewards completeness and transparency over speed-to-market alone.
Demand-Side Shifts Toward Natural and Sustainable Ingredients
Consumer and brand preferences continue to gravitate toward natural-origin and sustainably sourced ingredients. In the fragrance and personal care sectors, this trend drives formulators to seek sesquiterpenes that can deliver characteristic woody-spicy, minty, or herbal notes while meeting clean-label expectations. The commercial appeal extends beyond marketing narratives; it influences procurement specifications, supplier qualification criteria, and long-term contract structures. Brands are increasingly willing to pay a premium for ingredients that combine verified natural status with reliable supply and consistent sensory performance.
Parallel demand is emerging from agricultural pheromone applications, where Germacrene D serves as a component in insect attractant and mating disruption formulations. This segment benefits from broader agricultural trends emphasizing reduced synthetic pesticide reliance and integrated pest management strategies. While smaller in absolute terms compared to fragrance and cosmetics, the agricultural pheromone segment offers diversification benefits and growth potential tied to regulatory pressure on conventional agrochemicals and expanding adoption of biocontrol methods.
Supply Chain Restructuring and Cost Dynamics
Cost structures in the Germacrene D market are being reshaped by logistics complexity, energy input requirements, and the economics of scale. Fermentation-based routes, while offering supply stability, involve significant upfront capital expenditure and operational expertise in bioprocess engineering. Botanical extraction pathways face fluctuating input costs tied to crop yields and geographic sourcing constraints. In both cases, organizations that achieve scale, optimize yield per unit of input, and streamline downstream purification can establish meaningful cost advantages.
Farnesene Market
Supply chain resilience has also become a strategic priority. Buyers are increasingly evaluating suppliers not only on price and purity but on geographic diversification, inventory buffering capabilities, and contingency planning. The market concentration, with the top three participants holding a modest share and the top five capturing a slightly larger portion, indicates room for both specialized niche players and larger diversified ingredient companies. This fragmentation creates opportunities for regional suppliers to secure local partnerships while inviting larger entities to pursue selective acquisitions that broaden geographic reach and technical portfolios.
Competitive Landscape and Leading Strategies
Differentiation Through Positioning and Technical Capability
Market participants have adopted distinct strategic postures that reflect their organizational capabilities and target customer segments. Some companies emphasize fermentation-derived natural Germacrene D with comprehensive dietary and regulatory certifications, positioning themselves as reliable partners for flavor and fragrance formulators who require clean-label compliance and consistent supply. This approach combines biotechnological manufacturing with rigorous quality documentation, appealing to brand owners who prioritize transparency and auditability.
Other organizations focus on high-purity reagent and fragrance-grade products packaged for industrial and research use. These suppliers cater to application development, analytical testing, and specialized formulation work, where purity specifications and packaging integrity take precedence over natural-origin claims. By maintaining strict quality controls and offering flexible packaging options, these participants serve a different buyer persona that values technical precision and rapid availability over certification breadth.
Large flavor and fragrance houses with diversified botanical extraction capabilities include Germacrene D within broader portfolios of natural-origin ingredients. Their strategic advantage lies in integrated supply chains, established customer relationships, and the ability to offer formulation guidance alongside raw material supply. For these organizations, Germacrene D is one element of a larger sustainable sourcing narrative, supported by eco-friendly extraction practices and long-standing botanical expertise. Their scale and brand recognition provide credibility with multinational clients, while their portfolio breadth allows cross-selling and formulation synergy.
Recent Strategic Moves and Market Signals
Recent industry activity highlights how participants are sharpening their competitive positioning. A fermentation-based supplier renewed kosher certification for its natural Germacrene D product, reinforcing its commitment to dietary compliance and maintaining eligibility for markets where such certification is a procurement prerequisite. This type of certification maintenance may appear routine, but it signals ongoing operational discipline and protects market access in segments where religious and dietary standards influence purchasing decisions.
A major global fragrance and flavor company introduced a Germacrene D-based fragrance ingredient as part of an expanded natural-origin portfolio. This launch illustrates the use of targeted molecule development to refresh ingredient offerings, respond to formulator demand for specific olfactory profiles, and reinforce sustainability messaging. By embedding Germacrene D within a broader portfolio narrative, the company leverages the molecule's sensory characteristics while aligning with brand-level commitments to natural sourcing.
Another significant move involved a strategic partnership between two ingredient companies to co-develop sustainable fragrance ingredients, including Germacrene D, with an emphasis on resilient natural sourcing. Collaborative development arrangements allow participants to share technical risk, pool botanical or bioprocess expertise, and accelerate time-to-market for improved ingredients. Such partnerships also reflect an industry-wide recognition that sustainability and supply resilience are not easily achieved in isolation; they often require joint investment in sourcing relationships, process optimization, and certification alignment.
Sclareolide Market
Market Structure Evolution
The competitive landscape is undergoing gradual transformation rather than abrupt disruption. Market concentration remains moderate, indicating that no single entity dominates supply and that differentiated positioning can still yield viable market share. Over the forecast horizon, several dynamics are likely to shape structure. Larger ingredient companies may pursue selective acquisitions to fill technical gaps, expand geographic coverage, or bring fermentation capabilities in-house. Specialized manufacturers with unique purity profiles, certification portfolios, or regional sourcing advantages can maintain strong niche positions by serving customers who value specificity over breadth. New entrants with novel bioprocess technologies or alternative feedstock strategies may emerge if they can demonstrate cost parity, regulatory compliance, and scalable production.
The overall trend points toward a market where value creation shifts from volume-only competition to capability-based differentiation. Suppliers that combine reliable production, regulatory completeness, technical support, and sustainability credentials will be better positioned to command favorable terms and build long-term partnerships. Conversely, participants that compete solely on price without clear quality or compliance differentiation may face margin pressure as buyers increasingly weigh total cost of ownership and supply risk.
PW Consulting Chemical & Energy Research Center
Future Trends and Commercial Implications
Convergence of Natural Certification and Biotechnological Scale
Over the next three to five years, the intersection of natural-certification requirements and fermentation scalability will likely become a central theme. As formulators seek ingredients that satisfy both sensory expectations and sustainability mandates, suppliers capable of delivering certified natural-status molecules through reproducible bioprocesses will capture growing demand. The commercial opportunity lies in offering a credible alternative to botanically sourced sesquiterpenes while maintaining documentation that satisfies global regulatory and consumer expectations. Organizations that invest early in process optimization, certification breadth, and supply transparency can establish defensible positions before the segment becomes crowded.
Expansion of Application Diversification
Application diversification represents another meaningful trend. While fragrance and cosmetics continue to anchor demand, agricultural pheromone formulations and specialized research uses provide adjacent growth avenues. The agricultural segment, in particular, benefits from structural shifts toward reduced synthetic pesticide reliance and increased adoption of behavioral pest control methods. Suppliers that develop technical expertise in pheromone formulation requirements, stability testing, and field-performance considerations can extend their reach beyond traditional aroma chemical markets. This diversification also serves as a hedge against cyclicality in consumer-facing fragrance spending, smoothing revenue profiles across economic cycles.
Regulatory and Compliance Sophistication as Competitive Moat
Regulatory sophistication will increasingly function as a competitive moat rather than a baseline requirement. As safety assessments solidify and certification frameworks mature, the ability to maintain harmonized compliance across jurisdictions becomes a differentiator. Buyers will favor suppliers that provide clear documentation, predictable audit outcomes, and proactive engagement with evolving standards. The risk side of this trend involves the possibility of regulatory divergence across regions or the emergence of new substance-specific requirements that challenge existing production or labeling practices. Companies that monitor regulatory developments closely and maintain flexible quality systems will be better prepared to adapt without disrupting customer supply.
Strategic Recommendations for Decision Makers
For manufacturers and ingredient suppliers, the priority is to clarify segment focus and align operational capabilities with the value propositions that matter most to target customers. Companies serving fragrance and flavor formulators should invest in certification maintenance, application support, and supply transparency. Those focused on high-purity reagent or research-grade markets should emphasize quality control rigor, packaging integrity, and technical documentation. In both cases, building a clear narrative around sourcing, production method, and compliance status helps reduce customer uncertainty and supports pricing discipline.
Investors evaluating opportunities in this space should weigh the balance between scale advantages and specialization premiums. Larger diversified ingredient platforms offer portfolio breadth and customer relationships that can absorbGermacrene D within broader sustainable sourcing strategies. Specialized participants with differentiated fermentation capabilities, certification portfolios, or regional sourcing strengths may offer attractive growth profiles if they can demonstrate reproducible quality and market access. Due diligence should examine production scalability, regulatory standing, customer concentration, and the durability of any purity or certification advantages.
For procurement leaders and formulation teams, supplier selection should extend beyond unit price to encompass compliance documentation, supply resilience, technical support, and long-term sourcing strategy. Engaging suppliers that can articulate their production method, certification status, and continuity planning reduces downstream risk and facilitates smoother product development cycles. Early involvement of ingredient suppliers in formulation projects can also surface technical considerations before they become costly redesigns.
Market participants and investors seeking detailed segmentation data, competitive benchmarking, and customized scenario analysis will find value in consulting the complete research report, which provides deeper breakdowns of regional dynamics, purity-grade trends, application-specific demand patterns, and firm-level strategic profiles.
For detailed analysis of this topic, please visit the official page: Germacrene D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Indirect Gas-fired Make-up Air Unit Market: The 5.3% CAGR Reality Beyond 2032 Forecast
By pmarketresearch, 2026-09-18
Navigating the Strategic Landscape of the Worldwide Indirect Gas-fired Make-up Air Unit Market
Market Overview and Core Challenges
The global indirect gas-fired make-up air unit market has demonstrated steady expansion over the past half-decade, evolving from a niche HVAC component into a critical infrastructure element for industrial and commercial facilities. Valuation metrics from 2020 through 2025 indicate a consistent upward trajectory, with the market reaching approximately 878 million USD by 2025. Looking ahead, projections suggest continued growth through 2032, driven by replacement cycles, new construction, and retrofit activities. The compound annual growth rate reflects moderate but resilient expansion, signaling a maturing market that is increasingly sensitive to operational efficiency and regulatory compliance rather than pure volume growth.
Despite this positive momentum, the industry stands at a strategic inflection point defined by several persistent challenges. First, the balance between upfront capital expenditure and long-term operational savings remains a friction point for project owners. Indirect gas-fired units offer significant advantages in terms of air quality and combustion safety compared to direct-fired alternatives, but they often carry higher initial costs and complex installation requirements. Decision-makers in commercial and industrial sectors are increasingly scrutinizing total cost of ownership, pushing suppliers to justify premium pricing with demonstrable energy savings and durability.
Second, the regulatory environment is tightening across major regions, particularly regarding ventilation standards and energy efficiency. Compliance is no longer a checkbox exercise but a dynamic requirement that varies by jurisdiction and building type. Facilities managers must navigate a patchwork of codes that dictate airflow rates, combustion safety, and thermal performance. This complexity increases the barrier to entry for smaller players and elevates the value of manufacturers who can provide compliant, pre-engineered solutions that simplify approval processes.
Third, supply chain volatility and raw material fluctuations introduce uncertainty into pricing and lead times. The production of critical components, such as heat exchangers, is subject to commodity price swings and manufacturing capacity constraints. For instance, recent movements in steel markets and the valuation growth of the North America heat exchanger sector highlight how upstream cost pressures can ripple through to finished equipment pricing. These dynamics demand that manufacturers adopt more agile sourcing strategies and potentially pass through cost adjustments while maintaining competitiveness.
Key Drivers of Market Change
Technological Innovation and Performance Enhancement
Advancements in burner technology, heat exchanger design, and control systems are reshaping the value proposition of indirect gas-fired make-up air units. Manufacturers are increasingly offering modular configurations with modulating capabilities, allowing units to adjust output based on real-time demand. This flexibility improves energy efficiency and reduces fuel consumption during partial-load conditions, which is a significant consideration for facilities with variable ventilation needs. High-efficiency heat exchangers maximize thermal transfer while minimizing the footprint of the equipment, addressing space constraints in mechanical rooms and rooftop installations. Furthermore, integration with building management systems and advanced controls enables precise management of temperature, humidity, and air quality, aligning with broader trends toward smart building infrastructure.
Building Dedicated Outdoor Air System Market
Recent product documentation releases from leading companies underscore a focus on usability and comprehensive system integration. For example, updated start-up guides and installation manuals now include detailed control specifications and variable air volume options, reflecting an industry-wide emphasis on making complex systems easier to commission and operate. These documentation improvements support the adoption of indirect gas-fired technology by reducing the technical burden on contractors and facility staff, thereby accelerating deployment in commercial kitchens, industrial spaces, and institutional settings.
PW Consulting
Policy and Regulatory Environment
Regulatory frameworks are acting as both a constraint and a catalyst for market growth. Standards governing gas-fired equipment safety and performance, such as those maintained by ASHRAE and ANSI, provide the baseline for product certification and ensure consistent quality across regions. However, local building codes are increasingly embedding stricter ventilation and energy efficiency requirements. In California, for instance, the 2025 Building Energy Efficiency Standards, effective for permits applied on or after January 1, 2026, include strengthened mechanical system and ventilation mandates that directly impact HVAC equipment selection. Such regulations push facility owners toward compliant, higher-performance units that can meet elevated standards without compromising indoor air quality or thermal comfort.
The regulatory landscape also favors indirect-fired systems over direct-fired alternatives in applications where combustion byproducts must be fully isolated from the supplied air. This dynamic reinforces demand in sensitive environments such as healthcare facilities, food processing plants, and commercial kitchens, where air quality and safety are paramount. Manufacturers that proactively design for compliance and can navigate regional code variations gain a distinct competitive edge, as they reduce the risk and delay associated with permitting and inspection.
Demand-Side Shifts in Commercial and Industrial Sectors
Changes in how buildings and factories operate are altering ventilation requirements and, consequently, the demand for make-up air units. In industrial manufacturing, processes that generate heat, moisture, or airborne contaminants require reliable replacement air to maintain safe working conditions and operational efficiency. The trend toward decentralization and flexible manufacturing layouts means that ventilation systems must be adaptable and scalable. Similarly, in commercial buildings, the emphasis on occupant health and indoor environmental quality has elevated the importance of dedicated outdoor air systems and well-controlled make-up air solutions. Post-pandemic awareness has reinforced the link between ventilation and health, prompting asset owners to prioritize systems that deliver consistent, filtered, and tempered air.
Institutional and healthcare facilities represent another growing segment where precise air handling is critical. These environments often have stringent requirements for temperature stability, humidity control, and filtration to support infection control and patient comfort. Indirect gas-fired units that offer optional DX cooling and heat recovery capabilities are well-positioned to meet these demands. The convergence of health, safety, and comfort priorities is expanding the addressable market beyond traditional industrial applications, creating new revenue streams for manufacturers that can tailor solutions to diverse end-user needs.
Supply Chain and Cost Structure Dynamics
The cost structure of indirect gas-fired make-up air units is influenced by multiple factors, including raw material prices, manufacturing efficiency, and logistics. The health exchanger market, a key component segment, has seen valuation growth that reflects both demand and cost pressures. Volatility in steel and other metals can affect production costs, while regional manufacturing capacity and supply chain resilience determine lead times and delivery reliability. Companies that invest in localized production, strategic inventory management, and diversified supplier bases are better equipped to mitigate disruptions and maintain competitive pricing.
Moreover, the value of service and support is becoming more pronounced in the overall cost equation. Customers increasingly expect comprehensive documentation, technical assistance, and long-term maintenance support as part of the purchase. This shift means that total value is not solely determined by equipment price but by the reliability of the entire lifecycle offering. Manufacturers that can deliver consistent quality, timely support, and clear operational guidance reduce the hidden costs of ownership, making their products more attractive in a cost-conscious market.
Competitive Landscape and Leading Strategies
The market is characterized by a moderately concentrated competitive environment, with a mix of specialized manufacturers and broader HVAC conglomerates. Leading companies differentiate themselves through product specialization, regional presence, and solution-oriented approaches. Greenheck, for example, offers a broad range of indirect gas-fired make-up air units with high-efficiency furnaces and modulating options, catering to commercial and industrial applications with capacities spanning thousands of CFM. Their focus on detailed installation and operation documentation highlights a commitment to supporting proper deployment and long-term performance, which resonates with contractors and facility managers seeking reliability.
Modine HVAC provides a portfolio of indoor and outdoor indirect-fired systems designed for tempered outdoor air delivery in commercial and industrial buildings. Their product lines include power-vented and separated combustion options, allowing them to address diverse installation constraints and ventilation requirements. Trane contributes with rugged, compact units suitable for both indoor and outdoor use, emphasizing durability and versatile heating, cooling, and ventilating capabilities. AbsolutAire specializes in ventilation systems for contaminant control, positioning its make-up air units as integral components for industrial and commercial environments where air quality management is critical.
Wall Mounted Gas Boiler Market
Regional players and specialized manufacturers also play important roles. Halton, based in Finland, offers ETL-listed indirect-fired units for commercial kitchens, industrial spaces, and institutional facilities, with options for DX cooling and heat recovery, aligning with the growing demand for multifunctional systems. Accurex focuses on commercial kitchen environments with horizontally firing burners designed to maximize heat exchanger life, addressing a specific pain point in high-use settings. AAON and Applied Air contribute packaged dedicated outdoor air systems and ventilation solutions that integrate indirect gas-fired heating, appealing to customers seeking consolidated, engineered solutions. Cambridge Air Solutions distinguishes itself with patented low-fire start technology and stainless steel burners, emphasizing performance and longevity in commercial and industrial applications.
The competitive landscape is evolving through a combination of consolidation, specialization, and incremental innovation. Larger HVAC firms may seek to expand their share through acquisitions or by broadening their product portfolios to cover more segments, while niche players often compete on technical expertise, custom engineering, and responsive service. New entrants face high barriers due to the need for certification, established distribution networks, and the trust of specifiers and contractors. However, opportunities exist for companies that can introduce differentiated features, such as enhanced efficiency, smart controls, or modular designs that simplify installation and retrofit. Market dynamics are also shaped by the emphasis on documentation and support; companies that provide clear, up-to-date guidance and maintain robust customer education efforts reduce adoption friction and strengthen their position with end-users.
Future Trends and Commercial Opportunities
Over the next three to five years, the indirect gas-fired make-up air unit market is likely to be shaped by a few interconnected trends. First, efficiency and integration will become even more central to value creation. As energy costs and sustainability goals gain prominence, facilities will prioritize units that deliver precise air handling with minimal waste. Manufacturers that combine high-efficiency heat exchangers, modulating burners, and advanced controls with optional cooling and heat recovery will capture demand from customers seeking to optimize both comfort and operating expenses. The ability to integrate seamlessly with broader building management ecosystems will be a key differentiator, enabling data-driven operation and predictive maintenance.
Second, regulatory harmonization and code evolution will continue to influence product design and market access. As more regions adopt stringent ventilation and energy standards, there will be increased demand for pre-compliant solutions that reduce the complexity of permitting and commissioning. Companies that invest in certification, regional compliance mapping, and flexible product platforms will be well-positioned to serve markets where codes are tightening. This trend also favors partnerships with engineering firms and contractors who can specify compliant systems early in the design process, locking in market share before construction begins.
Third, the market may see gradual consolidation as larger players acquire specialized firms to expand their geographic reach or technical capabilities, while smaller manufacturers focus on niche applications where they can command premium positioning. Supply chain resilience will remain a strategic priority, with companies diversifying sourcing and investing in inventory buffers to manage raw material volatility. For commercial opportunities, the strongest growth potential lies in retrofit projects where existing systems need upgrading to meet new codes or improve efficiency, as well as in sectors like healthcare and institutional facilities where air quality requirements are intensifying. However, risks include potential economic slowdowns that could delay capital projects, as well as the possibility of alternative technologies gaining traction if they offer comparable performance at lower cost. Manufacturers and investors should monitor these dynamics and align their strategies with the segments and regions where demand momentum is most robust.
Strategic Actions for Decision-Makers
For manufacturers, the priority should be to deepen differentiation through efficiency, control integration, and lifecycle support. Investing in product platforms that can be configured for a wide range of applications while maintaining compliance with evolving codes will help capture share across commercial, industrial, and institutional end-users. Emphasis on documentation, training, and post-sale support can reduce adoption barriers and build long-term customer relationships, which are increasingly valuable in a market where total cost of ownership matters more than initial price.
For investors, attention should focus on companies with strong technical capabilities, diversified end-user exposure, and resilient supply chains. Evaluating how well a company navigates regulatory changes and raw material fluctuations can provide insight into its ability to sustain margins and growth. Opportunities may also exist in segments where retrofit demand and code-driven upgrades create recurring revenue streams, particularly in regions where ventilation standards are tightening.
For procurement and facility management teams, the focus should be on aligning equipment selection with operational goals and compliance requirements from the outset. Engaging with suppliers early to ensure that proposed systems meet current and anticipated codes can streamline approval processes and avoid costly redesigns. Considering total cost of ownership, including energy efficiency, maintenance needs, and support availability, will lead to better long-term outcomes than focusing solely on upfront price.
Staying ahead in this market requires access to detailed segmentation data, regional dynamics, and competitive intelligence that go beyond high-level trends. Comprehensive research provides the granularity needed to make informed decisions about product development, market entry, procurement strategy, and investment allocation. For those seeking deeper insights, exploring the full range of analysis on the worldwide indirect gas-fired make-up air unit market can reveal the specific opportunities and risks that matter most to your organization.
For detailed analysis of this topic, please visit the official page: Worldwide Indirect Gas-fired Make-up Air Unit Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com