

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Chemical Injection Metering Pumps & Valves Market: Why Diaphragm Pumps Drive 3.85% CAGR Growth Beyond 2032

Navigating the Chemical Injection Metering Pumps & Valves Market: Strategic Shifts and Growth Vectors
The Current Market Landscape and Core Challenges
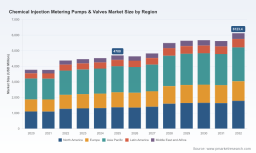
The global chemical injection metering pumps and valves market is experiencing a period of stabilization following a period of robust expansion. Valued at approximately $4.7 billion in 2025, the market has recovered from the pandemic-induced volatility of 2020-2021 and sustained growth through 2024. Current projections indicate a compound annual growth rate of 3.85 percent through 2032, implying a market valuation approaching $6.1 billion by the end of the forecast period. This trajectory signals a maturing market where growth is increasingly driven by replacement cycles, technological upgrades, and targeted capacity additions rather than broad-based industrial expansion.
Several structural challenges are reshaping how participants navigate this environment. First, the industry faces mounting pressure to meet increasingly stringent efficiency and environmental standards while managing rising raw material costs. Volatility in stainless steel and specialty alloy pricing directly affects the cost structure for corrosion-resistant metering pumps and valves, creating margin compression for manufacturers and procurement uncertainty for end-users. Second, the demand profile is fragmenting across applications. Oil and gas remains the dominant segment, but water and wastewater treatment, chemical processing, and emerging industrial applications represent distinct value pools with varying operational requirements, regulatory constraints, and pricing dynamics. Companies attempting to serve all segments with a standardized offering are encountering diminishing returns on engineering resources and commercial positioning.
A third challenge lies in the tension between legacy infrastructure and next-generation requirements. Many operational sites rely on graduated metering systems that prioritize reliability over precision, yet modern processes increasingly demand tighter control, reduced maintenance windows, and integration with digital monitoring platforms. Balancing upgrade economics with the need for enhanced performance is forcing both manufacturers and buyers to make deliberate trade-offs in technology adoption, service models, and total cost of ownership calculations.
Key Drivers Reshaping the Market
Technology innovation is fundamentally altering the competitive calculus in this market. The introduction of next-generation diaphragm metering pumps with expanded flow ranges, improved sealing architectures, and embedded digital connectivity reflects a broader shift toward precision, simplicity, and sustainability in chemical dosing. Recent product launches targeting ranges from milliliters per hour to tens of liters per hour illustrate how manufacturers are closing gaps between low-flow laboratory-grade applications and higher-capacity industrial dosing. Simultaneously, hydraulic diaphragm and solenoid-driven platforms are being refined to meet API 675 specifications, which remain the benchmark for reciprocating positive displacement metering pumps in petroleum, petrochemical, and gas chemical injection services. Compliance with these standards is no longer merely a technical checkbox; it is a commercial differentiator that signals reliability in harsh operating environments.
Regulatory and policy dynamics are acting as both a constraint and an accelerant. In oil and gas, increasing offshore and deepwater exploration activities are driving demand for high-pressure, reliable chemical injection systems that ensure flow assurance and corrosion control. Environmental regulations governing chemical handling, emissions, and wastewater discharge are pushing water treatment and chemical processing operators to upgrade metering accuracy and reduce spill risk. These regulatory pressures are not uniform across geographies, but the directional trend favors solutions that offer verifiable dosing accuracy, longer service intervals, and compatibility with leak-free design principles. Companies that can align product development with these regulatory expectations are gaining procurement preference, particularly in bid environments where lifecycle costs and compliance documentation weigh heavily in selection criteria.
Demand-side behavior is evolving as end-users recalibrate their procurement priorities. Industrial buyers are increasingly evaluating chemical injection equipment not as a standalone commodity but as part of a broader process reliability strategy. This shift is evident in the growing interest in pressure-independent chemical injection metering valves, which enable stable flow distribution across multiple injection points using a single pump source. Such configurations reduce capital intensity, simplify maintenance logistics, and improve dosing consistency in surface and subsea applications. At the same time, electrification and solar-powered pumping options are gaining traction in remote and decentralized installations, reflecting a broader operational push toward energy resilience and reduced dependence on grid-connected infrastructure.
Supply chain and cost structure dynamics continue to exert influence. The interplay between raw material pricing, manufacturing lead times, and regional sourcing strategies is shaping both product pricing and delivery reliability. Manufacturers with integrated casting, machining, and assembly capabilities are better positioned to absorb input cost fluctuations and maintain consistent delivery schedules. Conversely, players reliant on fragmented supplier networks face greater exposure to margin variability and inventory risk. This structural divergence is reinforcing a trend toward capacity consolidation and supplier qualification rigor among large end-users, who are prioritizing supply continuity alongside technical performance.
Competitive Landscape and Leading Strategies
The market features a mix of global platform providers, specialized niche manufacturers, and regional players with strong vertical application expertise. Leadership is not defined solely by scale; it is increasingly determined by the ability to combine technical differentiation with dependable delivery and lifecycle support. Several companies exemplify the strategic positioning shaping the current landscape.
One cohort of leaders focuses on high-pressure, critical-service applications, particularly in oil and gas and chemical processing. These manufacturers emphasize hermetically sealed diaphragm designs, complete chemical injection packages, and adherence to recognized industry standards. Their differentiation rests on engineering depth, proven performance in demanding environments, and the ability to deliver integrated solutions rather than isolated pump units. By aligning product architecture with the operational realities of refinery, upstream, and chemical processing settings, these players secure a premium position in projects where failure risk and downtime costs are decisive factors.
A second group competes through broad portfolio breadth and application coverage. These companies offer hydraulic diaphragm, solenoid-driven, and mechanical diaphragm metering pumps across industrial, water treatment, and chemical dosing segments. Their strategy leverages cross-selling opportunities, shared engineering platforms, and established distribution networks. Recent product introductions in hydraulic diaphragm metering and solenoid-driven chemical metering with advanced drive technologies illustrate how incumbents are renewing their portfolios to maintain relevance across both legacy and emerging applications. The advantage here lies in flexibility: the ability to serve multiple verticals with common components while still addressing segment-specific requirements through configuration and service options.
Balancing Valves Market
A third segment of the market consists of specialists focused on pressure-independent metering valves and niche high-pressure chemical injection solutions. These companies address a specific operational pain point: the need for stable, repeatable flow distribution across multiple injection points without proportional increases in pumping capacity. By enabling one pump to serve multiple points with controlled pressure independence, these specialists create value in surface and subsea oil and gas configurations where flow assurance and chemical distribution efficiency are critical. Their positioning demonstrates how targeted engineering focus can carve out defensible market space even in a broadly competitive environment. Manufacturers producing pneumatic, electric, and solar-driven chemical injection pumps with high-pressure capabilities further diversify the field, particularly for oilfield chemical programs requiring methanol, corrosion inhibitors, and similar applications under extreme operating conditions.
PW Consulting Automotive & Machinery Research Center
The competitive landscape is evolving along several axes. Consolidation remains a plausible pathway for larger players seeking to deepen application coverage, expand geographic reach, or acquire specialized engineering capabilities. At the same time, fragmentation persists in regional markets where local service responsiveness, price competitiveness, and familiarity with regional specification preferences drive procurement decisions. New entrants and smaller specialists continue to gain traction by focusing on precision dosing, digital connectivity, or underserved application niches such as micro-flow industrial dosing and remote-site solar-powered configurations. The net effect is a market where scale provides advantages in platform efficiency and supply chain leverage, but where differentiation increasingly depends on application-specific reliability, compliance alignment, and the ability to support aftermarket service and retrofits.
Forward-Looking Trends and Commercial Implications
Over the next three to five years, three trends are likely to shape the trajectory of this market. The first is the accelerating integration of metering pumps and valves with digital monitoring and control capabilities. Precision dosing, simplified maintenance, and sustainability objectives are pushing manufacturers and end-users toward platforms that offer clearer visibility into operating conditions, wear indicators, and dosing performance. This trend is not about replacing mechanical reliability; it is about augmenting it with data that supports predictive maintenance, reduces unplanned downtime, and improves process consistency. Commercial opportunities will accrue to providers that can package connectivity as a practical operational tool rather than a feature add-on, including those able to support integration with existing control architectures and aftermarket service workflows.
The second trend is the continued divergence between high-pressure, critical-service demand and broader industrial dosing requirements. Offshore and deepwater activity, flow assurance needs, and corrosion control requirements will sustain demand for high-pressure, high-reliability chemical injection systems. At the same time, water and wastewater treatment, chemical processing, and industrial dosing will drive demand for modular, configurable solutions that balance accuracy, cost, and ease of maintenance. Companies that can clearly separate these value pools in their product architecture, sales messaging, and service models will be better positioned to capture margin where it matters most, rather than diluting their offerings across incompatible requirements.
A third trend is the gradual influence of regulatory and cost pressures on procurement behavior. As environmental and operational compliance expectations tighten, buyers are placing greater weight on leak-free design, service intervals, and documented performance. Raw material volatility will continue to challenge cost structures, but it also favors organizations with robust sourcing strategies and engineering efficiency. Risk factors include uneven regional demand cycles, potential overcapacity in certain pump categories, and the possibility that digital connectivity investments outpace the readiness of end-users to absorb and act on the resulting data. Market participants that manage these uncertainties through disciplined product roadmaps and clear application focus are more likely to capture sustainable growth than those pursuing broad, undifferentiated expansion.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to sharpen technology roadmaps around precision, reliability, and practical digital integration while protecting cost competitiveness in materials and production. Rather than stretching across every application, leaders should emphasize differentiated platforms for high-pressure critical service and for modular industrial dosing, each supported by clear service and retrofit strategies. This segmentation allows engineering investment to translate into defensible pricing and stronger customer retention.
Powder Transfer Pumps Market
For investors, the opportunity lies in identifying providers with durable application positioning, disciplined cost structures, and credible aftermarket or service capabilities. The market’s moderate growth rate means outperformance will come from companies that can defend share in oil and gas critical service, expand selectively in water and chemical processing, and capture value from configuration flexibility and replacement cycles rather than relying solely on new equipment demand.
For procurement and operations leaders, the emphasis should shift from lowest initial price toward total cost of ownership, dosing accuracy, compliance alignment, and supply continuity. Evaluating pressure-independent configurations, leak-free designs, and service interval implications can materially affect long-term operating costs, particularly in distributed or remote installations where maintenance complexity is high. Detailed segmentation data, regional demand patterns, and vendor-specific capability comparisons can materially improve procurement decisions and investment timing. Accessing a comprehensive market assessment provides the granularity needed to validate assumptions, model scenarios, and align sourcing strategies with operational priorities.
For detailed analysis of this topic, please visit the official page: Chemical Injection Metering Pumps & Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com