

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Worldwide Synchronous Buck Converter Market: What 6.55% CAGR Means for 2032

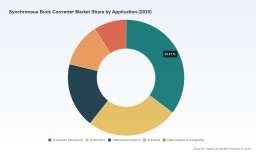
Strategic Trends and Commercial Opportunities in the Worldwide Synchronous Buck Converter Market
Market Overview and Core Challenges
The global synchronous buck converter market has entered a phase of sustained expansion, with the total market size reaching approximately $4.6 billion in 2025. Measured from 2020 through the forecast horizon extending to 2032, the sector demonstrates a compound annual growth rate of 6.55 percent, reflecting steady demand across power management applications. Revenue units are tracked in millions of USD, underscoring the commercial scale of this component category. The trajectory from 2020 to 2025 shows consistent year-over-year growth, with the market crossing the $3.3 billion mark in the early part of the decade and accelerating through the mid-2020s as electrification, data center buildouts, and consumer electronics refresh cycles converge. Projections through 2032 point toward a market exceeding $7.2 billion, driven by structural shifts rather than cyclical demand alone.
Three critical challenges define the current industry inflection point. First, the balance between performance and manufacturability is tightening as designs push toward higher switching frequencies and wider input voltage ranges. Engineers are increasingly tasked with maintaining thermal stability and electromagnetic compatibility while shrinking form factors, a constraint that places pressure on component suppliers to deliver integrated solutions without sacrificing reliability. Second, supply chain resilience has moved from a background concern to a board-level priority. Geopolitical tensions and export controls on semiconductors have accelerated onshoring initiatives, particularly in the United States, reshaping how power management ICs are sourced, qualified, and deployed across regions. Lead times for semiconductors have eased from the peaks observed in 2022, yet procurement strategies now require dual-sourcing flexibility and buffer planning that were less critical in earlier cycles. Third, the transition toward wide-bandgap materials is not uniformly adopted across all application segments. While gallium nitride and silicon carbide enable meaningful efficiency gains and support higher switching frequencies that reduce passive component size, the cost premium and qualification complexity create a phased adoption curve that varies by end-use and region.
These dynamics create a market that rewards companies capable of navigating technical complexity, supply chain volatility, and application-specific qualification requirements simultaneously. The overall concentration of the market, with the top three players holding a combined share near 38 percent and the top five near 52 percent, indicates that scale, portfolio breadth, and ecosystem integration matter, but there remains meaningful room for differentiated positioning by application or technology focus.
Key Drivers Shaping Market Trajectory
Several interconnected forces are propelling the synchronous buck converter market forward, and each carries distinct implications for product roadmaps, sourcing strategies, and investment allocation.
Technology Innovation and Wide-Bandgap Adoption
Advancements in wide-bandgap semiconductors are fundamentally improving efficiency and power density in synchronous buck converters, particularly for electric vehicle, data center, and renewable energy applications. The shift toward gallium nitride and silicon carbide enables efficiency gains on the order of two to five percent while supporting higher switching frequencies, which in turn reduces the size of passive components in synchronous buck designs. This is not simply a marginal improvement; it changes the design calculus for systems where thermal headroom, footprint, and conversion losses directly affect total cost of ownership. Recent product activity illustrates the pace of this transition. In October 2025, Texas Instruments released the LMG708B0, an 80V input, 20A output high power density GaN synchronous buck converter with reference designs incorporating frequency spread spectrum, targeting industrial, automotive, and computing applications where efficiency and integration are priorities. Around the same timeframe, Efficient Power Conversion launched the EPC91109, an ultra-compact 180W GaN-based two-phase synchronous buck converter evaluation board for USB-PD 3.1 applications, built around EPC2057 GaN FETs and an Analog Devices LTC7890 controller. These releases signal that GaN integration is moving from niche high-performance use cases into broader power delivery and compact power applications.
Policy, Regulation, and Supply Chain Realignment
Regulatory and geopolitical dynamics are reshaping where and how power management components are produced and qualified. Export controls and semiconductor-related tensions have accelerated onshoring initiatives in the United States, influencing supply chains for power management ICs including synchronous buck converters. At the same time, global supply chain dynamics for gallium nitride and silicon carbide discrete devices are being influenced by automotive electrification and AI data center demand, with a clear focus on stable sourcing. Average semiconductor lead times have decreased from a peak of 26.5 weeks in 2022 to around 15 weeks in 2024, easing pressure on production of power management components, but the structural preference for regional redundancy and qualified alternate sources remains. For manufacturers and procurement teams, this means that compliance, traceability, and multi-region qualification are becoming part of the baseline rather than exceptional requirements.
Demand-Side Shifts Across End-Use Segments
Demand is being reshaped by simultaneous growth in automotive electrification, data center and high-performance computing buildouts, and continued refresh cycles in consumer electronics. Automotive power architectures are increasingly requiring efficient step-down conversion for traction, gate drive, and auxiliary systems, while industrial and telecommunications infrastructure demands reliable conversion across wider input ranges. Consumer electronics continue to push for low quiescent current and compact footprints, especially in portable and battery-powered devices. Recent product introductions reflect these demand signals. In December 2025, Diodes Incorporated introduced a 5.5V, 4A low IQ synchronous buck converter with a versatile I²C interface designed for portable and compact power applications, addressing consumer electronics, computing, communications, and industrial markets. Such developments indicate that efficiency, intelligence, and integration are becoming table stakes across segments, even as the relative weight of each requirement differs by application.
PW Consulting
Cost Structure and Integration Trends
Cost structures are shifting as integration deepens and passive component reduction offsets some of the material cost premiums associated with wide-bandgap devices. Suppliers are emphasizing power efficiency, integration, and wide input ranges to help system designers manage bill-of-materials complexity while meeting performance targets. The result is a market where competitive advantage increasingly depends on reference design quality, qualification breadth, and the ability to support customers through application-specific integration challenges rather than on component pricing alone.
Competitive Landscape and Leading Strategies
The competitive field in synchronous buck converters is defined by a mix of broad-portfolio semiconductor leaders and specialized players that compete on technology depth, application focus, or integration advantage. The top three companies collectively hold roughly 38 percent of the market, and the top five reach just over 52 percent, indicating a landscape where scale and portfolio coverage provide meaningful leverage, but differentiation remains viable through technology positioning and application-specific solutions.
Strategic Positioning of Leaders
Texas Instruments maintains a broad portfolio spanning high-voltage and high-current synchronous buck converter ICs, including GaN-integrated solutions such as the LMG708B0 for industrial, automotive, and computing applications. Its emphasis on efficiency, integration, and wide input ranges aligns with the trend toward higher power density and application versatility. STMicroelectronics offers monolithic synchronous buck regulator ICs with input voltage capability up to 61V and output currents up to 4A, along with AEC-Q100 qualified isolated buck solutions targeted at automotive, industrial, and EV traction and gate drive systems, reflecting a strong orientation toward automotive-qualified and safety-relevant applications. Infineon Technologies supplies high-performance synchronous buck converters and dedicated synchronous buck driver ICs optimized for efficiency in computing, industrial, and automotive power management, with a focus on integration and thermal performance that addresses the thermal constraints of higher-density designs.
Synchronous Condenser Market
Analog Devices delivers synchronous buck regulators and controllers, including GaN-compatible offerings such as the LTC7890 and LTC7891, supporting high power density, multi-phase operation, and wide voltage ranges for data center, industrial, and high-performance computing needs. Its controller-centric approach complements the GaN ecosystem and positions the company well for applications where multi-phase and high-power density architectures are required. ON Semiconductor manufactures synchronous buck converter solutions for consumer, industrial, and automotive sectors, emphasizing power efficiency and integration in voltage regulation applications. Diodes Incorporated offers low-IQ synchronous buck converters, including a 5.5V, 4A device with an I²C interface announced in December 2025, targeting consumer electronics, computing, communications, and industrial markets with compact, high-efficiency designs. ROHM Semiconductor produces integrated FET synchronous buck DC/DC converters such as the BD9P series for high-efficiency voltage conversion in automotive, industrial, and consumer applications, while Microchip Technology supplies DC-DC switching synchronous buck converters and regulators with features tailored to power-sensitive industrial and embedded designs. Renesas Electronics provides high-performance buck regulators with integrated FETs for efficient step-down conversion in computing, industrial, and automotive power systems, and Efficient Power Conversion specializes in GaN-based high power density synchronous buck converter evaluation boards and reference designs, such as the EPC9195 and EPC91109 for USB-PD up to 180W, enabling compact, high-efficiency solutions that lower the barrier to adoption for GaN-based architectures.
Differentiation and Emerging Dynamics
Several patterns distinguish the current competitive dynamics. First, integration and reference design quality are becoming decisive. Companies that provide not only the IC but also controller pairings, evaluation boards, and application-specific reference designs reduce time-to-market for customers and reinforce lock-in through ecosystem familiarity. Second, qualification breadth is a strategic asset, particularly in automotive and industrial markets where AEC-Q100 and other reliability standards gate adoption. Third, the GaN ecosystem is fostering collaboration across suppliers, as seen in evaluation boards that pair GaN FETs with controller ICs from different vendors, suggesting that interoperability and reference design availability will matter as much as individual component specifications. Fourth, the market shows signs of both consolidation among scale players and fragmentation by application specialty, with new entrants and incumbents alike pursuing niche leadership in low-IQ portable designs, high-voltage industrial conversion, or GaN-based high power density solutions.
For decision-makers, the practical implication is that supplier selection is increasingly multidimensional. Portfolio breadth matters for platforms that span multiple applications, but application-specific qualification, thermal performance, integration support, and supply continuity can outweigh raw portfolio size in segment-critical deployments.
Future Trends and Commercial Implications
Looking ahead three to five years, several trends are likely to shape the synchronous buck converter market and create distinct commercial opportunities.
One trend is the continued diffusion of wide-bandgap technologies beyond high-end niches into broader mainstream designs. As gallium nitride and silicon carbide adoption matures, efficiency gains of two to five percent and higher switching frequencies that reduce passive component size will become more accessible across industrial, automotive, and computing applications. This creates opportunities for suppliers that can offer qualified, integrated GaN-enabled solutions with strong reference design support, and for system designers that can leverage smaller footprints and improved thermal margins to reduce total cost of ownership.
A second trend is the deepening alignment between power management and application-specific intelligence. Low quiescent current, configurable interfaces, and multi-phase control are increasingly expected, particularly in portable consumer electronics, data center power delivery, and industrial automation. Products that combine efficiency with programmability and diagnostic capabilities will find stronger adoption in designs where power management is integrated into broader system optimization.
A third trend is the continued recalibration of supply chain strategy toward regional resilience and stable sourcing, especially for wide-bandgap discrete devices and power management ICs. Demand from automotive electrification and AI data center buildouts will keep pressure on stable sourcing, while lead time normalization reduces but does not eliminate the need for dual-sourcing and buffer planning. Companies that invest early in qualified alternate sources, onshored or nearshored production options, and transparent traceability will be better positioned to manage volatility.
Potential risks include uneven adoption of wide-bandgap materials due to cost and qualification complexity, regulatory shifts that affect cross-border sourcing, and competitive pressure that compresses margins in commoditizing segments. The balance between integration benefits and component cost premiums will remain a key uncertainty, particularly in price-sensitive consumer and industrial applications.
Actionable Guidance for Decision-Makers
For manufacturers, the priority is to align product roadmaps with application-specific efficiency, integration, and qualification requirements while building reference design capability that accelerates customer adoption. Investing in GaN-compatible architectures, thermal performance, and multi-phase control where relevant can differentiate offerings in computing, automotive, and industrial segments. For investors, the opportunity lies in identifying companies with strong application qualification, ecosystem support, and supply chain resilience rather than relying solely on portfolio size. Segment leadership in low-IQ portable designs, high-voltage industrial conversion, or GaN-based high power density solutions may offer more durable positioning than broad but undifferentiated portfolios.
Worldwide Synchronous Conveyor Market
For procurement and sourcing teams, the practical focus should be on qualifying alternate suppliers, securing stable sourcing for wide-bandgap discrete devices, and building buffer strategies that reflect both normalized lead times and regional redundancy expectations. Evaluating suppliers on reference design quality, qualification breadth, and supply continuity will reduce deployment risk in application-critical designs. Detailed segment-level data and customized sourcing guidance can help translate these priorities into specific supplier shortlists, qualification roadmaps, and inventory strategies tailored to each organization's application mix and risk tolerance.
For detailed analysis of this topic, please visit the official page: Worldwide Synchronous Buck Converter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com