

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: DDR5 RDIMM Memory Interface Chip Market Set to Reach USD 7,930.15 Million by 2032, Growing at a 20.45% CAGR
By pmarketresearch, 2026-07-02
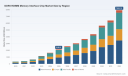
DDR5 RDIMM Memory Interface Chip Market: Strategic Intelligence for 2026 Decision-Making
Executive summary
PW Consulting's new market study on the DDR5 RDIMM Memory Interface Chip market provides actionable intelligence tailored for technology leaders, procurement heads, and corporate strategists preparing for 2026 and beyond. The market has moved from niche adoption to rapid commercialization: total industry revenue expanded from USD 350.0 Million in 2020 to USD 2,150.5 Million in 2025, and our forecast shows an acceleration toward USD 7,930.15 Million by 2032. The market's structural trajectory through the 2026–2032 forecast window implies a compounded annual growth rate (CAGR) of 20.45%, underpinning significant strategic implications for suppliers, OEMs, hyperscalers and system integrators.
DDR5 RDIMM Memory Interface Chip Market
Why this report matters for 2026 strategic choices
-
Timing and investment prioritization: With an inflection point between 2025 and 2026, organizations must decide whether to accelerate investments in DDR5-enabled server architectures or adopt a wait-and-see posture. Our study isolates the timing risk and reward profiles across product, supply-chain, and go-to-market moves.
DDR5 RDIMM Memory Interface Chip Market -
Sourcing and supplier risk mitigation: The memory interface chip layer is rapidly consolidating—top-three vendors control over 85% of the market concentration, and the top-five exceed 96%—making single-supplier dependency a material operational risk. The report provides sourcing playbooks to diversify exposure without sacrificing integration performance.
DDR5 RDIMM Memory Interface Chip Market -
Cost-to-performance optimization for AI and cloud workloads: As DDR5 RCD and PMIC innovations drive module performance and power profiles, procurement and platform engineering teams must reassess TCO assumptions. Our analysis translates chipset-level performance upgrades into platform-level cost impacts across typical enterprise deployment scenarios.
Market dynamics and structural drivers
Several concurrent forces are shaping the DDR5 RDIMM interface market as it moves into mainstream server adoption. Demand drivers include sustained AI training and inference deployments, hyperscale cloud expansions, and the upgrade cycle from DDR4 to DDR5 in enterprise data centers. On the supply side, innovation in registered clock drivers (RCDs), data buffers, and power management ICs (PMICs) is enabling higher speeds and better thermal profiles, accelerating module-level adoption.
From a macro perspective, the market grew more than sixfold between 2020 and 2025, reflecting rapid product maturation, and our bottom-up forecast points to a multi-billion-dollar opportunity by the end of the decade. This growth coexists with short-term noise—tariff adjustments introduced in 2025 that shifted sourcing patterns and near-term pricing volatility for DRAM and modules driven by AI demand—which collectively create both tactical risks and strategic windows for incumbents and new entrants.
Competitive landscape: who matters and why
The market is highly concentrated, with a few specialized players dominating the memory interface chipset layer. Key vendors combine chipset depth, IP portfolios, and supply-chain scale to win design cycles with server and module manufacturers. Our research highlights several strategic archetypes among market leaders:
-
Platform integrators focused on end-to-end module solutions: These firms provide integrated RDIMM chipset stacks—registered clock drivers, PMICs, SPD hubs and sensors—positioning themselves as turnkey partners for module houses and OEMs. Their value proposition centers on validated performance at higher data rates and accelerated time-to-market for RDIMM designs.
-
Component specialists with thermal and power differentiation: PMIC-focused companies emphasize energy efficiency and thermal integration, an increasingly important attribute as module densities climb and AI workloads stress power envelopes.
-
Regional-scale production players: A mix of firms are targeting volume scaling and cost-competitive mass production for Gen4 implementations to capture share during the mainstreaming phase of DDR5 adoption.
Representative companies covered in the study include Rambus, Renesas Electronics, Montage Technology, Texas Instruments, Analog Devices and Infineon Technologies. The report examines each firm’s strategic positioning, product roadmap focus (RCD, DB, PMIC, SPD hubs), go-to-market motions, and recent milestones—such as product launches, mass production ramp-ups, and industry recognition—that materially affect competitive dynamics.
Recent vendor developments with strategic implications
-
Rambus: Recognized in April 2026 with an industry award for its DDR5 RDIMM 8000 chipset, signaling strong validation of its high-bandwidth product strategy for AI and data center applications.
-
Renesas Electronics: In November 2025, introduced what it describes as an industry-first Gen6 DDR5 registered clock driver targeting next-generation server RDIMMs—an important leap for customers planning multi-generation roadmaps.
-
Montage Technology: Announced mass production of Gen4 RCD silicon in late 2025, reflecting the industry’s move from early adopter volumes to broader production-scale deployments.
Practical contents of the PW Consulting report (what’s inside)
Our market report is structured to be operationally useful to business leaders and technical decision-makers. It includes:
-
Market size and forecast model: A transparent, bottoms-up revenue model covering historical performance (2020–2025) and a detailed forecast (2026–2032) with sensitivity scenarios. The report documents our core assumptions and provides scenario outputs calibrated to demand, pricing, and adoption curve variables.
-
Technology and product taxonomy: Detailed mapping of the DDR5 RDIMM interface stack—RCDs, data buffers, PMICs, SPD hubs—and the functional and thermal trade-offs relevant for server and AI module designs.
-
Vendor scorecards and strategic playbooks: Comparative assessments of incumbents and challengers across product performance, roadmap breadth, integration support, manufacturing footprint, and go-to-market capabilities. Each scorecard is paired with a recommended playbook for purchasers and a partnering checklist for suppliers.
-
Supply-chain and tariff impact analysis: An examination of recent regulatory moves, tariff adjustments and sourcing shifts, showing how procurement strategies and geography of supply may alter cost and lead-time dynamics.
-
Use-case-driven TCO models: Module- and system-level examples that translate chipset choices into total cost of ownership for representative cloud and enterprise workloads.
-
Market concentration and competitive scenarios: Analysis of consolidation risk, barriers to entry, and likely competitive outcomes under high- and low-growth scenarios.
How to apply the findings in 2026 planning cycles
-
Procurement: Use the vendor scorecards and TCO models to revise supplier qualification criteria—prioritize proven high-speed RCD performance and robust PMIC thermal integration when negotiating multi-year contracts.
-
R&D and platform roadmaps: Align module validation timelines with the product roadmaps of primary RCD and PMIC vendors; accelerate lab validation for Gen4/Gen6 silicon if your workloads require sub-8000 MT/s performance in 2026 deployments.
-
M&A and partnership scouting: The high concentration suggests attractive bolt-on targets for system suppliers seeking vertical integration; our report identifies capability gaps where acquisitions or JV structures could create differentiated module offers.
-
Risk management: Model single-source exposure scenarios and execute contingency plans—second-source validation and phased adoption pathways are included in our pragmatic checklist.
Methodology and data integrity
The study combines primary interviews with module OEMs, chipset vendors and hyperscale IT architects, with secondary triangulation using shipment and pricing data, public filings, and regulatory disclosures. Our forecast employs a bottom-up approach, building revenues from device-level adoption curves and validated bill-of-material assumptions. All major assumptions are documented and sensitivity-tested to provide transparent decision levers for corporate planning teams.
Limitations and the PW Consulting “preview” approach
Consistent with the report’s intent to be a strategic decision tool, this announcement highlights the major market trajectories, competitive dynamics, and practical frameworks. To preserve the tactical exclusivity that many clients require, the detailed segment-by-segment revenue tables, regional breakouts, and full vendor share matrices are provided only in the full report. This “preview” is designed to answer the question of “why it matters” while prompting deeper examination of “where specifically” to allocate capital and engineering resources.
Key takeaways for executive teams
-
The DDR5 RDIMM interface market is at a rapid scale-up phase; total industry revenue reached USD 2,150.5 Million in 2025 and is projected to approach USD 7,930.15 Million by 2032 under our base case.
-
Market concentration is high—the top three and top five vendors dominate—so vendor selection and multi-sourcing strategies will materially affect cost, lead times, and design flexibility.
-
Recent product launches and mass-production ramps indicate both performance headroom (Gen6 roadmaps) and production readiness (Gen4 volumes), which require synchronized platform validation plans.
-
Tariff shifts and DRAM pricing volatility create immediate operational noise; however, medium-term demand from AI and hyperscale workloads supports sustained market expansion.
Next steps and how to get the full analysis
For executive teams and technical leaders who need the granular revenue matrices, regional and application breakdowns, detailed vendor market-share tables, and downloadable financial models, PW Consulting makes the complete DDR5 RDIMM Memory Interface Chip Market report available through our research portal. The full report contains the tables, charts, and step-by-step playbooks required to translate market intelligence into 2026 investment and procurement decisions.
Contact PW Consulting’s Market Intelligence team to schedule a briefing and obtain the complete dataset and actionable recommendations.
For detailed analysis of this topic, please visit the official page: DDR5 RDIMM Memory Interface Chip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 3.8% CAGR for Como Catalyst Market During 2026–2032
By pmarketresearch, 2026-07-02
Como Catalyst Market 2026: Strategic Imperatives for Refiners, Catalysts Suppliers, and Investors
PW Consulting today publishes the Como Catalyst Market — a focused, operationally oriented market intelligence study designed to shape capital allocation and procurement decisions through 2026 and beyond. With a 2025 base year and a forecast horizon to 2032, the report frames the CoMo (cobalt‑molybdenum) hydrotreating catalyst landscape against raw‑material shocks, refinery feedstock shifts, and tightening low‑sulfur fuel requirements. In macro terms, the CoMo market expanded from roughly USD 540 Million in 2020 to USD 648.5 Million in 2025 and is projected to grow at a 3.8% CAGR to reach the high‑hundreds of millions by 2032. This release summarizes the strategic takeaways; the full report contains the underlying models, vendor scorecards, and plant‑level demand tables.
Como Catalyst Market
Why 2026 Is a Turning Point
-
Operational complexity is increasing. Refiners are managing a broader mix of feedstocks — from VGO and FCC streams to renewable‑diesel blends — which alters hydrogen demand, contaminant profiles and, consequently, catalyst selection and cycle planning.
Como Catalyst Market -
Raw‑material volatility is reshaping cost and sourcing strategies. Supply constraints and policy actions on critical inputs have already manifested in higher price volatility and procurement risk premium for cobalt and molybdenum supplies, forcing manufacturers and end‑users to re‑optimize formulations and supply chains.
Como Catalyst Market -
Regulatory pressure and product quality targets (notably ultra‑low sulfur diesel) are driving demand for higher‑activity hydrotreating solutions, even as refiners seek longer on‑stream life and lower total cost of ownership. These dynamics require a strategic view of catalyst performance across pressure and carbon monoxide regimes.
Key Findings at a Glance
-
Market trajectory: The CoMo market demonstrates steady, mid‑single‑digit growth, underpinned by continued demand for hydrodesulfurization and hydrotreatment in both conventional and renewable fuel value chains.
-
Supplier concentration: Market share is meaningfully concentrated — the largest suppliers together account for the plurality of market revenues, creating distinct advantages in scale, application expertise and aftermarket service.
-
Product differentiation is shifting from basic activity metrics to lifecycle economics: activity, selectivity under relevant process conditions, attrition resistance and metal reclamation potential now drive procurement rather than headline activity alone.
-
Transactional momentum: Recent capacity expansions, product launches and strategic transactions are already reshaping supply availability and partnership opportunities heading into 2026.
What the Como Catalyst Market Report Delivers
-
Practice‑ready market sizing and a plant‑level demand model that allows refiners, catalyst vendors and investors to quantify incremental demand under customized feedstock and regulation scenarios.
-
Cost‑to‑serve and total cost of ownership models for competing CoMo formulations, including sensitivity to cobalt and molybdenum price swings and recovery/recycling pathways.
-
Competitive benchmarking and supplier scorecards that assess technical performance, regional manufacturing footprint, aftermarket support and strategic alignment to renewable fuel roadmaps.
-
Practical procurement playbooks: sourcing strategies, contracting templates, hedging approaches and inventory tactics designed to mitigate raw‑material and delivery risk.
-
Scenario analysis and decision trees for CAPEX and R&D investments, with break‑even and upside cases relevant to 2026 budget cycles.
Competitive Landscape: Who Matters — and How They Compete
The report profiles incumbent technology leaders and regional suppliers, emphasizing the aspects of competitive advantage that matter in 2026: product performance under real unit conditions, supply reliability, aftermarket analytics and the ability to collaborate on custom solutions.
-
Topsoe (Lyngby, Denmark) — Noted for high‑activity CoMo solutions designed for ultra‑low sulfur diesel, Topsoe continues to invest in capacity and new formulations. Its recent moves to expand hydrotreating catalyst production underline a strategic play to serve the renewable diesel and sustainable fuels market more aggressively.
-
BASF (Ludwigshafen, Germany) — Maintains deep experience with CoMo and NiMo hydrogenation catalysts across a range of feedstocks and applications. BASF’s value rests in field‑proven performance and global technical support, attractive for large integrated refiners.
-
Axens (Rueil‑Malmaison, France) — Offers CoMo series optimized for middle distillates and VGO hydrotreating and is differentiated by process‑integration expertise, particularly for units operating at low‑to‑medium pressures.
-
Shell Catalysts & Technologies / Criterion (Houston, USA) — Combines OEM process know‑how with a portfolio of CoMo and NiMo solutions for distillate hydrotreating, emphasizing low‑pressure HDS performance and lifecycle management.
-
Kuwait Catalyst Company (KCC) — A regional player focused on high‑performance CoMo for desulfurization and denitrification, KCC offers proximity advantages and tailored service for Middle East refining projects.
-
Ketjen (formerly Albemarle refining catalysts business) — Focused on robust hydrotreating solutions, Ketjen’s recent change in ownership signals potential strategic repositioning and partnership opportunities for buyers and investors monitoring supply reshuffling.
Recent Industry Moves to Watch
-
Capacity additions and product launches from leading catalyst manufacturers signal preparation for higher throughput and more demanding feedstock profiles in renewable and low‑sulfur fuel applications.
-
Transaction activity in the refining catalyst space — including divestitures and buyouts — is increasing vendor consolidation risks and, conversely, creating opportunities for strategic alliances and new entrants with capital backing.
Raw‑Material Dynamics and Supply‑Chain Risk
Two supply‑side factors are particularly salient for 2026 decision‑makers: cobalt availability and molybdenum price volatility. Policy actions in key producing regions and temporary export measures have elevated cobalt price sensitivity, while molybdenum has seen periodic swings that affect input costs materially. Producers and refiners should assume a higher baseline of procurement risk and plan for metal recovery, multi‑sourcing, and formulation optimization to reduce exposure. The report contains a detailed sensitivity model that quantifies P&L impact across alternative sourcing and recycling scenarios.
Regulatory and Technical Considerations
From a technical standpoint, CoMo catalysts retain advantages in low‑to‑medium pressure hydrodesulfurization applications, notably selectivity under certain operating windows. However, performance is affected by process variables such as carbon monoxide partial pressure. The interplay of reactor conditions, feed contaminants and catalyst composition is central to selecting the right solution for both front‑end hydrotreaters and FCC pretreatment units. Our comparative test‑matrix and field trial templates are included in the full report for immediate deployment.
Practical Recommendations for 2026 Strategy
-
Create a two‑track procurement program: secure base supply via multi‑year contracts with primary suppliers while maintaining short‑term agility through spot frameworks and qualified secondary vendors.
-
Invest in metal recovery and catalyst life‑extension programs. Small CAPEX for onsite reclamation or partnerships with recyclers can materially reduce metal exposure and lower TCO.
-
Run targeted head‑to‑head pilots under actual unit conditions to validate vendor claims on activity, selectivity and attrition. Use the PW Consulting trial protocol included in the report to shorten validation cycles.
-
Monitor M&A and capacity moves closely. Vendor ownership changes and recent expansions can create windows for renegotiation, preferential terms, or alternative sourcing.
-
Include raw‑material stress tests in budget cycles. Scenario modelling for cobalt and molybdenum swings should be part of 2026 planning and reflected in product and feedstock procurement decisions.
How PW Consulting Supports Your 2026 Agenda
We pair quantitative modeling with practical operational playbooks. Our engagement options include tailored demand modelling by refinery unit, vendor due diligence and benchmarking, procurement negotiation support, and implementation of catalyst life‑extension and reclamation programs. The Como Catalyst Market report is structured to provide immediate, executable outputs for strategy teams that must justify CAPEX and supply commitments in the coming 12–18 months.
To preserve the integrity of decision‑grade analysis in the public domain, this release highlights findings but intentionally omits detailed regional and application splits, unit‑level demand tables and full price curves. Those datasets and the interactive model are available exclusively in the full Como Catalyst Market report. Access the complete intelligence to deploy our templates, vendor scorecards, and sensitivity models directly into your 2026 planning process.
For detailed analysis of this topic, please visit the official page: Como Catalyst Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts Aluminum Bioclimatic Pergolas Market to Expand at a 7.2% CAGR
By pmarketresearch, 2026-07-02
PW Consulting: Strategic Preview — Aluminum Bioclimatic Pergolas Market Outlook (Report Base Year 2025)
PW Consulting today publishes a strategic preview of our forthcoming Aluminum Bioclimatic Pergolas Market report, designed to serve as a decision-grade briefing for executives shaping 2026 strategies. Drawing on a rigorous historical review (2020–2025), primary interviews and our proprietary modelling for the 2026–2032 forecast window, the research frames market dynamics that will determine winners and losers as the industry scales. At the macro level, the market reached roughly USD 850 Million (base year 2025) and is projected to expand at a compound annual growth rate (CAGR) of 7.2% through 2032 — a trajectory that elevates capital allocation and go‑to‑market choices to the centre of near-term strategic plans.
Aluminum Bioclimatic Pergolas Market
Why this matters for 2026 corporate decision-making
- Visibility into a high‑growth segment: A steady, mid‑single‑digit CAGR over the forecast window signals durable end‑market demand across residential and commercial use cases — making 2026 a pivotal year to secure channel partnerships, manufacturing capacity and product differentiation.
- Margin pressure via raw materials and specification premiums: Aluminum pricing volatility (industry benchmarks showed primary and LME pricing pressure in late‑2025/early‑2026) and the premium attached to advanced extrusion and integrated hardware mean procurement strategy is now a strategic lever, not a back‑office function.
- Sustainability and standards are table stakes: Green building standards, recyclable‑material requirements and energy‑efficiency expectations are increasingly embedded in procurement and specification language; compliance timelines must be reflected in product roadmaps and capex planning.
What the full PW Consulting report delivers (practical, executable content)
- Market-sizing and robust forecast models (USD, revenue units in Millions) with scenario analysis and sensitivity testing built around raw‑material swings, installation labour cost inflation and adoption curves for electrified/automated features.
- End‑to‑end supply‑chain maps and unit‑cost build‑ups showing where margin can be recaptured via sourcing, component standardization and modular design for manufacturing‑to‑installation economies.
- Product and technology taxonomy with competitive feature scoring — covering motorized louver systems, integrated heating/lighting, sensor packages, solar‑assist options and digital/IoT integrations — and recommended minimum viable product (MVP) configurations for prioritized segments.
- Go‑to‑market playbooks for OEMs, distributors and installers: channel segmentation, pricing architecture, bundling tactics (e.g., pergola + screens + service plans), and turnkey installation models that reduce friction for high‑value commercial projects.
- Regulatory and sustainability impact assessment that translates standards into product requirements, compliance roadmaps and potential certification pathways to win institutional specification.
- M&A and partnership decision framework with quick‑win integration checklists for bolt‑on acquisitions (manufacturing footprint, extrusion capability, digital control IP) and strategic JV templates for market entry.
- Installable commercial models and five‑year P&L templates to stress‑test new product introductions under differing price, mix and cost scenarios.
We purposefully avoid disclosing granular regional or application splits in this preview to preserve the report’s competitive intelligence value. The full report, however, contains the detailed segmentation executives need to make allocation and market entry decisions with confidence.
Aluminum Bioclimatic Pergolas Market
Competitive landscape: positioning and strategic takeaways
The aluminum bioclimatic pergola market remains a mosaic of premium innovators, regional champions and high‑volume manufacturers. Several players exemplify distinct strategic postures that other firms can emulate or counter:
Aluminum Bioclimatic Pergolas Market
- StruXure Outdoor (Dahlonega, GA, USA): A premium, experience‑led competitor that integrates motorized louvers with smart‑home ecosystems and weather certification. Their recent product line refresh emphasized accessory ecosystems (sound, heat, screens) and software updates — a deliberate move to convert single‑product buyers into platform customers. For incumbents, the lesson is clear: software and accessory ecosystems increase lifetime value and reduce churn.
- Azenco Outdoor (Miami, FL, USA): Focused on durable, climate‑adapted systems and product breadth (including retractable textiles alongside aluminum louver systems). Their 2026 trade‑show presence underscores a dual strategy: sustain product innovation while leveraging global trade shows to drive project pipelines. Firms targeting coastal or harsh‑climate applications should examine material specifications and corrosion protection practices showcased by players like Azenco.
- Renson (Waregem, Belgium), Solisysteme (Avanton, France), Gibus (Italy): European manufacturers continue to compete on integration — lighting, heating, screens and advanced climate control — coupled with high‑service channels. European premium positioning stresses certification and configurability, which appeals to hospitality and high‑end residential segments.
- Palmiye & Kenan Metal (Turkey), AlunoTec and Seroban (China): These manufacturers compete on manufacturing scale, export capability and competitive pricing for volume projects. Their business models often prioritize standardized platforms and efficient extrusion partnerships to serve commercial installers and international distributors.
- Biossun (France): An early mover in solar‑assisted pergolas and eco‑driven automation. As sustainability criteria tighten, solutions that combine renewable energy capture with automated shading will enjoy specification advantages in institutional projects.
Recent market movements demonstrate how firms are translating strategy into execution: StruXure’s late‑2025 product expansion built the ecosystem that supports higher ASPs and recurring service; Azenco’s showcase at IBS 2026 highlighted multi‑product portfolios to capture adjacent demand; and increased trade‑show activity in 2026 reflects a market pivot toward experiential selling and contractor education.
Industry dynamics to monitor in 2026
- Raw‑material volatility: Aluminum pricing experienced significant swings through late‑2025 and into 2026, and processed extrusion costs for pergola applications remain a meaningful share of BOM. Procurement teams should consider long‑lead hedging, multi‑sourcing and locked‑price contracts for critical components.
- Sustainability and regulation: Green building standards are shifting procurement criteria; recyclable aluminum and lifecycle impact disclosures improve bid competitiveness for institutional and corporate buyers.
- Year‑round usability demand: Customers are increasingly selecting systems that extend outdoor living through heating, waterproofing and automation — turning pergolas into hybrid living spaces and changing the value equation toward integrated solutions.
- Fragmentation and consolidation opportunities: The market remains fragmented across regions and price tiers, creating opportunities for strategic consolidation and for players that can scale installation and service networks.
Actionable strategic plays for 2026
- Prioritize channel transformation: Invest in installer training, certified partner programs and digital configurators to reduce order cycle times and minimize on‑site variability.
- Productize service: Convert one‑time sales into recurring revenue via maintenance contracts, extended warranties and connected‑device subscriptions for monitoring and predictive maintenance.
- De‑risk procurement: Implement layered sourcing strategies for aluminum extrusions and critical electronics, and evaluate nearshoring for reduced lead times in key markets.
- Design for manufacturability: Standardize interfaces and use modular platforms to reduce SKU proliferation, compress lead times and preserve margins as raw material costs fluctuate.
- Leverage sustainability as a premium: Certify products for recyclability and energy performance to unlock institutional and higher‑margin commercial contracts.
- Pursue selective M&A or JV moves: Target extrusion capability, digital control IP or established national installer networks that accelerate market access while minimizing greenfield risk.
How PW Consulting’s report accelerates executive decisions
This report is crafted as an operational tool for 2026: not an abstract market narrative, but a playbook that links macro projections with tactical moves across product, procurement, channels and corporate development. It provides scenarioized forecasts (base, upside and downside) around fixed and variable costs; supplier scorecards; and checklists for rapid integration post‑acquisition. Importantly, the report preserves the competitive intelligence that procurement and strategy teams use — detailed segment and regional breakdowns are available in the full publication to validate market prioritization and capex allocation.
Next steps
PW Consulting’s full Aluminum Bioclimatic Pergolas Market report includes the granular segmentation, competitive benchmarking and appendices (primary interviews, price‑build sheets and certification matrices) necessary to finalize 2026 strategies. Use the preview insights above to align leadership on priorities — then consult the report for the detailed models and playbooks that convert strategic intent into executable programs.
For access to the full report and supporting datasets, contact PW Consulting’s Market Intelligence team or visit our report page to download the comprehensive intelligence package and scenario models designed to guide your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Aluminum Bioclimatic Pergolas Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Antibody Market Poised for 7.19% CAGR Through 2032 as Monoclonals Drive Growth
By pmarketresearch, 2026-07-02
Oct-4 Antibody Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s Oct-4 Antibody Market Report (base year 2025) synthesizes five years of historical dynamics and a seven-year forecast to 2032, delivering a high-fidelity roadmap for R&D buyers, product managers, manufacturing strategists, and corporate development teams. This executive preview outlines the report’s strategic value for decisions you will make in 2026 — from portfolio prioritization and supplier selection to M&A screening and regulatory risk mitigation — while preserving the report’s proprietary segmentation and company-level revenue detail for subscribers.
Oct-4 Antibody Market
Market at a Glance: Growth Trajectory and Competitive Structure
Our bottom-up model indicates the global Oct-4 antibody market reached USD 88.45 Million in 2025 and is set to expand to approximately USD 143.85 Million by 2032, representing a compound annual growth rate (CAGR) of 7.19% across the 2026–2032 forecast window. The market has exhibited steady expansion since 2020, reflecting intensified investment in pluripotency and stem cell research, translational oncology programs, and assay development in both academic and commercial laboratories.
Oct-4 Antibody Market
From a structural standpoint, the market displays moderate concentration: the leading three suppliers account for nearly half of the market, while a broader top-five captures roughly six-in-ten market share. That configuration creates a market environment where scale, validation pedigree, and channel reach provide clear commercial advantages, but differentiated product features and validation claims (e.g., ChIP-seq grade certification, recombinant antibody platforms, and conjugation options) allow mid-tier and specialist vendors to sustain premium niches.
Oct-4 Antibody Market
Why this report matters for 2026 strategic planning
- Procurement and vendor rationalization: With supply chains still sensitive to geographic and manufacturing concentration, procurement teams must weigh price against validated performance and batch-to-batch reproducibility. Our report benchmarks supplier capability across manufacturing footprint, catalog depth, and citation impact to help buyers calibrate vendor consolidation versus diversification strategies.
- Product and portfolio decisions: R&D and product teams can use our demand and application trend analysis to prioritize investments in recombinant monoclonal formats, conjugates for flow and imaging, or ChIP-grade polyclonals — depending on the desired margin profile and validation burden. The report provides a decision matrix tying technical attributes to commercial outcomes (e.g., time-to-adoption, ASP ranges, and channel conversion rates).
- M&A and partnership screening: For corporate development professionals, the report’s valuation comparators, capability maps, and ten-year scenario modeling surface attractive targets — whether bolt-on catalog players with strong regional channels or technology-held assets with differentiated validation claims. Our heatmap narrows the universe to players whose capability sets align with scale-up or vertical integration hypotheses.
- Regulatory and commercialization readiness: Although Oct-4 antibodies are sold as research-use-only (RUO) reagents and are not approved for clinical diagnostics or therapeutic use, the report details the label and disclaimer environment and the practical implications for translational pipelines, reagent claims, and contract manufacturing agreements.
What’s inside the full report (practical, actionable components)
- Market sizing and growth drivers with transparent modeling assumptions covering historical (2020–2025) and forecast (2026–2032) periods.
- End-to-end product landscape mapping (format types, conjugation options, validation grades) and a buyer-focused decision framework that links product attributes to lab workflows.
- Supplier capability and readiness assessments: manufacturing footprint, QC protocols, catalogue breadth, citation analysis, and commercial channel strength.
- Go-to-market playbooks for incumbent suppliers and new entrants, including pricing archetypes, channel incentive structures, and digital commerce levers for 2026–2028.
- Risk register covering batch variability, reagent interchangeability, IP considerations, and regulatory labeling constraints typical to RUO products.
- M&A screening toolkit: valuation comparators, integration scorecards, and three acquisition scenarios with sensitivity tests for revenue ramp and cost synergies.
- Appendices of supplier scorecards, product validation checklists, and reproducibility guidance for lab managers.
Competitive landscape: positioning and tactical moves
Our supplier review concentrates on established life-science reagents manufacturers and specialist antibody houses that dominate research procurement lists. These firms vary by scale, validation focus, and channel strategy — implications that matter when negotiating 2026 supply agreements or selecting co-development partners.
- Large platform vendors: Major diversified life-science companies benefit from breadth of catalogue, global logistics, and institutional procurement relationships that ease large-volume purchasing and bundled product promotions. Their strategic advantage is the ability to tie Oct-4 reagents into larger consumable or instrument deals, which accelerates enterprise adoption within large labs and biopharma R&D groups.
- Specialist antibody houses: Niche suppliers focus on deep validation claims (e.g., ChIP-seq grade, recombinant monoclonal consistency), rapid technical support, and customizable conjugation services. These characteristics support premium pricing and strong academic citation momentum, making them attractive partners for translational research centers and assay developers.
- Regional players and OEM suppliers: Localized manufacturers address price-sensitive segments and regional supply resilience. Their value proposition is shorter lead times and localized technical servicing, but they often face higher hurdles in gaining validation trust outside their geographies.
Recent product catalog updates and targeted validation datasets (notably ChIP-grade verification and IHC-P focused listings) highlight an incremental strategic pivot across suppliers toward application-specific claims that reduce perceived switching costs for laboratory customers. For 2026, expect incremental differentiation to come from demonstrable batch metadata, recombinant engineering that reduces heterogeneity, and bundled assay solutions rather than from competing on price alone.
Company-level themes and implications
- Validation leadership sells: Firms that invest in application-specific validation (e.g., ChIP, IHC-P, flow cytometry panels) command credibility in adoption discussions. Buyers in 2026 will increasingly ask for batch-level QC and orthogonal validation evidence — an element our supplier scorecards quantify.
- Recombinant platforms shorten sales cycles: Suppliers offering recombinant monoclonal formats reduce customer uncertainty around reproducibility. In procurement negotiations, recombinant claims can be leveraged for premium pricing and longer contract cycles.
- Channel bundling influences account penetration: Vendors able to combine Oct-4 antibodies with cell culture media, reagents, or instrumentation capture a larger wallet share within institutional customers. Sales leaders should evaluate cross-sell metrics from such bundles when setting 2026 commercial targets.
Recent industry developments to watch in 2026
- Product catalog updates emphasizing application-specific validation (e.g., ChIP-seq grade and IHC-P) are becoming a primary marketing tool to reduce adoption friction.
- Continued RUO labeling and explicit disclaimers remain industry standard, constraining direct clinical positioning but opening opportunities for co-development agreements tied to regulated companion reagent programs.
- SKU rationalization is ongoing among several suppliers: discontinued SKUs are being replaced with recombinantly produced clones or consolidated catalog numbers — a practical consideration for long-term procurement contracts.
Actionable recommendations for 2026
- For procurement leaders: Build a two-tier supplier strategy: a core supplier for scale and continuity, plus validated niche suppliers for specialized applications. Require batch-level QC data in contracts and include service-level KPIs tied to technical support response times.
- For product and R&D heads: Prioritize investment in recombinant and conjugated formats with orthogonal validation packages. Design pilot studies that compare vendor batches across intended assay types and publish validation findings to accelerate internal buy-in.
- For corporate development teams: Use our M&A heatmap to prioritize targets that fill capability gaps (e.g., ChIP-grade expertise or strong regional channels). Focus due diligence on reproducibility evidence and order book stickiness rather than catalogue breadth alone.
- For CROs and assay developers: Offer bundled assay-reagent packages that include documented validation workflows to lock in institutional clients that prefer turnkey solutions.
Where this preview leaves you
This briefing gives you the strategic framing you need to prepare for procurement cycles, product bets, and M&A activity in 2026. It is intentionally a “trailer”: the full PW Consulting Oct-4 Antibody Market Report contains the proprietary segmentation tables, supplier-level revenue estimates, regional dynamics, and the source-level data that underpin our conclusions. Those proprietary datasets are excluded from this preview to preserve their commercial value and to provide you with an actionable reason to obtain the full intelligence package.
For teams planning budgets, vendor negotiations, or strategic initiatives in 2026, the full report will convert these strategic insights into specific tactical deliverables — from vendor shortlists and contract templates to deal modeling and product roadmaps. To access the comprehensive dataset, supplier scorecards, and step-by-step playbooks, please visit the PW Consulting report page or contact our subscriptions desk for enterprise licensing and bespoke advisory packages.
For detailed analysis of this topic, please visit the official page: Oct-4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Corrugating Grease Market to Rise from USD 215.45 Million in 2025 to USD 295.56 Million by 2032 at a 4.62% CAGR — Asia Pacific Leads with USD 91.56M
By pmarketresearch, 2026-07-02
Corrugating Grease Market 2026: Strategic Imperatives for Procurement, R&D and Operational Excellence
Executive summary
PW Consulting’s latest industry brief—based on a comprehensive 2020–2025 historical review and a 2026–2032 forecast horizon—maps the operational, regulatory and competitive inflection points shaping the corrugating grease market. The market, which reached approximately USD 215.45 million in 2025, is forecast to follow a steady growth trajectory with a compound annual growth rate of 4.62% across the outlook period, approaching roughly USD 295.56 million by 2032. That headline growth masks important volatility and structural shifts that will determine which suppliers, end-users and investors capture disproportionate value in 2026 and beyond.
Corrugating Grease Market
Why this matters for 2026 decision-makers
- Operational continuity: Corrugating greases are a small line-item cost with outsized impact—bearing life, plant uptime and finished-board quality hinge on lubrication choices. Our analysis links lubricant selection and maintenance cadence directly to unplanned downtime rates observed across surveyed corrugators.
- Regulatory pressure and reputational risk: NSF H1 registration remains a gating requirement where incidental food contact is possible. Simultaneously, tightening scrutiny on extraction and lifecycle impacts for key feedstocks (notably lithium-based thickeners and certain fluorinated chemistries) is changing formulation strategies.
- Consolidation and supplier power: The market shows moderate concentration, with three leading suppliers accounting for a significant share and five firms controlling a majority of the commercial landscape. This concentration creates both procurement risk and M&A opportunity.
- Technology and material transitions: Preference for high-temperature, low-volatility chemistries continues, but raw material shortages, cost cycles and regulatory pressure are driving R&D toward alternative thickeners and less environmentally contentious base fluids.
What the PW Corrugating Grease Report delivers
Our report is built for executives who must convert lubricant insight into measurable plant and P&L improvements. It is not a catalogue of high-level trends: it is a practitioner’s toolkit plus strategic foresight. Key deliverables include:
Corrugating Grease Market
- Market sizing and trajectory: a transparent, year-by-year model from 2020 to 2032 with scenario functionality for high-, base- and low-growth paths (CAGR 4.62% base).
- Competitive playbooks: supplier scorecards, commercial model benchmarks, and partner evaluation matrices that distil which vendor capabilities drive lower total cost of ownership (TCO).
- Procurement and inventory playbook: hedging approaches for fluorinated oils and lithium-based thickeners, reorder point models tuned to maintenance intervals, and contract clauses for supply continuity.
- Plant-level tools: lubrication audit templates, bearing failure root-cause checklists, conversion protocols for roll bearings, and validation procedures for switching greases without compromising board quality.
- Regulatory & sustainability watchlist: actionable compliance timelines (including NSF H1 implications and EU regulatory scenarios), lifecycle-impact scoring for candidate formulations, and supplier due-diligence checklists.
- Strategic scenarios and M&A radar: an acquisition readiness checklist, target-screening criteria for players with distribution or niche-formulation expertise, and five prioritized inorganic strategies tailored to different balance-sheet profiles.
Competitive landscape: who matters and why
The corrugating grease market is characterized by a mix of technology leadership and service-led conversions. Several companies repeatedly appear in procurement shortlists and plant case studies:
Corrugating Grease Market
- Chemours (Krytox) — Krytox Performance CORR: Known for PFPE/PTFE-based greases that set the industry benchmark for thermal stability and film strength on heated corrugator rolls. Their product positioning emphasizes long intervals between re-greasing, reduced bearing wear and a premium priced, high-reliability proposition.
- FUCHS Lubricants (Nye Lubricants) — NyeCorr 140 and services: Combines a high-performance, PTFE-thickened, food-grade offering with a Total Corrugator Plant Lubrication service that has driven hundreds of plant conversions. Their commercial model is notable for selling productivity gains and extended maintenance cycles rather than commodity volumes.
- LUBCON: Focuses on tailored high-temperature greases and system-level lubrication solutions for corrugating equipment, appealing to OEMs and plants seeking localized technical service.
- IKV Tribologie: An emerging specialist with NSF H1-registered food-grade greases positioned for facilities with strict incidental food contact requirements; their portfolio is attractive to converters and board producers with close ties to food-packaging customers.
Recent developments outside pure-lubricant vendors also matter. For example, a major ink manufacturer showcased water-based inks with higher bio-renewable content and improved grease resistance—an innovation that changes contamination vectors on finished board and may shift grease contamination management in production lines.
Dynamics to watch in 2026
- Raw-material rebalancing: In 2024, lithium soap and lithium complex thickeners were significant components of global grease manufacture, but volumes have shown slight declines amid competition for lithium from EV batteries and a push toward calcium-based alternatives. Expect ongoing formulation experiments and qualification cycles in 2026 as suppliers mitigate feedstock risk.
- Regulatory trajectories: REACH-type pressure in the EU and enhanced lifecycle disclosure expectations will accelerate reformulation roadmaps for some fluorinated oils. NSF H1 remains mission-critical for lines touching food packaging.
- Commercial models shift to services: Vendors that bundle grease technology with conversion services, plant lubrication programs and digital lubrication monitoring are winning longer-term contracts and better margin capture.
- Concentration and bargaining: The market’s top players control a material share of supply. Buyers should factor supplier concentration into contingency planning and procurement RFx design.
Actionable recommendations for 2026
- Recast lubrication procurement as a productivity lever: Move contract discussions from price-per-kg to price-per-operating-hour, with KPIs tied to bearing life, unplanned downtime reduction and maintenance labor.
- Prioritise qualification of alternative thickeners: Establish a two-track R&D and validation program—fast-track pilots for calcium-based systems where feasible, and parallel endurance testing for lower-fluorine PFPE blends where thermal performance is non-negotiable.
- Secure strategic feedstock agreements: For organizations with exposure to PFPE or specific fluorinated basestocks, negotiate supply continuity clauses and volume options with primary vendors; build secondary sourcing plans to reduce single-source vulnerability.
- Invest in plant-level lubrication governance: Deploy our lubrication audit template, mandate bearing-level lubrication records, and implement periodic third-party validations to avoid “run-to-fail” economics.
- Embed regulatory scenario planning into product roadmaps: Map NSF H1 renewal timelines, expected REACH-classification milestones and potential import control impacts to procurement and R&D calendars.
- Explore service-based partnerships or bolt-on M&A: For manufacturers seeking to capture more downstream value, consider partnerships or acquisitions of service-oriented vendors that provide plant conversion programs and digital lubrication monitoring.
Methodology and robustness
The report synthesizes four evidence streams: proprietary plant-level surveys, supplier revenue and shipment reconstructions, feedstock and price-index correlation analyses, and a bottom-up equipment population model for corrugators globally. Our base-case CAGR of 4.62% derives from an ensemble of econometric scenarios that account for packaging market elasticity, raw-material shock propagation, and regulatory tightening pathways. Where uncertainty is high—particularly around feedstock availability and EU regulatory outcomes—we provide sensitivity bands and contingency playbooks rather than single-point prescriptions.
What we deliberately withhold (and why)
In line with our “trailer” principle, this brief demonstrates the depth and practical value of the research while intentionally withholding granular segment-level revenue splits and certain per-region/application breakdowns. These finer disaggregations are included in the full report and interactive data workbook, which supply chain, procurement and R&D teams use to run customized scenario analyses and to prioritize investments at the plant level. The full dataset is required to operationalize many recommendations—especially those tied to plant-by-plant conversion economics and supplier selection matrices.
Next steps
For procurement directors, plant operations heads and corporate development teams preparing 2026 budgets: use this brief as a diagnostic to identify which risk levers you must pull. If you require the full dataset, conversion playbook, supplier scorecards and the interactive TCO models that underpin our conclusions, PW Consulting’s complete Corrugating Grease Market Report and the associated consultancy package are available. The full package includes a 90-minute executive briefing and a custom three-month implementation roadmap tailored to your footprint.
Contact PW Consulting to schedule a briefing and to obtain the dataset and tools needed to convert lubricant insight into measurable operational and financial outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Corrugating Grease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Embedded Storage (eMMC & UFS) Market to Surge at 15.02% CAGR, Hitting USD 10.9B by 2032
By pmarketresearch, 2026-07-02
Automotive Embedded Storage (eMMC & UFS) Market: Strategic Imperatives for 2026
As vehicles continue their transformation into data-centers-on-wheels, embedded storage has moved from a component line-item to a strategic enabler of user experience, safety and software-defined value capture. PW Consulting’s latest Automotive Embedded Storage (eMMC & UFS) Market report — built on a 2025 base year and a 2026–2032 forecast horizon — quantifies that transition. The market expanded from roughly USD 3.15 billion in 2023 to USD 4.10 billion in 2025 and is projected to reach approximately USD 10.91 billion by 2032, reflecting a compound annual growth rate (CAGR) of ~15.02% across the forecast period. For executive teams planning 2026 investments, procurement cycles, qualification roadmaps and M&A activity, these macro dynamics create both urgency and optionality.
Automotive Embedded Storage (eMMC and UFS) Market
What the report delivers — practical, decision-ready content
- Forward-looking market sizing and scenario-based forecasts (2026–2032) with sensitivity to NAND supply, pricing and adoption curves for eMMC and UFS.
- Buyer playbooks for procurement and qualification: realistic timelines, contract structures, inventory strategies and sample/qualification pathways for automotive OEMs and Tier-1 suppliers.
- Vendor benchmarking and scorecards: multidimensional profiles covering product maturity, automotive-grade qualification status, performance-per-watt, functional-safety support and aftermarket reliability evidence.
- Supply-chain and risk maps: concentrated production footprints, geopolitical exposure analysis, tariff and export-control scenarios, and contingency sourcing templates.
- Technical guidance for systems architects: design trade-offs between eMMC and UFS (cost, throughput, power, lifecycle), recommended interfaces for IVI, ADAS and telematics modules, and memory-stack optimization patterns.
- Hands-on commercial tools: pricing sensitivity models, contract negotiation levers (price collars, allocation commitments, volume-flex clauses), and an M&A/partnering framework targeting controller and NAND specialists.
Market dynamics shaping 2026 decisions
- Rapid market growth with elevated supply-side risk — The double-digit CAGR illustrates structural demand from richer infotainment stacks, data-logging for autonomy, and in-vehicle AI workloads. That demand is colliding with persistent NAND supply tightness and strategic production shifts by major suppliers, creating near-term allocation pressure for automotive-qualified eMMC and UFS parts.
- Price and allocation volatility — Contract and spot NAND prices rose into early 2026, increasing component costs for embedded storage. Procurement teams must model both price risk and delivery risk simultaneously; doing so will change how procurement prioritizes capacity reservations versus spot buys.
- Qualification cadence is a gating factor — Automotive qualification cycles for eMMC/UFS typically span 18–24 months. This creates durable demand lock-in for suppliers that achieve early qualification and implies that design and sourcing decisions made in 2026 will influence product roadmaps and supplier relationships well into 2028.
- Functional safety and regulatory overlay — AEC-Q100 and ISO 26262/ASIL requirements remain non-negotiable for ADAS and safety-adjacent storage. Suppliers with demonstrable ASIL-compliant solutions and long-tailed reliability data will command pricing and allocation advantages.
- Concentration and supplier power — The embedded storage market shows high concentration, with the top three suppliers accounting for a substantial majority of market share and the top five covering nearly nine-in-ten of the market. This structure amplifies supplier negotiating power, but also concentrates systemic risk if one node experiences capacity or trade disruptions.
- Geopolitical and supply-chain exposure — Global NAND production is heavily concentrated in Asia. That concentration introduces geopolitical risk vectors — export controls, tariffs and localized disruptions — which must be part of any sourcing or contingency planning exercise.
Competitive landscape — who matters and why
The competitive set combines large, vertically integrated memory manufacturers, controller specialists and regional players that focus on automotive-grade reliability. Key strategic considerations by supplier type include:
Automotive Embedded Storage (eMMC and UFS) Market
- Vertically integrated NAND leaders (e.g., major memory houses): offer depth in manufacturing scale, advanced process nodes and broad automotive-focused portfolios. Their strengths are supply stability (when capacity is allocated) and early access to high-density NAND generations.
- Controller specialists and system integrators: provide the firmware, controller IP and validation necessary to optimize UFS/eMMC in complex cockpit and ADAS platforms. Their validation on major vehicle SoCs creates a practical adoption pathway for OEMs.
- Regional and niche suppliers: focus on endurance, extended temperature ranges and automotive qualifications. These players are critical fallback partners for niche programs and aftermarket support.
Recent product and validation developments underscore technology momentum and competitive moves into automotive: a leading memory supplier began shipping qualification samples of an automotive UFS 4.1 solution built on G9 NAND and touting ASIL-B compliance; other players introduced UFS 4.1 samples and early UFS 5.0 evaluations; and controller vendors completed compatibility validation on prominent cockpit-class SoC platforms. These events accelerate OEMs’ ability to architect higher-performance storage stacks but also compress windows for supplier selection.
Automotive Embedded Storage (eMMC and UFS) Market
Strategic implications and recommended 2026 actions
Based on our analysis, PW Consulting recommends a multi-track approach that balances near-term risk mitigation with medium-term capability capture:
- Procurement: Move from annual spot buys to multi-year allocation agreements with clarity on volume, performance classes and price adjustment mechanisms. Negotiate explicit allocation guarantees for automotive-qualified parts and include reciprocal technical support commitments (e.g., co-engineering and failure-analysis SLAs).
- Qualification & Design: Start or accelerate qualification programs in H1 2026 for any platforms targeting 2028–2029 production. Treat qualification as a strategic barrier — securing early-qualified suppliers locks-in supply and reduces rework risk. Design teams should standardize interfaces to allow late-stage downgrades/upgrades (e.g., UFS-capable controllers that can operate with eMMC during shortage scenarios).
- Technology choices: Align storage architecture to product tiers. For high-performance IVI and ADAS domains, favor UFS generations that provide the necessary throughput and power efficiency. For cost-sensitive telematics or entry-level modules, validated eMMC solutions still offer compelling TCO. However, avoid rigid bifurcation: build BOM flexibility that anticipates rapid UFS adoption.
- Inventory & hedging: Consider strategic buffer stocks for critical SKUs and negotiate price-collar or index-linked contracts to mitigate spot price swings. Where capacity is tight, allocate a portion of your spend to upstream partners to secure wafer or die-level allocations as part of a vertical sourcing strategy.
- Supplier portfolio and partnerships: Diversify across vertically integrated NAND leaders and specialized controller vendors. Prioritize suppliers with proven automotive qualifications, ASIL support and demonstrated validation on target SoC platforms. For OEMs pursuing cockpit differentiation, early co-development agreements with controller/IP vendors can be a competitive advantage.
- M&A & innovation plays: For companies looking to enter or scale in this space, target assets that shorten qualification cycles (e.g., controller IP, firmware teams) or provide unique value-add (secure storage, endurance-enhancing firmware). Smaller acquisitions can be effective bolt-ons to accelerate time-to-market without incurring the long lead-time of in-house development.
- Risk & compliance: Embed scenario planning for geopolitical shock, export-control changes and supplier outages into 2026 budgeting cycles. Build dual-source and near-shore options for critical programs where feasible.
Decision roadmap and timing for 2026
- Immediate (Q1–Q2 2026): Freeze qualification roadmaps for 2028-bound platforms; initiate allocation negotiations with primary suppliers; conduct BOM flexibility audits.
- Near term (Q3–Q4 2026): Execute multi-year contracts with allocation and price mechanics; begin co-validation with chosen controller partners; formalize inventory hedging where justified.
- Medium term (2027): Operationalize supplier partnerships in production-intent runs; reassess portfolio by product tier and transition modules to higher-performance UFS where ROI and supply permit.
What we are deliberately withholding — and why
In keeping with the “trailer” principle that guides PW Consulting’s release strategy, this public summary intentionally highlights macro sizing, concentration metrics and strategic implications while withholding granular subsegment tables and raw numerical worksheets (e.g., detailed regional splits, application-specific revenue lines and per-supplier volumetric allocations). Those detailed datasets and interactive models are essential for program-level procurement negotiations and engineering BOM decisions; they are available exclusively in the full report and accompanying data workbook. The intent is to provide enough diagnostic clarity to inform executive strategy while preserving the detailed intelligence that operational teams require to execute supplier selection and contractual arrangements.
Final note — why 2026 matters
Decisions made in 2026 will disproportionately shape supplier relationships, product architectures and cost curves through the late-2020s. With a market expanding at roughly 15% annually and facing persistent supply-side stressors, OEMs and Tier-1s who coordinate procurement, qualification and design strategy now will gain preferential access to capacity, protect margins and accelerate time-to-market for differentiated cockpit and ADAS experiences. PW Consulting’s full Automotive Embedded Storage (eMMC & UFS) Market report provides the granular forecasting, supplier scorecards and commercial tools needed to operationalize these strategic recommendations. For teams preparing 2026 budgets and sourcing plans, the question is not whether to act — but how quickly and with which partners.
For detailed analysis of this topic, please visit the official page: Automotive Embedded Storage (eMMC and UFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: 14430 Cylindrical Lithium‑Ion Battery Market to Reach USD 171.22 Million by 2032 at a 5.85% CAGR, Asia‑Pacific to Command ~54.7% Share
By pmarketresearch, 2026-07-02
PW Consulting Releases Strategic Brief: 14430 Cylindrical Lithium‑Ion Battery Market — A 2026 Playbook for Decision Makers
PW Consulting today publishes an executive-facing industry brief summarizing the strategic implications of our full 14430 Cylindrical Lithium‑Ion Battery Market report (base year 2025). The study synthesizes five years of historical activity (2020–2025) and delivers a 2026–2032 forecast, giving procurement, product, and corporate strategy teams the context needed to make high‑confidence decisions in an increasingly dynamic component market. The global 14430 market reached approximately USD 115.0 Million in 2025 and, under our central case, is projected to expand at a compound annual growth rate (CAGR) of 5.85% through the forecast horizon — arriving near USD 171.22 Million by 2032.
14430 Cylindrical Lithium Ion Battery Market
Why this brief matters for 2026 planning
-
Timing and cadence: 2026 is a hinge year. Supply‑side efficiencies and chemistry shifts that accelerated in 2024–2025 now intersect with new regulatory and trade levers, creating both near‑term disruption and medium‑term opportunity for firms that act deliberately.
14430 Cylindrical Lithium Ion Battery Market -
Margin and reliability trade‑offs: Component buyers must balance energy density, unit cost, safety certification, and supplier resilience when specifying 14430 cells for compact applications. Small specification choices at the cell level materially change bill‑of‑materials economics across a product family.
14430 Cylindrical Lithium Ion Battery Market -
Portfolio fit: The 14430 form factor is increasingly selected for high‑durability consumer devices, portable medical instruments, and niche industrial modules. Companies that align product roadmaps with realistic supply scenarios will avoid costly redesigns or inventory overhang in 2026.
What the full report delivers — practical content you can use
-
Consolidated market sizing and trend narrative: A clear, audited view of market scale (historical and forecast totals), drivers, and likely inflection points through 2032, with sensitivity cases for raw‑material stress and policy shifts.
-
Procurement playbooks: Supplier segmentation, qualification checklists, contractual levers (including pass‑through clauses for raw‑material swings), procurement scorecards, and recommended hedging approaches tailored to 14430 sourcing.
-
Product engineering trade‑offs: Comparative analyses of chemistry and cell construction trade‑offs (safety, energy density, cycle life, thermal behavior) and design checklists for battery management integration and PCM/PCM‑less options.
-
Supplier due diligence templates and scorecards: A structured framework to evaluate quality systems, certifications, testing protocols, supply continuity, and ESG risk — enabling faster onboarding without compromising compliance.
-
Commercial and channel strategies: Go‑to‑market playbooks for OEMs, ODMs, and distributors, including pricing architecture, bundled warranty models, and small‑volume vs. scale manufacturing decisions.
-
Scenario and stress tests: Three actionable scenarios (base, upside, and downside) mapping the impact of raw‑material price volatility, tariff regimes, and sudden demand shifts on delivery times, cost per unit, and margin.
-
Risk map and mitigation matrix: Practical checklists for safety documentation updates, in‑country regulatory changes, and supplier concentration risks — prioritized by likelihood and impact.
Competitive landscape — what suppliers are signaling for 2026
The 14430 supplier ecosystem mixes established global players and specialized regional manufacturers. Market concentration metrics show a moderate level of aggregation among the leading firms, reflecting a landscape where a handful of suppliers control a sizeable share while a wide tail of nimble vendors competes on customization and cost. Our report’s supplier profiles and benchmarks include operational, product, and commercial intelligence intended to support vendor selection and partnership decisions.
-
Murata Manufacturing Co., Ltd. (Kyoto, Japan) — Murata’s US14430 series positions it as a technology leader for higher‑rate and higher‑capacity applications. Recent safety data sheet updates (February 2026) underscore an emphasis on product stewardship and regulatory alignment — a differentiator for customers operating in regulated medical and safety‑critical markets.
-
DNK Power (China) — Focused on customized battery packs and a range of cell capacities, DNK is representative of the Chinese supplier segment that competes on flexibility and integration services, making it a common choice for OEMs seeking rapid iterations.
-
Topwell Power (China) — With 14430 cells incorporating protection circuitry (PCM) and targeting consumer devices, Topwell exemplifies vendors who optimize for out‑of‑box safety and simpler integration for appliance manufacturers.
-
BZ Battery / Benzo Energy (Guangdong, China) — Specialized in compact, application‑specific 14430 batteries for portable consumer products such as e‑cigarettes, illustrating the demand for bespoke cell engineering in regulated consumer niches.
-
PKCELL (Shenzhen, China) — Active product promotion and application guidance for ICR14430 variants position PKCELL to capture demand from outdoor and portable electronics segments that prize reliability under variable environmental conditions.
-
ELB Energy Group (China) — Offering NCM chemistry in the 14430 footprint, ELB is an example of vendors targeting applications where higher energy density is prioritized over raw‑material cost advantages.
-
Mottcell (China) — The company’s focus on LiFePO4 variants and an updated supplier guide (December 2025) highlights the continuing interest in lower‑risk chemistries for energy storage and industrial applications where cycle life and thermal stability matter most.
Market dynamics and near‑term risks shaping 2026 decisions
-
Raw‑material volatility: Even as average pack prices fell in 2025 to historically low levels (reflecting manufacturing efficiencies and a shift toward lower‑cost chemistries), feedstock markets remain turbulent. Lithium carbonate prices rebounded sharply late in 2025, and cobalt supply constraints following new export quotas in key producing countries have kept price risk elevated. Buyers should not assume the 2025 price slide will be permanent.
-
Chemistry mix shifts: Fast growth in lower‑cost chemistries and rising adoption in stationary storage segments materially affect competitive positioning. A marked increase in demand for certain chemistries (and corresponding cell formats) creates both supply opportunities and substitution threats to traditional 14430 use cases.
-
Policy and trade headwinds: Recent trade policy adjustments and reciprocal tariff changes implemented in 2025–2026 introduce new landed cost and compliance considerations. Strategic sourcing now requires a combined view of tariffs, logistics, and certification timelines.
-
Demand acceleration: Market demand for lithium‑ion battery cells rose substantially in 2025, driven in part by infrastructure projects and BESS deployments. That demand trajectory implies procurement timelines and safety‑testing queues could extend if suppliers are not engaged early.
2026 strategic actions — a checklist for leadership
-
Re‑benchmark total cost to the unit: Move beyond headline cell prices to include testing, certification, PCM options, logistics, duty/tariff assumptions, and second‑order costs such as redesign risk and warranty exposure.
-
Lock in flexible supply arrangements: Prioritize multi‑sourcing, optionality on chemical families, and short‑term contracts with built‑in indexation to key raw‑material baskets to mitigate price shocks.
-
Prioritize supplier audits that emphasize safety and documentation: Recent SDS updates from leading suppliers reflect increasing regulatory scrutiny — compliance readiness is now a differentiator, not just a checkbox.
-
Invest in modular design: Where possible, decouple enclosure and electronics from the cell to allow late‑stage substitution between chemistries or supplier offers without extensive re‑engineering.
-
Prepare an acquisition and partnership toolkit: Smaller specialized cell manufacturers can accelerate time‑to‑market for new applications; consider minority stakes, long‑term supply agreements, or joint testing centers as strategic options.
-
Update commercial strategies for channel partners: Clear product qualification timelines, co‑funded testing, and shared inventory models can reduce lead times and protect revenue in constrained quarters.
How to use this brief and where to go next
This document is an executive companion designed to translate the full report’s data and analysis into immediate actions for 2026. The complete report includes detailed supplier benchmarking, scenario model files, procurement templates, and the granular segmentation that underpins our forecasts. To preserve commercial utility and to avoid disintermediating our clients’ need for a validated dataset, this summary intentionally omits core segmentation tables and specific sub‑segment allocations — those are available in full through the report distribution page and client‑subscription channels.
For teams preparing 2026 budgets, procurement commitments, or product roadmaps, the full PW Consulting report provides the calibrated inputs and executable templates necessary to convert insights into measurable outcomes. Contact our market intelligence desk or visit the PW Consulting report center to request the full dataset, vendor scorecards, and scenario model.
PW Consulting — Strategic clarity for the component decisions that define product futures.
For detailed analysis of this topic, please visit the official page: 14430 Cylindrical Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: MIF Photoresist Developer Market to Expand at a 7.38% CAGR Through 2032 as Asia‑Pacific Leads Global Demand
By pmarketresearch, 2026-07-02
Metal Ion Free (MIF) Photoresist Developer Market — Strategic Brief for 2026 Decision-Makers
PW Consulting’s newest market study on Metal Ion Free (MIF) photoresist developers provides a forward-looking lens for executives making high-stakes 2026 investments across chemicals supply, semiconductor materials, and lithography process chains. The market has expanded steadily from the early 2020s and—driven by sustained demand in advanced lithography—our model shows the global MIF developer market rising from the low‑billion dollar band in 2025 to a markedly larger addressable market by the end of the forecast horizon, tracking at a compound annual growth rate of 7.38% across 2026–2032. This brief synthesizes the strategic value of the report for corporate planners while intentionally reserving granular segment tables and region/application-level breakdowns for the full report.
Metal Ion Free (MIF) Photoresist Developer Market
Why this report matters in 2026
- Timing of capital allocation: Semiconductor materials procurement and fab expansions signed in 2026 will be operational through capacity ramps where developer chemistry specifications (purity, surfactant systems, normality) materially affect yield. Our study translates market growth assumptions into procurement and qualification timelines that minimize technical churn and supply disruption.
- Regulatory and quality alignment: MIF developers are increasingly the default to avoid ionic contamination in sub‑0.5 µm and advanced node processes. The report maps regulatory drivers and supplier responses—critical for product managers and compliance officers planning certification and incoming inspection regimes in 2026.
- Supplier strategy and sourcing: With the market exhibiting mid‑high concentration among leading incumbents, purchasers need a structured supplier-risk framework. The report gives actionable supplier scorecards, switching-cost matrices, and multi‑source qualification pathways to de‑risk single‑sourcing decisions.
Key market dynamics captured
Our analysis integrates supply‑side chemistry realities with downstream lithography roadmaps. Tetramethylammonium hydroxide (TMAH) remains the principal upstream feedstock for aqueous MIF developers; typical formulations in the market are around the standard nominal normality used by most fabs. In 2025 we observed regionally divergent TMAH pricing and demand patterns—softening in Asia in Q2 driven by cyclical electronics demand, with parallel softness in Europe and North America. These upstream swings propagate into supplier margins and inventory policies, which we model in multiple price‑supply scenarios to stress‑test procurement strategies.
Metal Ion Free (MIF) Photoresist Developer Market
Regulatory and device‑reliability considerations are another force multiplier. Our study documents why fabs prefer metal‑ion‑free chemistries for chemically amplified and DNQ‑based photoresists, especially as nodes scale down and process windows tighten. We translate this into practical implications: qualification cycles lengthen, incoming contamination tests intensify, and the value of customized developer blends and vendor‑assisted process support increases.
Metal Ion Free (MIF) Photoresist Developer Market
Competitive landscape — practical takeaways
The market is dominated by established specialty chemicals and electronic materials businesses, supported by a network of niche formulators and lab suppliers. PW Consulting’s vendor benchmarking highlights strategic positioning across R&D depth, global supply footprint, process support, and sustainability posture.
- Global incumbents with broad portfolios: Large specialty chemicals groups maintain leadership via broad AZ‑series or equivalent product lines and integrated customer support for high-throughput fabs. Their competitive advantages include scale manufacturing, certified quality systems, and strategic partnerships with major semiconductor manufacturers.
- Regional champions and formulators: Firms specializing in high‑purity MIF developers and lab‑to‑production transition services compete on agility and tailored formulations for edge cases—sub‑0.5 µm patterning, spray vs. puddle processes, and niche resist chemistries.
- Distribution and lab supply players: A separate category of distributors and lab suppliers extends reach into academic, R&D, and small‑volume production users. Their role in innovation diffusion and early adoption is non‑trivial and often precedes broader commercial uptake.
From a concentration standpoint, the top three players account for a clear majority share of market value, while the top five players command a substantial further portion—underscoring a market where scale and trusted certification matter. This consolidation creates premium capture opportunities for incumbents and entry barriers for newcomers that rely solely on price competition.
Recent supplier moves and what they signal for 2026
- Major suppliers are accelerating eco‑design and sustainability messaging—announcements in 2024–2025 show new “eco‑friendly” MIF developers and related ancillary products. Expect this theme to shift procurement evaluation criteria beyond purity and process compatibility toward lifecycle and regulatory footprints.
- Strategic partnerships between material suppliers and large fabs indicate a trend toward co‑development of customized MIF formulations. For suppliers, this raises switching‑costs for customers; for buyers, it offers process optimization advantages but increases vendor lock‑in risk.
- TMAH price volatility and regional demand softness observed in 2025 suggest that flexible sourcing and inventory strategies will be differentiators in 2026. Companies with hedging mechanisms or diversified geographic production will mitigate margin squeeze and qualification delays.
What the full report contains (practical, implementable modules)
PW Consulting’s report is engineered for decision‑makers who need executable plans, not just high‑level summaries. Core deliverables include:
- Market sizing and a transparent forecast model (2026–2032) with scenario toggles for TMAH price, fab CAPEX cycles, and adoption curves for advanced nodes.
- Supplier scorecards and capability matrices covering production quality, regulatory certifications, global footprint, and customer support depth.
- Supply‑chain vulnerability map with criticality scoring and recommended mitigations—dual sourcing playbooks, qualification timelines, and inventory triggers.
- Commercial strategies for incumbent suppliers and newcomers—product positioning, pricing levers, channel strategies, and partnership models with fabs and IDM/OEMs.
- Regulatory and sustainability impact assessment—how evolving environmental standards change total cost of ownership and procurement evaluation criteria.
- Operational playbooks—lab qualification checklists, process integration guidelines for spray/puddle/immersion tracks, and troubleshooting matrices for common yield and residue issues.
Actionable recommendations for 2026
Below are priority actions tailored to typical stakeholder types. Each recommendation is linked to trigger indicators and KPI alternatives so teams can operationalize within existing governance frameworks.
- For procurement and supply‑chain leaders: Implement a two‑tier supplier qualification plan—fast‑track a primary incumbent with proven scale and a secondary regional supplier with rapid delivery capability. Set inventory trigger points tied to commodity TMAH spot price volatility and fab ramp schedules.
- For product and R&D heads at material suppliers: Prioritize small‑batch co‑development programs with key customers and invest in eco‑formulation platforms. Use strategic partnerships to embed your product in customers’ process windows, while preserving modular IP to avoid full lock‑in risks.
- For fab process engineers: Expand contamination test panels during developer qualification and require vendor‑assisted onsite trials for any new MIF variant. Quantify yield impact across representative layers to accelerate go/no‑go decisions.
- For investors and corporate strategy teams: Focus diligence on players with deep R&D pipelines, proven GMP‑grade manufacturing, and strategic customer agreements. Given market concentration dynamics, M&A plays can be accretive if they add formulation IP or regional capacity without extending qualification timelines excessively.
Roadmap and monitoring framework (2026 milestones)
We recommend a 12‑ to 36‑month roadmap with quarterly milestones tied to both market and technical triggers:
- Q1–Q2 2026: Complete supplier scorecard reviews; establish back‑up sourcing contracts and initiate small co‑development pilots where needed.
- Q3–Q4 2026: Execute pilot transfers and scale validated formulations; benchmark environmental compliance metrics and incorporate into procurement RFPs.
- 2027: Full production readiness with KPI performance tracked (yield delta, qualification cycle time, supply lead time, incidence of contamination events).
Trigger indicators that should prompt tactical shifts include sustained TMAH price moves beyond modeled thresholds, major fab node transitions accelerating faster than forecast, or new regulatory requirements tightening allowable impurities.
Where the “trailer” leads
This note highlights the strategic contours and the practical urgency captured by PW Consulting’s MIF developer study—without reproducing the granular segment tables and vendor scorecards that procurement and product teams depend on for execution. The full report contains detailed regional and application segmentation, downloadable models, supplier negotiation playbooks, and an appendix of test protocols and acceptance criteria. For readers preparing vendor RFPs, M&A diligence, or procurement process rewrites in 2026, those datasets are indispensable.
To access the complete analysis, including interactive forecast scenarios, supplier heatmaps, and procurement templates, visit the report landing page where PW Consulting hosts the downloadable models and an executive briefing package tailored for 2026 decision timelines.
Final thought
In a market where chemistry, contamination control, and regulatory posture intersect with cyclical semiconductor investment patterns, MIF developer strategy is no longer a back‑office commodity decision. It is a strategic lever that affects yield, qualification velocity, and supplier relationships. PW Consulting’s study converts that complexity into executable programs—helping clients align R&D, procurement, and commercial strategy with the market evolution expected through 2032.
For detailed analysis of this topic, please visit the official page: Metal Ion Free (MIF) Photoresist Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com