

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Antibody Market Poised for 7.19% CAGR Through 2032 as Monoclonals Drive Growth

Oct-4 Antibody Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s Oct-4 Antibody Market Report (base year 2025) synthesizes five years of historical dynamics and a seven-year forecast to 2032, delivering a high-fidelity roadmap for R&D buyers, product managers, manufacturing strategists, and corporate development teams. This executive preview outlines the report’s strategic value for decisions you will make in 2026 — from portfolio prioritization and supplier selection to M&A screening and regulatory risk mitigation — while preserving the report’s proprietary segmentation and company-level revenue detail for subscribers.
Oct-4 Antibody Market
Market at a Glance: Growth Trajectory and Competitive Structure
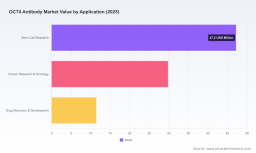
Our bottom-up model indicates the global Oct-4 antibody market reached USD 88.45 Million in 2025 and is set to expand to approximately USD 143.85 Million by 2032, representing a compound annual growth rate (CAGR) of 7.19% across the 2026–2032 forecast window. The market has exhibited steady expansion since 2020, reflecting intensified investment in pluripotency and stem cell research, translational oncology programs, and assay development in both academic and commercial laboratories.
Oct-4 Antibody Market
From a structural standpoint, the market displays moderate concentration: the leading three suppliers account for nearly half of the market, while a broader top-five captures roughly six-in-ten market share. That configuration creates a market environment where scale, validation pedigree, and channel reach provide clear commercial advantages, but differentiated product features and validation claims (e.g., ChIP-seq grade certification, recombinant antibody platforms, and conjugation options) allow mid-tier and specialist vendors to sustain premium niches.
Oct-4 Antibody Market
Why this report matters for 2026 strategic planning
- Procurement and vendor rationalization: With supply chains still sensitive to geographic and manufacturing concentration, procurement teams must weigh price against validated performance and batch-to-batch reproducibility. Our report benchmarks supplier capability across manufacturing footprint, catalog depth, and citation impact to help buyers calibrate vendor consolidation versus diversification strategies.
- Product and portfolio decisions: R&D and product teams can use our demand and application trend analysis to prioritize investments in recombinant monoclonal formats, conjugates for flow and imaging, or ChIP-grade polyclonals — depending on the desired margin profile and validation burden. The report provides a decision matrix tying technical attributes to commercial outcomes (e.g., time-to-adoption, ASP ranges, and channel conversion rates).
- M&A and partnership screening: For corporate development professionals, the report’s valuation comparators, capability maps, and ten-year scenario modeling surface attractive targets — whether bolt-on catalog players with strong regional channels or technology-held assets with differentiated validation claims. Our heatmap narrows the universe to players whose capability sets align with scale-up or vertical integration hypotheses.
- Regulatory and commercialization readiness: Although Oct-4 antibodies are sold as research-use-only (RUO) reagents and are not approved for clinical diagnostics or therapeutic use, the report details the label and disclaimer environment and the practical implications for translational pipelines, reagent claims, and contract manufacturing agreements.
What’s inside the full report (practical, actionable components)
- Market sizing and growth drivers with transparent modeling assumptions covering historical (2020–2025) and forecast (2026–2032) periods.
- End-to-end product landscape mapping (format types, conjugation options, validation grades) and a buyer-focused decision framework that links product attributes to lab workflows.
- Supplier capability and readiness assessments: manufacturing footprint, QC protocols, catalogue breadth, citation analysis, and commercial channel strength.
- Go-to-market playbooks for incumbent suppliers and new entrants, including pricing archetypes, channel incentive structures, and digital commerce levers for 2026–2028.
- Risk register covering batch variability, reagent interchangeability, IP considerations, and regulatory labeling constraints typical to RUO products.
- M&A screening toolkit: valuation comparators, integration scorecards, and three acquisition scenarios with sensitivity tests for revenue ramp and cost synergies.
- Appendices of supplier scorecards, product validation checklists, and reproducibility guidance for lab managers.
Competitive landscape: positioning and tactical moves
Our supplier review concentrates on established life-science reagents manufacturers and specialist antibody houses that dominate research procurement lists. These firms vary by scale, validation focus, and channel strategy — implications that matter when negotiating 2026 supply agreements or selecting co-development partners.
- Large platform vendors: Major diversified life-science companies benefit from breadth of catalogue, global logistics, and institutional procurement relationships that ease large-volume purchasing and bundled product promotions. Their strategic advantage is the ability to tie Oct-4 reagents into larger consumable or instrument deals, which accelerates enterprise adoption within large labs and biopharma R&D groups.
- Specialist antibody houses: Niche suppliers focus on deep validation claims (e.g., ChIP-seq grade, recombinant monoclonal consistency), rapid technical support, and customizable conjugation services. These characteristics support premium pricing and strong academic citation momentum, making them attractive partners for translational research centers and assay developers.
- Regional players and OEM suppliers: Localized manufacturers address price-sensitive segments and regional supply resilience. Their value proposition is shorter lead times and localized technical servicing, but they often face higher hurdles in gaining validation trust outside their geographies.
Recent product catalog updates and targeted validation datasets (notably ChIP-grade verification and IHC-P focused listings) highlight an incremental strategic pivot across suppliers toward application-specific claims that reduce perceived switching costs for laboratory customers. For 2026, expect incremental differentiation to come from demonstrable batch metadata, recombinant engineering that reduces heterogeneity, and bundled assay solutions rather than from competing on price alone.
Company-level themes and implications
- Validation leadership sells: Firms that invest in application-specific validation (e.g., ChIP, IHC-P, flow cytometry panels) command credibility in adoption discussions. Buyers in 2026 will increasingly ask for batch-level QC and orthogonal validation evidence — an element our supplier scorecards quantify.
- Recombinant platforms shorten sales cycles: Suppliers offering recombinant monoclonal formats reduce customer uncertainty around reproducibility. In procurement negotiations, recombinant claims can be leveraged for premium pricing and longer contract cycles.
- Channel bundling influences account penetration: Vendors able to combine Oct-4 antibodies with cell culture media, reagents, or instrumentation capture a larger wallet share within institutional customers. Sales leaders should evaluate cross-sell metrics from such bundles when setting 2026 commercial targets.
Recent industry developments to watch in 2026
- Product catalog updates emphasizing application-specific validation (e.g., ChIP-seq grade and IHC-P) are becoming a primary marketing tool to reduce adoption friction.
- Continued RUO labeling and explicit disclaimers remain industry standard, constraining direct clinical positioning but opening opportunities for co-development agreements tied to regulated companion reagent programs.
- SKU rationalization is ongoing among several suppliers: discontinued SKUs are being replaced with recombinantly produced clones or consolidated catalog numbers — a practical consideration for long-term procurement contracts.
Actionable recommendations for 2026
- For procurement leaders: Build a two-tier supplier strategy: a core supplier for scale and continuity, plus validated niche suppliers for specialized applications. Require batch-level QC data in contracts and include service-level KPIs tied to technical support response times.
- For product and R&D heads: Prioritize investment in recombinant and conjugated formats with orthogonal validation packages. Design pilot studies that compare vendor batches across intended assay types and publish validation findings to accelerate internal buy-in.
- For corporate development teams: Use our M&A heatmap to prioritize targets that fill capability gaps (e.g., ChIP-grade expertise or strong regional channels). Focus due diligence on reproducibility evidence and order book stickiness rather than catalogue breadth alone.
- For CROs and assay developers: Offer bundled assay-reagent packages that include documented validation workflows to lock in institutional clients that prefer turnkey solutions.
Where this preview leaves you
This briefing gives you the strategic framing you need to prepare for procurement cycles, product bets, and M&A activity in 2026. It is intentionally a “trailer”: the full PW Consulting Oct-4 Antibody Market Report contains the proprietary segmentation tables, supplier-level revenue estimates, regional dynamics, and the source-level data that underpin our conclusions. Those proprietary datasets are excluded from this preview to preserve their commercial value and to provide you with an actionable reason to obtain the full intelligence package.
For teams planning budgets, vendor negotiations, or strategic initiatives in 2026, the full report will convert these strategic insights into specific tactical deliverables — from vendor shortlists and contract templates to deal modeling and product roadmaps. To access the comprehensive dataset, supplier scorecards, and step-by-step playbooks, please visit the PW Consulting report page or contact our subscriptions desk for enterprise licensing and bespoke advisory packages.
For detailed analysis of this topic, please visit the official page: Oct-4 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com