

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: MIF Photoresist Developer Market to Expand at a 7.38% CAGR Through 2032 as Asia‑Pacific Leads Global Demand

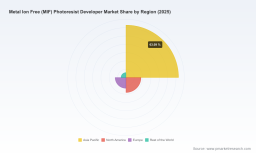
Metal Ion Free (MIF) Photoresist Developer Market — Strategic Brief for 2026 Decision-Makers
PW Consulting’s newest market study on Metal Ion Free (MIF) photoresist developers provides a forward-looking lens for executives making high-stakes 2026 investments across chemicals supply, semiconductor materials, and lithography process chains. The market has expanded steadily from the early 2020s and—driven by sustained demand in advanced lithography—our model shows the global MIF developer market rising from the low‑billion dollar band in 2025 to a markedly larger addressable market by the end of the forecast horizon, tracking at a compound annual growth rate of 7.38% across 2026–2032. This brief synthesizes the strategic value of the report for corporate planners while intentionally reserving granular segment tables and region/application-level breakdowns for the full report.
Metal Ion Free (MIF) Photoresist Developer Market
Why this report matters in 2026
- Timing of capital allocation: Semiconductor materials procurement and fab expansions signed in 2026 will be operational through capacity ramps where developer chemistry specifications (purity, surfactant systems, normality) materially affect yield. Our study translates market growth assumptions into procurement and qualification timelines that minimize technical churn and supply disruption.
- Regulatory and quality alignment: MIF developers are increasingly the default to avoid ionic contamination in sub‑0.5 µm and advanced node processes. The report maps regulatory drivers and supplier responses—critical for product managers and compliance officers planning certification and incoming inspection regimes in 2026.
- Supplier strategy and sourcing: With the market exhibiting mid‑high concentration among leading incumbents, purchasers need a structured supplier-risk framework. The report gives actionable supplier scorecards, switching-cost matrices, and multi‑source qualification pathways to de‑risk single‑sourcing decisions.
Key market dynamics captured
Our analysis integrates supply‑side chemistry realities with downstream lithography roadmaps. Tetramethylammonium hydroxide (TMAH) remains the principal upstream feedstock for aqueous MIF developers; typical formulations in the market are around the standard nominal normality used by most fabs. In 2025 we observed regionally divergent TMAH pricing and demand patterns—softening in Asia in Q2 driven by cyclical electronics demand, with parallel softness in Europe and North America. These upstream swings propagate into supplier margins and inventory policies, which we model in multiple price‑supply scenarios to stress‑test procurement strategies.
Metal Ion Free (MIF) Photoresist Developer Market
Regulatory and device‑reliability considerations are another force multiplier. Our study documents why fabs prefer metal‑ion‑free chemistries for chemically amplified and DNQ‑based photoresists, especially as nodes scale down and process windows tighten. We translate this into practical implications: qualification cycles lengthen, incoming contamination tests intensify, and the value of customized developer blends and vendor‑assisted process support increases.
Metal Ion Free (MIF) Photoresist Developer Market
Competitive landscape — practical takeaways
The market is dominated by established specialty chemicals and electronic materials businesses, supported by a network of niche formulators and lab suppliers. PW Consulting’s vendor benchmarking highlights strategic positioning across R&D depth, global supply footprint, process support, and sustainability posture.
- Global incumbents with broad portfolios: Large specialty chemicals groups maintain leadership via broad AZ‑series or equivalent product lines and integrated customer support for high-throughput fabs. Their competitive advantages include scale manufacturing, certified quality systems, and strategic partnerships with major semiconductor manufacturers.
- Regional champions and formulators: Firms specializing in high‑purity MIF developers and lab‑to‑production transition services compete on agility and tailored formulations for edge cases—sub‑0.5 µm patterning, spray vs. puddle processes, and niche resist chemistries.
- Distribution and lab supply players: A separate category of distributors and lab suppliers extends reach into academic, R&D, and small‑volume production users. Their role in innovation diffusion and early adoption is non‑trivial and often precedes broader commercial uptake.
From a concentration standpoint, the top three players account for a clear majority share of market value, while the top five players command a substantial further portion—underscoring a market where scale and trusted certification matter. This consolidation creates premium capture opportunities for incumbents and entry barriers for newcomers that rely solely on price competition.
Recent supplier moves and what they signal for 2026
- Major suppliers are accelerating eco‑design and sustainability messaging—announcements in 2024–2025 show new “eco‑friendly” MIF developers and related ancillary products. Expect this theme to shift procurement evaluation criteria beyond purity and process compatibility toward lifecycle and regulatory footprints.
- Strategic partnerships between material suppliers and large fabs indicate a trend toward co‑development of customized MIF formulations. For suppliers, this raises switching‑costs for customers; for buyers, it offers process optimization advantages but increases vendor lock‑in risk.
- TMAH price volatility and regional demand softness observed in 2025 suggest that flexible sourcing and inventory strategies will be differentiators in 2026. Companies with hedging mechanisms or diversified geographic production will mitigate margin squeeze and qualification delays.
What the full report contains (practical, implementable modules)
PW Consulting’s report is engineered for decision‑makers who need executable plans, not just high‑level summaries. Core deliverables include:
- Market sizing and a transparent forecast model (2026–2032) with scenario toggles for TMAH price, fab CAPEX cycles, and adoption curves for advanced nodes.
- Supplier scorecards and capability matrices covering production quality, regulatory certifications, global footprint, and customer support depth.
- Supply‑chain vulnerability map with criticality scoring and recommended mitigations—dual sourcing playbooks, qualification timelines, and inventory triggers.
- Commercial strategies for incumbent suppliers and newcomers—product positioning, pricing levers, channel strategies, and partnership models with fabs and IDM/OEMs.
- Regulatory and sustainability impact assessment—how evolving environmental standards change total cost of ownership and procurement evaluation criteria.
- Operational playbooks—lab qualification checklists, process integration guidelines for spray/puddle/immersion tracks, and troubleshooting matrices for common yield and residue issues.
Actionable recommendations for 2026
Below are priority actions tailored to typical stakeholder types. Each recommendation is linked to trigger indicators and KPI alternatives so teams can operationalize within existing governance frameworks.
- For procurement and supply‑chain leaders: Implement a two‑tier supplier qualification plan—fast‑track a primary incumbent with proven scale and a secondary regional supplier with rapid delivery capability. Set inventory trigger points tied to commodity TMAH spot price volatility and fab ramp schedules.
- For product and R&D heads at material suppliers: Prioritize small‑batch co‑development programs with key customers and invest in eco‑formulation platforms. Use strategic partnerships to embed your product in customers’ process windows, while preserving modular IP to avoid full lock‑in risks.
- For fab process engineers: Expand contamination test panels during developer qualification and require vendor‑assisted onsite trials for any new MIF variant. Quantify yield impact across representative layers to accelerate go/no‑go decisions.
- For investors and corporate strategy teams: Focus diligence on players with deep R&D pipelines, proven GMP‑grade manufacturing, and strategic customer agreements. Given market concentration dynamics, M&A plays can be accretive if they add formulation IP or regional capacity without extending qualification timelines excessively.
Roadmap and monitoring framework (2026 milestones)
We recommend a 12‑ to 36‑month roadmap with quarterly milestones tied to both market and technical triggers:
- Q1–Q2 2026: Complete supplier scorecard reviews; establish back‑up sourcing contracts and initiate small co‑development pilots where needed.
- Q3–Q4 2026: Execute pilot transfers and scale validated formulations; benchmark environmental compliance metrics and incorporate into procurement RFPs.
- 2027: Full production readiness with KPI performance tracked (yield delta, qualification cycle time, supply lead time, incidence of contamination events).
Trigger indicators that should prompt tactical shifts include sustained TMAH price moves beyond modeled thresholds, major fab node transitions accelerating faster than forecast, or new regulatory requirements tightening allowable impurities.
Where the “trailer” leads
This note highlights the strategic contours and the practical urgency captured by PW Consulting’s MIF developer study—without reproducing the granular segment tables and vendor scorecards that procurement and product teams depend on for execution. The full report contains detailed regional and application segmentation, downloadable models, supplier negotiation playbooks, and an appendix of test protocols and acceptance criteria. For readers preparing vendor RFPs, M&A diligence, or procurement process rewrites in 2026, those datasets are indispensable.
To access the complete analysis, including interactive forecast scenarios, supplier heatmaps, and procurement templates, visit the report landing page where PW Consulting hosts the downloadable models and an executive briefing package tailored for 2026 decision timelines.
Final thought
In a market where chemistry, contamination control, and regulatory posture intersect with cyclical semiconductor investment patterns, MIF developer strategy is no longer a back‑office commodity decision. It is a strategic lever that affects yield, qualification velocity, and supplier relationships. PW Consulting’s study converts that complexity into executable programs—helping clients align R&D, procurement, and commercial strategy with the market evolution expected through 2032.
For detailed analysis of this topic, please visit the official page: Metal Ion Free (MIF) Photoresist Developer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com