

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: 14430 Cylindrical Lithium‑Ion Battery Market to Reach USD 171.22 Million by 2032 at a 5.85% CAGR, Asia‑Pacific to Command ~54.7% Share

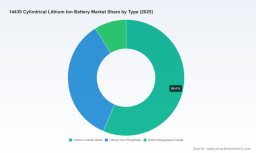
PW Consulting Releases Strategic Brief: 14430 Cylindrical Lithium‑Ion Battery Market — A 2026 Playbook for Decision Makers
PW Consulting today publishes an executive-facing industry brief summarizing the strategic implications of our full 14430 Cylindrical Lithium‑Ion Battery Market report (base year 2025). The study synthesizes five years of historical activity (2020–2025) and delivers a 2026–2032 forecast, giving procurement, product, and corporate strategy teams the context needed to make high‑confidence decisions in an increasingly dynamic component market. The global 14430 market reached approximately USD 115.0 Million in 2025 and, under our central case, is projected to expand at a compound annual growth rate (CAGR) of 5.85% through the forecast horizon — arriving near USD 171.22 Million by 2032.
14430 Cylindrical Lithium Ion Battery Market
Why this brief matters for 2026 planning
-
Timing and cadence: 2026 is a hinge year. Supply‑side efficiencies and chemistry shifts that accelerated in 2024–2025 now intersect with new regulatory and trade levers, creating both near‑term disruption and medium‑term opportunity for firms that act deliberately.
14430 Cylindrical Lithium Ion Battery Market -
Margin and reliability trade‑offs: Component buyers must balance energy density, unit cost, safety certification, and supplier resilience when specifying 14430 cells for compact applications. Small specification choices at the cell level materially change bill‑of‑materials economics across a product family.
14430 Cylindrical Lithium Ion Battery Market -
Portfolio fit: The 14430 form factor is increasingly selected for high‑durability consumer devices, portable medical instruments, and niche industrial modules. Companies that align product roadmaps with realistic supply scenarios will avoid costly redesigns or inventory overhang in 2026.
What the full report delivers — practical content you can use
-
Consolidated market sizing and trend narrative: A clear, audited view of market scale (historical and forecast totals), drivers, and likely inflection points through 2032, with sensitivity cases for raw‑material stress and policy shifts.
-
Procurement playbooks: Supplier segmentation, qualification checklists, contractual levers (including pass‑through clauses for raw‑material swings), procurement scorecards, and recommended hedging approaches tailored to 14430 sourcing.
-
Product engineering trade‑offs: Comparative analyses of chemistry and cell construction trade‑offs (safety, energy density, cycle life, thermal behavior) and design checklists for battery management integration and PCM/PCM‑less options.
-
Supplier due diligence templates and scorecards: A structured framework to evaluate quality systems, certifications, testing protocols, supply continuity, and ESG risk — enabling faster onboarding without compromising compliance.
-
Commercial and channel strategies: Go‑to‑market playbooks for OEMs, ODMs, and distributors, including pricing architecture, bundled warranty models, and small‑volume vs. scale manufacturing decisions.
-
Scenario and stress tests: Three actionable scenarios (base, upside, and downside) mapping the impact of raw‑material price volatility, tariff regimes, and sudden demand shifts on delivery times, cost per unit, and margin.
-
Risk map and mitigation matrix: Practical checklists for safety documentation updates, in‑country regulatory changes, and supplier concentration risks — prioritized by likelihood and impact.
Competitive landscape — what suppliers are signaling for 2026
The 14430 supplier ecosystem mixes established global players and specialized regional manufacturers. Market concentration metrics show a moderate level of aggregation among the leading firms, reflecting a landscape where a handful of suppliers control a sizeable share while a wide tail of nimble vendors competes on customization and cost. Our report’s supplier profiles and benchmarks include operational, product, and commercial intelligence intended to support vendor selection and partnership decisions.
-
Murata Manufacturing Co., Ltd. (Kyoto, Japan) — Murata’s US14430 series positions it as a technology leader for higher‑rate and higher‑capacity applications. Recent safety data sheet updates (February 2026) underscore an emphasis on product stewardship and regulatory alignment — a differentiator for customers operating in regulated medical and safety‑critical markets.
-
DNK Power (China) — Focused on customized battery packs and a range of cell capacities, DNK is representative of the Chinese supplier segment that competes on flexibility and integration services, making it a common choice for OEMs seeking rapid iterations.
-
Topwell Power (China) — With 14430 cells incorporating protection circuitry (PCM) and targeting consumer devices, Topwell exemplifies vendors who optimize for out‑of‑box safety and simpler integration for appliance manufacturers.
-
BZ Battery / Benzo Energy (Guangdong, China) — Specialized in compact, application‑specific 14430 batteries for portable consumer products such as e‑cigarettes, illustrating the demand for bespoke cell engineering in regulated consumer niches.
-
PKCELL (Shenzhen, China) — Active product promotion and application guidance for ICR14430 variants position PKCELL to capture demand from outdoor and portable electronics segments that prize reliability under variable environmental conditions.
-
ELB Energy Group (China) — Offering NCM chemistry in the 14430 footprint, ELB is an example of vendors targeting applications where higher energy density is prioritized over raw‑material cost advantages.
-
Mottcell (China) — The company’s focus on LiFePO4 variants and an updated supplier guide (December 2025) highlights the continuing interest in lower‑risk chemistries for energy storage and industrial applications where cycle life and thermal stability matter most.
Market dynamics and near‑term risks shaping 2026 decisions
-
Raw‑material volatility: Even as average pack prices fell in 2025 to historically low levels (reflecting manufacturing efficiencies and a shift toward lower‑cost chemistries), feedstock markets remain turbulent. Lithium carbonate prices rebounded sharply late in 2025, and cobalt supply constraints following new export quotas in key producing countries have kept price risk elevated. Buyers should not assume the 2025 price slide will be permanent.
-
Chemistry mix shifts: Fast growth in lower‑cost chemistries and rising adoption in stationary storage segments materially affect competitive positioning. A marked increase in demand for certain chemistries (and corresponding cell formats) creates both supply opportunities and substitution threats to traditional 14430 use cases.
-
Policy and trade headwinds: Recent trade policy adjustments and reciprocal tariff changes implemented in 2025–2026 introduce new landed cost and compliance considerations. Strategic sourcing now requires a combined view of tariffs, logistics, and certification timelines.
-
Demand acceleration: Market demand for lithium‑ion battery cells rose substantially in 2025, driven in part by infrastructure projects and BESS deployments. That demand trajectory implies procurement timelines and safety‑testing queues could extend if suppliers are not engaged early.
2026 strategic actions — a checklist for leadership
-
Re‑benchmark total cost to the unit: Move beyond headline cell prices to include testing, certification, PCM options, logistics, duty/tariff assumptions, and second‑order costs such as redesign risk and warranty exposure.
-
Lock in flexible supply arrangements: Prioritize multi‑sourcing, optionality on chemical families, and short‑term contracts with built‑in indexation to key raw‑material baskets to mitigate price shocks.
-
Prioritize supplier audits that emphasize safety and documentation: Recent SDS updates from leading suppliers reflect increasing regulatory scrutiny — compliance readiness is now a differentiator, not just a checkbox.
-
Invest in modular design: Where possible, decouple enclosure and electronics from the cell to allow late‑stage substitution between chemistries or supplier offers without extensive re‑engineering.
-
Prepare an acquisition and partnership toolkit: Smaller specialized cell manufacturers can accelerate time‑to‑market for new applications; consider minority stakes, long‑term supply agreements, or joint testing centers as strategic options.
-
Update commercial strategies for channel partners: Clear product qualification timelines, co‑funded testing, and shared inventory models can reduce lead times and protect revenue in constrained quarters.
How to use this brief and where to go next
This document is an executive companion designed to translate the full report’s data and analysis into immediate actions for 2026. The complete report includes detailed supplier benchmarking, scenario model files, procurement templates, and the granular segmentation that underpins our forecasts. To preserve commercial utility and to avoid disintermediating our clients’ need for a validated dataset, this summary intentionally omits core segmentation tables and specific sub‑segment allocations — those are available in full through the report distribution page and client‑subscription channels.
For teams preparing 2026 budgets, procurement commitments, or product roadmaps, the full PW Consulting report provides the calibrated inputs and executable templates necessary to convert insights into measurable outcomes. Contact our market intelligence desk or visit the PW Consulting report center to request the full dataset, vendor scorecards, and scenario model.
PW Consulting — Strategic clarity for the component decisions that define product futures.
For detailed analysis of this topic, please visit the official page: 14430 Cylindrical Lithium Ion Battery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com