

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Camouflage Netting Market to Reach USD 1.22 Billion by 2032, Driven by Strong Defense Demand
By pmarketresearch, 2026-07-02
Camouflage Netting Market — Strategic Briefing for 2026 Decision-Makers
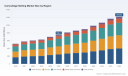
PW Consulting today publishes a synthesized industry briefing drawn from our full Camouflage Netting Market report (base year 2025, forecast 2026–2032). The market has entered a structurally positive phase: after consistent expansion through 2020–2025, global revenues exceeded USD 740 million in 2025 and are projected to grow at a compound annual growth rate (CAGR) of approximately 7.25% over the 2026–2032 forecast window, reaching a market scale in excess of USD 1.2 billion by 2032. For defense procurement officers, manufacturing executives, and investor teams preparing 2026 strategies, the implications are straightforward — demand momentum is real, the technology bar is rising, and strategic timing matters.
Camouflage Netting Market
Why this market matters for 2026 planning
-
Multispectral capability has transitioned from specialist niche to baseline requirement. Modern operational concepts increasingly require visual, near‑IR, thermal and radar signature management; buyers are reallocating budgets to acquire systems that perform across multiple sensor modalities rather than single-spectrum camouflage nets.
Camouflage Netting Market -
Defense procurement cycles and large tenders are shaping vendor pipelines. Recent public procurement activity, including major tenders and high-profile contract awards in late 2025–early 2026, underscores near-term procurement windows that vendors and primes should prioritize when aligning production and certification schedules.
Camouflage Netting Market -
Commercial opportunities are emerging alongside defense demand. Event, entertainment, and specialty commercial applications remain smaller by revenue but are sources of margin diversification and product innovation that can accelerate adoption of improved coatings and sustainable substrates.
What our full report delivers (practical, transaction‑ready content)
Our full market study goes beyond headline forecasts to provide tools executives can apply immediately in 2026 decision cycles. Highlights include:
-
Procurement playbooks for defense buyers — decision matrices that map requirement profiles (static site, vehicle, personnel, expeditionary shelters) to candidate product architectures and test protocols, allowing rapid shortlisting before issuing RFPs or executing urgent buys.
-
Supplier scorecards and risk heatmaps — proprietary benchmarking of technology fit, supply‑chain resilience, production lead times, and quality certification pathways to de‑risk single‑source exposure and optimize multi‑vendor contracts.
-
Dynamic cost models — driven by raw material price scenarios (including sensitivity to polyester resin volatility), manufacturing throughput, and finishing process costs for multispectral coatings; the model supports “what‑if” margin and pricing analyses for 12–36 month procurement cycles.
-
Go‑to‑market playbooks for manufacturers and investors — route‑to‑market options by capability tier, partnering templates with defence primes and integrators, and M&A screening criteria for accretive tuck‑ins versus capability acquisitions.
-
Technology adoption pathways — timelines and investment profiles for integrating thermal suppression, radar scattering treatments, ultralight fabrics, and sustainable material substitutions without compromising multispectral performance.
-
Regulatory and standards tracker — mapping of defence procurement priorities (including national defence appropriation shifts) and relevant certification pathways critical to market entry and contract performance.
Competitive landscape: how to read the supplier map in 2026
The market remains moderately concentrated, with leading specialized manufacturers and prime suppliers capturing meaningful shares overall. Our analysis of public and proprietary intelligence shows a mixed ecosystem: international engineering primes that offer multispectral systems and integration services; national or regional manufacturers with deep camouflage product portfolios; and agile niche players focused on cost‑effective or bespoke solutions for hunting, events, and civil uses.
-
Strategic integrators: Companies such as Saab (Barracuda) have positioned multispectral systems with heavy emphasis on signature management across visual-to-thermal bands and platform-level integration. Their offerings reflect investments in lightweight architectures and modular systems for vehicle and site concealment.
-
Tier‑one specialty suppliers: Firms with ULCANS/ULCAS (ultra‑lightweight camouflage screen) solutions have secured defense program placements and long-term framework positions in several national markets. Their competitive advantage is often certification pedigree and field-proven performance against modern sensor suites.
-
Regional and niche manufacturers: A broad set of companies supply durable, fire‑retardant, or cost‑optimized nets for non‑combat applications; these suppliers preserve margin by serving diverse civil markets (film, events, hunting) and via private‑labeling agreements with distributors.
Recent vendor developments highlight two important dynamics: first, large contract awards and procurement positioning are accelerating scale players’ revenue and R&D capacity; second, product launches in late 2025 and early 2026 show technology diffusion from defense into commercial product families (e.g., IR‑suppressive coatings and thermal mitigation variants). Our full competitive profiles drill down into product families, factory footprints, and supply‑chain linkages for each named supplier.
Supply‑side and cost dynamics to watch in 2026
-
Raw material volatility: Polyester remains a dominant base material for many net types due to strength/weight/cost balance. Historical price swings in polyester resin materially impact manufacturing margins and should be modeled as a core scenario when negotiating multi‑year contracts.
-
Manufacturing flexibility: Suppliers with modular production lines and diversified substrate capability (e.g., polyester, nylon blends, bio‑based fibres) can respond faster to near‑term contract awards and premium product opportunities.
-
Sustainability and supply risk: There is growing industry momentum to incorporate recycled polyester and plant‑based fibres without sacrificing multispectral performance. Early movers will gain procurement preference as defence buyers integrate environmental requirements in RFPs.
Demand drivers and procurement signals
Three demand vectors are particularly actionable for 2026 planning:
-
Military modernization programs prioritize multispectral signature management, creating recurring procurement windows and aftermarket sustainment demand. This underpins the mid‑term forecast and supports capital investment in production capacity and accreditation programs.
-
Expeditionary and rapid‑deployment capabilities push demand for lightweight, rapidly deployable net systems and integrated shelters. Procurement cycles for these assets often require accelerated lead times and verified supply‑chain continuity clauses.
-
Commercial diversification (events, architectural concealment, wildlife photography) remains a reserve growth channel for producers seeking to smooth seasonality and protect factory utilization.
Strategic recommendations for 2026
For executives and government buyers preparing decisions this year, PW Consulting recommends a three‑track approach:
-
For buyers (military and government): Insert multispectral performance requirements and supplier minimums into upcoming tenders; require price‑indexing clauses tied to raw material swings; and mandate capability demonstrations under representative sensor suites as part of evaluation criteria.
-
For manufacturers and tier‑one suppliers: Prioritize certification and field validation for multispectral solutions, invest selectively in low‑carbon feedstocks and finishings to win environmentally weighted contracts, and secure strategic supplier agreements for core resins to hedge volatility.
-
For investors and M&A teams: Target acquisitions that close capability gaps (thermal suppression coatings, rapid modular assembly lines, or distributor networks) rather than betting on volume alone; mid‑market technology specialists with proven defense program entries are the most accretive opportunities in 2026.
Risks and mitigating actions
-
Single‑source risk from large suppliers and concentration of critical component supply can disrupt timelines; mitigate with dual‑sourcing requirements and strategic stockpiles at program level.
-
Material price shocks remain a tail risk — incorporate flexible pricing mechanisms and short‑form hedges into supplier contracts to stabilize budgets over 12–24 month procurement cycles.
-
Regulatory and export controls can constrain cross‑border partnerships; maintain compliance roadmaps and pre‑clearance strategies for technology transfers when contracting with international primes.
Where the full PW Consulting report adds value
This briefing is designed to orient 2026 strategic decisions. The full PW Consulting Camouflage Netting Market report provides the granular tools and proprietary datasets that teams will use to execute those decisions: scenario financial models, supplier scorecards, technology readiness assessments, a procurement timing calendar aligned to public tenders and defense budget cycles, and downloadable templates for RFP language and acceptance testing. To respect the briefing “teaser” principle, we have withheld the detailed regional, material and application revenue splits from this summary — these are included in the full report alongside appendices that reconcile our market model to primary procurement and production intelligence.
Final note to decision‑makers
Entering 2026, the camouflage netting market presents a blend of stable defense-driven demand and commercial innovation opportunities. The path from supplier selection to contract execution will increasingly favor organizations that can demonstrate multispectral effectiveness, supply resilience, and environmental stewardship. PW Consulting’s full report equips teams to choose the right partners, time investments with procurement cycles, and structure contracts to protect margins amid material volatility. For procurement directors, program managers, and corporate strategists, the next 12 months will be decisive — well‑prepared actors will convert market momentum into long‑term advantage.
To request the full report, supplier scorecards, and scenario models, contact PW Consulting’s Camouflage Netting Market desk directly.
For detailed analysis of this topic, please visit the official page: Camouflage Netting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Spectrum Analyzer Market Poised to Hit USD 700.1 Million by 2032, Advancing at a 7.42% CAGR
By pmarketresearch, 2026-07-02
Laser Spectrum Analyzer Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market study on the Laser Spectrum Analyzer market delivers an evidence-based briefing designed to shape strategic choices in 2026. Anchored on a 2025 base year and a forward-looking forecast to 2032, this analysis translates measurable market dynamics into actionable options for product leaders, supply-chain executives, corporate development teams, and technical R&D managers. Below we summarize the report’s central findings, the practical content packed into the full deliverable, and prioritized recommendations to navigate competitive, regulatory, and supply-side disruptions.
Laser Spectrum Analyzer Market
Market trajectory at a glance
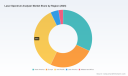
The laser spectrum analyzer market is on a steady expansion path: after a 2023–2025 period of measured growth, the market base in 2025 stands as the report’s anchor. From 2026 onward the market is projected to expand at a compound annual growth rate (CAGR) of 7.42%, with the total market approaching the high hundreds of millions of USD by 2032. This combination of resilient growth and accelerating investment in photonics instrumentation underscores a clear opportunity window for firms that can align product performance, supply security, and go-to-market agility.
Laser Spectrum Analyzer Market
What the full report contains — practical, deal-ready intelligence
- Robust market sizing and forecast model: Transparent methodology (historical 2020–2025 baseline; forecast 2026–2032) with scenario sensitivity to price erosion, component lead-time shocks, and accelerated adoption in telecommunications and scientific applications.
- Technology and product roadmaps: Comparative performance matrices for scanning Michelson interferometers, Fabry–Pérot devices, grating-based spectrometers, and static interferometers — including resolution, dynamic range, footprint, and test throughput trade-offs.
- Buy-side decision frameworks: Procurement checklists and cost-of-ownership models tailored to lab, manufacturing, and field-test environments, enabling procurement teams to quantify TCO and measurement risk across supplier options.
- Supply-chain and regulatory risk maps: Component-level sensitivity analysis, alternative sourcing strategies, and mitigation playbooks for emerging export controls and raw-material constraints.
- Competitive scouting and M&A watchlist: Qualitative profiles and capability gaps for leading incumbents and fast-growing specialists, together with an M&A scoring model to prioritize targets by technology fit, geographic reach, and integration risk.
- Commercial playbooks: Pricing strategies, channel design, and bundling approaches (hardware + firmware + services) to protect margin as instruments become more modular and software-driven.
Competitive landscape — what to watch in 2026
The market shows a moderate level of concentration among top vendors, reflecting established incumbents with deep optical-measurement portfolios alongside agile specialists targeting niches like VCSEL characterization, integrated photonics, and PXIe form factors. Leading instrument houses continue to compete on three axes: resolution and measurement fidelity, form-factor and integration flexibility, and verticalized product ecosystems that embed tunable sources and automated analysis.
Laser Spectrum Analyzer Market
- Bristol Instruments (US) — Strengths: Michelson interferometer implementations combined with FFT-based analysis provide high resolution and integrated wavelength metering for advanced laser labs. Strategic posture: pursue deeper integrations with laser-control electronics and stabilization systems to extend value beyond raw measurement.
- Thorlabs (US) — Strengths: Broad OSA portfolio focused on high resolution and dual-detection designs for both fiber-coupled and free-space testing. Strategic posture: leverage distribution and optical-component scale to bundle instruments into rapid-deployment lab kits for research and telecom testbeds.
- Yokogawa (Japan) — Strengths: Multi-decade heritage and wide wavelength coverage make it a default supplier for many telecom and industrial customers. Strategic posture: defend premium positioning by accelerating software upgrades and services for cloud-enabled measurement management.
- Anritsu and EXFO (Japan/Canada) — Strengths: Telecom-focused platforms and intelligent feature sets (OSNR, channel power, SMSR). Strategic posture: capitalize on network modernization cycles and expand lab-to-manufacturing workflows with factory-automation integrations.
- Keysight and Shimadzu — Strengths: Cross-domain test ecosystems and newly launched product variants that extend coverage into communications bands and high-speed measurement. Strategic posture: bundle ecosystem advantages (signal sources, analysis software) and highlight validated workflows for semiconductor and photonics fabs.
- Quantifi Photonics, APEX, HighFinesse, Optoplex, O/E Land, CNI — Strengths: Niche specialization in form factors (PXIe, benchtop), sub-micron resolution, integrated tunable lasers, and cost-competitive spectrometers. Strategic posture: scale selective partnerships with larger OEMs for distribution, and position IP-rich modules as acquisition targets for incumbents seeking capability in compact, high-resolution platforms.
Recent product and market movements to monitor
- Shimadzu’s 2026 roll-out of an InGaAs-type laser spectrum analyzer targets broader optical-communications coverage while emphasizing high-speed measurement — a signal that established instrumentation vendors are prioritizing communications-band performance and market reach expansion.
- Bristol Instruments’ 2024 introductions (multi-laser PID controllers and wavelength meters) reveal a persistent strategy: marry measurement with control to create closed-loop offerings that increase switching costs for customers.
- Smaller innovators showcased modular and integrated-source solutions (e.g., demonstrations combining novel light sources with PXIe analyzers), illustrating a trend to shrink benchtop footprints while raising throughput for component test.
Industry dynamics that will shape 2026 decisions
- Regulatory pressure: U.S. export controls affecting advanced equipment (with updates influencing supply chains through early 2026) require firms to embed regulatory contingency in procurement and corporate-development playbooks. Those that anticipate licensing timelines and technology carve-outs will have a competitive edge in cross-border deals.
- Component and material risk: Geopolitical tensions and semiconductor supply-chain disruptions are already lengthening lead times and inflating costs for critical optical components. Executives must quantify single-supplier exposures and validate dual-sourcing or buffer-inventory strategies for subassemblies.
- Helium and utility constraints: Ongoing regional supply shocks, partly driven by geopolitical conflict and trade restrictions, threaten process-critical gases used upstream in some optical component manufacturing. Buyers should stress-test suppliers for alternative process maturity and material-substitution roadmaps.
- Convergence of instrumentation and software: Competitive differentiation is shifting toward integrated measurement ecosystems—hardware plus advanced analytics, automation, and lifecycle services—creating recurring revenue opportunities but also increasing the importance of software security and calibration ecosystems.
Actionable strategic playbook for 2026
- Prioritize modular product architectures: Design next-generation instruments to accept pluggable detectors and tunable sources. This preserves upgrade paths and shortens sales cycles with large customers seeking platform consolidation.
- Mitigate supply risk now: Initiate dual-sourcing for critical components, secure multi-year contracts for process gases where possible, and invest in inventory hedges for long-lead optics and detectors.
- Embed regulatory intelligence: Assign a cross-functional export-control and trade-compliance task force for any M&A or distribution deal with Asia–North America linkages; pre-clearance and contingency clauses will speed time-to-revenue in restricted geographies.
- Commercialize software and services: Build calibration-as-a-service and cloud-enabled analytics offerings to convert one-time instrument sales into sticky, subscription-like revenue streams that also enhance customer retention.
- Use M&A selectively: Target smaller, IP-rich specialists that bring unique detector technologies, integrated tunable sources, or compact form factors. Use the report’s M&A scoring model to rank targets by technical fit, margin accretion potential, and integration complexity.
- Segment go-to-market by buyer-risk tolerance: Offer tiered product bundles for research labs (performance-first), manufacturing floors (throughput and automation), and field-test (ruggedness and portability). Align channel incentives to minimize inventory risk and accelerate adoption.
Why PW Consulting’s report matters for 2026
Decision-makers entering 2026 face a market where instrument capabilities and commercial models are evolving simultaneously. PW Consulting’s study converts raw market momentum (a mid-single-digit to high-single-digit CAGR through 2032) into prioritized strategic choices: where to invest in R&D, which supply-chain risks to remediate first, how to price and bundle instruments, and which potential acquisition targets will most rapidly extend capability or market reach.
We intentionally preserve detailed segment-level breakdowns, proprietary supplier scores, and the full dataset behind our model for the full report. Those granular figures are essential for transaction diligence, regional go-to-market planning, and product-roadmap prioritization—and are available through the PW Consulting report portal for clients who require deal-ready analytics.
Next steps
- Download the complete Laser Spectrum Analyzer Market report for the full datasets, regional and application-level projections, and the M&A watchlist.
- Schedule a strategy workshop with PW Consulting to translate the report into a tailored 90-day roadmap (product, supply chain, and corporate development).
- Request a brief on regulatory contingencies tailored to your geographic footprint and supplier network to quantify time-to-market impacts for targeted product launches in 2026.
PW Consulting’s Laser Spectrum Analyzer Market preview is designed to inform high-stakes decisions in 2026. It identifies where growth will concentrate, what operational risks to prioritize, and how to convert measurement innovation into sustainable, service-anchored revenue streams. For companies that move early on these priorities, 2026 represents not only continued market expansion but an opportunity to redefine leadership in a maturing yet still-innovative instrumentation sector.
For detailed analysis of this topic, please visit the official page: Laser Spectrum Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: HDI Biuret Market to Rise from USD 540.24 Million in 2025 to USD 804.29 Million by 2032 at a 5.85% CAGR, Led by Asia‑Pacific (USD 232.13 Million)
By pmarketresearch, 2026-07-02
Hdi Biuret Market 2026: Strategic Preview — What Every Executive Needs to Know
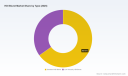
PW Consulting’s latest Hdi Biuret Market report (base year 2025; historical coverage 2020–2025; forecast period 2026–2032) delivers a focused, decision-ready view for executives planning capital, procurement, and product strategies in 2026. The market has evolved from roughly USD 410 million in 2020 to USD 540.24 million in 2025, and our forecast points to continued expansion — reaching an estimated USD 804.29 million by 2032 at a compound annual growth rate (CAGR) of 5.85% over the 2026–2032 horizon. This briefing outlines the strategic implications embedded in the full report, highlights competitive inflection points, and flags the operational and regulatory risks that should be on every 2026 agenda.
Hdi Biuret Market
Why Hdi Biuret Matters Now
Hdi biuret occupies a privileged position in high-durability, aliphatic polyurethane coatings — a segment where performance, weathering resistance, and low yellowing are non‑negotiable. As OEMs and refinish segments push for higher solids, lower VOCs, and better lifecycle footprint, demand for aliphatic polyisocyanates (and Hdi biuret specifically) is increasingly driven by formulation shifts rather than purely end‑market volume growth.
Hdi Biuret Market
- Market momentum: The market’s steady expansion since 2020 signals structural adoption across coatings classes and geographies. The 5.85% projected CAGR reflects both new application uptake (waterborne high‑solids systems, premium automotive and industrial finishes) and productivity-driven replacement cycles in maintenance and transportation coatings.
- Consolidation dynamics: The sector is concentrated — the top three players account for a sizable majority of market share, and the top five exceed four-fifths of the market. That concentration matters for pricing power, contract tenor, and new entrant economics.
- Value chain leverage: HDI biuret’s economics remain sensitive to upstream HDI monomer availability and pricing, regulatory compliance costs, and the availability of alternative crosslinker chemistries. Executives who map these linkages will be better positioned to time capacity investments and commercial negotiations.
What the 2026 Decision-Maker Needs from the Full Report
For C-suite and business unit leaders, the following capabilities are essential in 2026 and are included in the PW Consulting report at an actionable level:
Hdi Biuret Market
- Precise market sizing and validated demand scenarios across the 2026–2032 forecast horizon to underpin capital allocation and contract commitments.
- Commercial benchmarking and supplier scorecards that translate technological differentiation, product grade economics, and supply reliability into negotiation levers.
- Risk matrices that quantify feedstock price sensitivity, regulatory exposure (e.g., REACH compliance, VOC regime impacts), and trade/tariff scenarios.
- Go‑to‑market roadmaps for formulators and distributors, with tactical recommendations for channel segmentation, sample programs, and co‑development partnerships that shorten customer qualification cycles.
- M&A and partnering playbooks oriented to bolt‑on acquisitions, capacity partnerships, and tolling arrangements optimized for current market concentration and projected demand growth.
Competitive Landscape — Who Moves the Needle
The Hdi biuret space is characterized by a small number of global incumbents and a handful of regionally strong producers. The competitive environment combines brand, formulation expertise, and asset footprint. Key strategic players covered in the report include:
- Covestro AG (Leverkusen, Germany) — A premium portfolio player known for weather‑stable, non‑yellowing Desmodur N family products and recent innovation in bio‑content hardeners.
- BASF SE (Ludwigshafen, Germany) — An integrated materials powerhouse with HDI‑based polyisocyanates marketed for transportation coatings and industrial applications; recent capacity additions in Europe underline their strategic intent.
- Wanhua Chemical Group (Yantai, China) — Rapidly scaling HDI and downstream biuret capacity with a cost-competitive position in Asia and growing export reach following recent plant commissioning.
- Vencorex Holding SAS (France) — A specialist supplier focused on refinish and waterborne 2K clearcoat chemistries with long‑term commercial commitments in key end‑markets.
- Evonik, Asahi Kasei, Tosoh, Kowa, Mitsui Chemicals, and Huntsman — Each contributes complementary capabilities from hydrophilic crosslinkers to low‑viscosity, high‑solids products, underscoring that differentiation is now more formulation‑led than purely capacity‑led.
Market concentration metrics are notable: the top three players control approximately 62.5% of the market, and the top five exceed 84%. For buyers, this translates into limited supplier redundancy; for investors, it highlights strategic opportunities for consolidation through targeted M&A or capacity partnerships.
Recent Strategic Moves — Signals for 2026 Planning
- Product innovation: Late‑stage launches focused on bio‑content and high‑solids waterborne hardeners indicate supplier priorities around sustainability and regulatory-driven formulation shifts. Such launches change procurement criteria beyond price — emphasizing lifecycle metrics and formulation performance.
- Capacity investments: Multiple recent and near‑term capacity expansions — including large new HDI installations — increase available feedstock and downstream biuret potential. These moves are accelerating the shift from tight short‑term markets to a more balanced supply picture over a 24–36 month horizon.
- Commercial anchoring: Long‑term supply agreements in waterborne 2K segments demonstrate a trend toward strategic offtake arrangements that de‑risk downstream manufacturers but concentrate supplier commitments.
Regulatory, Trade, and Raw‑Material Dynamics
Three structural externalities will shape 2026 outcomes:
- Regulatory compliance and product stewardship: Hdi and its derivatives are subject to rigorous chemical regulation (e.g., EU REACH). Commercial grades typically control residual monomer below strict thresholds, and compliance processes materially affect time‑to‑market and cost structures for new products.
- VOC regulation acceleration: Regional VOC directives and comparable rules from major agencies are pushing formulators toward high‑solids and waterborne systems; this regulatory push is a primary driver of Hdi biuret adoption in premium coatings categories.
- Upstream feedstock pricing and trade friction: HDI monomer pricing showed marked regional variance in late 2025, influenced by feedstock availability. Tariff discussions and potential tariff reclassification in key markets add another layer of trade risk for importers and exporters. Procurement strategies that incorporate hedging, multi‑sourcing, and local capacity partnerships will materially reduce exposure.
Operational and Commercial Playbook for 2026
Based on our scenario modeling and supplier assessments, PW Consulting recommends executives consider the following prioritized actions for 2026:
- Lock strategic offtake but retain flexibility: Negotiate tiered long‑term agreements that include volume bands and price review mechanisms tied to feedstock indices to hedge both price and availability risk.
- Invest in formulation capability: Differentiate through co‑development arrangements with a limited set of suppliers to secure priority access to new low‑VOC and bio‑content chemistries.
- Map regulatory timelines to product launch windows: Build compliance milestones into product development Gantt charts to avoid late delays from registration or documentation gaps.
- Pursue tactical M&A or JV for capability gaps: Given the high concentration, bolt‑on acquisitions or capacity JVs can be an effective way to secure supply and accelerate market access while preserving margin economics.
- Implement a dynamic procurement dashboard: Combine real‑time HDI feedstock price feeds, supplier utilization rates, and inventory turn KPIs to enable rapid commercial decisions during supply volatility.
What the Full Report Contains (Practical, Executable Elements)
PW Consulting’s full Hdi Biuret Market report goes beyond top‑line numbers to deliver tools executives can act on immediately:
- Granular market sizing by year and scenario, with supplier‑level demand models calibrated to regional end‑market trends (note: detailed segment tables and split percentages are available in the full report).
- Supplier scorecards, asset maps, and capacity timelines with sensitivity analyses.
- Detailed regulatory and compliance checklists by jurisdiction, including registration cost estimates and typical timeframes.
- Procurement and commercial playbooks, sample contract clauses for long‑term supply, and templates for co‑development agreements.
- M&A valuation framework and a prioritized list of acquisition targets and strategic partners based on capability gaps and concentration metrics.
Conclusion — How to Use This Preview in 2026 Planning
This preview is designed to inform boardroom debates and operational plans as companies prepare for a year where supply dynamics, regulatory momentum, and product innovation converge. The market’s steady expansion — from approximately USD 410 million in 2020 to USD 540.24 million in 2025, and toward an estimated USD 804.29 million by 2032 at a 5.85% CAGR — underscores both growing commercial opportunity and increased strategic complexity.
Executives who treat Hdi biuret not as a commodity input but as a lever for differentiation — integrating procurement strategy, formulation partnerships, and regulatory foresight — will gain outsized advantage in 2026. PW Consulting’s full report equips leaders with the granular datasets, supplier intelligence, and executable playbooks necessary to convert that advantage into measurable commercial outcomes.
Next Steps
For decision-makers ready to translate this strategic preview into actionable plans, PW Consulting provides bespoke briefings, supplier diligence services, and scenario planning workshops. Access to the full report — including segment‑level tables, supplier contracts templates, and detailed country/regional risk scores — is available through our research portal.
For detailed analysis of this topic, please visit the official page: Hdi Biuret Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Party Costumes Market to Expand at a 6.2% CAGR Through 2032, New Report Finds
By pmarketresearch, 2026-07-02
Party Costumes Market 2026: Strategic Imperatives from PW Consulting’s Forward-Looking Analysis
Executive summary
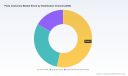
PW Consulting’s latest market research on the Party Costumes industry synthesizes five years of historical performance and a seven-year forecast horizon to deliver an actionable intelligence package for executives making 2026 decisions. Using 2025 as the base year, the global party costumes market demonstrated resilience—growing from a depressed 2020 base to a 2025 market size of approximately US$5.65 billion. Our forecast work projects continued expansion through 2032, reaching roughly US$8.61 billion by the end of the period at a compound annual growth rate (CAGR) of 6.2%.
Party Costumes Market
This release is intended as a strategic “trailer”: it surfaces the analytical themes, decision frameworks, and high-conviction recommendations PW Consulting clients will use to prioritize investments, redesign sourcing and assortment strategies, and size acquisition targets in 2026. Detailed sub-segment datapoints, regional splits, and company-level financials are intentionally reserved for the full report to preserve competitive value and encourage direct engagement with PW Consulting.
Party Costumes Market
What the market trajectory means for 2026 planning
-
From recovery to selective growth: the industry’s recovery since 2020 has translated into a larger and more mature addressable market by 2025. The projected multi-year expansion at ~6.2% CAGR through 2032 signals stable downstream demand driven by continued consumer interest in themed events, year-round celebrations, and expanded use cases (including adult, children’s and pet costumes, rentals, and experiential activations).
Party Costumes Market -
Fragmentation creates strategic openings: market concentration metrics indicate a fragmented competitive landscape, where the largest three and five companies account for a modest share of the total market. This fragmentation creates room for scale plays (horizontal consolidation), margin improvement via SKU rationalization, and differentiation through IP, sustainability, and omnichannel capabilities.
-
Margin pressure persists from trade dynamics: 2025 tariff actions and freight volatility materially affected cost structures across the supply chain—wholesale price increases were observed and consumer price expectations shifted accordingly. Given the industry’s heavy manufacturing footprint in parts of Asia, sourcing agility and tariff scenario planning must be front-and-center in 2026 planning.
Key industry dynamics we expect to shape 2026
-
Sourcing and cost pass-through: Companies that can rapidly reconfigure supplier networks, shorten lead times, or selectively nearshore will gain margin and service advantages. Our scenario models show meaningful P&L sensitivity to unit-cost moves and freight lead times in seasonal peaks.
-
Licensing and IP-led differentiation: Entertainment IP remains a primary demand driver—film- and franchise-tied product lines continue to outperform generic SKUs in velocity and conversion. Partnerships with rights holders, timed to theatrical and streaming release calendars, will be a high-return play for both manufacturers and retailers.
-
Channel evolution: Online retail has solidified as an essential growth channel, but experiential retail (seasonal pop-ups, curated in-store events) remains an effective strategy to capture high-margin, impulse-driven demand. Retailers that combine targeted digital acquisition with short-duration physical presence are consistently improving conversion and basket size.
-
Product innovation and format expansion: The 2026 trade show season highlighted demand for novel formats—movie-themed lines, inflatable costumes, and pet costumes were notable trend areas. Innovators that can rapidly commercialize these concepts with cost-effective BOMs will win shelf and screen share.
-
Sustainability and regulation: Material compliance, labeling accuracy and rising consumer interest in circular options are elevating requirements. Cost-effective sustainable material choices and reusable/rental business models can be points of differentiation rather than pure cost centers.
Competitive landscape — positioning and strategic implications
The market features a mix of global incumbents, regionally dominant retailers, and specialized manufacturers. Key players bring distinct advantages:
-
Rubie’s Costume Company — scale and licensing breadth. As one of the largest costume manufacturers and distributors, Rubie’s scale across licensed and generic lines provides bargaining power with license holders and retail partners. Their global supply chain expertise is a model for competitors managing dual-sourcing strategies.
-
Disguise Inc. — IP focus in children’s wear. Strong entertainment partnerships and product development cadence make Disguise a go-to example for how licensing-led assortments can rapidly capture seasonal demand.
-
Spirit Halloween and Party City — omnichannel and seasonal retail mastery. These retailers demonstrate the commercial value of a hybrid seasonal-store plus year-round digital strategy. Their playbooks for inventory velocity and pop-up economics are examined in the report.
-
Specialized manufacturers and suppliers — Smiffys, Boloparty, Lucida and others. These firms illustrate varied strategic axes: regional brand strength, low-cost manufacturing models, and flexible MOQ offers that appeal to small-to-mid retail chains.
-
Fashion-forward and niche players — Leg Avenue, Roma, Peris Costumes Group. High-margin niches—adult fashion-inspired costumes, theatre and rental archives—offer acquisition targets for companies seeking adjacent diversification.
Our competitive assessment includes capability scorecards, go-to-market archetypes, and a short list of strategic moves (licensing partnerships, JV models, and tuck-in acquisitions) that can materially shift market position in 12–24 months.
What is inside the PW Consulting report — a practitioner's toolkit
-
Robust market sizing and methodology — transparent assumptions, sensitivity tests, and scenario outputs for tariff, freight and consumer-spend shocks.
-
Channel playbooks — tailored strategies for online-first retailers, specialty stores, mass channels, and seasonal pop-up models, including margin archetypes and inventory turn targets.
-
Sourcing and supply chain playbook — supplier scorecards, nearshoring/dual-sourcing scenarios, freight and tariff mitigation tactics, and procurement KPIs.
-
Product and portfolio levers — SKU rationalization frameworks, IP-pricing guides, private-label vs licensed portfolio decision trees, and a short-list of high-potential product innovations for 2026 (e.g., inflatable formats, pet categories, and rental-ready designs).
-
Commercial and pricing toolkit — elasticities by product archetype, promotional optimization calendars aligned to media releases and event windows, and markdown/playbook recommendations to protect margin during post-peak sell-through.
-
M&A and partnership screens — valuation benchmarks, integration risk frameworks, and candidate archetypes for scale, capability and market entry.
-
Risk heatmaps and regulatory monitoring — tariff scenario models, compliance checklists, and recommended governance structures to monitor rapidly shifting trade policies.
Immediate tactical moves for 2026
-
Re-run product assortment using our SKU prioritization engine before committing peak-season production—free up working capital and improve turn.
-
Lock in hedges or alternative freight capacity for peak seasons and prioritize suppliers with proven dual-shore capabilities.
-
Accelerate IP tie-ups timed to media calendars; co-invest in marketing with licensors to shift promotional spend from awareness to conversion.
-
Pilot experiential pop-ups in top DMAs with aggressive A/B testing of assortment and price points to refine online-to-offline conversion playbooks.
-
Validate a rental/resale pilot in select urban markets to capture higher-LTV consumers while addressing sustainability concerns.
Why executives should care — the 2026 decision agenda
Board-level questions for 2026 will increasingly focus on three things: margin resilience in the face of trade volatility, portfolio agility to capture IP-driven surges, and channel orchestration to monetize high-intent shoppers. PW Consulting’s analysis turns these questions into decision-ready answers: prioritized investments, quantified scenarios, and a roadmap for converting market fragmentation into competitive advantage.
Conclusion — action versus observation
The Party Costumes market presents a classic growth-with-disruption opportunity: stable long-term growth at ~6.2% CAGR, ongoing structural change from trade dynamics, and clear levers for differentiation. Companies that act—reshaping sourcing, partnering on IP, and modernizing channel strategies—will materially outperform peers. PW Consulting’s full report contains the proprietary models, granular segment detail, and executable playbooks your leadership team needs to make those 2026 decisions with confidence.
For access to the complete dataset, segment-level analysis, company scorecards, and our interactive scenario models, please contact PW Consulting or visit our report portal to request the full Party Costumes Market 2026 report.
For detailed analysis of this topic, please visit the official page: Party Costumes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Surging Demand to Drive 6.81% CAGR: PW Consulting's 2026–2032 Flat Panel Loudspeaker Market Outlook
By pmarketresearch, 2026-07-02
Flat Panel Loudspeaker Market 2026: Strategic Signals from PW Consulting’s New Market Report
Executive teaser — why this report matters for 2026 decision cycles
PW Consulting’s latest Flat Panel Loudspeaker Market research, with a 2025 base year and a 2026–2032 forecast horizon, delivers the actionable intelligence executives need to set product roadmaps, supply‑chain hedges, and commercial priorities for the next three budget cycles. The market reached approximately USD 529 million in 2025 and is projected to expand to roughly USD 839 million by 2032, implying a compound annual growth rate of 6.81% across the forecast period. This report is designed as a decision tool for C‑suite leaders, product managers, M&A teams and channel strategists who must convert technical trends into predictable revenue and defensible margin improvement in 2026.
Flat Panel Loudspeaker Market
What the report gives you — practical content designed for execution
- Concise market sizing and a seven‑year forecast anchored on verified historicals (2020–2025) and macro scenarios that stress‑test demand drivers and downside risks.
- Investor‑grade competitive landscaping that goes beyond vendor logos to assess technology depth, route‑to‑market, and defensibility for each competitor profile.
- Supply‑chain and regulatory playbooks that model tariff scenarios, component lead‑time shocks and redesign cost impacts on time‑to‑market and margin profiles.
- Commercial blueprints: channel mix optimization, pricing sensitivity frameworks, partner selection matrices, and pilot program templates tied to expected ROI and payback windows.
- Product and technology roadmaps that prioritize features, materials, and platform investments based on buyer personas and real‑world tradeoffs.
- M&A and partnership screening criteria with a short list of archetypal targets, integration risks, and synergy capture models sized to your portfolio ambitions.
Market dynamics that will shape 2026 plays
Flat panel loudspeakers are evolving from niche audiophile and specialist AV solutions into a differentiated component class across consumer, professional and automotive channels. The projected mid‑single‑digit CAGR through 2032 reflects the confluence of three structural forces: expanding use cases for low‑profile and directional audio, higher customer expectations for intelligibility in noisy environments, and continued premiumization in home and commercial installations.
Flat Panel Loudspeaker Market
Yet growth is non‑linear across themes — innovation in transducer architectures (bending‑wave, distributed‑mode and planar magnetic approaches) often creates asymmetric value for specific use cases (e.g., reverberant venues, immersive consumer experiences, and zoned commercial audio). The report’s scenario models quantify how those adoption curves interact with price erosion, channel mix shifts, and regional policy shocks so that leaders can prioritize investments where payback is fastest.
Flat Panel Loudspeaker Market
Competitive outlook — differentiated capabilities mapped to strategy
Rather than treating suppliers as interchangeable, the report evaluates companies on six dimensions: core transducer IP, product breadth, systems capability (including subwoofer and amplification pairing), channel and install ecosystem, manufacturing flexibility, and go‑to‑market velocity. Key vendor archetypes include:
- FlatPanel Audio (San Jose) — A DML specialist that targets professional AV and reverberant environments. Their DML500 family and complementary subwoofer/amplifier pairings position them as a systems supplier for architects and integrators where room reflections are the primary design constraint.
- Magnepan (White Bear Lake) — A classic high‑end planar‑magnetic brand focused on audiophile and bespoke multi‑channel installations. Their strength is brand equity and craftsmanship, which supports premium pricing but limits scale without new distribution constructs.
- Flatt Speakers (Phoenix) — Emphasizes rugged, weather‑resistant planar transducers for intelligibility‑critical installations. Their thin, high‑SPL solutions are optimized for projects demanding low install footprint and reliability.
- Tectonic Audio Labs (Woodinville) — Advances in bending‑wave and Balanced Mode Radiator (BMR) tech make them a cross‑segment innovator, with components and full systems suitable for professional, consumer and automotive programs.
- Brown Innovations (USA) — Focused on directional ceiling/zone audio with market applications in museums, exhibits and commercial spaces where highly directed sound reduces spill and improves accessibility.
- Wisdom Audio (Reno) — Operates in the high‑performance home theater and custom install niche with multi‑octave planar designs built for fidelity and system integration into premium installations.
Our competitive heat maps highlight that the market is moderately consolidated: the top three suppliers capture a meaningful share of market value while the top five account for a majority of recognized commercial momentum. The report helps incumbents and challengers alike to choose whether to compete on system integration, channel reach, or pure‑play transducer IP and where to deploy scarce capex to generate differentiated performance.
Supply‑chain and regulatory hazards — modeling for resilience
Two external shocks dominate near‑term operational risk: tariff/regulatory headwinds and semiconductor component volatility. Recent tariff developments have created a “tariff inversion” where certain China‑sourced components attract substantially higher duties than comparable finished imports; this dynamic reshapes where final assembly occurs and whether vertical integration of subcomponents becomes economically viable for certain product families.
On the component side, persistent semiconductor lead‑time volatility — specifically for DSP and Class‑D amplifier ICs — has driven lead times beyond 26 weeks in 2025 and 2026. Our models quantify the cost of redesign and delay, showing typical platform redesigns can cost between USD 50,000 and USD 200,000 and postpone commercialization by up to six months. For manufacturers with narrow product windows, those delays translate directly into opportunity loss; for OEMs, supplier selection and multi‑sourcing strategies are decisive.
Strategic recommendations for 2026 decision cycles
- Adopt a two‑track product strategy: (1) defend existing revenue with cost‑in‑place improvements and supplier dual‑sourcing; (2) selectively invest in new flat panel platforms for differentiated use cases (directional audio, automotive integration, and integrated systems) with staged R&D milestones tied to gating metrics.
- Protect margins through tariff mitigation: re‑assess bill‑of‑materials localization thresholds, consider partial assembly in lower‑tariff jurisdictions, and evaluate tariff‑pass‑through models for large B2B customers.
- Make supply‑chain flexibility a KPI: require lead‑time SLAs for critical ICs, negotiate allocation clauses, and maintain a strategic buffer of key components where redesign costs and revenue timing are material.
- Deploy go‑to‑market pilots that prove zone‑based audio ROI: structured pilots for museums, retail and hospitality can accelerate adoption, generate case studies, and establish reference accounts for integrators.
- Prioritize partnerships over insourced scale for premium tech: for companies lacking planar or bending‑wave IP, licensing or white‑label arrangements can fast‑track product entry while preserving capital.
- Use M&A selectively to fill capability gaps, not market share for its own sake: targets should bring either proprietary transducer IP, route‑to‑market in a new vertical, or meaningful cost advantaged manufacturing capacity.
What leaders will be judged on in 2026
Executives who convert the market’s steady growth into sustained competitive advantage will be those who combine pragmatic supply‑chain design with a disciplined product playbook. Tactical measures — shorter supplier qualification cycles, phased product launches, and integrated channel incentive programs — will separate winners from laggards. Equally important is using the right metrics: share of install wallet, project-level margin analysis, and the time‑to‑reference account for new audio architectures.
Why PW Consulting’s report is more than a forecast
Beyond headline forecasts, this release equips decision‑makers with executable artifacts: vendor‑level SWOTs, scenario P&L templates, prioritized product feature sets, go‑to‑market test kits, and a short list of high‑probability M&A targets. The content is deliberately cross‑functional — blending acoustical engineering implications with commercial and regulatory levers so that R&D, supply chain, sales and corporate development can act in lockstep.
Next steps — where to find the full intelligence
This article is a condensed briefing intended to expose the strategic underpinnings of the flat panel loudspeaker opportunity while directing program owners to the complete dataset and playbooks. Core segmented splits, granular regional and application breakdowns, and the full competitive scorecards are reserved for the report’s subscribers and purchasers. For teams building 2026 budgets, the full PW Consulting report provides the validated inputs and downloadable templates needed to operationalize the recommendations in this release.
Contact PW Consulting to arrange a briefing, obtain the full report, or commission a tailored workshop that maps these findings to your product portfolio and P&L targets for 2026.
For detailed analysis of this topic, please visit the official page: Flat Panel Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Powered Electric Motorcycle & Scooter Market Poised to Reach USD 60.92 Billion by 2032, Growing at a 12.15% CAGR
By pmarketresearch, 2026-07-02
Low Powered Electric Motorcycle and Scooter Market — Strategic Outlook for 2026
PW Consulting’s latest market research — the Low Powered Electric Motorcycle and Scooter Market Report (base year 2025; forecast 2026–2032) — reframes how executives should approach the next decision cycle. After a sustained recovery between 2020 and 2025, the global market reached USD 27,300 Million in 2025 and is projected to accelerate to approximately USD 31,530 Million in 2026, continuing on a trajectory to exceed USD 60,900 Million by 2032 under a 12.15% compound annual growth rate (forecast 2026–2032). These macro trends are not academic: they translate to concrete investment thresholds, supplier commitments, and go-to-market choices that will determine who wins urban mobility share in the second half of the decade.
Low Powered Electric Motorcycle And Scooter Market
What corporate leaders need from this analysis in 2026
- Clarity on pace and shape of demand growth to size manufacturing and inventory commitments without overexposure to short-cycle volatility.
- A pragmatic framework for battery strategy and raw-material exposure in a market where battery-pack prices and critical mineral dynamics are rapidly evolving.
- Actionable competitive insight that differentiates platform plays (high-volume affordable scooters) from premium, software-led and swapping-ecosystem strategies.
- A compliance-first checklist aligned to tightening safety and certification regimes that materially affect product engineering and time-to-market.
PW Consulting’s report is designed as a decision tool for CEOs, heads of strategy, product and procurement officers — not just a forecast. The sections below summarize the strategic takeaways from our analysis while deliberately preserving the proprietary, segment-level datasets that underpin these conclusions. For full datasets and drill-downs by battery chemistry, product architecture and commercial use cases, please consult the report landing page.
Low Powered Electric Motorcycle And Scooter Market
Macro dynamics shaping 2026 strategy
- Demand momentum and scale economics: After an accelerated recovery across 2020–2025, the market’s near-term step-up in 2026 requires firms to balance scale-up speed with flexible manufacturing footprints. The market’s projected doubling trajectory through 2032 implies that platform and supply-chain investments made in 2026 will compound over the next six years.
- Battery-cost deflation and supply-side oversupply: Global analysis shows a meaningful fall in lithium-ion battery pack prices in 2024 with continued downward pressure into 2025–2026. Lithium prices fell nearly 20% in 2024. That creates windows for margin recovery, price-led share gains, or investment in higher-density chemistries — but it also raises strategic questions on inventory exposure and long-term supply contracts.
- Regulatory tightening and safety certification: Governments and standards bodies are increasing safety and classification requirements for electric two-wheelers. Compliance points to note include vehicle safety requirements under existing federal motor vehicle safety standards and product-level certification frameworks such as UL outlines that apply to battery systems. In practical terms, product design cycles and validation budgets must be reweighted to reflect these regulatory headwinds.
- Concentration vs. fragmentation: Market concentration is moderate — the top three players capture a substantial but not dominant share, and the top five still leave more than half the market accessible to challengers. That structure favors both scale seekers and nimble innovators with distinctive value propositions.
Competitive landscape: players, positions, and vectors of competition
The low-powered electric motorcycle and scooter market is a multi-modal battleground where manufacturing scale, channel strength, battery strategy and software ecosystems matter in different mixes across players.
Low Powered Electric Motorcycle And Scooter Market
- Scale-focused incumbents (manufacturing-led): Large-volume manufacturers continue to anchor the lower-cost segments through integrated supply chains and distribution networks. Their play is volume-led, optimized for price elasticity among first-time EV adopters.
- Tech-ecosystem challengers: Companies that combine vehicle hardware with IoT, connectivity and swapping ecosystems are moving beyond product-sales into recurring revenue models. Their moat is platform-led engagement and services.
- Legacy OEMs and premium incumbents: Established motorcycle OEMs and heritage scooter brands bring distribution credibility and brand equity; their strategic challenge is converting ICE loyalty into EV adoption while managing margin compression.
- New entrants and regional champions: Aggressive local players and digitally native OEMs are using fast-follower tactics, local sourcing advantages and go-to-market innovations to capture urban mobility niches.
Representative firm-level dynamics observed in our competitive benchmarking:
- Manufacturers with extensive production capacity remain best placed to execute aggressive price-volume plays and to absorb short-term cost fluctuations.
- IoT-enabled OEMs and swapping-ecosystem providers are monetizing software and energy services; their strategic focus is on retention, not just unit sales.
- Established OEMs and premium brands are leveraging distribution and service networks to accelerate customer trust and higher ASP propositions.
- Recent market events (for example, a major manufacturer unveiling a new low-powered scooter for 2026 and a strategic summit spotlighting full-size lithium products) underscore that product pipeline and partnership announcements will continue to be salient competitive levers.
Strategic playbook for 2026
Based on scenario-sensitivity modeling, supplier stress tests and competitor benchmarking, PW Consulting recommends five priority moves for organisations committing capital in 2026:
- Adopt a flexible manufacturing posture: Hybrid capacity models (core owned capacity + scalable contract manufacturing) reduce overhang risk while enabling rapid response to localized demand surges.
- Define a clear battery strategy aligned to margin objectives: Use short-term price declines to renegotiate supplier terms, secure conditional offtake agreements, and pilot mixed-chemistry portfolios to match product-tier needs. Consider strategic partnerships with swapping-platform players where viable.
- Invest selectively in software & services: Connectivity, OTA updates, subscription energy services and financing can materially increase lifetime value. Prioritize features that improve utilization and reduce warranty costs.
- Operationalize regulatory readiness: Embed safety certification and compliance checkpoints into product roadmaps; allocate validation budget-upfront to avoid costly redesigns and delayed launches.
- Pursue focused inorganic moves: Acquisition targets that deliver complementary software, rapid market access, or battery/charging IP are high-impact and should be evaluated against a strict return horizon tied to 2028 profitability inflection points.
What the report delivers (practical deliverables for 2026 planning)
Our full report is engineered for execution and includes:
- Proprietary full-market historical series (2020–2025) and a point-by-point forecast (2026–2032) with scenario bounds.
- Supplier ecosystem maps and critical-supplier risk profiles, including raw-material exposure analyses and cost-sensitivity models.
- Competitive playbooks — benchmarking feature sets, channel strategies, and unit-economics for representative OEM archetypes.
- Regulatory impact matrix and certification pathway playbooks (including vehicle safety and battery-system compliance pathways).
- Actionable go-to-market templates: pricing stress tests, launch-runway models, and partnership scorecards for battery swapping, ride-hailing and delivery fleet programs.
- M&A heatmaps and 24-month integration templates for acquirers seeking rapid scale or capability fills.
To preserve the value of these deliverables for paying subscribers and to keep this release focused, we have intentionally withheld granular segment-level splits and proprietary unit-level datasets from this press release. These datasets include the detailed battery-type economics, product-type volume-to-revenue mappings, and region-by-application microforecasts that are critical inputs for operational decisions.
How to use this intelligence in Q1–Q4 2026 planning
- Re-run capital allocation decisions using our scenario outputs to stress-test factories and supplier contracts under both accelerated and delayed-adoption paths.
- Re-negotiate battery and critical-mineral exposure with suppliers using our short-term deflation analysis as leverage for performance-linked pricing.
- Prioritize compliance investments by mapping product launches to regulatory timelines; use our certification playbook to compress time-to-market without compromising safety.
- Shortlist strategic partners for swapping infrastructure, fleet services and embedded-finance solutions using our partner scorecards.
Conclusion: why 2026 is a strategic inflection point
The interplay of accelerating unit demand, falling battery-pack costs and tightening safety standards creates both opportunity and execution risk in 2026. Companies that enter the year with a disciplined battery-sourcing stance, flexible manufacturing arrangements, and a clear services monetization plan will be positioned to capture disproportionate value as unit volumes scale. Conversely, firms that underinvest in certification or overcommit to fixed manufacturing without supply-side hedges will face avoidable margin pressure.
PW Consulting’s Low Powered Electric Motorcycle and Scooter Market Report combines macro forecasts — including a 2025 market base of USD 27,300 Million, a 2026 inflection point near USD 31,530 Million, and a 12.15% CAGR outlook through 2032 — with practical playbooks and executable templates. For the full, segmented datasets, competitor scorecards, and our proprietary scenario models, visit the report page to access the complete research package. This press release intentionally previews our strategic conclusions while withholding the granular segment-level datapoints that underpin operational decisions — because real execution requires the full dataset.
For detailed analysis of this topic, please visit the official page: Low Powered Electric Motorcycle And Scooter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Semiconductor Focus Ring Market to Expand at 8.22% CAGR Through 2032, Led by Silicon Focus Rings and Asia‑Pacific Demand
By pmarketresearch, 2026-07-02
Semiconductor Focus Ring Market: Strategic Imperatives for 2026
PW Consulting’s latest Semiconductor Focus Ring Market report (base year 2025; forecast 2026–2032) is designed as a practical playbook for decision-makers preparing for the next phase of capital deployment, supplier negotiations, and process qualification. The market has demonstrated sustained expansion over the past half-decade and is forecast to continue growing at a compound annual growth rate of 8.22% across the 2026–2032 horizon. That growth trajectory—driven by device miniaturization, multilayer stack complexity and the accelerating transition of etch architectures—creates both upside opportunity and supplier-risk exposure for OEMs, foundries and equipment manufacturers in 2026.
Semiconductor Focus Ring Market
Why this report matters for 2026 decision cycles
-
Actionable foresight timed to procurement and qualification calendars: 2026 is a year when many chipmakers and OEMs will finalize long-term supply agreements and tool upgrades. The report maps demand and supply scenarios across the upcoming investment cycle so procurement teams can align contracts with expected process technology ramps.
Semiconductor Focus Ring Market -
Quantified growth expectations to inform CapEx and inventory strategy: PW Consulting provides an end-to-end forecast for the focus ring market across the 2026–2032 period. That forecast is calibrated to semiconductor device roadmaps and etch-process trends, enabling CFOs and supply chain leaders to size buffers and capital commitments against a defensible baseline.
Semiconductor Focus Ring Market -
Risk-adjusted supplier playbooks: given ongoing raw material constraints and export-control volatility, the report offers playbooks for supplier diversification, qualification acceleration and joint development, tailored to both tier-1 chipmakers and smaller IDM/EPCM partners.
What the report contains — practical, field-ready intelligence
-
Proven demand forecasting models: multi-scenario projections that combine fab capacity additions, process mix shifts and material adoption curves to produce spend and unit forecasts through 2032.
-
Supplier performance and concentration analysis: objective measures of market concentration and supplier capabilities to support sourcing strategies and M&A diligence (includes CR3 and CR5 benchmarks to show competitive intensity at an industry level).
-
Material selection framework: decision matrices that weigh lifetime, particle risk, thermal performance and total cost of ownership (TCO) for silicon, silicon carbide (SiC), quartz and hybrid solutions—set up so engineering teams can rapidly map trade-offs for a given etch recipe.
-
Qualification acceleration templates: test plans, qualification gates and KPI thresholds that reduce time-to-production while preserving process yield and device performance.
-
Supply-chain stress tests and contingency playbooks: scenario analyses for lead-time shocks, export-control disruptions and material-price spikes, with prescriptive mitigations such as dual-sourcing tiers, strategic safety-stock, and localized manufacturing options.
-
Procurement negotiation guides: term-sheet templates, indexation clauses for raw-material pass-through, and collaborative innovation frameworks to align supplier investments with fab roadmaps.
Market dynamics shaping supplier and buyer strategies in 2026
-
Shift to more durable materials: device scaling and multilayer architectures are increasing the performance bar for focus rings. The market is seeing a sustained migration toward more durable carbide-based solutions in high-performance etch regimes, while silicon and quartz variants remain relevant for other process windows. This transition changes lifetime economics and qualification lead times for buyers.
-
Raw-material and lead-time pressure: high-purity SiC and specialty ceramics face extended lead times—often measured in months—driven by capacity constraints and geopolitical frictions. Procurement will need to treat these materials as strategic long-lead items in 2026 planning.
-
Regulatory and trade headwinds: export-control regimes implemented through 2024–2025, and subsequent trade policy moves, have re-shaped cross-border sourcing calculus. Buyers must bake regulatory scenario planning into sourcing and qualification workflows.
-
Consolidation and supplier concentration: the focus ring supply base shows notable concentration at the top tier, which affects price elasticity, qualification timelines and co-development options. Companies operating in this market should map the competitive structure and identify where negotiation leverage exists versus where strategic partnerships are required.
Competitive landscape — strategic profiles and implications
The competitive field combines global ceramic specialists, CVD SiC pioneers, silicon merchants and vertically-integrated materials houses. PW Consulting’s study profiles incumbents and emerging suppliers across capability, geography, manufacturing process and innovation roadmaps to help buyers select partners that align with technical and commercial priorities.
-
Materials and process leaders: companies with advanced CVD SiC capability and single-crystal silicon know-how are positioned to serve the highest-demand etch regimes. These suppliers bring long lifecycle performance advantages but often require longer qualification cycles and higher entry cost for collaboration.
-
Scale and cost-competitive producers: manufacturers using polycrystalline silicon or optimized ceramic processing can deliver competitive price points and faster ramp to volume; they are attractive as second-source suppliers or for process windows where lifetime demands are less severe.
-
Regional and niche players: smaller, geographically focused firms offer agility and faster customization, a useful option for fabs seeking short qualification turnarounds or unique form-factor requirements.
Representative companies covered in the report include global materials and ceramics houses, specialist CVD SiC providers and high-volume producers. Notable examples are CoorsTek, Morgan Technical Ceramics, Tokai Carbon Co., Ltd., and established equipment-component specialists such as Ferrotec and Kyocera. Emerging and regionally strong suppliers profiled include firms from China, Korea and Taiwan that are scaling both production and technical capabilities.
Recent industry developments underscore the dynamics at play: for example, a qualification and supply win announced in February 2025 illustrates how nitride-free polycrystalline silicon focus rings have moved into mass production for a major North American chipmaker—an event that signals both technological maturation and shifting buyer preferences (source: THE ELEC, February 2025).
Strategic recommendations for 2026
-
Classify process windows by criticality: prioritize single-sourcing only for truly non-substitutable, high-performance etch regimes. For other windows, qualify multiple materials to limit risk.
-
Adopt staged qualification with parallel testing: run coexistence qualification tracks for new materials (SiC variants and advanced ceramics) while maintaining legacy part stocks to avoid production interruptions.
-
Secure long-lead materials proactively: treat high-purity SiC and specialty ceramics as strategic inputs and negotiate multi-year commitments with flexible delivery options to mitigate 6–8 month lead-time exposures.
-
Design regulatory-resilient supply chains: build alternative sourcing footprints and legal-compliance playbooks to respond to export-control shifts without derailing fab schedules.
-
Leverage supplier co-development: investment-sharing on material/process innovations reduces time-to-market and aligns supplier roadmaps with fab needs—particularly valuable where consolidated suppliers hold significant IP.
-
Use concentration metrics for negotiation: measure CR and similar benchmarks to determine where collaborative partnerships are necessary and where competitive procurement can drive price discovery.
How PW Consulting’s report supports your 2026 execution plan
-
Decision-grade forecasts: a transparent, auditable projection engine links fab node transitions to focus-ring demand, enabling CapEx and inventory decisions with clear sensitivity bands.
-
Supplier scorecards and qualification templates: reduce time and cost to qualifying alternative materials and suppliers with ready-to-deploy templates designed for engineering and procurement teams.
-
Regulatory impact scenarios: modular playbooks that quantify the operational and sourcing effects of export controls and raw material policy moves so legal and sourcing teams can act before disruption occurs.
-
Implementation roadmaps: step-by-step guidance for integrating new material classes into etch processes, from lab validation to fab-scale rollouts, with embedded KPI dashboards for yield and contamination risk.
Next steps for executives and buying teams
As companies set budgets and programs for 2026, the choices made now about material qualification, supplier commitments and inventory posture will materially affect both unit cost and operational resiliency across the fab ecosystem. PW Consulting’s Semiconductor Focus Ring Market report presents the analytical foundations and operational tools needed to make those choices defensibly. The report intentionally presents depth—market models, supplier maps, and scenario playbooks—while reserving segment-level data tables and proprietary supplier-share analytics for the full report and dataset.
For procurement leaders, technology officers and strategy teams preparing 2026 plans: leverage the report’s scenario planning modules, supplier playbooks and material decision frameworks to reduce time-to-qualification and to construct resilient, cost-efficient sourcing architectures that can withstand material shortages and regulatory swings.
Contact PW Consulting to access the full dataset, supplier-share matrices and downloadable procurement templates that accompany this report. Our analysts stand ready to run bespoke scenarios calibrated to your process mix and sourcing constraints to support 2026 execution.
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 12.25% CAGR for Global Marine Electric Motor Market Through 2032
By pmarketresearch, 2026-07-02
Marine Electric Motor Market: Strategic Imperatives for 2026 — PW Consulting Insights
Executive summary
PW Consulting’s new Marine Electric Motor Market report delivers a decision-focused view for executives planning capital allocation, product roadmaps, and supply-chain strategies in 2026. The market has moved from early adoption toward broad commercial validation: by our base year (2025) the global marine electric motor market reached approximately USD 7.3 billion and is forecast to grow at a compound annual growth rate of 12.25% across 2026–2032, with our modelling pointing to a market size in excess of USD 16 billion by 2032. That trajectory — and the regulatory inflection points that underpin it — create near-term windows for strategic moves that will determine winners and losers over the next investment cycle.
Marine Electric Motor Market
Why 2026 is a strategic hinge year
-
Regulatory acceleration: IMO decisions through 2024–2025 culminated in standards entering into force from 2027. These rules materially change fuel-cost calculations and ship-level compliance timelines. Organisations that align procurement, retrofit, and newbuild programs in 2026 will be best placed to capture demand created by regulatory-driven fleet upgrades.
Marine Electric Motor Market -
Industrialisation of technology: Improvements in power density, cooling, and integration with power electronics have moved electric propulsion from niche to mainstream for a wider set of vessel types. New motor topologies and lighter permanent-magnet designs are reshaping system-level trade-offs between weight, efficiency and cost.
Marine Electric Motor Market -
Supply-side stress points: Critical-material concentration and copper market tightness have transitioned from theoretical risk to procurement reality in 2026; these factors will determine lead times, margins and the viability of several product strategies.
Market trajectory: what the numbers imply (strategic read)
The topline growth rate and forecast magnitude mean two practical things for decision-makers. First, scale matters: a market growing at a double-digit rate amplifies first-mover advantages for manufacturers who can secure capacity, certification, and service networks this year. Second, the pace of adoption compresses payback windows for integrated solutions (motors + drives + energy storage + digital optimisation). Our modelling shows total addressable demand expanding materially across vessel types and mission profiles, but the distribution of that demand is uneven — a point we treat as commercially sensitive in this release and cover in full in the report.
Key market dynamics shaping 2026 choices
-
Policy and compliance: The IMO’s 2025 resolutions introduce global fuel standards and emissions pricing that take effect in the latter half of the decade. This creates a staged timetable for owners and yards to electrify or hybridise propulsion systems — 2026 is the year to finalise retrofit standards, certification routes, and contractual obligations aligned to classification societies’ updated SEEMP guidance.
-
Materials and input risk: Permanent magnet motors offer high power density but expose manufacturers to rare-earth supply concentration. Concurrently, copper demand for electrification is tightening. Procurement strategies that address secured allocations, hedging, recycling and alternative motor architectures will materially reduce execution risk.
-
Technology evolution: The market is seeing rapid product introductions — from high-power permanent-magnet machines to compact, high-efficiency outboards for small craft. Advances in control electronics, thermal management, and modular drive systems are enabling platforms that scale from leisure boats to large commercial vessels.
-
Commercialisation and service economics: Owners increasingly value total lifecycle operating cost and serviceability. Business models that combine product sales with energy-optimisation services, performance guarantees and modular upgrade paths will capture higher-margin recurring revenue.
Competitive landscape: how incumbents and challengers are positioning
The market structure shows a moderate level of concentration: leading firms hold meaningful share but there remains room for innovative entrants and specialised suppliers. Competitive dynamics can be grouped into three strategic archetypes:
-
Systems integrators with scale (e.g., incumbent industrial players): These firms emphasise integrated propulsion systems, power electronics, and certification expertise. Their strengths are multi-megawatt product portfolios, relationships with shipyards and offshore operators, and established global service footprints. Their challenge is speed: aligning legacy manufacturing to rapid iteration cycles.
-
Specialist OEMs and tier innovators: Companies focused on high-efficiency outboards, pod drives and compact inboards are commercialising disruptive architectures for recreational and specialised commercial craft. Their advantage is agility and product-market fit; their constraint is scaling manufacturing and after-sales service internationally.
-
Scale-capable industrial motor manufacturers: Traditional motor makers are leveraging industrial expertise to enter marine-specific segments, often by partnering with electronics and systems providers. Execution hinges on marine certification and harsh-environment validation.
Recent trade-show activity and product roadmaps illustrate these shifts. Several companies showcased novel stator and magnet designs designed for higher power-to-weight ratios, while a number of OEMs previewed next-generation outboards and hybrid concepts. For strategic buyers and partners, these demonstrations represent both sourcing opportunities and benchmarking references.
What this means for corporate strategy in 2026
For manufacturers, shipowners, yards and investors, 2026 is the year to convert strategic intent into executable plans. Our recommendations — prioritised by impact and time-sensitivity — are practical and actionable.
-
Secure critical inputs and diversify supply: Sign multi-year agreements and co-investment arrangements for magnets and copper, and evaluate recycling partnerships and magnet-substitution R&D to reduce exposure to single-source suppliers.
-
Align product roadmaps to certification timelines: Finalise design-for-class and retrofit kits this year to be ready for elevated demand when IMO rules and SEEMP updates hit full effect. Invest in third-party validation sooner rather than later.
-
Adopt modular, upgradeable architectures: Design motors and drives that allow incremental upgrades (power electronics, cooling, controls) to extend platform lifecycles and protect customer investments.
-
Prioritise service and energy optimisation offers: Build telemetry, digital twins and outcome-based contracts into product launches to monetise operational efficiency gains across a vessel’s life.
-
Accelerate partnerships and bolt-on M&A: Where speed to market matters, acquire or partner with specialised suppliers (power-electronics, pod-drive specialists, battery integrators) to compress development cycles and obtain validated technology stacks.
-
Run pilots that reflect real-world operational cycles: Move beyond lab demonstrations: field-prove systems across representative routes, duty-cycles and environmental conditions this year to derisk certification and commercial rollouts.
Implications for specific stakeholders
-
Shipowners and operators: Use 2026 to lock conversion-capex schedules and negotiate supplier service-level agreements that include performance guarantees and upgrade rights tied to regulatory milestones.
-
OEMs and suppliers: Prioritise product families that allow cross-segment reuse (e.g., common drive electronics across multiple power classes) to speed certification and lower unit costs as demand scales.
-
Investors and private equity: Focus on platforms with defensible after-sales revenue models and clear pathways to scale; pay attention to suppliers with supply-chain control over magnets, power electronics or assembly capacity.
What PW Consulting’s report delivers (practical contents)
The full report is designed as a pragmatic playbook for 2026 execution. It includes:
-
Topline market sizing and forecast scenarios (base, accelerated and constrained), with sensitivity analysis around material-price and regulatory timing.
-
Competitive vendor profiles and an actionable heatmap of capability gaps across systems, service, and certification.
-
Technology roadmap and TCO models for common vessel archetypes, enabling comparative procurement decisions.
-
Supply-chain risk matrix with mitigation levers (contracting templates, alternative chemistries, recycling pathways).
-
Go-to-market playbooks for OEMs and service providers, including channel and partnership templates and pilot program designs.
-
M&A and partnership screening tool to prioritise targets that accelerate scale, capability or geographic reach.
To preserve competitive leverage for our clients, this press release deliberately omits granular segmentation tables and certain proprietary model outputs. The full dataset, including detailed regional and application splits and granular vendor benchmarking, is accessible via the report landing page.
Competitive highlights and recent developments
Incumbent industrial players continue to leverage system integration strengths; specialist OEMs and scale-ups are pushing rapid innovation in the small-to-medium craft segment. Notable recent activity includes product showcases at major marine and tech expos, updated multi-megawatt catalogues from established suppliers, and new motor-topology demonstrations from specialised designers. These validate our view that 2026 will be a year of both consolidation and focused product launches.
Bottom line: what to do in 2026
Decisive actions in 2026 — securing supply, validating modular product platforms, closing pilot programs, and aligning contractual and certification timelines — will determine which organisations capture the expanding addressable market. PW Consulting’s Marine Electric Motor Market report equips leaders with the frameworks and scenario-based tools needed to prioritise investments and to execute with confidence.
Next steps
Organisations preparing procurement, R&D and M&A plans for 2026 should mobilise a cross-functional team to: (1) review TCO scenarios under multiple material and regulatory timelines, (2) shortlist supplier partnership options against the supply-risk matrix, and (3) design field pilots that can be scaled rapidly. For access to the full report, dataset and the vendor benchmarking appendix, please visit PW Consulting’s report page.
For detailed analysis of this topic, please visit the official page: Marine Electric Motor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com