

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Surging Demand to Drive 6.81% CAGR: PW Consulting's 2026–2032 Flat Panel Loudspeaker Market Outlook

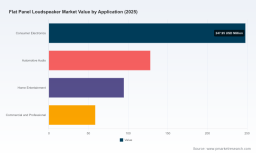
Flat Panel Loudspeaker Market 2026: Strategic Signals from PW Consulting’s New Market Report
Executive teaser — why this report matters for 2026 decision cycles
PW Consulting’s latest Flat Panel Loudspeaker Market research, with a 2025 base year and a 2026–2032 forecast horizon, delivers the actionable intelligence executives need to set product roadmaps, supply‑chain hedges, and commercial priorities for the next three budget cycles. The market reached approximately USD 529 million in 2025 and is projected to expand to roughly USD 839 million by 2032, implying a compound annual growth rate of 6.81% across the forecast period. This report is designed as a decision tool for C‑suite leaders, product managers, M&A teams and channel strategists who must convert technical trends into predictable revenue and defensible margin improvement in 2026.
Flat Panel Loudspeaker Market
What the report gives you — practical content designed for execution
- Concise market sizing and a seven‑year forecast anchored on verified historicals (2020–2025) and macro scenarios that stress‑test demand drivers and downside risks.
- Investor‑grade competitive landscaping that goes beyond vendor logos to assess technology depth, route‑to‑market, and defensibility for each competitor profile.
- Supply‑chain and regulatory playbooks that model tariff scenarios, component lead‑time shocks and redesign cost impacts on time‑to‑market and margin profiles.
- Commercial blueprints: channel mix optimization, pricing sensitivity frameworks, partner selection matrices, and pilot program templates tied to expected ROI and payback windows.
- Product and technology roadmaps that prioritize features, materials, and platform investments based on buyer personas and real‑world tradeoffs.
- M&A and partnership screening criteria with a short list of archetypal targets, integration risks, and synergy capture models sized to your portfolio ambitions.
Market dynamics that will shape 2026 plays
Flat panel loudspeakers are evolving from niche audiophile and specialist AV solutions into a differentiated component class across consumer, professional and automotive channels. The projected mid‑single‑digit CAGR through 2032 reflects the confluence of three structural forces: expanding use cases for low‑profile and directional audio, higher customer expectations for intelligibility in noisy environments, and continued premiumization in home and commercial installations.
Flat Panel Loudspeaker Market
Yet growth is non‑linear across themes — innovation in transducer architectures (bending‑wave, distributed‑mode and planar magnetic approaches) often creates asymmetric value for specific use cases (e.g., reverberant venues, immersive consumer experiences, and zoned commercial audio). The report’s scenario models quantify how those adoption curves interact with price erosion, channel mix shifts, and regional policy shocks so that leaders can prioritize investments where payback is fastest.
Flat Panel Loudspeaker Market
Competitive outlook — differentiated capabilities mapped to strategy
Rather than treating suppliers as interchangeable, the report evaluates companies on six dimensions: core transducer IP, product breadth, systems capability (including subwoofer and amplification pairing), channel and install ecosystem, manufacturing flexibility, and go‑to‑market velocity. Key vendor archetypes include:
- FlatPanel Audio (San Jose) — A DML specialist that targets professional AV and reverberant environments. Their DML500 family and complementary subwoofer/amplifier pairings position them as a systems supplier for architects and integrators where room reflections are the primary design constraint.
- Magnepan (White Bear Lake) — A classic high‑end planar‑magnetic brand focused on audiophile and bespoke multi‑channel installations. Their strength is brand equity and craftsmanship, which supports premium pricing but limits scale without new distribution constructs.
- Flatt Speakers (Phoenix) — Emphasizes rugged, weather‑resistant planar transducers for intelligibility‑critical installations. Their thin, high‑SPL solutions are optimized for projects demanding low install footprint and reliability.
- Tectonic Audio Labs (Woodinville) — Advances in bending‑wave and Balanced Mode Radiator (BMR) tech make them a cross‑segment innovator, with components and full systems suitable for professional, consumer and automotive programs.
- Brown Innovations (USA) — Focused on directional ceiling/zone audio with market applications in museums, exhibits and commercial spaces where highly directed sound reduces spill and improves accessibility.
- Wisdom Audio (Reno) — Operates in the high‑performance home theater and custom install niche with multi‑octave planar designs built for fidelity and system integration into premium installations.
Our competitive heat maps highlight that the market is moderately consolidated: the top three suppliers capture a meaningful share of market value while the top five account for a majority of recognized commercial momentum. The report helps incumbents and challengers alike to choose whether to compete on system integration, channel reach, or pure‑play transducer IP and where to deploy scarce capex to generate differentiated performance.
Supply‑chain and regulatory hazards — modeling for resilience
Two external shocks dominate near‑term operational risk: tariff/regulatory headwinds and semiconductor component volatility. Recent tariff developments have created a “tariff inversion” where certain China‑sourced components attract substantially higher duties than comparable finished imports; this dynamic reshapes where final assembly occurs and whether vertical integration of subcomponents becomes economically viable for certain product families.
On the component side, persistent semiconductor lead‑time volatility — specifically for DSP and Class‑D amplifier ICs — has driven lead times beyond 26 weeks in 2025 and 2026. Our models quantify the cost of redesign and delay, showing typical platform redesigns can cost between USD 50,000 and USD 200,000 and postpone commercialization by up to six months. For manufacturers with narrow product windows, those delays translate directly into opportunity loss; for OEMs, supplier selection and multi‑sourcing strategies are decisive.
Strategic recommendations for 2026 decision cycles
- Adopt a two‑track product strategy: (1) defend existing revenue with cost‑in‑place improvements and supplier dual‑sourcing; (2) selectively invest in new flat panel platforms for differentiated use cases (directional audio, automotive integration, and integrated systems) with staged R&D milestones tied to gating metrics.
- Protect margins through tariff mitigation: re‑assess bill‑of‑materials localization thresholds, consider partial assembly in lower‑tariff jurisdictions, and evaluate tariff‑pass‑through models for large B2B customers.
- Make supply‑chain flexibility a KPI: require lead‑time SLAs for critical ICs, negotiate allocation clauses, and maintain a strategic buffer of key components where redesign costs and revenue timing are material.
- Deploy go‑to‑market pilots that prove zone‑based audio ROI: structured pilots for museums, retail and hospitality can accelerate adoption, generate case studies, and establish reference accounts for integrators.
- Prioritize partnerships over insourced scale for premium tech: for companies lacking planar or bending‑wave IP, licensing or white‑label arrangements can fast‑track product entry while preserving capital.
- Use M&A selectively to fill capability gaps, not market share for its own sake: targets should bring either proprietary transducer IP, route‑to‑market in a new vertical, or meaningful cost advantaged manufacturing capacity.
What leaders will be judged on in 2026
Executives who convert the market’s steady growth into sustained competitive advantage will be those who combine pragmatic supply‑chain design with a disciplined product playbook. Tactical measures — shorter supplier qualification cycles, phased product launches, and integrated channel incentive programs — will separate winners from laggards. Equally important is using the right metrics: share of install wallet, project-level margin analysis, and the time‑to‑reference account for new audio architectures.
Why PW Consulting’s report is more than a forecast
Beyond headline forecasts, this release equips decision‑makers with executable artifacts: vendor‑level SWOTs, scenario P&L templates, prioritized product feature sets, go‑to‑market test kits, and a short list of high‑probability M&A targets. The content is deliberately cross‑functional — blending acoustical engineering implications with commercial and regulatory levers so that R&D, supply chain, sales and corporate development can act in lockstep.
Next steps — where to find the full intelligence
This article is a condensed briefing intended to expose the strategic underpinnings of the flat panel loudspeaker opportunity while directing program owners to the complete dataset and playbooks. Core segmented splits, granular regional and application breakdowns, and the full competitive scorecards are reserved for the report’s subscribers and purchasers. For teams building 2026 budgets, the full PW Consulting report provides the validated inputs and downloadable templates needed to operationalize the recommendations in this release.
Contact PW Consulting to arrange a briefing, obtain the full report, or commission a tailored workshop that maps these findings to your product portfolio and P&L targets for 2026.
For detailed analysis of this topic, please visit the official page: Flat Panel Loudspeaker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com