

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Semiconductor Focus Ring Market to Expand at 8.22% CAGR Through 2032, Led by Silicon Focus Rings and Asia‑Pacific Demand

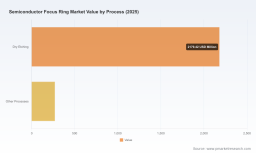
Semiconductor Focus Ring Market: Strategic Imperatives for 2026
PW Consulting’s latest Semiconductor Focus Ring Market report (base year 2025; forecast 2026–2032) is designed as a practical playbook for decision-makers preparing for the next phase of capital deployment, supplier negotiations, and process qualification. The market has demonstrated sustained expansion over the past half-decade and is forecast to continue growing at a compound annual growth rate of 8.22% across the 2026–2032 horizon. That growth trajectory—driven by device miniaturization, multilayer stack complexity and the accelerating transition of etch architectures—creates both upside opportunity and supplier-risk exposure for OEMs, foundries and equipment manufacturers in 2026.
Semiconductor Focus Ring Market
Why this report matters for 2026 decision cycles
-
Actionable foresight timed to procurement and qualification calendars: 2026 is a year when many chipmakers and OEMs will finalize long-term supply agreements and tool upgrades. The report maps demand and supply scenarios across the upcoming investment cycle so procurement teams can align contracts with expected process technology ramps.
Semiconductor Focus Ring Market -
Quantified growth expectations to inform CapEx and inventory strategy: PW Consulting provides an end-to-end forecast for the focus ring market across the 2026–2032 period. That forecast is calibrated to semiconductor device roadmaps and etch-process trends, enabling CFOs and supply chain leaders to size buffers and capital commitments against a defensible baseline.
Semiconductor Focus Ring Market -
Risk-adjusted supplier playbooks: given ongoing raw material constraints and export-control volatility, the report offers playbooks for supplier diversification, qualification acceleration and joint development, tailored to both tier-1 chipmakers and smaller IDM/EPCM partners.
What the report contains — practical, field-ready intelligence
-
Proven demand forecasting models: multi-scenario projections that combine fab capacity additions, process mix shifts and material adoption curves to produce spend and unit forecasts through 2032.
-
Supplier performance and concentration analysis: objective measures of market concentration and supplier capabilities to support sourcing strategies and M&A diligence (includes CR3 and CR5 benchmarks to show competitive intensity at an industry level).
-
Material selection framework: decision matrices that weigh lifetime, particle risk, thermal performance and total cost of ownership (TCO) for silicon, silicon carbide (SiC), quartz and hybrid solutions—set up so engineering teams can rapidly map trade-offs for a given etch recipe.
-
Qualification acceleration templates: test plans, qualification gates and KPI thresholds that reduce time-to-production while preserving process yield and device performance.
-
Supply-chain stress tests and contingency playbooks: scenario analyses for lead-time shocks, export-control disruptions and material-price spikes, with prescriptive mitigations such as dual-sourcing tiers, strategic safety-stock, and localized manufacturing options.
-
Procurement negotiation guides: term-sheet templates, indexation clauses for raw-material pass-through, and collaborative innovation frameworks to align supplier investments with fab roadmaps.
Market dynamics shaping supplier and buyer strategies in 2026
-
Shift to more durable materials: device scaling and multilayer architectures are increasing the performance bar for focus rings. The market is seeing a sustained migration toward more durable carbide-based solutions in high-performance etch regimes, while silicon and quartz variants remain relevant for other process windows. This transition changes lifetime economics and qualification lead times for buyers.
-
Raw-material and lead-time pressure: high-purity SiC and specialty ceramics face extended lead times—often measured in months—driven by capacity constraints and geopolitical frictions. Procurement will need to treat these materials as strategic long-lead items in 2026 planning.
-
Regulatory and trade headwinds: export-control regimes implemented through 2024–2025, and subsequent trade policy moves, have re-shaped cross-border sourcing calculus. Buyers must bake regulatory scenario planning into sourcing and qualification workflows.
-
Consolidation and supplier concentration: the focus ring supply base shows notable concentration at the top tier, which affects price elasticity, qualification timelines and co-development options. Companies operating in this market should map the competitive structure and identify where negotiation leverage exists versus where strategic partnerships are required.
Competitive landscape — strategic profiles and implications
The competitive field combines global ceramic specialists, CVD SiC pioneers, silicon merchants and vertically-integrated materials houses. PW Consulting’s study profiles incumbents and emerging suppliers across capability, geography, manufacturing process and innovation roadmaps to help buyers select partners that align with technical and commercial priorities.
-
Materials and process leaders: companies with advanced CVD SiC capability and single-crystal silicon know-how are positioned to serve the highest-demand etch regimes. These suppliers bring long lifecycle performance advantages but often require longer qualification cycles and higher entry cost for collaboration.
-
Scale and cost-competitive producers: manufacturers using polycrystalline silicon or optimized ceramic processing can deliver competitive price points and faster ramp to volume; they are attractive as second-source suppliers or for process windows where lifetime demands are less severe.
-
Regional and niche players: smaller, geographically focused firms offer agility and faster customization, a useful option for fabs seeking short qualification turnarounds or unique form-factor requirements.
Representative companies covered in the report include global materials and ceramics houses, specialist CVD SiC providers and high-volume producers. Notable examples are CoorsTek, Morgan Technical Ceramics, Tokai Carbon Co., Ltd., and established equipment-component specialists such as Ferrotec and Kyocera. Emerging and regionally strong suppliers profiled include firms from China, Korea and Taiwan that are scaling both production and technical capabilities.
Recent industry developments underscore the dynamics at play: for example, a qualification and supply win announced in February 2025 illustrates how nitride-free polycrystalline silicon focus rings have moved into mass production for a major North American chipmaker—an event that signals both technological maturation and shifting buyer preferences (source: THE ELEC, February 2025).
Strategic recommendations for 2026
-
Classify process windows by criticality: prioritize single-sourcing only for truly non-substitutable, high-performance etch regimes. For other windows, qualify multiple materials to limit risk.
-
Adopt staged qualification with parallel testing: run coexistence qualification tracks for new materials (SiC variants and advanced ceramics) while maintaining legacy part stocks to avoid production interruptions.
-
Secure long-lead materials proactively: treat high-purity SiC and specialty ceramics as strategic inputs and negotiate multi-year commitments with flexible delivery options to mitigate 6–8 month lead-time exposures.
-
Design regulatory-resilient supply chains: build alternative sourcing footprints and legal-compliance playbooks to respond to export-control shifts without derailing fab schedules.
-
Leverage supplier co-development: investment-sharing on material/process innovations reduces time-to-market and aligns supplier roadmaps with fab needs—particularly valuable where consolidated suppliers hold significant IP.
-
Use concentration metrics for negotiation: measure CR and similar benchmarks to determine where collaborative partnerships are necessary and where competitive procurement can drive price discovery.
How PW Consulting’s report supports your 2026 execution plan
-
Decision-grade forecasts: a transparent, auditable projection engine links fab node transitions to focus-ring demand, enabling CapEx and inventory decisions with clear sensitivity bands.
-
Supplier scorecards and qualification templates: reduce time and cost to qualifying alternative materials and suppliers with ready-to-deploy templates designed for engineering and procurement teams.
-
Regulatory impact scenarios: modular playbooks that quantify the operational and sourcing effects of export controls and raw material policy moves so legal and sourcing teams can act before disruption occurs.
-
Implementation roadmaps: step-by-step guidance for integrating new material classes into etch processes, from lab validation to fab-scale rollouts, with embedded KPI dashboards for yield and contamination risk.
Next steps for executives and buying teams
As companies set budgets and programs for 2026, the choices made now about material qualification, supplier commitments and inventory posture will materially affect both unit cost and operational resiliency across the fab ecosystem. PW Consulting’s Semiconductor Focus Ring Market report presents the analytical foundations and operational tools needed to make those choices defensibly. The report intentionally presents depth—market models, supplier maps, and scenario playbooks—while reserving segment-level data tables and proprietary supplier-share analytics for the full report and dataset.
For procurement leaders, technology officers and strategy teams preparing 2026 plans: leverage the report’s scenario planning modules, supplier playbooks and material decision frameworks to reduce time-to-qualification and to construct resilient, cost-efficient sourcing architectures that can withstand material shortages and regulatory swings.
Contact PW Consulting to access the full dataset, supplier-share matrices and downloadable procurement templates that accompany this report. Our analysts stand ready to run bespoke scenarios calibrated to your process mix and sourcing constraints to support 2026 execution.
For detailed analysis of this topic, please visit the official page: Semiconductor Focus Ring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com