

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Laser Spectrum Analyzer Market Poised to Hit USD 700.1 Million by 2032, Advancing at a 7.42% CAGR

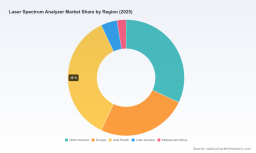
Laser Spectrum Analyzer Market: Strategic Imperatives for 2026 — PW Consulting Preview
PW Consulting’s latest market study on the Laser Spectrum Analyzer market delivers an evidence-based briefing designed to shape strategic choices in 2026. Anchored on a 2025 base year and a forward-looking forecast to 2032, this analysis translates measurable market dynamics into actionable options for product leaders, supply-chain executives, corporate development teams, and technical R&D managers. Below we summarize the report’s central findings, the practical content packed into the full deliverable, and prioritized recommendations to navigate competitive, regulatory, and supply-side disruptions.
Laser Spectrum Analyzer Market
Market trajectory at a glance
The laser spectrum analyzer market is on a steady expansion path: after a 2023–2025 period of measured growth, the market base in 2025 stands as the report’s anchor. From 2026 onward the market is projected to expand at a compound annual growth rate (CAGR) of 7.42%, with the total market approaching the high hundreds of millions of USD by 2032. This combination of resilient growth and accelerating investment in photonics instrumentation underscores a clear opportunity window for firms that can align product performance, supply security, and go-to-market agility.
Laser Spectrum Analyzer Market
What the full report contains — practical, deal-ready intelligence
- Robust market sizing and forecast model: Transparent methodology (historical 2020–2025 baseline; forecast 2026–2032) with scenario sensitivity to price erosion, component lead-time shocks, and accelerated adoption in telecommunications and scientific applications.
- Technology and product roadmaps: Comparative performance matrices for scanning Michelson interferometers, Fabry–Pérot devices, grating-based spectrometers, and static interferometers — including resolution, dynamic range, footprint, and test throughput trade-offs.
- Buy-side decision frameworks: Procurement checklists and cost-of-ownership models tailored to lab, manufacturing, and field-test environments, enabling procurement teams to quantify TCO and measurement risk across supplier options.
- Supply-chain and regulatory risk maps: Component-level sensitivity analysis, alternative sourcing strategies, and mitigation playbooks for emerging export controls and raw-material constraints.
- Competitive scouting and M&A watchlist: Qualitative profiles and capability gaps for leading incumbents and fast-growing specialists, together with an M&A scoring model to prioritize targets by technology fit, geographic reach, and integration risk.
- Commercial playbooks: Pricing strategies, channel design, and bundling approaches (hardware + firmware + services) to protect margin as instruments become more modular and software-driven.
Competitive landscape — what to watch in 2026
The market shows a moderate level of concentration among top vendors, reflecting established incumbents with deep optical-measurement portfolios alongside agile specialists targeting niches like VCSEL characterization, integrated photonics, and PXIe form factors. Leading instrument houses continue to compete on three axes: resolution and measurement fidelity, form-factor and integration flexibility, and verticalized product ecosystems that embed tunable sources and automated analysis.
Laser Spectrum Analyzer Market
- Bristol Instruments (US) — Strengths: Michelson interferometer implementations combined with FFT-based analysis provide high resolution and integrated wavelength metering for advanced laser labs. Strategic posture: pursue deeper integrations with laser-control electronics and stabilization systems to extend value beyond raw measurement.
- Thorlabs (US) — Strengths: Broad OSA portfolio focused on high resolution and dual-detection designs for both fiber-coupled and free-space testing. Strategic posture: leverage distribution and optical-component scale to bundle instruments into rapid-deployment lab kits for research and telecom testbeds.
- Yokogawa (Japan) — Strengths: Multi-decade heritage and wide wavelength coverage make it a default supplier for many telecom and industrial customers. Strategic posture: defend premium positioning by accelerating software upgrades and services for cloud-enabled measurement management.
- Anritsu and EXFO (Japan/Canada) — Strengths: Telecom-focused platforms and intelligent feature sets (OSNR, channel power, SMSR). Strategic posture: capitalize on network modernization cycles and expand lab-to-manufacturing workflows with factory-automation integrations.
- Keysight and Shimadzu — Strengths: Cross-domain test ecosystems and newly launched product variants that extend coverage into communications bands and high-speed measurement. Strategic posture: bundle ecosystem advantages (signal sources, analysis software) and highlight validated workflows for semiconductor and photonics fabs.
- Quantifi Photonics, APEX, HighFinesse, Optoplex, O/E Land, CNI — Strengths: Niche specialization in form factors (PXIe, benchtop), sub-micron resolution, integrated tunable lasers, and cost-competitive spectrometers. Strategic posture: scale selective partnerships with larger OEMs for distribution, and position IP-rich modules as acquisition targets for incumbents seeking capability in compact, high-resolution platforms.
Recent product and market movements to monitor
- Shimadzu’s 2026 roll-out of an InGaAs-type laser spectrum analyzer targets broader optical-communications coverage while emphasizing high-speed measurement — a signal that established instrumentation vendors are prioritizing communications-band performance and market reach expansion.
- Bristol Instruments’ 2024 introductions (multi-laser PID controllers and wavelength meters) reveal a persistent strategy: marry measurement with control to create closed-loop offerings that increase switching costs for customers.
- Smaller innovators showcased modular and integrated-source solutions (e.g., demonstrations combining novel light sources with PXIe analyzers), illustrating a trend to shrink benchtop footprints while raising throughput for component test.
Industry dynamics that will shape 2026 decisions
- Regulatory pressure: U.S. export controls affecting advanced equipment (with updates influencing supply chains through early 2026) require firms to embed regulatory contingency in procurement and corporate-development playbooks. Those that anticipate licensing timelines and technology carve-outs will have a competitive edge in cross-border deals.
- Component and material risk: Geopolitical tensions and semiconductor supply-chain disruptions are already lengthening lead times and inflating costs for critical optical components. Executives must quantify single-supplier exposures and validate dual-sourcing or buffer-inventory strategies for subassemblies.
- Helium and utility constraints: Ongoing regional supply shocks, partly driven by geopolitical conflict and trade restrictions, threaten process-critical gases used upstream in some optical component manufacturing. Buyers should stress-test suppliers for alternative process maturity and material-substitution roadmaps.
- Convergence of instrumentation and software: Competitive differentiation is shifting toward integrated measurement ecosystems—hardware plus advanced analytics, automation, and lifecycle services—creating recurring revenue opportunities but also increasing the importance of software security and calibration ecosystems.
Actionable strategic playbook for 2026
- Prioritize modular product architectures: Design next-generation instruments to accept pluggable detectors and tunable sources. This preserves upgrade paths and shortens sales cycles with large customers seeking platform consolidation.
- Mitigate supply risk now: Initiate dual-sourcing for critical components, secure multi-year contracts for process gases where possible, and invest in inventory hedges for long-lead optics and detectors.
- Embed regulatory intelligence: Assign a cross-functional export-control and trade-compliance task force for any M&A or distribution deal with Asia–North America linkages; pre-clearance and contingency clauses will speed time-to-revenue in restricted geographies.
- Commercialize software and services: Build calibration-as-a-service and cloud-enabled analytics offerings to convert one-time instrument sales into sticky, subscription-like revenue streams that also enhance customer retention.
- Use M&A selectively: Target smaller, IP-rich specialists that bring unique detector technologies, integrated tunable sources, or compact form factors. Use the report’s M&A scoring model to rank targets by technical fit, margin accretion potential, and integration complexity.
- Segment go-to-market by buyer-risk tolerance: Offer tiered product bundles for research labs (performance-first), manufacturing floors (throughput and automation), and field-test (ruggedness and portability). Align channel incentives to minimize inventory risk and accelerate adoption.
Why PW Consulting’s report matters for 2026
Decision-makers entering 2026 face a market where instrument capabilities and commercial models are evolving simultaneously. PW Consulting’s study converts raw market momentum (a mid-single-digit to high-single-digit CAGR through 2032) into prioritized strategic choices: where to invest in R&D, which supply-chain risks to remediate first, how to price and bundle instruments, and which potential acquisition targets will most rapidly extend capability or market reach.
We intentionally preserve detailed segment-level breakdowns, proprietary supplier scores, and the full dataset behind our model for the full report. Those granular figures are essential for transaction diligence, regional go-to-market planning, and product-roadmap prioritization—and are available through the PW Consulting report portal for clients who require deal-ready analytics.
Next steps
- Download the complete Laser Spectrum Analyzer Market report for the full datasets, regional and application-level projections, and the M&A watchlist.
- Schedule a strategy workshop with PW Consulting to translate the report into a tailored 90-day roadmap (product, supply chain, and corporate development).
- Request a brief on regulatory contingencies tailored to your geographic footprint and supplier network to quantify time-to-market impacts for targeted product launches in 2026.
PW Consulting’s Laser Spectrum Analyzer Market preview is designed to inform high-stakes decisions in 2026. It identifies where growth will concentrate, what operational risks to prioritize, and how to convert measurement innovation into sustainable, service-anchored revenue streams. For companies that move early on these priorities, 2026 represents not only continued market expansion but an opportunity to redefine leadership in a maturing yet still-innovative instrumentation sector.
For detailed analysis of this topic, please visit the official page: Laser Spectrum Analyzer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com