

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Low Salted Sodium Hypochlorite Market to Rise from USD 648.5 Million in 2025 to USD 930.29 Million by 2032 at a 5.29% CAGR
By pmarketresearch, 2026-07-06
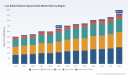
Low Salted Sodium Hypochlorite Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s lead strategic advisor and industry analyst, I present a concise, decision-focused preview of our latest market study on Low Salted Sodium Hypochlorite (LSSH). This “trailer” is designed to arm senior executives, procurement officers, and technology strategists with the high-level signals that will matter in 2026 — while reserving the granular maps and segment-level metrics for the full report. The LSSH market has entered a phase of steady, structurally driven expansion; our modelling, which uses 2025 as the base year and spans 2026–2032, shows a mid-single-digit compound annual growth rate (CAGR) and clear inflection points tied to purity, logistics, and on-site generation adoption.
Low Salted Sodium Hypochlorite Market
Why this market matters now
-
Purity and performance are becoming procurement criteria, not just price drivers. End-users in municipal water treatment, food & beverage, and critical industrial applications are prioritizing low-impurity chemistries to reduce by-product formation, minimize equipment wear, and extend effective dosing windows.
Low Salted Sodium Hypochlorite Market -
Supply-side sophistication is rising. Producers that combine multistage processing (salt removal and trace-metal filtration) with validated stewardship and handling protocols are capturing premium positions in buyer evaluations.
Low Salted Sodium Hypochlorite Market -
Operational models are fragmenting: bulk centralized supply competes with localized, on-site generation technologies. This bifurcation changes CAPEX/OPEX calculus for buyers and reshapes supplier engagement strategies.
Market trajectory and concentration — what to expect in 2026
Our base-year analysis (2025) and forecast horizon (2026–2032) show a clear growth path supported by demand-side shifts and incremental product innovation. The market exhibits a measured level of supplier concentration: the top-tier competitors collectively represent a meaningful share of industry revenue, leaving room for regional specialists and technology-driven entrants to capture niche advantages. For executives planning supplier rationalization or strategic sourcing in 2026, this implies both opportunity and caution: negotiating leverage exists but so does the risk of supplier capacity constraints for specialized low-impurity grades.
Key macro parameters that underpin our scenario planning:
-
Base-year anchoring and forward modelling across a seven-year forecast window (2026–2032) that captures both near-term operational decisions and medium-term capital allocation choices.
-
Mid-single-digit CAGR, reflecting steady adoption across municipal and industrial channels and incremental replacement of legacy chemistries where impurity control yields measurable operational savings.
What the full report delivers (practical, executable intelligence)
The full PW Consulting report is structured to move teams from insight to action. Highlights include:
-
Validated market model (historical 2020–2025; base year 2025) with scenarios that stress-test demand sensitivity to price, regulatory changes, and on-site generation penetration.
-
Supplier dossiers with plant footprints, product positioning, purity and handling claims, and a readiness checklist for qualification audits — tailored to support procurement RFIs and RFPs.
-
Decision-playbooks for water utilities and industrial users: when to trial high-strength low-salt products, how to quantify life-cycle savings (dosing efficiency, reduced chlorate/perchlorate formation, extended shelf life), and how to structure pilot-to-scale programs.
-
Operational guidance for handling, storage, and risk mitigation — including transport logistics, emergency response templates, and inventory strategies that minimize degradation-related losses.
-
Regulatory and standards matrix across major jurisdictions, highlighting certification practices (e.g., potable water chemistry approvals) and practical steps to document compliance during supplier qualification.
-
Supply chain risk mapping and mitigation options: dual-sourcing strategies, contract design (volume-flex, quality rebates), and investment thresholds for on-site generation where appropriate.
Competitive landscape — headings you can act on
The competitive environment is a mix of integrated chlor-alkali majors, specialized formulators, and global specialty-chemicals players. Our report profiles leading names and evaluates them across product purity claims, concentration capabilities, geographic reach, and commercial practices.
-
Kuehne Company — A private chlor-alkali producer with concentrated low-salt formulations marketed for stability and municipal reliability. Their positioning emphasizes purity and long-term application performance.
-
HASA Inc. — A market-moving specialty supplier known for premium, high-strength low-salt grades. Recent field trials by HASA demonstrated substantial usage reductions and more consistent residual control versus standard-strength products; these operational outcomes are central to total-cost-of-ownership arguments in water utilities.
-
Olin Corporation — An integrated player offering super-concentrated, proprietary low-salt hypochlorite grades, together with updated stewardship and handling guidance. Olin’s scale and product stewardship documentation make it a key counterparty for large-volume contracts.
-
Shin-Etsu Chemical — A producer focused on certified low-impurity grades that meet potable water association standards; strong relevance for regulated public water supply systems and certified industrial processes.
-
Kaneka Corporation — A specialty chemicals manufacturer with branded low-salt hypochlorite solutions tailored for public water and bleaching applications, emphasizing low-bromate/chlorate profiles.
Each supplier profile in the full report includes: product specifications (purity corridors and concentration ranges), claimed shelf-life and handling constraints, known field performance anecdotes, and a supplier risk/opportunity score to aid sourcing decisions.
Recent, actionable developments to watch in 2026
-
Field validation of higher-concentration, low-salt products has moved from pilot to documented performance. Notably, a mid-2025 trial showed a meaningful reduction in usage volumes and improved performance stability at a wastewater treatment plant — a proof point many municipalities are now using to justify pilot investments.
-
Large suppliers are codifying stewardship practices and technical handling documentation for super-concentrated low-salt products, reducing buyer uncertainty around safety and logistics.
-
On-site generation systems continue to advance as an alternative operating model. Their economics improve when transport costs, safety restrictions, or storage constraints are significant; however, they require a distinct investment and maintenance capability that not all users will embrace in the short term.
Strategic implications for 2026 decision-makers
For executives preparing budgets and procurement strategies for 2026, our analysis supports a handful of high-leverage moves:
-
Shift pilots from technical evaluation to financial validation. Run side-by-side dosing and operations trials that capture not only chlorine residual performance but also dosing volume, chemical degradation, equipment maintenance intervals, and total cost of ownership. Recent field data suggest that validated high-strength low-salt grades can lower usage volumes and stabilize operations — a metric that should be quantified locally.
-
Reframe supplier selection around purity risk and stewardship documentation. Require supplier-submitted handling and product stewardship manuals as part of RFPs; this materially reduces onboarding friction for high-concentration products.
-
Model the trade-offs between centralized supply and on-site generation. In many cases a hybrid approach — strategic bulk supply with on-site generation backup at critical nodes — optimizes resilience and cost. Our scenario tools in the full report quantify break-even thresholds for capitalized on-site systems versus contracted supply.
-
Institute a supply-concentration watch. While market concentration leaves room for negotiation, the specialized nature of low-impurity products creates pockets of supplier-specific risk. Build contract clauses that protect buyers (quality guarantees, remediation pathways, and volume-flex terms).
-
Prioritize regulatory match: where potable water certifications or low-impurity specifications are mandated, choose suppliers with documented certifications and independent test data to expedite compliance and approvals.
How PW Consulting supports your 2026 playbook
PW Consulting combines market modelling, supplier intelligence, and operational playbooks to accelerate procurement and technology decisions. The full LSSH report delivers the detailed inputs you need to:
-
Construct supplier scorecards and run tender scenarios that include purity-driven premiums.
-
Quantify pilot economics and project payback for switching to high-strength low-salt formulations or investing in on-site generation.
-
Design contract language and stewardship requirements that reduce transition risk and ensure continuity of service.
We intentionally limit this preview to strategic signals and select supplier insights to preserve the actionable, segment-level intelligence in the full report. If your 2026 plan includes supplier requalification, pilot roll-outs, or capital allocation for generation technology, the detailed scenario outputs, supplier dossiers, and operational templates in the full PW Consulting study will be essential.
Next steps
-
For procurement teams: request the supplier dossier package and stewardship checklist to start RFP revisions.
-
For operations leaders: download the pilot design template to capture dosing and lifecycle performance metrics in your next season.
-
For strategy and M&A teams: access the concentration and scenario modules to identify acquisition targets and partnership opportunities within the specialty LSSH value chain.
PW Consulting’s Low Salted Sodium Hypochlorite Market report is modelled on a 2025 base year, covering historical trends back to 2020 and providing scenario-based forecasts through 2032. It integrates verified field evidence, supplier stewardship documentation, and technology assessments to help you make lower-risk, higher-return decisions in 2026. Request the full report to obtain the complete datasets, supplier scorecards, and executable templates referenced here.
For detailed analysis of this topic, please visit the official page: Low Salted Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Primary Cell Media Market Poised for 9.25% CAGR Through 2032, Signaling Robust Growth
By pmarketresearch, 2026-07-06
Primary Cell Media Market 2026: Strategic Imperatives from PW Consulting’s New Market Research
Executive summary
As companies prepare strategic roadmaps for 2026, PW Consulting’s latest Primary Cell Media Market research delivers a concise, action-ready synthesis of the forces reshaping this vital life‑science input. The global market, which we benchmarked to a 2025 base year, shows robust momentum through our forecast window (2026–2032) at a compound annual growth rate (CAGR) of 9.25%. Our model projects material expansion in aggregate market value over the early 2026–2032 period, driven by accelerated demand across drug discovery, regenerative medicine, and translational research workflows.
Primary Cell Media Market
Why this report matters for 2026 decision-makers
-
Timing: The market’s structural inflection in 2026 creates both windowed opportunities and heightened execution risk — making near-term strategic choices disproportionately important for long-term positioning.
Primary Cell Media Market -
Signal-to-noise: Suppliers and end users face an increasingly fragmented technical landscape (formulation chemistries, serum alternatives, tissue‑specific factor mixes), and clear, comparative intelligence is required to prioritize technical investments and procurement strategies.
Primary Cell Media Market -
Portfolio alignment: R&D and commercial leaders must reconcile product roadmaps, scaling plans, and raw-material strategies with evolving customer expectations for consistency, regulatory traceability, and cost-to-quality trade-offs.
Market trajectory at a glance
Anchored on an exhaustive historical base (2020–2025) and our detailed scenario analysis for 2026–2032, the market is set to expand meaningfully in nominal terms. This expansion is not uniform: technological substitution, shifting customer preferences for chemically defined and serum-free systems, and the maturation of regenerative medicine pipelines will reshape product priorities. Our modelling incorporates macro adoption curves for novel formulations, expected procurement patterns of key end-users, and plausible supply‑chain shocks to produce probabilistic revenue pathways through 2032.
What the report contains — operational insights you can act on
PW Consulting’s report is purposely practical. We organized findings to support three immediate use cases: strategy, commercial execution, and supply‑chain resilience.
-
Strategy workshops: Playbooks for product portfolio prioritization, including criteria to decide between niche, tissue‑specific media versus broadly applicable, scalable formulations.
-
Go‑to‑market frameworks: Segmented buyer personas, procurement decision trees, and templates for channel and distributor selection to accelerate market access.
-
Supply‑chain diagnostics: Heatmaps of raw‑material sensitivity, contract‑manufacturing (CMO) readiness assessments, and a supplier‑risk scoring tool to inform hedging and vertical‑integration decisions.
-
Commercial modelling assets: Discounted cash flow (DCF) templates, pricing elasticity analyses, and high‑granularity scenarios to stress-test investment cases.
-
Regulatory and quality playbook: Practical guidance for aligning R&D and quality systems to expectations for consistency in amino acid, vitamin, and salt composition, and for managing transitions to low‑serum or serum‑free regimes.
Competitive landscape — who matters and why
The Primary Cell Media market exhibits moderate concentration dynamics: the top three players capture a meaningful share of market value, and the top five together represent a clear leadership stratum. This concentration indicates both scale benefits (R&D, validated supply chains, regulatory know‑how) and margin pressure points for smaller innovators competing on niche performance or cost.
Key incumbents include multinational life‑science and specialty media manufacturers with distinct strategic strengths:
-
Thermo Fisher Scientific — A broad portfolio under established consumer brands, offering specialized growth kits and tissue‑directed formulations. Thermo Fisher’s scale and distribution remain a decisive advantage for customers seeking global consistency and validated workflows.
-
Merck KGaA (MilliporeSigma) — Known for integrated reagent systems and ready‑to‑use kits that appeal to labs prioritizing reproducibility and supplier accountability across discovery pipelines.
-
Lonza Group — Leverages deep expertise in both research and bioprocessing contexts, positioning itself to capture opportunities where small‑scale R&D intersects with later‑stage manufacturing needs.
-
Corning Incorporated — Combines media offerings with consumables and surface technologies, supporting adopters who prioritize platform compatibility for adherent primary cells.
-
Specialized players (e.g., PromoCell, FUJIFILM Irvine Scientific, STEMCELL Technologies) — These vendors emphasize tissue‑specific or chemically defined formulations and often lead on rapid iteration and customer co‑development projects.
Our competitive analysis maps these capabilities against buyer priorities (validation, cost, supply security, technical performance) to highlight realistic routes for challengers to gain share — through specialization, strategic partnerships, or targeted M&A.
Supply chain and raw‑material considerations
Primary cell media formulations rely on a combination of basal salts, amino acids, vitamins, and targeted supplements (growth factors, cytokines), plus a growing set of serum alternatives and plant‑derived hydrolysates. Consistency in raw‑material composition is non‑negotiable for fastidious primary cells, which places a premium on supplier traceability and batch‑level analytics.
For 2026 planning, we recommend three immediate actions:
-
Establish raw‑material dual‑sourcing for key inputs and evolve contractual clauses to secure priority allocation in times of tight supply.
-
Invest in inbound analytical capability to detect lot‑to‑lot variability early and reduce downstream experiment failures.
-
Pursue supplier partnerships for co‑development of defined supplements to de‑risk reliance on complex biological reagents.
Regulatory and quality dynamics
Although most primary cell media products are marketed for research use, market participants increasingly face buyer expectations aligned with good laboratory practice (GLP) and traceability standards. Consistency in amino acid and salt composition, validated documentation for serum alternatives, and clear statements on use restrictions are all becoming table stakes. Our report provides a regulatory checklist and sample specification templates to accelerate compliance planning without diverting R&D capacity.
Go‑to‑market and partnership plays for 2026
We identify three pragmatic commercial plays that are actionable within a 12–18 month horizon:
-
Platform bundling: Combine media with consumables, surface treatments, or assay kits to create sticky offerings that raise switching costs for end users.
-
Co‑development agreements with translational labs: Use pilot partnerships to validate tissue‑specific formulations and generate published case studies that shorten sales cycles.
-
Manufacturing scale and cost optimization: For manufacturers, investing in modular production lines for defined media can reduce time‑to‑scale and improve margin resilience.
Scenario planning and investment priorities
Our multi‑scenario modelling highlights three plausible 2026 outcomes — a conservative base, an accelerated adoption case driven by regenerative‑medicine commercialization, and a downside scenario that assumes episodic raw‑material disruption. For each outcome, PW Consulting prescribes a prioritized investment queue ranging from defensive steps (quality systems, dual sourcing) to offensive plays (new formulation launches, strategic M&A). These recommendations are accompanied by bespoke financial templates for rapid validation against internal hurdle rates.
How PW Consulting supports execution
Beyond the report, PW Consulting offers hands‑on support to translate insights into deliverables: product roadmaps, channel partner selection, supplier negotiations, and M&A diligence. Our advisory engagement model is modular — from a two‑week strategy sprint to a multi‑quarter implementation program integrating commercial, regulatory, and manufacturing workstreams.
Invitation — access the full dataset and tools
This press release is a strategic preview: rich in actionable direction yet intentionally restrained in disclosing core sub‑segment metrics and granular regional or application splits. For executives preparing 2026 budgets and operational plans, the full report includes proprietary sub‑segment models, downloadable scenario calculators, supplier heatmaps, and validated buyer personas that are essential for confident decision‑making.
Contact PW Consulting to request the full Primary Cell Media Market report and accompanying decision‑support toolkit. Access to the complete dataset will enable precise revenue forecasting, product prioritization, and competitive positioning — the level of detail required to convert 2026 uncertainty into competitive advantage.
For detailed analysis of this topic, please visit the official page: Primary Cell Media Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bluetooth Audio IC Market Tops USD 6.72 Billion in 2025 — Asia‑Pacific Leads with USD 2.94B as 11.85% CAGR Fuels Growth Through 2032
By pmarketresearch, 2026-07-06
Bluetooth Audio IC Market: Strategic Imperatives for 2026 — PW Consulting Announces New Market Intelligence Brief
PW Consulting today releases an executive preview of our forthcoming Bluetooth Audio IC Market report (base year 2025), designed to equip senior executives, product strategists, and corporate development teams with the insight required to make high-consequence decisions in 2026. The global market for Bluetooth audio ICs has accelerated materially over the past five years and is forecast to maintain robust expansion through the end of this decade. Our analysis synthesizes market sizing, competitive positioning, supply-chain stress-tests, and actionable go-to-market playbooks — while reserving detailed segment-level figures to the full report to preserve the strategic value of the underlying intelligence.
Bluetooth Audio Ic Market
Headline market trajectory: scale, velocity, and implications
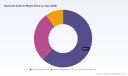
Bluetooth audio IC demand moved from an estimated USD 3,820.5 Million in 2020 to USD 6,720.0 Million in 2025, reflecting rapid adoption across hearables, personal audio, and a growing set of smart-speaker and automotive use cases. PW Consulting projects the market will continue to scale, reaching approximately USD 7,763.21 Million in 2026 and expanding toward USD 14,717.08 Million by 2032, underpinned by a compound annual growth rate of roughly 11.85% over the forecast window.
Bluetooth Audio Ic Market
For 2026 planning cycles, this trajectory translates into three critical operational realities:
Bluetooth Audio Ic Market
- Product roadmaps must align to accelerating unit volumes and evolving standards (notably Bluetooth 5.4 and LE Audio), or risk losing time-to-market advantages.
- Supply-chain agility — from wafer sourcing through packaging — will increasingly determine margin resilience as demand scales.
- Consolidation and platform-deepening by leading IC vendors will compress competitive windows for smaller entrants unless differentiated on software/IP or niche performance characteristics.
What the report delivers: practical, executable intelligence
Our full report is structured to convert market insight into executable plans. Key deliverables include:
- Validated market sizing and scenario models (2020–2032) with selectable assumptions for adoption curves and price erosion to support sensitivity testing.
- Roadmaps for chipset capabilities across Bluetooth Classic, Bluetooth Low Energy (LE) Audio, and dual-mode architectures — highlighting where investment in LC3 codec, spatial audio, low-latency stacks, and power-optimized DSPs will matter most.
- Supply-chain risk matrix that quantifies exposure to geopolitical controls, lead-time variability (post-2023 normalization for mid-node CMOS), and packaging bottlenecks.
- Commercial playbooks for OEMs and ODMs: recommended sourcing mixes, co-development KPIs, and timing guidelines to align product launches with standards rollouts and promotional windows.
- Go-to-market recommendations for IC vendors including premiumization levers, captive-software strategies, and channel tactics to defend against white-label competition.
- M&A and JV target shortlist methodology with high-level investment return profiles and integration risk scoring.
To preserve the competitive utility of the report to subscribing organizations, we intentionally withhold the granular segmentation tables and regional/application-level revenue allocations in this public summary. The full dataset and the interactive model are accessible via the PW Consulting report portal.
Competitive landscape — who matters and why
The Bluetooth audio IC space remains concentrated, with the leading three and five suppliers commanding a notable portion of market value. Market concentration enables platform owners to set de facto expectations for software ecosystems, codec support, and reference designs — factors that increasingly determine downstream OEM choices.
Our qualitative and quantitative competitive assessment highlights several strategic profiles:
- Qualcomm (San Diego, CA) — A market leader with deep software-radio integration and a compelling premium portfolio (Snapdragon Sound, aptX Adaptive, and LE Audio-capable families). Qualcomm’s strategy centers on vertical differentiation through proprietary audio pipelines and broad reference design programs that shorten OEM development cycles.
- Realtek Semiconductor (Hsinchu, Taiwan) — Competitive on cost and integration, Realtek’s Bluetooth audio SoCs are positioned to win high-volume hearable programs where price-performance and ANC capabilities are critical.
- Airoha Technology (Zhubei City, Taiwan) — Focused on premium TWS experiences with ultra-low latency and AI-driven noise cancellation; Airoha’s certification wins in LE Audio underscore its relevance for higher ASP segments.
- BES Technic (Shanghai, China) — Rapidly scaling in high-fidelity and low-power segments, BES is notable for advanced ANC and spatial audio implementations that target both premium and aspirational price tiers.
- Nordic Semiconductor (Trondheim, Norway) — A leader in Bluetooth LE Audio enablement with strong developer ecosystems for hearables and smart-speakers, particularly where LC3 codec support and low-power operation are mission-critical.
- Espressif Systems (Shanghai, China), Texas Instruments (Dallas, TX), and STMicroelectronics (Geneva, Switzerland) — Each offers differentiated propositions spanning integrated Wi‑Fi/Bluetooth combos, low-power audio stacks, and embedded MCU+BLE solutions that appeal to IoT audio and gateway applications.
PW Consulting’s vendor scoring model evaluates firms across technical roadmap alignment, reference design maturity, software ecosystems, pricing power, and customer diversification. Recent product announcements and certifications — such as Qualcomm’s QCC7226 LE Audio SoC launch (Feb 2024), BES Technic’s ultra-low power sampling (Jan 2024), and Airoha’s LE Audio qualifications (Dec 2023) — are mapped to our adoption scenarios to help clients decide partnership and sourcing priority for 2026.
Regulatory, supply, and standards context — implications for 2026 decisions
Strategic planning for 2026 cannot ignore macro drivers beyond pure demand-side forces:
- Standards evolution: Bluetooth 5.4 and the industry-wide LC3 codec mandate reshape performance baselines and interoperability requirements. OEMs that lag in LE Audio enablement risk higher lifecycle costs and reduced consumer appeal.
- Geopolitical trade measures: Export controls on advanced manufacturing equipment and selective tariffs have materially increased the operational complexity of cross-border supply chains. Our report provides decision trees to evaluate onshoring versus diversification for wafer, packaging, and test services.
- Fabrication and lead-time dynamics: After the acute shortages of 2020–2022, mid-node (e.g., 40nm) lead times stabilized in a 12–16 week range. That normalization reduces some short-term pressure but still requires disciplined inventory strategies for tier-one programs.
- Commercial policy risks: Tariff regimes and regulatory redlines (e.g., controls affecting equipment or finished IC exports) require proactive contract clauses, dual-sourcing arrangements, and contingency inventory buffers to protect launch timelines.
Strategic recommendations for 2026 — five imperatives
From our scenario work and vendor mapping, PW Consulting recommends five strategic moves for market participants planning 2026 investments:
- Prioritize LE Audio and LC3 enablement in all new product specs. Timeline alignment with standards adoption will determine which SKUs can command higher ASPs and longer revenue tails.
- Implement a two-track sourcing strategy: secure long-lead wafers through contractual commitments while qualifying alternative foundries and packaging houses to mitigate geopolitically driven disruptions.
- Invest in software IP and reference implementations that raise switching costs. Codec optimization, ANC tuning suites, and companion mobile apps are as decisive as baseband performance for end-user perception.
- Reassess go-to-market price ladders and after-sales monetization (firmware upgrades, codec licensing, feature bundles) to offset expected hardware price deflation as volumes scale.
- Use industry consolidation as an opportunity: target acquisitions or strategic JVs that fill gaps in RF expertise, low-power DSPs, or certification labs — accelerating time-to-market and reducing integration risk.
How PW Consulting supports 2026 decisions
We combine proprietary forecasting models, a live competitive database, and a decision analytics workbench to deliver outcomes-oriented support — from sourcing negotiation playbooks to M&A diligence packages. The full Bluetooth Audio IC Market report includes: the complete downloadable dataset (2020–2032), the editable Excel model for scenario testing, vendor scorecards with reference design maps, and a confidential shortlist of acquisition targets prioritized for ROI and integration ease.
This public brief intentionally omits granular regional and application-level revenue allocations to preserve the strategic leverage of the complete analysis. Executives seeking the segmented revenue tables, interactive models, and bespoke advisory engagements are invited to access the full report through the PW Consulting portal or contact our industry team for a private briefing.
Key takeaways
- Market scale and momentum are undeniable: from USD 3.82B in 2020 to USD 6.72B in 2025, with continued expansion forecast into 2032.
- Standards, software ecosystems, and supplier concentration will shape who captures the most value as the market grows.
- Proactive supply-chain and IP strategies are essential to secure 2026 product launches and to sustain margin resilience.
- PW Consulting’s report translates these dynamics into executable decisions — from product timing to partnerships and M&A — that materially affect competitiveness in 2026 and beyond.
To request the full report, schedule a private briefing, or license the dataset and model, please visit our website or contact PW Consulting’s Bluetooth Audio practice. Detailed segmentation, the interactive forecast model, and supplier scorecards are available to subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Bluetooth Audio Ic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Blackstrap Molasses Market to Reach USD 18,005.6 Million by 2032, Expanding at a 4.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-06
Blackstrap Molasses Market Outlook 2026: Strategic Imperatives for Growth, Resilience, and Value Capture
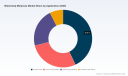
PW Consulting’s latest market research on the Blackstrap Molasses Market presents a forward-looking, decision-ready roadmap for corporate leaders, investors, and supply-chain strategists preparing for 2026 and beyond. Anchored on a 2025 base year and a robust historical lens (2020–2025), the study models outcomes across a 2026–2032 forecast horizon. At a compound annual growth rate (CAGR) of 4.2%, the global market expands from USD 13,500 Million in 2025 to an estimated USD 18,005.6 Million by 2032 — a steady trajectory that masks important inflection points and opportunity windows for early movers.
Blackstrap Molasses Market
Why this report matters for 2026 corporate decision-making
-
Actionable foresight, not vanity metrics: The research translates macro projections into operational triggers — procurement re-designs, price-risk playbooks, and product roadmaps — that leaders can deploy within quarters, not years.
Blackstrap Molasses Market -
Timing is strategic: 2026 is the first full-year window in the forecast period where incremental investments in formulation, branding, and capacity can compound to meaningful market share by 2030–2032. The report quantifies where those investments have the highest ROI in the medium term.
Blackstrap Molasses Market -
Fragmentation invites targeted consolidation: Market structure analysis reveals that the sector remains fragmented, enabling differentiated strategies from premium-brand plays to volume-scale supply agreements. The competitive assessment offers templates for M&A screening and strategic partnerships aligned to 2026 capital planning cycles.
Market dynamics and outlook — what the numbers tell us
The Blackstrap Molasses market demonstrates reliable, mid-single-digit growth driven by a combination of steady demand from traditional end uses and rapid adoption in emerging applications. With the market at USD 13,500 Million in the base year (2025), our forecast anticipates it growing to approximately USD 14,067 Million in 2026 and expanding to about USD 18,005.6 Million by 2032 under the baseline scenario (CAGR 4.2%). These topline projections are complemented by scenario layers in the full report — upside cases reflecting accelerated functional-food adoption and downside cases born of raw material price shocks.
Three structural forces underpin the forecast:
-
Demand diversification: Traditional demand centers such as animal feed and food manufacturing remain core, while new pulls from functional food fortification, renewable fuels, and specialty horticulture are reshaping consumption profiles.
-
Regulatory tailwinds: Nutrition policy shifts and renewable fuel mandates have created favorable regulatory backdrops. FDA emphasis on reduced added sugars and the positioning of natural sweeteners like blackstrap molasses in product reformulation, together with renewable fuel initiatives, enhance medium-term demand elasticity.
-
Price and input volatility: Raw-material and commodity price behavior will be a gating factor. Our situational analysis captured firm U.S. molasses price trends in mid-2025 and a lower global export reference in 2024 — both of which inform sourcing strategies and margin sensitivity scenarios contained in the report’s pricing matrices.
Competitive landscape — profiles and strategic implications
The sector’s competitive map blends long-established family-owned producers, regional bulk suppliers, branded consumer players, and specialized processors. PW Consulting’s company profiles synthesize operational strengths, channel footprints, and strategic postures to benchmark incumbents and challengers. Highlights include:
-
Zook Molasses Company (Zook Ag Company) — A family-owned, vertically integrated supplier with a strong presence in agricultural applications. Their capabilities in organic and non-GMO product lines make them a reference point for supply reliability and specialty positioning.
-
Golden Barrel (Good Food, Inc.) — Focused on unsulfured, sugarcane-derived products for retail and food service, Golden Barrel provides a model for premiumization within a traditionally commoditized category.
-
B&G Foods, Inc. — A consumer-brand centric player that in 2025 launched new organic and unsulfured variants under household brands. Their move illustrates how brand equity can accelerate category expansion into baking and health-conscious segments.
-
M.A. Patout & Son, LTD — One of the sector’s oldest family sugar producers; their byproduct integration demonstrates how upstream control can stabilize supply and cost exposure.
-
Crosby Molasses Co Ltd. — Recent product introductions include fortified, vitamin-enhanced blackstrap lines and sustainable packaging pilots, signaling rapid innovation in product-format and value-add strategies.
-
Bulk and specialty suppliers — Indiana Sugars, Buffalo Molasses LLC and Allied Old English — provide scale and channel reach, emphasizing the duality of volume-driven and niche premium strategies in the market.
Collectively, the firms profiled exemplify three strategic archetypes: (1) Vertical-integrators leveraging upstream sugar assets to control costs, (2) Brand-driven incumbents extending premium variants into health-oriented channels, and (3) Scale suppliers optimizing bulk distribution for industrial uses. The market’s fragmentation creates room for cross-archetype partnerships and targeted acquisitions — tactical plays the report models with estimated payback timelines.
Key risks and operational levers
-
Input-price volatility: Mid-2025 U.S. molasses pricing held in a tight band, while global export references (2024) were materially lower — a differential that affects international sourcing and export pricing models. Our price-sensitivity models show how procurement mix shifts and hedging strategies alter gross margins under multiple scenarios.
-
Regulatory shifts: FDA guidance encouraging reduced added sugars creates both risk and opportunity. Reformulation needs present a near-term cost burden but longer-term shelf-space gains for natural sweeteners. Likewise, renewable fuel policies support molasses-fed bioethanol pathways.
-
Product-perception and ingredient transparency: Consumer demand for organic, unsulfured and fortified options is driving premiumization. Packaging and traceability investments thus become revenue multipliers when executed alongside clear messaging.
What the full report delivers (practical components for 2026 planning)
PW Consulting’s deliverables are built for boardrooms and procurement desks alike. The full report includes:
-
Top-down and bottom-up forecasts across 2026–2032, inclusive of sensitivity and upside/downside scenarios.
-
Executive-ready pricing matrices and a procurement playbook for hedging and supplier diversification tailored to raw-material risk profiles.
-
Competitive benchmarking with operational scorecards, channel maps, and M&A screening models rooted in real-world comparables.
-
Commercial templates for product launches — from fortified lines to sustainable-packaging pilots — with estimated breakeven timelines and distribution pathways.
-
Regulatory impact assessments covering nutrition policy and renewable fuel mandates, with practical compliance checklists and reformulation cost calculators.
To preserve the strategic value of the research and encourage direct engagement, the public-facing summary intentionally withholds fine-grained regional and application-level split values; subscribers gain access to the complete segmentation tables, granular regional forecasts, and company-specific market shares.
Strategic recommendations — a 2026 playbook
-
Prioritize dual-sourcing and nearshoring where feasible. The report’s procurement scenarios demonstrate the marginal benefit of a hybrid sourcing approach that combines cost-competitive global supply with regional resilience.
-
Invest selectively in fortified and organic variants. Product innovation focused on nutrient-enhanced and unsulfured formulations offers disproportionate premium capture, particularly when coupled with sustainability messaging.
-
Use brand-strength to enter adjacent channels. Consumer-brand players should leverage household-name trust to accelerate adoption in health-oriented and functional food segments.
-
Target bolt-on acquisitions and strategic partnerships. Given the market’s fragmentation, disciplined M&A targeting capacity, distribution reach, or specialty product lines can accelerate scale without the premium of greenfield builds.
-
Embed regulatory intelligence into product R&D. Anticipatory reformulation and renewable-fuel-aligned product lines minimize compliance drag and open new industrial demand pools.
-
Operationalize sustainability as a commercial differentiator. Packaging, traceability, and low-carbon sourcing are increasingly table stakes that also justify price premiums in premium channels.
Concluding perspective
The Blackstrap Molasses market presents a judicious combination of stability and selective disruption. With a measured CAGR of 4.2% and a clear path from USD 13,500 Million in 2025 toward roughly USD 18,005.6 Million by 2032, the market rewards companies that convert macro foresight into tactical agility. Leaders who align procurement, product innovation, and regulatory strategy in 2026 position themselves to capture disproportionate share gains during the latter half of the decade.
PW Consulting’s full Blackstrap Molasses Market report is crafted to serve as the operating manual for that transition — from high-level market sizing to the granular playbooks procurement, R&D, commercial, and corporate development teams need to execute in 2026. For access to the complete dataset, regional and application-level forecasts, and company-level market-share tables, please consult the official report page.
For detailed analysis of this topic, please visit the official page: Blackstrap Molasses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: End‑Stage Renal Disease Market Poised to Reach USD 305.4 Billion by 2032
By pmarketresearch, 2026-07-06
End Stage Renal Disease Market 2026: Strategic Imperatives from PW Consulting
Executive summary
PW Consulting's latest End Stage Renal Disease (ESRD) Market report—anchored on a 2025 base year and delivering a 2026–2032 forecast—translates complex industry signals into clear action for executives planning their 2026 strategies. The global ESRD market demonstrated sustained expansion through 2020–2025 and reached approximately USD 152,306.5 Million in 2025. Under our base forecast, the market is expected to grow at a compound annual growth rate (CAGR) of about 10.45% across the 2026–2032 horizon, roughly doubling toward the end of the period. This trajectory and the competitive dynamics we observed make 2026 a pivotal year for decisions on product rollout, capital allocation, partnership formation, and regulatory positioning.
End Stage Renal Disease Market
Why this report matters for 2026 decision-making
-
Timely market inflection: After a period of incremental growth, the ESRD market is entering a phase where technology adoption, reimbursement changes, and delivery-model innovation converge. Companies that align product development and commercialization plans with these inflection points will capture disproportionate share.
End Stage Renal Disease Market -
Revenue-risk calibration: Our modeling quantifies upside scenarios for accelerated home-dialysis adoption and capital-substitution across care settings, as well as downside exposures tied to policy or reimbursement shocks. These scenario outputs are designed to inform 2026 budgeting, M&A valuation assumptions, and partnership term sheets.
End Stage Renal Disease Market -
Competitive clarity without overload: We synthesize market concentration indicators—showing a notably concentrated top-tier—and map the strategic moves of incumbent and challenger players, providing an actionable view of where white space exists without publishing our proprietary sub-segment tables in this release.
Market dynamics shaping 2026 strategy
The ESRD market's near-term runway will be shaped by three interlocking dynamics: technological innovation in dialysis systems and consumables; payment and policy adjustments; and service-delivery transformations that favor hybrid and home-based modalities.
-
Technology and product cycles: Recent regulatory clearances and product launches are accelerating refresh cycles for hemodialysis and home-dialysis platforms. Notable commercial moves include a planned 2026 US commercial roll-out of a high-volume hemodiafiltration platform from an established global vendor, and an early-2026 FDA clearance for a next-generation all-in-one hemodialysis system emphasizing cybersecurity and enterprise connectivity. These developments lower the technical entry barriers to integrated, digitally-enabled care pathways and create windows for complementary consumable and service offers.
-
Reimbursement and policy: The CY 2026 ESRD Prospective Payment System final rule formalized adjustments to the base rate and maintained key structural parameters such as the labor-related share and wage-index protections. The continued bundling of certain renal therapeutics into the PPS and alignment of certain acute dialysis rates with the ESRD base rate are immediate inputs into provider economics. PW Consulting’s scenario work demonstrates how even modest payment updates can materially affect facility-level margins and shift incentives toward home modalities and outpatient migration.
-
Service delivery evolution: Payors and large dialysis providers are actively testing value-based care arrangements and integrated care models. These pilots, combined with growing interest in remote-monitoring-enabled home dialysis, will alter capital allocation and sales strategies—favoring vendors and services that reduce total cost of care and demonstrate reliable outcomes across the continuum.
Competitive landscape — who matters and why
The ESRD market remains concentrated, with the top three and top five firms commanding a material share of industry revenue—an important context for strategic entrants and investors. Incumbents bring scale in clinic networks, procurement, and regulatory expertise; challengers are differentiating through platform design, digital integration, and novel care models.
-
Global dialysis platform leaders: Established multinationals continue to leverage broad product portfolios and clinic footprints to defend share. Their strategic playbooks emphasize deep integration across devices, consumables, and services to lock in care pathways and long-term recurring revenue.
-
Specialized device and consumable manufacturers: Several Japan- and Europe-headquartered firms maintain strong technology positions in membranes, dialyzers, and bloodlines. Their competitive advantage lies in technical performance and supply reliability, and they are active partners to both clinics and hospital systems.
-
Innovative system vendors and challengers: A cohort of companies focused on compact, home-ready dialysis machines and modular systems are reshaping expectations for usability, deployment cost, and cybersecurity. Successful commercialization for these players depends on payor engagement and evidence generation in home and outpatient settings.
-
Large services providers: Operators with extensive outpatient center networks and integrated care-management capabilities are pursuing vertical strategies—bundling clinical services with proprietary devices and supply agreements. Their negotiations with suppliers and payors will be crucial determinants of technology adoption speeds.
PW Consulting’s report profiles each major player across clinical footprint, product roadmap, distribution advantages, and strategic intent—providing boardrooms with the intelligence needed to prioritize partnerships, defensive actions, or entry strategies. To preserve the competitive sensitivity of our commercial-level datasets we summarize directional positioning in this release while reserving detailed competitor scorecards and supplier matrices for the full report.
Strategic implications by stakeholder
-
For device manufacturers: Prioritize interoperability, cybersecurity, and outcome-focused evidence generation. Competitive differentiation in 2026 will be defined by systems that reduce staffing complexity and enable secure remote management.
-
For consumables suppliers: Focus on supply-chain resilience and value-based contracting. Vendors that offer bundled solutions supporting lower total cost of care will gain traction with large service providers and payors.
-
For dialysis service operators: Revisit capital-allocation frameworks to balance investment in new in-center technologies with expansion of home-dialysis capacity. The 2026 policy environment favors operators that can demonstrate improved outcomes while managing unit economics under the PPS framework.
-
For payors and investors: Integrate provider-level scenario analyses into underwriting and portfolio construction. The market’s consolidation and the pace of home-dialysis adoption create both M&A opportunities and execution risk—detailed stress-testing in our report helps quantify these pathways.
What the PW Consulting ESRD Market report delivers
Our report is built for executive decision-making. Key deliverables include:
-
Market sizing and seven-year forecasts (2026–2032) with base-year anchoring and sensitivity scenarios that reflect alternative technology-adoption and reimbursement pathways.
-
Commercially actionable go-to-market playbooks for device OEMs, consumables manufacturers, and services providers—covering pricing architectures, channel design, and partnership templates.
-
Regulatory and reimbursement impact modeling that translates rules and rate updates into facility-level P&L implications under multiple operational assumptions.
-
Competitive intelligence dossiers on principal industry participants, including assessments of product roadmaps, clinic footprints, and strategic levers—alongside a proprietary opportunity matrix highlighting white-space by capability.
-
Investment and M&A framework with valuation overlays and integration risk checklists for acquirers and PE sponsors evaluating targets across the ESRD continuum.
To maintain the utility of this press release as a strategic prompt—and in line with our “trailer” principle—we are intentionally omitting the granular sub-segmentation tables, region-by-region breakdowns, and detailed revenue-by-treatment schedules from this summary. These are available within the full report and accompanying data pack.
Recent developments and near-term signals
-
March 2026: A leading global dialysis manufacturer published its 2025 annual report and confirmed plans for a full commercial launch in the US of a high-volume hemodiafiltration system in 2026. This introduces a new competitive axis around HVHDF capabilities in markets where clinical adoption is rising.
-
January 2026: A prominent innovative-system vendor received FDA 510(k) clearance for a next-generation hemodialysis platform emphasizing enhanced enterprise-level security and connectivity, with a planned Q2 2026 launch—an important development for hospital and home-integration strategies.
-
November 2025: The US CMS released the CY 2026 ESRD PPS final rule, updating base payment parameters and preserving key structural features of the payment bundle—affecting facility economics and payer-provider negotiations in 2026.
How to use this intelligence in Q1–Q4 2026 planning
-
Start with scenario triage: Use our three-point scenarios (base, upside, downside) to test capital projects, R&D prioritization, and sales-coverage redesigns. Even modest shifts in modality mix materially change ROI timelines.
-
Design modular contracting pilots: Structure early 2026 contracts to include outcome clauses and volume-flex terms that de-risk launches for both suppliers and operators.
-
Invest in evidence generation: Prioritize prospective studies and real-world pilots that demonstrate reduced hospitalization and resource utilization—data that payors and integrated operators will demand when negotiating broader rollouts.
-
Anticipate consolidation vectors: Use our M&A playbooks to prepare for both buy- and sell-side scenarios; mid-market consolidation is likely to accelerate once new platform deployments demonstrate predictable economics.
Accessing the full report
The PW Consulting End Stage Renal Disease Market report contains the complete datasets, proprietary segmentation, competitor scorecards, and customizable financial models referenced in this briefing. For boards, corporate strategy teams, and investors planning 2026 actions, the full report is designed to be an operational blueprint rather than a descriptive summary. Visit our report page to request the full study, data pack, and a complimentary briefing session with PW Consulting’s lead ESRD practice analysts.
PW Consulting remains committed to translating industry complexity into executable strategy. In an industry where clinical, technological, and policy shifts converge, timely intelligence and pragmatic playbooks will distinguish winners in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: End Stage Renal Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Aerial Inspections Service Market Set to Expand at a 13.5% CAGR, Fueling UAV and Drone Growth
By pmarketresearch, 2026-07-06
Aerial Inspections Service Market: A 2026 Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-level strategic briefing drawn from our forthcoming Aerial Inspections Service Market report (base year 2025). The market has accelerated into the mainstream of capital-intensive sectors — energy, utilities, infrastructure, agriculture and industrial operations — and now demands board‑level attention. From USD 7.45 billion in 2020 to USD 14.5 billion in 2025, the market is forecast to continue expanding at a robust compound annual growth rate (CAGR) of 13.5% through our 2026–2032 projection window, reaching roughly USD 35.18 billion by 2032. This trajectory creates both immediate opportunities and mid-term strategic imperatives for enterprises, investors, and public-sector planners preparing decisions in 2026.
Aerial Inspections Service Market
Why 2026 Is a Pivotal Year
2026 is the inflection year where technology maturity, regulatory evolution, and procurement economics converge. Rapid improvements in AI analytics, autonomy and sensor miniaturization are reducing the marginal cost and lead time of inspections, while regulatory moves (notably evolving FAA policy on BVLOS and enforcement programs such as DETER) are reshaping risk profiles and operational constraints for commercial operators. For organizations planning 2026 budgets and three‑to‑five‑year roadmaps, the question is not whether to invest in aerial inspections, but how — and with whom.
Aerial Inspections Service Market
Market Trajectory and Strategic Implications
-
Scale and speed: The market doubled from 2020 to 2025 and is poised to more than double again by 2032 under a 13.5% CAGR. This pace signals a transition from niche pilots to standardized enterprise workflows for asset inspection and condition monitoring.
Aerial Inspections Service Market -
Cost arbitrage: Empirical industry benchmarking indicates drone-based industrial inspections can reduce operational costs by 30–70% and compress inspection time by 75–85% versus traditional manual methods that require scaffolding, rope access, or plant shutdowns. That delta is driving rapid payback for capital and operating expenditure reallocation.
-
Fragmentation with pockets of influence: Market concentration remains relatively low; the top three and top five providers account for modest shares, creating fertile ground for strategic partnerships, regional rollouts, and M&A to secure scale in targeted verticals.
-
Unit economics and pricing dynamics: Commercial service pricing varies by scope and sensor mix — for example, roof and building inspections market benchmarks range from roughly USD 150–500 per property, or USD 200–700 per hour for thermal-enabled inspections. Buyers must normalize these rates against risk-adjusted labor and reinstatement costs for traditional methods.
What the PW Consulting Report Delivers (Practical, Executable)
Our report is designed as a decision support toolkit for 2026. It combines market sizing and scenario forecasts with operational playbooks so executives can move from strategy to execution without wading through raw data alone. Key deliverables include:
-
Decision frameworks that map inspection objectives (safety, uptime, predictive maintenance, compliance) to recommended technology stacks (rotary-wing drones, fixed-wing UAVs, manned overflights, satellite/remote sensing) and procurement pathways.
-
ROI and TCO models with adjustable levers — inspection frequency, sensor portfolio, internal vs. outsourced flight ops, data processing cadence — enabling finance teams to stress-test CAPEX/OPEX scenarios.
-
Operational playbooks covering governance, pilot competency and certification, BVLOS permitting strategy, data security, and integration points with asset management systems (EAM/CMMS/BIM).
-
Vendor assessment matrix and negotiation playbook: comparable scorecards, contract clauses to mitigate liability, SLAs for data quality and delivery latency, and benchmarks for pricing and managed-service terms.
-
Field‑proven use cases and migration roadmaps for tiered adoption — from trial pilots and center‑of‑excellence formation to enterprise rollout and cross‑asset standardization.
Competitive Landscape — Strategic Takeaways
The supplier ecosystem is multi‑modality and geographically distributed: established drone-inspection specialists, enterprise software platforms, wind‑turbine focused automation firms, and traditional aerial surveyors with expanding drone divisions. Several illustrative strategic profiles inform our assessment:
-
Cyberhawk (Edinburgh, UK) : A leader in drone-based asset inspection and aerial data management, Cyberhawk’s extensive asset portfolio and platform capabilities make it a natural partner for energy and heavy industry clients seeking end‑to‑end service continuity. Recent contract renewals with major operators underline their strength in long‑cycle maintenance programs.
-
DroneDeploy (San Francisco, USA) : With a robust reality-capture platform and accelerating enterprise adoption, DroneDeploy’s 2026 product releases and large-scale project partnerships reflect a play to be the digital backbone for construction, infrastructure and enterprise site standardization. Expect continued emphasis on integrations and performance at scale.
-
SkySpecs (Ann Arbor, USA) : Focused automation and vertical specialization (wind) combine with AI-driven analytics to deliver differentiated value in a niche where uptime and blade-level diagnostics drive revenue. Their proposition is attractive to asset owners seeking prescriptive maintenance insights rather than raw imagery.
-
Terra Drone (Tokyo, Japan) : Global service reach and diversification into defense-capable operations expand addressable markets. Their model suits organizations with complex regulatory footprints and cross-border assets.
-
Raptor Maps, SAM, AERIUM Analytics, Measure and other regional specialists: These providers offer deep domain expertise (solar farms, LiDAR surveying, industrial analytics, enterprise engagements) that make them strong regional partners or acquisition targets for scaling integrators.
Recent market moves — expanded multi‑year enterprise agreements, software performance releases, and division launches focused on offshore or subsea operations — indicate vendors are competing on platform capability, data velocity, and industry‑specific service packaging. For buyers, this means procurement evaluation should prioritize interoperability, analytics maturity, and proven SLAs over raw flight-hour cost alone.
Regulatory and Operational Dynamics
-
Regulatory evolution: Baseline certifications (e.g., FAA Part 107) remain foundational, but 2026 enforcement and policy initiatives — accelerated violation resolution programs and proposed BVLOS rule changes — materially affect operational timelines and risk registers. Organizations must fund regulatory affairs and legal engagement as part of program planning.
-
Operational readiness: Achieving the promised 30–70% cost reductions requires investments in data pipelines, analytics, and change management. Expect a two‑to‑three quarter ramp from pilot to dependable operational cadence for most enterprise implementations.
-
Labor and skills: Specialist pilot labor and thermal inspection expertise are priced at a premium. Procurement strategies should consider blended models where specialized tasks are outsourced while routine data capture is insourced or automated.
Actionable Recommendations for 2026 Decision-Makers
-
Prioritize a “use-case first” approach: Start with critical assets where inspection frequency, safety risk, or replacement cost creates the clearest ROI. Use PW Consulting’s TCO templates to quantify decision thresholds before scaling.
-
Lock in a two‑tier supplier architecture: one partner for platform/data management and another (or validated roster) for flight ops and subject-matter inspection. This reduces vendor lock‑in while ensuring redundancy and coverage.
-
Invest 5–10% of first‑year program savings back into data engineering: the long‑term value resides in analytics and integration with maintenance workflows, not only in reduced flight hours.
-
Engage regulatory pathways proactively: allocate resources for BVLOS waivers or equivalent approvals where necessary, and incorporate compliance milestones into procurement timelines to avoid rollout delays.
-
Consider inorganic options selectively: given the fragmented market and modest top‑tier concentration, targeted acquisitions or equity partnerships can rapidly secure domain expertise or geographic presence, particularly in offshore wind, solar operations, or critical infrastructure segments.
How to Use This Report in Your 2026 Planning Cycle
This briefing is intended as the strategic prelude; the full PW Consulting Aerial Inspections Service Market report provides the granular datasets, vendor scorecards, customizable financial models, and procurement templates necessary to operationalize the recommendations above. Use the report to:
-
Inform capital allocation decisions and build multi-year budgets aligned with expected savings and risk mitigation benefits.
-
Accelerate procurement cycles with ready-made RFP language and negotiation checklists focused on data SLAs and integration requirements.
-
Benchmark internal capability against vendor capabilities and industry KPIs to prioritize training, hiring, or outsourcing.
Closing: The Strategic Imperative
By 2026, aerial inspection services are no longer an experimental add‑on; they are a strategic lever that materially affects asset reliability, safety, and lifecycle economics. Our market forecast — reflecting sustained double‑digit growth and significant operational cost advantages — suggests that organizations delaying structured investment risk ceding efficiency and data leadership to faster-moving peers. PW Consulting’s full report is designed to convert market opportunity into executable programs: rigorous, vendor‑agnostic, and oriented to measurable performance outcomes. For executives preparing budgets, procurement cycles, and M&A priorities in 2026, this is the practical intelligence to act on — and the foundation for a defensible competitive position in the decade ahead.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Palm Kernel Shells Biomass Market Set to Surge at an 8.5% CAGR to Reach USD 2,318.9 Million by 2032
By pmarketresearch, 2026-07-06
Palm Kernel Shells Biomass Market — Strategic Imperatives for 2026
As global decarbonisation accelerates and thermal generation portfolios are restructured, palm kernel shells (PKS) have emerged from the palm-oil value chain as a strategically important biomass feedstock. PW Consulting’s latest Palm Kernel Shells Biomass Market report (base year 2025) frames the PKS opportunity with a rigorous, forward-looking lens: the market was worth roughly USD 1.31 billion in 2025 and our demand-supply model projects an 8.5% compounded annual growth rate through the forecast window, reaching institutional-scale market sizes by the early 2030s. For decision-makers planning 2026 roadmaps, the report converts this macro momentum into operational actions, risk maps and investment-ready scenarios — while reserving the granular cell-level datasets and company-level volume tables for the full report.
Palm Kernel Shells Biomass Market
Why 2026 Is an Inflection Year
-
Policy and procurement are aligning. A suite of sustainability-driven procurement filters—most visibly certification regimes required for export markets—has shifted buyer behaviour toward traceable, certified PKS. This is changing offtake dynamics and elevating premiums for compliant supply chains.
Palm Kernel Shells Biomass Market -
Supply-side restructuring is underway. Processing capacity additions, plant rationalisations and the emergence of dedicated PKS aggregators have made feedstock availability more market-responsive, but not uniformly so across trading corridors. Logistics chokepoints (port capacity, seasonal vessel availability and inland trucking) remain decisive cost drivers.
Palm Kernel Shells Biomass Market -
Commercial concentration sits in a middle band: the sector is not hyper-consolidated, but neither is it atomised. The competitive geometry leaves room for scale players to secure advantage through integrated supply chains, and for nimble intermediaries to capture margins through logistics and quality arbitrage.
-
Price and risk transmission are intensifying. Macroeconomic variables—including palm oil reference pricing, local export levies and currency movements—feed quickly into PKS export economics. Buyers and producers face several months of lagged, but material, pricing effects as these variables evolve.
What the Report Delivers — Practical, Transaction-Ready Intelligence
The PW Consulting report is built for commercial teams, buyers, asset owners and investors who must convert sector momentum into defensible decisions. Key deliverables include:
-
Proprietary market sizing and a reconciled demand-supply model covering historical 2020–2025 dynamics and forward projections across the 2026–2032 forecast window (methodology, input assumptions and sensitivity runs included).
-
Price-driver decomposition that isolates origin fundamentals, logistics cost components and sustainability-premium mechanics — and translates these into forward price envelopes under alternative macro scenarios.
-
Regulatory and certification matrix connecting country-level export measures, sustainability standards and buyer compliance requirements to offtake and insurance considerations.
-
Operational playbooks for procurement and inbound logistics — tender templates, quality specs and sample contract clauses calibrated to typical PKS grading (net calorific values, ash and moisture specifications) and international shipping practices.
-
Supplier benchmarking and a competitive landscape module: company profiles, capability heatmaps, processing footprints and capacity-change trackers. (Note: granular company volumes and regional/applications splits are only available in the full report.)
-
Transaction support tools: valuation checklists for acquisition targets, due-diligence scorecards for offtake counterparties, and scenario-based investment cases for processing plants and port-side logistics hubs.
Competitive Dynamics — Who Matters and Why
The market ecology is shaped by three archetype players: certified export-focused processors, regional aggregators with buyer linkages, and diversified palm-oil groups that monetise residues as energy feedstock. Leading examples illustrate these roles:
-
Export-focused processors who emphasise certified, traceable product and have expanded processing capacity to serve demanding buyers. Their advantage: faster market access to sustainability-conscious buyers and the ability to capture contract premiums.
-
Regional trading houses and industrial buyers that combine long-term supplier relationships with flexible delivery nodes across Southeast Asia. Their advantage: lower logistical friction and the ability to tailor delivery schedules to utility ramp profiles.
-
Integrated plantation and milling groups that treat PKS as a closed-loop complement to their core operations, supplying both domestic industrial boilers and export markets. Their advantage: feedstock security and internal price arbitrage opportunities.
Recent industry actions illustrate the strategic choices companies are making: capacity additions in strategic coastal locations, multi-year offtake agreements with sustainability clauses, and new long-haul shipments into established biomass markets. These moves confirm two structural themes: certification and logistics access are the immediate value multipliers; and scale in processing plus export capability materially improves negotiating leverage with large buyers and utilities.
Regulatory and Quality Constraints — Operational Realities
-
Certification requirements in key import markets have real economic consequences. Compliance regimes that verify origin and processing chain integrity shape which tonnes are contractable on long-term terms.
-
Origin-level trade measures and export administration changes can tighten or loosen realisable export economics. Even modest changes to export tariffs or service fees materially shift the margin calculus for both exporters and buyers.
-
Technical specifications matter in procurement: calorific value bands, ash content and moisture drive boiler performance, handling systems and downstream emission profiles. Buyers increasingly specify these parameters to reduce plant risk and maintenance costs.
Strategic Actions for 2026 — Tactical Steps with Immediate Payback
For corporate leaders planning budgets and contracts in 2026, the report recommends a focused set of executable steps that can be initiated in quarters rather than years.
-
Secure multi-year offtake frameworks that include flexibility clauses for modal choice and force majeure calibrated to seasonality. Prioritise counterparties that accept staggered pricing collars rather than rigid floor/ceiling structures.
-
Invest in certification and traceability early. The incremental operational cost of documented chain-of-custody is often exceeded many times over by the price premium and counterparty access it unlocks.
-
Conduct logistics-to-market audits. Small reductions in port dwell time and vessel scheduling uncertainty can yield outsized margin improvements across contracted volumes.
-
Calibrate procurement to quality tiers. A deliberate blend of screened and unscreened product, matched to buyer technical tolerance, can optimise yield while avoiding costly downgrades at delivery.
-
Prepare contingency sourcing corridors. Diversifying supply nodes, even within the same country, reduces exposure to localized levies, mill outages and transport disruptions.
Investment & M&A Radar
Investors and strategic buyers should prioritise assets that combine three attributes: processing capacity with modular scalability, deep buyer offtake relationships (preferably with sustainability clauses), and resilient port/rail access. Our transaction playbook—which includes due diligence templates and valuation sensitivities—targets these attributes, emphasising the need to stress-test projections against alternative palm oil price paths and regional trade-policy shifts.
Risk Management — What Keeps CFOs Awake
-
Policy volatility in originating countries that can change export economics quickly.
-
Quality divergence between batch receipts and contractual specs that can trigger penalties or rejection risk at destination boilers.
-
Logistics and vessel availability, where a single bottleneck can cascade into missed offtake deliveries and credit exposure.
Why PW Consulting’s Report Is Different
We combine a granular operational view (tender templates, QC checklists, port-rotation maps) with a robust macro model that produces scenario-weighted forecasts. Our market-concentration metrics and company capability matrices offer a diagnostic not found in commodity-only studies: we show where value accrues in the commercial chain and provide the implementation tools commercial teams need to capture it.
How to Use This Insight in 2026
-
Procurement teams: use the modelled price envelopes and tender templates to design contracts that reduce basis risk and lock in certified capacity.
-
Asset owners: use the scenario toolset to validate investments in processing or port-capacity expansions and to quantify payback under different demand-growth trajectories.
-
Investors and M&A advisers: apply the due diligence scorecards and consolidation playbook to prioritise targets that are most likely to deliver accretive margin expansion.
Next Steps
The summary here highlights the structural logic and actionable directions for corporates and investors considering PKS in 2026. To access the full intelligence — including detailed regional and application breakouts, company-level benchmarking, contract clause templates and the complete dataset underpinning our forecast — please consult the full Palm Kernel Shells Biomass Market report. PW Consulting offers bespoke briefings and implementation support packages to translate this market-level view into transactional milestones and operational change programs.
In a market growing at a mid-single-digit to high-single-digit compound rate and shifting under the twin forces of sustainability and logistics, 2026 is the year to convert strategic intent into measurable advantage. Our report gives you both the high-level map and the on-the-ground tools required to act with speed and conviction.
For detailed analysis of this topic, please visit the official page: Palm Kernel Shells Biomass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wafer‑Level Burn‑In Systems Market to More Than Double — From USD 1,420 Million in 2025 to USD 3,456.2 Million by 2032 at a 13.55% CAGR
By pmarketresearch, 2026-07-06
Wafer Level Burn‑In Systems Market: Strategic Imperatives for 2026 — PW Consulting Releases In‑Depth Industry Brief
PW Consulting today publishes an executive briefing accompanying our full Wafer Level Burn‑In (WLBI) System Market report (base year 2025, forecast 2026–2032). As semiconductor manufacturers and equipment suppliers prepare investment plans and product-roadmap decisions for 2026, this briefing synthesizes the most consequential market dynamics, risk vectors, and tactical plays that should inform board‑level and C‑suite decisions. Our analysis situates WLBI not as a niche reliability step but as a strategic fulcrum in the broader acceleration of SiC/GaN power, silicon photonics, AI compute, and advanced optoelectronics supply chains.
Wafer Level Burn In System Market
Market Trajectory: A Rapid, Capital‑Intensive Expansion
WLBI demand has expanded materially over the last five years and PW Consulting’s modeling shows sustained, above‑market growth through the forecast horizon. The global WLBI market more than doubled between 2020 and 2025 and — under our base case — continues to grow at a mid‑teens compound annual rate over the next several years, reflecting intensified wafer‑level qualification requirements across emerging device families. By 2032 the market reaches multiple billions (USD, revenue unit: Million), driven by multi‑wafer parallelism and higher‑power burn‑in needs characteristic of next‑generation power and photonics devices.
Wafer Level Burn In System Market
This growth is not uniform: it is being shaped by three structural forces — accelerated adoption of wide bandgap and high‑power device families, increasing wafer sizes and parallel test architectures, and the growing economics of wafer‑level reliability versus traditional package‑level approaches. For companies deciding 2026 capital budgets, timing and configuration choices made this year will materially affect unit economics and throughput in the 2027–2030 window.
Wafer Level Burn In System Market
Why This Report Matters for 2026 Decision‑Making
- CapEx timing and configuration: We quantify how incremental investment in multi‑wafer parallel burn‑in versus selective single‑chuck systems affects throughput payback under realistic adoption curves. Our scenarios isolate the break‑even thresholds that matter when wafer sizes, test times and contactor costs are pulling in different directions.
- Supply‑chain risk management: The report maps critical component dependencies — from high‑precision wafer contactors to specialized high‑power controllers — and models the impact of elongating lead times and tariff pressures on procurement calendars.
- Procurement strategies: Based on equipment vendor roadmaps and real order activity in 2025–2026, we provide actionable vendor selection criteria and negotiation levers for OEMs and IDMs choosing between full‑wafer parallel approaches and more modular selective solutions.
- Business model innovation: We explore alternatives to capital purchase — including contactor subscription models, burn‑in as a service, and shared‑facility partnerships — and quantify when these can preserve margin and accelerate time‑to‑market.
Practical Contents — What Executives Will Find Inside the Full Report
- Methodology and transparent market modeling calibrated to historical data (2020–2025) and our detailed scenario framework for 2026–2032.
- Throughput and cost models that let procurement and manufacturing leaders test sensitivity to cycle time, wafer sharing, and consumable replacement rates.
- A supply‑chain risk heat‑map highlighting single‑source exposures, long‑lead components, and geopolitical tariff vectors.
- Vendor scorecards that assess technology fit, automation compatibility (including SECS/GEM standards), service footprint, and roadmap alignment for AI, photonics and wide‑bandgap device segments.
- Actionable playbooks for OEMs, equipment suppliers, and capital partners to deploy WLBI investments with lower implementation risk and faster ramp.
Note: This public briefing is designed as a “trailer” — it demonstrates the report’s practical depth while withholding proprietary segment tables, regional and application splits, and detailed vendor ranking matrices. These proprietary data and downloadable models are available in the full PW Consulting report and online dataset.
Competitive Landscape: Technology Leaders and Tactical Opportunities
WLBI is characterized by a mix of specialized providers and broader test‑equipment incumbents. Leading vendors present differentiated approaches — from full‑wafer parallel systems optimized for high‑power SiC/GaN and silicon photonics, to modular selective solutions geared toward mixed workloads and constrained CAPEX.
- Aehr Test Systems (Fremont, California) — recognized for wafer‑level systems that enable high‑power parallel testing and for modular contactor technology that supports photonics and AI‑oriented interconnects. Recent order intake and shipments indicate robust demand from both silicon photonics and AI compute segments, and the vendor is scaling configurations that support advanced automation interfaces.
- Semight Instruments (Suzhou) — focuses on multi‑wafer automated WLBI systems for wide bandgap devices; their platform choices speak to aggregated throughput requirements in power markets.
- 4JMSolutions (Pieta, Malta) and Pentamaster (Penang) — provide multi‑wafer and high‑temperature platforms targeting VCSELs, LEDs, MicroLED and power devices where thermal excursion and alignment precision are critical.
- Delta V Instruments, Advantest, Teradyne, Abrel Products, and niche suppliers — collectively serve varied parts of the WLBI value chain, from patented full‑wafer exercising technologies to configurable burn‑in boards and fixtures.
Market concentration is meaningful: a limited set of suppliers currently captures the lion’s share of WLBI demand, and OEM selection decisions are materially influenced by automation compatibility, device‑specific contactor availability, and global service footprint. For buyers, the vendor landscape presents both challenge and leverage: incumbents enjoy technical moats in specific device segments, while well‑timed partnerships and co‑development agreements can secure preferred access to capacity and consumables.
Risk Factors and Operational Constraints for 2026 Planning
- Export controls and geopolitics: Controls on advanced semiconductor equipment and related components are an active factor in 2025–2026. Procurement teams must include regulatory compliance pathways and alternative sourcing scenarios in capital planning.
- Consumable economics: High recurring costs for wafer contactors and probe modules — combined with finite lifespans — materially influence total cost of ownership. Manufacturers should model consumable replacement cadence alongside throughput gains from parallel architectures.
- Tariffs and tariffs‑driven lead times: Trade measures and regionally‑varying tariffs are inducing supply‑chain diversification. Buyers should plan longer procurement lead times and consider buffer inventory strategies for critical long‑lead items.
- Component shortages: In 2025 a notable share of WLBI operations experienced delays driven by shortages of specialized components. Our scenario work illustrates how these shortages can cascade, delaying program ramps by quarters if contingency provisions are not in place.
Strategic Recommendations — What Companies Should Do in 2026
- Align WLBI investments to device roadmaps: Map WLBI capital and automation investments directly to near‑term device ramps (SiC/GaN, photonics, AI I/O). Prioritize configurations that preserve flexibility across these high‑growth segments.
- Secure consumable pipelines: Negotiate multi‑year supply agreements for high‑wear items, consider vendor‑supported stocking programs, and evaluate contracted replacement price caps to reduce margin volatility.
- Adopt modular automation standards: Where possible, insist on SECS/GEM and other open automation interfaces to future‑proof factory integration and preserve competitive optionality between hardware vendors.
- Explore shared‑facility and service models: For firms with sporadic WLBI demand, consider burn‑in as a service or shared‑floor arrangements to avoid inefficient capital deployment while maintaining test capacity.
- Stress‑test procurement and regulatory scenarios: Run procurement war‑games that include export control constraints, tariff variations, and extended supplier lead times to validate go‑to‑market schedules.
Examples from the Market — Signals Worth Watching
Recent order flow and shipment activity in late‑2025 and early‑2026 underscore shifting demand patterns. Several high‑visibility orders for multi‑wafer high‑power systems and shipment announcements to analog and embedded chip manufacturers reflect both wafer‑level and package‑level testing momentum. Such vendor activity is an early indicator that WLBI is being adopted at larger scale for high‑value device families where defect avoidance and early life reliability translate directly into product credibility and lower system‑level failure rates.
Conclusion — From Tactical Choices to Strategic Advantage
WLBI is at an inflection point. The technology’s role is expanding from reliability assurance to a competitive production lever: faster time‑to‑market, higher yields for high‑power and photonics devices, and new monetization pathways through service models and consumable revenue. For 2026, executives must treat WLBI decisions as strategic investments with multi‑year operational and financial consequences — not merely as tooling line items.
PW Consulting’s full WLBI Systems Market report provides the granular segmentation, vendor scorecards, downloadable cost models and scenario analyses needed to underwrite those decisions. This briefing highlights the strategic framing and actionable implications; the detailed, proprietary datasets and segment splits that underpin our conclusions are available in the full report and accompanying online dashboard.
How to Access the Full Report
Executives, procurement leaders and investors seeking the complete market dataset, regional and application segmentation, and vendor benchmarking should visit PW Consulting’s report page to request the full document and supporting models. Our advisory team is available to conduct customized briefings and scenario workshops tailored to your device roadmaps and manufacturing footprints.
For detailed analysis of this topic, please visit the official page: Wafer Level Burn In System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com