

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Low Salted Sodium Hypochlorite Market to Rise from USD 648.5 Million in 2025 to USD 930.29 Million by 2032 at a 5.29% CAGR

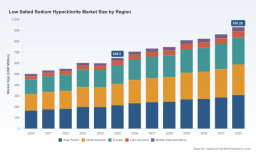
Low Salted Sodium Hypochlorite Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As PW Consulting’s lead strategic advisor and industry analyst, I present a concise, decision-focused preview of our latest market study on Low Salted Sodium Hypochlorite (LSSH). This “trailer” is designed to arm senior executives, procurement officers, and technology strategists with the high-level signals that will matter in 2026 — while reserving the granular maps and segment-level metrics for the full report. The LSSH market has entered a phase of steady, structurally driven expansion; our modelling, which uses 2025 as the base year and spans 2026–2032, shows a mid-single-digit compound annual growth rate (CAGR) and clear inflection points tied to purity, logistics, and on-site generation adoption.
Low Salted Sodium Hypochlorite Market
Why this market matters now
-
Purity and performance are becoming procurement criteria, not just price drivers. End-users in municipal water treatment, food & beverage, and critical industrial applications are prioritizing low-impurity chemistries to reduce by-product formation, minimize equipment wear, and extend effective dosing windows.
Low Salted Sodium Hypochlorite Market -
Supply-side sophistication is rising. Producers that combine multistage processing (salt removal and trace-metal filtration) with validated stewardship and handling protocols are capturing premium positions in buyer evaluations.
Low Salted Sodium Hypochlorite Market -
Operational models are fragmenting: bulk centralized supply competes with localized, on-site generation technologies. This bifurcation changes CAPEX/OPEX calculus for buyers and reshapes supplier engagement strategies.
Market trajectory and concentration — what to expect in 2026
Our base-year analysis (2025) and forecast horizon (2026–2032) show a clear growth path supported by demand-side shifts and incremental product innovation. The market exhibits a measured level of supplier concentration: the top-tier competitors collectively represent a meaningful share of industry revenue, leaving room for regional specialists and technology-driven entrants to capture niche advantages. For executives planning supplier rationalization or strategic sourcing in 2026, this implies both opportunity and caution: negotiating leverage exists but so does the risk of supplier capacity constraints for specialized low-impurity grades.
Key macro parameters that underpin our scenario planning:
-
Base-year anchoring and forward modelling across a seven-year forecast window (2026–2032) that captures both near-term operational decisions and medium-term capital allocation choices.
-
Mid-single-digit CAGR, reflecting steady adoption across municipal and industrial channels and incremental replacement of legacy chemistries where impurity control yields measurable operational savings.
What the full report delivers (practical, executable intelligence)
The full PW Consulting report is structured to move teams from insight to action. Highlights include:
-
Validated market model (historical 2020–2025; base year 2025) with scenarios that stress-test demand sensitivity to price, regulatory changes, and on-site generation penetration.
-
Supplier dossiers with plant footprints, product positioning, purity and handling claims, and a readiness checklist for qualification audits — tailored to support procurement RFIs and RFPs.
-
Decision-playbooks for water utilities and industrial users: when to trial high-strength low-salt products, how to quantify life-cycle savings (dosing efficiency, reduced chlorate/perchlorate formation, extended shelf life), and how to structure pilot-to-scale programs.
-
Operational guidance for handling, storage, and risk mitigation — including transport logistics, emergency response templates, and inventory strategies that minimize degradation-related losses.
-
Regulatory and standards matrix across major jurisdictions, highlighting certification practices (e.g., potable water chemistry approvals) and practical steps to document compliance during supplier qualification.
-
Supply chain risk mapping and mitigation options: dual-sourcing strategies, contract design (volume-flex, quality rebates), and investment thresholds for on-site generation where appropriate.
Competitive landscape — headings you can act on
The competitive environment is a mix of integrated chlor-alkali majors, specialized formulators, and global specialty-chemicals players. Our report profiles leading names and evaluates them across product purity claims, concentration capabilities, geographic reach, and commercial practices.
-
Kuehne Company — A private chlor-alkali producer with concentrated low-salt formulations marketed for stability and municipal reliability. Their positioning emphasizes purity and long-term application performance.
-
HASA Inc. — A market-moving specialty supplier known for premium, high-strength low-salt grades. Recent field trials by HASA demonstrated substantial usage reductions and more consistent residual control versus standard-strength products; these operational outcomes are central to total-cost-of-ownership arguments in water utilities.
-
Olin Corporation — An integrated player offering super-concentrated, proprietary low-salt hypochlorite grades, together with updated stewardship and handling guidance. Olin’s scale and product stewardship documentation make it a key counterparty for large-volume contracts.
-
Shin-Etsu Chemical — A producer focused on certified low-impurity grades that meet potable water association standards; strong relevance for regulated public water supply systems and certified industrial processes.
-
Kaneka Corporation — A specialty chemicals manufacturer with branded low-salt hypochlorite solutions tailored for public water and bleaching applications, emphasizing low-bromate/chlorate profiles.
Each supplier profile in the full report includes: product specifications (purity corridors and concentration ranges), claimed shelf-life and handling constraints, known field performance anecdotes, and a supplier risk/opportunity score to aid sourcing decisions.
Recent, actionable developments to watch in 2026
-
Field validation of higher-concentration, low-salt products has moved from pilot to documented performance. Notably, a mid-2025 trial showed a meaningful reduction in usage volumes and improved performance stability at a wastewater treatment plant — a proof point many municipalities are now using to justify pilot investments.
-
Large suppliers are codifying stewardship practices and technical handling documentation for super-concentrated low-salt products, reducing buyer uncertainty around safety and logistics.
-
On-site generation systems continue to advance as an alternative operating model. Their economics improve when transport costs, safety restrictions, or storage constraints are significant; however, they require a distinct investment and maintenance capability that not all users will embrace in the short term.
Strategic implications for 2026 decision-makers
For executives preparing budgets and procurement strategies for 2026, our analysis supports a handful of high-leverage moves:
-
Shift pilots from technical evaluation to financial validation. Run side-by-side dosing and operations trials that capture not only chlorine residual performance but also dosing volume, chemical degradation, equipment maintenance intervals, and total cost of ownership. Recent field data suggest that validated high-strength low-salt grades can lower usage volumes and stabilize operations — a metric that should be quantified locally.
-
Reframe supplier selection around purity risk and stewardship documentation. Require supplier-submitted handling and product stewardship manuals as part of RFPs; this materially reduces onboarding friction for high-concentration products.
-
Model the trade-offs between centralized supply and on-site generation. In many cases a hybrid approach — strategic bulk supply with on-site generation backup at critical nodes — optimizes resilience and cost. Our scenario tools in the full report quantify break-even thresholds for capitalized on-site systems versus contracted supply.
-
Institute a supply-concentration watch. While market concentration leaves room for negotiation, the specialized nature of low-impurity products creates pockets of supplier-specific risk. Build contract clauses that protect buyers (quality guarantees, remediation pathways, and volume-flex terms).
-
Prioritize regulatory match: where potable water certifications or low-impurity specifications are mandated, choose suppliers with documented certifications and independent test data to expedite compliance and approvals.
How PW Consulting supports your 2026 playbook
PW Consulting combines market modelling, supplier intelligence, and operational playbooks to accelerate procurement and technology decisions. The full LSSH report delivers the detailed inputs you need to:
-
Construct supplier scorecards and run tender scenarios that include purity-driven premiums.
-
Quantify pilot economics and project payback for switching to high-strength low-salt formulations or investing in on-site generation.
-
Design contract language and stewardship requirements that reduce transition risk and ensure continuity of service.
We intentionally limit this preview to strategic signals and select supplier insights to preserve the actionable, segment-level intelligence in the full report. If your 2026 plan includes supplier requalification, pilot roll-outs, or capital allocation for generation technology, the detailed scenario outputs, supplier dossiers, and operational templates in the full PW Consulting study will be essential.
Next steps
-
For procurement teams: request the supplier dossier package and stewardship checklist to start RFP revisions.
-
For operations leaders: download the pilot design template to capture dosing and lifecycle performance metrics in your next season.
-
For strategy and M&A teams: access the concentration and scenario modules to identify acquisition targets and partnership opportunities within the specialty LSSH value chain.
PW Consulting’s Low Salted Sodium Hypochlorite Market report is modelled on a 2025 base year, covering historical trends back to 2020 and providing scenario-based forecasts through 2032. It integrates verified field evidence, supplier stewardship documentation, and technology assessments to help you make lower-risk, higher-return decisions in 2026. Request the full report to obtain the complete datasets, supplier scorecards, and executable templates referenced here.
For detailed analysis of this topic, please visit the official page: Low Salted Sodium Hypochlorite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com