

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bluetooth Audio IC Market Tops USD 6.72 Billion in 2025 — Asia‑Pacific Leads with USD 2.94B as 11.85% CAGR Fuels Growth Through 2032

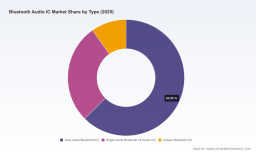
Bluetooth Audio IC Market: Strategic Imperatives for 2026 — PW Consulting Announces New Market Intelligence Brief
PW Consulting today releases an executive preview of our forthcoming Bluetooth Audio IC Market report (base year 2025), designed to equip senior executives, product strategists, and corporate development teams with the insight required to make high-consequence decisions in 2026. The global market for Bluetooth audio ICs has accelerated materially over the past five years and is forecast to maintain robust expansion through the end of this decade. Our analysis synthesizes market sizing, competitive positioning, supply-chain stress-tests, and actionable go-to-market playbooks — while reserving detailed segment-level figures to the full report to preserve the strategic value of the underlying intelligence.
Bluetooth Audio Ic Market
Headline market trajectory: scale, velocity, and implications
Bluetooth audio IC demand moved from an estimated USD 3,820.5 Million in 2020 to USD 6,720.0 Million in 2025, reflecting rapid adoption across hearables, personal audio, and a growing set of smart-speaker and automotive use cases. PW Consulting projects the market will continue to scale, reaching approximately USD 7,763.21 Million in 2026 and expanding toward USD 14,717.08 Million by 2032, underpinned by a compound annual growth rate of roughly 11.85% over the forecast window.
Bluetooth Audio Ic Market
For 2026 planning cycles, this trajectory translates into three critical operational realities:
Bluetooth Audio Ic Market
- Product roadmaps must align to accelerating unit volumes and evolving standards (notably Bluetooth 5.4 and LE Audio), or risk losing time-to-market advantages.
- Supply-chain agility — from wafer sourcing through packaging — will increasingly determine margin resilience as demand scales.
- Consolidation and platform-deepening by leading IC vendors will compress competitive windows for smaller entrants unless differentiated on software/IP or niche performance characteristics.
What the report delivers: practical, executable intelligence
Our full report is structured to convert market insight into executable plans. Key deliverables include:
- Validated market sizing and scenario models (2020–2032) with selectable assumptions for adoption curves and price erosion to support sensitivity testing.
- Roadmaps for chipset capabilities across Bluetooth Classic, Bluetooth Low Energy (LE) Audio, and dual-mode architectures — highlighting where investment in LC3 codec, spatial audio, low-latency stacks, and power-optimized DSPs will matter most.
- Supply-chain risk matrix that quantifies exposure to geopolitical controls, lead-time variability (post-2023 normalization for mid-node CMOS), and packaging bottlenecks.
- Commercial playbooks for OEMs and ODMs: recommended sourcing mixes, co-development KPIs, and timing guidelines to align product launches with standards rollouts and promotional windows.
- Go-to-market recommendations for IC vendors including premiumization levers, captive-software strategies, and channel tactics to defend against white-label competition.
- M&A and JV target shortlist methodology with high-level investment return profiles and integration risk scoring.
To preserve the competitive utility of the report to subscribing organizations, we intentionally withhold the granular segmentation tables and regional/application-level revenue allocations in this public summary. The full dataset and the interactive model are accessible via the PW Consulting report portal.
Competitive landscape — who matters and why
The Bluetooth audio IC space remains concentrated, with the leading three and five suppliers commanding a notable portion of market value. Market concentration enables platform owners to set de facto expectations for software ecosystems, codec support, and reference designs — factors that increasingly determine downstream OEM choices.
Our qualitative and quantitative competitive assessment highlights several strategic profiles:
- Qualcomm (San Diego, CA) — A market leader with deep software-radio integration and a compelling premium portfolio (Snapdragon Sound, aptX Adaptive, and LE Audio-capable families). Qualcomm’s strategy centers on vertical differentiation through proprietary audio pipelines and broad reference design programs that shorten OEM development cycles.
- Realtek Semiconductor (Hsinchu, Taiwan) — Competitive on cost and integration, Realtek’s Bluetooth audio SoCs are positioned to win high-volume hearable programs where price-performance and ANC capabilities are critical.
- Airoha Technology (Zhubei City, Taiwan) — Focused on premium TWS experiences with ultra-low latency and AI-driven noise cancellation; Airoha’s certification wins in LE Audio underscore its relevance for higher ASP segments.
- BES Technic (Shanghai, China) — Rapidly scaling in high-fidelity and low-power segments, BES is notable for advanced ANC and spatial audio implementations that target both premium and aspirational price tiers.
- Nordic Semiconductor (Trondheim, Norway) — A leader in Bluetooth LE Audio enablement with strong developer ecosystems for hearables and smart-speakers, particularly where LC3 codec support and low-power operation are mission-critical.
- Espressif Systems (Shanghai, China), Texas Instruments (Dallas, TX), and STMicroelectronics (Geneva, Switzerland) — Each offers differentiated propositions spanning integrated Wi‑Fi/Bluetooth combos, low-power audio stacks, and embedded MCU+BLE solutions that appeal to IoT audio and gateway applications.
PW Consulting’s vendor scoring model evaluates firms across technical roadmap alignment, reference design maturity, software ecosystems, pricing power, and customer diversification. Recent product announcements and certifications — such as Qualcomm’s QCC7226 LE Audio SoC launch (Feb 2024), BES Technic’s ultra-low power sampling (Jan 2024), and Airoha’s LE Audio qualifications (Dec 2023) — are mapped to our adoption scenarios to help clients decide partnership and sourcing priority for 2026.
Regulatory, supply, and standards context — implications for 2026 decisions
Strategic planning for 2026 cannot ignore macro drivers beyond pure demand-side forces:
- Standards evolution: Bluetooth 5.4 and the industry-wide LC3 codec mandate reshape performance baselines and interoperability requirements. OEMs that lag in LE Audio enablement risk higher lifecycle costs and reduced consumer appeal.
- Geopolitical trade measures: Export controls on advanced manufacturing equipment and selective tariffs have materially increased the operational complexity of cross-border supply chains. Our report provides decision trees to evaluate onshoring versus diversification for wafer, packaging, and test services.
- Fabrication and lead-time dynamics: After the acute shortages of 2020–2022, mid-node (e.g., 40nm) lead times stabilized in a 12–16 week range. That normalization reduces some short-term pressure but still requires disciplined inventory strategies for tier-one programs.
- Commercial policy risks: Tariff regimes and regulatory redlines (e.g., controls affecting equipment or finished IC exports) require proactive contract clauses, dual-sourcing arrangements, and contingency inventory buffers to protect launch timelines.
Strategic recommendations for 2026 — five imperatives
From our scenario work and vendor mapping, PW Consulting recommends five strategic moves for market participants planning 2026 investments:
- Prioritize LE Audio and LC3 enablement in all new product specs. Timeline alignment with standards adoption will determine which SKUs can command higher ASPs and longer revenue tails.
- Implement a two-track sourcing strategy: secure long-lead wafers through contractual commitments while qualifying alternative foundries and packaging houses to mitigate geopolitically driven disruptions.
- Invest in software IP and reference implementations that raise switching costs. Codec optimization, ANC tuning suites, and companion mobile apps are as decisive as baseband performance for end-user perception.
- Reassess go-to-market price ladders and after-sales monetization (firmware upgrades, codec licensing, feature bundles) to offset expected hardware price deflation as volumes scale.
- Use industry consolidation as an opportunity: target acquisitions or strategic JVs that fill gaps in RF expertise, low-power DSPs, or certification labs — accelerating time-to-market and reducing integration risk.
How PW Consulting supports 2026 decisions
We combine proprietary forecasting models, a live competitive database, and a decision analytics workbench to deliver outcomes-oriented support — from sourcing negotiation playbooks to M&A diligence packages. The full Bluetooth Audio IC Market report includes: the complete downloadable dataset (2020–2032), the editable Excel model for scenario testing, vendor scorecards with reference design maps, and a confidential shortlist of acquisition targets prioritized for ROI and integration ease.
This public brief intentionally omits granular regional and application-level revenue allocations to preserve the strategic leverage of the complete analysis. Executives seeking the segmented revenue tables, interactive models, and bespoke advisory engagements are invited to access the full report through the PW Consulting portal or contact our industry team for a private briefing.
Key takeaways
- Market scale and momentum are undeniable: from USD 3.82B in 2020 to USD 6.72B in 2025, with continued expansion forecast into 2032.
- Standards, software ecosystems, and supplier concentration will shape who captures the most value as the market grows.
- Proactive supply-chain and IP strategies are essential to secure 2026 product launches and to sustain margin resilience.
- PW Consulting’s report translates these dynamics into executable decisions — from product timing to partnerships and M&A — that materially affect competitiveness in 2026 and beyond.
To request the full report, schedule a private briefing, or license the dataset and model, please visit our website or contact PW Consulting’s Bluetooth Audio practice. Detailed segmentation, the interactive forecast model, and supplier scorecards are available to subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Bluetooth Audio Ic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com