

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: End‑Stage Renal Disease Market Poised to Reach USD 305.4 Billion by 2032

End Stage Renal Disease Market 2026: Strategic Imperatives from PW Consulting
Executive summary
PW Consulting's latest End Stage Renal Disease (ESRD) Market report—anchored on a 2025 base year and delivering a 2026–2032 forecast—translates complex industry signals into clear action for executives planning their 2026 strategies. The global ESRD market demonstrated sustained expansion through 2020–2025 and reached approximately USD 152,306.5 Million in 2025. Under our base forecast, the market is expected to grow at a compound annual growth rate (CAGR) of about 10.45% across the 2026–2032 horizon, roughly doubling toward the end of the period. This trajectory and the competitive dynamics we observed make 2026 a pivotal year for decisions on product rollout, capital allocation, partnership formation, and regulatory positioning.
End Stage Renal Disease Market
Why this report matters for 2026 decision-making
-
Timely market inflection: After a period of incremental growth, the ESRD market is entering a phase where technology adoption, reimbursement changes, and delivery-model innovation converge. Companies that align product development and commercialization plans with these inflection points will capture disproportionate share.
End Stage Renal Disease Market -
Revenue-risk calibration: Our modeling quantifies upside scenarios for accelerated home-dialysis adoption and capital-substitution across care settings, as well as downside exposures tied to policy or reimbursement shocks. These scenario outputs are designed to inform 2026 budgeting, M&A valuation assumptions, and partnership term sheets.
End Stage Renal Disease Market -
Competitive clarity without overload: We synthesize market concentration indicators—showing a notably concentrated top-tier—and map the strategic moves of incumbent and challenger players, providing an actionable view of where white space exists without publishing our proprietary sub-segment tables in this release.
Market dynamics shaping 2026 strategy
The ESRD market's near-term runway will be shaped by three interlocking dynamics: technological innovation in dialysis systems and consumables; payment and policy adjustments; and service-delivery transformations that favor hybrid and home-based modalities.
-
Technology and product cycles: Recent regulatory clearances and product launches are accelerating refresh cycles for hemodialysis and home-dialysis platforms. Notable commercial moves include a planned 2026 US commercial roll-out of a high-volume hemodiafiltration platform from an established global vendor, and an early-2026 FDA clearance for a next-generation all-in-one hemodialysis system emphasizing cybersecurity and enterprise connectivity. These developments lower the technical entry barriers to integrated, digitally-enabled care pathways and create windows for complementary consumable and service offers.
-
Reimbursement and policy: The CY 2026 ESRD Prospective Payment System final rule formalized adjustments to the base rate and maintained key structural parameters such as the labor-related share and wage-index protections. The continued bundling of certain renal therapeutics into the PPS and alignment of certain acute dialysis rates with the ESRD base rate are immediate inputs into provider economics. PW Consulting’s scenario work demonstrates how even modest payment updates can materially affect facility-level margins and shift incentives toward home modalities and outpatient migration.
-
Service delivery evolution: Payors and large dialysis providers are actively testing value-based care arrangements and integrated care models. These pilots, combined with growing interest in remote-monitoring-enabled home dialysis, will alter capital allocation and sales strategies—favoring vendors and services that reduce total cost of care and demonstrate reliable outcomes across the continuum.
Competitive landscape — who matters and why
The ESRD market remains concentrated, with the top three and top five firms commanding a material share of industry revenue—an important context for strategic entrants and investors. Incumbents bring scale in clinic networks, procurement, and regulatory expertise; challengers are differentiating through platform design, digital integration, and novel care models.
-
Global dialysis platform leaders: Established multinationals continue to leverage broad product portfolios and clinic footprints to defend share. Their strategic playbooks emphasize deep integration across devices, consumables, and services to lock in care pathways and long-term recurring revenue.
-
Specialized device and consumable manufacturers: Several Japan- and Europe-headquartered firms maintain strong technology positions in membranes, dialyzers, and bloodlines. Their competitive advantage lies in technical performance and supply reliability, and they are active partners to both clinics and hospital systems.
-
Innovative system vendors and challengers: A cohort of companies focused on compact, home-ready dialysis machines and modular systems are reshaping expectations for usability, deployment cost, and cybersecurity. Successful commercialization for these players depends on payor engagement and evidence generation in home and outpatient settings.
-
Large services providers: Operators with extensive outpatient center networks and integrated care-management capabilities are pursuing vertical strategies—bundling clinical services with proprietary devices and supply agreements. Their negotiations with suppliers and payors will be crucial determinants of technology adoption speeds.
PW Consulting’s report profiles each major player across clinical footprint, product roadmap, distribution advantages, and strategic intent—providing boardrooms with the intelligence needed to prioritize partnerships, defensive actions, or entry strategies. To preserve the competitive sensitivity of our commercial-level datasets we summarize directional positioning in this release while reserving detailed competitor scorecards and supplier matrices for the full report.
Strategic implications by stakeholder
-
For device manufacturers: Prioritize interoperability, cybersecurity, and outcome-focused evidence generation. Competitive differentiation in 2026 will be defined by systems that reduce staffing complexity and enable secure remote management.
-
For consumables suppliers: Focus on supply-chain resilience and value-based contracting. Vendors that offer bundled solutions supporting lower total cost of care will gain traction with large service providers and payors.
-
For dialysis service operators: Revisit capital-allocation frameworks to balance investment in new in-center technologies with expansion of home-dialysis capacity. The 2026 policy environment favors operators that can demonstrate improved outcomes while managing unit economics under the PPS framework.
-
For payors and investors: Integrate provider-level scenario analyses into underwriting and portfolio construction. The market’s consolidation and the pace of home-dialysis adoption create both M&A opportunities and execution risk—detailed stress-testing in our report helps quantify these pathways.
What the PW Consulting ESRD Market report delivers
Our report is built for executive decision-making. Key deliverables include:
-
Market sizing and seven-year forecasts (2026–2032) with base-year anchoring and sensitivity scenarios that reflect alternative technology-adoption and reimbursement pathways.
-
Commercially actionable go-to-market playbooks for device OEMs, consumables manufacturers, and services providers—covering pricing architectures, channel design, and partnership templates.
-
Regulatory and reimbursement impact modeling that translates rules and rate updates into facility-level P&L implications under multiple operational assumptions.
-
Competitive intelligence dossiers on principal industry participants, including assessments of product roadmaps, clinic footprints, and strategic levers—alongside a proprietary opportunity matrix highlighting white-space by capability.
-
Investment and M&A framework with valuation overlays and integration risk checklists for acquirers and PE sponsors evaluating targets across the ESRD continuum.
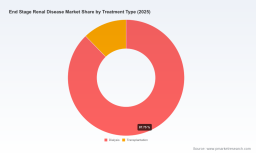
To maintain the utility of this press release as a strategic prompt—and in line with our “trailer” principle—we are intentionally omitting the granular sub-segmentation tables, region-by-region breakdowns, and detailed revenue-by-treatment schedules from this summary. These are available within the full report and accompanying data pack.
Recent developments and near-term signals
-
March 2026: A leading global dialysis manufacturer published its 2025 annual report and confirmed plans for a full commercial launch in the US of a high-volume hemodiafiltration system in 2026. This introduces a new competitive axis around HVHDF capabilities in markets where clinical adoption is rising.
-
January 2026: A prominent innovative-system vendor received FDA 510(k) clearance for a next-generation hemodialysis platform emphasizing enhanced enterprise-level security and connectivity, with a planned Q2 2026 launch—an important development for hospital and home-integration strategies.
-
November 2025: The US CMS released the CY 2026 ESRD PPS final rule, updating base payment parameters and preserving key structural features of the payment bundle—affecting facility economics and payer-provider negotiations in 2026.
How to use this intelligence in Q1–Q4 2026 planning
-
Start with scenario triage: Use our three-point scenarios (base, upside, downside) to test capital projects, R&D prioritization, and sales-coverage redesigns. Even modest shifts in modality mix materially change ROI timelines.
-
Design modular contracting pilots: Structure early 2026 contracts to include outcome clauses and volume-flex terms that de-risk launches for both suppliers and operators.
-
Invest in evidence generation: Prioritize prospective studies and real-world pilots that demonstrate reduced hospitalization and resource utilization—data that payors and integrated operators will demand when negotiating broader rollouts.
-
Anticipate consolidation vectors: Use our M&A playbooks to prepare for both buy- and sell-side scenarios; mid-market consolidation is likely to accelerate once new platform deployments demonstrate predictable economics.
Accessing the full report
The PW Consulting End Stage Renal Disease Market report contains the complete datasets, proprietary segmentation, competitor scorecards, and customizable financial models referenced in this briefing. For boards, corporate strategy teams, and investors planning 2026 actions, the full report is designed to be an operational blueprint rather than a descriptive summary. Visit our report page to request the full study, data pack, and a complimentary briefing session with PW Consulting’s lead ESRD practice analysts.
PW Consulting remains committed to translating industry complexity into executable strategy. In an industry where clinical, technological, and policy shifts converge, timely intelligence and pragmatic playbooks will distinguish winners in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: End Stage Renal Disease Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com