

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Aerial Inspections Service Market Set to Expand at a 13.5% CAGR, Fueling UAV and Drone Growth

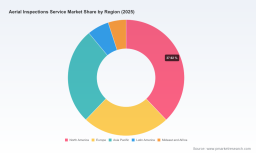
Aerial Inspections Service Market: A 2026 Strategic Preview for Decision-Makers
As PW Consulting’s lead industry analyst, I present a high-level strategic briefing drawn from our forthcoming Aerial Inspections Service Market report (base year 2025). The market has accelerated into the mainstream of capital-intensive sectors — energy, utilities, infrastructure, agriculture and industrial operations — and now demands board‑level attention. From USD 7.45 billion in 2020 to USD 14.5 billion in 2025, the market is forecast to continue expanding at a robust compound annual growth rate (CAGR) of 13.5% through our 2026–2032 projection window, reaching roughly USD 35.18 billion by 2032. This trajectory creates both immediate opportunities and mid-term strategic imperatives for enterprises, investors, and public-sector planners preparing decisions in 2026.
Aerial Inspections Service Market
Why 2026 Is a Pivotal Year
2026 is the inflection year where technology maturity, regulatory evolution, and procurement economics converge. Rapid improvements in AI analytics, autonomy and sensor miniaturization are reducing the marginal cost and lead time of inspections, while regulatory moves (notably evolving FAA policy on BVLOS and enforcement programs such as DETER) are reshaping risk profiles and operational constraints for commercial operators. For organizations planning 2026 budgets and three‑to‑five‑year roadmaps, the question is not whether to invest in aerial inspections, but how — and with whom.
Aerial Inspections Service Market
Market Trajectory and Strategic Implications
-
Scale and speed: The market doubled from 2020 to 2025 and is poised to more than double again by 2032 under a 13.5% CAGR. This pace signals a transition from niche pilots to standardized enterprise workflows for asset inspection and condition monitoring.
Aerial Inspections Service Market -
Cost arbitrage: Empirical industry benchmarking indicates drone-based industrial inspections can reduce operational costs by 30–70% and compress inspection time by 75–85% versus traditional manual methods that require scaffolding, rope access, or plant shutdowns. That delta is driving rapid payback for capital and operating expenditure reallocation.
-
Fragmentation with pockets of influence: Market concentration remains relatively low; the top three and top five providers account for modest shares, creating fertile ground for strategic partnerships, regional rollouts, and M&A to secure scale in targeted verticals.
-
Unit economics and pricing dynamics: Commercial service pricing varies by scope and sensor mix — for example, roof and building inspections market benchmarks range from roughly USD 150–500 per property, or USD 200–700 per hour for thermal-enabled inspections. Buyers must normalize these rates against risk-adjusted labor and reinstatement costs for traditional methods.
What the PW Consulting Report Delivers (Practical, Executable)
Our report is designed as a decision support toolkit for 2026. It combines market sizing and scenario forecasts with operational playbooks so executives can move from strategy to execution without wading through raw data alone. Key deliverables include:
-
Decision frameworks that map inspection objectives (safety, uptime, predictive maintenance, compliance) to recommended technology stacks (rotary-wing drones, fixed-wing UAVs, manned overflights, satellite/remote sensing) and procurement pathways.
-
ROI and TCO models with adjustable levers — inspection frequency, sensor portfolio, internal vs. outsourced flight ops, data processing cadence — enabling finance teams to stress-test CAPEX/OPEX scenarios.
-
Operational playbooks covering governance, pilot competency and certification, BVLOS permitting strategy, data security, and integration points with asset management systems (EAM/CMMS/BIM).
-
Vendor assessment matrix and negotiation playbook: comparable scorecards, contract clauses to mitigate liability, SLAs for data quality and delivery latency, and benchmarks for pricing and managed-service terms.
-
Field‑proven use cases and migration roadmaps for tiered adoption — from trial pilots and center‑of‑excellence formation to enterprise rollout and cross‑asset standardization.
Competitive Landscape — Strategic Takeaways
The supplier ecosystem is multi‑modality and geographically distributed: established drone-inspection specialists, enterprise software platforms, wind‑turbine focused automation firms, and traditional aerial surveyors with expanding drone divisions. Several illustrative strategic profiles inform our assessment:
-
Cyberhawk (Edinburgh, UK) : A leader in drone-based asset inspection and aerial data management, Cyberhawk’s extensive asset portfolio and platform capabilities make it a natural partner for energy and heavy industry clients seeking end‑to‑end service continuity. Recent contract renewals with major operators underline their strength in long‑cycle maintenance programs.
-
DroneDeploy (San Francisco, USA) : With a robust reality-capture platform and accelerating enterprise adoption, DroneDeploy’s 2026 product releases and large-scale project partnerships reflect a play to be the digital backbone for construction, infrastructure and enterprise site standardization. Expect continued emphasis on integrations and performance at scale.
-
SkySpecs (Ann Arbor, USA) : Focused automation and vertical specialization (wind) combine with AI-driven analytics to deliver differentiated value in a niche where uptime and blade-level diagnostics drive revenue. Their proposition is attractive to asset owners seeking prescriptive maintenance insights rather than raw imagery.
-
Terra Drone (Tokyo, Japan) : Global service reach and diversification into defense-capable operations expand addressable markets. Their model suits organizations with complex regulatory footprints and cross-border assets.
-
Raptor Maps, SAM, AERIUM Analytics, Measure and other regional specialists: These providers offer deep domain expertise (solar farms, LiDAR surveying, industrial analytics, enterprise engagements) that make them strong regional partners or acquisition targets for scaling integrators.
Recent market moves — expanded multi‑year enterprise agreements, software performance releases, and division launches focused on offshore or subsea operations — indicate vendors are competing on platform capability, data velocity, and industry‑specific service packaging. For buyers, this means procurement evaluation should prioritize interoperability, analytics maturity, and proven SLAs over raw flight-hour cost alone.
Regulatory and Operational Dynamics
-
Regulatory evolution: Baseline certifications (e.g., FAA Part 107) remain foundational, but 2026 enforcement and policy initiatives — accelerated violation resolution programs and proposed BVLOS rule changes — materially affect operational timelines and risk registers. Organizations must fund regulatory affairs and legal engagement as part of program planning.
-
Operational readiness: Achieving the promised 30–70% cost reductions requires investments in data pipelines, analytics, and change management. Expect a two‑to‑three quarter ramp from pilot to dependable operational cadence for most enterprise implementations.
-
Labor and skills: Specialist pilot labor and thermal inspection expertise are priced at a premium. Procurement strategies should consider blended models where specialized tasks are outsourced while routine data capture is insourced or automated.
Actionable Recommendations for 2026 Decision-Makers
-
Prioritize a “use-case first” approach: Start with critical assets where inspection frequency, safety risk, or replacement cost creates the clearest ROI. Use PW Consulting’s TCO templates to quantify decision thresholds before scaling.
-
Lock in a two‑tier supplier architecture: one partner for platform/data management and another (or validated roster) for flight ops and subject-matter inspection. This reduces vendor lock‑in while ensuring redundancy and coverage.
-
Invest 5–10% of first‑year program savings back into data engineering: the long‑term value resides in analytics and integration with maintenance workflows, not only in reduced flight hours.
-
Engage regulatory pathways proactively: allocate resources for BVLOS waivers or equivalent approvals where necessary, and incorporate compliance milestones into procurement timelines to avoid rollout delays.
-
Consider inorganic options selectively: given the fragmented market and modest top‑tier concentration, targeted acquisitions or equity partnerships can rapidly secure domain expertise or geographic presence, particularly in offshore wind, solar operations, or critical infrastructure segments.
How to Use This Report in Your 2026 Planning Cycle
This briefing is intended as the strategic prelude; the full PW Consulting Aerial Inspections Service Market report provides the granular datasets, vendor scorecards, customizable financial models, and procurement templates necessary to operationalize the recommendations above. Use the report to:
-
Inform capital allocation decisions and build multi-year budgets aligned with expected savings and risk mitigation benefits.
-
Accelerate procurement cycles with ready-made RFP language and negotiation checklists focused on data SLAs and integration requirements.
-
Benchmark internal capability against vendor capabilities and industry KPIs to prioritize training, hiring, or outsourcing.
Closing: The Strategic Imperative
By 2026, aerial inspection services are no longer an experimental add‑on; they are a strategic lever that materially affects asset reliability, safety, and lifecycle economics. Our market forecast — reflecting sustained double‑digit growth and significant operational cost advantages — suggests that organizations delaying structured investment risk ceding efficiency and data leadership to faster-moving peers. PW Consulting’s full report is designed to convert market opportunity into executable programs: rigorous, vendor‑agnostic, and oriented to measurable performance outcomes. For executives preparing budgets, procurement cycles, and M&A priorities in 2026, this is the practical intelligence to act on — and the foundation for a defensible competitive position in the decade ahead.
For detailed analysis of this topic, please visit the official page: Aerial Inspections Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com