

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Commercial Small Batteries Market to Expand at 6.79% CAGR, Reaching USD 23,108 Million by 2032
By pmarketresearch, 2026-07-07
Commercial Small Batteries Market 2026 Strategic Briefing — PW Consulting
PW Consulting’s new market intelligence on the Commercial Small Batteries Market has been produced to equip executives with the forward-looking, decision-ready analysis necessary for 2026. Our base-year market sizing shows a market of USD 14,580 Million in 2025. Built on a consistent historical series and scenario modelling, the analysis demonstrates a compounded annual growth rate (CAGR) of 6.79% across the forecast window, with the market trajectory pointing toward materially higher scale by the end of the decade. This briefing highlights the strategic takeaways from the full report, the practical modules included, and the near-term actions corporate leaders should prioritize — while preserving the report’s proprietary segmentation and tactical tables to encourage direct access to the full intelligence package.
Commercial Small Batteries Market
Why this matters for 2026 decision-makers
-
Demand inflection and margin pressure converge: Commercial small batteries are transitioning from a stable commodity to a value-rich product class defined by performance, regulatory compliance and upstream volatility. From a buyer and OEM perspective, the near-term imperative is balancing product differentiation with cost control.
Commercial Small Batteries Market -
Regulation and safety are no longer niche compliance items: New standards and supplier obligations are raising the bar on product design, labeling, and extended producer responsibility. These have direct implications for time-to-market and packaging/assembly costs.
Commercial Small Batteries Market -
Concentration and competitive positioning matter: The market shows a moderate level of concentration among the largest producers. Our competitive concentration analysis signals both defensive moves by incumbents and opportunistic entry points for specialized suppliers and regional champions.
-
Raw-material volatility is a strategic risk: Price swings in key feedstocks propagate into procurement, pricing and product roadmaps — requiring companies to embed commodity scenarios into commercial planning.
What the PW Consulting report delivers — practical, operational intelligence
-
Proprietary market sizing and validated forecasting: A transparent methodology with scenario envelopes that capture base, upside and downside outcomes for the 2026–2032 window. We present topline market trajectory, drivers and leading indicators to watch, without disclosing the proprietary sub-segmentation matrices in this release.
-
Supplier and competitor playbooks: Strategic profiles and capability maps for the market’s leading firms, with actionable recommendations for partnering, co-development, and competitive defense. Profiles cover manufacturing footprint, product breadth, and commercial strengths.
-
Go-to-market frameworks for OEMs and distributors: Tactical playbooks for channel selection, pricing architecture, private-label vs. branded strategies, and bundling options that protect margin while accelerating adoption in commercial channels.
-
Procurement and cost-modelling toolkit: A downloadable, parametric cost model that lets procurement teams run sensitivity tests (including commodity price swings, freight, and regulatory compliance costs) and derive contract breakpoints and hedging alternatives.
-
Regulatory and safety compliance checklist: Step-by-step remediation paths to comply with new and evolving standards and requirements relevant to small and button/coin cells, including packaging and ingestion-risk mitigations.
-
M&A and partnership screening matrix: Criteria and scorecards for identifying bolt-on targets, strategic JV partners or contract manufacturers that can close capability gaps in chemistry, safety testing or geographic reach.
-
Case studies and supplier negotiation templates: Real-world examples of cost takeout, speed-to-market accelerations, and safety-driven design changes that materially reduced product risk or opened incremental commercial channels.
Key dynamics shaping 2026
-
Commodity swings: Lithium carbonate exhibited significant volatility in 2025 — rebounding sharply during the second half of the year — and is expected to remain in a wide trading band through 2026. PW Consulting’s procurement scenarios explicitly model a range of price outcomes and their pass-through to small lithium battery production costs.
-
Regulatory tightening: A combination of new standards and updated regulations is changing product design constraints. Notable developments include UL 4200A addressing physiological hazards from button and coin cells, the updated IEC safety provisions for primary button cells, and regional batteries regulations that increase labeling and producer obligations. These translate into longer product qualification cycles and higher compliance costs if not actively managed.
-
Safety-first product evolution: Child-ingestion risk has catalyzed both product-level and packaging innovations (mechanical barriers, bitter coatings, tamper-evident features). Vendors introducing these features are seeing faster acceptance in healthcare, medical device and other safety-sensitive end markets.
-
Commercial convergence and targeted innovation: Incumbent battery brands, diversified electronics manufacturers and industrial power specialists are expanding product sets to capture adjacent commercial use-cases — from IoT sensors to emergency lighting — increasing competition on product performance and lifecycle services.
Competitive landscape — who to watch and why
The report includes strategic profiles of the market’s primary participants and synthesizes their likely near-term moves. Among the names that executives should monitor closely:
-
Major global brands with deep retail and B2B channels — these firms continue to leverage brand trust and broad distribution to protect premium positions across multiple chemistries.
-
Japanese and European technology-focused manufacturers — players with capabilities in precision coin and micro cells are capitalizing on medical and high-reliability segments.
-
Industrial and backup specialists — firms serving UPS, standby and motive applications position differently from consumer-oriented suppliers, often competing on system integration and lifecycle services rather than unit-cost.
-
Regional and niche players — agile manufacturers are capturing specific commercial applications by optimizing local supply chains and compliance know-how.
Recent market developments underscore these dynamics: product line expansions by battery system manufacturers, global trade-show showcases of small-format battery technologies, and safety-driven product innovations such as bitter coatings for coin cells. These events are consistent with a market that is both expanding and maturing in terms of technical and regulatory complexity.
Actionable implications and recommended next steps for 2026
-
Embed commodity scenarios into commercial plans: Procurement and product teams should run three-tier commodity sensitivity tests (base/volatile/stretch) and translate outcomes into pricing contracts, pass-through clauses and inventory policy.
-
Prioritize compliance-readiness: Map product portfolios to emerging standards and regulations, and fast-track redesigns for SKUs targeting safety-sensitive channels. Delays in adaptation materially increase time-to-revenue.
-
Rebalance supplier strategies: Move from single-sourcing to a dual-track approach that secures capacity while enabling competitive price discovery. For high-risk chemistries, consider toll-manufacturing or captive production as hedges.
-
Invest in value-added differentiation: In commercial segments where safety, longevity and service matter, invest in certification, extended warranties and integrated lifecycle services to justify premium pricing.
-
Use M&A selectively to fill capability gaps: Targets with specific chemistry expertise, testing infrastructure or regulatory know-how can accelerate entry into higher-margin commercial subsectors.
-
Design a compliance-driven go-to-market timeline: Regulatory changes impose calendar constraints. Map certification timelines against product launches to avoid costly delays.
How PW Consulting’s intelligence supports your 2026 playbook
The full PW Consulting report packages market forecasts, supplier maps, tactical playbooks and procurement tools into a single deliverable calibrated for commercial decision-makers. It connects macro growth trajectories and concentration metrics with operational levers — from sourcing and manufacturing to product safety and after-sales service — enabling executives to convert market growth into sustainable margin expansion.
To preserve the commercial value of our proprietary segmentation, stratified scenarios and the detailed supplier scorecards, this briefing has intentionally avoided disclosure of core breakouts. Clients and stakeholders who need the full, actionable dataset — including region and application breakouts, chemistry-specific roadmaps, and downloadable cost-model assets — are invited to access the full report and accompanying tools on PW Consulting’s portal.
Next steps
-
Book a strategic briefing with PW Consulting to receive a tailored executive summary aligned to your portfolio and priority markets.
-
Request the procurement sensitivity model to run your own scenario tests against the lithium price bands, freight and compliance cost assumptions used in our base and stress cases.
-
Engage our M&A and partnership advisory to identify targets and construct integration roadmaps that preserve product integrity while accelerating market entry.
PW Consulting’s Commercial Small Batteries Market report is designed for senior executives, procurement leads, product managers and corporate development teams who must make confident, defensible decisions in 2026. With the market at a strategic inflection point — higher regulation, raw-material volatility, and demand for safer, differentiated products — firms that combine rigorous scenario planning with decisive operational moves will capture the disproportionate share of growth. Contact PW Consulting to access the full report and the complete dataset.
For detailed analysis of this topic, please visit the official page: Commercial Small Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water-Based Acrylic Emulsion Market Hits USD 11,081.6 Million in 2025; Poised for 6.09% CAGR Through 2032
By pmarketresearch, 2026-07-07
Water-Based Acrylic Emulsion Market: Strategic Outlook for 2026 — PW Consulting Industry Brief
As PW Consulting releases its latest industry study on the Water-Based Acrylic Emulsion market, this briefing highlights the strategic value the report delivers to executive teams planning for 2026. The market has shown steady expansion, growing from a base of roughly USD 8,450 Million in 2020 to about USD 11,082 Million in 2025. Our forecast model projects continued healthy growth into the coming decade, with the market reaching approximately USD 16,762 Million by 2032 under a compound annual growth rate (CAGR) of 6.09% for the 2026–2032 forecast window. These macro dynamics frame immediate tactical choices — from supply-chain resilience and product innovation to targeted commercial plays — that manufacturers, converters, and strategic investors must act on in 2026.
Water Based Acrylic Emulsion Market
Why this report matters for 2026 decision-making
-
Regulatory inflection points are compressing product lifecycles and procurement windows. Tighter VOC rules and permissive enforcement timelines mean reformulation and qualification cycles must accelerate; our report maps practical timelines and compliance levers that matter to procurement, product and regulatory teams.
Water Based Acrylic Emulsion Market -
Raw-material volatility and regional price divergence are raising margin risk. Strategic purchasing decisions made in 2026 will materially affect unit economics through 2027; the study includes scenario-based impact matrices to quantify those exposures and mitigation options.
Water Based Acrylic Emulsion Market -
Competitive positioning is shifting from scale-only advantages to combined capabilities in low-VOC, PFAS/APEs-free chemistries and bio-based content. The research identifies how participants can convert regulatory demand into differentiated commercial offers that command premium pricing.
Report—what’s inside (practical, actionable, but intentionally selective)
-
Executive decision frameworks: step-by-step guides for capex prioritization, short-listing technology partnerships, and accelerating product qualification with Tier-1 buyers.
-
Commercial playbooks: go-to-market templates tailored to coatings, adhesives, and specialty paper segments showing pricing levers, channel strategies, and sample objection-handling scripts for formulators and distributors.
-
Supply-chain stress tests: scenario models that translate raw-material swings and regional logistics disruption into margin and working-capital outcomes; includes hedging and dual-sourcing heuristics.
-
Technology & innovation roadmap: assessment of low-VOC, fluorosurfactant-free, and bio-derived resin readiness, with triage on short-, medium- and long-term R&D investments.
-
Regulatory compliance playbook: practical checklists and sample timelines aligned to recent EPA and state-level rules, helping ensure procurement, product and compliance teams hit critical milestones.
-
M&A and partnership diligence templates: valuation sensitivities for assets focused on specialty grades, regional capacity, or differentiated additive portfolios — designed for corporate development and private equity teams.
-
Supplier scorecards and procurement scripts: standardized templates for vendor evaluation covering technical performance, sustainability credentials, and supply resilience.
Market dynamics shaping 2026
-
Growth trajectory: The market’s steady rise from 2020 through 2025 establishes a robust base for continued expansion. With a projected CAGR of approximately 6.1% in the forecast horizon, businesses that align investments to mid-cycle demand expansion will capture disproportionate share gains.
-
Regulatory tailwinds: Recent tightening of VOC emission standards and accelerated compliance deadlines have elevated water-based acrylic emulsions as a compliance-first choice for many end-users. Simultaneously, PFAS- and certain surfactant-free requirements are increasingly de facto procurement standards rather than nice-to-haves.
-
Raw-material pressure and regional divergence: Acrylic acid and other upstream inputs remain the primary source of cost volatility. During late 2025 and into early 2026, industry conversations reflected downward price pressure in some regions while others experienced intermittent upward blips. This dynamic is motivating increased emphasis on cost-to-serve optimization and hedging strategies.
-
Consolidation pressure but room for specialty: Market concentration is meaningful among the top suppliers, with the largest five players controlling a material share of global supply. However, specialization — particularly around low-VOC, bio-based, and fluorosurfactant-free grades — continues to create margin-rich niches for agile players and innovators.
Competitive landscape — what the executive summary reveals
Our competitive analysis synthesizes corporate strategy, technology investments, and go-to-market execution across the leading producers. Rather than a rote ranking, the study profiles capability clusters and strategic plays observed across the industry.
-
BASF SE — Leveraging a broad portfolio and regional production investments, BASF blends scale with application-level R&D. Their emphasis on bio-based and low-VOC chemistries positions them strongly in regulated markets where technical validation cycles favor established suppliers.
-
Dow Inc. — Focused capacity expansions and next-generation low-VOC product introductions illustrate a strategy of pairing supply assurance with value-added formulations for construction and automotive end uses.
-
Arkema SA — Strategic partnerships to access fermentation-derived feedstocks and low-carbon intermediates highlight Arkema’s playbook: combine chemistry expertise with upstream sustainability partnerships to create differentiated, lower-carbon offerings.
-
The Lubrizol Corporation — Investment in production capacity and specialty grades signals a push to capture higher-margin, performance-driven segments where formulation complexity and service matter.
-
Celanese, Synthomer, and other regional specialists — These players compete on technical support, localized service footprints, and tailored grades for adhesives, paper, and industrial coatings markets. Many are moving quickly to eliminate legacy chemistries that no longer meet buyer sustainability checklists.
-
Smaller specialized manufacturers — Companies with deep formulation expertise and customer intimacy continue to win selective projects. Their advantages are speed, customization and the ability to provide end-to-end co-development for large customers.
Recent industry moves — capacity investments, new low-VOC launches, and strategic partnerships with bio-feedstock developers — reinforce a dual trend: incumbents defending scale while tech-focused players attack specialty niches. Our report includes profiles and strategy maps for each named participant to help executives quantify competitive threats and partnership opportunities.
Strategic implications and recommended actions for 2026
-
Prioritize rapid reformulation pathways: Make 2026 the year to complete technical requalification for low-VOC and PFAS/APEs-free grades for all strategic contracts. Delays will expose teams to lost sales and longer lead-times for qualification with national accounts.
-
Reassess sourcing strategies: Implement tiered supplier strategies that balance cost, sustainability credentials, and dual-sourcing where feasible. Use the supplied stress-test models to identify the minimum effective redundancy for critical SKUs.
-
Invest selectively in differentiated chemistry: Allocate R&D and targeted capex to grades that deliver verifiable end-user benefits (durability, dirt resistance, low-temperature film formation) and clear sustainability advantages.
-
Accelerate commercial playbooks: Equip sales teams with technical value propositions linked to regulatory compliance and total cost-of-ownership benefits; the report’s negotiation scripts and margin models reduce price erosion risks.
-
Pursue partnerships over greenfield where speed matters: For companies needing rapid access to bio-based intermediates or novel polymerization technologies, partnerships and licensing deals often beat the multi-year timelines for internal development.
-
Prepare M&A diligence in advance: Create pre-approved valuation frameworks and integration checklists tailored to specialty grades and regional assets to act quickly when targets surface in 2026.
How to use PW Consulting’s report in your 2026 planning cycle
-
Board-level strategy sessions: Use the macro forecasts and competitive scenarios to stress-test growth targets and capital allocation plans.
-
Product and R&D roadmaps: Prioritize projects by commercial readiness and margin uplift potential using our ranked fit-gap matrix.
-
Procurement and supply-chain: Adopt the report’s supplier scorecard and stress-test templates to build resilient sourcing strategies.
-
M&A and corporate development: Leverage the included diligence checklists and valuation sensitivities to accelerate decision cycles and limit execution risk.
Conclusion and next steps
The Water-Based Acrylic Emulsion market is at an operational and strategic inflection point as regulatory pressure, raw-material volatility, and a clear shift toward sustainability converge. With the global market expanding from a multi-billion-dollar base and an expected CAGR of ~6.1% across the 2026–2032 horizon, 2026 becomes the pivotal year to convert macro momentum into defensible market share and improved margin structures.
PW Consulting’s full report delivers the granular models, supplier diagnostics, and go-to-market playbooks that senior teams need to make high-confidence 2026 decisions. To access the complete dataset, detailed segmentation analysis, and company-level scorecards that support these strategic prescriptions, please visit the full report page on our website.
For detailed analysis of this topic, please visit the official page: Water Based Acrylic Emulsion Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Intelligent Automatic Warehouse and Logistic Equipment Market Set to Surge at a 12.04% CAGR Through 2032
By pmarketresearch, 2026-07-07
Intelligent Automatic Warehouse and Logistic Equipment Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research update for Intelligent Automatic Warehouse and Logistic Equipment is built as a decision-grade briefing for executives planning capital allocation, procurement, and capability buildout in 2026. Drawing on a validated historical series (2020–2025) and a forward-looking forecast window (2026–2032), the report synthesizes macro growth trajectories, supplier dynamics, technology inflection points, and near-term risk vectors into an actionable playbook. At the aggregate level the market reached approximately USD 35.6 billion in 2025 and is projected to expand to roughly USD 78.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of 12.04% across the forecast period — a scale and pace that make strategic timing and supplier choice critical for competitive advantage.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this preview matters for 2026
-
Capital planning windows closing in early 2026 must reconcile inflationary input costs, evolving ESG compliance, and the accelerating substitution of capital for recurring labor. This report frames those trade-offs with a quantified market trajectory and tactical investment levers.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Procurement and operations leaders face a fragmented vendor landscape where no single approach dominates — our analysis profiles the strategic sweet spots where integrators, software-first players, and robotics specialists deliver differentiated returns.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Systems integrators and OEMs preparing M&A, partnership, or distribution strategies will find scenario-based valuation sensitivities tied to macro and regulatory shocks, enabling defensible negotiation positions.
Market dynamics and near-term disruptors
The 2020–2025 period established the structural drivers that will determine winners and losers through 2032: e-commerce acceleration, persistent labor shortages, and the maturation of robotics and warehouse execution software (WES/WMS). In 2025, wage pressures in key logistics markets — for example, North American logistics wages having advanced materially over recent years — continued to push customers toward automation. Combined with energy and sustainability mandates in Europe and North America, buyers are prioritizing systems that lower total cost of ownership (TCO) through energy recovery, regenerative braking and power-optimized architectures.
At the same time, supply-side cost inflation is non-trivial. Rising prices for steel and aluminum and trade-policy shocks (notably a significant increase in tariffs affecting structural components) have raised upfront project costs and extended supplier lead times. The net effect is a shift in procurement preferences: a longer evaluation horizon, greater emphasis on modular retrofit solutions, and heavier negotiation around indexation clauses and supplier risk-sharing.
Technology inflection points to watch in 2026
-
Autonomous fleets and collaborative AMRs continue to converge with WMS/WES stacks, but the high-value opportunities are now in orchestration: multi-agent coordination, real-time congestion management and plug‑and‑play interoperability layers.
-
High-density AS/RS and cube-based storage technologies remain compelling where footprint and labor substitution dominate; however, system-level ROI is increasingly driven by integration with downstream sorting and last‑mile staging.
-
AI and predictive maintenance are moving from pilot to standard practice — expect measurable uptime improvements and deferred capex via condition-based replacement strategies for key mechanical assets.
Competitive landscape — consolidation, specialization, and partnership maps
The industry structure remains moderately fragmented (the top three players capture under one-fifth of the market; the top five account for roughly a quarter), which creates strategic space for vertical specialists and regional champions. Global systems integrators and OEMs each bring distinct advantages:
-
Long-established material handling firms have scale in high-throughput conveyor and AS/RS projects and continue to win large distribution center programs where end-to-end delivery risk matters.
-
Software-first automation vendors and AMR specialists are creating white-space through faster deployments, subscription models and modular upgrades that lower entry barriers for mid-market customers.
-
Robotics and AI-centric entrants are expanding the envelope on labor replacement and micro-fulfillment, particularly for e-commerce and retail fulfillment applications that prioritize cycle-time over maximum density.
Recent industry activity reinforces these patterns. Major suppliers displayed new product lines and integrated offerings at MODEX 2026; KNAPP and other vendors publicly detailed advances in multi-agent AI for fleet coordination earlier in 2026; and multiple automation conferences in early 2026 showcased integration patterns combining robotics, WMS, and energy-efficient subsystems. These events demonstrate that capability leadership now mixes mechanical engineering depth with agile software development and services economics.
What PW Consulting’s report provides — operational, not ornamental
We designed this study to be prescriptive for 2026 decision-makers. The deliverables emphasize implementable outputs rather than abstract models, including:
-
Decision frameworks for build vs. buy vs. partner, tied to customer size, throughput profiles and expansion roadmaps.
-
Procurement playbooks and RFP templates that embed indexation clauses, SLAs for uptime and spare-parts strategies aligned to current tariffs and input-cost volatility.
-
ROI and TCO modeling tools calibrated to 2025 baseline costs, energy efficiency scenarios, and labor-cost replacement curves — enabling rapid scenario comparison across multiple project horizons.
-
Technology roadmaps that sequence investments (e.g., WMS modernization, AMR pilots, full AS/RS deployment) to minimize operational disruption while maximizing throughput gains.
-
Supplier shortlists and integration risk matrices that map vendor strengths to project archetypes — from retrofit micro-fulfillment to greenfield high-throughput DCs.
-
Regulatory and materials-impact analyses, with mitigation strategies for tariff exposure and supply-chain substitution options.
To preserve competitive value for our subscribers, the report intentionally withholds granular regional and application-level revenue splits in this press summary. Those segmentation tables, vendor pairwise scoring matrices and project-level case studies are available in the full report and online portal.
Actionable recommendations for corporate leadership in 2026
-
Shift from CapEx-only ROI to blended CapEx/OpEx models: consider vendor financing, outcome-based service contracts and modular deployment to preserve cash while accelerating automation.
-
Prioritize interoperability and open APIs in procurement criteria — integration costs are now a larger share of project budgets than a few years ago.
-
Design pilot-to-scale pathways that lock in one performance metric (throughput, SKU mix, or energy reduction) per phase to avoid scope creep and allow rapid learning.
-
Embed tariff and input-cost clauses in supplier agreements and maintain alternative sourcing for critical structural components; negotiate lead-time guarantees with penalty/rebate mechanics.
-
Invest in people and process alongside automation: reskilling plans, cross-training and change-management reduce the ramp to full productivity and improve long-term resiliency.
How to use the report in the first 90–180 days of 2026
For boards and executive teams, the report is a structured input to capital allocation and M&A deliberations. For operations and supply-chain leaders, it becomes a tactical playbook: run a rapid supplier due-diligence round using the report’s vendor scorecards; run three scenario-TCO runs (conservative, base, aggressive) on any proposed automation project; and pilot a single AMR-enabled picking cell with tightly scoped KPIs that match corporate ESG and energy objectives.
Final perspective — risk, opportunity and the path to competitive differentiation
Automation investment in 2026 is not binary — it is a portfolio choice. The industry’s projected expansion through 2032 creates significant upside, but execution is nuanced: raw material inflation and elevated tariffs increase project sensitivity to engineering design choices and supplier resilience; energy and ESG imperatives create opportunities for systems that deliver both productivity and sustainability gains; and market fragmentation means that choice of partner will materially influence time-to-value.
PW Consulting’s report equips executives to convert market growth into strategic advantage: a repeatable investment playbook, a prioritized vendor roadmap and scenario-ready financial tools. For readers who require the granular segmentation, vendor scoring, and downloadable TCO templates that empower procurement and program teams, the full report and interactive dashboards are available on our report page.
To request the full report, data tables, or a tailored executive briefing that applies these findings to your specific network footprint and project queue, contact PW Consulting’s industry team via our website.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: At-Home Hair Removal Devices Market Poised to Expand at a 7.2% CAGR Through 2032
By pmarketresearch, 2026-07-07
At-Home Hair Removal Devices Market 2026: Strategic Imperatives from PW Consulting’s New Industry Deep Dive
Executive preview
PW Consulting’s latest market research on At-Home Hair Removal Devices provides an authoritative, action-oriented vantage point for executives preparing 2026 strategic plans. The global market reached USD 725.5 Million in our base year (2025) and is positioned to expand to approximately USD 777.7 Million in 2026, accelerating to an estimated USD 1,180.3 Million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 7.2% across the 2026–2032 forecast window, reflecting sustained consumer demand, technology diffusion, and regulatory maturation.
At Home Hair Removal Devices Market
Why this matters for corporate decisions in 2026
-
Timing matters: The market’s steady, above-market CAGR signals a window in which product launches, regulatory approvals, and channel investments can compound value quickly. Companies that align 2026 product roadmaps with validated safety and ease-of-use claims will accelerate adoption curves.
At Home Hair Removal Devices Market -
Regulatory clarity creates optionality: Recent regulatory activity is lowering barriers for credible entrants while imposing predictable compliance costs. Organizations that build regulatory strategy into product design and commercialization timelines will de-risk launch investments and access larger addressable segments faster.
At Home Hair Removal Devices Market -
Concentration and M&A signals: Market concentration is moderate—lead players hold meaningful shares but fragmentation persists—creating fertile ground for bolt-on acquisitions, strategic alliances, and private-label plays that can unlock scale economies or channel access in 2026.
-
Cost and supply-side pressures: Upward pressure on raw material and electronic component costs is compressing gross margins for manufacturers. Firms that prioritize supply-chain resilience and design-for-cost will protect margins even as pricing dynamics evolve.
Market dynamics: what the numbers tell us (and what we intentionally withhold)
Our topline market sizing provides a clear growth arc from 2023 through 2032. After the market’s recovery and expansion in the early 2020s, 2025 stands as a practical planning baseline (USD 725.5 Million) from which corporate 2026 budgets and resource allocations should be built. Forecasts show the sector growing to roughly USD 777.7 Million in 2026 and continuing to expand to more than USD 1.18 Billion by 2032 under a 7.2% CAGR.
While this release shares the high-level trajectory and underlying growth drivers, we intentionally limit disclosure of granular regional, technology and channel splits in this preview. The full report contains the detailed segmentations, sensitivity scenarios, and proprietary demand-models that corporate teams use to allocate R&D, CAPEX, and commercial resources with confidence.
Regulation, reimbursement and product safety: recent developments and implications
-
Regulatory pathway: At-home IPL and laser devices continue to be regulated as Class II medical devices in major markets that require 510(k) clearances for over‑the‑counter marketing. 2025–2026 has seen ongoing 510(k) activity that is validating new models and enabling market entry for established and emerging vendors alike.
-
Recent signals: Multiple manufacturers received 510(k) clearances for ice-cooling and other design enhancements in 2025. For corporate strategists, this trend means that technological differentiation—combined with clear, evidence-based safety claims—can be converted into commercial advantage more rapidly than in the prior decade.
-
Reimbursement reality: At-home hair removal remains predominantly cosmetic and is generally not covered by health insurers. Professional procedures may qualify for reimbursement under specific medical indications, but these are specialty cases. For most device manufacturers, ROI models should therefore assume predominantly cash-pay consumer demand.
-
Supply chain considerations: Rising costs for plastics, metals, and electronic components are non-trivial. Companies should prioritize dual-sourcing, negotiate long-term agreements, and explore design optimizations to reduce part counts and BOM costs without sacrificing safety or efficacy.
Competitive landscape: who’s shaping the market and what they’re doing
The competitive field blends heritage consumer-electronics brands, focused medical-device specialists, and nimble regional challengers. Key companies profiled in our analysis include:
-
Philips (Amsterdam, Netherlands) — A major incumbent offering the Lumea IPL series with SkinAI enhancements and multi‑attachment versatility. Philips leverages global brand equity and service networks to support premium positioning. ( https://www.philips.com)
-
Braun / Procter & Gamble (Kronberg im Taunus, Germany) — The Silk Expert Pro IPL devices emphasize adaptive skin-tone sensing for safety and consistent performance, grounded in consumer trust built over decades. ( https://us.braun.com)
-
Tria Beauty (San Leandro, California, USA) — A specialist distributor of diode‑laser at-home devices, offering higher‑power, clinical-grade laser technology targeted at customers seeking long‑term permanence. ( https://www.triabeauty.com)
-
Ulike (Hangzhou, China; R&D presence in Seoul) — Competitive advantage from cooling‑enhanced IPL systems designed for painless experiences, and aggressive digital marketing in Asia-Pacific markets. ( https://www.ulike.com)
-
Cyden Ltd / SmoothSkin (Swansea, UK) — Focused IPL product portfolio engineered for consumer adoption and broad retail distribution. ( https://www.smoothskin.com)
-
Remington (USA; owned by Spectrum Brands) — Longstanding consumer grooming brand presence with IPL product lineups targeting mainstream retail. ( https://www.remingtonproducts.com)
-
Silk’n (Home Skinovations; Israel) — Developer of IPL and alternative light-based at-home devices emphasizing compact design and price accessibility. ( https://silkn.com)
Collectively, the market shows a moderate level of concentration: the top three firms account for roughly one-third of the market, while the leading five capture close to half. That structure creates both defensive imperatives for incumbents and acquisition or niche‑opportunity pathways for challengers.
Strategic playbook for 2026: five concrete moves
-
Embed regulatory planning in product development: Allocate budget to preclinical testing and 510(k)-or-equivalent documentation early. First-to-market clearances for safety-enhancing design features (e.g., active cooling, skin-tone sensing) translate to durable shelf advantage.
-
Prioritize channel segmentation and digital-first go-to-market: E-commerce continues to be a dominant acquisition channel; however, hybrid strategies that blend online education, subscription consumables, and limited experiential retail create higher lifetime value.
-
Design for cost without diluting trust: Modular product platforms reduce SKUs and lower inventory risk. Standardize electronics across models; differentiate via software, attachments, and service.
-
Pursue tactical M&A and partnership plays: With moderate concentration, bolt-on acquisitions can deliver rapid access to geographic or technology niches. Consider partnerships with dermatology clinics and telehealth platforms to create hybrid care-to-consumer funnels.
-
Operational resilience and component strategy: Hedge exposure to commodity cycles via long-term supplier contracts, early component qualifying, and by exploring alternative materials or assembly geographies that preserve regulatory compliance.
What PW Consulting’s full report delivers (highly practical content)
This release is an executive preview. The complete report is an operational toolkit designed for 2026 decision-makers and includes:
-
Proprietary demand models (historical 2020–2025 and forecast 2026–2032) with scenario analytics to stress-test investment cases;
-
Segment-level playbooks across region, technology, and channel (note: granular segment data withheld in this preview to protect proprietary modeling and to direct stakeholders to the full report);
-
Regulatory pathway matrices and step-by-step 510(k) preparation checklists for teams planning U.S. launches;
-
Commercialization templates: sample launch plans, promotional mixes, and SKU rationalization frameworks tailored to different buyer personas;
-
Supplier risk heatmaps, BOM cost scenarios, and sourcing playbooks to preserve margins under raw material inflation;
-
Competitive benchmarking with strategic implications—detailed profiles, go-to-market tactics, and M&A targets;
-
Scorecards and KPIs for performance tracking post-launch—adoption metrics, unit economics, and churn drivers for subscription models.
Call to action
For senior leaders and product teams mapping 2026 strategy, the full PW Consulting report transforms high-level industry trends into executable programs. If your board is aiming to position for accelerated growth, mitigate regulatory and supply risks, and capture outsized share within the next 18 months, the full dossier contains the segmented forecasts, playbooks, and vendor-level intelligence necessary to move from intent to impact.
Contact PW Consulting to access the complete report and to schedule a strategy briefing. Our analysts will walk your leadership team through tailored scenario planning that uses the report’s proprietary models to quantify investment choices, prioritize markets, and sequence product and regulatory milestones for 2026 execution.
For detailed analysis of this topic, please visit the official page: At Home Hair Removal Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Automotive Connecting Rod Bush Market to Expand at a 3.82% CAGR During 2026–2032
By pmarketresearch, 2026-07-07
Automotive Connecting Rod Bush Market: A 2026 Strategic Preview
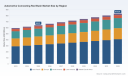
PW Consulting is pleased to release a strategic preview of our authoritative report on the Automotive Connecting Rod Bush market. Built from a rigorous base year of 2025 and a comprehensive historical window (2020–2025), the study projects the market from 2026 through 2032. At a macro level the market demonstrates steady expansion — rising from an estimated global revenue base of USD 642.5 Million in 2025 to an expected USD 835.28 Million by 2032, reflecting a compound annual growth rate (CAGR) of 3.82%. This preview highlights the report’s core practical value for boards, business unit leaders, product managers and corporate development teams making critical 2026 decisions, while reserving the granular sub-segment tables for the full report.
Automotive Connecting Rod Bush Market
Why this market matters to 2026 corporate strategy
-
Timing of structural decisions: The connecting rod bush segment sits at the intersection of engine efficiency improvements, emissions regulation pressure, and the aftermarket life-cycle of internal combustion engines (ICE). 2026 will be a pivotal year for decisions that lock-in sourcing, materials and aftermarket strategies for the next product cycle.
Automotive Connecting Rod Bush Market -
Predictable, durable growth: With a mid-single-digit CAGR through 2032, demand growth is consistent and high enough to justify targeted investments — yet not explosive enough to eliminate the need for disciplined portfolio prioritization.
Automotive Connecting Rod Bush Market -
Supply chain optimization opportunity: Incremental product and process innovation (materials, coatings, manufacturing tolerances) yields outsized returns in reduced warranty exposure, lower friction losses and improved fuel-efficiency metrics.
What our full report delivers (practical, operational outputs)
-
Actionable market sizing and forecasts. We provide a robust top-down and bottom-up view of global demand across 2023–2032, with scenario modelling for 2026 planning cycles. The preview above cites headline totals; full segment-level schedules, unit volumes and price assumptions are restricted to the full report.
-
Supply-chain heatmaps. End-to-end maps that expose concentration risks, single-source dependencies, and Tier‑2 raw material vulnerabilities for implementation planning.
-
Cost-to-serve and margin benchmarks. Product-level cost curves, manufacturing hour and scrap benchmarks and working-capital profiles designed for operational read-throughs by CFOs and plant managers.
-
Technology and materials playbook. Comparative analysis of bi-metal, tri-metal, aluminum and brass solutions — with recommended trials, test protocols and expected performance deltas under engine-relevant stressors.
-
Commercial and aftermarket strategies. Go-to-market blueprints for OEMs and aftermarket suppliers including channel segmentation, warranty-incentive structures, and parts-repair economics.
-
M&A and partnership screening. A pre-vetted shortlist of acquisition targets, JV structures and supplier consolidation scenarios tuned to 2026 budget cycles — along with integration risk checklists.
-
Regulatory and compliance tracker. A dynamic timeline of aviation and automotive directives that intersect with connecting rod bush design and replacement requirements, with impact scoring for product portfolios.
Competitive landscape — capabilities to watch in 2026
Our report maps market positioning across global OEM suppliers, regional specialists and high-performance niche players. Below we summarize the strategic posture of the manufacturers and suppliers that shape competitive dynamics:
-
MAHLE GmbH (Stuttgart, Germany) — A global engine components leader with deep OEM relationships. MAHLE’s strengths lie in high‑performance, low-friction designs and systems-level integration with internal combustion architectures. For strategic partners and challengers, MAHLE’s R&D cadence and OEM footprints present both a benchmark and a competitive moat.
-
Federal‑Mogul Motorparts (Tenneco) (Southfield, Michigan, USA) — Noted for aftermarket reach and extensive experience with bi-metal and tri-metal technologies. Federal‑Mogul’s dual OEM/aftermarket playbook is instructive for players seeking to balance margin stability with volume exposure.
-
King Engine Bearings (Israel) — A performance-focused supplier offering high-load capacity pin bushings and advanced low-friction surfaces. King’s technical orientation makes it a go-to for motorsport and high-performance OEM projects; a partner or acquisition target for firms seeking faster time-to-market on performance upgrades.
-
K1 Technologies (Ohio, USA) — Specialized in precise, engine-specific small-end bushings for North American V‑engine platforms. K1’s customer-aligned manufacturing and tight-tolerance expertise illustrate the value of localized, application-specific capability.
-
VIIPLUS (Zhejiang, China) — Leading supplier of bi‑metal solutions with scale manufacturing and cost-competitive delivery models; relevant for organizations evaluating dual-sourcing and scale economics.
-
BronzeLube, MYWAY, Raj Metal, AECO and Power Industries (China/India regional groups) — These regional manufacturers provide a range of bimetal/brass options and are central to aftermarket replacement flows and regional OEM programs. Their manufacturing breadth and catalog update cadence have implications for procurement and quality assurance programs.
For decision-makers, the takeaway is straightforward: incumbency rests on a mix of engineering IP, OEM certification depth and cost-competitive supply networks. Partnerships across these dimensions are often the fastest route to upgrading or defending a position in the supply chain.
Regulation, materials and dynamics shaping near-term decisions
-
Regulatory catalysts: Recent airworthiness directives and automotive emissions/fuel economy standards have direct engineering consequences. For example, aviation ADs requiring replacement of certain connecting rod bushings demonstrate how regulatory moves can suddenly accelerate aftermarket demand and influence OEM retrofit cycles.
-
Materials reality: The industry remains grounded in bi-metal steel-backed bronzes, high-tin aluminum alloys and brass formulations. Choices among these materials drive trade-offs in wear-resistance, thermal behavior and manufacturing cost. Our report quantifies expected life-cycle performance deltas and suggests where materials substitution yields net TCO advantages.
-
Aftermarket vs OEM balance: Catalog updates and repair-kit introductions from aftermarket leaders illustrate ongoing demand for reverse-engineered replacement parts. 2026 planning should treat aftermarket demand as a distinct profit pool with different margin dynamics and service requirements compared to OEM supply contracts.
Strategic implications and recommended plays for 2026
-
Prioritize dual-sourcing for critical alloys: Implement validated second-source suppliers for high‑wear alloys and back-up capacity for key manufacturing steps. Use supplier scorecards tied to delivery, fatigue performance and certification readiness.
-
Investment in friction-reduction R&D: Small coefficient-of-friction improvements compound into measurable fuel-economy and emissions benefits. Allocate a proportion of 2026 R&D budgets to advanced coatings, surface engineering and test-rig validation.
-
Commercialize aftermarket playbooks: Develop repair-kits and retrofit bundles aligned with regulatory replacement windows. Coordinate warranty and reverse-logistics approaches to capture rapid post-AD replacement opportunities.
-
Evaluate targeted M&A and partnerships: Pursue acquisitions that bring complementary metallurgy or OEM certifications rather than volume-only scale. Consider JVs in regions where local content and certification accelerate OEM entry.
-
Operationalize regulatory monitoring: Build a simple delegate-and-escalate mechanism to convert regulatory alerts into product action plans — with pre-authorized inventory and technical service teams on-call for mandatory replacements.
Practical 2026 implementation checklist (90–180 day horizon)
-
Run supplier resilience stress-tests focused on alloy availability and single-line production risks.
-
Kick-off a 90‑day friction-reduction test programme benchmarking two coating/material options on representative engine cycles.
-
Align aftermarket SKUs and packaging for rapid fulfillment tied to likely AD-triggered demand spikes.
-
Authorize a focused M&A diligence budget for one to two targets that add certification or metallurgy capabilities.
-
Deploy a regulatory watch dashboard flagging aviation and automotive directives with immediate product impact.
How to use this preview — and next steps
This preview is intended to orient leadership teams for the 2026 planning cycle. It showcases where durable, evidence‑based actions can improve competitive position while deliberately withholding granular sub‑segment matrices and tables that are proprietary to the full PW Consulting report. The complete study contains the detailed regional and application breakdowns, supplier share schedules, unit-price curves and a downloadable playbook that operational teams can execute from.
For boards, corporate development leads and plant executives preparing 2026 budgets: use the insights above to frame investment priorities, select pilot projects and scope supplier negotiations. For procurement and engineering teams: request the full report to obtain exacting supplier scorecards, test-protocol templates and expected unit-cost impacts by material and process.
To access the full intelligence set, including the proprietary sub-segmentation outputs and our executable 18‑month commercial plan, please visit the PW Consulting report page. The full dataset is curated to support immediate 2026 decision-making and includes interactive scenarios that translate macro CAGR and market-size trajectories into program-level financials.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Software Asset Management Managed Services Market Poised for 14.83% CAGR Through 2026–2032
By pmarketresearch, 2026-07-07
PW Consulting Strategic Brief: Software Asset Management Managed Service Market — What 2026 Decision‑Makers Must Know
Executive Preview
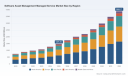
As enterprises confront accelerating software sprawl, opaque SaaS consumption and increasingly aggressive vendor audits, Software Asset Management (SAM) managed services have become a board‑level consideration. PW Consulting’s new market research — using 2025 as the analytical base year and projecting through 2032 — shows a resilient, high‑growth market propelled by hybrid IT adoption, SaaS subscription complexity and tightening regulatory obligations. The market has moved decisively beyond point solutions to managed services, and our analysis forecasts a compound annual growth rate (CAGR) of 14.83% across the 2026–2032 forecast window, lifting total spend from mid‑2020s levels into multi‑billion dollar scale by 2032.
Software Asset Management Managed Service Market
Why This Report Matters for 2026 Strategy
-
Timing: 2026 is a pivot year. Many enterprises that deferred SAM modernization during digital transformation are now facing simultaneous pressures — enterprise SaaS exposure, cloud cost overruns, and new privacy and data handling mandates. Decisions made in 2026 on governance, tooling and outsourcing will materially affect 2027 budgets and risk profiles.
Software Asset Management Managed Service Market -
Regulatory inflection: Recent US state privacy laws and federal rules (including the DOJ’s Bulk Data Rule effective 2025) increase the compliance burden for SAM providers and their clients. The report translates these legal shifts into operational requirements and vendor selection criteria to protect sensitive usage data without compromising discovery and optimization capabilities.
Software Asset Management Managed Service Market -
Vendor landscape and concentration: The SAM managed services marketplace is neither a commoditized long tail nor a closed oligopoly — our concentration analysis shows meaningful room for both global integrators and focused specialists. This creates strategic choices for buyers: work with scale for complex global licensing and compliance, or engage specialists for rapid ROI and niche automation.
What the Report Delivers — Practical, Executable Content
Our research is designed as a practitioner’s toolkit for CIOs, procurement heads, and managed‑service leaders. Beyond market sizing and trend analysis, the full report includes:
-
Decision frameworks that translate market forces into procurement scoring (governance, data protection, tooling interoperability, and SLA design).
-
Detailed buyer playbooks: 90/180/360‑day roadmaps covering discovery, contract remediation, negotiation levers and governance setup for hybrid environments.
-
Operational runbooks for SAM providers and in‑house teams, including automated discovery patterns, SaaS reconciliation workflows, and vendor audit response templates.
-
Financial models: TCO templates and scenario analyses to quantify savings from license optimization, SaaS rationalization, and cloud spend alignment under multiple adoption and audit intensity scenarios.
-
Compliance and data handling playbook aligned to recent regulatory developments — practical controls for minimization, encryption, access logging and contractual clauses to reduce liability exposure when sharing discovery artifacts with third parties.
-
Procurement artifacts: RFP and evaluation checklists tailored for global, multi‑vendor, and SaaS‑heavy estates; vendor due diligence questionnaires focused on privacy, security and audit defense.
-
M&A and partner strategy guidance for SAM providers — valuation multiples, integration risk checklists and talent retention plans for specialized licensing experts.
Competitive Landscape — Who’s Moving the Market
The market’s competitive fabric mixes pure‑play SAM specialists, global system integrators and SaaS‑centric platform providers. Our vendor analysis — built from primary interviews, vendor disclosures and independent validation — profiles the leading providers so buyers can match capabilities to strategic needs.
-
Anglepoint (United States) — Recognized repeatedly for leader‑level execution in licensing visibility, optimization and compliance. Their focus on shadow IT and comprehensive portfolio coverage positions them for enterprises prioritizing audit defense and full‑stack license governance.
-
SoftwareOne (Switzerland) — A global provider blending managed services with deep licensing advisory. Their SAMSimple offerings are aimed at enterprises seeking centralized licensing optimization and repeatable compliance processes.
-
Crayon (Norway) — Known for executional rigor and a strong licensing vision; Crayon is frequently chosen in scenarios requiring global delivery and integrated optimization services across cloud and on‑prem estates.
-
Insight (United States) — Emphasizes cloud cost optimization and integration with broader IT portfolio services. Recently recognized in industry benchmarks for execution and vision, making them a strong contender for cloud‑forward organizations.
-
Deloitte (United Kingdom/global) — Leverages deep vendor licensing expertise and enterprise transformation capabilities. Attractive for buyers needing orchestration across complex enterprise change programs tied to SAM improvements.
-
Zluri (United States) — A SaaS management platform with SAM capabilities, focused on discovery and subscription control for SaaS‑heavy organizations seeking rapid time‑to‑value.
-
Livingstone Technologies (United Kingdom) — Specializes in cost optimization and adaptive handling of vendor licensing change; a fit where bespoke licensing complexity requires focused technical competence.
-
Softchoice (Canada) — Combines SAM managed services with cloud enablement and digital workplace services, useful where SAM needs to be embedded in broader digital workplace programs.
Recent recognitions underline market momentum: several providers were named Leaders in the 2025 Gartner Magic Quadrant, and others received notable recognition for execution and vision. These signals matter for procurement but should be balanced against fit, data‑handling practices and scalability.
Market Dynamics: Risk, Regulation and Talent
-
Regulatory intensification: Multiple US state privacy laws now require stronger transparency and data protection for the usage data SAM tools collect. Simultaneously, the DOJ’s Bulk Data Rule places new record‑keeping and cybersecurity obligations on transactions involving large volumes of sensitive data. Buyers must demand auditable, minimally invasive discovery methods and stringent contractual safeguards.
-
Data handling as a competitive differentiator: SAM providers that bake privacy‑by‑design into discovery and analytics — e.g., masking, pseudonymization and narrow consent processes — are likely to win enterprise mandates where legal risk is the primary procurement filter.
-
Talent and automation: The operational backbone of SAM still relies on license specialists; however, the next wave of value comes from AI‑augmented tooling that reduces manual reconciliation and accelerates optimization recommendations. Expect labor cost pressures for vendor‑specific licensing expertise alongside investment in automation to preserve margins.
Actionable Guidance for 2026
PW Consulting recommends a pragmatic three‑track approach for executives planning SAM strategy in 2026:
-
Protect: Immediately inventory high‑risk estates (SaaS, enterprise databases, collaboration platforms) and deploy privacy‑first discovery. Update vendor contracts to include strict data handling terms and breach escalations tied to regulatory thresholds.
-
Optimize: Use short, outcome‑oriented pilots with providers that can demonstrate rapid ROI through license reclaim, subscription rationalization and cloud spend alignment. Make vendor selection decision criteria explicit: audit defense capability, data controls, automation depth and global delivery reach.
-
Transform: For organizations ready to scale SAM into continuous governance, define a three‑year roadmap that integrates SAM with FinOps and ITAM, invests in AI augmentation and builds an internal center of excellence to sustain improvements.
Why PW Consulting’s Report Is a Strategic Tool
This study blends rigorous market sizing and forecasting with field‑tested playbooks, vendor scorecards and legal operationalization templates. It is intentionally structured to support C‑suite discussions, procurement decision matrices and program roadmaps — not merely to describe the market but to enable action.
Important note: while the executive summary herein highlights market direction and high‑level positioning, the report intentionally withholds detailed segmentation tables and sensitive vendor financial splits to preserve actionable insight for licensed report users. Those granular allocations — by region, service type and enterprise size — are included in the full research package and are critical for precise budgeting and regional procurement planning.
Next Steps
For CISOs, procurement leads and SAM program owners preparing 2026 roadmaps, PW Consulting’s report provides the playbooks, scenario models and vendor assessments needed to convert market dynamics into defensible decisions. To access the full dataset, segmented analytics and downloadable procurement artifacts, visit PW Consulting’s report page or contact our client team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Software Asset Management Managed Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Aircraft Composite Enclosures Market Poised for 7.12% CAGR in 2026–2032 Forecast
By pmarketresearch, 2026-07-07
Aircraft Composite Enclosures Market: Strategic Insights for 2026 Decision-Makers
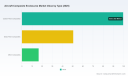
PW Consulting’s newest market research release on the Aircraft Composite Enclosures market is timed to inform critical 2026 strategic choices across aerospace OEMs, Tier 1 suppliers, materials producers and investors. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the study consolidates empirical trend analysis, supplier mapping, regulatory impact assessment and actionable playbooks designed to convert market signals into defensible decisions. The headline: the global market is growing at a compound annual growth rate (CAGR) of 7.12%, moving from an estimated USD 166.7 Million (base year 2025) into continued expansion through 2032.
Aircraft Composite Enclosures Market
Why this report matters in 2026
2026 is shaping up to be a watershed year for composite enclosures used in avionics, embedded electronics and aircraft interiors. Several converging forces—material price volatility, renewed defense and commercial aircraft investment, and tighter certification expectations—are turning what was incremental product substitution into strategic reengineering programs. Our analysis places these dynamics into business rhythms that matter to executives making sourcing, product roadmapping and M&A decisions this year.
Aircraft Composite Enclosures Market
-
Material and cost pressure: Raw material inputs are volatile. For example, epoxy resin spot pricing in key markets jumped recently—an input behavior that materially affects enclosure cost math and supplier margin. Simultaneously, aerospace-grade carbon fiber pricing remains a lever that can alter TCO across program lifecycles.
Aircraft Composite Enclosures Market -
Regulatory and certification gating: Composite structures are now addressed explicitly in updated advisory frameworks. Compliance pathways are increasingly constraining time-to-market; early alignment with certification expectations reduces technical rework and program delay risk.
-
Supply-chain architecture evolution: Long-term supply agreements are emerging as the preferred risk management tool. Recent strategic partnerships in the carbon-fiber supply chain underline how firms are seeking stability through contracted supply rather than spot exposure.
What this report delivers—practical, decision-ready intelligence
The report is built to be immediately actionable for corporate leaders. It goes beyond high-level forecasts to deliver structured inputs you can use in operating and investment plans. Highlights include:
-
Rigorous market sizing & scenario forecasts: Baseline and upside/downside scenarios across the 2026–2032 horizon, with demand drivers traced to fleet growth, avionics modernization and defense procurement cycles.
-
Cost and margin intelligence: Detailed cost-builds for typical enclosure architectures—material mix, processing, assembly and qualification overhead—enabling sensitivity analysis against resin and fiber price swings.
-
Supplier and technology maps: A heatmap of capability clusters, manufacturing footprints, and technology differentiation (EMI solutions, molding processes, integration of high-voltage interconnects), enabling targeted partner selection.
-
Regulatory path playbook: Step-by-step guidance on aligning design and test plans to contemporary advisory circulars and certification norms to compress qualification timelines.
-
M&A and commercial playbooks: Criteria-based prioritization for acquisition targets, joint-venture structures and licensing strategies tuned to market concentration and competitive dynamics.
-
Interactive analytics: Scenario tables and modifiable demand levers so strategy teams can stress-test procurement, product and investment plans for 2026 budget cycles.
Competitive landscape—what to watch in 2026
The market demonstrates moderate concentration: the top three and top five firms capture a meaningful share of value, with room for mid-tier and specialized players to influence niche segments. This structure creates both consolidation risks and whitespace for differentiated entrants.
-
TE Connectivity: Leveraging strengths in EMI shielding and robust electronics packaging, TE’s composite enclosures are positioned where electromagnetic compatibility and weight reduction are jointly prioritized. Expect continued program wins where enclosure integration is specified as part of larger system-level work packages.
-
Collins Aerospace: With a deep presence across commercial and defense programs, Collins pairs scale manufacturing with systems integration capabilities. Their advantage is in offering turnkey avionics enclosure subsystems that lower integration risk for airframers and Tier-1 contractors.
-
Carlisle Interconnect Technologies (Amphenol CIT): Focused on high-performance interconnect and enclosures, Amphenol CIT competes on designs that support higher-voltage and denser interconnect topologies—an important angle as electrical architectures in aircraft become more electrified.
-
GE Aerospace: Recent orders in adjacent marine and defense markets demonstrate the strategic value of cross-domain validation. Such crossovers accelerate qualification cycles for aerospace variants and create a pull-through channel for composite enclosure solutions in defense programs.
-
Automated Dynamics (Trelleborg), AIM Aerospace, RAMPF Group and Kaman (Vermont Composites): These firms represent specialized capabilities—custom enclosures, bespoke carbon-fiber structures, and EMI-shielded solutions. They are frequently acquisition targets or preferred partners for OEMs seeking modular, low-volume, high-value enclosures.
Recent industry moves underscore these themes. For instance, a notable cross-industry supply agreement signed in early 2026 aims to stabilize carbon-fiber availability for aerospace programs, while high-profile program awards have showcased how defense contracts can accelerate composite enclosure adoption and qualification.
Strategic implications and recommended 2026 actions
For executives building 2026 plans, the right mix is pragmatic hedging and targeted investment. Below are prioritized actions calibrated to timing, cost, and risk.
-
Secure upstream inputs with layered contracts: Negotiate longer-term supply agreements for aerospace-grade fiber and consider price-indexed clauses for resin procurement. Where appropriate, explore strategic inventory buffering at critical program junctures.
-
Fast-track certification-readiness: Invest in pre-certification testing and documentation aligned with current advisory circulars to remove late-stage surprises. Early dialogue with certification authorities can materially compress program schedules.
-
Modularize designs for platform reuse: Adopt enclosure platforms that can be reconfigured across avionics, IFE and embedded computing applications to capture scale while preserving performance differentiation.
-
Target mid-tier partnerships and tuck-ins: Use M&A selectively to acquire specialized capabilities (EMI shielding, high-voltage composites) or localized manufacturing footprint to reduce lead times and qualification costs.
-
Hedge cost exposure through engineering substitution: Where certification allows, evaluate alternative resin chemistries and hybrid fiber architectures to optimize the trade-off between weight, cost and manufacturability.
-
Productize aftermarket and sustainment services: Enclosures in service increasingly require repairability and traceability. Offerings that bundle retrofit kits, repair tooling and qualification support create durable aftermarket revenue streams.
-
Embed sustainability metrics into procurement: With lifecycle scrutiny increasing, prioritize suppliers with carbon management plans and recyclability pathways for composite waste—this reduces program obsolescence risk and aligns with customer procurement policies.
How to use this report in your 2026 planning cycle
PW Consulting designed the report to be a living tool for business planning: finance teams can run budget sensitivities with the included cost models; procurement can draft robust sourcing strategies using supplier maps; R&D can prioritize investments against quantified program paybacks; and corporate development can screen M&A targets through our prioritized criteria. The full dataset provides the granular segmentation, regional breakdowns and application-level demand curves required to operationalize these strategies.
We intentionally present an executive-grade preview here—profiling market trajectory, competitive posture and actionable recommendations—while reserving the full segmentation tables, company-level revenue splits and downloadable scenario models for the report subscribers. That deeper dataset is where execution-grade allocations and negotiation tactics are articulated in program-ready detail.
Next steps
PW Consulting’s Aircraft Composite Enclosures Market report is positioned as the execution manual for 2026 decisions. If your team is preparing 2026 budgets, seeking to derisk supply for a new avionics program, evaluating acquisition targets, or recalibrating engineering roadmaps for electrified architectures, this research is specifically structured to shorten decision cycles and raise the probability of program success.
Contact PW Consulting to access the full report, interactive datasets and a tailored briefing for your executive team. Our analysts are available to run bespoke scenario workshops that map your choices against the market trajectories and supplier realities outlined in the study.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 7.46% CAGR for Fully Automatic Full‑Screen Laser Cutting Equipment Market Through 2032
By pmarketresearch, 2026-07-07
Fully Automatic Full Screen Laser Cutting Equipment Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting today publishes an advanced industry briefing derived from our new market research report on the Fully Automatic Full Screen Laser Cutting Equipment market. This briefing synthesizes the high-level commercial and technological trends that will shape procurement, investment, and partnership strategy in 2026. It draws on a five-year historical analysis (2020–2025) and a forward-looking forecast window (2026–2032) built on proprietary primary research, vendor interviews, and rigorous econometric modeling.
Fully Automatic Full Screen Laser Cutting Equipment Market
Why this market matters for 2026 strategy
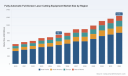
The fully automatic full screen laser cutting segment is moving from an efficiency-driven niche to a core platform in modern, high-mix manufacturing. Our topline model shows that the market expanded steadily through 2020–2025 and is positioned to grow at a compound annual growth rate (CAGR) of approximately 7.46% over the 2026–2032 forecast period. By 2026 the market is forecast to enter a new phase of scale as manufacturers accelerate automation investments, replace legacy capital equipment for energy efficiency, and pursue higher-throughput, lower-tco operations.
Fully Automatic Full Screen Laser Cutting Equipment Market
For corporate planners weighing capital allocation and footprint optimization in 2026, the implications are clear: timing, vendor selection, and integration capability will determine whether investments produce immediate productivity gains or become stranded assets.
Fully Automatic Full Screen Laser Cutting Equipment Market
Key market dynamics shaping 2026 decisions
- Automation and precision are the demand levers. Widespread adoption of industrial automation is the primary driver behind acceleration in full-screen laser systems. OEMs are prioritizing integrated production lines where laser cutting is a deterministic step tightly coupled with upstream and downstream processes.
- Energy-efficiency and regulatory pressure. Regulatory emphasis on energy efficiency is accelerating transitions toward fiber and solid‑state laser technologies. This is influencing total cost of ownership calculations and shortening useful life assumptions for older systems.
- Raw material and input-cost volatility. Fluctuating prices for steel, aluminum, and other inputs affect both capital spending cycles and operating margins for manufacturers that depend on laser cutting. Procurement strategies in 2026 must therefore be synchronized with hedging and inventory approaches.
- Moderate market concentration favors strategic partnerships. The market concentration profile indicates a moderately consolidated supplier landscape among the top vendors, creating opportunities for buyers to negotiate integrated service bundles while remaining mindful of vendor lock-in risks.
What our report delivers — operationally relevant content
The PW Consulting report is designed for practitioners who need executable guidance rather than high-level theory. Key deliverables include:
- Proprietary market-sizing and forecasting model calibrated to 2020–2025 history and running through 2032, with scenario sensitivities for macro shocks and technology adoption ramps.
- A rigorous methodology appendix documenting data sources, interview protocols, and model assumptions to ensure the reproducibility of findings for internal stakeholders and auditors.
- Competitive benchmarking that compares suppliers across performance, automation maturity, service footprint, and software integration capability.
- Go-to-market and procurement playbooks tailored for OEMs, contract manufacturers, and electronics integrators to optimize timing and contract terms.
- Technology roadmaps and adoption curves for laser sources (including ultrafast and UV technologies), integration patterns, and automation architectures.
- Supply chain risk matrix and a capital expenditure (CapEx) calculator to support board-level investment approvals.
- Case studies and implementation templates for factory pilots, ROI proofs of concept, and scale-up plans across high-mix/low-volume and high-volume manufacturing environments.
- M&A and partnership opportunity maps, highlighting acquisition targets and strategic alliance candidates based on capability gaps and market positioning.
Competitive landscape — who matters and why
Our proprietary vendor analysis highlights a set of core incumbents and fast followers. Each brings distinctive strengths that procurement teams must weigh when structuring 2026 contracts and integration plans:
- Farley Laserlab (HG Farley / HGTECH subsidiary) — A specialist in high-power fiber cutting and large-format solutions, with advanced automation offerings suited to sheet and tube applications. Their engineering depth makes them a strong partner for large-scale deployments requiring high throughput.
- GD HAN’S YUEMING LASER TECH — Broad product breadth and strong manufacturing scale position them as a pragmatic option for integrated line supply and fast fulfillment.
- Kunshan Dapeng Precision Machinery — Focused on precision, automated full-screen capabilities, attractive to manufacturers prioritizing tight tolerances and repeatability.
- Beijing Torch SMT — Known for precision laser solutions that integrate well with SMT manufacturing lines, which is a differentiator for electronics-focused operations.
- Mitsubishi Electric — Offers advanced processing systems with strong automation and global service coverage, appealing for mission-critical, high-reliability environments.
- Control Micro Systems — A specialist in precision control systems suitable for niche, high-accuracy full-screen applications.
- EBSO GmbH — European provider with automation and processing expertise tuned to electronics manufacturing needs.
- Aurotek Corporation — Taiwanese automation and laser integrator with emphasis on production line interoperability.
- ASYS Group — Systems integrator delivering automated production lines with embedded laser cutting functionality.
Strategic buyers should use the report’s vendor heatmaps and supplier scorecards to align procurement RFQs with long‑term service and software roadmaps, not just initial capex metrics. The market’s moderate top-end concentration means there is bargaining power, but switching costs and integration complexity are real and growing.
Practical recommendations for 2026
- Adopt a staged CapEx approach. Implement pilot lines to validate ROI with clearly defined throughput and yield KPIs before committing to full-factory rollouts. Use the report’s CapEx calculator to model payback under multiple raw-material price and demand scenarios.
- Prioritize integration and serviceability over headline performance specs. Select systems with robust PLC/SCADA interoperability, local service options, and remote diagnostic capabilities to minimize downtime risk.
- Factor energy-efficiency into TCO models. Given regulatory and operating-cost drivers, choose technologies that align with corporate sustainability targets and local energy regulations to avoid obsolescence via compliance-driven retrofits.
- Design supplier diversification into contract awards. Use a tiered-sourcing strategy to balance strategic partnerships with alternative suppliers for commodity replacement parts and maintenance services.
- Embed predictive maintenance and digital-twin pilots early. Systems that deliver high-quality telemetry and model-based maintenance unlock the greatest margin improvements over time.
- Develop M&A and partnership scouting. For companies seeking rapid capability build, the report identifies target archetypes and acquisition playbooks to accelerate vertical integration or expand automation offerings.
Risk factors to monitor into 2026
- Macro-driven CapEx tightening that could delay fleet renewals.
- Raw-material price spikes that compress OEM margins and drive consolidation among weaker suppliers.
- Regulatory shifts that accelerate obsolescence of older laser technologies.
- Service-network limitations for regions with nascent local support, which increase downtime risk.
How PW Consulting’s report supports your 2026 playbook
Our report equips decision-makers with both the quantitative foundation and the qualitative context needed to make defensible investment choices in 2026. It simulates multiple adoption scenarios tied to realistic inputs and lays out a sequence of actions — from pilot design through supplier contracting and post-installation optimization — that procurement, operations, and corporate development teams can operationalize immediately.
Because we intentionally present this briefing as a strategic trailer, detailed segmented tables and granular regional or application-level revenue splits are reserved for the full report and accompanying data workbook. These deliverables include the vendor heatmaps, region- and application-level modelling, unit economics by laser source, and the full list of primary interviews that underpin our vendor assessments.
Next steps
For procurement leads, operations managers, and corporate strategists preparing budgets and roadmaps for 2026, PW Consulting recommends obtaining the complete report and data workbook to access the full segmentation, supplier scorecards, and the interactive CapEx model. The full dataset will enable deeper scenario testing, bespoke supplier shortlists, and executable implementation plans tailored to your manufacturing footprint and product mix.
Contact PW Consulting to schedule a tailored briefing and to examine the model under your company’s specific assumptions. Our analysts are available to support board presentations, RFP development, and M&A diligence based on the report’s findings.
For detailed analysis of this topic, please visit the official page: Fully Automatic Full Screen Laser Cutting Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com