

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts 7.46% CAGR for Fully Automatic Full‑Screen Laser Cutting Equipment Market Through 2032

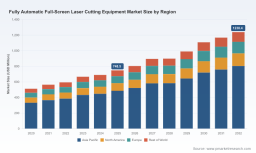
Fully Automatic Full Screen Laser Cutting Equipment Market: Strategic Outlook for 2026 Decision-Makers
PW Consulting today publishes an advanced industry briefing derived from our new market research report on the Fully Automatic Full Screen Laser Cutting Equipment market. This briefing synthesizes the high-level commercial and technological trends that will shape procurement, investment, and partnership strategy in 2026. It draws on a five-year historical analysis (2020–2025) and a forward-looking forecast window (2026–2032) built on proprietary primary research, vendor interviews, and rigorous econometric modeling.
Fully Automatic Full Screen Laser Cutting Equipment Market
Why this market matters for 2026 strategy
The fully automatic full screen laser cutting segment is moving from an efficiency-driven niche to a core platform in modern, high-mix manufacturing. Our topline model shows that the market expanded steadily through 2020–2025 and is positioned to grow at a compound annual growth rate (CAGR) of approximately 7.46% over the 2026–2032 forecast period. By 2026 the market is forecast to enter a new phase of scale as manufacturers accelerate automation investments, replace legacy capital equipment for energy efficiency, and pursue higher-throughput, lower-tco operations.
Fully Automatic Full Screen Laser Cutting Equipment Market
For corporate planners weighing capital allocation and footprint optimization in 2026, the implications are clear: timing, vendor selection, and integration capability will determine whether investments produce immediate productivity gains or become stranded assets.
Fully Automatic Full Screen Laser Cutting Equipment Market
Key market dynamics shaping 2026 decisions
- Automation and precision are the demand levers. Widespread adoption of industrial automation is the primary driver behind acceleration in full-screen laser systems. OEMs are prioritizing integrated production lines where laser cutting is a deterministic step tightly coupled with upstream and downstream processes.
- Energy-efficiency and regulatory pressure. Regulatory emphasis on energy efficiency is accelerating transitions toward fiber and solid‑state laser technologies. This is influencing total cost of ownership calculations and shortening useful life assumptions for older systems.
- Raw material and input-cost volatility. Fluctuating prices for steel, aluminum, and other inputs affect both capital spending cycles and operating margins for manufacturers that depend on laser cutting. Procurement strategies in 2026 must therefore be synchronized with hedging and inventory approaches.
- Moderate market concentration favors strategic partnerships. The market concentration profile indicates a moderately consolidated supplier landscape among the top vendors, creating opportunities for buyers to negotiate integrated service bundles while remaining mindful of vendor lock-in risks.
What our report delivers — operationally relevant content
The PW Consulting report is designed for practitioners who need executable guidance rather than high-level theory. Key deliverables include:
- Proprietary market-sizing and forecasting model calibrated to 2020–2025 history and running through 2032, with scenario sensitivities for macro shocks and technology adoption ramps.
- A rigorous methodology appendix documenting data sources, interview protocols, and model assumptions to ensure the reproducibility of findings for internal stakeholders and auditors.
- Competitive benchmarking that compares suppliers across performance, automation maturity, service footprint, and software integration capability.
- Go-to-market and procurement playbooks tailored for OEMs, contract manufacturers, and electronics integrators to optimize timing and contract terms.
- Technology roadmaps and adoption curves for laser sources (including ultrafast and UV technologies), integration patterns, and automation architectures.
- Supply chain risk matrix and a capital expenditure (CapEx) calculator to support board-level investment approvals.
- Case studies and implementation templates for factory pilots, ROI proofs of concept, and scale-up plans across high-mix/low-volume and high-volume manufacturing environments.
- M&A and partnership opportunity maps, highlighting acquisition targets and strategic alliance candidates based on capability gaps and market positioning.
Competitive landscape — who matters and why
Our proprietary vendor analysis highlights a set of core incumbents and fast followers. Each brings distinctive strengths that procurement teams must weigh when structuring 2026 contracts and integration plans:
- Farley Laserlab (HG Farley / HGTECH subsidiary) — A specialist in high-power fiber cutting and large-format solutions, with advanced automation offerings suited to sheet and tube applications. Their engineering depth makes them a strong partner for large-scale deployments requiring high throughput.
- GD HAN’S YUEMING LASER TECH — Broad product breadth and strong manufacturing scale position them as a pragmatic option for integrated line supply and fast fulfillment.
- Kunshan Dapeng Precision Machinery — Focused on precision, automated full-screen capabilities, attractive to manufacturers prioritizing tight tolerances and repeatability.
- Beijing Torch SMT — Known for precision laser solutions that integrate well with SMT manufacturing lines, which is a differentiator for electronics-focused operations.
- Mitsubishi Electric — Offers advanced processing systems with strong automation and global service coverage, appealing for mission-critical, high-reliability environments.
- Control Micro Systems — A specialist in precision control systems suitable for niche, high-accuracy full-screen applications.
- EBSO GmbH — European provider with automation and processing expertise tuned to electronics manufacturing needs.
- Aurotek Corporation — Taiwanese automation and laser integrator with emphasis on production line interoperability.
- ASYS Group — Systems integrator delivering automated production lines with embedded laser cutting functionality.
Strategic buyers should use the report’s vendor heatmaps and supplier scorecards to align procurement RFQs with long‑term service and software roadmaps, not just initial capex metrics. The market’s moderate top-end concentration means there is bargaining power, but switching costs and integration complexity are real and growing.
Practical recommendations for 2026
- Adopt a staged CapEx approach. Implement pilot lines to validate ROI with clearly defined throughput and yield KPIs before committing to full-factory rollouts. Use the report’s CapEx calculator to model payback under multiple raw-material price and demand scenarios.
- Prioritize integration and serviceability over headline performance specs. Select systems with robust PLC/SCADA interoperability, local service options, and remote diagnostic capabilities to minimize downtime risk.
- Factor energy-efficiency into TCO models. Given regulatory and operating-cost drivers, choose technologies that align with corporate sustainability targets and local energy regulations to avoid obsolescence via compliance-driven retrofits.
- Design supplier diversification into contract awards. Use a tiered-sourcing strategy to balance strategic partnerships with alternative suppliers for commodity replacement parts and maintenance services.
- Embed predictive maintenance and digital-twin pilots early. Systems that deliver high-quality telemetry and model-based maintenance unlock the greatest margin improvements over time.
- Develop M&A and partnership scouting. For companies seeking rapid capability build, the report identifies target archetypes and acquisition playbooks to accelerate vertical integration or expand automation offerings.
Risk factors to monitor into 2026
- Macro-driven CapEx tightening that could delay fleet renewals.
- Raw-material price spikes that compress OEM margins and drive consolidation among weaker suppliers.
- Regulatory shifts that accelerate obsolescence of older laser technologies.
- Service-network limitations for regions with nascent local support, which increase downtime risk.
How PW Consulting’s report supports your 2026 playbook
Our report equips decision-makers with both the quantitative foundation and the qualitative context needed to make defensible investment choices in 2026. It simulates multiple adoption scenarios tied to realistic inputs and lays out a sequence of actions — from pilot design through supplier contracting and post-installation optimization — that procurement, operations, and corporate development teams can operationalize immediately.
Because we intentionally present this briefing as a strategic trailer, detailed segmented tables and granular regional or application-level revenue splits are reserved for the full report and accompanying data workbook. These deliverables include the vendor heatmaps, region- and application-level modelling, unit economics by laser source, and the full list of primary interviews that underpin our vendor assessments.
Next steps
For procurement leads, operations managers, and corporate strategists preparing budgets and roadmaps for 2026, PW Consulting recommends obtaining the complete report and data workbook to access the full segmentation, supplier scorecards, and the interactive CapEx model. The full dataset will enable deeper scenario testing, bespoke supplier shortlists, and executable implementation plans tailored to your manufacturing footprint and product mix.
Contact PW Consulting to schedule a tailored briefing and to examine the model under your company’s specific assumptions. Our analysts are available to support board presentations, RFP development, and M&A diligence based on the report’s findings.
For detailed analysis of this topic, please visit the official page: Fully Automatic Full Screen Laser Cutting Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com