

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Automotive Connecting Rod Bush Market to Expand at a 3.82% CAGR During 2026–2032

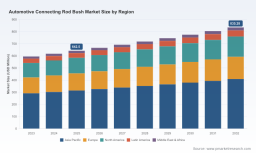
Automotive Connecting Rod Bush Market: A 2026 Strategic Preview
PW Consulting is pleased to release a strategic preview of our authoritative report on the Automotive Connecting Rod Bush market. Built from a rigorous base year of 2025 and a comprehensive historical window (2020–2025), the study projects the market from 2026 through 2032. At a macro level the market demonstrates steady expansion — rising from an estimated global revenue base of USD 642.5 Million in 2025 to an expected USD 835.28 Million by 2032, reflecting a compound annual growth rate (CAGR) of 3.82%. This preview highlights the report’s core practical value for boards, business unit leaders, product managers and corporate development teams making critical 2026 decisions, while reserving the granular sub-segment tables for the full report.
Automotive Connecting Rod Bush Market
Why this market matters to 2026 corporate strategy
-
Timing of structural decisions: The connecting rod bush segment sits at the intersection of engine efficiency improvements, emissions regulation pressure, and the aftermarket life-cycle of internal combustion engines (ICE). 2026 will be a pivotal year for decisions that lock-in sourcing, materials and aftermarket strategies for the next product cycle.
Automotive Connecting Rod Bush Market -
Predictable, durable growth: With a mid-single-digit CAGR through 2032, demand growth is consistent and high enough to justify targeted investments — yet not explosive enough to eliminate the need for disciplined portfolio prioritization.
Automotive Connecting Rod Bush Market -
Supply chain optimization opportunity: Incremental product and process innovation (materials, coatings, manufacturing tolerances) yields outsized returns in reduced warranty exposure, lower friction losses and improved fuel-efficiency metrics.
What our full report delivers (practical, operational outputs)
-
Actionable market sizing and forecasts. We provide a robust top-down and bottom-up view of global demand across 2023–2032, with scenario modelling for 2026 planning cycles. The preview above cites headline totals; full segment-level schedules, unit volumes and price assumptions are restricted to the full report.
-
Supply-chain heatmaps. End-to-end maps that expose concentration risks, single-source dependencies, and Tier‑2 raw material vulnerabilities for implementation planning.
-
Cost-to-serve and margin benchmarks. Product-level cost curves, manufacturing hour and scrap benchmarks and working-capital profiles designed for operational read-throughs by CFOs and plant managers.
-
Technology and materials playbook. Comparative analysis of bi-metal, tri-metal, aluminum and brass solutions — with recommended trials, test protocols and expected performance deltas under engine-relevant stressors.
-
Commercial and aftermarket strategies. Go-to-market blueprints for OEMs and aftermarket suppliers including channel segmentation, warranty-incentive structures, and parts-repair economics.
-
M&A and partnership screening. A pre-vetted shortlist of acquisition targets, JV structures and supplier consolidation scenarios tuned to 2026 budget cycles — along with integration risk checklists.
-
Regulatory and compliance tracker. A dynamic timeline of aviation and automotive directives that intersect with connecting rod bush design and replacement requirements, with impact scoring for product portfolios.
Competitive landscape — capabilities to watch in 2026
Our report maps market positioning across global OEM suppliers, regional specialists and high-performance niche players. Below we summarize the strategic posture of the manufacturers and suppliers that shape competitive dynamics:
-
MAHLE GmbH (Stuttgart, Germany) — A global engine components leader with deep OEM relationships. MAHLE’s strengths lie in high‑performance, low-friction designs and systems-level integration with internal combustion architectures. For strategic partners and challengers, MAHLE’s R&D cadence and OEM footprints present both a benchmark and a competitive moat.
-
Federal‑Mogul Motorparts (Tenneco) (Southfield, Michigan, USA) — Noted for aftermarket reach and extensive experience with bi-metal and tri-metal technologies. Federal‑Mogul’s dual OEM/aftermarket playbook is instructive for players seeking to balance margin stability with volume exposure.
-
King Engine Bearings (Israel) — A performance-focused supplier offering high-load capacity pin bushings and advanced low-friction surfaces. King’s technical orientation makes it a go-to for motorsport and high-performance OEM projects; a partner or acquisition target for firms seeking faster time-to-market on performance upgrades.
-
K1 Technologies (Ohio, USA) — Specialized in precise, engine-specific small-end bushings for North American V‑engine platforms. K1’s customer-aligned manufacturing and tight-tolerance expertise illustrate the value of localized, application-specific capability.
-
VIIPLUS (Zhejiang, China) — Leading supplier of bi‑metal solutions with scale manufacturing and cost-competitive delivery models; relevant for organizations evaluating dual-sourcing and scale economics.
-
BronzeLube, MYWAY, Raj Metal, AECO and Power Industries (China/India regional groups) — These regional manufacturers provide a range of bimetal/brass options and are central to aftermarket replacement flows and regional OEM programs. Their manufacturing breadth and catalog update cadence have implications for procurement and quality assurance programs.
For decision-makers, the takeaway is straightforward: incumbency rests on a mix of engineering IP, OEM certification depth and cost-competitive supply networks. Partnerships across these dimensions are often the fastest route to upgrading or defending a position in the supply chain.
Regulation, materials and dynamics shaping near-term decisions
-
Regulatory catalysts: Recent airworthiness directives and automotive emissions/fuel economy standards have direct engineering consequences. For example, aviation ADs requiring replacement of certain connecting rod bushings demonstrate how regulatory moves can suddenly accelerate aftermarket demand and influence OEM retrofit cycles.
-
Materials reality: The industry remains grounded in bi-metal steel-backed bronzes, high-tin aluminum alloys and brass formulations. Choices among these materials drive trade-offs in wear-resistance, thermal behavior and manufacturing cost. Our report quantifies expected life-cycle performance deltas and suggests where materials substitution yields net TCO advantages.
-
Aftermarket vs OEM balance: Catalog updates and repair-kit introductions from aftermarket leaders illustrate ongoing demand for reverse-engineered replacement parts. 2026 planning should treat aftermarket demand as a distinct profit pool with different margin dynamics and service requirements compared to OEM supply contracts.
Strategic implications and recommended plays for 2026
-
Prioritize dual-sourcing for critical alloys: Implement validated second-source suppliers for high‑wear alloys and back-up capacity for key manufacturing steps. Use supplier scorecards tied to delivery, fatigue performance and certification readiness.
-
Investment in friction-reduction R&D: Small coefficient-of-friction improvements compound into measurable fuel-economy and emissions benefits. Allocate a proportion of 2026 R&D budgets to advanced coatings, surface engineering and test-rig validation.
-
Commercialize aftermarket playbooks: Develop repair-kits and retrofit bundles aligned with regulatory replacement windows. Coordinate warranty and reverse-logistics approaches to capture rapid post-AD replacement opportunities.
-
Evaluate targeted M&A and partnerships: Pursue acquisitions that bring complementary metallurgy or OEM certifications rather than volume-only scale. Consider JVs in regions where local content and certification accelerate OEM entry.
-
Operationalize regulatory monitoring: Build a simple delegate-and-escalate mechanism to convert regulatory alerts into product action plans — with pre-authorized inventory and technical service teams on-call for mandatory replacements.
Practical 2026 implementation checklist (90–180 day horizon)
-
Run supplier resilience stress-tests focused on alloy availability and single-line production risks.
-
Kick-off a 90‑day friction-reduction test programme benchmarking two coating/material options on representative engine cycles.
-
Align aftermarket SKUs and packaging for rapid fulfillment tied to likely AD-triggered demand spikes.
-
Authorize a focused M&A diligence budget for one to two targets that add certification or metallurgy capabilities.
-
Deploy a regulatory watch dashboard flagging aviation and automotive directives with immediate product impact.
How to use this preview — and next steps
This preview is intended to orient leadership teams for the 2026 planning cycle. It showcases where durable, evidence‑based actions can improve competitive position while deliberately withholding granular sub‑segment matrices and tables that are proprietary to the full PW Consulting report. The complete study contains the detailed regional and application breakdowns, supplier share schedules, unit-price curves and a downloadable playbook that operational teams can execute from.
For boards, corporate development leads and plant executives preparing 2026 budgets: use the insights above to frame investment priorities, select pilot projects and scope supplier negotiations. For procurement and engineering teams: request the full report to obtain exacting supplier scorecards, test-protocol templates and expected unit-cost impacts by material and process.
To access the full intelligence set, including the proprietary sub-segmentation outputs and our executable 18‑month commercial plan, please visit the PW Consulting report page. The full dataset is curated to support immediate 2026 decision-making and includes interactive scenarios that translate macro CAGR and market-size trajectories into program-level financials.
For detailed analysis of this topic, please visit the official page: Automotive Connecting Rod Bush Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com