

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Aircraft Composite Enclosures Market Poised for 7.12% CAGR in 2026–2032 Forecast

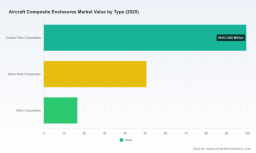
Aircraft Composite Enclosures Market: Strategic Insights for 2026 Decision-Makers
PW Consulting’s newest market research release on the Aircraft Composite Enclosures market is timed to inform critical 2026 strategic choices across aerospace OEMs, Tier 1 suppliers, materials producers and investors. Anchored on a 2025 base year and a 2026–2032 forecast horizon, the study consolidates empirical trend analysis, supplier mapping, regulatory impact assessment and actionable playbooks designed to convert market signals into defensible decisions. The headline: the global market is growing at a compound annual growth rate (CAGR) of 7.12%, moving from an estimated USD 166.7 Million (base year 2025) into continued expansion through 2032.
Aircraft Composite Enclosures Market
Why this report matters in 2026
2026 is shaping up to be a watershed year for composite enclosures used in avionics, embedded electronics and aircraft interiors. Several converging forces—material price volatility, renewed defense and commercial aircraft investment, and tighter certification expectations—are turning what was incremental product substitution into strategic reengineering programs. Our analysis places these dynamics into business rhythms that matter to executives making sourcing, product roadmapping and M&A decisions this year.
Aircraft Composite Enclosures Market
-
Material and cost pressure: Raw material inputs are volatile. For example, epoxy resin spot pricing in key markets jumped recently—an input behavior that materially affects enclosure cost math and supplier margin. Simultaneously, aerospace-grade carbon fiber pricing remains a lever that can alter TCO across program lifecycles.
Aircraft Composite Enclosures Market -
Regulatory and certification gating: Composite structures are now addressed explicitly in updated advisory frameworks. Compliance pathways are increasingly constraining time-to-market; early alignment with certification expectations reduces technical rework and program delay risk.
-
Supply-chain architecture evolution: Long-term supply agreements are emerging as the preferred risk management tool. Recent strategic partnerships in the carbon-fiber supply chain underline how firms are seeking stability through contracted supply rather than spot exposure.
What this report delivers—practical, decision-ready intelligence
The report is built to be immediately actionable for corporate leaders. It goes beyond high-level forecasts to deliver structured inputs you can use in operating and investment plans. Highlights include:
-
Rigorous market sizing & scenario forecasts: Baseline and upside/downside scenarios across the 2026–2032 horizon, with demand drivers traced to fleet growth, avionics modernization and defense procurement cycles.
-
Cost and margin intelligence: Detailed cost-builds for typical enclosure architectures—material mix, processing, assembly and qualification overhead—enabling sensitivity analysis against resin and fiber price swings.
-
Supplier and technology maps: A heatmap of capability clusters, manufacturing footprints, and technology differentiation (EMI solutions, molding processes, integration of high-voltage interconnects), enabling targeted partner selection.
-
Regulatory path playbook: Step-by-step guidance on aligning design and test plans to contemporary advisory circulars and certification norms to compress qualification timelines.
-
M&A and commercial playbooks: Criteria-based prioritization for acquisition targets, joint-venture structures and licensing strategies tuned to market concentration and competitive dynamics.
-
Interactive analytics: Scenario tables and modifiable demand levers so strategy teams can stress-test procurement, product and investment plans for 2026 budget cycles.
Competitive landscape—what to watch in 2026
The market demonstrates moderate concentration: the top three and top five firms capture a meaningful share of value, with room for mid-tier and specialized players to influence niche segments. This structure creates both consolidation risks and whitespace for differentiated entrants.
-
TE Connectivity: Leveraging strengths in EMI shielding and robust electronics packaging, TE’s composite enclosures are positioned where electromagnetic compatibility and weight reduction are jointly prioritized. Expect continued program wins where enclosure integration is specified as part of larger system-level work packages.
-
Collins Aerospace: With a deep presence across commercial and defense programs, Collins pairs scale manufacturing with systems integration capabilities. Their advantage is in offering turnkey avionics enclosure subsystems that lower integration risk for airframers and Tier-1 contractors.
-
Carlisle Interconnect Technologies (Amphenol CIT): Focused on high-performance interconnect and enclosures, Amphenol CIT competes on designs that support higher-voltage and denser interconnect topologies—an important angle as electrical architectures in aircraft become more electrified.
-
GE Aerospace: Recent orders in adjacent marine and defense markets demonstrate the strategic value of cross-domain validation. Such crossovers accelerate qualification cycles for aerospace variants and create a pull-through channel for composite enclosure solutions in defense programs.
-
Automated Dynamics (Trelleborg), AIM Aerospace, RAMPF Group and Kaman (Vermont Composites): These firms represent specialized capabilities—custom enclosures, bespoke carbon-fiber structures, and EMI-shielded solutions. They are frequently acquisition targets or preferred partners for OEMs seeking modular, low-volume, high-value enclosures.
Recent industry moves underscore these themes. For instance, a notable cross-industry supply agreement signed in early 2026 aims to stabilize carbon-fiber availability for aerospace programs, while high-profile program awards have showcased how defense contracts can accelerate composite enclosure adoption and qualification.
Strategic implications and recommended 2026 actions
For executives building 2026 plans, the right mix is pragmatic hedging and targeted investment. Below are prioritized actions calibrated to timing, cost, and risk.
-
Secure upstream inputs with layered contracts: Negotiate longer-term supply agreements for aerospace-grade fiber and consider price-indexed clauses for resin procurement. Where appropriate, explore strategic inventory buffering at critical program junctures.
-
Fast-track certification-readiness: Invest in pre-certification testing and documentation aligned with current advisory circulars to remove late-stage surprises. Early dialogue with certification authorities can materially compress program schedules.
-
Modularize designs for platform reuse: Adopt enclosure platforms that can be reconfigured across avionics, IFE and embedded computing applications to capture scale while preserving performance differentiation.
-
Target mid-tier partnerships and tuck-ins: Use M&A selectively to acquire specialized capabilities (EMI shielding, high-voltage composites) or localized manufacturing footprint to reduce lead times and qualification costs.
-
Hedge cost exposure through engineering substitution: Where certification allows, evaluate alternative resin chemistries and hybrid fiber architectures to optimize the trade-off between weight, cost and manufacturability.
-
Productize aftermarket and sustainment services: Enclosures in service increasingly require repairability and traceability. Offerings that bundle retrofit kits, repair tooling and qualification support create durable aftermarket revenue streams.
-
Embed sustainability metrics into procurement: With lifecycle scrutiny increasing, prioritize suppliers with carbon management plans and recyclability pathways for composite waste—this reduces program obsolescence risk and aligns with customer procurement policies.
How to use this report in your 2026 planning cycle
PW Consulting designed the report to be a living tool for business planning: finance teams can run budget sensitivities with the included cost models; procurement can draft robust sourcing strategies using supplier maps; R&D can prioritize investments against quantified program paybacks; and corporate development can screen M&A targets through our prioritized criteria. The full dataset provides the granular segmentation, regional breakdowns and application-level demand curves required to operationalize these strategies.
We intentionally present an executive-grade preview here—profiling market trajectory, competitive posture and actionable recommendations—while reserving the full segmentation tables, company-level revenue splits and downloadable scenario models for the report subscribers. That deeper dataset is where execution-grade allocations and negotiation tactics are articulated in program-ready detail.
Next steps
PW Consulting’s Aircraft Composite Enclosures Market report is positioned as the execution manual for 2026 decisions. If your team is preparing 2026 budgets, seeking to derisk supply for a new avionics program, evaluating acquisition targets, or recalibrating engineering roadmaps for electrified architectures, this research is specifically structured to shorten decision cycles and raise the probability of program success.
Contact PW Consulting to access the full report, interactive datasets and a tailored briefing for your executive team. Our analysts are available to run bespoke scenario workshops that map your choices against the market trajectories and supplier realities outlined in the study.
For detailed analysis of this topic, please visit the official page: Aircraft Composite Enclosures Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com