

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Intelligent Automatic Warehouse and Logistic Equipment Market Set to Surge at a 12.04% CAGR Through 2032

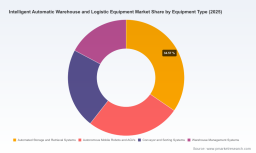
Intelligent Automatic Warehouse and Logistic Equipment Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s latest market research update for Intelligent Automatic Warehouse and Logistic Equipment is built as a decision-grade briefing for executives planning capital allocation, procurement, and capability buildout in 2026. Drawing on a validated historical series (2020–2025) and a forward-looking forecast window (2026–2032), the report synthesizes macro growth trajectories, supplier dynamics, technology inflection points, and near-term risk vectors into an actionable playbook. At the aggregate level the market reached approximately USD 35.6 billion in 2025 and is projected to expand to roughly USD 78.8 billion by 2032, reflecting a compound annual growth rate (CAGR) of 12.04% across the forecast period — a scale and pace that make strategic timing and supplier choice critical for competitive advantage.
Intelligent Automatic Warehouse And Logistic Equipment Market
Why this preview matters for 2026
-
Capital planning windows closing in early 2026 must reconcile inflationary input costs, evolving ESG compliance, and the accelerating substitution of capital for recurring labor. This report frames those trade-offs with a quantified market trajectory and tactical investment levers.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Procurement and operations leaders face a fragmented vendor landscape where no single approach dominates — our analysis profiles the strategic sweet spots where integrators, software-first players, and robotics specialists deliver differentiated returns.
Intelligent Automatic Warehouse And Logistic Equipment Market -
Systems integrators and OEMs preparing M&A, partnership, or distribution strategies will find scenario-based valuation sensitivities tied to macro and regulatory shocks, enabling defensible negotiation positions.
Market dynamics and near-term disruptors
The 2020–2025 period established the structural drivers that will determine winners and losers through 2032: e-commerce acceleration, persistent labor shortages, and the maturation of robotics and warehouse execution software (WES/WMS). In 2025, wage pressures in key logistics markets — for example, North American logistics wages having advanced materially over recent years — continued to push customers toward automation. Combined with energy and sustainability mandates in Europe and North America, buyers are prioritizing systems that lower total cost of ownership (TCO) through energy recovery, regenerative braking and power-optimized architectures.
At the same time, supply-side cost inflation is non-trivial. Rising prices for steel and aluminum and trade-policy shocks (notably a significant increase in tariffs affecting structural components) have raised upfront project costs and extended supplier lead times. The net effect is a shift in procurement preferences: a longer evaluation horizon, greater emphasis on modular retrofit solutions, and heavier negotiation around indexation clauses and supplier risk-sharing.
Technology inflection points to watch in 2026
-
Autonomous fleets and collaborative AMRs continue to converge with WMS/WES stacks, but the high-value opportunities are now in orchestration: multi-agent coordination, real-time congestion management and plug‑and‑play interoperability layers.
-
High-density AS/RS and cube-based storage technologies remain compelling where footprint and labor substitution dominate; however, system-level ROI is increasingly driven by integration with downstream sorting and last‑mile staging.
-
AI and predictive maintenance are moving from pilot to standard practice — expect measurable uptime improvements and deferred capex via condition-based replacement strategies for key mechanical assets.
Competitive landscape — consolidation, specialization, and partnership maps
The industry structure remains moderately fragmented (the top three players capture under one-fifth of the market; the top five account for roughly a quarter), which creates strategic space for vertical specialists and regional champions. Global systems integrators and OEMs each bring distinct advantages:
-
Long-established material handling firms have scale in high-throughput conveyor and AS/RS projects and continue to win large distribution center programs where end-to-end delivery risk matters.
-
Software-first automation vendors and AMR specialists are creating white-space through faster deployments, subscription models and modular upgrades that lower entry barriers for mid-market customers.
-
Robotics and AI-centric entrants are expanding the envelope on labor replacement and micro-fulfillment, particularly for e-commerce and retail fulfillment applications that prioritize cycle-time over maximum density.
Recent industry activity reinforces these patterns. Major suppliers displayed new product lines and integrated offerings at MODEX 2026; KNAPP and other vendors publicly detailed advances in multi-agent AI for fleet coordination earlier in 2026; and multiple automation conferences in early 2026 showcased integration patterns combining robotics, WMS, and energy-efficient subsystems. These events demonstrate that capability leadership now mixes mechanical engineering depth with agile software development and services economics.
What PW Consulting’s report provides — operational, not ornamental
We designed this study to be prescriptive for 2026 decision-makers. The deliverables emphasize implementable outputs rather than abstract models, including:
-
Decision frameworks for build vs. buy vs. partner, tied to customer size, throughput profiles and expansion roadmaps.
-
Procurement playbooks and RFP templates that embed indexation clauses, SLAs for uptime and spare-parts strategies aligned to current tariffs and input-cost volatility.
-
ROI and TCO modeling tools calibrated to 2025 baseline costs, energy efficiency scenarios, and labor-cost replacement curves — enabling rapid scenario comparison across multiple project horizons.
-
Technology roadmaps that sequence investments (e.g., WMS modernization, AMR pilots, full AS/RS deployment) to minimize operational disruption while maximizing throughput gains.
-
Supplier shortlists and integration risk matrices that map vendor strengths to project archetypes — from retrofit micro-fulfillment to greenfield high-throughput DCs.
-
Regulatory and materials-impact analyses, with mitigation strategies for tariff exposure and supply-chain substitution options.
To preserve competitive value for our subscribers, the report intentionally withholds granular regional and application-level revenue splits in this press summary. Those segmentation tables, vendor pairwise scoring matrices and project-level case studies are available in the full report and online portal.
Actionable recommendations for corporate leadership in 2026
-
Shift from CapEx-only ROI to blended CapEx/OpEx models: consider vendor financing, outcome-based service contracts and modular deployment to preserve cash while accelerating automation.
-
Prioritize interoperability and open APIs in procurement criteria — integration costs are now a larger share of project budgets than a few years ago.
-
Design pilot-to-scale pathways that lock in one performance metric (throughput, SKU mix, or energy reduction) per phase to avoid scope creep and allow rapid learning.
-
Embed tariff and input-cost clauses in supplier agreements and maintain alternative sourcing for critical structural components; negotiate lead-time guarantees with penalty/rebate mechanics.
-
Invest in people and process alongside automation: reskilling plans, cross-training and change-management reduce the ramp to full productivity and improve long-term resiliency.
How to use the report in the first 90–180 days of 2026
For boards and executive teams, the report is a structured input to capital allocation and M&A deliberations. For operations and supply-chain leaders, it becomes a tactical playbook: run a rapid supplier due-diligence round using the report’s vendor scorecards; run three scenario-TCO runs (conservative, base, aggressive) on any proposed automation project; and pilot a single AMR-enabled picking cell with tightly scoped KPIs that match corporate ESG and energy objectives.
Final perspective — risk, opportunity and the path to competitive differentiation
Automation investment in 2026 is not binary — it is a portfolio choice. The industry’s projected expansion through 2032 creates significant upside, but execution is nuanced: raw material inflation and elevated tariffs increase project sensitivity to engineering design choices and supplier resilience; energy and ESG imperatives create opportunities for systems that deliver both productivity and sustainability gains; and market fragmentation means that choice of partner will materially influence time-to-value.
PW Consulting’s report equips executives to convert market growth into strategic advantage: a repeatable investment playbook, a prioritized vendor roadmap and scenario-ready financial tools. For readers who require the granular segmentation, vendor scoring, and downloadable TCO templates that empower procurement and program teams, the full report and interactive dashboards are available on our report page.
To request the full report, data tables, or a tailored executive briefing that applies these findings to your specific network footprint and project queue, contact PW Consulting’s industry team via our website.
For detailed analysis of this topic, please visit the official page: Intelligent Automatic Warehouse And Logistic Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com