

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: At-Home Hair Removal Devices Market Poised to Expand at a 7.2% CAGR Through 2032

At-Home Hair Removal Devices Market 2026: Strategic Imperatives from PW Consulting’s New Industry Deep Dive
Executive preview
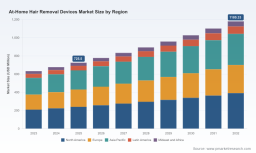
PW Consulting’s latest market research on At-Home Hair Removal Devices provides an authoritative, action-oriented vantage point for executives preparing 2026 strategic plans. The global market reached USD 725.5 Million in our base year (2025) and is positioned to expand to approximately USD 777.7 Million in 2026, accelerating to an estimated USD 1,180.3 Million by 2032. This trajectory represents a compound annual growth rate (CAGR) of 7.2% across the 2026–2032 forecast window, reflecting sustained consumer demand, technology diffusion, and regulatory maturation.
At Home Hair Removal Devices Market
Why this matters for corporate decisions in 2026
-
Timing matters: The market’s steady, above-market CAGR signals a window in which product launches, regulatory approvals, and channel investments can compound value quickly. Companies that align 2026 product roadmaps with validated safety and ease-of-use claims will accelerate adoption curves.
At Home Hair Removal Devices Market -
Regulatory clarity creates optionality: Recent regulatory activity is lowering barriers for credible entrants while imposing predictable compliance costs. Organizations that build regulatory strategy into product design and commercialization timelines will de-risk launch investments and access larger addressable segments faster.
At Home Hair Removal Devices Market -
Concentration and M&A signals: Market concentration is moderate—lead players hold meaningful shares but fragmentation persists—creating fertile ground for bolt-on acquisitions, strategic alliances, and private-label plays that can unlock scale economies or channel access in 2026.
-
Cost and supply-side pressures: Upward pressure on raw material and electronic component costs is compressing gross margins for manufacturers. Firms that prioritize supply-chain resilience and design-for-cost will protect margins even as pricing dynamics evolve.
Market dynamics: what the numbers tell us (and what we intentionally withhold)
Our topline market sizing provides a clear growth arc from 2023 through 2032. After the market’s recovery and expansion in the early 2020s, 2025 stands as a practical planning baseline (USD 725.5 Million) from which corporate 2026 budgets and resource allocations should be built. Forecasts show the sector growing to roughly USD 777.7 Million in 2026 and continuing to expand to more than USD 1.18 Billion by 2032 under a 7.2% CAGR.
While this release shares the high-level trajectory and underlying growth drivers, we intentionally limit disclosure of granular regional, technology and channel splits in this preview. The full report contains the detailed segmentations, sensitivity scenarios, and proprietary demand-models that corporate teams use to allocate R&D, CAPEX, and commercial resources with confidence.
Regulation, reimbursement and product safety: recent developments and implications
-
Regulatory pathway: At-home IPL and laser devices continue to be regulated as Class II medical devices in major markets that require 510(k) clearances for over‑the‑counter marketing. 2025–2026 has seen ongoing 510(k) activity that is validating new models and enabling market entry for established and emerging vendors alike.
-
Recent signals: Multiple manufacturers received 510(k) clearances for ice-cooling and other design enhancements in 2025. For corporate strategists, this trend means that technological differentiation—combined with clear, evidence-based safety claims—can be converted into commercial advantage more rapidly than in the prior decade.
-
Reimbursement reality: At-home hair removal remains predominantly cosmetic and is generally not covered by health insurers. Professional procedures may qualify for reimbursement under specific medical indications, but these are specialty cases. For most device manufacturers, ROI models should therefore assume predominantly cash-pay consumer demand.
-
Supply chain considerations: Rising costs for plastics, metals, and electronic components are non-trivial. Companies should prioritize dual-sourcing, negotiate long-term agreements, and explore design optimizations to reduce part counts and BOM costs without sacrificing safety or efficacy.
Competitive landscape: who’s shaping the market and what they’re doing
The competitive field blends heritage consumer-electronics brands, focused medical-device specialists, and nimble regional challengers. Key companies profiled in our analysis include:
-
Philips (Amsterdam, Netherlands) — A major incumbent offering the Lumea IPL series with SkinAI enhancements and multi‑attachment versatility. Philips leverages global brand equity and service networks to support premium positioning. ( https://www.philips.com)
-
Braun / Procter & Gamble (Kronberg im Taunus, Germany) — The Silk Expert Pro IPL devices emphasize adaptive skin-tone sensing for safety and consistent performance, grounded in consumer trust built over decades. ( https://us.braun.com)
-
Tria Beauty (San Leandro, California, USA) — A specialist distributor of diode‑laser at-home devices, offering higher‑power, clinical-grade laser technology targeted at customers seeking long‑term permanence. ( https://www.triabeauty.com)
-
Ulike (Hangzhou, China; R&D presence in Seoul) — Competitive advantage from cooling‑enhanced IPL systems designed for painless experiences, and aggressive digital marketing in Asia-Pacific markets. ( https://www.ulike.com)
-
Cyden Ltd / SmoothSkin (Swansea, UK) — Focused IPL product portfolio engineered for consumer adoption and broad retail distribution. ( https://www.smoothskin.com)
-
Remington (USA; owned by Spectrum Brands) — Longstanding consumer grooming brand presence with IPL product lineups targeting mainstream retail. ( https://www.remingtonproducts.com)
-
Silk’n (Home Skinovations; Israel) — Developer of IPL and alternative light-based at-home devices emphasizing compact design and price accessibility. ( https://silkn.com)
Collectively, the market shows a moderate level of concentration: the top three firms account for roughly one-third of the market, while the leading five capture close to half. That structure creates both defensive imperatives for incumbents and acquisition or niche‑opportunity pathways for challengers.
Strategic playbook for 2026: five concrete moves
-
Embed regulatory planning in product development: Allocate budget to preclinical testing and 510(k)-or-equivalent documentation early. First-to-market clearances for safety-enhancing design features (e.g., active cooling, skin-tone sensing) translate to durable shelf advantage.
-
Prioritize channel segmentation and digital-first go-to-market: E-commerce continues to be a dominant acquisition channel; however, hybrid strategies that blend online education, subscription consumables, and limited experiential retail create higher lifetime value.
-
Design for cost without diluting trust: Modular product platforms reduce SKUs and lower inventory risk. Standardize electronics across models; differentiate via software, attachments, and service.
-
Pursue tactical M&A and partnership plays: With moderate concentration, bolt-on acquisitions can deliver rapid access to geographic or technology niches. Consider partnerships with dermatology clinics and telehealth platforms to create hybrid care-to-consumer funnels.
-
Operational resilience and component strategy: Hedge exposure to commodity cycles via long-term supplier contracts, early component qualifying, and by exploring alternative materials or assembly geographies that preserve regulatory compliance.
What PW Consulting’s full report delivers (highly practical content)
This release is an executive preview. The complete report is an operational toolkit designed for 2026 decision-makers and includes:
-
Proprietary demand models (historical 2020–2025 and forecast 2026–2032) with scenario analytics to stress-test investment cases;
-
Segment-level playbooks across region, technology, and channel (note: granular segment data withheld in this preview to protect proprietary modeling and to direct stakeholders to the full report);
-
Regulatory pathway matrices and step-by-step 510(k) preparation checklists for teams planning U.S. launches;
-
Commercialization templates: sample launch plans, promotional mixes, and SKU rationalization frameworks tailored to different buyer personas;
-
Supplier risk heatmaps, BOM cost scenarios, and sourcing playbooks to preserve margins under raw material inflation;
-
Competitive benchmarking with strategic implications—detailed profiles, go-to-market tactics, and M&A targets;
-
Scorecards and KPIs for performance tracking post-launch—adoption metrics, unit economics, and churn drivers for subscription models.
Call to action
For senior leaders and product teams mapping 2026 strategy, the full PW Consulting report transforms high-level industry trends into executable programs. If your board is aiming to position for accelerated growth, mitigate regulatory and supply risks, and capture outsized share within the next 18 months, the full dossier contains the segmented forecasts, playbooks, and vendor-level intelligence necessary to move from intent to impact.
Contact PW Consulting to access the complete report and to schedule a strategy briefing. Our analysts will walk your leadership team through tailored scenario planning that uses the report’s proprietary models to quantify investment choices, prioritize markets, and sequence product and regulatory milestones for 2026 execution.
For detailed analysis of this topic, please visit the official page: At Home Hair Removal Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com