

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Heated Windshields Market to Reach USD 3,118.9 Million by 2032 at 7.35% CAGR | PW Consulting
By pmarketresearch, 2026-07-08
Heated Windshields Market: Strategic Intelligence for 2026 Decision-Making
As vehicle electrification, advanced driver assistance systems (ADAS), and rising expectations for occupant comfort reshape automotive architecture, heated windshields have moved from a comfort accessory to a strategic component of vehicle design. PW Consulting’s new Heated Windshields Market study—anchored on a 2025 base year and forecasting through 2032—translates that transformation into a practical, decision-ready intelligence package for executives planning moves in 2026 and beyond.
Heated Windshields Market
Macro snapshot: scale, trajectory, and concentration
The global heated windshields market has expanded steadily through the early 2020s and enters 2026 from a position of maturity into accelerated adoption. Our topline metrics (all values in USD Million) show the market rising from approximately 1.52k in 2020 to roughly 1.89k in 2025, with a compound annual growth rate of 7.35% projected over the upcoming forecast horizon (2026–2032). Under our base scenario the market passes the 2.0k mark in 2026 and approaches 3.12k by 2032—illustrating a durable, multi-year expansion driven by safety regulations, EV thermal-management requirements, and premiumization of vehicle comfort.
Heated Windshields Market
Market structure is moderately concentrated: the three largest players control a majority share, while the top five account for near seven-tenths of the market. This concentration profile creates both barriers and openings—scale matters for OEM contracts, but technological differentiation and focused niche plays remain viable routes to meaningful revenue.
Heated Windshields Market
Why this report matters for 2026 strategies
- Timing for procurement & integration: 2026 is a pivotal year for series introductions and EV platform rollouts. Our study pinpoints where heated windshield technologies intersect with battery thermal management, HVAC design, and ADAS sensor integration—helping sourcing and engineering leaders prioritize supplier qualification timelines.
- Regulatory and safety-driven adoption: With regionally specific regulations and stringent safety standards pushing visibility technologies, manufacturers and Tier suppliers must align product development roadmaps with compliance timelines. The report translates regulatory signals into commercial impact scenarios, enabling executives to prepare capital and production plans with greater confidence.
- Investment and M&A planning: Investors and corporate development teams use the forecast to size target segments, stress-test valuation assumptions under different adoption curves, and identify acquisition candidates that offer accelerants in film-based heating, low-voltage systems, or ADAS-compatible glazing.
- Cost-to-serve and margin optimization: Raw material dynamics—most notably fluxes in silica and soda ash—drive glass production costs. Our practical cost models help C-suite leaders anticipate margin pressure and evaluate pass-through strategies or vertical integration options.
What the PW Consulting study delivers (practical, executable content)
- Topline market forecast (2020–2032) with scenario analyses calibrated to EV penetration, regulatory adoption, and raw material swings.
- Commercial playbooks for OEMs, Tier glaziers, and aftermarket participants: supplier selection criteria, performance-spec templates, and contract clauses to protect against warranty and delamination risks.
- Technology deep-dive: comparative performance mapping across conductive coatings, film-based heating, laminated integration, and low-voltage architectures—framed against unit energy consumption, defogging speed, and ADAS sensor compatibility.
- Go-to-market tools: distributor and installation channel assessments, pricing ladders, and an ROI calculator for retrofit and OEM programs.
- Regulatory matrix and compliance roadmap: a region-by-region heatmap of safety and equipment mandates, with recommended timing for certification and homologation activities.
- Commercial diligence templates for PE and strategic buyers: supplier scorecards, customer-concentration risk metrics, and post-acquisition integration checklists.
Note: in line with our “trailer” approach, the above describes the actionable components without reproducing the report’s granular segment tables and pricing schedules, which are available in full in the source study.
Competitive landscape — who’s shaping the market
The heated windshield value chain is dominated by established global glass-makers and specialist integrators. Leading firms combine scale manufacturing, global OEM relationships, and continuous product innovation. Our report profiles each of the major incumbents and synthesizes strategic implications for 2026:
- AGC Inc. (Tokyo, Japan) — AGC’s emphasis on transparent film-based systems and energy-efficient thermal control is directly targeted at EV manufacturers seeking minimized parasitic loads. Their 2025 launch of a next-generation transparent-film heated windshield signals a push to be the preferred partner on low-energy platforms.
- Saint-Gobain Sekurit (Courbevoie, France) — With a portfolio focusing on electrically conductive glass that supports rapid defogging and safety-centric performance, Saint-Gobain’s 2025 product optimized for autonomous sensor performance exemplifies the integration of glazing with ADAS validation needs.
- Nippon Sheet Glass / Pilkington (NSG Group, Tokyo/St Helens) — NSG Group has doubled down on smart solutions and solar-control technologies, positioning heated windshields as part of a broader thermal-comfort strategy—important for OEMs balancing cabin cooling and heating loads in EVs.
- Fuyao Glass & Xinyi Glass (China) — These groups emphasize cost-efficient, durable heated windshields and low-voltage options, respectively—critical in high-volume programs where unit cost and supply proximity are decisive.
- Guardian Glass (Auburn Hills, US) & Omni Glass & Paint (Oshkosh, US) — Guardian contributes to mainstream automotive portfolios, while Omni Glass & Paint captures niche OEM and commercial vehicle opportunities with custom solutions for heavy-duty and specialized equipment.
Market dynamics are active: in 2025 several incumbents introduced next-generation offerings—AGC’s transparent film-based product (Mar 2025), Saint-Gobain’s ADAS-optimized system (May 2025), and NSG’s solar-control windshield innovation (Jun 2025)—indicating a competitive tempo in both materials science and systems integration. For 2026, the strategic question for suppliers is not merely product performance, but demonstration of system-level value to OEM battery and ADAS teams.
Industry dynamics, risks and levers
- Regulatory tailwinds: Safety rules and fleet regulations are practical levers. Some jurisdictions already mandate electrically heated windshields for heavier trucks, and EU safety frameworks continue to favor visibility-enhancing technologies. These forces create a predictable base demand for commercial vehicles and fleet replacements.
- Raw materials and cost volatility: Glass production relies on silica, soda ash and other inputs whose price swings affect gross margins. Our sensitivity analysis shows that even modest raw material inflation can compress supplier margins unless offset by efficiency gains or contractual hedges.
- Technology and integration risk: The rising importance of ADAS requires heated windshield solutions that do not degrade sensor performance. Solutions that combine defogging, deicing, solar control, and sensor transparency will command premium positioning—but failing to certify early can exclude suppliers from program-level awards.
- Channel and aftermarket considerations: While OEM programs drive scale, aftermarket and retrofit channels remain attractive for specialized applications (commercial, heavy equipment, and regional climates). Our go-to-market scenarios quantify the tradeoffs for 2026 market-entry plays.
How to use this intelligence in 2026
- OEMs: Use the report’s integration checklists to validate supplier R&D roadmaps against vehicle architecture and ADAS validation timelines. Prioritize partnerships with glazing suppliers that can demonstrate low-energy heating and sensor transparency under lab and field conditions.
- Tier suppliers: If you manufacture conductive coatings, films, or laminated assemblies, deploy the supplier scorecard in the report to benchmark where to invest (capacity, automated assembly, or certification) to win 2026 platform awards.
- Investors: Leverage the forecast and sensitivity scenarios to stress-test deal models; focus on targets with demonstrable cost structures and defensible technology IP, as market concentration favors scale but niches remain for differentiated players.
- Policy makers & fleet operators: Use the regulatory impact mappings to align procurement cycles and retrofit programs that maximize safety gains while controlling lifecycle costs.
Methodology & credibility
The study synthesizes primary supplier interviews, OEM procurement data, material cost indices, and bottom-up unit modeling. Base year data is anchored to 2025 and the forecast window extends to 2032 under multiple scenarios. For readers who require granular regional, type, and application breakdowns—including the full tables, supplier scorecards, and detailed pricing models—these are deliberately reserved to the full report to preserve the integrity of proprietary inputs and to ensure actionable uptake by commercial teams.
Next steps
For executives drafting 2026 budgets, negotiating supplier contracts, or evaluating strategic investments in glazing and thermal solutions, the PW Consulting Heated Windshields Market study provides both the strategic framing and the operational tools to move from analysis to execution. Access the full report to retrieve the detailed segment tables, supplier maps, and downloadable decision-support tools that convert this high-level intelligence into winning commercial actions.
For detailed analysis of this topic, please visit the official page: Heated Windshields Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Fireworks Market Poised for 6.5% CAGR — Strategic Outlook
By pmarketresearch, 2026-07-08
Fireworks Market 2026: Strategic Intelligence for Decisions that Spark Value
As enterprises, investors and public-sector planners prepare strategies in 2026, the global fireworks market presents a distinct blend of resilient growth dynamics, legacy manufacturing concentration, emergent safety and regulatory pressures, and accelerating demand-side innovation. PW Consulting’s new Fireworks Market study (base year 2025, historical period 2020–2025, forecast 2026–2032) synthesizes quantitative market-size trajectories with qualitative scenario analysis so leaders can make informed, time-sensitive choices. This article highlights the report’s strategic value for 2026 decision cycles while purposefully omitting detailed sub-segment tables to encourage direct access to the full intelligence product.
Fireworks Market
Macro picture: a compact market with steady momentum
The fireworks market is characterized by modest absolute scale but steady expansion. Between 2020 and the 2025 base year, the market moved from a lower base through consistent year-on-year growth. With a compound annual growth rate (CAGR) of 6.5% projected for the forecast period, the market is expected to continue expanding from the 2025 base into the early 2030s. By 2026 the market is poised to register a notable uplift as pent-up event demand, product innovations and geographic recovery converge; projections in our study extend through 2032 to map longer-tail scenarios and sensitivity to regulatory shocks.
Fireworks Market
Why this matters for 2026 decisions
- Timing of investment and capacity decisions. The market’s steady CAGR means that incremental capacity additions and targeted capital expenditure can still yield attractive returns—provided they are timed to avoid short-term regulatory or production interruptions. Our report provides validated demand curves and scenario-based timing recommendations so procurement and operations leaders can phase investments rather than overcommit to cyclical peaks.
- Supply-chain and sourcing risk management. A concentrated manufacturing geography remains central to global supply. Disruptions in key clusters have outsized system effects—making dual-sourcing strategies and near-shoring analyses high-priority items for 2026 supply agendas. The report models supplier interruption scenarios and quantifies inventory strategies tied to different risk tolerances.
- Regulatory and reputational risk calibration. 2026 will be a pivotal year for compliance-led decisions: recent safety incidents have prompted intensified scrutiny and temporary enforcement actions. Our dynamics chapter maps likely regulatory trajectories across major jurisdictions and translates them into compliance cost bands and timeline impacts for product certification, testing and transport protocols.
- Portfolio and go-to-market optimization. Manufacturers and event producers must reconcile traditional product lines with experiential offerings—large-scale displays, indoor pyrotechnics, hybrid live-digital spectacles, and in some markets non-pyrotechnic alternatives. The study offers playbooks for portfolio rationalization, channel prioritization, and pricing tactics that reflect seasonality and event-driven demand.
What the report contains (practical, executable assets)
- Market-sizing model (2020–2032) with baseline and three stress-case scenarios, delivered in spreadsheet-friendly format for board-level what-if analysis.
- Segment and application-level growth drivers with qualitative overlays on seasonality, festival calendars and B2B event pipelines—presented as decision-ready narratives rather than raw tables.
- Supply-chain risk maps that identify single-point-of-failure suppliers, critical raw-material dependencies and logistics chokepoints, with mitigation playbooks and inventory heuristics for each risk tier.
- Regulatory-impact framework that translates safety incidents, probable policy responses and certification trajectories into quantitative margin pressure and time-to-market estimates.
- Competitive landscaping and capability heatmaps for leading manufacturers and display houses, including IP, certification footprints, product breadth and route-to-market strengths.
- M&A and partnership opportunity screening, with quantified valuation levers, integration risks and proposed deal structures tailored to strategic buyers, private-equity sponsors and strategic alliances.
- Scenario-based tactical recommendations for commercial teams—pricing strategies, channel incentives, and event-centric product bundles optimized for 12–24 month horizons.
- Executive dashboards and investor-ready slide templates that distill the analysis into concise decision materials for board meetings and capital committees.
Competitive landscape: mature crafts, rising modernizers
The market remains a mix of heritage family-owned manufacturers—many operating in long-standing production clusters—and smaller professional display firms with deep event expertise. Our competitive analysis assesses capability differentiation across production scale, certifications, export networks, and services for professional displays.
Fireworks Market
- Established manufacturing clusters in traditional production centers continue to supply the majority of consumer and display-grade product lines. Many of these manufacturers have expanded export capabilities, achieved international certifications and maintain extensive cooperative factory networks to manage seasonal demand.
- Professional display houses in major end markets retain strong positions in large-scale events and custom shows through in-house technical teams, logistics capabilities, and legacy client relationships. Their value lies less in volume manufacturing and more in end-to-end event orchestration and safety governance.
- Across both groups, differentiation increasingly depends on demonstrable compliance (international safety standards), product innovation (effects, reliability, environmentally conscious formulations), and the ability to execute cross-border logistics under tightened regulatory regimes.
PW Consulting’s profiles of leading players examine how certification credentials, cooperative production models, joint-venture footprints, and century-spanning reputations translate into strategic advantages or vulnerabilities. The study also assesses how trade-show activity, product launches and on-site demonstrations signal evolving market positioning in 2026.
Regulatory shock and the Liuyang inflection
2026 introduced a notable regulatory inflection point following a major safety incident at a manufacturing facility in a primary production cluster. Authorities ordered temporary production halts across local manufacturers, demonstrating how single-site events can cascade into global supply interruptions and compliance reassessments. Simultaneously, that production cluster remains the historic heart of fireworks manufacturing, hosting hundreds of specialized operations and dense supplier ecosystems.
Our Dynamics chapter places this event in context: we quantify immediate output loss scenarios, model the transmission of shortages to major consuming regions, and outline pragmatic remedial measures—ranging from accelerated alternative sourcing and inventory strategies to supplier audits and third-party certification acceleration. We also model the potential medium-term policy responses, from heightened factory inspections to revised storage and transport regulations, and estimate the operational cost impact under each policy scenario.
Opportunities and threats mapped for 2026
- Opportunities: Specialized display services, safety-as-a-service offerings (certification, on-site QA), premium event packages, and product lines emphasizing reduced-noise and lower-smoke formulations. Strategic entrants can capture premium margins by pairing validated safety credentials with event-management competencies.
- Threats: Heightened regulatory enforcement, concentration risk tied to production clusters, raw-material price volatility, and the competitive pressure of non-pyrotechnic experiential technologies (drones, AR/VR spectacles) in high-profile events.
- Consolidation potential: Low-to-moderate market concentration among top players leaves room for roll-up strategies that prioritize compliance, distribution control, and service bundling. The study identifies acquisition archetypes that can both reduce compliance exposure and unlock cross-border sales synergies.
How executives should act in 2026
- Prioritize short-term resilience: implement dual-sourcing, increase critical-safety inventories selectively, and accelerate third-party compliance checks for key suppliers to mitigate stoppage risk.
- Invest in certification and traceability: buyers and brands that can prove higher compliance will secure premium event contracts and reduce insurance costs.
- Rebalance portfolios: consider shifting capital toward experiential event services and hybrid offerings that combine pyrotechnics with digital augmentation.
- Prepare for policy tightening: integrate regulatory scenario planning into capital allocation and pricing models; update contractual clauses to reflect force majeure and extended lead-time realities.
- Scan M&A selectively: target assets that provide distribution control in key consuming markets or that bring differentiated safety and testing capabilities.
Why PW Consulting’s report is a strategic asset
The study is designed as a decision-enabler for 2026. It combines a rigorously validated market-size model (with transparent assumptions and sensitivity tests), actionable playbooks for supply-chain and regulatory risk mitigation, and competitive profiles that identify concrete pathways to strengthen market position. Importantly, the analysis is calibrated to preserve confidentiality of sensitive sub-segment economics in this preview—enabling clients to use the report as a practical playbook while we retain the granular segmentation and proprietary data for direct subscribers.
Next steps
For corporate strategy teams, procurement leaders, event producers, and private-equity investors considering deals in or adjacent to the fireworks ecosystem, the full PW Consulting Fireworks Market study provides the operational detail and scenario-level diagnostics required to act with confidence in 2026. Visit our report page to access the full dataset, downloadable models, and bespoke advisory options that translate study insights into executable 12–36 month plans.
For detailed analysis of this topic, please visit the official page: Fireworks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Medical Refrigerator Market to Hit USD 3,002.04 Million by 2032 (4.55% CAGR)
By pmarketresearch, 2026-07-08
Medical Refrigerator Market—Strategic Briefing for 2026 Decisions
Executive snapshot
As healthcare systems prioritize cold-chain integrity and regulatory scrutiny tightens around vaccine and biologic storage, the medical refrigerator market is transitioning from a steady replacement cycle into a period of purposeful investment. PW Consulting’s latest study (base year 2025) synthesizes historical performance, regulatory inflections, and forward-looking scenarios to equip executives with the actionable intelligence needed to make confident 2026 capital, product and M&A decisions.
Medical Refrigerator Market
Why this research matters for 2026
- Timing of investments: 2026 is a hinge year for many buyers—hospital systems updating pharmacy infrastructure, manufacturers optimizing product portfolios, and distributors refreshing logistics offerings. Our analysis isolates the pockets of demand that will be purchase-ready in 2026 versus those likely to defer.
- Regulatory convergence: New clearances and certification guidance across major markets are reshaping competitive parity. Understanding which product features translate into procurement preferences (and reimbursement uplift) is essential to avoid product obsolescence.
- Strategic capital allocation: With moderate but durable growth projected, firms must choose where to prioritize R&D, channel expansion, or bolt-on M&A to outpace peers without overextending balance sheets.
Market trajectory — what the macro numbers tell us
The medical refrigerator market demonstrated resilient growth through the early 2020s, expanding from an estimated USD 1,800.0 million in 2020 to USD 2,198.6 million in 2025 (base year). Our forecast model projects the market will continue on a compounded expansion path, reaching approximately USD 3,002.0 million by 2032, reflecting a CAGR of 4.55% for the forecast period. These macro dynamics are driven by a combination of sustained demand for vaccine and biologic storage, upgrades to laboratory infrastructure, and incremental adoption of specialized temperature-range products.
Medical Refrigerator Market
What this means for 2026 decision-makers
- Revenue predictability vs. product risk: The market’s steady CAGR suggests reliable baseline demand, but pockets of accelerated growth are tied to regulatory approvals, procurement cycles and healthcare capital expenditure plans. Firms should prioritize flexible production and modular feature-sets to capture upside while limiting margin erosion.
- Channel optimization: Distributors and OEMs that redesign commercial models—balancing direct institutional sales with certified channel partnerships—will capture larger share of tender and GPO-driven volumes in 2026.
- Cost-to-serve focus: Cooling technology improvements and energy-efficiency standards are creating differentiation opportunities. Investment in lower lifecycle-cost platforms yields a two-fold benefit: procurement preference and lower total cost of ownership for buyers, supporting premium pricing.
- M&A and JV opportunities: Given moderate market concentration and continued fragmentation across product niches, targeted acquisitions (technology, regional distribution, or service capability) can deliver immediate scale and fill go-to-market gaps faster than organic build.
Competitive landscape — interpretive summary
The market is characterized by a mix of specialized medical-grade manufacturers, global life-science incumbents, and well-capitalized regional players. The top three firms account for a meaningful portion of revenue, while the top five increase that share further—indicating moderate concentration but continued room for challengers that can demonstrate product differentiation or superior service.
Medical Refrigerator Market
- Helmer Scientific (USA): A specialist in pharmacy, blood bank and laboratory refrigeration with strong certifications for vaccine storage. Helmer’s emphasis on compliance and healthcare-focused channel relationships positions it well in institutional procurement, but scale expansion will depend on international distribution and aftermarket service network buildout.
- B Medical Systems (Luxembourg): A global cold-chain supplier with breadth across vaccine, blood bank and plasma storage. Its credentialing across major regulatory regimes provides access to public health tenders; strategic focus should be on consolidating service contracts and optimizing cost structure for emerging markets.
- PHCbi (Japan): A technology-led provider whose recent regulatory successes enhance its product credibility. In June 2025 PHCbi received U.S. FDA 510(k) clearance for new pharmaceutical refrigerator models—an event that will materially influence procurement cycles in markets that prioritize cleared devices.
- Thermo Fisher Scientific (USA): Leveraging a broad laboratory portfolio, Thermo Fisher supplies refrigerators as part of integrated lab solutions. Cross-selling to existing laboratory customers and leveraging global logistics is its key advantage; maintaining product differentiation within a broader catalog is the tactical challenge.
- Accucold (Felix Storch, USA) and American Biotech Supply (ABS, USA): Both operate with strong brand recognition in performance and certified vaccine storage niches. Their ability to service retrofit and replacement demand—combined with NSF/ANSI certifications—makes them credible choices for customers prioritizing proven compliance.
Signals to watch in 2026
- Regulatory approvals and guidance: New clearances or updated vaccine storage standards will re-rank competitive advantages quickly. Monitor regulatory calendars in core markets.
- Procurement cycles at system level: Tenders from large hospital networks and public health programs have a disproportionately large impact on order books—timing and pre-qualification are decisive.
- Energy and sustainability benchmarks: New efficiency standards will reshape total cost models and influence procurement specifications; early movers with validated lifecycle analyses will command premium positioning.
- Service and digital enablement: Remote monitoring, predictive maintenance and validated temperature logging are becoming baseline expectations rather than optional features.
What the report delivers — practical contents for teams executing in 2026
PW Consulting’s full report goes beyond high-level narrative to provide operationally-relevant tools that teams can deploy immediately:
- Market sizing and methodical vintage modeling with an auditable workbook (base year 2025; forecast 2026–2032).
- Scenario-based revenue models reflecting regulatory shifts, procurement wave timing and technology adoption curves (including a conservative, base, and accelerated case).
- Buyer personas and procurement playbooks tailored for hospitals, public health agencies, laboratories and private clinics—mapping evaluation criteria, certification requirements, and decision timelines.
- A regulatory and standards matrix highlighting certification pathways (FDA, EU MDR, WHO PQS, NSF/ANSI and equivalents), plus guidance on dossier prioritization to accelerate approvals in key markets.
- Go-to-market roadmaps: direct sales vs. distributor hybrid models, tender capture checklists, pricing ladders and service contract templates to protect margin on replacement cycles.
- Competitive benchmarking: capabilities heatmaps for leading suppliers, feature gap analysis, and an M&A target shortlist with rationale, valuation heuristics and integration risks.
- Operational playbooks for manufacturability, supply-chain resilience and aftermarket service scaling—including vendor scorecards and break-even analyses for regional service hubs.
How to use the research to make confident 2026 bets
- CEOs and corporate strategy: Use scenario outputs to set capital allocation bands for R&D, M&A and channel expansion—aligning investment pace to the forecasted CAGR and your desired market-share trajectory.
- Product and R&D leads: Prioritize features that materially influence procurement decisions (validated temperature control, energy efficiency, remote monitoring) and defer investments that do not improve selection likelihood within the next two procurement cycles.
- Commercial teams: Reorient sales incentives around tender capture and service contract renewal. The market favors suppliers that can demonstrate lower total cost of ownership and proven compliance.
- Corporate development: Target acquisitions that close gaps in service footprint or digital capabilities rather than acquiring for pure revenue scale—integration value will be realized fastest where service and certification synergies exist.
Market concentration and competitive opportunity
The market shows moderate concentration: the top three players account for a material share of revenue, and the top five increase that share further—leaving meaningful opportunity for focused challengers. This structure supports targeted consolidation strategies: well-executed M&A or strategic partnerships can shift competitive dynamics quickly if combined with disciplined post-merger integration and service expansion.
Conclusion — the strategic lens for 2026
For executives planning 2026 actions, the imperative is clear: convert macro predictability into micro advantage by aligning product roadmaps, regulatory strategies and go-to-market execution. The market’s steady compound growth affords a window to scale thoughtfully—rewarding those who can marry compliance credibility with lower lifecycle cost and superior service delivery.
PW Consulting’s full Medical Refrigerator Market report contains the granular segmentation, financial models, and supplier scorecards required to operationalize these insights. The executive summary above is designed to show the strategic contours and immediate decision levers; the detailed datasets and playbooks needed to finalize 2026 budgets and M&A targets are available in the complete study.
For detailed analysis of this topic, please visit the official page: Medical Refrigerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ESR Analyzers Market to Reach USD 86.4M by 2032 at 4.6% CAGR
By pmarketresearch, 2026-07-08
ESR Analyzers Market 2026: Strategic Preview for Corporate Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, actionable preview of our ESR Analyzers Market research — timed for the strategic inflection many organizations face when shaping 2026 priorities. This briefing synthesizes the report’s analytical framing, the market’s recent trajectory, competitive dynamics, and the regulatory and technology forces that will determine winners and laggards over the 2026–2032 forecast period.
ESR Analyzers Market
Why this study matters for 2026 planning
Clinical laboratories, diagnostic OEMs, investors, and procurement organizations are moving into 2026 with limited runway to recalibrate product roadmaps, supply-chain arrangements, and compliance programs. Our research distills the evidence base that should inform those choices. The market for ESR analyzers is advancing steadily — underpinned by demand for higher automation, faster turnaround, and tighter laboratory integration — but it is not a high-growth breakout market. Instead, measured expansion and technology substitution characterize the opportunity, creating a premium on disciplined market segmentation and execution.
ESR Analyzers Market
Snapshot: historic performance and the forward path
- Historic base: The analysis uses 2025 as the base year and reviews market behavior from 2020 through 2025 to establish demand drivers, adoption inflection points, and cost curves.
- Near-term momentum: Between 2020 and 2025 the global ESR analyzers market expanded from roughly USD 50 million to approximately USD 63 million (revenues reported in USD Million), reflecting steady investment by clinical labs into automation and sample-processing efficiency.
- Forecast outlook: Over the 2026–2032 forecast period our model projects compound annual growth of 4.6%, with the market continuing to grow as laboratories adopt higher-throughput automated platforms and as regulatory and interoperability requirements drive replacement cycles.
These headline numbers matter because they frame the scale of opportunity: the market is large enough for specialized players to compete profitably, but small enough that incremental share gains require focused commercial strategies and product differentiation rather than broad, undirected sales efforts.
ESR Analyzers Market
Core market dynamics shaping 2026 strategy
- Technology substitution: Faster analytical techniques and closed-tube workflows are accelerating replacement of legacy manual methods. Devices that deliver rapid results with minimal sample handling and strong LIS integration are increasingly table stakes.
- Throughput segmentation: Different lab profiles — high-volume hospital central labs versus decentralized outpatient or physician-office labs — demand different value propositions. Product line strategies should be tailored to throughput, connectivity, and workflow automation rather than a one-size-fits-all approach.
- Regulatory pressure: A material regulatory change that took effect in early 2026 requires alignment of device quality systems with ISO 13485:2016 as incorporated by reference into FDA QMSR. Manufacturers who have not converged their quality management systems risk delayed clearances, audit remediation costs, and restricted access to certain markets.
- Interoperability and data: Laboratories are prioritizing analyzers offering robust LIS connectivity and bi-directional interfaces. The ability to support real-world IT environments, including middleware and cloud-based lab information systems, materially influences adoption decisions.
- Service and consumables economics: Total cost of ownership (TCO) — including consumable usage, maintenance intervals, and remote-support capabilities — is increasingly a purchase driver, particularly among constrained public-health buyers and mid-sized private labs.
Competitive landscape — profiles and strategic implications
The market features a mix of focused instrument specialists and broader diagnostics groups. We analyzed the competitive positions of key suppliers to extract tactical implications for 2026 moves.
- ALCOR Scientific (Smithfield, RI, USA)
Product strength: Fully automated platforms that emphasize rapid throughput (multi-second to minute-range result claims), closed-tube EDTA sampling, and LIS connectivity. Recent development: launch of a high-throughput iSED PRO with bi-directional LIS support (Nov 2024).
Strategic takeaways: ALCOR’s focus on speed and integration positions it well for large clinical labs pursuing rapid STAT throughput. For competitors, counterstrategies should emphasize differentiated cost structures, service models, or domain-specific integrations (e.g., niche middleware partnerships).
- Diesse Diagnostica Senese (Monteriggioni, Italy)
Product strength: Automated analyzers using modified Westergren methods with direct EDTA tube sampling and STAT capability, tailored for high-volume lab workflows.
Strategic takeaways: Devices that preserve method lineage (Westergren) while reducing handling friction appeal to conservative labs. New entrants should frame validation studies and equivalence data to win these conservative adopters.
- ELITechGroup (Logan, UT, USA)
Product strength: Platforms aimed at mid-to-high volume labs with closed-tube workflows, temperature correction, and random access. Result times in the minutes are balanced with integration and throughput features.
Strategic takeaways: ELITechGroup’s breadth suggests a channel advantage; rivals should assess direct partnerships with large integrated labs or identify underserved microsegments where lighter-weight instruments outperform.
- Alifax (Polverara, Italy)
Product strength: Capillary photometry-based analyzers optimized for very rapid results and no sample consumption, attractive to smaller labs seeking automation without high throughput overhead.
Strategic takeaways: The capillary approach opens distinct clinical use cases. Competitors can either match the speed claims with alternative low-consumption designs or pursue differentiated pricing and consumable strategies.
- RR Mechatronics (Austria)
Product strength: Fully automated Westergren-method analyzers designed for lab automation integration, with high precision and rack-based compatibility for automated lines.
Strategic takeaways: Strong integration with automated lab lines makes RR Mechatronics a natural partner for large consolidation projects; OEMs should design integration toolkits and certified integration services to lower adoption friction.
Across these vendors, the competitive pattern is clear: differentiated performance claims (speed, method fidelity), integration capabilities (LIS, rack automation), and service/consumable economics are the axes on which market share will shift in 2026. Our market model shows a market structure that favors specialists with deep product-market fit; scale helps, but focused execution matters more for share gains than broad product portfolios.
What the PW Consulting ESR Analyzers Market report delivers
Designed for commercial leaders, product strategists, M&A teams, and procurement decision-makers, the full report contains several operational deliverables you can use this year:
- Proprietary market-size model and downloadable dataset (historical 2020–2025, forecast 2026–2032) calibrated at the device and channel level so you can run your own sensitivity analyses.
- Scenario-driven revenue paths (base, accelerated adoption, and downside) to stress-test product launches and commercial investments against realistic adoption curves.
- Vendor scorecards that assess product features, integration maturity, service footprint, and regulatory posture — with clear strengths/weaknesses and suggested countermeasures.
- Regulatory impact matrix including practical steps to align quality systems with the recent FDA QMSR/ISO 13485 reference, and a compliance roadmap tailored for device manufacturers and contract manufacturers.
- Go-to-market playbooks by lab archetype (central hospital labs, commercial reference labs, point-of-care locations) including pricing levers, consumable bundling strategies, and channel models.
- Buy-side playbook and procurement checklist to shorten evaluation cycles and minimize integration surprises (LIS testing, validation protocols, installation and uptime commitments).
- M&A and partnership framework that prioritizes targets by technology fit, service network, and integration complexity — with sensitivity testing for inorganic growth scenarios.
Note: In keeping with the “trailer” principle of this preview, we present the report’s scope and the practical tools it includes, while withholding the granular segment-level tables, regional application breakdowns, and exact vendor share numbers that are available in the full dataset.
Practical recommendations for 2026 executives
- Prioritize compliance readiness now. Update quality systems to align with the post-2025 regulatory reference framework to avoid market-access delays and additional validation costs.
- Target product-market fit over product breadth. For suppliers, concentrate R&D and go-to-market resources on one or two lab archetypes where you can demonstrate clear TCO and workflow benefits within 12–18 months.
- Invest in integration-first engineering. Strengthen LIS/middleware partnerships and publish interoperability test results; labs will favor devices that reduce IT integration risk and validation time.
- Reassess consumables strategy. Consider subscription or reagent-agnostic offerings to reduce buyer resistance and create recurring revenue — but model service economics carefully given the market’s measured growth rate.
- Use M&A selectively. For buyers, look for targets that add integration IP, middleware partnerships, or service coverage rather than only incremental device capacity.
Next step — access the full intelligence
This preview is structured to show the research’s strategic value while preserving the granular analytics that confer competitive advantage. The full PW Consulting ESR Analyzers Market report provides the complete market model, vendor share breakdowns, regional and application segmentation tables, and scenario-based financial projections required to make confident 2026 investment and sourcing decisions.
For organizations preparing budgets, launching new devices, negotiating distribution agreements, or reassessing procurement specifications this year, the report offers executable guidance and the data infrastructure you will need to align your 2026 plans with market realities.
For detailed analysis of this topic, please visit the official page: ESR Analyzers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Vitamin D Market — 2026 Strategic Preview
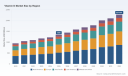
As executive teams set budgets and strategic priorities for 2026, understanding where the Vitamin D value chain is headed is no longer optional — it is a competitive necessity. PW Consulting’s latest Vitamin D Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) synthesizes five years of market behavior with forward-looking scenario analysis. The market reached approximately USD 1,350 million in 2025 and, under our central scenario, expands at a compound annual growth rate of 7.8% across the 2026–2032 forecast window, moving toward a materially larger global footprint by 2032. This preview highlights the strategic takeaways our clients will use to align product portfolios, secure supply, and prioritize investment in 2026 — while reserving the granular regional and application splits for the full report.
Vitamin D Market
Why this research matters for 2026 decision-makers
-
Timing: 2026 is the inflection year for a wave of capacity and regulatory developments that will reshape supplier economics and access to specific Vitamin D formats.
Vitamin D Market -
Risk mitigation: Raw material sourcing (lanolin, lichen-derived D3 and ergosterol-derived D2) is concentrated around a small set of suppliers and processes; procurement teams must re-evaluate counterparty exposure now to avoid costly disruptions.
Vitamin D Market -
Portfolio fit: Formulation choices (oily vs. dry, beadlets, gummies, fortified food premixes) and the rise of plant-based and hybrid offerings demand a reappraisal of product roadmaps to capture higher-margin growth segments.
-
M&A and capacity allocation: Several leading producers have announced capacity and product-line investments; the coming 18–24 months are likely to favor either rapid consolidation or premium niche plays depending on how companies react.
Market trajectory snapshot (what the numbers show)
From 2020 to 2025 the Vitamin D market showed steady recovery and expansion following pandemic disruptions, reaching roughly USD 1.35 billion in 2025. Looking ahead, our central forecast — which incorporates demand-side drivers such as rising supplementation adoption, expanding food fortification programs, and stable feed demand — assumes a 7.8% CAGR through 2032. Under that trajectory, the market more than doubles from the low‑billion base into a multi‑billion opportunity by the end of the forecast window. This represents a compelling growth runway for companies that can pair capacity with differentiated formulations and robust regulatory strategies.
Supply- and demand-side dynamics that will define 2026
-
Raw material architecture: D3 production pathways remain dominated by irradiation of 7‑dehydrocholesterol derived from lanolin, while animal‑free D3 from lichen is an emerging alternative for major formulators targeting clean‑label and vegan segments. D2 continues to be sourced from UV‑irradiated ergosterol in yeast. Each route presents tradeoffs across cost, scalability, and labeling claims that affect product placement and price tolerance.
-
Regulatory inflection points: Late‑2025 and early‑2026 regulatory rulings (including approvals of novel metabolites for animal nutrition) materially change allowable claims and formulations in feed and certain fortified products. Companies that maintain regulatory monitoring and fast adaptation of technical dossiers will enjoy first‑mover advantages.
-
Clinical and public‑health inputs: Large population studies completed through 2025–2026 continue to shape recommendations and consumer perceptions of Vitamin D supplementation. These outcomes influence payer conversations, private‑label uptake, and mass‑market demand elasticity.
-
Manufacturing and onshoring trends: Several market participants have accelerated local production to shorten lead times and appeal to traceability-minded buyers. One leading North American brand has moved the overwhelming majority of its finished‑goods production to domestic facilities — a model that will pressure lesser‑integrated suppliers to offer faster turnaround or strategic partnerships.
-
Product innovation: Expect growth to be driven by format innovation (beadlets, gummies, combined micronutrient premixes) and plant‑based D3 alternatives. Ingredient suppliers that offer performance‑tested beadlets and stable oily-to-dry systems will capture formulators seeking shelf-stability and manufacturing ease.
Competitive landscape — positioning and strategic moves
The Vitamin D value chain blends global commodity producers with branded finishers and regionally focused specialist manufacturers. In our coverage universe, a small set of companies stand out for scale, breadth, or innovative positioning:
-
Global ingredient champions: The world’s largest D3 producers continue to supply both oily and dry formats for supplements, fortified foods, and feed. Their strengths are scale, broad product portfolios, and integrated technical support to large formulators. Expect them to focus on premium, regulated‑food applications and on expanding metabolite and specialty derivatives where regulatory pathways allow.
-
Industrial chemistry and formulation leaders: Large chemical conglomerates active in beadlets and coated formulations are leveraging Verbund sites and application labs to deliver end‑to‑end premixes and turnkey solutions for human and animal nutrition. Product launches in animal nutrition portfolios underline a strategy to deepen downstream integration and capture higher value per ton.
-
Branded supplement manufacturers moving upstream: Consumer brands with high single‑market share have materially expanded manufacturing footprints to secure finished‑goods control, instrument R&D for novel formats, and guarantee supply continuity. This represents a structural shift as brand owners internalize more of the value chain.
-
Specialist fermenters and plant‑based players: Regional producers with pharma‑grade certifications have positioned plant‑based D3 and specialty grades for the nutraceutical market; their agility in certification and niche claims makes them attractive partners for premium and vegan product lines.
Each archetype presents different partnership profiles. Ingredient champions will seek long‑term offtake arrangements and collaborative product development; branded manufacturers will focus on captive capacity and co‑packing; specialists will trade on certification and formulation agility.
Recent strategic developments to watch in 2026
-
Capacity and facility investments completed in 2025 have begun to pipeline additional finished‑goods supply into North America and Europe, reducing lead‑time friction for large retail and contract manufacturers.
-
New combined vitamin formulations aimed at animal nutrition and aquaculture have shifted supplier demand patterns; these product introductions respond to regulatory openings for novel metabolites and higher inclusion rates in feed premixes.
-
Large clinical studies and trial updates through 2025–2026 are influencing public health guidance, which in turn affects OTC supplementation demand curves and formulators’ claims strategies.
Actionable implications and 2026 playbook
-
Secure multi‑tier supply: Negotiate flexible contracts with both global producers and regional specialists. Layer long‑dated capacity agreements for critical grades while maintaining spot access to alternative sources (e.g., lichen‑derived D3) to defend against single‑source failures.
-
Prioritize format economics: Decide, within Q1 2026, whether to standardize on beadlets, oily solutions, or dry premixes for new SKUs — because formulation choice materially affects COGS, shelf‑life, and manufacturing footprint.
-
Embed regulatory agility: Establish a regulatory monitoring cell to track metabolite approvals, claim permissibility across major markets, and food/animal nutrition labeling changes. Approvals can create short windows of competitive advantage for first movers.
-
Invest in sustainability narratives: Validate plant‑based and low‑carbon sourcing claims through third‑party certification and lifecycle assessment. These signals can unlock premium distribution channels in developed markets.
-
Refine M&A criteria: Target assets that address one of three strategic gaps — incremental compliant capacity, specialized process know‑how (e.g., plant‑based D3), or downstream branded channels — rather than chasing scale alone.
-
Stress‑test pricing: Run scenario models that combine raw‑material shocks, formulation shifts, and toggles in fortification policy to set dynamic price floors and rebate terms for 2026 contracts.
What the full PW Consulting report provides (practical deliverables)
Our full study is built for executable decision-making and includes:
-
Transparent methodology, data tables, and forecast models with sensitivity analyses across low, central and high scenarios for 2026–2032;
-
Company profiles and strategic playbooks for major producers and innovators, including capacity maps, recent investments, and M&A pipelines;
-
End‑use demand deep dives (supplements, fortified foods, animal feed) with product-level implications and commercialization timelines;
-
Supply‑chain risk heatmaps, raw‑material cost drivers, and supplier scorecards designed for procurement renegotiations;
-
Regulatory tracker and claim‑risk matrix incorporating recent approvals and pending dossiers that will affect 2026 market access;
-
Go‑to‑market playbooks and due‑diligence checklists for executives evaluating contract‑manufacturing, captive build‑outs, or bolt‑on acquisitions;
-
Interactive dashboards and client workshops to translate the market views into 2026 P&L scenarios and capital allocation plans.
Note: This preview is intentionally high‑level. We withhold granular regional and application splits, and detailed competitive market‑share tables, to preserve the strategic value of the full report and our proprietary models. Clients who require the complete datasets, segment‑level forecasts, and supplier share matrices can access them through PW Consulting’s research portal or via a bespoke advisor engagement.
How to use these insights in Q1 2026
-
Schedule a 90‑minute strategy workshop to stress‑test your supply agreements and align a capital plan with our scenario outputs.
-
Direct procurement to open secondary sourcing conversations for critical grades and formats identified in this preview.
-
Prioritize one pilot SKU for a plant‑based D3 variant if your brand is pursuing vegan positioning — use the pilot to validate cost and claims ahead of broader rollout.
-
Task regulatory and R&D to map product dossiers against the new metabolite permissions and clinical evidence trajectories highlighted here.
PW Consulting’s full Vitamin D Market report is designed to move your 2026 planning from high‑level intent to implementable action. For access to the complete report, data tables, and a tailored briefing for your executive team, please visit our research portal or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Vitamin D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: PVC Compound Market to Hit USD 237M by 2032 at 4.57% CAGR
By pmarketresearch, 2026-07-08
PVC Compound Market — Strategic Outlook for 2026 Decision‑Makers
Executive preview
As companies recalibrate portfolios for a second half of the decade defined by feedstock volatility, regulatory scrutiny and targeted capacity additions, the PVC compound market is entering a phase where strategic clarity delivers disproportionate value. PW Consulting’s latest market research synthesizes five years of historical performance and a forward-looking forecast to 2032, combining quantitative baselines with executable commercial recommendations. This introduction outlines the analytical framing and the high‑value takeaways you should act on in 2026 — while preserving the detailed subsegment tables and proprietary models for subscribers who require the full intelligence package.
PVC Compound Market
Topline context: growth trajectory and what it means
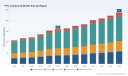
After steady recovery through the early 2020s, the market’s topline expanded markedly between 2020 and 2025. Using our base year of 2025, the market reached a clear inflection compared with 2020, and our scenario-informed forecast anticipates continued expansion to 2032 at a compound annual growth rate (CAGR) of approximately 4.57% over the forecast window. That pace implies a market that is neither hyper‑cyclical nor stagnant: it favors disciplined capital allocation, iterative product innovation, and supply‑chain flexibility rather than speculative capacity builds without demand linkage.
PVC Compound Market
Key dynamics shaping decisions in 2026
-
Feedstock and pricing volatility — Resin and upstream feedstock cycles remain the dominant near‑term risk. Price rebounds in North America and a rebalancing of global PVC availability following Asia’s capacity movements have created a more pronounced short‑term correlation between resin margins and downstream compound pricing than seen in prior cycles. Buyers and compounders that adopt more active feedstock hedging and dynamic pricing clauses will preserve margins in 2026.
PVC Compound Market -
Regulatory pressure and chemical risk evaluation — Vinyl chloride continues to attract regulatory attention in major markets. Recent high‑priority designations and draft scopes of regulatory risk evaluations increase compliance overhead and potential product substitution risk for certain use cases. Firms will need regulatory playbooks and contingency formulations for sensitive applications.
-
Capacity moves and network readjustment — The industry is experiencing selective capacity additions and re‑shoring/relocation of compounding assets, alongside strategic plant modernizations (including low‑carbon manufacturing). These shifts create pockets of tightening and oversupply across regions and product classes, which will influence contract negotiation dynamics and logistics optimization.
-
Concentration and competitive positioning — The market demonstrates a moderate level of concentration among the largest compounders. That structure supports scale advantages in procurement and distribution, but also creates opportunities for specialized or regional players to capture premium niches through technical differentiation and service intensity.
-
Sustainability and circularity as differentiators — Demand for recycled content, lower‑emission production footprints, and halogen‑free or low‑emission grades is shifting customer selection criteria from pure price to total cost of ownership and brand risk mitigation. Early movers with validated circular offerings and traceable supply chains gain preferential access to high‑value customers.
What to prioritise in 2026 — operational and strategic levers
-
Short‑term: secure feedstock flexibility. Implement layered purchase strategies, index‑linked contracts and volume options to protect margins while keeping commercial agility.
-
Medium‑term: rationalise capacity with customer demand mapping. Align incremental plant investment with verified demand pathways — focusing on specialty grades, recycled compound production, and faster time‑to‑market for custom formulations.
-
Regulatory mitigation: embed chemical risk into product roadmaps. Build substitution matrices for sensitive applications, and accelerate testing and certification pipelines for lower‑risk alternatives.
-
Commercial: shift to outcome‑oriented offers. Move beyond commodity pricing to bundled services — technical support, formulation co‑development and sustainability documentation — to protect margins and deepen customer relationships.
-
Portfolio: prioritize specialty and circular products. Given market growth moderated by a mid‑single digits CAGR, value creation will come from higher‑margin niches rather than scale alone.
Competitive landscape — practical implications beyond the headlines
Below we summarise strategic postures of representative players and the implications for buyers, suppliers and potential investors. This is not an exhaustive ranking — our full report contains benchmarking matrices, capability scores and channel maps.
-
Westlake Global Compounds — With a broad global footprint and a product range that spans rigid and flexible systems, Westlake leverages scale in procurement and distribution. Their strengths include integrated supply relationships and a broad portfolio targeted at infrastructure segments. Counterparty strategies should focus on long‑term contracts with flexibility clauses to balance scale benefits and market exposures.
-
Aurora Material Solutions — Known for technical compounding and custom grades, Aurora’s competitive edge is service intensity and formulation agility. For OEMs and specifiers, partnering with such providers is efficient when time‑to‑market and application performance dominate procurement criteria.
-
Benvic Group — A strong European compounder with specialized premix and stabilizer capabilities. Benvic’s regional depth makes it a natural partner for customers seeking localized supply and regulatory alignment in European jurisdictions.
-
Orbia / Polymer Solutions (Vestolit, Alphagary) — Vertical integration across resin, additives and compound formulations gives Orbia strategic optionality. Their brands are often positioned to capture value across multiple stages of the value chain; counter‑strategies include dual‑sourcing and focusing on differentiated technical requirements not served by large integrated suppliers.
-
Manner Polymers — Recent manufacturing modernization and investments in low‑carbon operations position Manner as an emblem of how sustainability can be converted into capacity and customer differentiation. Buyers emphasizing green sourcing should evaluate Manner’s certifications and lifecycle data.
-
DDEV Plastiks Industries — Rapid capacity ramp‑up in emerging markets underscores the competitive pressure from cost‑efficient compounders with export ambitions. For incumbents in mature markets, the response should be a mix of specialization and service enhancement rather than competing solely on price.
-
Thevinyl AB — A niche, customization‑oriented compounder with strength in bespoke formulations. Their model illustrates a profitable path for small‑to‑mid players focused on technical depth and close customer integration.
-
TPV Compound Spa — Deep technical experience in medical and high‑performance technical compounds. This underscores a durable premium segment where regulatory and quality capabilities create barriers to entry.
How PW Consulting’s research converts insight into action
The full PVC Compound Market study we released combines rigorous topline measurement with tailored decision tools aimed at commercial, operational and corporate strategy teams. Key deliverables include:
-
Market sizing and trajectory models anchored to our 2025 base year and extending to 2032, including sensitivity runs on feedstock and demand scenarios.
-
Segment and application frameworks that map addressable markets, substitution risk and price elasticity — with playbooks for growth, defence and exit options per product cluster.
-
Supplier and competitor benchmarking with capability heatmaps, service profiles and strategic intent indicators to guide sourcing and partnership decisions.
-
Regulatory and ESG risk matrices, integrating projected policy trajectories with product exposure to help compliance, R&D and procurement teams prioritise mitigations.
-
Commercial tools — pricing algorithms, contract clause templates and customer segmentation models — designed to be operationalised by sales and customer success functions.
-
M&A and portfolio optimisation guidance, including acquisition target archetypes and integration risk checklists for buyers and private equity investors focused on the mid‑market.
Final takeaways for 2026 planning cycles
The PVC compound market presents a classic “manage for resilience, invest for differentiation” scenario in 2026. With a steady underlying growth trajectory and clear headwinds from feedstock and regulatory dynamics, the highest value moves are those that (1) lock in feedstock optionality and predictable margins, (2) accelerate transition to higher‑value, lower‑risk product classes, and (3) align capital deployment with verified, sustainable demand pathways rather than short‑term volume chasing.
PW Consulting’s full report equips executives with the granular segmentation, supplier scores, and scenario tools to operationalise those moves. For teams preparing budgets, negotiating agreements, or assessing acquisition targets in 2026, our analysis converts market direction into measurable actions.
Next step
For the complete dataset, proprietary segmentation tables, and the hands‑on playbooks referenced here, visit PW Consulting’s PVC Compound Market page to access the full report and supporting models. Stakeholders who wish to discuss tailored scenario runs or a bespoke supplier assessment can contact our industry practice for a briefing and implementation roadmap.
For detailed analysis of this topic, please visit the official page: PVC Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Concrete Vibrator Market to Expand at 4.8% CAGR Through 2032
By pmarketresearch, 2026-07-08
Concrete Vibrator Market: Strategic Brief for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a concentrated strategic preview of our Concrete Vibrator Market research — designed to equip executives, product leaders, and corporate development teams with the insights required to make confident 2026 investment and operational decisions. The market has evolved beyond a simple equipment play; product architecture, ergonomic design, electrification, regulatory compliance and channel economics now determine winners. This brief synthesizes the research’s macro view, competitive dynamics, regulatory and innovation vectors, and the practical, executable intelligence contained in the full report — while preserving the granular segment tables and company-level revenue breakdowns for subscribers.
Concrete Vibrator Market
Why this market matters in 2026
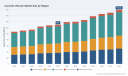
The global concrete vibrator market reached USD 130.0 Million in 2025 (base year) after steady growth through the 2020–2025 period, and our forecast model projects expansion at a compound annual growth rate (CAGR) of 4.8% through 2032, reaching roughly USD 180 Million by the end of the forecast window. That trajectory reflects a combination of infrastructure refresh cycles, increased construction activity in selected markets, and a technology shift toward electrified, ergonomic and modular solutions that reduce labour intensity and improve quality control on site. For 2026 decision-makers, the implications are simple: product and channel strategies that align with these underlying drivers can convert moderate market growth into outsized returns.
Concrete Vibrator Market
Macro dynamics shaping opportunity
- Electrification and cordless mobility: Battery-powered and cordless backpack units have moved from niche to mainstream in innovation roadmaps, driven by site cable management concerns and a preference among contractors for cordless tooling systems. This change elevates battery-pack supply chains and creates cross-sell potential with power-system OEMs.
- Performance differentiation through frequency and control: High-frequency platforms with variable-speed control enable better consolidation performance across diverse concrete mixes. Variable-speed control also supports energy efficiency and operator safety compliance, making it a fast-emerging feature premium buyers will pay for.
- Ergonomics and modularity: Reduced weight, improved ergonomics and interchangeable shaft/head systems are changing replacement cycles and aftermarket revenue dynamics. Modular systems expand addressable use-cases and simplify rental/dealer stocking strategies.
- Regulatory and certification thresholds: Market access increasingly depends on international certifications and safety approvals. CE marking and similar approvals are gating factors for growth in developed markets, affecting product development timelines and go-to-market sequencing.
- Market structure and concentration: The market exhibits moderate concentration. The top three and top five incumbent groups provide meaningful competitive anchors, but a long tail of regional and specialist manufacturers keeps pricing pressure and innovation incentives high.
Competitive snapshot — strategic positions to watch
Our analysis covers global OEMs, specialist manufacturers and adjacent-tool incumbents that have recently expanded into concrete consolidation. Several strategic patterns stand out across the competitor set:
Concrete Vibrator Market
- Systems incumbents pursuing electrified mobility: Established manufacturers are launching high-frequency internal vibrators and cordless backpack models to capture demand among contractors who prefer reduced cable clutter and higher mobility on site. These offerings target a higher-margin segment of the market and align with broader electrification trends across construction equipment.
- Ergonomics and operator-first design: New platform iterations emphasize lighter weight, better handling and reduced vibration transfer to operators. Ergonomics has emerged as a purchase driver for mid-to-large contractors that quantify safety and productivity gains.
- Modular and interchangeable architectures: Suppliers emphasizing interchangeable shafts and multiple head options reduce the number of SKUs dealers must carry, supporting rental strategies and enabling faster fleet customization.
- Compliance-driven market entry: Recent certifications and market-specific launches demonstrate a strategic focus on regulatory-compliant entries into high-value regions; this is a necessary investment for suppliers serious about scale.
Representative entrants and their strategic plays (high-level):
- A group of legacy construction-equipment OEMs has moved to high-frequency internal platforms and battery-backed backpack units to defend share and pursue higher ASPs through technology bundling.
- Specialist manufacturers continue to compete on SKU breadth, flexible shaft offerings and OEM supply partnerships, maintaining relevance in regional markets and the rental channel.
- New and adjacent-tool entrants are leveraging cordless tool ecosystems to cross-promote battery systems and accessories, creating potential channel conflict but also cross-market synergies.
Recent moves and what they signal
- Multiple product launches in 2025–2026 show suppliers racing to commercialize electrified, high-cycle and ergonomically refined platforms. These are not incremental updates; they change procurement economics on job sites with constrained labour and strict timeline penalties.
- Certification wins in late 2025 and early 2026 underline the transactional importance of regulatory compliance for EU market access — a requirement that changes product release sequencing and distribution strategy.
- Platform launches at major trade shows mark a shift to system-level selling: tool + powerpack + service contracts — increasing lifetime revenue per customer if suppliers can unlock aftermarket service economics.
Practical implications for corporate strategy in 2026
- Product roadmap prioritization: If your business competes in internal vibrators or portable consolidation tools, prioritize investments in high-frequency motors, variable-speed control, battery-integration and ergonomic design. Time-to-market for certified variants will be a competitive differentiator in key buyer geographies.
- Channel & go-to-market alignment: Reposition channel incentives to support rental houses and dealer service capabilities. Rental penetration materially alters replacement cycles and increases the value of durable, serviceable designs.
- Aftermarket and service strategy: Build warranty and service propositions tied to preventive maintenance and quick-change modular components. Aftermarket margins can offset initial price competition in new product launch phases.
- M&A and partner criteria: Look for targets that add capabilities in battery systems, ergonomics engineering, certification track record, or dealer footprint in high-growth local markets. Smaller specialist OEMs with strong rental or dealer relationships are attractive tuck-in candidates.
- Supply chain resilience: Secure alternate sourcing for key subsystems (motors, battery packs, flexible shafts) and de-risk logistics for components subject to trade-policy or tariff exposure.
Risk factors and mitigants
- Price competition from low-cost manufacturers: Maintain a clear product differentiation and service play to protect margins; compete on total cost of ownership rather than unit price.
- Certification and regulatory delays: Proactively map certification timelines into product development and pre-market investments to avoid lost selling seasons in regulated markets.
- Channel fragmentation: Simplify SKUs where possible and invest in dealer training and digital ordering to reduce friction and inventory costs.
- Technology substitution: Monitor adjacent consolidation technologies and materials innovation that may change consolidation requirements; retain R&D optionality to pivot motor and shaft designs.
What the full PW Consulting report delivers (practical contents)
- Proprietary market model (2020–2032) with baseline, upside and downside scenarios driven by construction cycles and product-adoption curves.
- Competitive benchmarking by product architecture, channel strategy, certification status and aftermarket model.
- Detailed go-to-market playbooks for launch, dealer enablement, rental partnerships and OEM alliances.
- Pricing and margin matrices, including suggested pricing ladders for electrified vs. legacy platforms and regional go-to-market sensitivity analyses.
- Supply-chain heat map identifying critical component risk and recommended nearshoring/dual-sourcing actions.
- M&A target shortlists and valuation frameworks tailored to strategic buyers.
- Primary interviews with contractors, rental operators and dealers that validate feature willingness-to-pay and procurement preferences.
- Regulatory tracker and certification timelines for major markets, including EU compliance checklists and recommended testing roadmaps.
Note: this preview deliberately omits the granular regional, type and application revenue splits and individual company revenue breakdowns included in the full dataset — those tables, transaction views and downloadable models are available only in the complete report.
Recommended next steps for executives
- Secure the full PW Consulting report and Excel model to access the granular segmentation, dealer maps and company revenue benchmarks needed for actionable planning.
- Convene a cross-functional 90-day “market capture” sprint: product, supply-chain, sales and finance — with charter to define a launch sequence for an electrified/ergonomic variant and an aftermarket monetization plan.
- Initiate targeted diligence on potential acquisition targets that close capability gaps in battery systems, modular shafts, or certification expertise.
- Implement short-term channel pilots with rental partners in two prioritized markets to validate unit economics and refine TCO messaging.
In summary, the concrete vibrator market in 2026 offers predictable growth underpinned by structural product shifts rather than a cyclic boom. Companies that marry product innovation (electrification, high-frequency control, ergonomics) with intelligent channel and service models will extract disproportionate value. PW Consulting’s full report provides the granular data, scenario models and prescriptive playbooks required to convert strategic intent into measurable market share and margin gains. Contact PW Consulting to request the full report, the underlying Excel model, or a tailored advisory engagement to accelerate decision-making.
For detailed analysis of this topic, please visit the official page: Concrete Vibrator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Thermal Paper Market 2026: Strategic Imperatives for Corporate Decision‑Makers
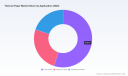
As PW Consulting publishes its 2026 Thermal Paper Market study, the sector sits at a strategic inflection point. After a measured recovery through 2020–2025 the global thermal paper market reached roughly USD 4.51 billion in the base year (2025) and is projected to expand at a mid‑single‑digit compound annual growth rate (CAGR) of about 5.0% across the 2026–2032 forecast window—driving the market toward the low‑to‑mid USD 6 billion range by the end of the period. These headline figures mask important structural shifts in supply, regulation, raw materials and buyer behaviour that will determine winners and losers over the next three to five years.
Thermal Paper Market
Why this study matters for 2026 decisions
- Immediate commercial impact: Input cost pressures and coordinated pricing actions by major coaters in early 2026 have created a new pricing baseline. Corporates must decide quickly whether to absorb, pass through, or strategically renegotiate long‑term contracts.
- Regulatory and reformulation risk: Public policy and chemical regulators are accelerating the shift away from legacy developers in thermal coatings; this drives near‑term compliance costs and medium‑term product roadmaps.
- Supply chain fragility: Structural bottlenecks in key chemical developers and uneven energy/pulp cost dynamics mean procurement and continuity planning are now front‑line strategic issues.
- Portfolio and M&A sizing: The market remains moderately consolidated at the top end, but fragmentation across regional mills and specialty coaters creates attractive bolt‑on targets for industrial consolidators and financial sponsors.
Current market dynamics: what is changing
- Price resets and margin pass‑through: Several leading producers announced synchronized price increases in early 2026—an explicit response to elevated energy, chemical and logistics costs. This reset changes negotiation dynamics for distributors, large retail chains and label converters and will influence purchasing cadence through 2026.
- Regulatory acceleration: The enforcement of state‑level bans on bisphenols (first implemented at the state level in the U.S. on January 1, 2026) and classifications by major chemical authorities are pushing customers and suppliers toward phenol‑free developer systems, certified alternatives, and new testing requirements. Compliance timelines vary by jurisdiction, but the direction is clear: reformulation is a must for market access in key markets.
- Raw material concentration risk: Key leuco‑dye developers and other coating intermediates are in tight global supply, creating episodic shortages and spot volatility. At the same time, mills in regions exposed to energy and pulp cost inflation experienced double‑digit input cost increases in late 2025—forcing many suppliers to choose between margin erosion and customer price increases.
- Demand resiliency and product mix change: While digital receipts and e‑commerce continue to alter certain use cases for thermal paper, persistent demand for point‑of‑sale labels, tags and tickets—especially in retail and logistics—sustains overall growth. Buyers are increasingly segmenting purchases by grade, certification and lifecycle attributes rather than buying solely on price.
Competitive landscape — the practical implications
The industry is anchored by a handful of global players with differentiated capabilities in base paper and coating technologies, production footprint and sustainability certification. Important strategic trends that emerge from competitive behaviour include:
Thermal Paper Market
- Price leadership as signaling: Several major suppliers implemented price increases in early 2026. These moves serve not only to recover cost inflation but to test customer elasticity and lock in new contract levels—creating a window for suppliers to secure longer‑term commitments.
- Product differentiation through reformulation and certification: Market leaders are investing in phenol‑free grades, high‑archivability papers, UV‑printable securities and sustainability credentials (chain‑of‑custody certifications, recycled content). These attributes are increasingly table stakes for premium commercial contracts and public procurement.
- Integration and specialisation paths: Some players are leveraging backward integration or exclusive developer supply to stabilize margins, while others focus on specialty coating and niche applications that command higher margins and stickier customer relationships.
- M&A and partnership appetite: Given the mix of concentrated technology and fragmented regional assets, strategic buyers are likely to look for bolt‑on capacity, chemical developer technologies, or specialty coating capabilities to accelerate access to compliant grades and new geographies.
What our report gives you — practical, transaction‑ready intelligence
PW Consulting’s Thermal Paper Market study is structured to support decisions that must be made in 2026. The report blends quantitative market sizing and scenario forecasting with operational and commercial playbooks targeted at C‑suite and SBU leaders. Highlights include:
Thermal Paper Market
- Top‑down market sizing and an empirically derived forecast (2026–2032) under multiple scenarios, with sensitivity analysis aligned to price shocks and regulatory outcomes.
- End‑to‑end supply‑chain mapping and a raw‑material risk matrix highlighting critical node vulnerabilities and mitigation levers for procurement teams.
- Detailed pricing and cost‑build models that dissect the drivers behind recent supplier price actions and quantify pass‑through impacts at different contract terms.
- Competitive profiles and strategic capability maps for incumbent global producers and selected regional players—covering production footprint, product portfolio, certification status and strategic intent.
- Regulatory heatmaps and compliance roadmaps for major jurisdictions, with operational checklists to accelerate reformulation, testing and certification for market access.
- An M&A playbook: target archetypes, valuation multiples observed in recent deals, integration pitfalls and a 100‑day plan for acquiring chemical developer or specialty coating capabilities.
- Commercial go‑to‑market playbooks for suppliers and buyers—contract design templates, hedging strategies, inventory policies and negotiation scripts tied to market scenarios.
Note: this overview intentionally omits the granular regional and application splits, and detailed segment‑level financials that appear in the full report—these items are preserved as proprietary intelligence to support transaction and strategic planning.
Actionable recommendations for 2026
- Procurement — move from spot‑to‑term strategies: Convert a larger share of your volume to medium‑term indexed contracts with volume flexibility and pass‑through mechanics calibrated to supplier cost drivers. Include raw‑material escape clauses tied to developer availability and energy indices.
- Product strategy — accelerate compliant grade adoption: Prioritise procurement and product development for phenol‑free and certified grades to reduce regulatory exposure and support premium positioning. Build a phased SKU rationalisation to migrate customers smoothly.
- Supply continuity — diversify developer sourcing: Target redundancy in critical chemical developers and invest in supplier qualification programmes. Explore toll‑coating partnerships or co‑investment to secure priority allocation.
- Pricing and commercial models — test value‑based pricing: Where sustainable or certified grades deliver operational benefits (reduced returns, brand value), shift commercial conversations to value rather than purely cost per roll.
- M&A and partnerships — pursue capability fills: For strategic investors: look for technologies (developers, coatings) and regional mills that accelerate access to compliant products or reduce logistics exposure. For corporates: consider partnerships with specialty coaters to de‑risk reformulation timelines.
- Risk management — scenario and stress testing: Embed scenario analysis into board discussions: base case assumes the consensus CAGR; an adverse regulatory or developer‑supply shock should be run as high‑probability stress cases for budgets and capex decisions.
How to use this intelligence in boardroom and transaction work
Executives should treat the report not as a passive market brief but as a decision toolkit. Use the supply‑chain maps to re‑score supplier criticality; apply the cost‑build models to renegotiate supplier contracts or to validate price increase justifications; leverage the regulatory roadmaps to time reformulation investments and to design compliant product launches. For M&A teams, our target archetypes and due diligence checklists shorten evaluation cycles and reduce execution risk.
Closing — the strategic opportunity
The thermal paper market in 2026 is neither a simple commodity story nor a closed‑book speciality niche. It is a market where regulatory drift, raw‑material bottlenecks and coordinated supplier pricing have combined to create short‑term turbulence and long‑term opportunity. Companies that move decisively—locking supply, investing in compliant grades, and aligning commercial models to reflect product quality and certification—will protect margins and capture outsized share as the market expands at the projected mid‑single‑digit CAGR.
For practitioners preparing 2026 budgets, negotiating supplier agreements, or sizing M&A plays, PW Consulting’s full Thermal Paper Market report contains the granular, actionable intelligence you will need. The executive summary here is a strategic preview; the complete study provides the underlying models, segment detail and playbooks required for implementation.
For detailed analysis of this topic, please visit the official page: Thermal Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com