

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
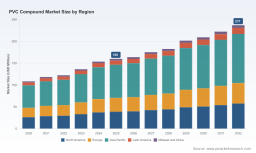
PW Consulting: PVC Compound Market to Hit USD 237M by 2032 at 4.57% CAGR

PVC Compound Market — Strategic Outlook for 2026 Decision‑Makers
Executive preview
As companies recalibrate portfolios for a second half of the decade defined by feedstock volatility, regulatory scrutiny and targeted capacity additions, the PVC compound market is entering a phase where strategic clarity delivers disproportionate value. PW Consulting’s latest market research synthesizes five years of historical performance and a forward-looking forecast to 2032, combining quantitative baselines with executable commercial recommendations. This introduction outlines the analytical framing and the high‑value takeaways you should act on in 2026 — while preserving the detailed subsegment tables and proprietary models for subscribers who require the full intelligence package.
PVC Compound Market
Topline context: growth trajectory and what it means
After steady recovery through the early 2020s, the market’s topline expanded markedly between 2020 and 2025. Using our base year of 2025, the market reached a clear inflection compared with 2020, and our scenario-informed forecast anticipates continued expansion to 2032 at a compound annual growth rate (CAGR) of approximately 4.57% over the forecast window. That pace implies a market that is neither hyper‑cyclical nor stagnant: it favors disciplined capital allocation, iterative product innovation, and supply‑chain flexibility rather than speculative capacity builds without demand linkage.
PVC Compound Market
Key dynamics shaping decisions in 2026
-
Feedstock and pricing volatility — Resin and upstream feedstock cycles remain the dominant near‑term risk. Price rebounds in North America and a rebalancing of global PVC availability following Asia’s capacity movements have created a more pronounced short‑term correlation between resin margins and downstream compound pricing than seen in prior cycles. Buyers and compounders that adopt more active feedstock hedging and dynamic pricing clauses will preserve margins in 2026.
PVC Compound Market -
Regulatory pressure and chemical risk evaluation — Vinyl chloride continues to attract regulatory attention in major markets. Recent high‑priority designations and draft scopes of regulatory risk evaluations increase compliance overhead and potential product substitution risk for certain use cases. Firms will need regulatory playbooks and contingency formulations for sensitive applications.
-
Capacity moves and network readjustment — The industry is experiencing selective capacity additions and re‑shoring/relocation of compounding assets, alongside strategic plant modernizations (including low‑carbon manufacturing). These shifts create pockets of tightening and oversupply across regions and product classes, which will influence contract negotiation dynamics and logistics optimization.
-
Concentration and competitive positioning — The market demonstrates a moderate level of concentration among the largest compounders. That structure supports scale advantages in procurement and distribution, but also creates opportunities for specialized or regional players to capture premium niches through technical differentiation and service intensity.
-
Sustainability and circularity as differentiators — Demand for recycled content, lower‑emission production footprints, and halogen‑free or low‑emission grades is shifting customer selection criteria from pure price to total cost of ownership and brand risk mitigation. Early movers with validated circular offerings and traceable supply chains gain preferential access to high‑value customers.
What to prioritise in 2026 — operational and strategic levers
-
Short‑term: secure feedstock flexibility. Implement layered purchase strategies, index‑linked contracts and volume options to protect margins while keeping commercial agility.
-
Medium‑term: rationalise capacity with customer demand mapping. Align incremental plant investment with verified demand pathways — focusing on specialty grades, recycled compound production, and faster time‑to‑market for custom formulations.
-
Regulatory mitigation: embed chemical risk into product roadmaps. Build substitution matrices for sensitive applications, and accelerate testing and certification pipelines for lower‑risk alternatives.
-
Commercial: shift to outcome‑oriented offers. Move beyond commodity pricing to bundled services — technical support, formulation co‑development and sustainability documentation — to protect margins and deepen customer relationships.
-
Portfolio: prioritize specialty and circular products. Given market growth moderated by a mid‑single digits CAGR, value creation will come from higher‑margin niches rather than scale alone.
Competitive landscape — practical implications beyond the headlines
Below we summarise strategic postures of representative players and the implications for buyers, suppliers and potential investors. This is not an exhaustive ranking — our full report contains benchmarking matrices, capability scores and channel maps.
-
Westlake Global Compounds — With a broad global footprint and a product range that spans rigid and flexible systems, Westlake leverages scale in procurement and distribution. Their strengths include integrated supply relationships and a broad portfolio targeted at infrastructure segments. Counterparty strategies should focus on long‑term contracts with flexibility clauses to balance scale benefits and market exposures.
-
Aurora Material Solutions — Known for technical compounding and custom grades, Aurora’s competitive edge is service intensity and formulation agility. For OEMs and specifiers, partnering with such providers is efficient when time‑to‑market and application performance dominate procurement criteria.
-
Benvic Group — A strong European compounder with specialized premix and stabilizer capabilities. Benvic’s regional depth makes it a natural partner for customers seeking localized supply and regulatory alignment in European jurisdictions.
-
Orbia / Polymer Solutions (Vestolit, Alphagary) — Vertical integration across resin, additives and compound formulations gives Orbia strategic optionality. Their brands are often positioned to capture value across multiple stages of the value chain; counter‑strategies include dual‑sourcing and focusing on differentiated technical requirements not served by large integrated suppliers.
-
Manner Polymers — Recent manufacturing modernization and investments in low‑carbon operations position Manner as an emblem of how sustainability can be converted into capacity and customer differentiation. Buyers emphasizing green sourcing should evaluate Manner’s certifications and lifecycle data.
-
DDEV Plastiks Industries — Rapid capacity ramp‑up in emerging markets underscores the competitive pressure from cost‑efficient compounders with export ambitions. For incumbents in mature markets, the response should be a mix of specialization and service enhancement rather than competing solely on price.
-
Thevinyl AB — A niche, customization‑oriented compounder with strength in bespoke formulations. Their model illustrates a profitable path for small‑to‑mid players focused on technical depth and close customer integration.
-
TPV Compound Spa — Deep technical experience in medical and high‑performance technical compounds. This underscores a durable premium segment where regulatory and quality capabilities create barriers to entry.
How PW Consulting’s research converts insight into action
The full PVC Compound Market study we released combines rigorous topline measurement with tailored decision tools aimed at commercial, operational and corporate strategy teams. Key deliverables include:
-
Market sizing and trajectory models anchored to our 2025 base year and extending to 2032, including sensitivity runs on feedstock and demand scenarios.
-
Segment and application frameworks that map addressable markets, substitution risk and price elasticity — with playbooks for growth, defence and exit options per product cluster.
-
Supplier and competitor benchmarking with capability heatmaps, service profiles and strategic intent indicators to guide sourcing and partnership decisions.
-
Regulatory and ESG risk matrices, integrating projected policy trajectories with product exposure to help compliance, R&D and procurement teams prioritise mitigations.
-
Commercial tools — pricing algorithms, contract clause templates and customer segmentation models — designed to be operationalised by sales and customer success functions.
-
M&A and portfolio optimisation guidance, including acquisition target archetypes and integration risk checklists for buyers and private equity investors focused on the mid‑market.
Final takeaways for 2026 planning cycles
The PVC compound market presents a classic “manage for resilience, invest for differentiation” scenario in 2026. With a steady underlying growth trajectory and clear headwinds from feedstock and regulatory dynamics, the highest value moves are those that (1) lock in feedstock optionality and predictable margins, (2) accelerate transition to higher‑value, lower‑risk product classes, and (3) align capital deployment with verified, sustainable demand pathways rather than short‑term volume chasing.
PW Consulting’s full report equips executives with the granular segmentation, supplier scores, and scenario tools to operationalise those moves. For teams preparing budgets, negotiating agreements, or assessing acquisition targets in 2026, our analysis converts market direction into measurable actions.
Next step
For the complete dataset, proprietary segmentation tables, and the hands‑on playbooks referenced here, visit PW Consulting’s PVC Compound Market page to access the full report and supporting models. Stakeholders who wish to discuss tailored scenario runs or a bespoke supplier assessment can contact our industry practice for a briefing and implementation roadmap.
For detailed analysis of this topic, please visit the official page: PVC Compound Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com