

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Medical Refrigerator Market to Hit USD 3,002.04 Million by 2032 (4.55% CAGR)

Medical Refrigerator Market—Strategic Briefing for 2026 Decisions
Executive snapshot
As healthcare systems prioritize cold-chain integrity and regulatory scrutiny tightens around vaccine and biologic storage, the medical refrigerator market is transitioning from a steady replacement cycle into a period of purposeful investment. PW Consulting’s latest study (base year 2025) synthesizes historical performance, regulatory inflections, and forward-looking scenarios to equip executives with the actionable intelligence needed to make confident 2026 capital, product and M&A decisions.
Medical Refrigerator Market
Why this research matters for 2026
- Timing of investments: 2026 is a hinge year for many buyers—hospital systems updating pharmacy infrastructure, manufacturers optimizing product portfolios, and distributors refreshing logistics offerings. Our analysis isolates the pockets of demand that will be purchase-ready in 2026 versus those likely to defer.
- Regulatory convergence: New clearances and certification guidance across major markets are reshaping competitive parity. Understanding which product features translate into procurement preferences (and reimbursement uplift) is essential to avoid product obsolescence.
- Strategic capital allocation: With moderate but durable growth projected, firms must choose where to prioritize R&D, channel expansion, or bolt-on M&A to outpace peers without overextending balance sheets.
Market trajectory — what the macro numbers tell us
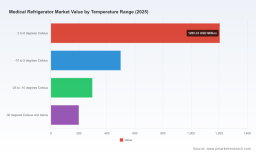
The medical refrigerator market demonstrated resilient growth through the early 2020s, expanding from an estimated USD 1,800.0 million in 2020 to USD 2,198.6 million in 2025 (base year). Our forecast model projects the market will continue on a compounded expansion path, reaching approximately USD 3,002.0 million by 2032, reflecting a CAGR of 4.55% for the forecast period. These macro dynamics are driven by a combination of sustained demand for vaccine and biologic storage, upgrades to laboratory infrastructure, and incremental adoption of specialized temperature-range products.
Medical Refrigerator Market
What this means for 2026 decision-makers
- Revenue predictability vs. product risk: The market’s steady CAGR suggests reliable baseline demand, but pockets of accelerated growth are tied to regulatory approvals, procurement cycles and healthcare capital expenditure plans. Firms should prioritize flexible production and modular feature-sets to capture upside while limiting margin erosion.
- Channel optimization: Distributors and OEMs that redesign commercial models—balancing direct institutional sales with certified channel partnerships—will capture larger share of tender and GPO-driven volumes in 2026.
- Cost-to-serve focus: Cooling technology improvements and energy-efficiency standards are creating differentiation opportunities. Investment in lower lifecycle-cost platforms yields a two-fold benefit: procurement preference and lower total cost of ownership for buyers, supporting premium pricing.
- M&A and JV opportunities: Given moderate market concentration and continued fragmentation across product niches, targeted acquisitions (technology, regional distribution, or service capability) can deliver immediate scale and fill go-to-market gaps faster than organic build.
Competitive landscape — interpretive summary
The market is characterized by a mix of specialized medical-grade manufacturers, global life-science incumbents, and well-capitalized regional players. The top three firms account for a meaningful portion of revenue, while the top five increase that share further—indicating moderate concentration but continued room for challengers that can demonstrate product differentiation or superior service.
Medical Refrigerator Market
- Helmer Scientific (USA): A specialist in pharmacy, blood bank and laboratory refrigeration with strong certifications for vaccine storage. Helmer’s emphasis on compliance and healthcare-focused channel relationships positions it well in institutional procurement, but scale expansion will depend on international distribution and aftermarket service network buildout.
- B Medical Systems (Luxembourg): A global cold-chain supplier with breadth across vaccine, blood bank and plasma storage. Its credentialing across major regulatory regimes provides access to public health tenders; strategic focus should be on consolidating service contracts and optimizing cost structure for emerging markets.
- PHCbi (Japan): A technology-led provider whose recent regulatory successes enhance its product credibility. In June 2025 PHCbi received U.S. FDA 510(k) clearance for new pharmaceutical refrigerator models—an event that will materially influence procurement cycles in markets that prioritize cleared devices.
- Thermo Fisher Scientific (USA): Leveraging a broad laboratory portfolio, Thermo Fisher supplies refrigerators as part of integrated lab solutions. Cross-selling to existing laboratory customers and leveraging global logistics is its key advantage; maintaining product differentiation within a broader catalog is the tactical challenge.
- Accucold (Felix Storch, USA) and American Biotech Supply (ABS, USA): Both operate with strong brand recognition in performance and certified vaccine storage niches. Their ability to service retrofit and replacement demand—combined with NSF/ANSI certifications—makes them credible choices for customers prioritizing proven compliance.
Signals to watch in 2026
- Regulatory approvals and guidance: New clearances or updated vaccine storage standards will re-rank competitive advantages quickly. Monitor regulatory calendars in core markets.
- Procurement cycles at system level: Tenders from large hospital networks and public health programs have a disproportionately large impact on order books—timing and pre-qualification are decisive.
- Energy and sustainability benchmarks: New efficiency standards will reshape total cost models and influence procurement specifications; early movers with validated lifecycle analyses will command premium positioning.
- Service and digital enablement: Remote monitoring, predictive maintenance and validated temperature logging are becoming baseline expectations rather than optional features.
What the report delivers — practical contents for teams executing in 2026
PW Consulting’s full report goes beyond high-level narrative to provide operationally-relevant tools that teams can deploy immediately:
- Market sizing and methodical vintage modeling with an auditable workbook (base year 2025; forecast 2026–2032).
- Scenario-based revenue models reflecting regulatory shifts, procurement wave timing and technology adoption curves (including a conservative, base, and accelerated case).
- Buyer personas and procurement playbooks tailored for hospitals, public health agencies, laboratories and private clinics—mapping evaluation criteria, certification requirements, and decision timelines.
- A regulatory and standards matrix highlighting certification pathways (FDA, EU MDR, WHO PQS, NSF/ANSI and equivalents), plus guidance on dossier prioritization to accelerate approvals in key markets.
- Go-to-market roadmaps: direct sales vs. distributor hybrid models, tender capture checklists, pricing ladders and service contract templates to protect margin on replacement cycles.
- Competitive benchmarking: capabilities heatmaps for leading suppliers, feature gap analysis, and an M&A target shortlist with rationale, valuation heuristics and integration risks.
- Operational playbooks for manufacturability, supply-chain resilience and aftermarket service scaling—including vendor scorecards and break-even analyses for regional service hubs.
How to use the research to make confident 2026 bets
- CEOs and corporate strategy: Use scenario outputs to set capital allocation bands for R&D, M&A and channel expansion—aligning investment pace to the forecasted CAGR and your desired market-share trajectory.
- Product and R&D leads: Prioritize features that materially influence procurement decisions (validated temperature control, energy efficiency, remote monitoring) and defer investments that do not improve selection likelihood within the next two procurement cycles.
- Commercial teams: Reorient sales incentives around tender capture and service contract renewal. The market favors suppliers that can demonstrate lower total cost of ownership and proven compliance.
- Corporate development: Target acquisitions that close gaps in service footprint or digital capabilities rather than acquiring for pure revenue scale—integration value will be realized fastest where service and certification synergies exist.
Market concentration and competitive opportunity
The market shows moderate concentration: the top three players account for a material share of revenue, and the top five increase that share further—leaving meaningful opportunity for focused challengers. This structure supports targeted consolidation strategies: well-executed M&A or strategic partnerships can shift competitive dynamics quickly if combined with disciplined post-merger integration and service expansion.
Conclusion — the strategic lens for 2026
For executives planning 2026 actions, the imperative is clear: convert macro predictability into micro advantage by aligning product roadmaps, regulatory strategies and go-to-market execution. The market’s steady compound growth affords a window to scale thoughtfully—rewarding those who can marry compliance credibility with lower lifecycle cost and superior service delivery.
PW Consulting’s full Medical Refrigerator Market report contains the granular segmentation, financial models, and supplier scorecards required to operationalize these insights. The executive summary above is designed to show the strategic contours and immediate decision levers; the detailed datasets and playbooks needed to finalize 2026 budgets and M&A targets are available in the complete study.
For detailed analysis of this topic, please visit the official page: Medical Refrigerator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com