

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Vitamin D Market Poised for 7.8% CAGR Through 2032

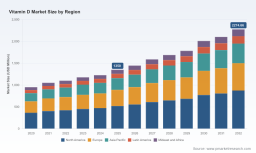
Vitamin D Market — 2026 Strategic Preview
As executive teams set budgets and strategic priorities for 2026, understanding where the Vitamin D value chain is headed is no longer optional — it is a competitive necessity. PW Consulting’s latest Vitamin D Market study (base year 2025; historical window 2020–2025; forecast horizon 2026–2032) synthesizes five years of market behavior with forward-looking scenario analysis. The market reached approximately USD 1,350 million in 2025 and, under our central scenario, expands at a compound annual growth rate of 7.8% across the 2026–2032 forecast window, moving toward a materially larger global footprint by 2032. This preview highlights the strategic takeaways our clients will use to align product portfolios, secure supply, and prioritize investment in 2026 — while reserving the granular regional and application splits for the full report.
Vitamin D Market
Why this research matters for 2026 decision-makers
-
Timing: 2026 is the inflection year for a wave of capacity and regulatory developments that will reshape supplier economics and access to specific Vitamin D formats.
Vitamin D Market -
Risk mitigation: Raw material sourcing (lanolin, lichen-derived D3 and ergosterol-derived D2) is concentrated around a small set of suppliers and processes; procurement teams must re-evaluate counterparty exposure now to avoid costly disruptions.
Vitamin D Market -
Portfolio fit: Formulation choices (oily vs. dry, beadlets, gummies, fortified food premixes) and the rise of plant-based and hybrid offerings demand a reappraisal of product roadmaps to capture higher-margin growth segments.
-
M&A and capacity allocation: Several leading producers have announced capacity and product-line investments; the coming 18–24 months are likely to favor either rapid consolidation or premium niche plays depending on how companies react.
Market trajectory snapshot (what the numbers show)
From 2020 to 2025 the Vitamin D market showed steady recovery and expansion following pandemic disruptions, reaching roughly USD 1.35 billion in 2025. Looking ahead, our central forecast — which incorporates demand-side drivers such as rising supplementation adoption, expanding food fortification programs, and stable feed demand — assumes a 7.8% CAGR through 2032. Under that trajectory, the market more than doubles from the low‑billion base into a multi‑billion opportunity by the end of the forecast window. This represents a compelling growth runway for companies that can pair capacity with differentiated formulations and robust regulatory strategies.
Supply- and demand-side dynamics that will define 2026
-
Raw material architecture: D3 production pathways remain dominated by irradiation of 7‑dehydrocholesterol derived from lanolin, while animal‑free D3 from lichen is an emerging alternative for major formulators targeting clean‑label and vegan segments. D2 continues to be sourced from UV‑irradiated ergosterol in yeast. Each route presents tradeoffs across cost, scalability, and labeling claims that affect product placement and price tolerance.
-
Regulatory inflection points: Late‑2025 and early‑2026 regulatory rulings (including approvals of novel metabolites for animal nutrition) materially change allowable claims and formulations in feed and certain fortified products. Companies that maintain regulatory monitoring and fast adaptation of technical dossiers will enjoy first‑mover advantages.
-
Clinical and public‑health inputs: Large population studies completed through 2025–2026 continue to shape recommendations and consumer perceptions of Vitamin D supplementation. These outcomes influence payer conversations, private‑label uptake, and mass‑market demand elasticity.
-
Manufacturing and onshoring trends: Several market participants have accelerated local production to shorten lead times and appeal to traceability-minded buyers. One leading North American brand has moved the overwhelming majority of its finished‑goods production to domestic facilities — a model that will pressure lesser‑integrated suppliers to offer faster turnaround or strategic partnerships.
-
Product innovation: Expect growth to be driven by format innovation (beadlets, gummies, combined micronutrient premixes) and plant‑based D3 alternatives. Ingredient suppliers that offer performance‑tested beadlets and stable oily-to-dry systems will capture formulators seeking shelf-stability and manufacturing ease.
Competitive landscape — positioning and strategic moves
The Vitamin D value chain blends global commodity producers with branded finishers and regionally focused specialist manufacturers. In our coverage universe, a small set of companies stand out for scale, breadth, or innovative positioning:
-
Global ingredient champions: The world’s largest D3 producers continue to supply both oily and dry formats for supplements, fortified foods, and feed. Their strengths are scale, broad product portfolios, and integrated technical support to large formulators. Expect them to focus on premium, regulated‑food applications and on expanding metabolite and specialty derivatives where regulatory pathways allow.
-
Industrial chemistry and formulation leaders: Large chemical conglomerates active in beadlets and coated formulations are leveraging Verbund sites and application labs to deliver end‑to‑end premixes and turnkey solutions for human and animal nutrition. Product launches in animal nutrition portfolios underline a strategy to deepen downstream integration and capture higher value per ton.
-
Branded supplement manufacturers moving upstream: Consumer brands with high single‑market share have materially expanded manufacturing footprints to secure finished‑goods control, instrument R&D for novel formats, and guarantee supply continuity. This represents a structural shift as brand owners internalize more of the value chain.
-
Specialist fermenters and plant‑based players: Regional producers with pharma‑grade certifications have positioned plant‑based D3 and specialty grades for the nutraceutical market; their agility in certification and niche claims makes them attractive partners for premium and vegan product lines.
Each archetype presents different partnership profiles. Ingredient champions will seek long‑term offtake arrangements and collaborative product development; branded manufacturers will focus on captive capacity and co‑packing; specialists will trade on certification and formulation agility.
Recent strategic developments to watch in 2026
-
Capacity and facility investments completed in 2025 have begun to pipeline additional finished‑goods supply into North America and Europe, reducing lead‑time friction for large retail and contract manufacturers.
-
New combined vitamin formulations aimed at animal nutrition and aquaculture have shifted supplier demand patterns; these product introductions respond to regulatory openings for novel metabolites and higher inclusion rates in feed premixes.
-
Large clinical studies and trial updates through 2025–2026 are influencing public health guidance, which in turn affects OTC supplementation demand curves and formulators’ claims strategies.
Actionable implications and 2026 playbook
-
Secure multi‑tier supply: Negotiate flexible contracts with both global producers and regional specialists. Layer long‑dated capacity agreements for critical grades while maintaining spot access to alternative sources (e.g., lichen‑derived D3) to defend against single‑source failures.
-
Prioritize format economics: Decide, within Q1 2026, whether to standardize on beadlets, oily solutions, or dry premixes for new SKUs — because formulation choice materially affects COGS, shelf‑life, and manufacturing footprint.
-
Embed regulatory agility: Establish a regulatory monitoring cell to track metabolite approvals, claim permissibility across major markets, and food/animal nutrition labeling changes. Approvals can create short windows of competitive advantage for first movers.
-
Invest in sustainability narratives: Validate plant‑based and low‑carbon sourcing claims through third‑party certification and lifecycle assessment. These signals can unlock premium distribution channels in developed markets.
-
Refine M&A criteria: Target assets that address one of three strategic gaps — incremental compliant capacity, specialized process know‑how (e.g., plant‑based D3), or downstream branded channels — rather than chasing scale alone.
-
Stress‑test pricing: Run scenario models that combine raw‑material shocks, formulation shifts, and toggles in fortification policy to set dynamic price floors and rebate terms for 2026 contracts.
What the full PW Consulting report provides (practical deliverables)
Our full study is built for executable decision-making and includes:
-
Transparent methodology, data tables, and forecast models with sensitivity analyses across low, central and high scenarios for 2026–2032;
-
Company profiles and strategic playbooks for major producers and innovators, including capacity maps, recent investments, and M&A pipelines;
-
End‑use demand deep dives (supplements, fortified foods, animal feed) with product-level implications and commercialization timelines;
-
Supply‑chain risk heatmaps, raw‑material cost drivers, and supplier scorecards designed for procurement renegotiations;
-
Regulatory tracker and claim‑risk matrix incorporating recent approvals and pending dossiers that will affect 2026 market access;
-
Go‑to‑market playbooks and due‑diligence checklists for executives evaluating contract‑manufacturing, captive build‑outs, or bolt‑on acquisitions;
-
Interactive dashboards and client workshops to translate the market views into 2026 P&L scenarios and capital allocation plans.
Note: This preview is intentionally high‑level. We withhold granular regional and application splits, and detailed competitive market‑share tables, to preserve the strategic value of the full report and our proprietary models. Clients who require the complete datasets, segment‑level forecasts, and supplier share matrices can access them through PW Consulting’s research portal or via a bespoke advisor engagement.
How to use these insights in Q1 2026
-
Schedule a 90‑minute strategy workshop to stress‑test your supply agreements and align a capital plan with our scenario outputs.
-
Direct procurement to open secondary sourcing conversations for critical grades and formats identified in this preview.
-
Prioritize one pilot SKU for a plant‑based D3 variant if your brand is pursuing vegan positioning — use the pilot to validate cost and claims ahead of broader rollout.
-
Task regulatory and R&D to map product dossiers against the new metabolite permissions and clinical evidence trajectories highlighted here.
PW Consulting’s full Vitamin D Market report is designed to move your 2026 planning from high‑level intent to implementable action. For access to the complete report, data tables, and a tailored briefing for your executive team, please visit our research portal or contact your PW Consulting account lead.
For detailed analysis of this topic, please visit the official page: Vitamin D Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com