

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Thermal Paper Market to Grow at 5.0% CAGR (2026-2032)

Thermal Paper Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As PW Consulting publishes its 2026 Thermal Paper Market study, the sector sits at a strategic inflection point. After a measured recovery through 2020–2025 the global thermal paper market reached roughly USD 4.51 billion in the base year (2025) and is projected to expand at a mid‑single‑digit compound annual growth rate (CAGR) of about 5.0% across the 2026–2032 forecast window—driving the market toward the low‑to‑mid USD 6 billion range by the end of the period. These headline figures mask important structural shifts in supply, regulation, raw materials and buyer behaviour that will determine winners and losers over the next three to five years.
Thermal Paper Market
Why this study matters for 2026 decisions
- Immediate commercial impact: Input cost pressures and coordinated pricing actions by major coaters in early 2026 have created a new pricing baseline. Corporates must decide quickly whether to absorb, pass through, or strategically renegotiate long‑term contracts.
- Regulatory and reformulation risk: Public policy and chemical regulators are accelerating the shift away from legacy developers in thermal coatings; this drives near‑term compliance costs and medium‑term product roadmaps.
- Supply chain fragility: Structural bottlenecks in key chemical developers and uneven energy/pulp cost dynamics mean procurement and continuity planning are now front‑line strategic issues.
- Portfolio and M&A sizing: The market remains moderately consolidated at the top end, but fragmentation across regional mills and specialty coaters creates attractive bolt‑on targets for industrial consolidators and financial sponsors.
Current market dynamics: what is changing
- Price resets and margin pass‑through: Several leading producers announced synchronized price increases in early 2026—an explicit response to elevated energy, chemical and logistics costs. This reset changes negotiation dynamics for distributors, large retail chains and label converters and will influence purchasing cadence through 2026.
- Regulatory acceleration: The enforcement of state‑level bans on bisphenols (first implemented at the state level in the U.S. on January 1, 2026) and classifications by major chemical authorities are pushing customers and suppliers toward phenol‑free developer systems, certified alternatives, and new testing requirements. Compliance timelines vary by jurisdiction, but the direction is clear: reformulation is a must for market access in key markets.
- Raw material concentration risk: Key leuco‑dye developers and other coating intermediates are in tight global supply, creating episodic shortages and spot volatility. At the same time, mills in regions exposed to energy and pulp cost inflation experienced double‑digit input cost increases in late 2025—forcing many suppliers to choose between margin erosion and customer price increases.
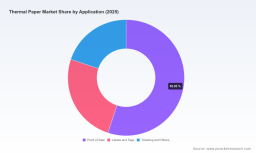
- Demand resiliency and product mix change: While digital receipts and e‑commerce continue to alter certain use cases for thermal paper, persistent demand for point‑of‑sale labels, tags and tickets—especially in retail and logistics—sustains overall growth. Buyers are increasingly segmenting purchases by grade, certification and lifecycle attributes rather than buying solely on price.
Competitive landscape — the practical implications
The industry is anchored by a handful of global players with differentiated capabilities in base paper and coating technologies, production footprint and sustainability certification. Important strategic trends that emerge from competitive behaviour include:
Thermal Paper Market
- Price leadership as signaling: Several major suppliers implemented price increases in early 2026. These moves serve not only to recover cost inflation but to test customer elasticity and lock in new contract levels—creating a window for suppliers to secure longer‑term commitments.
- Product differentiation through reformulation and certification: Market leaders are investing in phenol‑free grades, high‑archivability papers, UV‑printable securities and sustainability credentials (chain‑of‑custody certifications, recycled content). These attributes are increasingly table stakes for premium commercial contracts and public procurement.
- Integration and specialisation paths: Some players are leveraging backward integration or exclusive developer supply to stabilize margins, while others focus on specialty coating and niche applications that command higher margins and stickier customer relationships.
- M&A and partnership appetite: Given the mix of concentrated technology and fragmented regional assets, strategic buyers are likely to look for bolt‑on capacity, chemical developer technologies, or specialty coating capabilities to accelerate access to compliant grades and new geographies.
What our report gives you — practical, transaction‑ready intelligence
PW Consulting’s Thermal Paper Market study is structured to support decisions that must be made in 2026. The report blends quantitative market sizing and scenario forecasting with operational and commercial playbooks targeted at C‑suite and SBU leaders. Highlights include:
Thermal Paper Market
- Top‑down market sizing and an empirically derived forecast (2026–2032) under multiple scenarios, with sensitivity analysis aligned to price shocks and regulatory outcomes.
- End‑to‑end supply‑chain mapping and a raw‑material risk matrix highlighting critical node vulnerabilities and mitigation levers for procurement teams.
- Detailed pricing and cost‑build models that dissect the drivers behind recent supplier price actions and quantify pass‑through impacts at different contract terms.
- Competitive profiles and strategic capability maps for incumbent global producers and selected regional players—covering production footprint, product portfolio, certification status and strategic intent.
- Regulatory heatmaps and compliance roadmaps for major jurisdictions, with operational checklists to accelerate reformulation, testing and certification for market access.
- An M&A playbook: target archetypes, valuation multiples observed in recent deals, integration pitfalls and a 100‑day plan for acquiring chemical developer or specialty coating capabilities.
- Commercial go‑to‑market playbooks for suppliers and buyers—contract design templates, hedging strategies, inventory policies and negotiation scripts tied to market scenarios.
Note: this overview intentionally omits the granular regional and application splits, and detailed segment‑level financials that appear in the full report—these items are preserved as proprietary intelligence to support transaction and strategic planning.
Actionable recommendations for 2026
- Procurement — move from spot‑to‑term strategies: Convert a larger share of your volume to medium‑term indexed contracts with volume flexibility and pass‑through mechanics calibrated to supplier cost drivers. Include raw‑material escape clauses tied to developer availability and energy indices.
- Product strategy — accelerate compliant grade adoption: Prioritise procurement and product development for phenol‑free and certified grades to reduce regulatory exposure and support premium positioning. Build a phased SKU rationalisation to migrate customers smoothly.
- Supply continuity — diversify developer sourcing: Target redundancy in critical chemical developers and invest in supplier qualification programmes. Explore toll‑coating partnerships or co‑investment to secure priority allocation.
- Pricing and commercial models — test value‑based pricing: Where sustainable or certified grades deliver operational benefits (reduced returns, brand value), shift commercial conversations to value rather than purely cost per roll.
- M&A and partnerships — pursue capability fills: For strategic investors: look for technologies (developers, coatings) and regional mills that accelerate access to compliant products or reduce logistics exposure. For corporates: consider partnerships with specialty coaters to de‑risk reformulation timelines.
- Risk management — scenario and stress testing: Embed scenario analysis into board discussions: base case assumes the consensus CAGR; an adverse regulatory or developer‑supply shock should be run as high‑probability stress cases for budgets and capex decisions.
How to use this intelligence in boardroom and transaction work
Executives should treat the report not as a passive market brief but as a decision toolkit. Use the supply‑chain maps to re‑score supplier criticality; apply the cost‑build models to renegotiate supplier contracts or to validate price increase justifications; leverage the regulatory roadmaps to time reformulation investments and to design compliant product launches. For M&A teams, our target archetypes and due diligence checklists shorten evaluation cycles and reduce execution risk.
Closing — the strategic opportunity
The thermal paper market in 2026 is neither a simple commodity story nor a closed‑book speciality niche. It is a market where regulatory drift, raw‑material bottlenecks and coordinated supplier pricing have combined to create short‑term turbulence and long‑term opportunity. Companies that move decisively—locking supply, investing in compliant grades, and aligning commercial models to reflect product quality and certification—will protect margins and capture outsized share as the market expands at the projected mid‑single‑digit CAGR.
For practitioners preparing 2026 budgets, negotiating supplier agreements, or sizing M&A plays, PW Consulting’s full Thermal Paper Market report contains the granular, actionable intelligence you will need. The executive summary here is a strategic preview; the complete study provides the underlying models, segment detail and playbooks required for implementation.
For detailed analysis of this topic, please visit the official page: Thermal Paper Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com