

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Bone Conduction Headphones Market to Reach USD 11,120M by 2032
By pmarketresearch, 2026-07-08
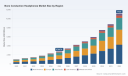
Bone Conduction Headphones Market — Strategic Outlook for 2026 Decision-Making
As bone conduction audio moves from niche novelty to a mainstream product category, corporate leaders face a rapid convergence of technological advances, regulatory normalization, and shifting channel economics. PW Consulting’s latest Bone Conduction Headphones Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes these forces into an action-oriented intelligence package designed to inform 2026 strategy cycles. The market we modelled reached a multi‑hundred million USD scale in 2025 and — under our central case — is positioned to expand at a compound annual growth rate (CAGR) of 6.98% through 2032, reaching a substantially larger market size by the end of the forecast window. This briefing highlights the report’s strategic value while deliberately withholding granular segmentation so decision-makers must access the full study for playbooks and line-item forecasts.
Bone Conduction Headphones Market
What this research delivers — practical, operational, and strategic
-
Proven market sizing and scenario engine: transparent methodology that reconciles supplier volumes, sell‑through data, and channel checks to produce base, upside, and downside cases for 2026–2032.
Bone Conduction Headphones Market -
Decision-ready go‑to‑market playbooks: specific product, channel, pricing and partnership options for OEMs, brands, and channel partners. Includes launch sequences, promotional mixes, and expected payback timelines under differing unit cost assumptions.
Bone Conduction Headphones Market -
Supply chain and cost anatomy: a component‑level map that identifies cost drivers, strategic single points of failure, and levers to reduce the 25–40% manufacturing cost premium associated with bone conduction designs versus conventional headphones.
-
Regulatory and compliance roadmap: certification requirements, timelines and test houses for key markets (including EU CE/TÜV pathways for active noise reduction and IP68/IP69 waterproofing expectations for sports lines).
-
Competitive intelligence and vendor scorecards: qualitative and quantitative assessments for leading OEMs, contract manufacturers and branded incumbents; benchmark criteria include product durability, IP portfolio, channel strength, and margin structures.
-
Commercial and M&A playbooks: prioritized target lists, valuation heuristics for bolt‑on acquisitions, and integration checklists tailored to the market’s current concentration dynamics.
Why the study matters for 2026 corporate planning
Three practical reasons executives should incorporate this report into their 2026 planning cycle:
-
It converts top‑line growth into actionable bets. The underlying market trajectory — underpinned by steady, mid‑single‑digit CAGR — converts exploratory investment into investment prioritization: which platforms to accelerate, which features to deprioritize, and where to reserve R&D capital.
-
It reveals structural cost asymmetries. Specialized transducers, enclosure tolerances and premium materials (notably titanium bands used in active models) create a durable cost delta versus true wireless earbud designs. The report shows where that delta is absorbed, where it compresses margins, and how design or sourcing choices change unit economics.
-
It aligns compliance with commercialization. Waterproofing benchmarks (IP68/IP69) and EU certification norms (CE marking and third‑party validation such as TÜV for active noise capabilities) move from checklist items to strategic gating factors for cross‑border launches.
Competitive landscape — snapshot and strategic implications
The market is concentrated: our CR3 and CR5 metrics indicate a top‑heavy structure, where a few brands and OEMs account for a meaningful share of revenue and influence on standards, pricing and channel access. That concentration creates both defensive moats and opportunistic entry points for challengers.
-
Shokz — positioned as the flagship premium brand, combining titanium band designs with product extensions (e.g., integrated MP3 storage and communications‑oriented models). Recent product recognition at CES 2026 validates a brand premium strategy and sets engineering bar for open‑ear ergonomics.
-
H2O Audio — niche leader in waterproof, multi‑sport devices. Certifications such as IP68 and integration of on‑device storage illustrate a feature stack designed for dedicated sports adopters.
-
Nank and analogous players — focus on swim‑optimized and outdoor sport models, competing on IP rating, fit and durability.
-
Suunto — the sports‑training playbook: long battery life and integration with performance ecosystems (trainers, app platforms) make it a model for co‑branded product strategies with wearables incumbents.
-
Raycon — orienting to everyday consumers with an open‑ear form factor and waterproof rating, competing via price and mainstream distribution.
-
Contract manufacturers / OEMs (several China‑based firms) — serve as critical scale partners for private‑label and cost‑sensitive brands. Their role is central to time‑to‑market and margin optimisation, particularly for new entrants seeking rapid SKU proliferation.
Strategically, incumbents with strong brand equity and proprietary hardware (e.g., resilient titanium frames, tuned transducers) can protect price, while nimble OEMs and distribution‑focused challengers pressure average selling prices through rapid SKU iteration and lower channel costs.
Market dynamics, constraints and tipping points
-
Component and labor cost pressure: the specialized nature of bone conduction transducers and assembly raises manufacturing costs relative to conventional headphones. Companies must weigh near‑term margin pressure against long‑term price elasticity as adoption broadens.
-
Raw material and design trade‑offs: premium models that leverage titanium bands (typical active models use bands in a narrow weight band) achieve superior durability and perceived value but increase material cost and constrain design flexibility.
-
Regulatory and standards evolution: waterproof and active noise reduction features are increasingly subject to standardized verification. CE marking and recognized third‑party testing bodies are becoming de facto entry tickets for major e‑commerce and retail channels.
-
Distribution and channel dynamics: sports specialty retail, direct‑to‑consumer, and hearing‑aid channels each demand differentiated product specifications, return policies and marketing approaches—fragmentation that benefits players with adaptable supply chains.
-
Substitution and cannibalization risk: as true wireless buds continue to improve safety and situational awareness features, bone conduction players must continually justify the use case premium in safety‑conscious or hearing‑impaired segments.
Recommended 2026 moves — prioritized and pragmatic
-
Adopt a two‑track product portfolio: a cost‑engineered family for broad consumer channels and a premium, titanium‑based line that defends margins and supports partner co‑branding with sports and professional segments.
-
Invest in certification early: secure CE/TÜV and IP6x test results before large scale launch windows to avoid market delays and retailer refusals.
-
Rationalize supplier base with conditional dual sourcing: lock long‑lead, specialized transducer capacity while qualifying lower‑cost assembly partners for commoditized components.
-
Pursue tactical M&A where CR3 concentration creates scale advantages — look for targets that fill capability gaps (e.g., digital audio processing, clinical hearing device interfaces, or swim‑certified enclosures).
-
Design channel pilots that quantify lifetime value by use case: sports subscription bundles, hearing‑aid integration programs and defense/military procurement pilots have materially different acquisition economics.
What we keep proprietary — why you’ll want the full report
To preserve the strategic advantage for subscribing clients, certain high‑value content is intentionally summarized in this preview. The full report contains:
-
Detailed country and application revenue splits and forecast decks for 2026–2032;
-
SKU‑level average selling price and volume assumptions, by vendor and channel;
-
Vendor scorecards with manufacturing lead times, warranty claims, and quality failure rates;
-
Excel scenario models you can plug into your planning systems to stress test capex and go‑to‑market scenarios;
-
Proprietary supplier risk map and tactical sourcing checklists to mitigate component and labor cost disruption.
Conclusion — timing and next steps for 2026
Bone conduction headphones are no longer a curiosity: they are a category with meaningful scale, evolving regulatory norms, and a concentrated competitive structure that rewards both brand differentiation and supply chain savvy. For 2026 strategy cycles, actionable intelligence—ranging from certification timelines to supplier scorecards and SKU economics—will determine whether an organisation captures premium share or competes in a margin squeeze.
PW Consulting stands ready to support executive teams with tailored workshops, acquisition target canvases, and rapid due‑diligence packages derived from the full study. For access to the complete dataset, VBA‑ready models, and vendor playbooks, please visit the report page or contact our research services desk to arrange a briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Bone Conduction Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Electrostatic Chucks for Wafer Market Poised for 8.45% CAGR through 2032
By pmarketresearch, 2026-07-08
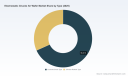
Electrostatic Chucks for Wafer Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As semiconductor nodes compress and fabs push throughput, the electrostatic chuck (ESC) market is entering a sustained growth phase that demands proactive strategic responses. Our latest PW Consulting study, built on a 2020–2025 historical baseline and projecting to 2032, quantifies the sector’s momentum and decodes the operational, supply-chain, and regulatory inflection points that will shape supplier and end‑user strategies in 2026 and beyond. At a compound annual growth rate (CAGR) of 8.45% through the forecasting horizon, the market trajectory underscores both expanding demand and intensifying competitive dynamics. The global market expands notably from the 2025 base year into the 2032 horizon—an outcome that validates investment and reshoring conversations across the value chain.
Electrostatic Chucks for Wafer Market
Why this report matters for 2026 decisions
- Actionable foresight: The report converts macro growth projections into decision-ready scenarios for procurement, R&D prioritization, and capacity investments timed for 2026 capex cycles.
- Risk-informed planning: It overlays supply‑chain fragilities and export/regulatory noise onto demand forecasts to quantify exposure and recommend mitigation measures appropriate for near‑term contracting windows.
- Competitive advantage: By synthesizing technical trends (multi‑zone thermal control, RF‑optimized chucks, AI‑enabled sensing) with market structure metrics, the study helps executives select between organic product development, alliances, and M&A pathways to defend or expand market share.
Market trajectory — what the headline numbers reveal
Using 2025 as a base year, the ESC market exhibits a clear upward trajectory through 2032. Historical market development between 2020 and 2025 shows steady maturation, while the forecast period captures accelerated adoption driven by advanced node requirements and increased localized equipment spending. The reported CAGR of 8.45% reflects both unit demand growth and a premiumization effect as customers adopt high‑value ESC variants (e.g., multi‑zone thermal chucks, RF‑optimized solutions) that command higher average selling prices.
Electrostatic Chucks for Wafer Market
This growth picture is not uniform: technology migration (from legacy nodes to sub‑10nm processes), capacity expansions in leading foundry clusters, and non‑semiconductor usage (MEMS, sensors, specialty fabs) all create differentiated pockets of demand. Our analysis quantifies these dynamics in a way that is immediately usable for capacity planning, but, in line with our 'trailer' approach, detailed subsegment figures are reserved for the full report to ensure maximum commercial utility for subscribers.
Electrostatic Chucks for Wafer Market
Concentration and competitive dynamics
The industry exhibits high concentration among the top suppliers, with the three‑firm concentration and five‑firm concentration indicators signaling a market where scale, IP, and service footprint matter. This structure has strategic implications for pricing power, partnership approaches, and the speed at which new entrants can scale.
- Applied Materials, Inc. — Leveraging multi‑zone thermal control capabilities and recent moves into AI‑enabled wafer handling, Applied Materials is positioning ESCs as integrated subsystems within tool platforms. The firm’s M&A activity signals a push to embed predictive maintenance and process‑aware sensing into the ESC layer.
- Lam Research Corporation — Focused on etch and deposition applications, Lam’s ESC strategy centers on process optimization and tool‑level integration, reinforcing the importance of close OEM‑supplier collaboration for high‑throughput fabs.
- Japanese ceramic specialists (Shinko Electric, Kyocera, NGK, Sumitomo Osaka Cement, TOTO, NTK CERATEC) — These players emphasize materials engineering (e.g., aluminum nitride ceramics, rare earth doping) and production precision, maintaining a competitive edge in manufacturing quality and thermal management.
- Specialized component and regional suppliers (Entegris, II‑VI M Cubed, Calitech, Beijing U‑PRECISION) — These firms compete on niche performance attributes, service proximity to fabs, and cost flexibility, often serving as vital second‑source partners for major tool integrators.
Recent industry moves reinforce these trends: product launches optimized for advanced nodes, acquisitions integrating AI sensors into chuck systems, and partnerships to develop eco‑friendly ceramic solutions—each event illustrates the dual push for technical differentiation and supply resilience.
Supply‑chain and regulatory realities that will shape 2026 playbooks
We identify five interlocking sources of risk that require immediate incorporation into 2026 planning:
- Export controls and licensing complexity: New rules targeting advanced computing items with sophisticated ESC features (for example, systems with many independently controlled temperature zones) mean export licensing is now an integral part of go‑to‑market planning. Firms must integrate compliance and trade remediation costs into tender responses and subcontracting decisions.
- Raw‑material concentration: Key inputs—most notably high‑purity aluminum nitride powder and certain rare‑earth dopants—are concentrated among a few suppliers. The sector has already experienced delivery delays and has been compelled to hold extended safety stocks. Tactical playbooks must include multi‑sourcing, strategic inventory, and supplier development programs.
- Volatility in specialty materials pricing: Quarterly price swings for dopants and engineered ceramics can materially affect margins on high‑performance ESCs. Hedging policies, pass‑through clauses, and cost‑reduction roadmaps must be established before 2026 procurement cycles.
- Localized production incentives: U.S. and EU incentives are accelerating the establishment of near‑fab service hubs and manufacturing footprints. This is a two‑edged sword: proximity unlocks faster service, but it also raises the bar for fixed‑cost investments and drives consolidation among players that can absorb regional setups.
- Geopolitical supply constraints: Technology restrictions affecting cross‑border flows—particularly between the U.S. and China—create uncertainty for companies relying on integrated supply networks. Scenarios range from re‑routing procurement to building duplicate capacity in friendly jurisdictions.
What the PW Consulting report delivers (practical components)
The report is designed to be a practical toolkit for executives and program managers responsible for product roadmap, procurement, and M&A decisions in 2026. Key deliverables include:
- Top‑line and bottom‑line scenario modeling (2026–2032) calibrated to process node adoption curves and fab expansion schedules.
- Supply‑chain heat map highlighting single‑points‑of‑failure for critical materials and optional mitigations (second‑source, inventories, supplier co‑development).
- Regulatory impact assessment that translates current export control and incentive frameworks into commercially relevant constraints and opportunities by geography and product capability.
- Commercial playbooks for OEMs and ESC specialists covering pricing strategy, service‑network design, and aftermarket revenue levers.
- A competitive scorecard benchmarking product features (thermal uniformity, RF compatibility, sensing integration), service reach, and horizontal capabilities such as AI‑enabled predictive maintenance.
- M&A and alliance decision framework that maps capability gaps to likely targets and partnership archetypes—supporting both bolt‑on and platform plays.
How to translate insights into 2026 actions
For executives preparing 2026 budgets, the report suggests a prioritized sequence of actions:
- Immediate (0–6 months): Conduct a supplier concentration audit for critical materials; commence trade‑compliance scenario planning for advanced ESC features; and assess short‑term inventory strategies.
- Near‑term (6–18 months): Validate product roadmaps against node migration timelines; pilot AI‑enabled sensing in controlled lines to validate predictive maintenance ROI; negotiate strategic supply agreements with manufacturing‑grade clauses to lock in quality and lead times.
- Medium‑term (18–36 months): Decide on localized production investments informed by incentive programs; implement near‑fab service hubs where economics and customer proximity justify the cost; or form alliances with local manufacturers to secure market access.
Competitive bets and M&A signals
Given the market concentration and technological premiumization, we see three dominant strategic bets that will differentiate winners in 2026:
- Integration of intelligence: Embedding sensing and analytics into ESCs (as evidenced by recent acquisitions and product launches) yields superior uptime and total cost of ownership narratives for customers.
- Materials leadership: Control over high‑quality ceramics and dopants—either through vertical integration, strategic partnerships, or secured long‑term supply—reduces production variability and shortens qualification cycles.
- Service proximity: Near‑fab servicing and rapid spare availability convert into tangible revenue premiums for tool integrators and ESC specialists alike; investors should expect consolidation to accelerate around these capabilities.
Call to action — what to read next
This preview outlines the contours of a market that is both expanding and becoming more complex. The full PW Consulting report contains the granular segmentation, regional scenario models, detailed supplier matrices, and exact financial forecasts that procurement, product, and corporate development teams will need to craft binding 2026 strategies. We intentionally withhold detailed subsegment and region‑level figures here to preserve the actionable value of that intelligence for subscribers.
For companies preparing capital and operational plans for 2026, the report functions as a strategic playbook: quantify exposure, prioritize mitigations, and align investments with the node and geography‑specific demand signals that will determine who captures premium margins in the coming cycle.
Closing
Electrostatic chucks are no longer a commodity component: they sit at the intersection of materials science, precision manufacturing, and embedded intelligence. The market growth and structural signals highlighted herein make 2026 a pivotal planning year. PW Consulting’s full study equips decision‑makers with the data, risk maps, and playbooks required to convert an industry inflection into competitive advantage—while the accompanying dataset provides the fine‑grained insights necessary to operationalize those choices.
For detailed analysis of this topic, please visit the official page: Electrostatic Chucks for Wafer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
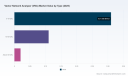
Vector Network Analyzer (VNA) Market — Strategic Preview for 2026 Decision-Makers
As organizations allocate R&D budgets, plan product roadmaps and evaluate M&A targets for 2026, the Vector Network Analyzer (VNA) market presents a mix of steady expansion, concentrated supply, and technical complexity that demands a focused strategy. This preview synthesizes PW Consulting’s latest market study (base year 2025, forecast 2026–2032) to surface the high‑impact implications for corporate leaders without disclosing the granular segmentation tables reserved for subscribers.
Vector Network Analyzer (VNA) Market
Market snapshot: steady, specialised growth
The VNA market has demonstrated a low‑double‑digit resilience in a niche, capital‑intensive segment. After recovering from near‑term volatility, global market revenue stood at approximately USD 0.44 Billion in 2025 and is projected to reach roughly USD 0.56 Billion by 2032, corresponding to a compound annual growth rate of ~3.38% over the forecast period. Historical patterns (2020–2025) show incremental growth punctuated by product refresh cycles and field‑instrument enhancements that temporarily accelerate procurement.
Vector Network Analyzer (VNA) Market
Why this matters for 2026 planning
- Portfolio Prioritisation: A modest but predictable CAGR implies companies can plan multi‑year product investments with reasonable demand visibility, prioritising platforms that are modular and upgradable rather than single‑use, high‑capex refreshes.
- Capital Allocation: Given the capital intensity of high‑frequency VNAs, firms must balance investment in R&D for >15 GHz performance against near‑term revenue opportunities in existing bands. The market’s steady growth favors incremental innovations and service expansion as revenue levers.
- M&A and Partnerships: Market concentration metrics (CR3 ~67%, CR5 ~84%) indicate a top‑heavy competitive landscape. Strategic buyers can gain material share via targeted tuck‑ins that expand multiport capability, software ecosystems or field‑portable instrument portfolios.
Key demand drivers and structural dynamics
Understanding the forces behind VNA demand is essential for scenario planning. Our study identifies several structural drivers that will shape procurement and product development choices through 2026 and beyond:
Vector Network Analyzer (VNA) Market
- Technological mandates: VNAs are indispensable for compliance testing across 5G, IoT and Industry 4.0 applications. As standards evolve and mmWave deployments expand, precise RF characterization becomes non‑negotiable for device OEMs and infrastructure vendors.
- R&D and calibration costs: High‑frequency operation requires premium components, sophisticated data acquisition chains and rigorous calibration. These elements drive up unit costs and favour manufacturers able to amortize R&D over broad product families or service contracts.
- Lab accreditation and trust: Accreditation to standards such as ISO/IEC 17025 is a differentiator for calibration and service networks; buyers increasingly prioritise traceability and documented measurement uncertainty when outsourcing calibration or choosing supplier‑validated instruments.
- Field portability vs. lab capability: The market bifurcates along a functional axis—portable field instruments for on‑site verification and high‑performance lab VNAs for R&D and manufacturing test. Each segment has distinct buying cycles and aftermarket service profiles.
Competitive landscape — what to watch
The VNA suppliers’ landscape is dominated by a handful of incumbents that set the technical benchmark, while a cohort of specialist and cost‑focused vendors compete on form factor and service. The top three firms account for roughly two‑thirds of the market, and the top five capture the vast majority—an important context for acquirers and suppliers alike.
- Keysight Technologies (Santa Rosa, CA, USA) : A technology leader with broad portfolio depth, Keysight continues to push multi‑source, low‑noise receiver architectures into mainstream lab VNAs. Recent product introductions emphasize enhanced internal RF sourcing and receiver combinations to accelerate multiport and non‑linear measurement workflows.
- Rohde & Schwarz (Munich, Germany) : Renowned for high‑frequency performance and multiport systems, Rohde & Schwarz competes at the top end, extending capabilities into sub‑THz ranges and integrated system solutions for aerospace and defence use cases.
- Copper Mountain Technologies (Indianapolis, IN, USA) : A niche competitor that differentiates through compact, USB‑powered 1‑port and 2‑port VNAs and modular calibration solutions—well suited to field applications and cost‑sensitive use cases.
- Anritsu (Morgan Hill, CA, USA) : Offers a balanced product mix spanning portable Site Master instruments to lab VNAs; recent additions have augmented portable units with vector measurement capabilities, blurring the line between field and lab functionality.
Recent development highlights underscore how vendors are translating market needs into product and service moves. For example, a leading supplier launched a PNA‑class VNA architecture with multiple internal RF sources and advanced receiver combinations to accelerate multiport and multi‑tone testing. Another major vendor extended field instruments with vector measurement capabilities—enabling a broader range of on‑site validation tasks previously confined to labs. These moves reduce operational friction for complex RF test, but they also raise the bar for service and calibration support.
Go‑to‑market and pricing considerations
In 2026, successful market plays will combine technical differentiation with service‑led monetisation:
- Value‑based pricing: Charge for measurement accuracy and traceability rather than raw spec metrics. OEMs and tier‑1 buyers will pay a premium for lower uncertainty, documented calibration chains and integrated software that shortens test cycles.
- Service ecosystems: Calibration, software updates, and remote diagnostics are recurring revenue streams. Firms that scale accredited calibration networks and offer subscription‑style analytics will increase customer stickiness and margin stability.
- Modular design and software licensing: Hardware that supports software‑defined measurement modes and paid feature enablement can lower entry price points while preserving ARPU growth over time.
Report deliverables — what our full study contains
PW Consulting’s full VNA Market report is built for practitioners who must make decisions in 2026. Key deliverables include:
- Market sizing and growth models (historical 2020–2025; forecast 2026–2032) with scenario analyses and sensitivity to component cost and standards adoption.
- Granular segmentation across regions, frequency bands and end‑use applications, accompanied by TAM/SAM/SOM methodologies. (Note: detailed segment tables and model files are available in the full report.)
- Competitive benchmarking and product matrix covering performance, port counts, calibration workflows and software ecosystems for leading vendors.
- Supply‑chain heat maps highlighting sources of premium components, lead‑time risk and cost drivers at >15 GHz production thresholds.
- Commercial playbooks for OEMs and test‑service providers: pricing frameworks, go‑to‑market options, partnership targets, and acquisition scorecards.
- Risk register and regulatory tracker covering calibration standards, export controls, and compliance thresholds relevant to RF test and measurement.
Actionable recommendations for 2026
We translate the study’s findings into six immediate actions leaders should consider in 2026:
- Prioritise modular VNA platforms that enable software upgrades to support emerging standards—this reduces stranded capex risk as frequency needs evolve.
- Invest in accredited calibration capability (in‑house or via certified partners). Traceability and low uncertainty are now procurement prerequisites for large OEMs and defence contracts.
- Pair product launches with service bundles (calibration, analytics, remote diagnostics) to create recurring revenue and defend margins in a concentrated market.
- Screen M&A targets using a weighted index that emphasises multiport capability, software IP and field‑instrument share—these factors accelerate entry into adjacent test segments.
- Design a pricing ladder that separates baseline hardware from advanced measurement modes, enabling lower entry points and feature monetisation over time.
- Monitor component supply chains for premium parts used in >15 GHz VNAs; hedging or vendor partnerships can mitigate production and time‑to‑market disruption.
Why PW Consulting’s study helps executives in 2026
Our research is purpose‑built for decision timelines typical of 2026 budgeting cycles: it combines validated growth forecasts (CAGR and revenue trajectory), competitive intelligence on incumbent and challenger vendors, and operational playbooks for engineering, procurement and commercial teams. The analysis is backed by supplier product releases, accreditation and calibration datasets, and sector‑level cost studies that quantify the trade‑offs between performance and manufacturability.
Next steps — access the full intelligence
This preview intentionally omits the detailed segmentation and proprietary financial models that underpin strategic decisions. For procurement teams, product leaders and corporate development groups preparing budgets and bids for 2026, the complete report contains the segment‑level figures, downloadable model files, supplier scorecards and a ranked list of acquisition targets.
To obtain the full report and model pack, visit the PW Consulting Vector Network Analyzer Market page or contact our industry team for a tailored briefing. Our analysts can run a custom workshop to map the implications for your product roadmaps, supply chain hedging and M&A pipeline within a 6–8 week advisory engagement.
— PW Consulting, Advanced Industries Practice
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Metal Fencing Market to Hit USD 15,540M by 2032 at 4.2% CAGR
By pmarketresearch, 2026-07-08
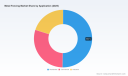
Metal Fencing Market — Strategic Preview for 2026 Decision‑Makers
Executive snapshot
PW Consulting’s latest Metal Fencing Market study builds an actionable intelligence framework designed to inform high‑stakes decisions in 2026. Using 2025 as the base year and a historical review covering 2020–2025, the study models the market through a 2026–2032 forecast window. At a macro level the market is sized at approximately USD 11,650 Million (2025, revenue unit: Million) and is projected to grow at a compound annual growth rate (CAGR) of 4.2% across the forecast period, reaching roughly USD 15,540 Million by 2032. These headline numbers frame an environment where measured growth returns after near-term headwinds, and where strategic positioning — not mere scale — will determine winners.
Metal Fencing Market
Why this report matters in 2026
- Policy shocks and trade friction are now operational risks. Recent policy moves, including antidumping and countervailing duty actions affecting temporary steel fencing and ongoing investigations into imports, have elevated trade policy from occasional nuisance to quarterly planning variable. Supply contracts, sourcing strategies and near‑term pricing need to be stress‑tested against tariff scenarios that are plausible in 2026.
- Raw material volatility is non‑trivial. Global crude steel output and trade flows have shifted recently — monthly production data show declines that translate into meaningful cost and availability swings for metal fencing producers. These dynamics change procurement calculus and the value of vertical integration or long‑term purchasing agreements.
- Fragmentation opens both risk and opportunity. The market structure remains fragmented: a relatively low concentration among leading players means national players can scale through focused M&A while regional specialists retain pricing power in local markets. Identifying the right targets and partnership models is a primary strategic lever for 2026.
Key dynamics shaping near‑term strategy
Decision‑makers should treat the combination of regulatory action, raw material supply shifts, and end‑market demand oscillations as a system of interdependent signals. Our research crystallizes these into four practical dynamics:
Metal Fencing Market
- Trade and tariff regimes: The imposition or threat of antidumping/countervailing duties materially alters cost competitiveness of imported fencing products. Companies must model margins and contract terms under both tariffed and tariff‑free scenarios and prepare playbooks for rapid sourcing shifts.
- Input cost and capacity constraints: Changes in crude steel production and global flows affect lead times and spot pricing. Suppliers with flexible procurement and inventory strategies will outperform fixed‑cost operators when volatility spikes.
- Product and service differentiation: Demand for perimeter security, automation (gate drives and integrated access control), and higher‑durability finishes is rising. Firms that can package hardware with installation, maintenance and automation services capture higher lifetime value.
- Channel and end‑market mix: Residential, commercial and industrial end‑uses respond differently to cyclical pressures. Tailoring channel strategies and financing structures by end market reduces revenue cyclicality and improves client retention.
Competitive landscape — what incumbent moves tell us
We profile established players to illustrate playbooks that succeed in the current environment. Players range from legacy manufacturers of perimeter security systems to specialists in gate automation and woven wire fencing. Representative examples from our primary research include:
Metal Fencing Market
- AMICO Security (Birmingham, AL, USA) — A long‑standing manufacturer of metal fence systems, wire mesh fencing and perimeter security solutions. Historical breadth gives scale benefits, but incumbents must aggressively modernize to maintain margin under supply pressure.
- Calimet Co., Inc. (South El Monte, CA, USA) — Known for assembled‑in‑USA gate automation solutions and metal fence components. Automation and service bundling are clear differentiation levers for suppliers seeking higher margin and stickier customer relationships.
- Bull Barn Fence Factory (USA) — Specialist in woven wire and barbed wire products for agricultural and industrial uses. Niche positioning and category expertise can insulate firms from commodity price moves when coupled with local manufacturing strategies.
- Gregory Fence (Canton, OH, USA) — Manufacturer of American‑made steel fence systems and C‑post products focused on perimeter protection. Strong domestic manufacturing credentials reduce exposure to import disruption and can be monetized in politically sensitive procurement processes.
Recent market activity underscores these trends: multiple vendors showcased product lines and security solutions at The Fence Show & Security Expo (February 2026), indicating continued investment in product innovation and channel engagement. These exhibitions are both a tactical platform and a barometer of firms’ priorities — automation, security integration, and domestic manufacturing were common themes among exhibitors.
Report contents — what you get (practical modules)
The full PW Consulting report is intentionally structured for immediate operational use by C‑suite, strategy, procurement and business development teams. Key deliverables include:
- Market sizing and forecast model (historical 2020–2025; base year 2025; forecast 2026–2032) with downloadable scenario variants
- Demand‑driver mapping by end‑use and channel, with leading indicators and early warning signals to watch quarterly
- Supply chain and input cost model that captures steel and aluminium cost sensitivities, lead‑time risk, and alternative sourcing paths
- Regulatory risk matrix and playbooks for tariff scenarios, antidumping outcomes, and compliance pathways
- Competitive benchmarking toolkit with capability heatmaps and an M&A target short‑list methodology tuned to fragmentation dynamics
- Commercial playbooks: pricing tactics, contract clauses, inventory hedging, and service packaging to defend margins
- Implementation checklist and 90‑day sprint plans for cost containment, supplier diversification and go‑to‑market pivots
Each module combines quantitative models, primary interviews, and executable recommendations. To respect the “preview” principle, our executive summary surfaces strategic implications while the full report contains the granular segment breakdowns, financial models and company scorecards required for transaction due diligence and operational execution.
Strategic recommendations for 2026
- Institutionalize scenario planning: Build tariff/no‑tariff and high/low steel‑price scenarios into monthly reporting. Operationally tag contracts and inventory positions to each scenario to enable rapid activation of contingency plans.
- Prioritise supply‑chain optionality: Diversify suppliers across domestic, near‑shored and vetted offshore partners. Negotiate flexible terms that allow short‑term volume shifts without punitive penalties.
- Monetize services and automation: Shift revenue mix toward bundled offers (hardware + installation + maintenance + automation) to stabilize margins and increase customer switching costs.
- Execute targeted M&A: Use acquisition to fill capability gaps (automation, coating/finishing, local installation networks). The market’s fragmentation makes bolt‑on acquisitions an efficient path to scale and margin expansion.
- Hedge raw material exposure: Combine long‑term purchase agreements, financial hedges and inventory strategies timed to construction seasonality to smooth cost impacts.
- Invest in compliance capability: Strengthen trade compliance and customs intelligence to respond quickly to antidumping and countervailing duty developments and to capture preference opportunities.
- Differentiate on sustainability and circularity: Highlight recycled content, recyclable product designs, and end‑of‑life takeback programs to win public and private procurement mandates increasingly sensitive to ESG metrics.
How to use this preview — next steps for decision makers
This briefing is intended as a strategic primer: it exposes the essential signals, competitive behaviors and decision levers you need to prioritize for 2026. The full PW Consulting Metal Fencing Market report contains the operational detail you will need to act — proprietary segmentation, downloadable financial models, supplier scorecards, and a transaction playbook for M&A activity. We intentionally withhold granular segment numbers in this preview to protect the data and encourage accessing the full intelligence package, which is optimized for implementation.
Final thought
2026 will be a year where tactical agility and strategic clarity matter more than ever. The metal fencing market is not simply recovering to its previous trajectory; it is reshaping under the influence of trade policy, input volatility and changing buyer expectations. Companies that pair disciplined scenario planning with targeted investments in supply‑chain optionality, product differentiation and service monetization will convert a fragmented market into a runway for profitable growth. PW Consulting’s full report equips leaders with the models and playbooks to do exactly that — robustly, fast, and with evidence‑based conviction.
For detailed analysis of this topic, please visit the official page: Metal Fencing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tank Cleaning Services Market to Reach USD 14.44 Billion by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-08
Tank Cleaning Service Market — Strategic Preview for 2026 Decision-Making
Executive summary
As companies plan capital allocations and go-to-market moves for 2026, the tank cleaning services sector presents a clear, accessible growth pathway underpinned by steady demand from energy, chemicals, water treatment and industrial manufacturing. Our analysis shows the global market expanding from an estimated USD 9.28 billion in 2025 toward roughly USD 14.44 billion by 2032, implying a mid-single-digit compounded annual growth rate (CAGR) of approximately 6.5% through the forecast window. That trajectory masks important structural shifts — consolidation among established environmental services players, accelerated adoption of automation and robotics in desludging operations, and a tightening regulatory and liability landscape that is reshaping service design and commercial terms.
Tank Cleaning Service Market
Why this research matters for 2026 planning
-
Portfolio allocation: The growth profile and earnings visibility of tank cleaning services make the segment an attractive defensive growth bet for industrial services investors — but returns will depend on operational discipline and margin capture in hazardous- vs. non-hazardous segments.
Tank Cleaning Service Market -
M&A and partnership timing: The market is at an inflection where strategic buyers can either buy scale to win larger industrial and municipal contracts or acquire specialized capability (robotics, PFAS treatment, advanced sludge recovery). Recent large-scale deals signal that scale plus niche capability is being rewarded in valuations.
Tank Cleaning Service Market -
Cost and insurance planning: Rising compliance scrutiny and high-profile safety incidents are increasing the importance of robust risk management — a material contributor to tender evaluation and insurance pricing in 2026 procurement cycles.
Market trajectory — the macro picture
The market’s expansion from the early 2020s into the mid-2020s reflects a combination of steady replacement demand (scheduled cleaning and desludging), episodic large projects (tank decommissioning, remediation), and an increasing share of work driven by environmental compliance and advanced waste treatment requirements. By 2025, global annual industry revenue reached the high single-digit billions (USD 9.28 billion), and the consensus forecast in our model points toward a roughly USD 14.44 billion market by 2032 at an approximate 6.5% CAGR. That pace is sufficient to sustain both organic investment cases and an active M&A market, but not so rapid as to obscure the need for operational rigor.
Key strategic implications for 2026
-
Invest in safe, automated capabilities now — and make them commercial: Robotics, remote monitoring, and online desludging technologies materially reduce confined-space risk and downtime. Companies that can commercialize automation through time-and-motion productivity gains and demonstrable HSE benefits will command premium contract terms in 2026.
-
Prioritize compliance and liability-proofing: Regulators and customers are tightening permit and entry requirements. High-profile enforcement actions — such as a multi-violation OSHA citation tied to failure to perform atmospheric testing inside tanks (and substantial proposed penalties) — illustrate how safety lapses can create existential cost shocks. Buyers and insurers will prefer vendors with documented confined-space programs, third-party certifications, and digital entry-permit systems.
-
Structure M&A to combine scale with specialty: The market exhibits moderate concentration at the top, making scale attractive for national and multinational procurement. However, buyers should layer on specialty capabilities (advanced contaminant management, PFAS solutions, sludge recovery) to protect margins and reduce cyclicality.
-
Design commercial models around total cost of ownership (TCO): Procurement is shifting from low-cost per-job pricing to TCO models that include environmental disposal, remediation risk, downtime, and reputational factors. Service providers must build and sell integrated TCO analyses to win longer-term agreements.
-
Capitalize on environmental tailwinds: Waste treatment and contaminant-specific remediation (notably PFAS and complex hydrocarbons) are driving incremental service spend. Vendors that integrate advanced treatment and recovery — rather than purely focusing on removal and transport — can capture higher-value scopes.
Competitive landscape — who matters and why
The vendor field contains a mix of global environmental services groups, regional specialists, and technology-focused entrants. Market concentration is meaningful but not prohibitive — the top three players control a significant share of industry revenues, and the top five an even larger slice, leaving space for specialized and regional players to outcompete on capability or cost.
-
Veolia — A global environmental services leader with a strategy of capability-led scale. Recent large acquisitions aimed at hazardous waste and advanced contaminant management underscore Veolia’s intent to broaden its North American footprint and advanced treatment capabilities. For corporate buyers, Veolia represents the archetype of the scale-specialist consolidator.
-
Clean Harbors — A principal North American hazardous-waste and industrial services platform. Its integrated model across treatment, transport and disposal is designed to capture end-to-end value on complex tank cleaning projects.
-
Tradebe and National Tank Services — Regional to continental players that blend full-service offerings with niche remediation projects. They are often preferred on contracts where local permitting and rapid response are determinants.
-
Dulsco and Arham Oil — Examples of regionally dominant firms innovating with service delivery models suited to local market dynamics; case in point, Arham Oil’s 2025 nationwide launch of upgraded robotic crude oil tank cleaning services signals growing market acceptance for automation-led service propositions in high-volume markets.
-
Evergreen Industrial Services , Thompson Industrial Services , SWS Environmental Services , and ARKOIL Technologies — Mid-market players that emphasize time-critical shutdown work, industrial cleaning contracts, and specialist technologies. They are potential acquisition targets for scale players or strategic partners for capability augmentation.
Operational and compliance dynamics shaping vendor selection
-
Confined-space safety and atmospheric testing regimes are now table-stakes. Buyers increasingly require documented permit-to-work systems, third-party auditability, and digital logs of atmospheric testing and PPE compliance. Failure to meet these expectations materially increases both bid rejection rates and insurance costs.
-
Environmental performance is pricing power: Disposal pathways, sludge recovery rates, and PFAS handling capabilities influence lifetime contract economics more than marginal cleaning price. Vendors that can demonstrate higher recovery rates and lower disposal liabilities will command longer contracts and higher margins.
-
Workforce and training are competitive differentiators. Skilled operator scarcity is real in many jurisdictions; firms that invest in upskilling, remote-operated platforms and predictive workforce planning will reduce labor cost volatility.
-
Technology and digital enablement are shifting cost structures. Remote monitoring, digital permits, and automated desludging reduce non-productive time and can be monetized through performance-based contracting.
What the full report delivers — an operational playbook
The PW Consulting Tank Cleaning Service Market report is structured to support executable decisions in 2026. It combines top-line market sizing and forward-looking scenarios with operational toolkits and commercial templates. Highlights include:
- Robust market-sizing methodology with base-year 2025 calibration and a 2026–2032 forecast scenario set; sensitivity testing for oil price, regulatory tightening, and municipal spend.
- Actionable M&A playbooks: target screening criteria, valuation multiples benchmarking, and integration checklists tailored for both scale buyers and capability acquirers.
- Vendor due-diligence templates and RFP evaluation rubrics that weight safety, environmental treatment capability, and TCO impact.
- Commercial models and sample contract language for performance-based and TCO-oriented deal structures.
- Operational levers: productivity-improvement roadmaps (automation adoption curves, crew productivity KPIs), and CapEx/Opex models for scaling robotics and advanced treatment lines.
- Regulatory and safety compendium: concise summaries of confined-space entry requirements, permit frameworks, and recent enforcement trends to inform compliance budgeting and insurance discussions.
Concrete near-term recommendations for 2026
-
Buyers: Tighten vendor pre-qualification on HSE and advanced treatment credentials; prefer multi-year TCO contracts that shift disposal and remediation risk back to vendors with demonstrated treatment capability.
-
Service providers: Prioritize investments in robotic desludging and online sludge-processing capability that demonstrably reduce confined-space exposure; use pilot projects to build commercial case studies for premium pricing.
-
Investors: Target carve-outs and bolt-on acquisitions that add contaminant-specific treatment or coverage in underpenetrated geographies, but require clear integration plans to capture cross-selling opportunities.
-
Risk managers: Reassess insurance programs and bonding capacity, incorporating recent regulatory actions and penalties into stress-testing models for potential operational lapses.
Concluding perspective — opportunity with discipline
The tank cleaning services market in 2026 offers predictable top-line growth and multiple strategic pathways for value creation — organic specialization, technology-driven productivity, and consolidation-led scale. Yet, the market prize will go to organizations that combine safety-first operational discipline with differentiated technical capability and commercially savvy contract design. Our full report equips executives with the diagnostic data, playbooks, and vendor intelligence needed to act decisively in 2026. For a deep dive into scenario-modeled forecasts, company profiles, and the full competitive dataset, access the complete PW Consulting Tank Cleaning Service Market study.
For detailed analysis of this topic, please visit the official page: Tank Cleaning Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Diamond Wire Saw Market to reach USD 1,586.66M by 2032 at 5.2% CAGR
By pmarketresearch, 2026-07-08
Diamond Wire Saw Market 2026: Strategic Imperatives for Corporate Decision‑Makers
As organizations plan their capital allocation and product roadmaps for 2026, the diamond wire saw market demands strategic attention. Our latest PW Consulting study—anchored on a 2025 base year and a forecast through 2032—translates raw market movement into decision-ready insight. The global market, measured in USD Million, has trended upward from the early 2020s and reached a robust baseline in 2025; our model projects continued expansion through 2032 at a compound annual growth rate (CAGR) of 5.2%. This briefing explains why that trajectory matters, what the full study delivers, and the pragmatic moves we recommend for market leaders, challengers, and investors approaching the crucial 2026 inflection point.
Diamond Wire Saw Market
Executive snapshot — what the headline numbers mean
-
Historical momentum: The market recovered and expanded through the 2020–2025 period, establishing a more resilient base for the next planning cycle. Variations across years reflect cyclical demand in target end‑markets and episodic supply constraints.
Diamond Wire Saw Market -
2025 as the strategic baseline: Our analysis uses 2025 as the base year to normalize recent volatility and to provide a clean reference for 2026 budget cycles and contract negotiations.
Diamond Wire Saw Market -
Forecast envelope: With a 5.2% CAGR applied over 2026–2032, scenario modeling indicates steady market expansion under a mid‑case macroeconomic assumption. The upper and lower bounds in the report stress‑test this trajectory against commodity price shocks, policy shifts in solar and semiconductor sectors, and accelerated automation adoption.
-
Market structure: Concentration metrics indicate a market that is meaningfully consolidated among leading suppliers, creating both barriers and strategic opportunities for entrants and incumbents. Our competitive concentration indicators show high top‑tier control, which has implications for pricing power, channel strategy, and M&A dynamics.
Why this study matters for 2026 decisions
-
CapEx and capacity planning: Equipment manufacturers and component suppliers must align 2026 capital plans with expected demand profiles. The report provides a forward‑looking capacity utilization model and oxygenates strategic timing for factory investments or outsourcing agreements.
-
Portfolio rationalization: OEMs and distributors face decisions on product line breadth versus depth. Our economics‑driven framework quantifies margin trade‑offs between premium single‑wire solutions and high‑throughput multi‑wire systems—information that is essential for 2026 product rationalization cycles.
-
Pricing strategy and procurement: With core supply chain inputs under pressure in intermittent spurts, procurement teams need indexed pricing strategies and hedging options. The study offers a practical pricing calendar and procurement playbook tailored to 12–36 month contract negotiations.
-
M&A and partnership screening: Given industry concentration and technology differentiation, 2026 will be active for bolt‑on acquisitions and strategic alliances. Our target screening matrix ranks candidates by capability, IP strength, and integration risk to accelerate dealflow due diligence.
What’s in the full report — practical, implementable content
-
Market sizing and methodology: Transparent bottom‑up and top‑down approaches, reconciled to the 2025 base year, with sensitivity ranges tied to macro scenarios.
-
Demand‑side segmentation: A stripped, decision‑centric view of demand drivers across end‑use verticals and regions, with an emphasis on adoption curves, procurement cycles, and lifecycle replacement rates.
-
Technology and product taxonomy: Comparative benchmarking of electroplated, resin‑bond, and emerging hybrid wire systems—covering lifecycle costs, throughput, and suitability by application cluster.
-
Supply‑chain heatmap: Identification of supplier concentration points, critical raw‑material exposures, typical lead times, and contingency sourcing options for 2026 and beyond.
-
Pricing and cost models: Unit economics, TCO calculators, and live‑scenario templates that allow commercial teams to model offers by customer type and contract length.
-
Regulatory and standards impact: Assessment of relevant quality standards, certification pathways, and regional compliance considerations that influence procurement and export strategies.
-
Commercial playbooks: Go‑to‑market blueprints for incumbents, niche specialists, and new entrants—covering channel models, service monetization, digital aftermarket offers, and warranty design.
-
Risk framework and early‑warning indicators: A prioritized list of macro, supply, and demand signals to monitor monthly or quarterly to detect turning points.
-
M&A and partnership briefings: Valuation benchmarks, integration scorecards, and a short‑list of strategic targets by capability cluster.
Competitive landscape — who to watch and why
-
Well Diamond Saws SA (Switzerland) — https://www.well-dws.com/en/ : A long‑standing precision specialist with a global installed base. Their patented approaches to synthetic diamond coatings and low‑heat cutting mechanics position them as the reference standard for high‑precision, low‑waste applications. Technical differentiators (e.g., low applied force operation and conservative wire speeds to avoid thermal damage) create strong value in brittle‑material slicing and premium industrial use cases.
-
Ensoll Tools Technology Co., Ltd. (China) — https://www.ensolltools.com/ : An integrated supplier of endless loops and machines, with an IP portfolio and certifications that underpin industrial adoption. Their vertically integrated model and engagement in digital content and customer education accelerate adoption in price‑sensitive, high‑volume segments.
-
GTI Technologies, Inc. (United States) — https://www.gti-usa.com/ : A specialist channel and systems supplier focused on high‑speed slicing and multi‑wire systems for advanced materials. Their emphasis on high throughput and system scalability makes them relevant for semiconductor and advanced material applications where cycle time is the primary performance metric.
-
Collective trend: Leading players combine machine design, diamond wire engineering, and aftermarket services. Competitive advantage accrues to firms that control the full lifecycle—from consumable design to predictive maintenance—enabling recurring revenue and defender economics.
-
Recent product and market moves: Throughout 2025 several notable launches and product updates appeared in the ecosystem—from multi‑size ingot systems announced at major industry events to high‑speed releases for stone processing—signaling a bifurcation between premium precision investments and volume‑oriented solar/photovoltaic plays.
Market dynamics and immediate 2026 risks
-
Input cost volatility: The market is sensitive to diamond abrasive availability and specialty steel wire costs. Procurement disciplines and dual‑sourcing strategies are essential to dampen margin cyclicality.
-
Technology substitution and lifecycle risk: As wafer and ingot geometries evolve, so do cutting requirements. Firms that fail to align product roadmaps with downstream format shifts will face accelerated obsolescence.
-
Regulatory and certification pressures: Quality and safety certifications remain a gating factor for large OEM contracts. Compliance roadmaps should be part of any 2026 go‑to‑market plan.
-
Aftermarket and services as defense: With equipment becoming more capable and longer‑lasting, recurring revenue strategies—consumables contracts, predictive maintenance, software updates—are the primary lever for margin protection.
Strategic playbook — five priority moves for 2026
-
Lock in mid‑term supply via tiered contracts: Structure multi‑year agreements with price adjustment collars and performance SLAs to stabilize input cost exposure while preserving upside if prices decline.
-
Monetize the aftermarket: Design subscription and outcome‑based offers around consumables and uptime guarantees. Use telematics and remote diagnostics to convert installed bases into recurring revenue streams.
-
Prioritize modular product architectures: Invest in modular machine platforms that can be reconfigured for premium or high‑throughput slices. This reduces time‑to‑market for emerging use cases and lowers NPI risk.
-
Pursue targeted bolt‑ons and strategic alliances: Seek acquisitions that fill capability gaps—either in abrasives, wire metallurgy, or software—rather than broadscale horizontal buyouts. Our M&A scorecard in the report ranks candidate types by integration complexity and ROI horizon.
-
Operationalize early‑warning indicators: Adopt the report’s sensor set to monitor lead times, order intake cadence, and end‑market booking slippage so you can shift between capacity modes without incurring excess cost.
Accessing the full intelligence — what we deliberately withhold here
This briefing intentionally demonstrates the depth and framing that characterize the full PW Consulting report while withholding granular regional and application‑level splits, exact pricing curves by configuration, and the detailed segment revenue tables. Those core segmentation datasets, scenario files, and model workbooks are the proprietary parts of the study designed to be used as interactive tools by strategy and procurement teams. If you are preparing 2026 budgets, negotiating supplier agreements, or evaluating acquisition targets, the full report contains the actionable line‑by‑line inputs and model artifacts you will need.
To convert the directional guidance above into executable plans—including downloadable TCO calculators, supplier scorecards, and a prioritized M&A shortlist—access the complete market study. PW Consulting’s proprietary models will let you stress‑test your 2026 choices across price shocks, demand pivots in semiconductor and photovoltaic channels, and alternative competitive responses.
For executives and investors who need decision‑grade intelligence on the diamond wire saw market in 2026, the full report is the operational primer for turning macro projections and competitive signals into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Diamond Wire Saw Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Rotary Kiln Market 2026: Strategic Intelligence for Executive Decision-Making
As global industrial priorities shift toward decarbonization, resource efficiency, and resilient supply chains, rotary kilns remain a strategic asset across cement, lime, metallurgical and specialty thermal-processing industries. PW Consulting’s latest Rotary Kiln Market study — anchored on a 2025 base year and extending forecasts to 2032 — translates market movements into concrete actions executives must consider in 2026. This introduction outlines why the study matters for near-term capital allocation, technology choices, and partnership strategies, while intentionally reserving the granular segment figures for the full report.
Rotary Kiln Market
Macro trajectory: clear growth, measured pace
Between 2020 and 2025 the global rotary kiln market expanded from roughly USD 550 million to approximately USD 719 million, reflecting recovery dynamics, equipment renewal cycles, and pockets of retrofit activity. Looking forward, our model indicates a compound annual growth rate of about 3.1% through the 2026–2032 forecast window, with the market approaching the high-eight-hundred million USD range by the end of the period. These headline metrics frame the operating environment: steady expansion rather than explosive disruption, which implies that disciplined, targeted investments will outperform broad-brush rollouts.
Rotary Kiln Market
Why this matters for 2026 enterprise decisions
- Capex timing and sizing — A 3.1% CAGR and the observed mid-cycle demand patterns suggest that 2026 is an optimal year for selective brownfield upgrades and efficiency-focused revamps rather than widescale greenfield expansion in most regions. Firms with constrained capital should prioritize projects that deliver improved fuel efficiency, longer refractory life, and emissions compliance.
- Technology selection — The incremental nature of market growth favors modular, upgradeable systems (e.g., advanced preheater configurations, sensorized drives, and distributed combustion systems) over one-off bespoke builds that carry longer payback horizons.
- Supply‑chain & procurement strategy — Steel-price volatility and delivery lead times remain key inputs into procurement decisions. Locking flexible procurement terms, staged deliveries, and vertical partnerships with supplier-manufacturers capable of factory-direct execution will materially reduce schedule and cost risk.
- Decarbonization investment sequencing — Regulatory pressure and operational economics make staged fuel-switching, advanced combustion controls, and waste-heat recovery compelling near-term priorities with tangible ROI, while low-carbon fuels and CCUS-linked pathways can be prioritized for later implementation as costs and policy incentives evolve.
- M&A and partnership signals — The market concentration profile — moderately consolidated with a top-three share under half and the top-five collectively stronger — creates acquisition and partnership opportunities for companies seeking scale, geographic diversification, or technology access.
Report practicalities: what PW Consulting delivers to executives
Our full study is structured to be immediately operational for leadership teams, plant managers, and corporate development groups. Deliverables include:
Rotary Kiln Market
- Robust historical benchmarking (2020–2025) and a transparent 2026–2032 forecasting model with scenario toggles for fuel cost shocks, steel-price volatility, and regulatory tightening.
- Actionable capex prioritization matrices that rank projects by payback, CO2 abatement per USD invested, and implementation complexity.
- Vendor selection frameworks and an RFP template calibrated to kiln-specific technical milestones, warranty structures, and spare-parts logistics.
- Retrofit pathways and techno-economic case studies that outline stepwise interventions (combustion tuning, preheater retrofits, automation overlay) with expected efficiency gains and risk profiles.
- Regulatory and standards playbooks, including implications from recent ASTM guidance affecting kiln-produced aggregates and materials handling.
- Risk heatmaps capturing raw-material exposure (notably steel), labor and skills scarcity, and supply-chain single points of failure, plus mitigation strategies.
To preserve competitive advantage for report subscribers, this public introduction highlights the strategic contours while withholding the granular segment- and region-level revenue breakdowns that drive precise sourcing and portfolio decisions. The full report contains those figures, supporting downloadable models, and supplier scorecards.
Competitive landscape — profiles and strategic implications
The rotary kiln market is served by a mix of global engineering houses, regional manufacturers, and niche systems integrators. Our competitive review focuses on eight firms that exemplify the diverse capable players shaping 2026 strategies:
- FLSmidth (Copenhagen, Denmark) — A global leader with extensive installed base and turnkey capabilities. Recent high-profile deliveries underscore their capacity to execute long-lead, complex kiln projects for minerals and refined-material processors. Strategic implication: premium engineering and project-management capability, making them a partner of choice for high-complexity greenfield and large revamp projects.
- FEECO International (Eau Claire, WI, USA) — North American specialist with strong pilot-scale and testing services. Strategic implication: ideal for firms that require empirically validated process scale-up and customized thermal solutions.
- KHD Humboldt Wedag (Cologne, Germany) — German engineering specialist focused on cement-industry kiln systems. Strategic implication: deep process know-how and integration competence for plants pursuing high-reliability modernization.
- CITIC Heavy Industries (China) — High-volume manufacturer with extensive global deployment of rotary kilns across cement, lime and pellet applications. Strategic implication: competitive cost and manufacturing scale, attractive for large-volume procurement with considerations for local service networks.
- AGICO Cement Machinery (China) — Factory-direct supplier offering a breadth of kiln types and comprehensive revamp services. Strategic implication: compelling value proposition for price-sensitive projects where direct sourcing can offset logistic complexity.
- Jiangsu Pengfei Group (China) — Strong in customized rotary kiln systems including specialty wet-pulp caustic processes. Strategic implication: good fit for niche process applications and custom engineering requirements.
- thyssenkrupp Polysius (Germany) — Integrated pyro-processing systems supplier with an emphasis on holistic plant performance. Strategic implication: favored where tight integration between kiln systems and overall plant architecture delivers operational synergies.
- HiTemp Tech Corporation (USA) — Manufacturer of factory-built rotary kiln incineration systems for waste streams. Strategic implication: key for firms pursuing waste-to-energy or hazardous-waste thermal processing pathways.
Recent commercial movements reinforce market signals: notable deliveries and orders announced in 2025 include a long rotary kiln delivery to a lithium refinery, strategic wet-pulp caustic orders, and large-scale revamp completions. These developments indicate continued investment in processing capacity for critical minerals and ongoing optimization of cement production lines.
Market dynamics and structural risks
- Raw materials: Steel is the principal input for kiln shells and structural components. Price instability in steel markets can compress margins and delay projects if not hedged appropriately.
- Labor and technology: Adoption of AI-enabled process optimization and IoT monitoring is reducing operational labor intensity while improving fuel efficiency by an estimated 10–15% in adopters. Firms that deploy these systems early can capture significant operating cost advantages.
- Regulation and standards: Stricter emissions regimes — particularly in Europe — are accelerating investments in advanced filtration, combustion optimization, and fuel-switching. Additionally, updated ASTM standards for kiln-produced aggregates and amendments affect product specifications and downstream market access.
- Concentration dynamics: The market displays moderate concentration: the top three vendors do not dominate the market, while the top five exert a meaningful share. This structure supports both global, scale-driven suppliers and well-positioned regional specialists.
Practical takeaways for 2026 planning
- Prioritize retrofit projects that deliver both emissions reductions and fuel-efficiency gains — these repay capex faster and reduce regulatory and carbon liabilities.
- Negotiate procurement terms that account for steel-price volatility, phased delivery, and local service commitments to mitigate schedule risk.
- Embed digital monitoring and predictive maintenance as part of any capital project to accelerate OPEX improvement and extend asset life.
- Use external pilot testing or vendor-led demonstration programs for process-critical applications — the incremental cost is modest relative to the downside of scale-up failure.
- Monitor standards and regulatory trends closely; compliance-adjacent investments (e.g., filtration pilot units) can often be staged to align with incentive windows.
Next steps
PW Consulting’s Rotary Kiln Market report provides the detailed segment and regional breakdowns, downloadable modeling tools, vendor scorecards, and retrofit blueprints needed to convert these strategic takeaways into executable plans. For executives preparing 2026 capex cycles, procurement rounds, or M&A activity, the full report is structured to accelerate decisions with defensible numbers and pragmatic implementation guidance.
Contact PW Consulting or visit our report page to access the full analysis, scenario models, and supplier benchmarking tools — the granular revenue splits and actionable vendor matrices are available exclusively in the subscriber package.
For detailed analysis of this topic, please visit the official page: Rotary Kiln Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Neutron Generators Market: Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a concise, decision‑focused introduction to our new Neutron Generators Market study. This briefing highlights the strategic value of the research for corporate leaders, investors, procurement teams, and policy planners as they set priorities for 2026. It demonstrates the analytical depth of the full report while deliberately omitting the detailed segment tables and region/application breakouts that are reserved for subscribers and licensed users.
Neutron Generators Market
Market at a glance — what the macro numbers tell us
Between 2020 and 2025 the global neutron generators market expanded steadily, moving from USD 45.23 Million (2020) to USD 58.45 Million (2025). Our forecast covers 2026–2032 and projects continued expansion to USD 93.45 Million by 2032, driven by a compound annual growth rate (CAGR) of 6.95% across the period. Those headline figures encapsulate multiple, overlapping demand streams — from industrial nondestructive testing and resource exploration to emerging medical and security applications — each affected by technology, regulation, and procurement rhythms.
Neutron Generators Market
Why this study matters for 2026 decisions
- Timing capital and procurement cycles correctly. The market trajectory implies a window in which early movers that align product roadmaps with regulatory readiness, export controls, and customer validation can capture disproportionate value. The report prioritizes scenarios where spending accelerates and where it plateaus, enabling CFOs to align capex schedules with realistic revenue capture.
- Understanding technology inflection points. Compact high‑yield D‑D generators and extended‑life D‑T architectures are shifting value toward new OEMs and technology integrators. Our analysis identifies where performance improvements (flux, lifetime, portability) change use cases and where incumbents face obsolescence risk.
- Navigating complex compliance and export constraints. Regulatory dynamics materially affect addressable markets. Our research synthesizes NRC/Agreement State licensing implications, EAR export licensing requirements, dual‑use controls under multilateral regimes, and medical device approval pathways — all essentials for 2026 export and go‑to‑market planning.
- Translating fragmentation into M&A and partnership opportunities. The market concentration metrics point to a fragmented competitive set with room for consolidation and strategic alliances. For corporate development teams, the report provides a structured framework for value‑capture through tuck‑ins, technology licensing, and distribution partnerships.
Key strategic implications by stakeholder
- Buyers (Oil & Gas, Aerospace, Research Institutions, Hospitals, Security Agencies)
Procurement teams should treat neutron generator purchases as integrated procurements — equipment, licensing, installation, maintenance, and regulatory compliance form a single project. Our report provides a procurement checklist and decision tree that maps performance requirements to licensing pathways and total cost of ownership (TCO) profiles over typical lifecycles.
Neutron Generators Market - Suppliers and OEMs
Product roadmaps must prioritize not only yield and lifetime but also serviceability and regulatory provenance. Investments in modular designs, evidence packages for CE/medical approvals, and validated export control compliance will determine which suppliers can scale across jurisdictions in 2026.
- Investors and PE
Private investors should underwrite technology risk separately from regulatory risk. Our model produces alternate valuations under different licensing and export scenarios, helping investment committees price the impact of denied or delayed exports and extended medical certification timelines.
Technology and market dynamics to watch in 2026
- High‑intensity, compact D‑D systems: Recent technical advances show that compact D‑D sources can achieve imaging‑grade yields with high uptime. This reduces operational constraints for laboratories and mobile inspection fleets and changes total cost equations when tritium licensing is avoidable.
- Extended‑life neutron tubes: Patented long‑life designs with multi‑thousand‑hour operational windows change service and replacement cycles, favoring platforms that can demonstrate predictable lifetime economics.
- Medical adoption hurdles and opportunities: Hospital‑grade BNCT and other therapeutic applications present high revenue upside but require compliance with Class III medical device frameworks, extensive clinical evidence, and long reimbursement cycles — critical inputs for any commercialization plan.
- Export and classification regimes: Dual‑use status under multilateral arrangements and national export controls create gating factors for addressable market geography. Supply chain design and customer selection must reflect validated licensing strategies.
Competitive landscape — who matters and why
The market is characterized by an interplay of specialist producers, large instrument houses, and fast‑moving technology startups. The three‑ and five‑firm concentration levels indicate a moderately fragmented industry where niche differentiation and IP matter:
- Adelphi Technology, Inc. (Redwood City, CA) — Known for a product range covering D‑T, D‑D and moderated D‑D neutron sources, Adelphi is positioned across industrial analysis, radiography, NDT and security segments. Its engineering focus makes it a key supplier for integrated field systems.
- Sodern (Bois‑Guillaume, France) — With strengths in electric neutron sources and activation analyzers, Sodern is a specialist in oil‑logging, waste characterization and cross‑belt analysis for heavy industries. Its civil tube expertise makes it a preferred partner for continuous process analytics.
- Phoenix (Germany) — Focused on high‑intensity neutron sources for imaging and NDT, Phoenix serves aerospace and defense quality assurance needs where imaging resolution and throughput are critical procurement criteria.
- NSD Fusion / Gradel (Germany) — Holds patents on long‑life generators with high specific power and stable output profiles. These attributes translate into lower life‑cycle costs for customers requiring routine, high‑uptime operations.
- Thermo Fisher Scientific (Colorado Springs, CO) — A major instrument house delivering compact portable generators for elemental analysis and field/laboratory use. Thermo Fisher’s distribution reach and catalog updates position it as a bridge between research markets and commercial deployments.
Recent vendor and research developments reinforce the above dynamics: product catalog updates and new laboratory models have appeared from established instrument manufacturers; academic and national labs continue to place procurement orders for 14 MeV systems; and independent R&D efforts report compact, high‑uptake D‑D breakthroughs. These events collectively accelerate adoption in applications where footprint and uptime are decisive.
Regulatory and policy "noise" that changes outcomes
- U.S. regulatory practice treats electronic neutron generators as radiation‑producing machines under Agreement State regimes, which affects licensing timelines and operational compliance in domestic projects.
- D‑T systems containing tritium above set activity thresholds require specific possession licenses, making alternatives attractive where regulatory burden is a strategic consideration.
- High‑performance systems are often subject to EAR controls and may need validated export licenses for certain destinations; dual‑use classification under multilateral arrangements adds another layer of export risk.
- Hospital‑grade BNCT and similar medical systems face Class III medical device approvals in the U.S., CE marking and equivalent processes elsewhere — a multi‑year pathway with significant clinical evidence requirements.
What PW Consulting’s full report provides (practical deliverables)
- Historical market sizing (2020–2025) and a detailed 2026–2032 forecast model with scenario analysis tied to regulatory and technology outcomes.
- Vendor benchmarking and detailed company profiles with SWOT for leading and fast‑emerging players, including engineering capabilities and service models.
- Commercial due diligence tools — TCO calculators, licensing‑sensitive addressable market models, contract risk checklists, and export control playbooks.
- Go‑to‑market and M&A playbooks — recommended partnership archetypes, valuation sensitivity tests, and integration considerations for cross‑border deals.
- Actionable procurement templates — bid evaluation matrices, installation and commissioning roadmaps, and lifecycle maintenance schedules.
Note: in line with our “trailer” approach, the public summary intentionally omits the granular regional, type and application split tables and the full numeric segment sheets. Those segment‑level datapoints and executable slide decks are available through the report access page and are essential for transaction‑level decision making.
How to use this research to inform 2026 plans
- Align budget cycles with the forecasted growth windows and the licensing cadence in your jurisdictions; avoid committing to procurement before export approvals can be obtained for cross‑border deployments.
- Prioritize partnerships with vendors that can document lifecycle performance and regulatory compliance; long‑life tube patents and proven field uptime materially reduce operational risk.
- For investors, segregate technology value from regulatory exposure in valuation models; price in probability‑weighted scenarios for export denials and prolonged medical approvals.
- For R&D leaders, target performance metrics that unlock new use cases — e.g., reductions in tritium dependence, increases in uptime, and modular designs that simplify maintenance and compliance.
For executives preparing strategic plans, procurement directors drafting RFPs, or investors conducting due diligence in 2026, our study provides the frameworks and validated scenario models needed to make defensible decisions. To access the detailed segmentation, vendor scorecards, and the licensing impact matrices that support executable plans, consult the full PW Consulting Neutron Generators Market report.
Contact PW Consulting to request the complete report and the accompanying decision toolkits. The full deliverable contains the proprietary segment tables and model workbooks that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Neutron Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com