

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: VNA Market Poised for 3.38% CAGR Through 2032

Vector Network Analyzer (VNA) Market — Strategic Preview for 2026 Decision-Makers
As organizations allocate R&D budgets, plan product roadmaps and evaluate M&A targets for 2026, the Vector Network Analyzer (VNA) market presents a mix of steady expansion, concentrated supply, and technical complexity that demands a focused strategy. This preview synthesizes PW Consulting’s latest market study (base year 2025, forecast 2026–2032) to surface the high‑impact implications for corporate leaders without disclosing the granular segmentation tables reserved for subscribers.
Vector Network Analyzer (VNA) Market
Market snapshot: steady, specialised growth
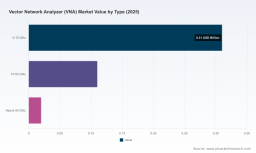
The VNA market has demonstrated a low‑double‑digit resilience in a niche, capital‑intensive segment. After recovering from near‑term volatility, global market revenue stood at approximately USD 0.44 Billion in 2025 and is projected to reach roughly USD 0.56 Billion by 2032, corresponding to a compound annual growth rate of ~3.38% over the forecast period. Historical patterns (2020–2025) show incremental growth punctuated by product refresh cycles and field‑instrument enhancements that temporarily accelerate procurement.
Vector Network Analyzer (VNA) Market
Why this matters for 2026 planning
- Portfolio Prioritisation: A modest but predictable CAGR implies companies can plan multi‑year product investments with reasonable demand visibility, prioritising platforms that are modular and upgradable rather than single‑use, high‑capex refreshes.
- Capital Allocation: Given the capital intensity of high‑frequency VNAs, firms must balance investment in R&D for >15 GHz performance against near‑term revenue opportunities in existing bands. The market’s steady growth favors incremental innovations and service expansion as revenue levers.
- M&A and Partnerships: Market concentration metrics (CR3 ~67%, CR5 ~84%) indicate a top‑heavy competitive landscape. Strategic buyers can gain material share via targeted tuck‑ins that expand multiport capability, software ecosystems or field‑portable instrument portfolios.
Key demand drivers and structural dynamics
Understanding the forces behind VNA demand is essential for scenario planning. Our study identifies several structural drivers that will shape procurement and product development choices through 2026 and beyond:
Vector Network Analyzer (VNA) Market
- Technological mandates: VNAs are indispensable for compliance testing across 5G, IoT and Industry 4.0 applications. As standards evolve and mmWave deployments expand, precise RF characterization becomes non‑negotiable for device OEMs and infrastructure vendors.
- R&D and calibration costs: High‑frequency operation requires premium components, sophisticated data acquisition chains and rigorous calibration. These elements drive up unit costs and favour manufacturers able to amortize R&D over broad product families or service contracts.
- Lab accreditation and trust: Accreditation to standards such as ISO/IEC 17025 is a differentiator for calibration and service networks; buyers increasingly prioritise traceability and documented measurement uncertainty when outsourcing calibration or choosing supplier‑validated instruments.
- Field portability vs. lab capability: The market bifurcates along a functional axis—portable field instruments for on‑site verification and high‑performance lab VNAs for R&D and manufacturing test. Each segment has distinct buying cycles and aftermarket service profiles.
Competitive landscape — what to watch
The VNA suppliers’ landscape is dominated by a handful of incumbents that set the technical benchmark, while a cohort of specialist and cost‑focused vendors compete on form factor and service. The top three firms account for roughly two‑thirds of the market, and the top five capture the vast majority—an important context for acquirers and suppliers alike.
- Keysight Technologies (Santa Rosa, CA, USA) : A technology leader with broad portfolio depth, Keysight continues to push multi‑source, low‑noise receiver architectures into mainstream lab VNAs. Recent product introductions emphasize enhanced internal RF sourcing and receiver combinations to accelerate multiport and non‑linear measurement workflows.
- Rohde & Schwarz (Munich, Germany) : Renowned for high‑frequency performance and multiport systems, Rohde & Schwarz competes at the top end, extending capabilities into sub‑THz ranges and integrated system solutions for aerospace and defence use cases.
- Copper Mountain Technologies (Indianapolis, IN, USA) : A niche competitor that differentiates through compact, USB‑powered 1‑port and 2‑port VNAs and modular calibration solutions—well suited to field applications and cost‑sensitive use cases.
- Anritsu (Morgan Hill, CA, USA) : Offers a balanced product mix spanning portable Site Master instruments to lab VNAs; recent additions have augmented portable units with vector measurement capabilities, blurring the line between field and lab functionality.
Recent development highlights underscore how vendors are translating market needs into product and service moves. For example, a leading supplier launched a PNA‑class VNA architecture with multiple internal RF sources and advanced receiver combinations to accelerate multiport and multi‑tone testing. Another major vendor extended field instruments with vector measurement capabilities—enabling a broader range of on‑site validation tasks previously confined to labs. These moves reduce operational friction for complex RF test, but they also raise the bar for service and calibration support.
Go‑to‑market and pricing considerations
In 2026, successful market plays will combine technical differentiation with service‑led monetisation:
- Value‑based pricing: Charge for measurement accuracy and traceability rather than raw spec metrics. OEMs and tier‑1 buyers will pay a premium for lower uncertainty, documented calibration chains and integrated software that shortens test cycles.
- Service ecosystems: Calibration, software updates, and remote diagnostics are recurring revenue streams. Firms that scale accredited calibration networks and offer subscription‑style analytics will increase customer stickiness and margin stability.
- Modular design and software licensing: Hardware that supports software‑defined measurement modes and paid feature enablement can lower entry price points while preserving ARPU growth over time.
Report deliverables — what our full study contains
PW Consulting’s full VNA Market report is built for practitioners who must make decisions in 2026. Key deliverables include:
- Market sizing and growth models (historical 2020–2025; forecast 2026–2032) with scenario analyses and sensitivity to component cost and standards adoption.
- Granular segmentation across regions, frequency bands and end‑use applications, accompanied by TAM/SAM/SOM methodologies. (Note: detailed segment tables and model files are available in the full report.)
- Competitive benchmarking and product matrix covering performance, port counts, calibration workflows and software ecosystems for leading vendors.
- Supply‑chain heat maps highlighting sources of premium components, lead‑time risk and cost drivers at >15 GHz production thresholds.
- Commercial playbooks for OEMs and test‑service providers: pricing frameworks, go‑to‑market options, partnership targets, and acquisition scorecards.
- Risk register and regulatory tracker covering calibration standards, export controls, and compliance thresholds relevant to RF test and measurement.
Actionable recommendations for 2026
We translate the study’s findings into six immediate actions leaders should consider in 2026:
- Prioritise modular VNA platforms that enable software upgrades to support emerging standards—this reduces stranded capex risk as frequency needs evolve.
- Invest in accredited calibration capability (in‑house or via certified partners). Traceability and low uncertainty are now procurement prerequisites for large OEMs and defence contracts.
- Pair product launches with service bundles (calibration, analytics, remote diagnostics) to create recurring revenue and defend margins in a concentrated market.
- Screen M&A targets using a weighted index that emphasises multiport capability, software IP and field‑instrument share—these factors accelerate entry into adjacent test segments.
- Design a pricing ladder that separates baseline hardware from advanced measurement modes, enabling lower entry points and feature monetisation over time.
- Monitor component supply chains for premium parts used in >15 GHz VNAs; hedging or vendor partnerships can mitigate production and time‑to‑market disruption.
Why PW Consulting’s study helps executives in 2026
Our research is purpose‑built for decision timelines typical of 2026 budgeting cycles: it combines validated growth forecasts (CAGR and revenue trajectory), competitive intelligence on incumbent and challenger vendors, and operational playbooks for engineering, procurement and commercial teams. The analysis is backed by supplier product releases, accreditation and calibration datasets, and sector‑level cost studies that quantify the trade‑offs between performance and manufacturability.
Next steps — access the full intelligence
This preview intentionally omits the detailed segmentation and proprietary financial models that underpin strategic decisions. For procurement teams, product leaders and corporate development groups preparing budgets and bids for 2026, the complete report contains the segment‑level figures, downloadable model files, supplier scorecards and a ranked list of acquisition targets.
To obtain the full report and model pack, visit the PW Consulting Vector Network Analyzer Market page or contact our industry team for a tailored briefing. Our analysts can run a custom workshop to map the implications for your product roadmaps, supply chain hedging and M&A pipeline within a 6–8 week advisory engagement.
— PW Consulting, Advanced Industries Practice
For detailed analysis of this topic, please visit the official page: Vector Network Analyzer (VNA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com