

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Bone Conduction Headphones Market to Reach USD 11,120M by 2032

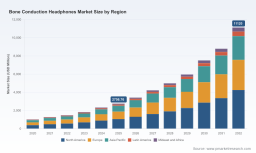
Bone Conduction Headphones Market — Strategic Outlook for 2026 Decision-Making
As bone conduction audio moves from niche novelty to a mainstream product category, corporate leaders face a rapid convergence of technological advances, regulatory normalization, and shifting channel economics. PW Consulting’s latest Bone Conduction Headphones Market study (base year 2025; historical coverage 2020–2025; forecast 2026–2032) synthesizes these forces into an action-oriented intelligence package designed to inform 2026 strategy cycles. The market we modelled reached a multi‑hundred million USD scale in 2025 and — under our central case — is positioned to expand at a compound annual growth rate (CAGR) of 6.98% through 2032, reaching a substantially larger market size by the end of the forecast window. This briefing highlights the report’s strategic value while deliberately withholding granular segmentation so decision-makers must access the full study for playbooks and line-item forecasts.
Bone Conduction Headphones Market
What this research delivers — practical, operational, and strategic
-
Proven market sizing and scenario engine: transparent methodology that reconciles supplier volumes, sell‑through data, and channel checks to produce base, upside, and downside cases for 2026–2032.
Bone Conduction Headphones Market -
Decision-ready go‑to‑market playbooks: specific product, channel, pricing and partnership options for OEMs, brands, and channel partners. Includes launch sequences, promotional mixes, and expected payback timelines under differing unit cost assumptions.
Bone Conduction Headphones Market -
Supply chain and cost anatomy: a component‑level map that identifies cost drivers, strategic single points of failure, and levers to reduce the 25–40% manufacturing cost premium associated with bone conduction designs versus conventional headphones.
-
Regulatory and compliance roadmap: certification requirements, timelines and test houses for key markets (including EU CE/TÜV pathways for active noise reduction and IP68/IP69 waterproofing expectations for sports lines).
-
Competitive intelligence and vendor scorecards: qualitative and quantitative assessments for leading OEMs, contract manufacturers and branded incumbents; benchmark criteria include product durability, IP portfolio, channel strength, and margin structures.
-
Commercial and M&A playbooks: prioritized target lists, valuation heuristics for bolt‑on acquisitions, and integration checklists tailored to the market’s current concentration dynamics.
Why the study matters for 2026 corporate planning
Three practical reasons executives should incorporate this report into their 2026 planning cycle:
-
It converts top‑line growth into actionable bets. The underlying market trajectory — underpinned by steady, mid‑single‑digit CAGR — converts exploratory investment into investment prioritization: which platforms to accelerate, which features to deprioritize, and where to reserve R&D capital.
-
It reveals structural cost asymmetries. Specialized transducers, enclosure tolerances and premium materials (notably titanium bands used in active models) create a durable cost delta versus true wireless earbud designs. The report shows where that delta is absorbed, where it compresses margins, and how design or sourcing choices change unit economics.
-
It aligns compliance with commercialization. Waterproofing benchmarks (IP68/IP69) and EU certification norms (CE marking and third‑party validation such as TÜV for active noise capabilities) move from checklist items to strategic gating factors for cross‑border launches.
Competitive landscape — snapshot and strategic implications
The market is concentrated: our CR3 and CR5 metrics indicate a top‑heavy structure, where a few brands and OEMs account for a meaningful share of revenue and influence on standards, pricing and channel access. That concentration creates both defensive moats and opportunistic entry points for challengers.
-
Shokz — positioned as the flagship premium brand, combining titanium band designs with product extensions (e.g., integrated MP3 storage and communications‑oriented models). Recent product recognition at CES 2026 validates a brand premium strategy and sets engineering bar for open‑ear ergonomics.
-
H2O Audio — niche leader in waterproof, multi‑sport devices. Certifications such as IP68 and integration of on‑device storage illustrate a feature stack designed for dedicated sports adopters.
-
Nank and analogous players — focus on swim‑optimized and outdoor sport models, competing on IP rating, fit and durability.
-
Suunto — the sports‑training playbook: long battery life and integration with performance ecosystems (trainers, app platforms) make it a model for co‑branded product strategies with wearables incumbents.
-
Raycon — orienting to everyday consumers with an open‑ear form factor and waterproof rating, competing via price and mainstream distribution.
-
Contract manufacturers / OEMs (several China‑based firms) — serve as critical scale partners for private‑label and cost‑sensitive brands. Their role is central to time‑to‑market and margin optimisation, particularly for new entrants seeking rapid SKU proliferation.
Strategically, incumbents with strong brand equity and proprietary hardware (e.g., resilient titanium frames, tuned transducers) can protect price, while nimble OEMs and distribution‑focused challengers pressure average selling prices through rapid SKU iteration and lower channel costs.
Market dynamics, constraints and tipping points
-
Component and labor cost pressure: the specialized nature of bone conduction transducers and assembly raises manufacturing costs relative to conventional headphones. Companies must weigh near‑term margin pressure against long‑term price elasticity as adoption broadens.
-
Raw material and design trade‑offs: premium models that leverage titanium bands (typical active models use bands in a narrow weight band) achieve superior durability and perceived value but increase material cost and constrain design flexibility.
-
Regulatory and standards evolution: waterproof and active noise reduction features are increasingly subject to standardized verification. CE marking and recognized third‑party testing bodies are becoming de facto entry tickets for major e‑commerce and retail channels.
-
Distribution and channel dynamics: sports specialty retail, direct‑to‑consumer, and hearing‑aid channels each demand differentiated product specifications, return policies and marketing approaches—fragmentation that benefits players with adaptable supply chains.
-
Substitution and cannibalization risk: as true wireless buds continue to improve safety and situational awareness features, bone conduction players must continually justify the use case premium in safety‑conscious or hearing‑impaired segments.
Recommended 2026 moves — prioritized and pragmatic
-
Adopt a two‑track product portfolio: a cost‑engineered family for broad consumer channels and a premium, titanium‑based line that defends margins and supports partner co‑branding with sports and professional segments.
-
Invest in certification early: secure CE/TÜV and IP6x test results before large scale launch windows to avoid market delays and retailer refusals.
-
Rationalize supplier base with conditional dual sourcing: lock long‑lead, specialized transducer capacity while qualifying lower‑cost assembly partners for commoditized components.
-
Pursue tactical M&A where CR3 concentration creates scale advantages — look for targets that fill capability gaps (e.g., digital audio processing, clinical hearing device interfaces, or swim‑certified enclosures).
-
Design channel pilots that quantify lifetime value by use case: sports subscription bundles, hearing‑aid integration programs and defense/military procurement pilots have materially different acquisition economics.
What we keep proprietary — why you’ll want the full report
To preserve the strategic advantage for subscribing clients, certain high‑value content is intentionally summarized in this preview. The full report contains:
-
Detailed country and application revenue splits and forecast decks for 2026–2032;
-
SKU‑level average selling price and volume assumptions, by vendor and channel;
-
Vendor scorecards with manufacturing lead times, warranty claims, and quality failure rates;
-
Excel scenario models you can plug into your planning systems to stress test capex and go‑to‑market scenarios;
-
Proprietary supplier risk map and tactical sourcing checklists to mitigate component and labor cost disruption.
Conclusion — timing and next steps for 2026
Bone conduction headphones are no longer a curiosity: they are a category with meaningful scale, evolving regulatory norms, and a concentrated competitive structure that rewards both brand differentiation and supply chain savvy. For 2026 strategy cycles, actionable intelligence—ranging from certification timelines to supplier scorecards and SKU economics—will determine whether an organisation captures premium share or competes in a margin squeeze.
PW Consulting stands ready to support executive teams with tailored workshops, acquisition target canvases, and rapid due‑diligence packages derived from the full study. For access to the complete dataset, VBA‑ready models, and vendor playbooks, please visit the report page or contact our research services desk to arrange a briefing and licensing options.
For detailed analysis of this topic, please visit the official page: Bone Conduction Headphones Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com