

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Neutron Generators Market to Reach $58.45M in 2025

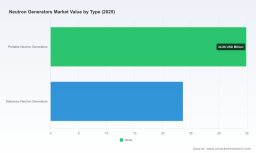
Neutron Generators Market: Strategic Outlook for 2026 Decision‑Making
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a concise, decision‑focused introduction to our new Neutron Generators Market study. This briefing highlights the strategic value of the research for corporate leaders, investors, procurement teams, and policy planners as they set priorities for 2026. It demonstrates the analytical depth of the full report while deliberately omitting the detailed segment tables and region/application breakouts that are reserved for subscribers and licensed users.
Neutron Generators Market
Market at a glance — what the macro numbers tell us
Between 2020 and 2025 the global neutron generators market expanded steadily, moving from USD 45.23 Million (2020) to USD 58.45 Million (2025). Our forecast covers 2026–2032 and projects continued expansion to USD 93.45 Million by 2032, driven by a compound annual growth rate (CAGR) of 6.95% across the period. Those headline figures encapsulate multiple, overlapping demand streams — from industrial nondestructive testing and resource exploration to emerging medical and security applications — each affected by technology, regulation, and procurement rhythms.
Neutron Generators Market
Why this study matters for 2026 decisions
- Timing capital and procurement cycles correctly. The market trajectory implies a window in which early movers that align product roadmaps with regulatory readiness, export controls, and customer validation can capture disproportionate value. The report prioritizes scenarios where spending accelerates and where it plateaus, enabling CFOs to align capex schedules with realistic revenue capture.
- Understanding technology inflection points. Compact high‑yield D‑D generators and extended‑life D‑T architectures are shifting value toward new OEMs and technology integrators. Our analysis identifies where performance improvements (flux, lifetime, portability) change use cases and where incumbents face obsolescence risk.
- Navigating complex compliance and export constraints. Regulatory dynamics materially affect addressable markets. Our research synthesizes NRC/Agreement State licensing implications, EAR export licensing requirements, dual‑use controls under multilateral regimes, and medical device approval pathways — all essentials for 2026 export and go‑to‑market planning.
- Translating fragmentation into M&A and partnership opportunities. The market concentration metrics point to a fragmented competitive set with room for consolidation and strategic alliances. For corporate development teams, the report provides a structured framework for value‑capture through tuck‑ins, technology licensing, and distribution partnerships.
Key strategic implications by stakeholder
- Buyers (Oil & Gas, Aerospace, Research Institutions, Hospitals, Security Agencies)
Procurement teams should treat neutron generator purchases as integrated procurements — equipment, licensing, installation, maintenance, and regulatory compliance form a single project. Our report provides a procurement checklist and decision tree that maps performance requirements to licensing pathways and total cost of ownership (TCO) profiles over typical lifecycles.
Neutron Generators Market - Suppliers and OEMs
Product roadmaps must prioritize not only yield and lifetime but also serviceability and regulatory provenance. Investments in modular designs, evidence packages for CE/medical approvals, and validated export control compliance will determine which suppliers can scale across jurisdictions in 2026.
- Investors and PE
Private investors should underwrite technology risk separately from regulatory risk. Our model produces alternate valuations under different licensing and export scenarios, helping investment committees price the impact of denied or delayed exports and extended medical certification timelines.
Technology and market dynamics to watch in 2026
- High‑intensity, compact D‑D systems: Recent technical advances show that compact D‑D sources can achieve imaging‑grade yields with high uptime. This reduces operational constraints for laboratories and mobile inspection fleets and changes total cost equations when tritium licensing is avoidable.
- Extended‑life neutron tubes: Patented long‑life designs with multi‑thousand‑hour operational windows change service and replacement cycles, favoring platforms that can demonstrate predictable lifetime economics.
- Medical adoption hurdles and opportunities: Hospital‑grade BNCT and other therapeutic applications present high revenue upside but require compliance with Class III medical device frameworks, extensive clinical evidence, and long reimbursement cycles — critical inputs for any commercialization plan.
- Export and classification regimes: Dual‑use status under multilateral arrangements and national export controls create gating factors for addressable market geography. Supply chain design and customer selection must reflect validated licensing strategies.
Competitive landscape — who matters and why
The market is characterized by an interplay of specialist producers, large instrument houses, and fast‑moving technology startups. The three‑ and five‑firm concentration levels indicate a moderately fragmented industry where niche differentiation and IP matter:
- Adelphi Technology, Inc. (Redwood City, CA) — Known for a product range covering D‑T, D‑D and moderated D‑D neutron sources, Adelphi is positioned across industrial analysis, radiography, NDT and security segments. Its engineering focus makes it a key supplier for integrated field systems.
- Sodern (Bois‑Guillaume, France) — With strengths in electric neutron sources and activation analyzers, Sodern is a specialist in oil‑logging, waste characterization and cross‑belt analysis for heavy industries. Its civil tube expertise makes it a preferred partner for continuous process analytics.
- Phoenix (Germany) — Focused on high‑intensity neutron sources for imaging and NDT, Phoenix serves aerospace and defense quality assurance needs where imaging resolution and throughput are critical procurement criteria.
- NSD Fusion / Gradel (Germany) — Holds patents on long‑life generators with high specific power and stable output profiles. These attributes translate into lower life‑cycle costs for customers requiring routine, high‑uptime operations.
- Thermo Fisher Scientific (Colorado Springs, CO) — A major instrument house delivering compact portable generators for elemental analysis and field/laboratory use. Thermo Fisher’s distribution reach and catalog updates position it as a bridge between research markets and commercial deployments.
Recent vendor and research developments reinforce the above dynamics: product catalog updates and new laboratory models have appeared from established instrument manufacturers; academic and national labs continue to place procurement orders for 14 MeV systems; and independent R&D efforts report compact, high‑uptake D‑D breakthroughs. These events collectively accelerate adoption in applications where footprint and uptime are decisive.
Regulatory and policy "noise" that changes outcomes
- U.S. regulatory practice treats electronic neutron generators as radiation‑producing machines under Agreement State regimes, which affects licensing timelines and operational compliance in domestic projects.
- D‑T systems containing tritium above set activity thresholds require specific possession licenses, making alternatives attractive where regulatory burden is a strategic consideration.
- High‑performance systems are often subject to EAR controls and may need validated export licenses for certain destinations; dual‑use classification under multilateral arrangements adds another layer of export risk.
- Hospital‑grade BNCT and similar medical systems face Class III medical device approvals in the U.S., CE marking and equivalent processes elsewhere — a multi‑year pathway with significant clinical evidence requirements.
What PW Consulting’s full report provides (practical deliverables)
- Historical market sizing (2020–2025) and a detailed 2026–2032 forecast model with scenario analysis tied to regulatory and technology outcomes.
- Vendor benchmarking and detailed company profiles with SWOT for leading and fast‑emerging players, including engineering capabilities and service models.
- Commercial due diligence tools — TCO calculators, licensing‑sensitive addressable market models, contract risk checklists, and export control playbooks.
- Go‑to‑market and M&A playbooks — recommended partnership archetypes, valuation sensitivity tests, and integration considerations for cross‑border deals.
- Actionable procurement templates — bid evaluation matrices, installation and commissioning roadmaps, and lifecycle maintenance schedules.
Note: in line with our “trailer” approach, the public summary intentionally omits the granular regional, type and application split tables and the full numeric segment sheets. Those segment‑level datapoints and executable slide decks are available through the report access page and are essential for transaction‑level decision making.
How to use this research to inform 2026 plans
- Align budget cycles with the forecasted growth windows and the licensing cadence in your jurisdictions; avoid committing to procurement before export approvals can be obtained for cross‑border deployments.
- Prioritize partnerships with vendors that can document lifecycle performance and regulatory compliance; long‑life tube patents and proven field uptime materially reduce operational risk.
- For investors, segregate technology value from regulatory exposure in valuation models; price in probability‑weighted scenarios for export denials and prolonged medical approvals.
- For R&D leaders, target performance metrics that unlock new use cases — e.g., reductions in tritium dependence, increases in uptime, and modular designs that simplify maintenance and compliance.
For executives preparing strategic plans, procurement directors drafting RFPs, or investors conducting due diligence in 2026, our study provides the frameworks and validated scenario models needed to make defensible decisions. To access the detailed segmentation, vendor scorecards, and the licensing impact matrices that support executable plans, consult the full PW Consulting Neutron Generators Market report.
Contact PW Consulting to request the complete report and the accompanying decision toolkits. The full deliverable contains the proprietary segment tables and model workbooks that underpin the strategic recommendations summarized here.
For detailed analysis of this topic, please visit the official page: Neutron Generators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com