

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Sodium Permanganate Market to Grow at 4.6% CAGR Through 2032
By pmarketresearch, 2026-07-09
Sodium Permanganate Market — Strategic Outlook for 2026 Decision-Makers
As PW Consulting’s lead industry analyst, I present a focused, decision-grade briefing on the sodium permanganate market that frames the strategic choices organizations will face in 2026. This market is no longer a niche chemical business insulated from broader industrial trends — it sits at the intersection of water infrastructure, semiconductor and electronics manufacturing, and evolving battery- and critical-materials policy. The briefing that follows synthesizes our market sizing, competitive mapping, supply-chain stress testing, and scenario-driven recommendations. It is designed to signal the levers that matter to procurement, commercial strategy, operations, and M&A teams while deliberately withholding full segment-level detail to encourage access to the full PW Consulting report.
Sodium Permanganate Market
Market snapshot: scale, trajectory, and concentration
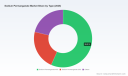
Using 2025 as the base year, our topline market model values global sodium permanganate demand at approximately USD 357.7 Million (USD Million). The market is projected to expand to roughly USD 379.9 Million in 2026 and to approach USD 488.0 Million by 2032, implying a compound annual growth rate (CAGR) of 4.6% over the 2026–2032 forecast horizon. These figures reflect a steady expansion driven by sustained municipal water-treatment procurement, growth in specialty industrial applications, and incremental gains in electronics and high-purity use cases.
Sodium Permanganate Market
Market structure matters: the industry shows a high degree of concentration (CR3 ≈ 70%; CR5 ≈ 75%), which shapes competitive dynamics, pricing behavior, and the speed at which supply shocks are transmitted to end markets. For corporate decision-makers, this concentration implies that a relatively small set of incumbent suppliers will continue to set commercial norms — but it also creates pockets of opportunity for differentiated entrants and vertically integrated players.
Sodium Permanganate Market
Why 2026 is a pivotal year for strategic choices
- Procurement inflection: Recent upstream volatility has shortened suppliers’ planning cycles and increased the value of contract certainty. Buyers who act early to secure flexible, indexed contracts will reduce margin exposure.
- Regulatory realignments: New critical-materials rules and public investment programs are shifting the economics of manganese sourcing and downstream processing, creating both compliance burdens and investment incentives.
- Demand mix evolution: While water treatment remains the backbone of demand, higher-value segments — notably electronics and research-grade supplies — are growing faster and require different quality, packaging, and service models.
Key market dynamics shaping 2026 decisions
- Raw material tightness and cost pass-through: Price volatility at the manganese sulfate and ore level has become a persistent theme. Q1 2026 data showed a notable quarter-over-quarter uptick in manganese sulfate pricing linked to rising sulphuric acid costs. That spike, combined with legacy supply disruptions (for example, mine suspensions following severe weather events in 2024), has amplified input-cost transmission into finished sodium permanganate prices.
- Policy and strategic-materials pressure: The European Union’s Critical Raw Materials Act (effective May 2024) explicitly flagged high-purity manganese as strategic, creating compliance and sourcing implications for anyone competing in EU markets. At the same time, U.S. Department of Energy and Department of Defense grant programs supporting domestic battery-grade manganese production are altering the competitive landscape for manganese feedstocks, potentially diverting material and investment into the battery supply chain.
- Public procurement as a demand anchor: Municipal tendering remains a stable and predictable revenue channel for certified suppliers. Recent public awards — exemplified by a municipal contract award in March 2025 — underscore the premium placed on certifications (e.g., NSF, AWWA), logistics reliability, and compliance documentation.
Supply chain and margin levers
Our scenario analysis highlights three levers that determine supplier and buyer outcomes through 2026:
- Sourcing strategy: Vertical integration into manganese sulfate conversion or long-term offtake agreements can buffer margin swings but require capital and lead time.
- Product differentiation: Certification, purity grading, and service (e.g., just-in-time deliveries, on-site dosing solutions) create defensible pricing tiers, especially for municipal and electronics customers.
- Contract design: Indexed pricing with caps/floors and blended-term structures reduces the probability of one-sided shocks while preserving supplier economics.
Competitive landscape — strategic positioning and implications
The market is populated by incumbent suppliers that follow distinct routes to competitive advantage. Below is a synthesis of the strategic posture of core industry players covered in our research.
- Carus Corporation (Peru, Illinois) — A major U.S. producer with a strong focus on water-treatment liquid grades and recognized certifications. Carus’s strengths lie in scale, certification credentials, and a deep municipal-sales footprint. Strategy implication: Carus is well positioned to defend municipal share and expand into adjacent treatment services; competitors should consider niche specialization or superior service models to counteract its scale.
- Hawkins, Inc. (Roseville, Minnesota) — A domestic manufacturer, blender, and distributor focused on municipal and government contracts through B2B channels. Hawkins’s distribution-centric model emphasizes localized supply and contract flexibility, a differentiator in municipal procurement cycles.
- Valudor Products, LLC (Encinitas, California) — A supplier of certified 40% solution grades with complete safety and compliance documentation. Valudor’s emphasis on certified formulations and documentation makes it a natural supplier to regulated water-treatment buyers and specialty industrial users.
- American Elements (Los Angeles, California) — Provider of very high-purity sodium permanganate grades targeting research, electronics, and high-end industrial customers. Their product focus allows premium pricing but requires tight quality controls and traceability.
- Rock Chemicals, Inc. — A bulk supplier that differentiates on reliable sourcing, compliance documentation, and logistics. Rock is attractive to buyers seeking scale purchasing and straightforward compliance support.
Collectively, these players illustrate three viable strategic archetypes: scale/certification (large incumbents), distribution-led reliability (regional blenders/distributors), and quality-differentiation (high-purity specialists). Our competitive scorecards in the full report benchmark each against CAPEX plans, certification breadth, and logistics resilience.
Strategic playbook for 2026
Below are actionable recommendations tailored to different organizational roles — buyers, producers, and investors — grounded in our market modeling and stress tests.
- For buyers and municipal procurement teams: Revisit sourcing cadence and contract design. Prioritize suppliers with dual strengths in certification and logistics. Build 12–18 month buffer inventories for critical projects and negotiate indexed, two-way price adjustment mechanisms tied to transparent input-cost proxies.
- For producers and distributors: Accelerate investments that raise barriers to entry — NSF/AWWA certifications, high-purity production lines for electronics, and traceable sourcing agreements. Consider selective vertical integration into manganese sulfate processing or structured partnerships with miners to manage feedstock risk.
- For investors and corporate development: Look for bolt-on opportunities that add either certification capabilities or localized logistics footprints. The concentrated supplier base presents M&A potential, but diligence must stress test feedstock exposure and regulatory compliance readiness, particularly for EU market access.
What PW Consulting’s full report provides (practical deliverables)
- Granular market model (2020–2032) with base-year 2025 calibration, scenario runs, and sensitivity matrices.
- Segmented demand analysis by region, grade, and application with adoption curves and forecasted unit consumption patterns (note: detailed segment tables are only available in the full report).
- Supplier scorecards covering certification breadth, capacity, contract history, and logistical strengths, plus a CR3/CR5 concentration assessment.
- Raw-material flow maps, stress-test results (including the impacts of manganese sulfate price shocks), and mitigation playbooks for buyers and sellers.
- Contract templates, procurement negotiation checklists, and a shortlist of strategic M&A targets aligned to three archetypal buyer/investor strategies.
Closing—why this matters for your 2026 agenda
Decisions made in 2026 around contracting, capacity investments, and certification will determine who captures the upside of the projected 4.6% CAGR through 2032 and who remains exposed to raw-material and regulatory dislocations. The concentrated nature of the market rewards strategic clarity: incumbents can protect margins through certification and logistics; new entrants must pursue either niche quality premiums or stronger supply-chain control to scale.
For executives preparing 2026 plans, the most valuable near-term actions are pragmatic: secure flexible supply terms, prioritize certifications demanded by large public buyers, and align capex to segments showing above-average growth in our forecasts. PW Consulting’s full Sodium Permanganate Market report operationalizes these priorities with the models, templates, and supplier analytics needed to convert insight into measurable outcomes.
To access the full dataset, including segment-level shares, price forecasts, and supplier scorecards, please refer to the complete PW Consulting report. The executive-level summary above is intentionally high-level — it surfaces the structural risks and strategic levers without disclosing the proprietary segment splits and microdata that underpin our proprietary conclusions.
For detailed analysis of this topic, please visit the official page: Sodium Permanganate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Silicon Monoxide Market Set for 15.1% CAGR Through 2032
By pmarketresearch, 2026-07-09
Silicon Monoxide Market: Strategic Imperatives for 2026 Decision-Makers
Executive summary
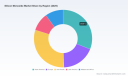
The silicon monoxide market is entering a phase of accelerated expansion that will materially affect sourcing, product development, and competitive positioning in 2026 and beyond. Our PW Consulting analysis (base year: 2025; historical window: 2020–2025; forecast horizon: 2026–2032) models a compound annual growth rate (CAGR) of 15.1% across the forecast period, with total market size rising markedly from the mid‑2020s into the early 2030s. This growth trajectory creates both structural risks and multi‑layered strategic opportunities for materials producers, battery and electronics OEMs, and downstream integrators. Below we synthesize the high‑level implications you need to weigh as you set budgets, partnerships, and R&D priorities for 2026 — preserving the granular segment data for subscribers to the full report.
Silicon Monoxide Market
Why 2026 is a strategic inflection point
-
Momentum and scale: The market more than doubled in scale through the 2020–2025 period and our modelling anticipates sustained expansion through 2032. That acceleration is not linear; it reflects a confluence of technology adoption cycles (notably in energy storage and advanced coatings), upstream material constraints, and expanding industrial applications.
Silicon Monoxide Market -
Supply‑chain leverage: Silicon monoxide production requires high‑purity silicon feedstock and consistently controlled high‑temperature processes. This makes feedstock sourcing, process reliability, and quality assurance top strategic levers for any firm seeking to move beyond niche supply into volume supply chains.
Silicon Monoxide Market -
Regulatory and trade dynamics: The compound is classified under HTSUS 2811.29.5000 with general duty‑free treatment in some jurisdictions, which reduces tariff friction but increases the emphasis on non‑tariff barriers (quality certification, transport logistics, export controls for battery materials). Recent trade records also show concentrated export activity by a limited number of exporters across measured shipment windows, signaling the need for careful partner due diligence.
Market structure and competitive logic (high‑level)
The silicon monoxide market remains relatively fragmented. The top three and top five suppliers collectively represent a minority share of global volume, which indicates low incumbent concentration and room for both consolidation and vertical integration. That structural profile shapes the competitive playbook in three ways:
-
Scale matters for battery supply chains. Battery manufacturers increasingly prefer bundled, qualified suppliers who can commit to multiyear specifications, traceability, and logistics. Suppliers that can scale while maintaining high‑purity feedstock controls become strategic partners rather than commodity vendors.
-
Specialization preserves margins. Vendors focused on vacuum deposition sources, research‑grade materials, or niche coating applications can sustain attractive margins by targeting stringent specifications and short, high‑value customer lists.
-
M&A and JV activity will be selective and strategic. Expect partnerships that address feedstock security, process scale‑up (kiln and reduction capacity), and regional customer access rather than broad horizontal rollups.
Competitive landscape: who matters and why
Several types of suppliers are shaping the market today. Below is an analytical snapshot of representative firms and the strategic roles they play — presented to clarify competitive intent rather than disclose sensitive market shares.
-
High‑purity specialty producers (example profile: Osaka Titanium Technologies) — Firms with high‑control production targeting barrier films and emerging battery anodes. Their strengths are quality credentials, long OEM qualification cycles, and incremental product innovation aimed at food packaging and electrochemical applications. For corporates, these players are potential partners for co‑development deals where technical risk is high and qualification lead times are long.
-
Evaporation and deposition material specialists (example profile: RD Mathis) — Suppliers focused on vacuum technology feed materials and deposition sources. Their strategic value lies in catering to high‑margin electronics and R&D markets, where product form (pellets, pieces, targets) and process integration are critical. OEMs in optics, thin films, and specialty electronics should prioritize these suppliers for iterative prototyping and pilot production windows.
-
Catalogue and research suppliers (example profiles: American Elements, Stanford Advanced Materials) — Broad‑range suppliers that serve academic labs and small industrial customers. They act as innovation accelerants by making materials available for early‑stage testing; however, transitioning from catalogue supply to qualified, high‑volume procurement often requires different contractual and QC structures.
-
Volume and cost‑competitive producers (example profiles: Unilong, Hebei Yanxi, Hefei TNJ) — These manufacturers supply powder and pieces for coatings and industrial chemistries. Their competitive advantage is scale and cost control. For buyers prioritizing TCO (total cost of ownership), these firms represent attractive partners, provided due diligence validates supply consistency and environmental controls.
Operational and commercial levers for 2026
Decision‑makers should be prioritizing a mix of tactical moves and strategic bets in 2026. The following levers are pragmatic and time‑sensitive given the market’s projected trajectory.
-
Secure feedstock and dual sourcing: Given the importance of high‑purity silicon inputs and the capital intensity of downstream upgrading, companies should execute feedstock contracts with escalation mechanisms and maintain at least two qualified suppliers to mitigate disruption risk during scale‑up.
-
Invest in qualification pathways: Battery and electronics OEMs should accelerate on‑ramp programs (pilot batches, accelerated aging, and cross‑qualification) with target suppliers now. Qualification cycles for anode materials and deposition sources can exceed typical component qualification timelines, so starting in 2026 preserves product launch windows in the 2027–2029 timeframe.
-
Design partnerships over transactions: For firms lacking internal scale, consider manufacturing partnerships, tolling arrangements, or minority JV stakes with specialists that bring process expertise and certification systems. These structures can secure capacity without the full capital burden of greenfield expansion.
-
Embed regulatory intelligence into sourcing: While tariff exposure is limited in some markets, non‑tariff requirements and traceability expectations (particularly for battery value chains) will become binding. Incorporate regulatory audit clauses and export compliance checks into procurement processes.
Report scope: what PW Consulting delivers
Our full Silicon Monoxide Market report provides the actionable detail operational teams need to act in 2026, including:
- Reconciled market sizing (2020–2025 historicals; 2026–2032 forecasts) built from bottom‑up shipments, vendor disclosures, and proprietary demand modeling.
- Demand‑driver mapping across end‑use categories with sensitivity scenarios that reflect technology adoption and policy shifts.
- Supply chain topology, capacity maps, and critical input risk scores (feedstock availability, energy intensity, capital intensity).
- Price dynamics and margin waterfall analysis for common product forms and process routes.
- Competitive benchmarking and supplier scorecards (technical capability, scale, certification, geographic reach).
- Deal rationales for M&A and JV activity, including valuation frameworks for strategic acquirers.
- Go‑to‑market playbooks and procurement templates for OEMs and materials buyers.
What the data signals for strategic planning
Three data‑driven signals should inform 2026 resource allocation decisions:
-
Scale and speed matter: the projected multi‑year expansion implies early movers will capture the best contracts and technology relationships. Delays in qualification or feedstock commitments will compound cost and timing penalties.
-
Quality control is a gatekeeper: high‑purity requirements and process variability mean that technical verification and supplier audits are not optional overhead — they are essential competitive safeguards.
-
Market architecture favors both specialists and integrators: opportunities exist for companies that either deepen technical differentiation (high‑value, low‑volume) or execute disciplined scale strategies (volume, cost, and logistics).
Final recommendation and next steps
If your 2026 plan includes new product launches, expanded battery relationships, or supply‑chain resilience initiatives, begin with three concurrent tracks this quarter: (1) a supplier due‑diligence sprint focused on feedstock security and quality systems; (2) an accelerated qualification program with prioritized OEMs and pilot partners; and (3) a scenario planning exercise that maps capital needs for either tolling agreements or greenfield capacity. PW Consulting’s full report contains the granular segmentation, regional and application breakdowns, and vendor scorecards necessary to execute these tracks with confidence.
To access the detailed segment datapacks, vendor scorecards, and scenario models that underpin these recommendations, please consult the full Silicon Monoxide Market report on our site or contact your PW Consulting advisor. The high‑growth window opening in 2026 rewards early, informed action; equip your team now with the data and supplier insights to convert market expansion into defensible commercial outcomes.
For detailed analysis of this topic, please visit the official page: Silicon Monoxide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Steering Wheel Switch Market to grow at 7.25% CAGR to 2032
By pmarketresearch, 2026-07-09
Automotive Steering Wheel Switch Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
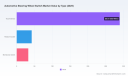
By 2025 the global Automotive Steering Wheel Switch market has evolved from a functional accessory into a strategic touchpoint for vehicle HMI, safety integration, and software-defined differentiation. PW Consulting’s latest industry study — built on a 2020–2025 historical base and projecting through 2032 — shows a clear, sustained growth trajectory underpinned by electrification, steer‑by‑wire readiness, and software-enabled human‑machine interfaces. The market expands at a compound annual growth rate (CAGR) of 7.25%, rising from the early‑decade base to a materially larger addressable market by the end of our forecast horizon.
Automotive Steering Wheel Switch Market
This preview highlights the report’s strategic value for 2026 corporate planning: we show why steering wheel controls are no longer mere hardware, outline the competitive and regulatory inflection points to watch, and describe the actionable content you will find in the full study. Critical granular splits and segment tables are intentionally withheld here to encourage direct access to the primary report for procurement‑grade data and model outputs.
Automotive Steering Wheel Switch Market
Why this market matters for 2026 strategies
- Control surfaces as experience platforms: Steering wheel switches increasingly serve as primary HMI elements for infotainment, driver assistance, biometric signaling, and tactile fail‑safe controls as vehicles become more software‑centric.
- Technology convergence: Capacitive touch, haptic feedback, grip sensing, and embedded vibration actuators are converging with software overlays (voice, gesture, AI) to create hybrid interaction models. OEMs that integrate these layers coherently convert hardware spend into perceived quality and safety differentiation.
- Regulatory and safety inflection: New steer‑by‑wire deployments and evolving ISO standards around driver input systems mean hardware partners must demonstrate both functional safety and system‑level traceability. 2026 procurement cycles must therefore prioritize suppliers with end‑to‑end compliance and systems integration capabilities.
- Economic vote of confidence: From a macro perspective, the market scaled steadily through 2020–2025 and, based on our forecasts, continues to accelerate through 2032. The growth trajectory and projected mid‑cycle market size support investment into modular platforms and software upgradeability.
Market trajectory — headline metrics
PW Consulting uses 2025 as the base year for our model. The market has climbed notably since 2020 and, under a 7.25% CAGR, reaches a significantly higher level by the end of the forecast period. These headline numbers frame capital allocation decisions: they demonstrate a durable addressable market that justifies medium‑term R&D programs, platform investments, and strategic partnerships.
Automotive Steering Wheel Switch Market
Drivers, risks and scenario levers
- Demand drivers: Transition to EVs, proliferation of advanced driver assistance systems (ADAS), and the push toward software‑defined vehicle architectures are the principal demand drivers. OEMs are rethinking switch ergonomics and functionality to enhance occupant experience and enable over‑the‑air feature rollouts.
- Supply‑side pressure: Integration of electronics and sensors into switch assemblies has raised material and labor intensity in recent model cycles, putting pressure on margins for lower‑tier suppliers and reshaping supplier selection criteria toward higher technical competence.
- Regulatory risk: Steer‑by‑wire and autonomous operation introduce amplified safety and testing requirements. Suppliers failing to embed functional safety engineering and compliance traceability into their product development lifecycle will face longer time‑to‑market and constrained qualification pathways.
- Market consolidation & M&A: The study documents accelerating consolidation activity among HMI and switch suppliers as players acquire capabilities for modular, customizable control platforms and software integration. This dynamic will alter competitive maps and bargaining power over the next 12–36 months.
Competitive landscape: strategic profiles and positioning
The competitive field is mixed: established component specialists, steering system integrators, and traditional tier‑1s are all expanding their offerings. The report analyzes capability clusters — tactile mechanical expertise, capacitive/haptic competency, systems integration for steer‑by‑wire, and software/UX provisioning — and maps principal players against these clusters.
- Preh GmbH (Bad Neustadt, Germany): Multi‑decade supplier of multifunction steering wheel controls. Strengths include configurable, brand‑specific switch suites and deep OEM customization experience. Preh’s portfolio is attractive to OEMs wanting bespoke ergonomics coupled with high mechanical reliability.
- Marquardt GmbH (Rietheim‑Weilheim, Germany): Noted for precise, high‑quality switches with strong haptic design. Marquardt’s value lies in tactile engineering and the ability to marry mechanical cues with electronic sensing for safe, intuitive user experiences.
- ZF Friedrichshafen AG (Friedrichshafen, Germany): Integration leader with system‑level offerings, including capacitive HMI and steer‑by‑wire compatible controls. ZF’s scale and systems expertise make it a preferred partner for programs requiring integration of steering systems and electronic controls into a unified architecture.
- Autoliv Inc. (Stockholm, Sweden): Safety‑centric supplier combining steering assemblies with functional switches and vibration modules. Autoliv’s recent foldable steering wheel reveal highlights its push into novel form factors for autonomous vehicle applications, reinforcing the trend toward safety‑aware HMI innovation.
- Toyoda Gosei Co., Ltd. (Nagoya, Japan): Strong in integrated steering systems, including grip sensing and vibration units designed for ADAS compatibility. Their steer‑by‑wire compatible developments demonstrate early readiness for future vehicle platforms seeking digital control surfaces.
- DENSO Corporation (Kariya, Japan): Focused on ergonomic switch modules linked to infotainment and driver assistance. DENSO’s strengths are in systems engineering and cross‑domain integration with vehicle electronics.
Collectively, the major players demonstrate differentiated plays: mechanical/haptic leadership, systems integrators pushing steer‑by‑wire, and safety specialists exploring new form factors for autonomy. Market concentration remains moderate — enough to allow niche specialists to thrive while enabling scale benefits for integrators.
Recent industry movements to watch
- Autoliv’s 2026 foldable steering wheel product reveal underscores the push toward new form factors and the need for resilient, safety‑critical switch designs in autonomous modes.
- Continental’s modular control interface platform (2025) signals OEM demand for configurable, cross‑model button ecosystems that reduce per‑variant engineering costs.
- Toyoda Gosei’s steer‑by‑wire compatible steering system announcement (2025) highlights supply‑chain readiness for next‑generation vehicle controls.
- ZF’s move to series production for steer‑by‑wire systems reflects regulatory and technical maturity across vehicle segments, increasing the strategic importance of compatible switch architectures.
- Industry reports show intensified M&A activity among HMI suppliers and upward pressure on material and labor costs for electronic‑integrated switch assemblies — both factors that will shape 2026 supplier selection and pricing negotiations.
What the PW Consulting report delivers — practical, decision‑grade assets
Our full study is built for direct use in procurement, product strategy, and corporate development workflows. The actionable components include:
- Robust market model (2020–2032) with sensitivity testing, scenario outputs and distributional assumptions to support CAPEX and portfolio prioritization.
- Demand‑driver matrices linking EV penetration, ADAS feature mix, and software‑defined vehicle architectures to switch functionality requirements.
- Supplier heatmaps that score vendors across technical capabilities, safety credentials, integration experience, cost competitiveness, and scalability.
- Go‑to‑market playbooks for OEMs and Tier‑1s that cover product modularization, licensing vs. buy decisions for software stacks, and supplier governance models to accelerate qualification.
- M&A scouting dossiers and valuation yardsticks for capability targets (e.g., capacitive/haptic IP, steer‑by‑wire integration, biometric sensing), plus integration‑risk checklists.
- Regulatory roadmap and compliance checklist tailored to steer‑by‑wire and autonomous readiness, including recommended test regimes and documentation templates.
- Commercial negotiation templates and cost‑down levers informed by componentization and materials trends observed through 2025.
How to use this study in 2026 planning cycles
- Portfolio prioritization: Use the market model to stress‑test investment cases under differentiated EV/ADAS adoption scenarios. Allocate R&D budgets to platform architectures that offer the fastest path to OTA feature deployment.
- Supplier strategy: Segment suppliers into partnership tiers (core, strategic, tactical) using our heatmaps and align qualification timelines with program milestones. Prioritize partners who deliver both hardware reliability and software upgradeability.
- M&A and alliance playbook: Identify capability gaps that are best filled by acquisition versus joint development. Our scouting dossiers narrow the universe to targets with defensible IP and rapid integration potential.
- Risk mitigation: Adopt our regulatory checklist early in 2026 programs to avoid qualification delays, particularly for steer‑by‑wire and autonomous applications where safety validation cycles can be lengthy.
Concluding perspective and next steps
Steering wheel switches are transitioning from commoditized inputs to strategic interfaces that shape safety, UX, and software monetization. The market’s growth profile through 2032 and the technology and regulatory inflection points described here make 2026 a pivotal planning year: companies that align product architecture, supplier ecosystems, and compliance tracks now will capture disproportionate value as vehicles become more software‑defined and interaction‑centric.
For procurement teams, product leaders, and corporate development executives preparing budgets and partnership strategies in 2026, PW Consulting’s full Automotive Steering Wheel Switch Market study provides the granular segmentations, supplier scores, and financial models necessary to operationalize these insights. This article is a strategic preview; the complete report contains the detailed data tables, scenario models, and supplier scorecards that inform concrete decisions. Contact PW Consulting or visit our report page to access the full analysis and the downloadable decision toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
EPDM Market 2026: Strategic Briefing for Decision-Makers
As EPDM moves from a mature commodity to a strategic material in automotive, construction and industrial applications, 2026 will be a pivotal year for corporate choices around capacity, sourcing and product positioning. This preview of PW Consulting’s latest Ethylene Propylene Diene Monomer (EPDM) Market study synthesizes the high‑level, decision-relevant signals you need now — while intentionally withholding the granular segment tables and proprietary allocations contained in the full report to preserve the strategic value of our primary research.
Ethylene Propylene Diene Monomer (EPDM) Market
Market snapshot: scale, trend and near-term trajectory
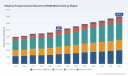
By PW Consulting’s accounting (base year 2025), the global EPDM market reached approximately USD 5,000 Million, up from roughly USD 4,000 Million in 2020. Under a baseline outlook we model a steady compound annual growth rate of about 5.0% across 2026–2032, with total market value rising toward the low‑seven‑billion USD range by 2032. The market’s mid-single-digit CAGR masks material variation in end‑use demand, feedstock sensitivity and regulatory exposure — factors that should shape near‑term corporate priorities.
Ethylene Propylene Diene Monomer (EPDM) Market
Why 2026 matters: three strategic inflection points
- Regulatory compression around recycled content and taxation risk. Policy moves are converging on both sides of the Atlantic: recycled content mandates for packaging (and related pressure on elastomer use in automotive and industrial components) are accelerating customer and OEM requirements, while tax/regulatory proposals in major jurisdictions are elevating the risk profile of certain raw polymer categories. These developments will reframe cost, compliance and product specification conversations with buyers.
- Supply architecture reconfiguration. Producers are starting to react to demand recovery and sustainability pressures with capacity adjustments and site reinvestments. Announced capacity restarts and expansions in 2025–2026 alter near‑term supplier bargaining power and create windows for downstream players to lock favorable terms or to diversify suppliers strategically.
- Consolidation and competitive positioning. The market exhibits a moderate level of concentration: the top three producers account for a meaningful share of global supply, and the top five further broaden that footprint. This structure produces both risk (single‑supplier constraints in specific product classes) and opportunity (strategic partnerships and selective vertical integration).
Key dynamics shaping commercial outcomes
- Demand heterogeneity. Growth drivers in automotive, building & construction, and wires & cables remain intact, but demand intensity, specification complexity and lead‑time sensitivity differ substantially by end‑use. Commercial teams need to translate product roadmaps into differentiated go‑to‑market propositions rather than rely on volume plays alone.
- Feedstock and input cost volatility. EPDM economics remain linked to ethylene/propylene markets and to energy dynamics. Procurement flexibility — via tolling, long‑term offtake agreements, or co‑location strategies — will materially affect margin stability across scenarios.
- Sustainability and product reformulation pressure. OEM and regulatory pressure for recycled content and lifecycle performance is accelerating reformulation R&D and scale trials. Players that can validate recycled‑content EPDM at automotive performance levels will command pricing premiums and preferred supplier status.
- Regulatory tail‑risks. Recent filings seeking to change tax treatment of certain elastomers highlight a non‑zero probability of retroactive cost impacts or additional compliance burdens. Proactive tax and regulatory scenario planning is now a board‑level priority for exposed companies.
Competitive landscape — what the major players are doing
The market is served by a mix of global petrochemical majors, specialty elastomer producers and regional champions. Each competitor follows distinct strategic archetypes: global scale players pursuing integrated feedstock-to‑polymer advantages; specialty firms focusing on grade differentiation and application engineering; and regional providers leveraging localized cost or customer intimacy.
Ethylene Propylene Diene Monomer (EPDM) Market
- Integrated majors (example profile) — Companies with integrated petrochemical value chains deploy branded EPDM elastomers aimed at high‑volume, industrial specifications. Their scale enables investment in grades for weatherability and performance and supports broad distribution networks.
- Specialty elastomer houses (example profile) — These firms emphasize differentiated EPDM grades and technical support for OEMs, investing in compound development, application testing and co‑development programs with Tier‑1 customers.
- Regional and cost‑focused competitors (example profile) — These producers target local markets with competitive pricing and faster commercial response, often serving converters and downstream compounders where logistics and lead times are decisive.
Our report includes focused company dossiers covering the leading producers, their brand portfolios and their strategic moves (including recent capacity announcements). A representative development with sectoral implications: a July 2025 announcement to restart additional production capacity in the United States underscores the immediacy of supply repositioning — a lever that will influence procurement negotiations and spot market behavior through 2026.
Strategic implications and recommended actions for 2026
- Scenario‑based procurement strategies. Build layered sourcing models (short‑term spot + medium‑term contracts + strategic partnerships) that preserve flexibility while securing critical volumes. Stress‑test contracts against potential tax/regulatory outcomes and include review clauses tied to recycled‑content mandates.
- Prioritize product and application segmentation. Move beyond volume segmentation toward value segmentation: define premium grade pathways (e.g., higher durability, validated recycled content, lower lifecycle carbon intensity) and align pricing and service models to capture margin uplift.
- Accelerate validation of recycled content. Invest in accelerated testing and co‑development with OEMs to shorten qualification timelines. Early movers that can certify recycled‑content EPDM for demanding automotive applications will gain durable commercial advantages.
- Capex and footprint recalibration. Reassess greenfield and brownfield investments against a 5% CAGR baseline and alternative downside/upside scenarios. Consider capacity flexibility (modular lines, tolling agreements) over large irreversible investments in uncertain regulatory environments.
- M&A and alliance playbook. Use the current market structure to evaluate bolt‑on acquisitions that provide technical capability (e.g., compounding, specialty grades) or regional market access. Partnerships with recyclers and compounders can accelerate capability creation at lower capital cost.
What PW Consulting’s full EPDM Market report delivers
This briefing is a strategic trailer. The complete study provides hands‑on tools and proprietary data designed to convert insight into action for 2026 planning cycles:
- Detailed market model (historical 2020–2025, base year 2025, forecast 2026–2032) with scenario toggles for price, demand shock and regulatory outcomes.
- Proprietary demand matrices and application-specific adoption curves, including validated OEM specification timelines and qualification hurdles.
- Comprehensive competitive dossiers on the leading producers, including product portfolios, grade mappings, capacity footprints and strategic initiatives.
- Supply chain heat maps and risk indices that connect feedstock exposure, logistics complexity and supplier concentration to commercial risk metrics.
- Actionable playbooks: procurement templates, CAPEX prioritization frameworks, commercial segmentation strategies and an M&A screening tool tailored to EPDM.
- Regulatory impact assessment, including tax scenarios and recycled‑content compliance pathways with quantified margin and cost-to‑serve implications.
To protect the integrity of our primary research and to ensure commercial exclusivity, we have purposefully withheld the granular regional and application split tables in this preview. The full dataset—containing detailed regional, type and application allocations, supplier share by grade, and downloadable financial models—is available through our publication portal.
How to use this briefing in your 2026 planning
- Deliverable alignment: use the high‑level scenarios herein to challenge budget assumptions and to prioritize options in your Q1 corporate planning cycle.
- Immediate operational moves: assess short‑term supplier agreements for flexibility clauses and begin pilot testing of recycled‑content blends with key OEMs.
- Board‑level conversation starters: present the regulatory and tax risk scenarios to the audit and risk committee, and commission a focused regulatory impact study if your exposure is material.
PW Consulting stands ready to support execution—whether that means running supplier negotiations, building a recycled‑content validation roadmap, or modeling the cashflow impact of capacity options under alternative regulatory futures. For teams that require the full dataset and executable tools to finalize 2026 commitments, the complete EPDM Market report provides the granular intelligence and operational templates needed to act with confidence.
Next step
Access the full report to unlock the detailed segmentation, supplier share matrices and the Excel model that power actionable decisions for 2026 and beyond. Our analysts are available for briefing sessions that map the findings directly to your portfolio and go‑to‑market plans.
For detailed analysis of this topic, please visit the official page: Ethylene Propylene Diene Monomer (EPDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: LED Strip Market set for USD 11.02B by 2032 with 9.6% CAGR
By pmarketresearch, 2026-07-09
LED Strip Market 2026: Strategic Imperatives for Rapidly Scaling Opportunities
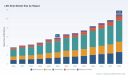
The LED strip market is at an inflection point. With a compound annual growth rate (CAGR) of 9.6% anchored to a 2025 base year, total addressable revenue has roughly doubled from the early 2020s and is projected to continue expanding through our 2032 horizon. For executives planning capital allocation, product roadmaps, and channel strategies in 2026, this research is designed to convert macro momentum into executable, low-regret actions while spotlighting the operational and regulatory levers that will determine winners in the next three years.
LED Strip Market
Why this study matters for 2026 decision-making
- Translate growth into profitable scale: High headline growth does not guarantee margin expansion. Our analysis differentiates top-line opportunity from sustainably profitable adoption by isolating where value migrates (product premiumization, systems integration, and recurring services) versus where commoditization compresses returns.
- Prioritize roadmap investments: The market is bifurcating between highly integrated, smart lighting systems and high-performance, specification-driven strips for commercial/industrial uses. The report maps where R&D and certification spend will produce the highest ROI in 2026–2028.
- Derisk supply chains strategically: Raw material volatility, certification timelines, and evolving regulation present concentrated operational risk. We quantify exposure points and present mitigation playbooks that can be actioned within 6–12 months.
- Target M&A and partnership windows: With measured market concentration and large numbers of specialty suppliers, we identify archetypal targets and partnership structures that accelerate access to end-markets without repeating costly build cycles.
- Operationalize compliance as a competitive advantage: New high-end color and safety standards are reshaping buyer expectations. The report turns regulatory compliance from a cost center into a product differentiator in procurement conversations.
What the report contains — practical, actionable deliverables
- Bottom-up demand model: A proprietary, scenario-capable model spanning 2020–2032 (base year 2025) that reconciles historical adoption curves with technology substitution dynamics and service revenue assumptions.
- Revenue and margin scenarios: Three stress-tested pathways (constrained, baseline, accelerated) that show how pricing, BOM optimization, and channel mix drive EBITDA outcomes through 2032.
- Commercial playbooks: Tactical GTM bundles for OEMs, lighting contractors, and retail brands, including channel economics, sales comping, and promotional hygiene for 2026 launch windows.
- Product-specification scorecards: Decision matrices that map CRI, SDCM, IP ratings, and driver integration options to monetization levers across residential, commercial, and industrial use cases.
- Supplier and risk matrix: A prioritized list of raw-material and supplier risks (with mitigation options such as dual-sourcing, hedging, and design-to-material substitutions) and time-to-implement estimates.
- Competitor dossiers and pricing benchmark: Executive summaries and go-to-market positions for the market’s leading vendors, plus a pricing ladder and margin sensitivity analysis.
- Regulatory scenario planning: Tailored playbooks for RoHS compliance, UL certification timelines, and color-imperfection remediation, including estimated compliance cost bands and supplier contract language.
- Downloadable assets: A modular Excel model, slide-ready market maps, and an executive decision checklist designed for board-ready briefings.
Market structure and concentration — what leaders should know
The LED strip market presents meaningful room for both scale players and specialist challengers. Measured concentration is modest: the combined share of the three largest suppliers is limited, and even the five-leader block leaves substantial share for nimble incumbents and regional specialists. That structure creates two strategic playbooks that work in parallel in 2026: (1) platform-led scale (integrated smart systems, global distribution), and (2) niche specialization (spec-driven strips for automotive, industrial, and high-color-fidelity applications).
LED Strip Market
Competitive landscape — profiles and tactical implications
- Philips Hue (Netherlands): Positioned as a premium smart lighting leader, Philips Hue’s expansion into gradient and outdoor Neon strips signals a push to own decorative and architectural ecosystems. Their delayed regional rollouts highlight the execution risk in global launches; premium feature sets will command higher ASPs but require strong inventory and channel coordination.
- LEDVANCE (Germany): Focused on professional and modular systems, LEDVANCE’s trade-show presence and project-oriented offerings make them a first-choice partner for commercial and institutional installers. Their approach underscores the importance of systemization — drivers, profiles, and service contracts — to capture larger project-level margins.
- Govee (United States): Govee’s product cadence (RGBIC, COB, and the recent Lumiblend+ color accuracy tech plus AI lighting bot demoed at CES 2026) demonstrates how consumer-tech speed and data features can rapidly commoditize lower tiers while opening services-led adjacencies (apps, subscription features).
- OSRAM (Germany): With a strong automotive and entertainment lighting lineage, OSRAM’s high-performance modules position them advantageously for interior automotive retrofits and specialized entertainment installations — segments where certification and endurance testing create higher barriers to entry.
- HitLights, Flexfire LEDs, Super Bright LEDs (US): These players emphasize professional-grade outputs, high-density COB offerings, UL listings, and installer-focused accessories — a playbook that converts product reliability and spec-accuracy into repeat business with contractors and systems integrators. Recent tactical moves include Flexfire’s strategic bulk-pricing and price reductions announced in early 2026 — a sign that price competition in project segments may intensify.
Regulatory and raw-material dynamics to model now
- RoHS exemption expirations (July 21, 2026): The lapse of several lead-related exemptions requires immediate product and supply-chain reassessment for companies relying on legacy alloys or ceramic/glaze processes. Lead-time for alternative certs and material validation can extend several quarters.
- Certification expectations: UL certification continues to be a gating factor for U.S. market access; concurrently, high-end segments are consolidating around color-quality thresholds (CRI 90+ and SDCM ≤3). Meeting both safety and color fidelity requirements is now table stakes for premium segments.
- Raw-material inflation and security: A sharp copper price move in 2025 — upward of thirty-some percent — materially lifted BOMs and has driven opportunistic copper theft from assemblies. Mitigation requires supply contracts, alternative board designs, and physical security measures for distribution and warehousing.
2026 tactical playbook — three priority moves
- Fast-track high-value certification: Prioritize UL and high-CRI compliance for SKUs targeting commercial and premium residential channels. Certification timelines must be built into 2026 launch schedules and CAPEX plans.
- Segment-focused product tiers: Introduce a three-tier portfolio (value, professional, flagship) that balances rapid reflow of commodity SKUs with higher-margin, spec-driven offerings that require certification and services-bundling.
- Hedge supply and secure BOMs: Negotiate multi-year offtake or price collars for copper and critical components; consider design-for-material-reduction exercises and selective vertical integration for strategic components.
Where this preview stops — and why you should access the full dataset
To preserve the strategic value of this preview while offering immediate, operational insight, we intentionally limit disclosure of granular segment-level revenue splits and region-by-application percentages in this article. The full PW Consulting LED Strip Market report contains the proprietary line-item segmentation, region and application matrices, competitive benchmarking tables, and the downloadable demand model that enable transaction-level decision-making — from SKU rationalization to acquisition target screening.
LED Strip Market
If your 2026 planning requires precise allocation of R&D dollars, a prioritized M&A shortlist, or merchant-level pricing ladders tied to expected channel mix, the full report converts directional intelligence into executable milestones and financial-ready scenarios.
Conclusion — actionable urgency
The headline growth and favorable long-term demand trajectory present compelling upside, but the path to capturing sustainable margin is narrow and time-bound. Certification commitments, supply-chain reengineering, and the ability to translate features into service-enabled revenues will distinguish leaders from followers in 2026. This research is built to shorten the runway from insight to action: offering the models, scenario playbooks, and competitor intelligence needed to make defensible decisions now. For the complete market architecture, proprietary models, and the granular segmentation critical to investment-grade decisions, access the full report and supporting assets.
For detailed analysis of this topic, please visit the official page: LED Strip Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Cold Milling Machine Market to Expand at 6.26% CAGR Through 2032
By pmarketresearch, 2026-07-09
Cold Milling Machine Market 2026: Strategic Preview for Senior Decision‑Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused, decision‑oriented primer on the Cold Milling Machine market to frame capital allocation, product strategy, and go‑to‑market decisions in 2026. This short briefing synthesizes macro growth dynamics, competitive positioning, regulatory drivers and technology inflection points uncovered in our comprehensive market study (base year 2025; historical 2020–2025; forecast 2026–2032). It is written to help executives prioritize where to act now and what to reserve for next‑stage investment. Detailed segment tables and granular regional/application splits are intentionally withheld in this preview to guide you to the full report for transaction‑level intelligence.
Cold Milling Machine Market
Market snapshot — direction and scale
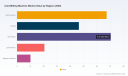
The cold milling machine market is on a steady upward trajectory. Our modeled market size expanded from a 2020 base through 2025, reaching US$215.0 Million (revenue unit: Million USD, base year 2025). Under current assumptions the market is projected to continue growing at a compound annual growth rate (CAGR) of approximately 6.26% through our forecast horizon (2026–2032), reaching a mid‑high three‑hundreds million USD outcome by 2032.
Cold Milling Machine Market
Two implications follow for 2026 planning. First, this is not a nascent niche; the market is mature enough to support differentiated product strategies (high‑power flagship machines, compact electrified units, and rental/aftermarket business models). Second, predictable growth creates a runway for both CapEx and M&A playbooks — but only for market participants who align product roadmaps with evolving regulation and lifecycle economics.
Cold Milling Machine Market
Why 2026 is a strategic inflection point
- Regulatory tightening meets measurable tech: Stricter Stage V / Tier 4 and carbon disclosure regimes across major markets are turning emissions performance from a compliance item into a competitive differentiator. Products that provide real‑time emissions tracking and demonstrable fuel savings will gain procurement preference.
- Operational economics trump headline price: Widespread adoption of telematics, automation and energy‑efficient drivetrains shifts buyer focus to lifecycle total cost of ownership (TCO) and contractor productivity metrics rather than unit price alone.
- Product diversification is now essential: Demand is bifurcating between ultra‑high‑productivity, high‑horsepower machines for large‑scale rehabilitation and compact, low‑emission units for urban and recycled workflows. OEMs without clear caravans across these submarkets risk losing share.
Competitive landscape — who matters and why
The market exhibits modest leader concentration. Our concentration metrics (CR3 ≈ 24.6%, CR5 ≈ 26.2%) indicate a fragmented competitive field with room for consolidation and for strong regional champions to scale internationally. Across OEMs, three strategic archetypes dominate thinking:
- Technology and productivity leaders: Wirtgen Group (Windhagen, Germany; https://www.wirtgen-group.com) exemplifies this archetype. Its wide portfolio — from compact units to super‑powerful machines — demonstrates investments in automation (Mill Assist), real‑time performance tracking, and high‑productivity design. Recent launches of very large machines and battery‑electric small units indicate a dual strategy: maximize output on big projects while addressing urban emission constraints.
- Scale and systems integrators: Caterpillar Inc. (Deerfield, IL; https://www.cat.com) and Roadtec/CMI (Chattanooga / Mokomo; https://www.roadtec.com / https://www.cmi.com) bring established machine reliability, telematics integration and aftersales reach. Their emphasis on high‑horsepower planers and Tier 4 final engines supports contractors focused on throughput and uptime.
- Cost‑and‑coverage challengers: Major Chinese OEMs — SANY, XCMG, LiuGong, Shantui — are pursuing aggressive product updates and network expansion. Their strengths are competitive pricing, expanding feature parity, and rapid delivery cycles, making them formidable in emerging and price‑sensitive segments.
Regional European players such as Bomag, Dynapac and Volvo Construction Equipment maintain strong product portfolios and durability reputations, while Japanese specialist Sakai offers niche value in road maintenance. Collectively, this field of incumbents, challengers, and specialists creates a dynamic competitive environment where product differentiation — not merely cost leadership — determines margins.
Recent product and technology signals to monitor
- High‑power flagship launches (e.g., new Wirtgen large‑frame machines) demonstrate OEM focus on maximizing productivity for large rehabilitation projects.
- Upgrades to high‑horsepower offerings with regulatory‑compliant engines (e.g., Roadtec’s RX series) signal continued investments in output and reliability rather than pure electrification at scale — at least in the heavy segment.
- Introduction of battery‑electric small milling units and real‑time CO2/performance tracking suggests OEMs expect sustainable credentials to become a procurement pass/fail criterion within five years.
Regulation and macro trends shaping buyer choices
Emissions regulation (Stage V/Tier 4 and evolving carbon mandates) combined with procurement policies that increasingly weight lifecycle emissions is accelerating the adoption of automated, fuel‑efficient and telematics‑enabled machines. Some OEMs claim up to 30% fuel savings with advanced drum and drive controls; while claims should be validated on customer fleets, the strategic consequence is clear: measurable efficiency improvements will underpin future tender wins.
Practical, prioritized moves for 2026 decision calendars
- Procurement and fleet managers: Re‑score suppliers on TCO and emissions reporting capabilities. Prioritize pilot purchases of electrified small mills where urban project access or emissions caps are binding.
- OEM product planners: Accelerate modular architectures that allow platform sharing between high‑power and compact variants; embed telematics and emissions dashboards as standard features rather than optional extras.
- Aftermarket and rental operators: Build service packages emphasizing uptime analytics, drum wear monitoring and certified refurbishment to extend machine life and margins.
- M&A and corporate development teams: Look for tuck‑ins that add telematics, battery integration, or regional dealer networks. The fragmented field and moderate CR metrics make targeted consolidation an attractive value‑creation lever.
What our full PW Consulting study contains (practical, executable content)
The published report goes beyond high‑level forecasts to provide operational tools executives use in 2026 decisions, including:
- Proprietary market sizing and scenario forecasts (base year 2025, revenue unit: Million USD) across our forecast horizon (2026–2032).
- Buyer journey and procurement scoring matrices that translate emissions, productivity and uptime into bid‑winning value propositions.
- Vendor benchmarking templates and an objective OEM scorecard covering product breadth, automation, emissions technology, telematics maturity, and service network.
- CapEx modeling tools and TCO calculators tailored to contractor use cases (urban vs. highway rehabilitation vs. recycled materials workflows).
- Strategic M&A screens and a shortlist of potential acquisition archetypes by capability (telemetry, electrification, regional aftermarket networks).
- Operational playbooks for fleet electrification pilots, retrofit opportunities, and rental fleet optimization.
- Comprehensive company dossiers on the principal OEMs and innovators in the market, including product maps, recent developments and strategic implications.
How to use this intelligence to win in 2026
- Make emissions transparency a purchasing filter: require demonstrated real‑world CO2 and fuel metrics during tender evaluation.
- Run 12‑month pilot programs to validate OEM productivity claims on representative projects before large fleet purchases.
- Prioritize vendors that package machines with robust telematics and predictive maintenance services — these suppliers will yield the fastest return on TCO initiatives.
- For OEMs, invest now in modular electrification pathways and operator automation — late entrants will face steep retrofit costs and slower adoption curves among risk‑averse contractors.
Closing — why the full report matters for 2026
The 2026 planning cycle is about converting predictable market growth into durable competitive advantage. Our analysis shows the market is large enough to reward differentiated strategies but still sufficiently fragmented to reward decisive consolidation, rapid product differentiation and superior aftermarket economics. The full PW Consulting Cold Milling Machine Market report contains the granular segmentation, regional deployment strategies, and vendor performance data you need to translate these strategic themes into executable investment, procurement, and M&A decisions.
To access the complete dataset, vendor scorecards, and tactical deployment blueprints, please refer to the full PW Consulting report and online portal — the source for the proprietary tables and transaction‑level guidance we withheld from this preview to preserve its role as a strategic trailer for executive action.
For detailed analysis of this topic, please visit the official page: Cold Milling Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Tea Tree Oil Market to Reach USD 1,419 Million by 2032 at 10.6% CAGR
By pmarketresearch, 2026-07-09
Tea Tree Oil Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive snapshot
The global Tea Tree Oil market is in the midst of a structural growth phase. After recovering from pandemic-era supply constraints, the market scaled to an estimated USD 700 Million in 2025 and is forecast to more than double by 2032 under the scenario modelled in our research. PW Consulting’s baseline projection shows a compounded annual growth rate (CAGR) of approximately 10.6% across the 2026–2032 forecast window — a rate that turns near-term tactical choices into multi-year strategic bets for producers, processors, brands and investors.
Tea Tree Oil Market
Why this preview matters for 2026 decision cycles
-
2026 is the inflection point at which capacity, regulation and premiumisation converge. Producers that expanded capacity in 2024–2025 face critical choices about contract terms, product-grade allocation, and geographic deployment of volumes. Our research quantifies the timing sensitivity of those choices against projected demand trajectories and price elasticity for commodity versus high-purity grades.
Tea Tree Oil Market -
Regulatory shifts that matured in late‑2025 substantially change the compliance and trade landscape for formulators and importers. A final SCCS opinion confirming permitted cosmetic uses (under strict limits) reduces certain regulatory risk vectors for personal-care applications — but parallel EU trade and hazard-classification conversations introduce import friction that can materially alter sourcing economics by geography.
Tea Tree Oil Market -
Premium consumer demand in personal care, natural household hygiene and certified organic segments is rising faster than baseline market growth. That premiumisation creates margin dispersion: organizations that can reliably supply validated higher‑purity or certified oils capture outsized value relative to bulk commodity streams.
Market structure and concentration
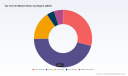
The market remains moderately concentrated: our market concentration assessment places the top three players at roughly one-third of market share and the top five below the halfway mark. This concentration dynamic creates room for scale advantages while leaving meaningful opportunities for differentiated niche players (certified organics, regenerative-sourced, community‑owned supply chains) to capture specialty premiums.
Competitive landscape — positioning and near-term moves
PW Consulting’s company dossiers synthesise operational footprints, certification portfolios, recent capital investments and go‑to‑market orientations. A few illustrative signals from our corporate surveillance through late 2025:
-
Established Australian producers have doubled down on integrated operations — from plantation to distillation and refinement — raising output of pharmaceutical‑grade oil through steam distillation upgrades and efficiency investments. These moves are aimed at securing higher-margin institutional contracts and export sales.
-
Larger essential‑oil brands and direct-to-consumer players have expanded extraction capacity in market-proximate or duty‑efficient jurisdictions to support product launches targeted at natural and sustainable personal-care segments in North America and Europe.
-
Community-based and organic-certified producers in origin markets are optimising low‑impact extraction and adding sustainability certifications (organic, Fair Trade, regenerative) to access value pools that pay a premium for traceability and social impact.
Recent corporate developments (selection)
-
Major producers announced capacity and plantation expansions and production optimisations during 2025, signalling confidence in medium‑term demand growth and a shift toward securing higher-purity and certified volumes to meet both pharmaceutical and premium personal‑care needs.
-
Notable exporters expanded dedicated supply chains and facility footprints to better serve Europe and Asia, anticipating tighter import controls and shifting classification proposals that could raise friction for unverified consignments.
-
Leading brands launched new organic and sustainability-branded product lines, indicating that brand-driven demand will increasingly prefer traceable, certified inputs over undifferentiated commodity oil.
Regulatory and trade dynamics — what keeps executives awake
-
SCCS decisions in late 2025 clarified acceptable cosmetic uses within tightly defined limits. That reduces some product formulation risk but imposes compliance costs — particularly for firms selling into the EU where testing and documentation expectations have hardened.
-
Concurrent EU notifications to WTO around hazard classification and ongoing consultations on reprotoxic concerns introduce a trade‑policy tail risk. The pace and eventual outcome of these processes will influence customs handling, labeling, and, potentially, insurance and logistics premiums for certain origin‑to‑destination routes.
-
Standard‑setting bodies and industry associations are responding with guidance and pre‑competitive testing schemes. Firms that invest early in robust analytical traceability and compliance controls will reduce friction and position themselves as preferred suppliers to regulated buyers.
Strategic implications for 2026 planning
For executive teams preparing 2026 budgets and three‑year strategic plans, our research surfaces several priority actions that convert market growth into defensible profit pools:
-
Supply‑security engineering: lock capacity with a mix of owned production, contracted volumes and near‑term toll‑processing agreements to manage quality variability and price swings while preserving optionality for premium allocation.
-
Certification-led segmentation: target investment in certifications and traceability systems commensurate with the premium being pursued (organic, Fair Trade, Regenerative Organic). Certification is not binary — map the value capture curve for each certification to avoid over-investment.
-
Regulatory hedging: establish compliance playbooks aligned to the strictest major market (e.g., EU), including conservative limits in formulations and a legal/regulatory monitoring cadence to pre-empt reclassification risks.
-
Product and channel gating: separate commodity-grade supply chains from pharmaceutical and premium channels to protect brand integrity and ensure formulators receive consistent analytical specifications.
-
M&A and partnership sequencing: prioritize bolt-on acquisitions that add certified supply or analytical capabilities, and explore long-term offtake agreements with origin producers for predictable margins and lower working capital volatility.
-
Pricing and margin defense: deploy dynamic pricing models that account for certification premiums, freight and regulatory compliance differentials rather than treating Tea Tree Oil as an undifferentiated commodity.
-
Sustainability as differentiation: quantify emissions, land-use and social-impact KPIs tied to sourcing decisions. Buyers increasingly award multi‑year contracts to suppliers who can demonstrate credible, audit‑able sustainability trajectories.
What PW Consulting’s full report delivers (practical contents)
This preview is intentionally high‑level. The full PW Consulting Tea Tree Oil Market study is engineered as an operational toolkit for 2026 decision cycles and includes:
-
Complete market sizing with annual historical series (2020–2025) and a granular forecast through 2032, modelled across alternative demand scenarios and price trajectories.
-
Segment-level demand forecasts, differentiated by grade, application and trade channels — with sensitivity analyses to quantify the impacts of regulatory shifts and certification uptake.
-
Supply-side mapping including plantation economics, distillation and refinement capacity, key supplier scorecards and an origin‑to‑customer cost curve.
-
Practical go‑to‑market frameworks for producers and brands: route-to-market decision trees, contract templates for offtake and toll processing, and sourcing checklists designed to de‑risk supply chains.
-
Regulatory risk matrix and compliance playbooks calibrated to major markets, with recommended monitoring cadences and escalation triggers for reclassification developments.
-
Commercial intelligence: supplier and competitor profiles, recent capital projects and M&A targets, and a watchlist of emerging entrants and certification bodies to monitor.
-
Actionable financial models and board‑ready slides: scenario P&L and ROI templates for capacity investments, certification business cases and potential acquisition targets.
How to use this intelligence in 90 days
-
Week 1–2: Run a short diagnostic mapping current supply commitments, grade allocations and contract maturities to identify immediate exposure to 2026 supply shifts.
-
Week 3–6: Prioritise investments (certification, testing, traceability) that unlock the highest margin differential for your SKU mix and customer set.
-
Month 2–3: Open targeted supplier dialogues anchored to feasibility studies from our report — secure offtakes or option agreements that protect against hazard‑classification and import friction scenarios.
Closing — the strategic choice for 2026
Tea Tree Oil is transitioning from a largely commodity‑oriented botanical into a stratified market where grade, certification and compliance competence determine value capture. With market value projected to expand materially from the 2025 base and a robust CAGR underpinning mid‑term growth, the strategic choices firms make in 2026 will define competitive positions for the remainder of the decade.
PW Consulting’s full study provides the data, models and playbooks required to translate growth forecasts into executable strategies — from procurement and production to product development and M&A. For the complete segment tables, regional splits, supplier scorecards and board‑ready financial models, access the full report and supporting datasets on our website.
For detailed analysis of this topic, please visit the official page: Tea Tree Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Industrial Plugs & Sockets Market to Hit USD 4,010M by 2032 at 5.4% CAGR
By pmarketresearch, 2026-07-09
Industrial Plugs and Sockets Market — Strategic Preview for 2026
Executive snapshot
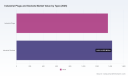
As PW Consulting’s lead industry analyst, I present a condensed strategic preview of our full Industrial Plugs and Sockets Market study. The global market has shown steady recovery and expansion through the early 2020s, registering multi-year growth and arriving at an estimated USD 2.796 billion in the base year (2025). Our forecast work projects continued, structurally driven growth into the coming decade, with the market advancing at a compound annual growth rate (CAGR) of approximately 5.4% during the 2026–2032 forecast window and exceeding four billion dollars by the terminal year in our model. This trajectory creates concrete windows for investment, product development, and commercial repositioning in 2026 — but the tactical moves will differ sharply by capability and market reach.
Industrial Plugs and Sockets Market
Why this preview matters to decision-makers in 2026
- Actionable horizon alignment: Capital allocation, product roadmaps, and supply‑chain reengineering initiated in 2026 will realize most of their value over the next five to seven years. The market’s mid-single-digit CAGR means deliberate, sustained action compounds.
- Risk‑reward visibility: Regulatory updates, evolving hazardous‑location requirements and the introduction of data-enabled connectors are reshaping product specifications and margin profiles — creating both compliance risk and premium product opportunities.
- Competitive arbitrage: The vendor landscape is neither a classic monopoly nor atomized commodity market; leading incumbents retain strong technical moats in high‑ampacity, ATEX and switch‑rated designs while a broad middle tier competes on cost and distribution. That structure creates distinct M&A and alliance strategies for market entrants and incumbents alike.
Market dynamics shaping strategy
Three structural dynamics will determine winners and losers in 2026 and beyond:
Industrial Plugs and Sockets Market
- Regulatory and standards evolution: Global interoperability remains anchored in IEC 60309 family standards, which continue to evolve — notably incorporating provisions that enable basic data-communication within power connectors. In parallel, North American standards activity (including revisions to UL 508A and related UL 2237/2238 guidance) is broadening acceptable designs for control panels and multi-point power assemblies. Firms that map product roadmaps to these trajectories can convert compliance work into differentiated features rather than cost drains.
- Product innovation at the connector edge: Two technical threads are accelerating: ruggedized high‑ampacity connectors and switch‑rated, inherently safe devices that reduce arc and maintenance risk in hazardous environments. These product families command specification advantages in heavy industry, and several established suppliers are actively promoting solutions built around them.
- Service and lifecycle monetization: With installed bases maturing, customers increasingly value integrated offers — condition monitoring, field‑service agreements, and retrofit kits. Connectors that support remote diagnostics (enabled by the new data provisions in connector standards) can be sold as platform entrances to annuity revenue streams.
Regulatory and standards tailwinds — practical implications
Executives should treat standards movement not as a compliance tax but as a product strategy lever. The IEC 60309 updates that permit limited data channels inside power connectors create options to embed identification, load measurement and basic fault telemetry without adding external cabling. Meanwhile, UL revisions affecting industrial control panels and interconnection cable assemblies open new qualification pathways for plug-and-play solutions in HVAC, motor controls and distributed generation — categories that are likely to be material contributors to demand in the near term.
Industrial Plugs and Sockets Market
Competitive landscape — how the majors are positioned
Our research highlights a group of established suppliers with differentiated positions:
- Marechal Electric (France): Deep expertise in very high current connectors and ATEX-rated products positions Marechal as the go‑to supplier where hazardous‑location performance and thermal/arc management are mission‑critical. Their technical guidance publications and field application support are important signaling tools for specification teams.
- MELTRIC Corporation (USA): Known for switch‑rated DECONTACTOR™ technology, MELTRIC is active in electrical‑safety forums and trade shows and is leveraging inherently safe designs to win specification work in industrial safety programs. Their recent, visible presence at IEEE and PowerGen events underscores a proactive commercial posture.
- Hubbell Incorporated (USA): A broad heavy‑duty industrial portfolio and well‑established distribution channels make Hubbell an effective incumbent for large OEM and industrial customers where reliability and supply continuity matter.
- Mennekes (Germany): With a strong CEE pin‑and‑sleeve heritage and platformized product families, Mennekes competes on modularity and interchangeability, including interlocked receptacles and power distribution systems that simplify site installation.
- Schneider Electric and ABB: Both global electrification platforms supply IEC‑compliant industrial plugs and sockets as part of larger system offers — a distinct advantage when customers prefer single‑vendor sourcing for control systems, distribution and accessories.
- Legrand, Amphenol Industrial, Eaton: These suppliers combine channel reach and engineering depth to serve commercial, industrial and niche heavy‑duty applications. Their competitive playbooks often emphasize integrated systems, aftermarket service and regional manufacturing footprints.
Collectively, the market leaders balance product engineering, channel strength and regulatory engagement. Tactical moves to watch in 2026 include heightened trade‑show activity, targeted product guidance releases, and small-scale platform innovations (e.g., aluminum conductor compatibility guidance, or enhanced ingress/cord retention solutions).
Recent market signals (what they imply)
- Exhibited safety‑rated technologies at major electrical‑safety forums indicate vendor investment in education-led specification wins. Expect incumbents to push for inclusion in safety standards and application guidelines.
- Product advisories about conductor termination practice and connector materials reflect both supply‑chain realities and a push toward installer-friendly differentiation. These advisories often precede specification updates in tender documents.
- Participation by smaller regional vendors in major trade fairs signals active competitive pressure in price‑sensitive channels and a likelihood of new regional entrants striving for OEM contracts.
How PW Consulting’s report turns insight into 2026 decisions
Our full report is built around decision‑centric deliverables designed for executives, product managers, and commercial leaders who must act in 2026:
- Investment prioritization model: Scenario‑based ROI modeling for capex and product development that compares near‑term retrofit demand against multi‑year greenfield projects in manufacturing, energy and mining.
- Regulatory impact matrix: Practical checklists tying IEC/UL updates to required product changes, testing timelines and certification costs — calibrated by geography and end‑use risk profile.
- Go‑to‑market playbooks: Channel strategies for OEM partnerships, distributor optimization, and regional manufacturing decisions, including supplier selection criteria and contract language templates focused on lead‑time protection and IP control.
- Competitive benchmarking: A qualitative and technical comparison of the major providers (product breadth, safety credentials, service coverage, and innovation cadence) with suggested positioning moves for challenger brands.
- M&A and alliance screening tools: A short‑list methodology and financial filters to identify tuck‑in targets and capability buys aligned to high‑probability application verticals (e.g., hazardous locations, mining, utilities).
- Commercial negotiation aids: Tender language templates, warranty and aftersales clauses, and sample total cost of ownership (TCO) calculators to convert feature differentials into commercial value.
Recommended 2026 playbook — prioritized actions
For executives who can commit resources in 2026, we recommend the following prioritized actions (in order):
- Quick wins (0–12 months): Update product qualification plans to reflect IEC/UL revisions; run targeted tender audits to identify specification drift; publish installer guidance for aluminum conductor terminations where relevant to reduce field failures.
- Mid‑term bets (12–36 months): Invest in a data‑enabled product line pilot leveraging the new IEC provisions for embedded telemetry; secure strategic distributor agreements in select regions; pursue a tuck‑in acquisition to add switch‑rated or high‑ampacity competencies if you lack them.
- Structural moves (36+ months): Expand service programs and digital maintenance offerings to monetize installed bases; reconfigure production footprints to manage cost and lead time volatility; embed safety and monitoring features as platform differentiators rather than point products.
What we intentionally withhold in this preview
To preserve the utility of our intelligence product as a decision tool, this preview is deliberately high‑signal and low‑detail: we have not published granular regional splits, application‑level dollar allocations or proprietary scenario tables here. Those segmented datasets, supplier‑level market shares and downloadable financial models are included in the full PW Consulting report and interactive dashboard. If you require the disaggregated figures to stress‑test a procurement or M&A case, the full dataset provides the necessary line‑item granularity and supporting assumptions.
Next steps — use this preview to accelerate your 2026 agenda
- Schedule a 60‑minute briefing with our consulting team to map these insights to your portfolio and receive a tailored risk/opportunity heatmap.
- Request the full report to access the segmented market models, supplier scorecards and the downloadable playbook templates described above.
- Engage our M&A screening workshop if you are evaluating acquisitions or strategic partnerships — we can run target screening against the market model and deliver a prioritized shortlist within two weeks.
In a market characterized by steady growth, standards shifts and platform‑level product innovation, 2026 is a year to convert technical credibility into commercial advantage. PW Consulting’s full Industrial Plugs and Sockets Market report supplies the evidence base, scenario models and executable playbooks you need to do that — without forcing you to guess around hidden assumptions. Contact our research desk to receive the full dataset and schedule a strategic briefing.
For detailed analysis of this topic, please visit the official page: Industrial Plugs and Sockets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com