

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Automotive Steering Wheel Switch Market to grow at 7.25% CAGR to 2032

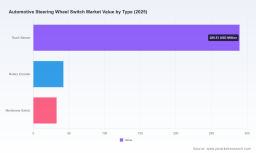
Automotive Steering Wheel Switch Market — Strategic Outlook for 2026 Decision‑Making
Executive summary
By 2025 the global Automotive Steering Wheel Switch market has evolved from a functional accessory into a strategic touchpoint for vehicle HMI, safety integration, and software-defined differentiation. PW Consulting’s latest industry study — built on a 2020–2025 historical base and projecting through 2032 — shows a clear, sustained growth trajectory underpinned by electrification, steer‑by‑wire readiness, and software-enabled human‑machine interfaces. The market expands at a compound annual growth rate (CAGR) of 7.25%, rising from the early‑decade base to a materially larger addressable market by the end of our forecast horizon.
Automotive Steering Wheel Switch Market
This preview highlights the report’s strategic value for 2026 corporate planning: we show why steering wheel controls are no longer mere hardware, outline the competitive and regulatory inflection points to watch, and describe the actionable content you will find in the full study. Critical granular splits and segment tables are intentionally withheld here to encourage direct access to the primary report for procurement‑grade data and model outputs.
Automotive Steering Wheel Switch Market
Why this market matters for 2026 strategies
- Control surfaces as experience platforms: Steering wheel switches increasingly serve as primary HMI elements for infotainment, driver assistance, biometric signaling, and tactile fail‑safe controls as vehicles become more software‑centric.
- Technology convergence: Capacitive touch, haptic feedback, grip sensing, and embedded vibration actuators are converging with software overlays (voice, gesture, AI) to create hybrid interaction models. OEMs that integrate these layers coherently convert hardware spend into perceived quality and safety differentiation.
- Regulatory and safety inflection: New steer‑by‑wire deployments and evolving ISO standards around driver input systems mean hardware partners must demonstrate both functional safety and system‑level traceability. 2026 procurement cycles must therefore prioritize suppliers with end‑to‑end compliance and systems integration capabilities.
- Economic vote of confidence: From a macro perspective, the market scaled steadily through 2020–2025 and, based on our forecasts, continues to accelerate through 2032. The growth trajectory and projected mid‑cycle market size support investment into modular platforms and software upgradeability.
Market trajectory — headline metrics
PW Consulting uses 2025 as the base year for our model. The market has climbed notably since 2020 and, under a 7.25% CAGR, reaches a significantly higher level by the end of the forecast period. These headline numbers frame capital allocation decisions: they demonstrate a durable addressable market that justifies medium‑term R&D programs, platform investments, and strategic partnerships.
Automotive Steering Wheel Switch Market
Drivers, risks and scenario levers
- Demand drivers: Transition to EVs, proliferation of advanced driver assistance systems (ADAS), and the push toward software‑defined vehicle architectures are the principal demand drivers. OEMs are rethinking switch ergonomics and functionality to enhance occupant experience and enable over‑the‑air feature rollouts.
- Supply‑side pressure: Integration of electronics and sensors into switch assemblies has raised material and labor intensity in recent model cycles, putting pressure on margins for lower‑tier suppliers and reshaping supplier selection criteria toward higher technical competence.
- Regulatory risk: Steer‑by‑wire and autonomous operation introduce amplified safety and testing requirements. Suppliers failing to embed functional safety engineering and compliance traceability into their product development lifecycle will face longer time‑to‑market and constrained qualification pathways.
- Market consolidation & M&A: The study documents accelerating consolidation activity among HMI and switch suppliers as players acquire capabilities for modular, customizable control platforms and software integration. This dynamic will alter competitive maps and bargaining power over the next 12–36 months.
Competitive landscape: strategic profiles and positioning
The competitive field is mixed: established component specialists, steering system integrators, and traditional tier‑1s are all expanding their offerings. The report analyzes capability clusters — tactile mechanical expertise, capacitive/haptic competency, systems integration for steer‑by‑wire, and software/UX provisioning — and maps principal players against these clusters.
- Preh GmbH (Bad Neustadt, Germany): Multi‑decade supplier of multifunction steering wheel controls. Strengths include configurable, brand‑specific switch suites and deep OEM customization experience. Preh’s portfolio is attractive to OEMs wanting bespoke ergonomics coupled with high mechanical reliability.
- Marquardt GmbH (Rietheim‑Weilheim, Germany): Noted for precise, high‑quality switches with strong haptic design. Marquardt’s value lies in tactile engineering and the ability to marry mechanical cues with electronic sensing for safe, intuitive user experiences.
- ZF Friedrichshafen AG (Friedrichshafen, Germany): Integration leader with system‑level offerings, including capacitive HMI and steer‑by‑wire compatible controls. ZF’s scale and systems expertise make it a preferred partner for programs requiring integration of steering systems and electronic controls into a unified architecture.
- Autoliv Inc. (Stockholm, Sweden): Safety‑centric supplier combining steering assemblies with functional switches and vibration modules. Autoliv’s recent foldable steering wheel reveal highlights its push into novel form factors for autonomous vehicle applications, reinforcing the trend toward safety‑aware HMI innovation.
- Toyoda Gosei Co., Ltd. (Nagoya, Japan): Strong in integrated steering systems, including grip sensing and vibration units designed for ADAS compatibility. Their steer‑by‑wire compatible developments demonstrate early readiness for future vehicle platforms seeking digital control surfaces.
- DENSO Corporation (Kariya, Japan): Focused on ergonomic switch modules linked to infotainment and driver assistance. DENSO’s strengths are in systems engineering and cross‑domain integration with vehicle electronics.
Collectively, the major players demonstrate differentiated plays: mechanical/haptic leadership, systems integrators pushing steer‑by‑wire, and safety specialists exploring new form factors for autonomy. Market concentration remains moderate — enough to allow niche specialists to thrive while enabling scale benefits for integrators.
Recent industry movements to watch
- Autoliv’s 2026 foldable steering wheel product reveal underscores the push toward new form factors and the need for resilient, safety‑critical switch designs in autonomous modes.
- Continental’s modular control interface platform (2025) signals OEM demand for configurable, cross‑model button ecosystems that reduce per‑variant engineering costs.
- Toyoda Gosei’s steer‑by‑wire compatible steering system announcement (2025) highlights supply‑chain readiness for next‑generation vehicle controls.
- ZF’s move to series production for steer‑by‑wire systems reflects regulatory and technical maturity across vehicle segments, increasing the strategic importance of compatible switch architectures.
- Industry reports show intensified M&A activity among HMI suppliers and upward pressure on material and labor costs for electronic‑integrated switch assemblies — both factors that will shape 2026 supplier selection and pricing negotiations.
What the PW Consulting report delivers — practical, decision‑grade assets
Our full study is built for direct use in procurement, product strategy, and corporate development workflows. The actionable components include:
- Robust market model (2020–2032) with sensitivity testing, scenario outputs and distributional assumptions to support CAPEX and portfolio prioritization.
- Demand‑driver matrices linking EV penetration, ADAS feature mix, and software‑defined vehicle architectures to switch functionality requirements.
- Supplier heatmaps that score vendors across technical capabilities, safety credentials, integration experience, cost competitiveness, and scalability.
- Go‑to‑market playbooks for OEMs and Tier‑1s that cover product modularization, licensing vs. buy decisions for software stacks, and supplier governance models to accelerate qualification.
- M&A scouting dossiers and valuation yardsticks for capability targets (e.g., capacitive/haptic IP, steer‑by‑wire integration, biometric sensing), plus integration‑risk checklists.
- Regulatory roadmap and compliance checklist tailored to steer‑by‑wire and autonomous readiness, including recommended test regimes and documentation templates.
- Commercial negotiation templates and cost‑down levers informed by componentization and materials trends observed through 2025.
How to use this study in 2026 planning cycles
- Portfolio prioritization: Use the market model to stress‑test investment cases under differentiated EV/ADAS adoption scenarios. Allocate R&D budgets to platform architectures that offer the fastest path to OTA feature deployment.
- Supplier strategy: Segment suppliers into partnership tiers (core, strategic, tactical) using our heatmaps and align qualification timelines with program milestones. Prioritize partners who deliver both hardware reliability and software upgradeability.
- M&A and alliance playbook: Identify capability gaps that are best filled by acquisition versus joint development. Our scouting dossiers narrow the universe to targets with defensible IP and rapid integration potential.
- Risk mitigation: Adopt our regulatory checklist early in 2026 programs to avoid qualification delays, particularly for steer‑by‑wire and autonomous applications where safety validation cycles can be lengthy.
Concluding perspective and next steps
Steering wheel switches are transitioning from commoditized inputs to strategic interfaces that shape safety, UX, and software monetization. The market’s growth profile through 2032 and the technology and regulatory inflection points described here make 2026 a pivotal planning year: companies that align product architecture, supplier ecosystems, and compliance tracks now will capture disproportionate value as vehicles become more software‑defined and interaction‑centric.
For procurement teams, product leaders, and corporate development executives preparing budgets and partnership strategies in 2026, PW Consulting’s full Automotive Steering Wheel Switch Market study provides the granular segmentations, supplier scores, and financial models necessary to operationalize these insights. This article is a strategic preview; the complete report contains the detailed data tables, scenario models, and supplier scorecards that inform concrete decisions. Contact PW Consulting or visit our report page to access the full analysis and the downloadable decision toolkit.
For detailed analysis of this topic, please visit the official page: Automotive Steering Wheel Switch Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com