

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Tea Tree Oil Market to Reach USD 1,419 Million by 2032 at 10.6% CAGR

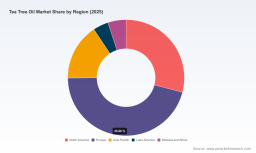
Tea Tree Oil Market: Strategic Imperatives for 2026 — PW Consulting Preview
Executive snapshot
The global Tea Tree Oil market is in the midst of a structural growth phase. After recovering from pandemic-era supply constraints, the market scaled to an estimated USD 700 Million in 2025 and is forecast to more than double by 2032 under the scenario modelled in our research. PW Consulting’s baseline projection shows a compounded annual growth rate (CAGR) of approximately 10.6% across the 2026–2032 forecast window — a rate that turns near-term tactical choices into multi-year strategic bets for producers, processors, brands and investors.
Tea Tree Oil Market
Why this preview matters for 2026 decision cycles
-
2026 is the inflection point at which capacity, regulation and premiumisation converge. Producers that expanded capacity in 2024–2025 face critical choices about contract terms, product-grade allocation, and geographic deployment of volumes. Our research quantifies the timing sensitivity of those choices against projected demand trajectories and price elasticity for commodity versus high-purity grades.
Tea Tree Oil Market -
Regulatory shifts that matured in late‑2025 substantially change the compliance and trade landscape for formulators and importers. A final SCCS opinion confirming permitted cosmetic uses (under strict limits) reduces certain regulatory risk vectors for personal-care applications — but parallel EU trade and hazard-classification conversations introduce import friction that can materially alter sourcing economics by geography.
Tea Tree Oil Market -
Premium consumer demand in personal care, natural household hygiene and certified organic segments is rising faster than baseline market growth. That premiumisation creates margin dispersion: organizations that can reliably supply validated higher‑purity or certified oils capture outsized value relative to bulk commodity streams.
Market structure and concentration
The market remains moderately concentrated: our market concentration assessment places the top three players at roughly one-third of market share and the top five below the halfway mark. This concentration dynamic creates room for scale advantages while leaving meaningful opportunities for differentiated niche players (certified organics, regenerative-sourced, community‑owned supply chains) to capture specialty premiums.
Competitive landscape — positioning and near-term moves
PW Consulting’s company dossiers synthesise operational footprints, certification portfolios, recent capital investments and go‑to‑market orientations. A few illustrative signals from our corporate surveillance through late 2025:
-
Established Australian producers have doubled down on integrated operations — from plantation to distillation and refinement — raising output of pharmaceutical‑grade oil through steam distillation upgrades and efficiency investments. These moves are aimed at securing higher-margin institutional contracts and export sales.
-
Larger essential‑oil brands and direct-to-consumer players have expanded extraction capacity in market-proximate or duty‑efficient jurisdictions to support product launches targeted at natural and sustainable personal-care segments in North America and Europe.
-
Community-based and organic-certified producers in origin markets are optimising low‑impact extraction and adding sustainability certifications (organic, Fair Trade, regenerative) to access value pools that pay a premium for traceability and social impact.
Recent corporate developments (selection)
-
Major producers announced capacity and plantation expansions and production optimisations during 2025, signalling confidence in medium‑term demand growth and a shift toward securing higher-purity and certified volumes to meet both pharmaceutical and premium personal‑care needs.
-
Notable exporters expanded dedicated supply chains and facility footprints to better serve Europe and Asia, anticipating tighter import controls and shifting classification proposals that could raise friction for unverified consignments.
-
Leading brands launched new organic and sustainability-branded product lines, indicating that brand-driven demand will increasingly prefer traceable, certified inputs over undifferentiated commodity oil.
Regulatory and trade dynamics — what keeps executives awake
-
SCCS decisions in late 2025 clarified acceptable cosmetic uses within tightly defined limits. That reduces some product formulation risk but imposes compliance costs — particularly for firms selling into the EU where testing and documentation expectations have hardened.
-
Concurrent EU notifications to WTO around hazard classification and ongoing consultations on reprotoxic concerns introduce a trade‑policy tail risk. The pace and eventual outcome of these processes will influence customs handling, labeling, and, potentially, insurance and logistics premiums for certain origin‑to‑destination routes.
-
Standard‑setting bodies and industry associations are responding with guidance and pre‑competitive testing schemes. Firms that invest early in robust analytical traceability and compliance controls will reduce friction and position themselves as preferred suppliers to regulated buyers.
Strategic implications for 2026 planning
For executive teams preparing 2026 budgets and three‑year strategic plans, our research surfaces several priority actions that convert market growth into defensible profit pools:
-
Supply‑security engineering: lock capacity with a mix of owned production, contracted volumes and near‑term toll‑processing agreements to manage quality variability and price swings while preserving optionality for premium allocation.
-
Certification-led segmentation: target investment in certifications and traceability systems commensurate with the premium being pursued (organic, Fair Trade, Regenerative Organic). Certification is not binary — map the value capture curve for each certification to avoid over-investment.
-
Regulatory hedging: establish compliance playbooks aligned to the strictest major market (e.g., EU), including conservative limits in formulations and a legal/regulatory monitoring cadence to pre-empt reclassification risks.
-
Product and channel gating: separate commodity-grade supply chains from pharmaceutical and premium channels to protect brand integrity and ensure formulators receive consistent analytical specifications.
-
M&A and partnership sequencing: prioritize bolt-on acquisitions that add certified supply or analytical capabilities, and explore long-term offtake agreements with origin producers for predictable margins and lower working capital volatility.
-
Pricing and margin defense: deploy dynamic pricing models that account for certification premiums, freight and regulatory compliance differentials rather than treating Tea Tree Oil as an undifferentiated commodity.
-
Sustainability as differentiation: quantify emissions, land-use and social-impact KPIs tied to sourcing decisions. Buyers increasingly award multi‑year contracts to suppliers who can demonstrate credible, audit‑able sustainability trajectories.
What PW Consulting’s full report delivers (practical contents)
This preview is intentionally high‑level. The full PW Consulting Tea Tree Oil Market study is engineered as an operational toolkit for 2026 decision cycles and includes:
-
Complete market sizing with annual historical series (2020–2025) and a granular forecast through 2032, modelled across alternative demand scenarios and price trajectories.
-
Segment-level demand forecasts, differentiated by grade, application and trade channels — with sensitivity analyses to quantify the impacts of regulatory shifts and certification uptake.
-
Supply-side mapping including plantation economics, distillation and refinement capacity, key supplier scorecards and an origin‑to‑customer cost curve.
-
Practical go‑to‑market frameworks for producers and brands: route-to-market decision trees, contract templates for offtake and toll processing, and sourcing checklists designed to de‑risk supply chains.
-
Regulatory risk matrix and compliance playbooks calibrated to major markets, with recommended monitoring cadences and escalation triggers for reclassification developments.
-
Commercial intelligence: supplier and competitor profiles, recent capital projects and M&A targets, and a watchlist of emerging entrants and certification bodies to monitor.
-
Actionable financial models and board‑ready slides: scenario P&L and ROI templates for capacity investments, certification business cases and potential acquisition targets.
How to use this intelligence in 90 days
-
Week 1–2: Run a short diagnostic mapping current supply commitments, grade allocations and contract maturities to identify immediate exposure to 2026 supply shifts.
-
Week 3–6: Prioritise investments (certification, testing, traceability) that unlock the highest margin differential for your SKU mix and customer set.
-
Month 2–3: Open targeted supplier dialogues anchored to feasibility studies from our report — secure offtakes or option agreements that protect against hazard‑classification and import friction scenarios.
Closing — the strategic choice for 2026
Tea Tree Oil is transitioning from a largely commodity‑oriented botanical into a stratified market where grade, certification and compliance competence determine value capture. With market value projected to expand materially from the 2025 base and a robust CAGR underpinning mid‑term growth, the strategic choices firms make in 2026 will define competitive positions for the remainder of the decade.
PW Consulting’s full study provides the data, models and playbooks required to translate growth forecasts into executable strategies — from procurement and production to product development and M&A. For the complete segment tables, regional splits, supplier scorecards and board‑ready financial models, access the full report and supporting datasets on our website.
For detailed analysis of this topic, please visit the official page: Tea Tree Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com